
 Pediatric Tube Feeding Market | 2026-2036
Pediatric Tube Feeding Market Size, Share, and Industry Trends Forecast 2026-2036
Pediatric Tube Feeding Market Insights
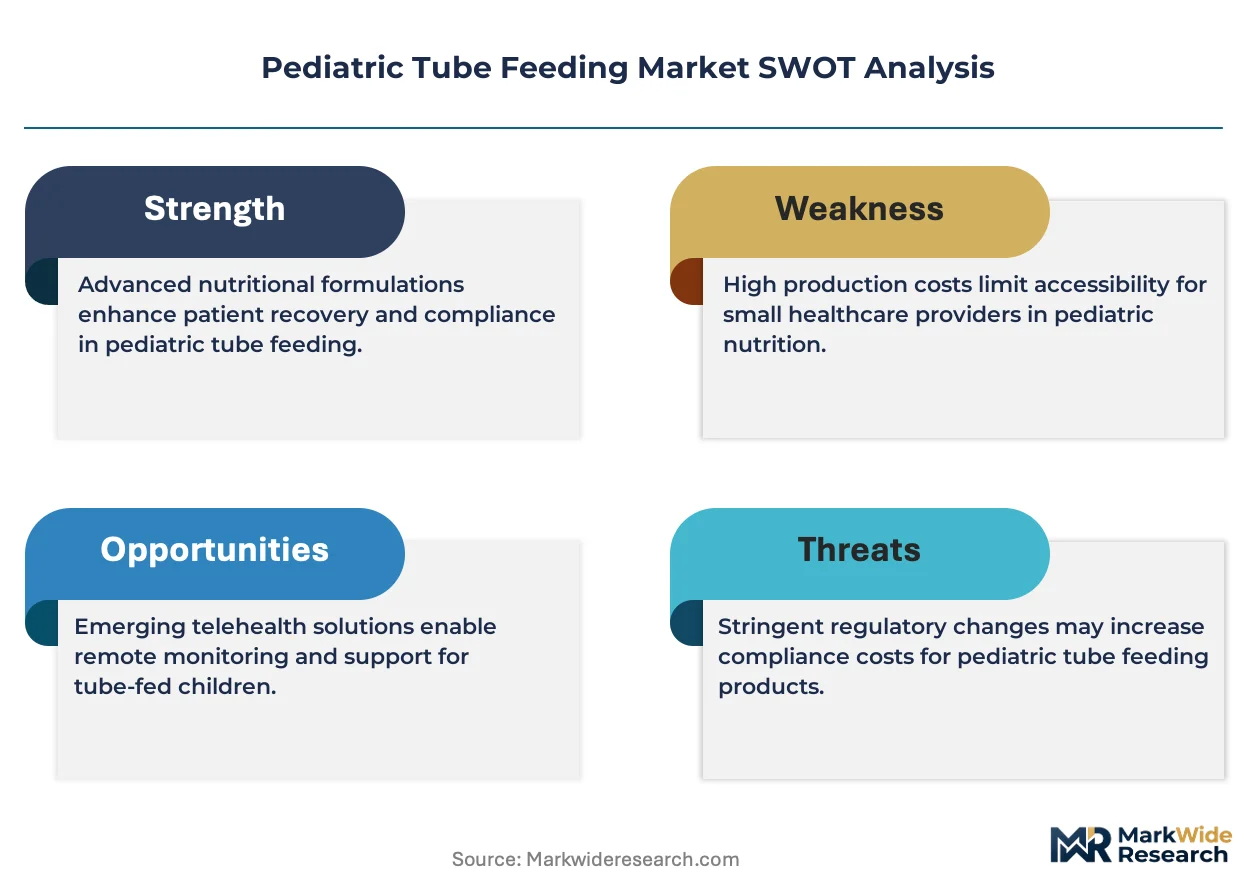
Project finance and equipment leasing for home enteral feeding programs is tilting competitive dynamics toward providers with balance-sheet flexibility. Abbott leverages its nutrition science platform to sustain leadership in pediatric formula portfolios. Fresenius Kabi anchors its position through integrated supply chains spanning clinical nutrition to delivery devices. Cardinal Health competes on distribution density, controlling hospital and home care channels across North American markets.
Pediatric tube feeding encompasses the delivery of liquid nutrition directly to the stomach or small intestine via flexible polymer tubes sized for neonatal and pediatric anatomy, typically constructed from silicone or polyurethane with radiopaque strips for imaging verification. The primary purpose is to sustain nutritional intake in children unable to achieve adequate oral feeding due to anatomical, neurological, or metabolic conditions. Gastrostomy tubes occupy the largest installed base among product categories, reflecting surgical placement durability for chronic conditions. Home care providers represent the fastest-expanding end user segment as payors shift reimbursement toward outpatient management. Continuous feeding methods dominate neonatal intensive care settings, while bolus feeding gains traction among ambulatory pediatric patients transitioning to home environments.
FDA enteral device regulations and ISO 80369 small-bore connector standards shape product design and interoperability requirements for manufacturers serving US markets. The Centers for Medicare & Medicaid Services home health benefit structures directly influence patient eligibility and device procurement economics for pediatric enteral therapy. Stakeholders must monitor evolving reimbursement thresholds between institutional and home-based care settings to align portfolio investments with shifting site-of-service economics.
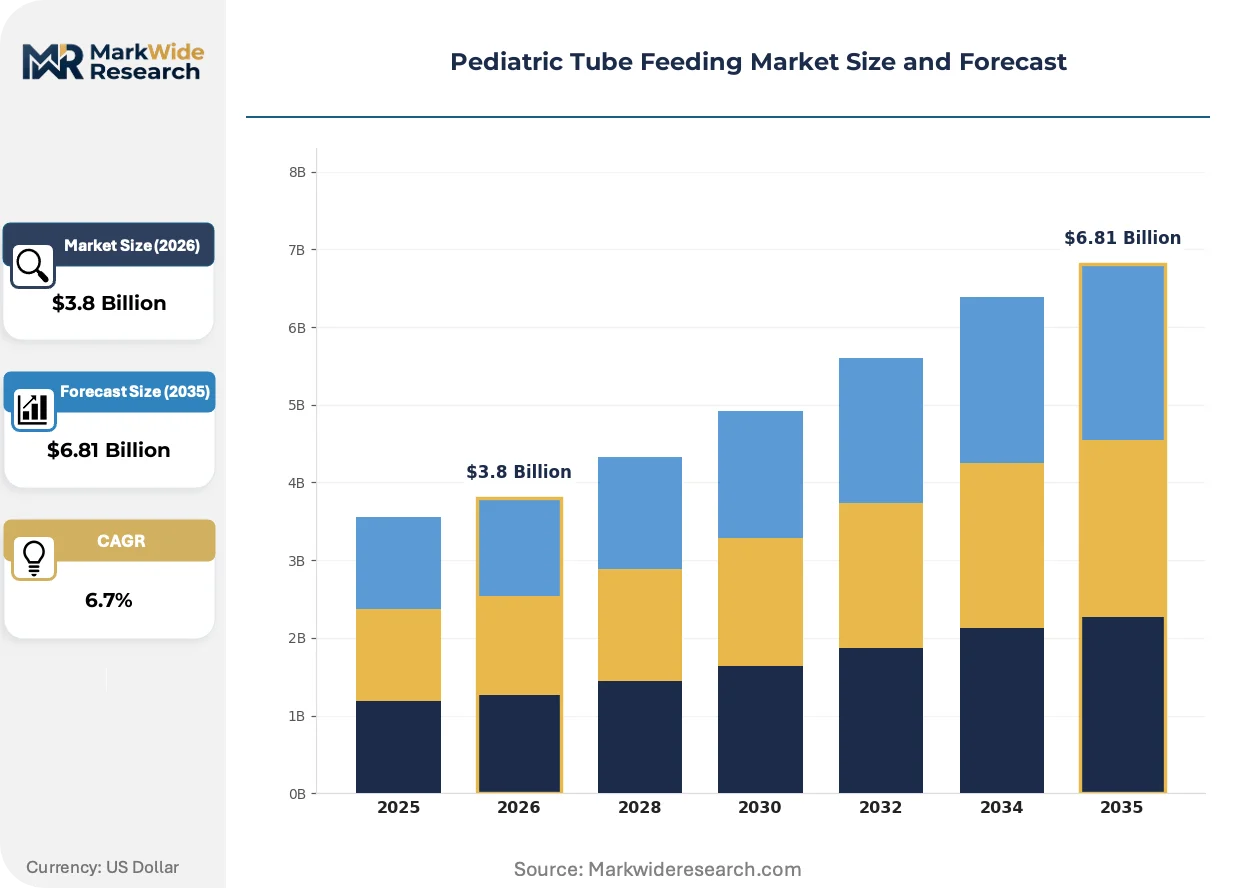
Market Dynamics
Medicaid reimbursement expansion for home-based pediatric nutrition support is restructuring site-of-service economics, tilting capital deployment toward outpatient enteral feeding infrastructure and away from institutional care models.
Growth Catalysts
- ISO 80369 small-bore connector mandates:The FDA's alignment with international interoperability standards is forcing device replacement cycles across US hospital systems, creating hardware refresh demand.
- Neonatal intensive care specialization:Regional perinatal centers in Texas, California, and Ohio are expanding capacity for medically complex infants requiring surgical gastrostomy placement.
- Silicone-to-polyurethane material transition:Polyurethane's superior durability for long-term indwelling use is extending device replacement intervals in chronic pediatric populations.
Market Restraints
- Medical-grade silicone supply concentration:Three Southeast Asian compounders control the majority of platinum-cured silicone feedstock for enteral device manufacturing, exposing producers to raw material bottlenecks.
- Gastrostomy tube migration risks:Dislodgement complications in ambulatory pediatric patients generate costly emergency interventions and device replacement expenses.
- Enteral pump capital intensity:Precision dosing electronics and occlusion detection sensors require specialized manufacturing equipment with limited second-hand market liquidity.
Strategic Opportunities
- Remote patient monitoring integration:Cloud-connected feeding pumps with flow-rate telemetry enable proactive clinical intervention before adverse events escalate.
- Medicaid waiver program expansion:State-level 1915(c) waivers in Arizona and Colorado are extending home nursing hours for technology-dependent children, expanding addressable device volumes.
- Formula-device bundling models:Integrated nutrition therapy contracts spanning specialty formulas and delivery hardware are capturing longitudinal patient relationships.
Industry Challenges
- Pediatric enterostomy specialist scarcity:Certified pediatric surgeons capable of laparoscopic gastrostomy placement remain concentrated at academic medical centers, constraining procedural capacity.
- Legacy hospital inventory systems:ERP platforms designed for pharmaceutical procurement struggle with enteral device SKU complexity and patient-specific sizing requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pediatric Tube Feeding Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nasogastric Tubes, Gastrostomy Tubes, Jejunostomy Tubes, Orogastric Tubes Application: Neurological Disorders, Congenital Anomalies, Prematurity, Failure to Thrive End User: Children's Hospitals, Pediatric Clinics, Specialty Nursing Centers, Home Care Providers Feeding Method: Continuous Feeding, Intermittent Feeding, Bolus Feeding, Gravity Feeding |
| Companies Covered | Abbott, Avanos Medical, B. Braun, Baxter International, BD, Cardinal Health, Danone, Fresenius Kabi, Nestlé Health Science, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pediatric Tube Feeding Market Trends and Innovations
Device miniaturization and connectivity integration are converging to reshape how enteral therapy is monitored and reimbursed, compressing the gap between clinical oversight and home autonomy.
Low-profile gastrostomy buttons are migrating from institutional discharge planning to direct-to-home placement protocols. Ambulatory surgery centers in Florida and Pennsylvania are adopting these devices for same-day pediatric procedures. The shift is compressing hospital length-of-stay metrics and reallocating margin capture toward outpatient surgical suites.
REACH chemical safety registrations in the European Union are restricting certain plasticizers in polymer formulations used for enteral tubing. Manufacturers serving EU markets are reformulating compounds to maintain compliance without sacrificing flexibility performance. German and French notified bodies are processing updated technical documentation with extended review timelines.
Family caregiver training protocols are displacing traditional home health nursing for stable pediatric enteral patients. Hospital discharge planners in Michigan and Georgia are certifying parents on pump operation and tube site care. The behavioral shift is most visible in Medicaid-managed care populations where nursing hour authorization faces tightening utilization review.
Pediatric Tube Feeding Market Segmentation
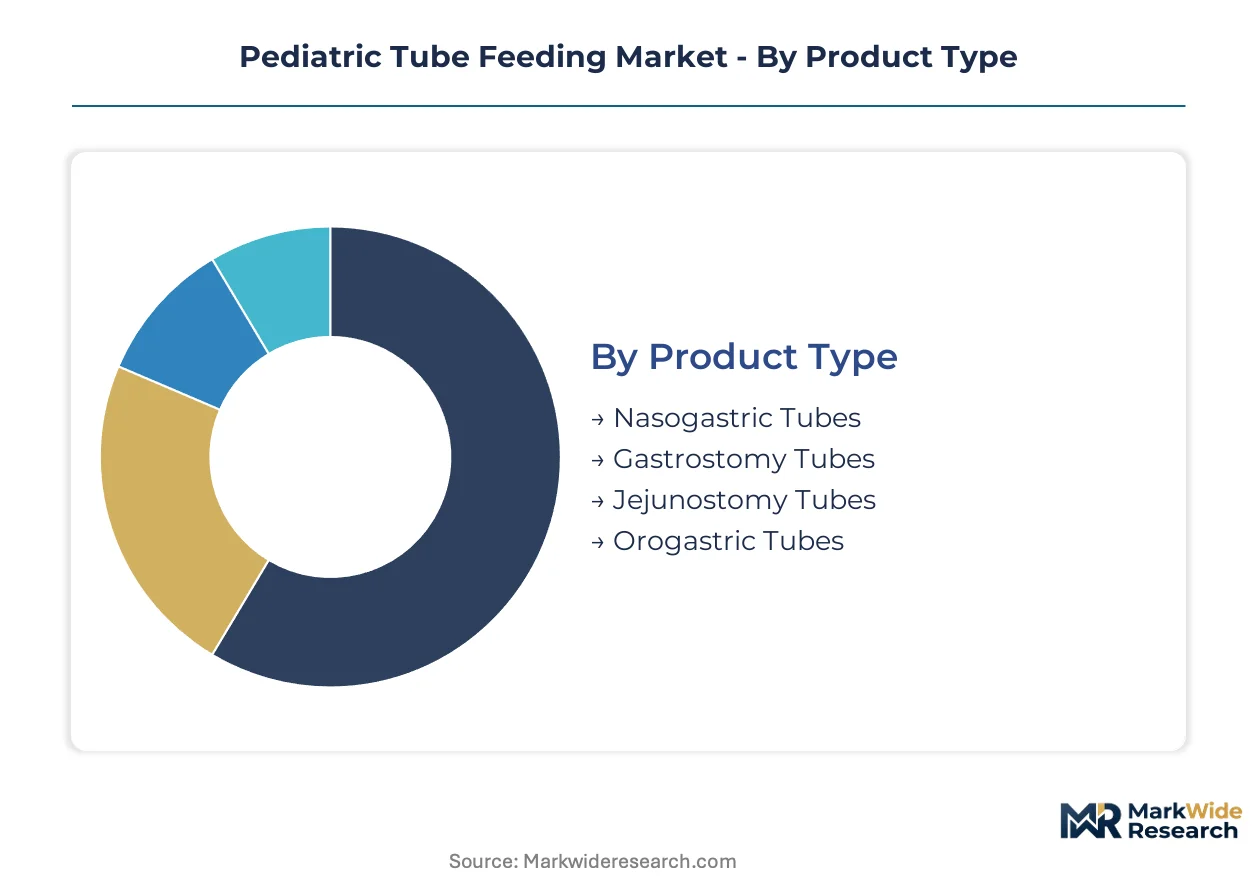
Pediatric tube feeding segmentation reflects divergent clinical workflows across acute and ambulatory settings. Product durability requirements, reimbursement site-of-service rules, and caregiver training protocols each reshape how manufacturers configure their portfolios.
Product Type:
Mature surgical placement devices anchor hospital procurement budgets while emerging minimally invasive formats capture outpatient migration.
- Gastrostomy Tubes:Silicone or polyurethane constructs with internal retention balloons or bumper mechanisms for percutaneous endoscopic placement. Demand concentrates in Texas and Ohio perinatal centers where Medicaid-funded surgical volumes for neurologically impaired infants continue rising.
- Nasogastric Tubes:Flexible polymer tubes inserted transnasally with weighted tips and radiopaque markers for gastric positioning verification. Children's hospitals in California and New York maintain the largest installed bases for acute neurological and post-surgical pediatric populations.
- Jejunostomy Tubes:Smaller-bore extensions for post-pyloric feeding in gastric motility disorders.
- Orogastric Tubes:Oral-insertion variants for neonates with nasal obstruction or midfacial anomalies.
Gastrostomy tubes retain volume leadership; nasogastric tubes hold the steepest expansion curve.
Application:
Chronic conditions drive recurring device replacement revenue while acute indications concentrate in institutional purchasing.
- Neurological Disorders:Cerebral palsy, traumatic brain injury, and seizure disorders requiring permanent enteral access. Home care providers in Arizona and Colorado are expanding device volumes through Medicaid 1915(c) waiver programs for technology-dependent children.
- Congenital Anomalies:Esophageal atresia, tracheoesophageal fistula, and gastrointestinal malformations necessitating surgical feeding routes. Pediatric surgery centers in Florida and Pennsylvania are standardizing low-profile button placements for same-day discharge protocols.
- Prematurity:Extremely low birth weight infants in neonatal intensive care requiring temporary nutritional support.
- Failure to Thrive:Growth faltering from metabolic or behavioral feeding aversion in toddlers.
Neurological disorders retain volume leadership; congenital anomalies are climbing the fastest.
End User:
Capital intensity separates acute care infrastructure from distributed home-based service models.
- Home Care Providers:Durable medical equipment suppliers and home health agencies managing long-term pediatric enteral therapy. Michigan and Georgia discharge planners are certifying family caregivers to reduce nursing hour utilization under Medicaid managed care constraints.
- Children's Hospitals:Academic medical centers with specialized pediatric gastroenterology and surgery departments. These institutions concentrate gastrostomy placement volume and drive protocol standardization for complex neonatal cases.
- Pediatric Clinics:Outpatient settings for tube monitoring and complication management.
- Specialty Nursing Centers:Skilled nursing facilities for medically fragile children with 24-hour nursing requirements.
Children's hospitals retain volume leadership; home care providers are gaining share fastest.
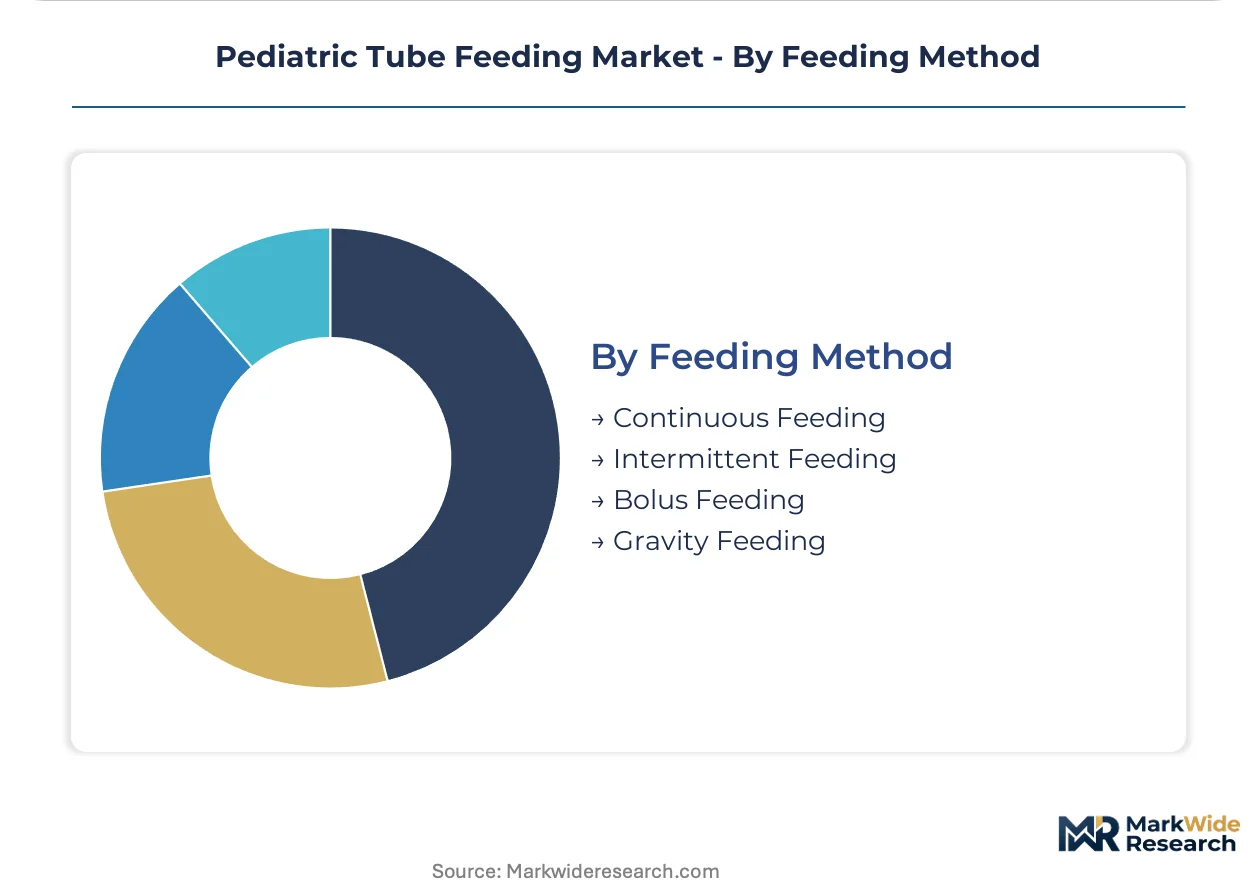
Feeding Method:
Control precision and caregiver autonomy define the technical trade-offs across delivery modalities.
- Continuous Feeding:Pump-controlled slow infusion over 8-24 hours using electronic flow-rate regulation and occlusion detection. Neonatal intensive care units in regional perinatal centers depend on this method for premature infants with immature gastric emptying.
- Bolus Feeding:Gravity or syringe-administered discrete meals mimicking oral intake schedules. Ambulatory pediatric patients transitioning to home environments in Medicaid expansion states are driving adoption of simplified bolus protocols.
- Intermittent Feeding:Scheduled pump or gravity cycles combining continuous control with meal-based timing.
- Gravity Feeding:Passive flow without electronic components for cost-sensitive or backup scenarios.
Continuous feeding retains volume leadership; bolus feeding holds the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial trade surplus in pediatric enteral devices, exporting precision-manufactured feeding pumps and gastrostomy tubes to European and Asia-Pacific markets while importing specialty silicone compounds from Southeast Asian chemical processors.
United States
Texas and California perinatal centers drive gastrostomy placement volumes for neurologically impaired infants under expanded Medicaid 1915(c) waiver programs. The FDA's updated enteral device safety guidelines and ISO 80369 small-bore connector mandates are forcing hardware replacement cycles across hospital systems. Abbott and Cardinal Health anchor device manufacturing and distribution infrastructure in Illinois and Ohio, serving domestic demand and export markets.
Germany
Bavarian medical technology clusters specialize in precision enteral pump electronics and occlusion detection sensors for neonatal intensive care applications. ECHA REACH chemical safety registrations are restricting specific plasticizers in polymer tubing formulations, compelling manufacturers to reformulate compounds. Fresenius Kabi maintains integrated supply chain operations across Baden-Württemberg, spanning clinical nutrition production to delivery device assembly.
Japan
Tokyo and Osaka metropolitan hospitals concentrate demand for miniaturized feeding devices serving extremely low birth weight infant populations. PMDA medical device regulations enforce stringent biocompatibility testing for long-term indwelling enteral products. METI industrial policy supports domestic silicone processing capabilities in Nagoya industrial corridors to reduce import dependence for medical-grade feedstock.
United Kingdom
London and Manchester pediatric gastroenterology departments standardize low-profile gastrostomy button protocols for same-day discharge surgical pathways. NHS England commissioning frameworks are shifting reimbursement toward home-based enteral therapy, expanding durable medical equipment procurement. B. Braun and Danone maintain distribution and formula blending operations in the Midlands, serving National Health Service contract structures.
Australia
Sydney and Melbourne children's hospitals drive demand for remote patient monitoring integration in cloud-connected feeding pumps. TGA medical device regulations align with international interoperability standards while maintaining additional pediatric-specific safety requirements. Nestlé Health Science operates specialized nutrition formulation facilities in New South Wales, supporting Asia-Pacific export markets alongside domestic supply.
Pediatric Tube Feeding Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in materials and precision electronics. The pediatric tube feeding market structures around three to four dominant nutrition science conglomerates with integrated device portfolios, flanked by specialized medical technology firms focused on delivery hardware. Strategic archetypes include formula-device bundlers, precision pump manufacturers, and distribution-anchored service integrators. Competitive dynamics center on backward integration into silicone compounding and geographic expansion through Medicaid waiver program penetration.
Among diversified nutrition and medical technology conglomerates, Abbott, Fresenius Kabi, and Cardinal Health occupy positions reflecting distinct competitive vectors. Abbott exemplifies the formula-science platform archetype, leveraging clinical nutrition research infrastructure to sustain pediatric specialty portfolio breadth. Fresenius Kabi represents integrated supply chain control, spanning parenteral and enteral nutrition production through to delivery device manufacturing. Cardinal Health anchors the distribution-density model, commanding hospital and home care channel access across North American markets through logistics scale rather than manufacturing ownership.
| Leading Market Players |
|---|
| Abbott |
| Avanos Medical |
| B. Braun |
| Baxter International |
| BD |
| Cardinal Health |
| Danone |
| Fresenius Kabi |
| Nestlé Health Science |
| Others |
Pricing and Supply Chain Analysis
Medical-grade silicone supply concentration in Southeast Asian compounders determines both three-tier pricing structure across premium, standard, and economy levels and supply chain resilience for enteral device manufacturers serving US and European markets.
Pricing Analysis
Hospital procurement committees anchor contract-based long-term offtake structures for gastrostomy tubes and feeding pumps. Price differentiation rests on FDA clearance tier and silicone-to-polyurethane material grade, with premium tiers commanding margins for ISO 80369-compliant small-bore connectors. Cost compression in standard tiers is intensifying because Medicaid managed care plans are tightening reimbursement bands for home enteral equipment. Home care providers exhibit the highest price sensitivity, while academic medical centers prioritize clinical performance over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for Southeast Asian silicone compounders supplying platinum-cured feedstock to US and German device manufacturers. Raw material sourcing draws from Thailand and Malaysia for silicone compounding, with precision electronics for pump controls anchored in Bavarian industrial clusters. Single-source vulnerability concentrates in platinum-cured silicone feedstock where three compounders dominate global capacity. Distribution runs through Cardinal Health and regional durable medical equipment suppliers to hospital systems and home care channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pediatric tube feeding market sits at a regulatory inflection where FDA enteral device safety guidelines and ISO 80369 mandates are forcing hardware replacement cycles across installed hospital bases.
For Market Incumbents: Entrench formula-device bundling contracts to capture longitudinal patient relationships before Medicaid waiver expansion commoditizes hardware procurement. Deepen backward integration into silicone compounding to mitigate Southeast Asian supply concentration risks. Prioritize cloud-connected pump telemetry investments to differentiate against emerging remote monitoring specialists. For New Entrants and Emerging Players: Establish a beachhead in remote patient monitoring integration for cloud-connected feeding pumps, where incumbent device manufacturers lack software-native capabilities. Target Arizona and Colorado Medicaid 1915(c) waiver programs for technology-dependent children, where nursing hour expansion is outpacing established service infrastructure. Lead with family caregiver training protocols to displace traditional home health nursing in Medicaid-managed care populations. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform integrators with nutrition science and device manufacturing capabilities. Long-term viability hinges on capturing Medicaid reimbursement expansion for home-based care settings. Watch state-level 1915(c) waiver program adoption rates as the signal for inflection in addressable device volumes.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 80369 Compliance Investment | FDA-mandated small-bore connector standards force hardware refresh cycles across US hospital systems. |
| Cloud-Connected Pump Development | Flow-rate telemetry enables proactive clinical intervention before adverse events escalate in home settings. |
| Silicone Compounding Acquisition | Backward integration into platinum-cured feedstock mitigates Southeast Asian supply concentration risks. |
| Medicaid Waiver Program Penetration | State-level 1915(c) expansions in Arizona and Colorado extend nursing hours for technology-dependent children. |
| Family Caregiver Training Certification | Hospital discharge planners in Michigan and Georgia are certifying parents to reduce nursing utilization. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with pediatric gastroenterologists, hospital procurement managers, home health agency directors, and Medicaid policy specialists; and secondary validation against FDA 510(k) filings, CMS Medicare and Medicaid data, hospital GPO contracts, and ISO 80369 implementation timelines. Bottom-up and top-down triangulation cross-checked device shipment volumes against reimbursement claim patterns.
Forecast inputs considered product type segmentation across gastrostomy, nasogastric, and jejunostomy tubes; application segmentation spanning neurological disorders, congenital anomalies, and prematurity; and end-user segmentation separating home care providers from children's hospitals. CAGRs were derived from modeled replacement cycles for ISO 80369-mandated connectors and Medicaid waiver program expansion trajectories across the analysis window. Feeding method preferences and material transitions from silicone to polyurethane shaped volume assumptions.
Sensitivities concentrate around FDA enforcement timelines for enteral device safety guidelines and state-level Medicaid waiver program adoption rates. Forecasts reflect assumptions about reimbursement site-of-service economics and silicone feedstock supply stability. Macroeconomic contraction affecting Medicaid budgets, regulatory deviation in EU REACH chemical safety registrations, or technological disruption in remote monitoring would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pediatrics
Pediatric Mattress Market
Pediatrics
Pediatric Chronic Rhinosinusitis Market
Pediatrics
Pediatrics Medicine Market
Pediatrics
Autism Service Platform Market
Pediatrics
Paediatric Neuropsychiatric Disorders Treatment Market
Pediatrics
Global Pediatric Neuroblastoma Treatment Market
Pediatrics
Global Pediatric Radiology Market
Pediatrics
Pediatric Asthma Treatment Market
Pediatrics
Middle East and Africa Pediatric Healthcare Market
Pediatrics
Pediatric Obesity Management Market
Pediatrics
Paediatric Wheelchairs Market
Pediatrics
Pediatric Oncology Treatment Market
Pediatrics
Global Pediatric Home Healthcare Services Market
Pediatrics
Pediatric Palliative Care Drugs Market
Pediatrics
Paediatric Spasticity Treatment Market
Pediatrics
Pediatric Catheter Market