
 Global Pediatric Neuroblastoma Treatment Market | 2026-2036
Global Pediatric Neuroblastoma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pediatric Neuroblastoma Treatment Market Foresight
Multi-source biologics procurement is shifting toward vertically integrated antibody developers. Pfizer sustains manufacturing scale across oncology biologics through captive production networks. Y-mAbs Therapeutics specializes in radiolabeled antibody constructs for pediatric indications. Bayer AG leverages its radiopharmaceutical infrastructure to compete in targeted neuroblastoma therapy delivery.
Pediatric neuroblastoma treatment encompasses multimodal therapeutic interventions against a pediatric solid tumor arising from neural crest progenitor cells, with functional parameters including MYCN amplification status and International Neuroblastoma Risk Group staging dictating protocol selection. Immunotherapy now occupies the fastest-expanding margin pool as anti-GD2 monoclonal antibodies displace frontline chemotherapy intensity in intermediate-risk protocols. High-risk neuroblastoma remains the dominant therapy area by clinical trial volume, though refractory neuroblastoma segments command premium pricing due to orphan-drug designations and limited therapeutic alternatives.
FDA accelerated approval pathways and EMA pediatric investigation plans shape development timelines and market access conditions for novel neuroblastoma therapeutics. The WHO Essential Medicines List inclusion criteria and national reimbursement frameworks determine commercial viability across European and North American markets. Stakeholders must monitor evolving biomarker-driven trial designs and companion diagnostic requirements that will determine which antibody-drug conjugates and CAR-T platforms secure priority regulatory review.
Market Dynamics
FDA accelerated approval pathways compress development timelines for pediatric oncology biologics, while EMA pediatric investigation plans reshape European market access conditions. This regulatory velocity concentrates investment in anti-GD2 monoclonal antibodies and radiolabeled constructs.
Growth Catalysts
- Accelerated FDA Pathways:The FDA's breakthrough therapy and priority review designations compress Phase II-to-approval timelines for high-risk neuroblastoma indications, attracting venture capital into pediatric orphan drug development.
- Specialized Children's Hospital Networks:Consolidated pediatric oncology centers in the United States anchor multi-site trial recruitment, reducing patient accrual periods and enabling faster biomarker validation.
- MYCN Biomarker Stratification:Risk-group staging protocols now integrate genomic amplification status, expanding addressable populations for targeted immunotherapy beyond frontline chemotherapy responders.
Market Restraints
- Isotope Supply Concentration:Molybdenum-99 production concentrates in aging nuclear reactors across Canada and the Netherlands, creating radiopharmaceutical supply vulnerability for I-131-MIBG therapy protocols.
- Manufacturing Scale Limitations:Antibody-drug conjugate production requires single-use bioreactor capacity that remains captive to large oncology biologics manufacturers, constraining mid-tier developer output.
- Reimbursement Fragmentation:National health technology assessment bodies in Germany, France, and England apply divergent cost-effectiveness thresholds to CAR-T and radiolabeled therapies, delaying uniform European access.
Strategic Opportunities
- Refractory Segment Premium Positioning:Relapsed neuroblastoma patient populations command orphan drug pricing advantages with limited therapeutic alternatives, enabling margin capture beyond frontline commoditization.
- Companion Diagnostic Integration:GD2 expression assays and circulating tumor DNA platforms converge with therapeutic development, creating integrated test-and-treat revenue streams alongside antibody delivery.
- Japanese Pediatric Cancer Centers:PMDA's Sakigake designation system offers priority review for innovative pediatric oncology mechanisms, opening Asia-Pacific market expansion for Western biologics developers.
Industry Challenges
- Pediatric Trial Design Complexity:Small patient populations across risk strata complicate randomized controlled endpoint validation, forcing reliance on single-arm studies that regulators scrutinize heavily.
- Long-Term Toxicity Surveillance:Survivorship monitoring requirements for cardiopulmonary and secondary malignancy risks extend post-approval commitment timelines and inflate pharmacovigilance infrastructure costs.
- Cross-Border Regulatory Misalignment:Divergent pediatric investigation plan requirements between EMA and FDA create duplicative clinical development costs for developers seeking simultaneous Atlantic market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pediatric Neuroblastoma Treatment Market |
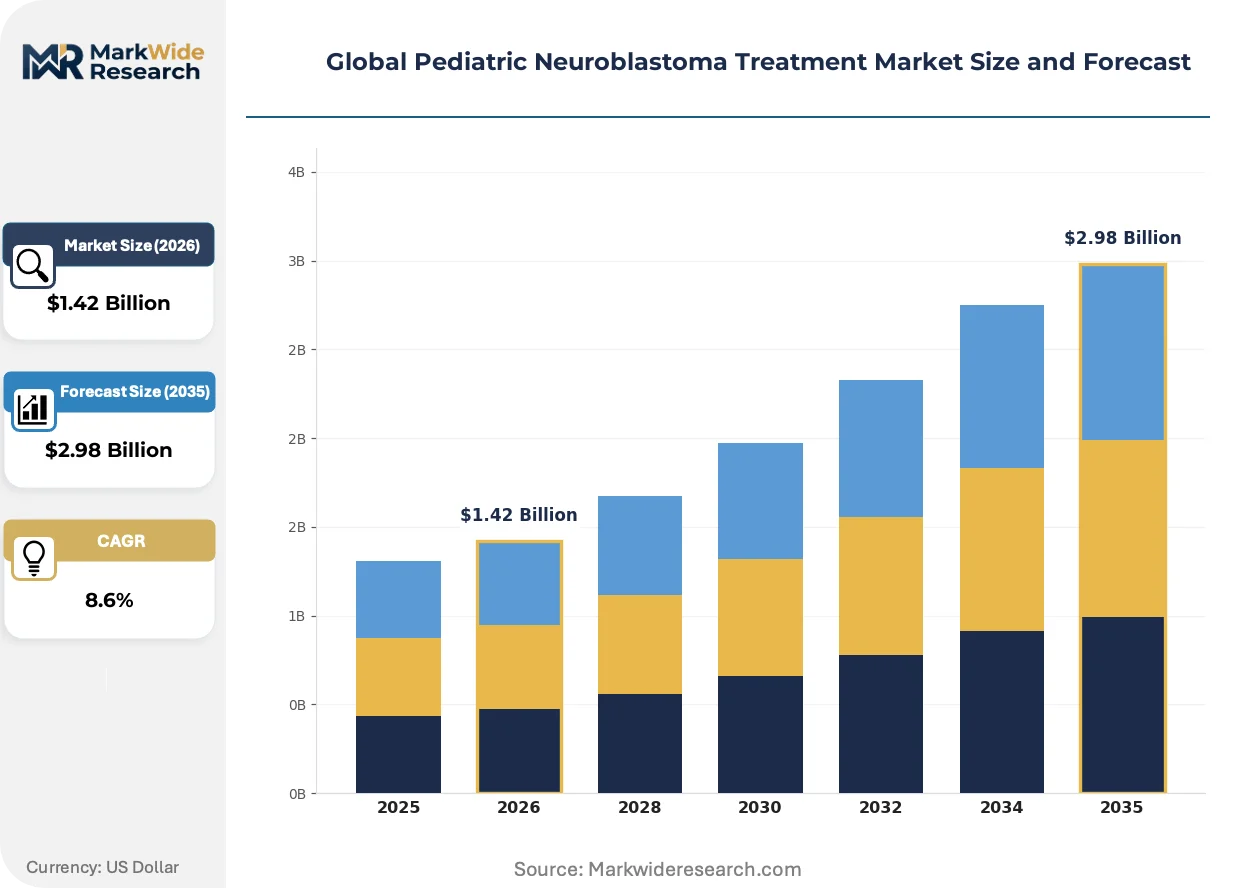
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Radiation Therapy, Stem Cell Transplant, Targeted Therapy Therapy Area: High-Risk Neuroblastoma, Intermediate-Risk Neuroblastoma, Low-Risk Neuroblastoma, Refractory Neuroblastoma End User: Specialized Children’s Hospitals, Oncology Clinics, Research Institutions, Pediatric Centers Delivery Mode: Intravenous, Oral, Subcutaneous, Intrathecal, Continuous Infusion |
| Companies Covered | Cellectar Biosciences, Pfizer, United Therapeutics Corporation, MacroGenics, Bayer AG, APEIRON Biologics AG, Y-mAbs Therapeutics, Sartorius AG, Baxter International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pediatric Neuroblastoma Treatment Market Shifts & Advancements
Anti-GD2 monoclonal antibodies are consolidating frontline protocol positioning across intermediate-risk neuroblastoma, compressing chemotherapy intensity while expanding immunotherapy margin pools. This therapeutic reconfiguration attracts manufacturing investment and reshapes competitive capability requirements.
Radioimmunotherapy constructs are consolidating targeted delivery mechanisms for refractory neuroblastoma, combining antibody specificity with isotope cytotoxicity. Specialized radiopharmaceutical manufacturing networks in the United States and Germany are scaling cGMP capacity to meet clinical demand. This convergence is consolidating treatment protocols around lutetium-177 and iodine-131 labeled antibodies, displacing external beam radiation in select metastatic indications.
REACH authorization requirements for novel chemical entities in radiopharmaceutical manufacturing are tightening European supply chain documentation standards. EMA's good manufacturing practice inspections now emphasize isotope traceability and cold-chain validation for antibody conjugate stability. Pediatric oncology centers in France and Italy are responding by qualifying single-source suppliers with dedicated radiochemistry suites, reducing multi-vendor procurement flexibility.
Consolidated buying through children's hospital group purchasing organizations is compressing antibody pricing negotiations in the United States. Major pediatric oncology networks now leverage volume commitments across chemotherapy, immunotherapy, and supportive care categories to extract tiered rebates from biologics manufacturers. This concentration is most visible in the Northeast and Midwest, where three hospital systems control majority patient volume and trial site accreditation.
Global Pediatric Neuroblastoma Treatment Market Segmentation
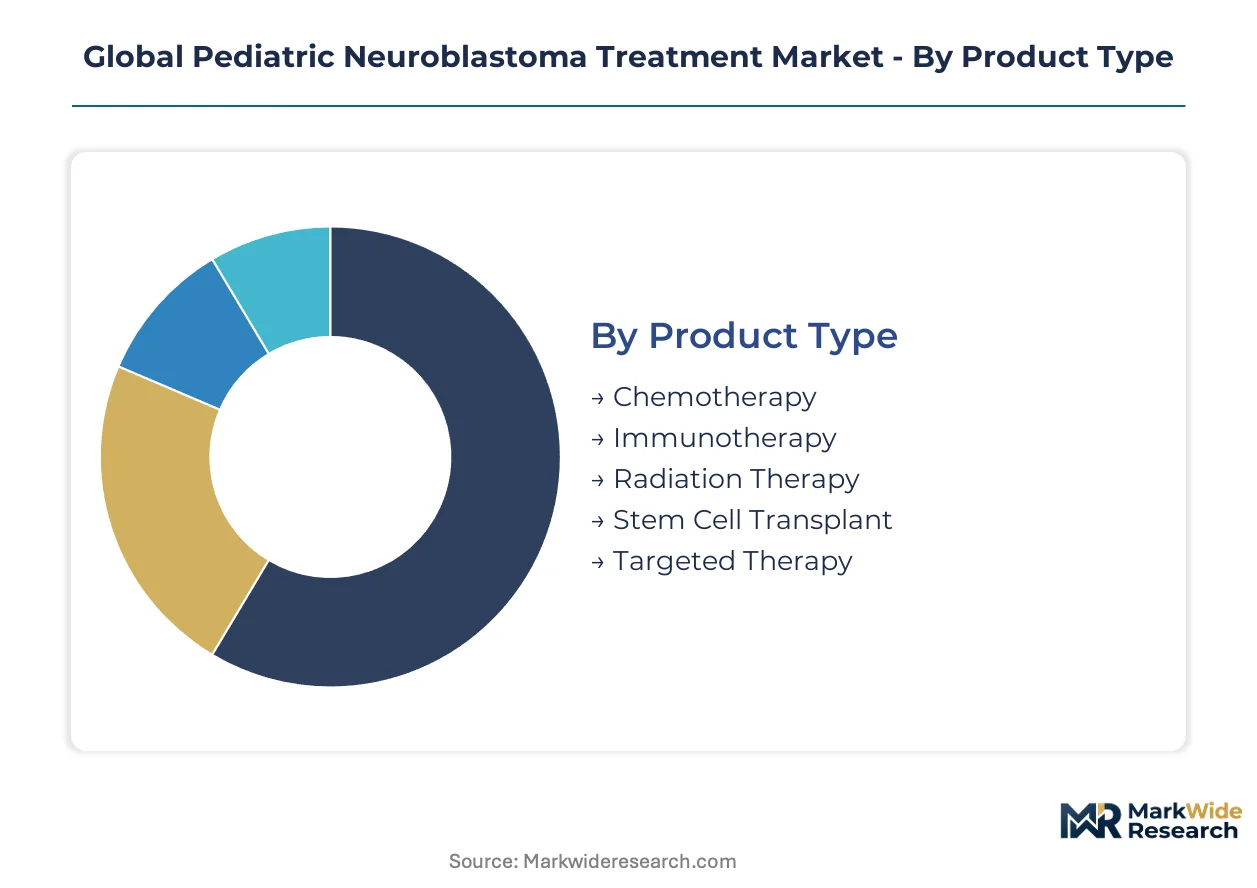
Pediatric neuroblastoma treatment protocols stratify across risk categories, product modalities, and institutional capabilities. Treatment selection hinges on MYCN amplification status, patient age, and tumor staging rather than cost alone. Each segment carries distinct regulatory, manufacturing, and reimbursement requirements that shape competitive positioning.
Product Type:
Oncologists weigh efficacy evidence against toxicity profiles when selecting among available modalities, with immunotherapy gaining preference in intermediate-risk protocols.
- Immunotherapy:Anti-GD2 monoclonal antibodies deliver targeted cytotoxicity with reduced systemic burden versus multi-agent chemotherapy. Demand concentrates in United States pediatric oncology networks where FDA breakthrough designations have accelerated protocol adoption. The category captures the fastest margin expansion as frontline chemotherapy intensity compresses.
- Chemotherapy:Multi-agent regimens combining platinum compounds, alkylators, and topoisomerase inhibitors remain foundational for high-risk induction. Manufacturing scale concentrates with captive biologics producers serving major children's hospital systems in Germany and the United States.
- Radiation Therapy:External beam and I-131-MIBG protocols target residual disease post-surgical resection.
- Stem Cell Transplant:Autologous hematopoietic rescue follows myeloablative conditioning in consolidation-phase protocols.
- Targeted Therapy:ALK inhibitors and retinoid derivatives address molecular subsets with defined genomic alterations.
Immunotherapy leads on momentum; chemotherapy retains scale dominance across all risk strata.
Therapy Area:
Risk stratification determines treatment intensity, with genomic biomarkers now driving protocol selection beyond anatomical staging alone.
- High-Risk Neuroblastoma:MYCN-amplified or metastatic disease requires intensive multimodal therapy spanning induction, consolidation, and maintenance phases. Clinical trial volume concentrates in United States cooperative groups and European pediatric oncology networks.
- Refractory Neuroblastoma:Relapsed or progressive disease after frontline therapy commands orphan drug pricing with limited therapeutic alternatives. Patient accrual challenges in France and Italy have prompted adaptive trial designs.
- Intermediate-Risk Neuroblastoma:Localized disease with favorable biology permits chemotherapy de-escalation.
- Low-Risk Neuroblastoma:Observation or surgical resection alone suffices for perinatal tumors with spontaneous regression potential.
High-risk neuroblastoma anchors clinical trial investment; refractory neuroblastoma offers the steepest pricing premiums.
End User:
Institutional capabilities determine patient access to advanced modalities, with consolidated networks extracting volume-based concessions.
- Specialized Children's Hospitals:Comprehensive pediatric oncology centers integrate surgery, stem cell transplant, and radiopharmaceutical therapy under single accreditation. United States networks in the Northeast and Midwest control majority patient volume and anchor FDA trial recruitment.
- Oncology Clinics:Community and regional facilities manage lower-risk protocols and supportive care. German and French reimbursement frameworks concentrate advanced therapy authorization at designated reference centers.
- Research Institutions:Academic medical centers conduct early-phase trials and biomarker validation studies.
- Pediatric Centers:General hospitals with pediatric oncology units handle initial diagnosis and stabilization.
Specialized children's hospitals capture the most complex cases; oncology clinics expand access across broader geographies.
Delivery Mode:
Route selection balances pharmacokinetic requirements against patient tolerance and caregiver burden in pediatric populations.
- Intravenous:Continuous or intermittent infusion dominates antibody delivery and cytotoxic chemotherapy administration. United States home infusion services are expanding to reduce hospitalization duration for maintenance protocols.
- Oral:Retinoid maintenance and targeted small molecules offer outpatient convenience. Compliance challenges in younger patients have prompted formulation innovations in Japan and European markets.
- Subcutaneous:Cytokine and supportive care agents enable home administration.
- Intrathecal:CNS prophylaxis and treatment require specialized neuraxial delivery capabilities.
- Continuous Infusion:Protracted 24-hour or multi-day schedules optimize cell-cycle-specific agents.
Intravenous delivery dominates biologics volume; oral formulations are gaining share fastest in maintenance settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States pediatric oncology networks anchor clinical trial recruitment and immunotherapy protocol adoption. Specialized children's hospitals in Boston, New York, and Philadelphia concentrate patient volume and FDA breakthrough therapy designations. Manufacturing scale for antibody-drug conjugates clusters around Massachusetts and California biologics corridors.
United States
FDA accelerated approval pathways compress Phase II-to-approval timelines for high-risk neuroblastoma indications. The Orphan Drug Act provisions grant seven-year market exclusivity to developers addressing pediatric populations under 200,000 patients. Memorial Sloan Kettering Cancer Center and Dana-Farber Cancer Institute anchor cooperative group trials for anti-GD2 monoclonal antibodies.
Germany
EMA pediatric investigation plans reshape market access conditions for novel radiolabeled constructs. The country's national pharmaceutical regulator, BfArM, coordinates with G-BA on early benefit assessments for CAR-T and antibody therapies. Heidelberg and Berlin pediatric oncology centers qualify single-source radiopharmaceutical suppliers with dedicated cGMP suites.
Japan
PMDA's Sakigake designation system offers priority review for innovative pediatric oncology mechanisms. The Ministry of Health, Labour and Welfare expanded reimbursement pathways for antibody-drug conjugates in 2023. Tokyo and Osaka pediatric cancer centers are expanding immunotherapy adoption through university hospital networks.
France
ANSM enforces REACH authorization requirements for novel chemical entities in radiopharmaceutical manufacturing. The Haute Autorité de Santé applies distinct cost-effectiveness thresholds to CAR-T therapies, delaying uniform access. Lyon and Paris pediatric oncology reference centers concentrate advanced therapy authorization and trial recruitment.
United Kingdom
NICE technology appraisals determine commercial viability for neuroblastoma therapeutics across England and Wales. The MHRA's post-Brexit recognition routes with FDA and EMA create parallel submission pathways. London and Manchester children's hospital networks control majority patient volume and extract volume-based rebates from biologics manufacturers.
Global Pediatric Neuroblastoma Treatment Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and radiopharmaceutical infrastructure. Large-cap biopharmaceutical corporations retain captive antibody production networks, while mid-tier developers concentrate on radiolabeled constructs for refractory indications. Three archetypes dominate: vertically integrated oncology biologics manufacturers, radiopharmaceutical specialists with isotope supply relationships, and emerging immunotherapy developers with orphan-drug portfolios. Competitive moves center on manufacturing capacity expansion and companion diagnostic integration.
Among established biopharmaceutical developers, Pfizer exemplifies scale-driven manufacturing archetypes with captive production networks. Bayer AG occupies a position within radiopharmaceutical infrastructure, leveraging isotope delivery capabilities for targeted therapy. Y-mAbs Therapeutics represents the emerging immunotherapy specialist tier, concentrating on radiolabeled antibody constructs for pediatric indications.
| Leading Market Players |
|---|
| Cellectar Biosciences |
| Pfizer |
| United Therapeutics Corporation |
| MacroGenics |
| Bayer AG |
| APEIRON Biologics AG |
| Y-mAbs Therapeutics |
| Sartorius AG |
| Baxter International |
| Others |
Supply & Pricing Matrix
Isotope procurement costs cascade through radiopharmaceutical pricing tiers, with molybdenum-99 reactor capacity in Canada and the Netherlands determining downstream I-131-MIBG therapy availability for United States pediatric oncology centers. Cold-chain logistics for antibody-drug conjugates add geographic premiums that specialized children's hospital networks negotiate through consolidated volume commitments.
Pricing Analysis
Input-cost pass-through from isotope supply constraints shapes radiolabeled therapy pricing, with molybdenum-99 production limitations forcing tiered premium-mid-economy pricing differentiation across institutional buyers. Price differentiation hinges on GD2 expression assay bundling and orphan drug designation status, with refractory neuroblastoma segments showing lowest price sensitivity due to limited therapeutic alternatives. Pricing pressure stems from consolidated buying through children's hospital group purchasing organizations in the Northeast and Midwest United States. Community oncology clinics exhibit highest price sensitivity, driving demand for standardized chemotherapy regimens over immunotherapy protocols.
Supply Chain Analysis
Domestic-content mandates in European radiopharmaceutical manufacturing reshape sourcing, with REACH authorization requirements and EMA good manufacturing practice inspections emphasizing isotope traceability that favors single-source suppliers with dedicated cGMP suites. Supply concentrates in United States biologics corridors around Massachusetts and California for antibody-drug conjugates, and in Germany and the Netherlands for radiochemistry infrastructure. Raw material dependencies include molybdenum-99 for isotope generation, single-use bioreactor components for antibody production, and specialized cold-chain packaging for conjugate stability. Single-source vulnerability concentrates around aging nuclear reactors for isotope supply. Distribution runs through children's hospital group purchasing organizations and qualified radiopharmaceutical networks with dedicated delivery capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pediatric neuroblastoma treatment represents a late-cycle quality story where demand consolidates toward premium immunotherapy specifications as anti-GD2 monoclonal antibodies displace frontline chemotherapy intensity in intermediate-risk protocols.
For Market Incumbents: To counter manufacturing scale limitations that constrain mid-tier developer output, large-cap biopharmaceutical corporations should expand captive antibody production capacity in Massachusetts and California biologics corridors. Backward integration into single-use bioreactor supply and companion diagnostic development for GD2 expression assays reinforces protocol positioning against emerging radiolabeled construct competitors.
For New Entrants and Emerging Players: Community oncology clinics in Germany and France present underserved buyer archetypes where reimbursement fragmentation delays uniform access to CAR-T and radiolabeled therapies. White-space targets include oral retinoid formulations for maintenance protocols and subcutaneous cytokine delivery for home administration. A go-to-market angle anchored in compliance support for divergent EMA and FDA pediatric investigation plans unlocks Atlantic market entry.
For Investors and Strategic Acquirers: Consolidation pressure builds where radiopharmaceutical infrastructure scarcity intersects with orphan drug pricing premiums in refractory neuroblastoma segments. Long-term viability over the next decade favors vertically integrated developers combining antibody manufacturing with isotope supply relationships. The signal to watch is PMDA Sakigake designation uptake signaling Asia-Pacific expansion readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | GD2 expression assays create test-and-treat revenue streams alongside antibody delivery. |
| Radiopharmaceutical Infrastructure Expansion | Dedicated cGMP suites in Heidelberg and Berlin qualify single-source isotope suppliers. |
| Regulatory Pathway Optimization | EMA pediatric investigation plans and FDA breakthrough designations compress development timelines. |
| Manufacturing Scale-Up | Captive bioreactor capacity in United States biologics corridors constrains mid-tier competitors. |
| Asia-Pacific Market Entry | PMDA Sakigake designation unlocks priority review for innovative pediatric oncology mechanisms. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors at children's hospital systems, and payer access specialists with secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient population modeling and top-down market sizing triangulated across therapy area, risk stratification, and product modality dimensions.
Comparable-period anchoring established historical baselines against which projection assumptions were stress-tested across the analysis window, with segmentation modeling spanning treatment line, administration route, patient risk category, and regional regulatory cluster. CAGRs derived from epidemiological trend analysis, protocol adoption curves, and pricing elasticity estimates incorporated immunotherapy penetration rates and radiopharmaceutical supply constraints as industry-specific forecast inputs.
Underlying measurement precision varies by segment; high-risk neuroblastoma carries tighter precision due to cooperative group trial transparency than refractory segments where patient accrual challenges complicate endpoint validation. Forecasts reflect documented assumptions regarding regulatory approval timelines and isotope supply continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pediatrics
Middle East and Africa Pediatric Healthcare Market
Pediatrics
Paediatric Wheelchairs Market
Pediatrics
Pediatric Brain Tumor Market
Pediatrics
Pediatric Obesity Management Market
Pediatrics
Pediatric Chronic Rhinosinusitis Market
Pediatrics
Paediatric Influenza Treatment Market
Pediatrics
Pediatrics Medicine Market
Pediatrics
Paediatric Spasticity Treatment Market
Pediatrics
Pediatric Catheter Market
Pediatrics
Global Pediatric Home Healthcare Services Market
Pediatrics
Pediatric Growth Hormone Deficiency Market
Pediatrics
Global Cerebral Palsy Treatment Market
Pediatrics
Pediatric Home Healthcare Market
Pediatrics
Pediatric Mattress Market
Pediatrics
Pediatric Asthma Treatment Market
Pediatrics
Pediatric Nasal Cannula Market