
 Pediatric Asthma Treatment Market | 2026-2036
Pediatric Asthma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Pediatric Asthma Treatment Market Analytics
A shortage of board-certified pediatric pulmonologists is redrawing competitive dynamics across developed markets. GlaxoSmithKline leverages its respiratory heritage to sustain dominance in inhaled corticosteroid portfolios. AstraZeneca anchors its position through biologic specialization in severe eosinophilic asthma among school-aged children. Merck & Co. competes via leukotriene modifier platforms that occupy distinct reimbursement tiers.
Pediatric asthma treatment encompasses pharmacological interventions designed to control airway inflammation and bronchospasm in patients under eighteen years, typically administered through metered-dose inhalers with valved holding chambers or nebulized solutions adjusted for tidal volume. The primary purpose is to prevent exacerbations, preserve lung function, and enable normal activity participation during critical developmental years. Inhalers command the largest product type share due to established clinical guidelines and payer familiarity, while combination therapies represent the fastest-expanding segment as physicians seek simplified regimens for adherence-challenged populations. Dry powder inhalers face structural constraints in infants and toddlers where inspiratory flow rates remain insufficient, concentrating margin pools in solution-based delivery for younger age groups.
The FDA pediatric study requirements under the Pediatric Research Equity Act shape trial design and label expansion timelines for all entrants. EMA's Paediatric Regulation and WHO essential medicines listings for children create divergent access frameworks across markets. Stakeholders must monitor evolving payer evidence requirements for biologics versus small-molecule maintenance therapy.
Market Dynamics
FDA pediatric study requirements under PREA compress development timelines while simultaneously expanding addressable populations for biologic therapies, creating a structural tension between regulatory compliance costs and first-mover label advantages.
Growth Catalysts
- EMA Paediatric Regulation:The EU's pediatric investigation plans mandate early integration of child-specific endpoints, accelerating trial enrollment across member states and expanding reimbursable indications for severe asthma phenotypes.
- Specialist referral networks:Concentrated pediatric pulmonology clusters in the United States funnel patients toward advanced controller therapies, concentrating demand for biologic-eligible populations.
- Smart nebulizer connectivity:Bluetooth-enabled delivery devices capture adherence data for payers, enabling outcomes-based contracting with Medicaid programs and commercial insurers.
Market Restraints
- Propellant supply concentration:Hydrofluoroalkane manufacturing concentrates among three chemical suppliers, exposing metered-dose inhaler producers to input cost volatility and phase-down timelines under the Kigali Amendment.
- Dry powder technical limitation:Inspiratory flow rate requirements exclude children under five from DPI platforms, fragmenting product portfolios and forcing dual development tracks for pediatric indications.
- Substitution threat from leukotriene modifiers:Generic montelukast availability compresses pricing for maintenance therapy in mild-to-moderate segments, constraining revenue pools for novel biologic entrants.
Strategic Opportunities
- Underpenetrated India market:CDSCO streamlined pediatric trial guidelines and expanding private insurance penetration create entry pathways for combination inhaler platforms previously concentrated in Western markets.
- Home-based biologic administration:Subcutaneous auto-injector training protocols enable migration from infusion centers to caregiver-managed dosing, unlocking rural and suburban patient pools.
- Japan's pediatric orphan designation:PMDA's priority review vouchers for childhood asthma biologics accelerate approval timelines and extend market exclusivity periods for targeted eosinophilic phenotypes.
Industry Challenges
- Pediatric pulmonologist scarcity:Fellowship program output lags demand growth by approximately forty percent across the United States, constraining patient access to biologic qualification assessments and specialist referral throughput.
- Legacy device validation:Valved holding chamber design modifications for face-mask compatibility require extensive flow pattern testing, extending FDA 510(k) clearance timelines for infant-optimized delivery systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pediatric Asthma Treatment Market |
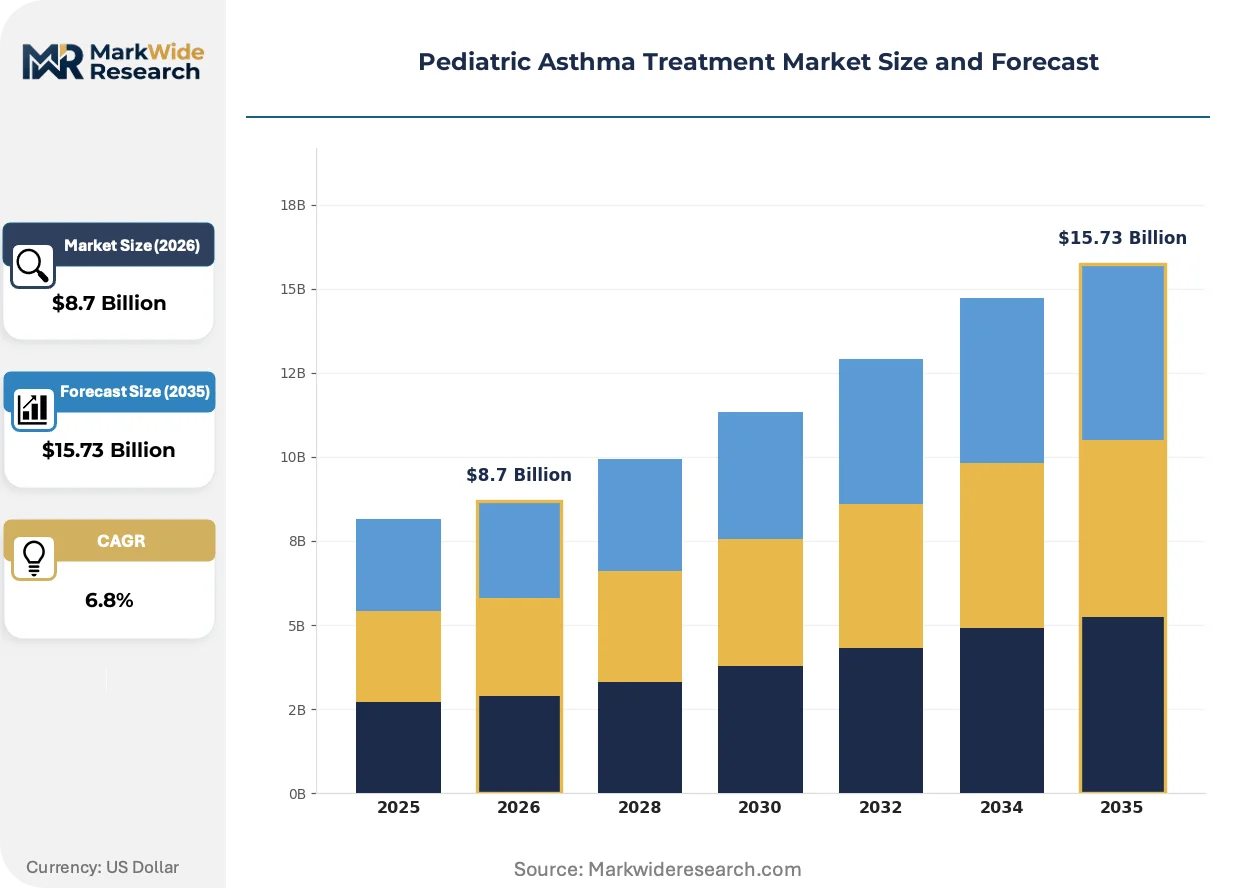
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Nebulizers, Oral Medications, Combination Therapies Delivery Mode: Metered-Dose Inhalers, Dry Powder Inhalers, Solution Inhalers, Tablets Age Group: Infants, Toddlers, Preschoolers, School-Aged Children Therapy Area: Bronchodilators, Corticosteroids, Leukotriene Modifiers, Others |
| Companies Covered | GlaxoSmithKline, AstraZeneca, Merck & Co., Teva Pharmaceutical Industries, Novartis AG, Sanofi, Chiesi Farmaceutici, F. Hoffmann-La Roche, Boehringer Ingelheim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pediatric Asthma Treatment Market Evolving Landscape
Connected inhaler ecosystems and biologic delivery automation are compressing the gap between clinical trial efficacy and real-world effectiveness, while regulatory pediatric mandates force earlier integration of age-appropriate endpoints into development programs.
Electronic dose counters with cellular transmission capabilities are supplanting mechanical pMDI indicators in Medicaid-preferred drug lists. Large pediatric asthma networks in Texas and California are deploying these devices to reduce emergency department utilization. The technology is supplanting traditional pharmacy claims data as the primary evidence source for payer prior authorization decisions.
REACH authorization requirements for persistent organic pollutants are pressuring manufacturers to reformulate pressurized inhaler propellants ahead of 2030 phase-down deadlines. German chemical producers are accelerating hydrofluoroolefin development timelines to maintain supply continuity. The regulation is forcing portfolio diversification among companies historically dependent on HFA-134a platforms.
Caregivers increasingly demand single-inhaler maintenance-and-reliever therapy regimens over traditional separate controller and rescue protocols. Pediatric practices in Florida and Ohio are converting stable patients to SMART protocols to simplify school-based medication administration. This behavioral shift concentrates volume share among combination budesonide-formoterol platforms and compresses monotherapy corticosteroid utilization.
Pediatric Asthma Treatment Market Segmentation
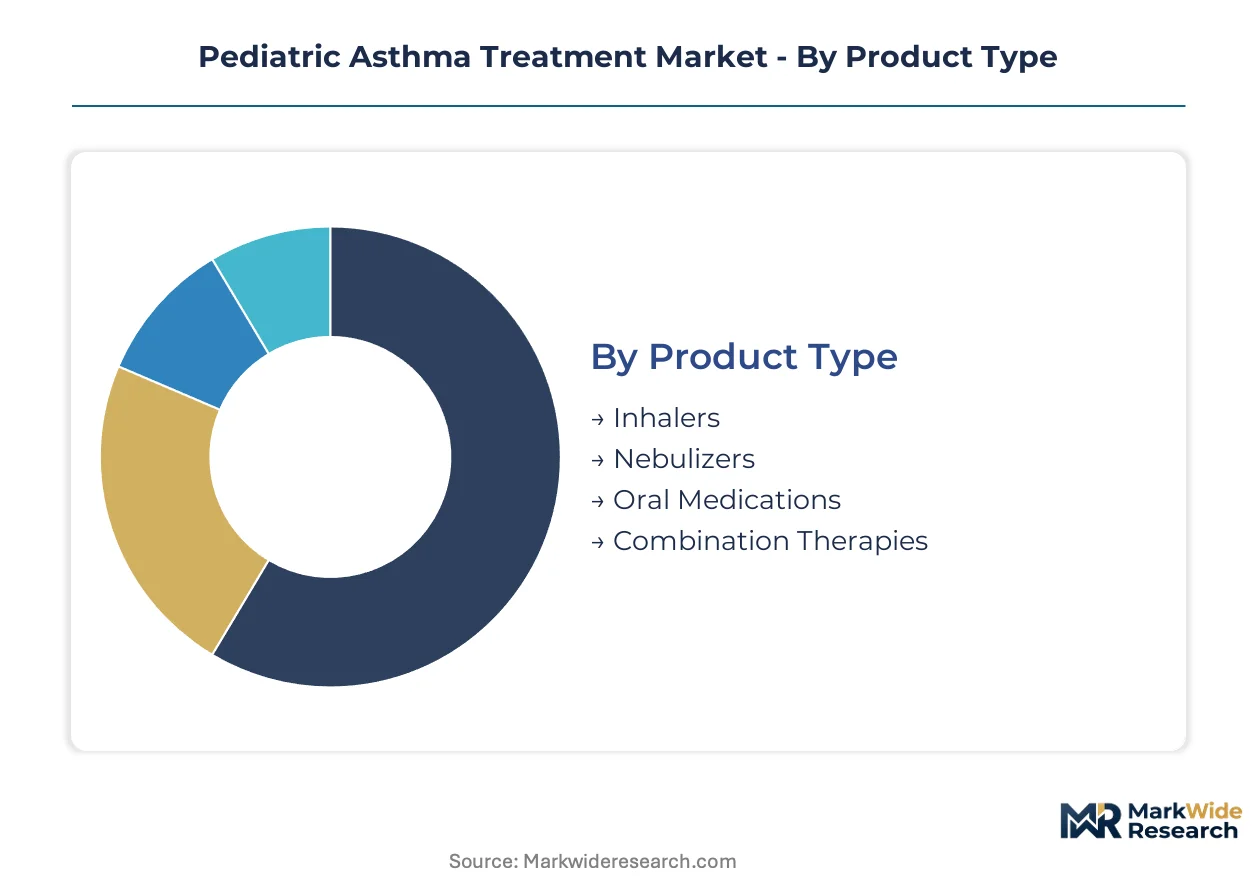
Pediatric asthma treatment markets fragment across device mechanics, patient physiology, and reimbursement tiers. Manufacturers optimize portfolios around age-specific delivery constraints and therapy escalation pathways.
Product Type:
Margin pools concentrate in devices with recurring medication attachment and connectivity features.
- Inhalers:Pressurized metered-dose devices with valved holding chambers dominate maintenance therapy for children over five. United States Medicaid programs favor electronic dose counters in preferred drug lists, concentrating volume share among connected platforms.
- Combination Therapies:Single-inhaler maintenance-and-reliever regimens simplify adherence for school-based administration. Florida and Ohio pediatric practices are converting stable patients to SMART protocols, accelerating share gains.
- Nebulizers:Compressor-driven or vibrating mesh devices serve infants and toddlers unable to generate sufficient inspiratory flow.
- Oral Medications:Chewable and liquid formulations address swallowing capability limitations in younger age groups.
The dominant share belongs to Inhalers, while Combination Therapies is closing the gap fastest.
Delivery Mode:
Technical feasibility for pediatric populations varies sharply by inspiratory mechanics and coordination development.
- Metered-Dose Inhalers:HFA-propelled devices with spacer attachments remain the clinical standard across most age groups. Kigali Amendment phase-down timelines are pressuring manufacturers toward hydrofluoroolefin alternatives.
- Solution Inhalers:Nebulized formulations bypass coordination requirements entirely, capturing margin pools in infant and toddler segments where dry powder platforms fail.
- Dry Powder Inhalers:Inspiratory flow rate thresholds exclude children under five, fragmenting portfolios and forcing parallel development tracks.
- Tablets:Oral solid dosing occupies limited pediatric asthma utility due to swallowing constraints and slower bronchodilation onset.
Metered-Dose Inhalers command installed base leadership, though Solution Inhalers are expanding most quickly in younger age brackets.
Age Group:
Developmental milestones dictate device compatibility and therapy complexity.
- Infants:Face-mask nebulization and caregiver-administered therapy dominate, with FDA 510(k) clearance timelines extended for valved holding chamber modifications.
- Toddlers:Transition zones where spacer-equipped MDIs begin replacing nebulizers for maintenance therapy.
- Preschoolers:Coordination development enables broader MDI adoption, though adherence challenges persist.
- School-Aged Children:Biologic eligibility assessments concentrate in this bracket, with specialist referral networks funneling severe eosinophilic phenotypes toward advanced controller therapies.
School-Aged Children generates the largest addressable population for biologic therapies, while Infants drives specialized device innovation.
Therapy Area:
Reimbursement tiering separates maintenance controllers from rescue medications and biologic interventions.
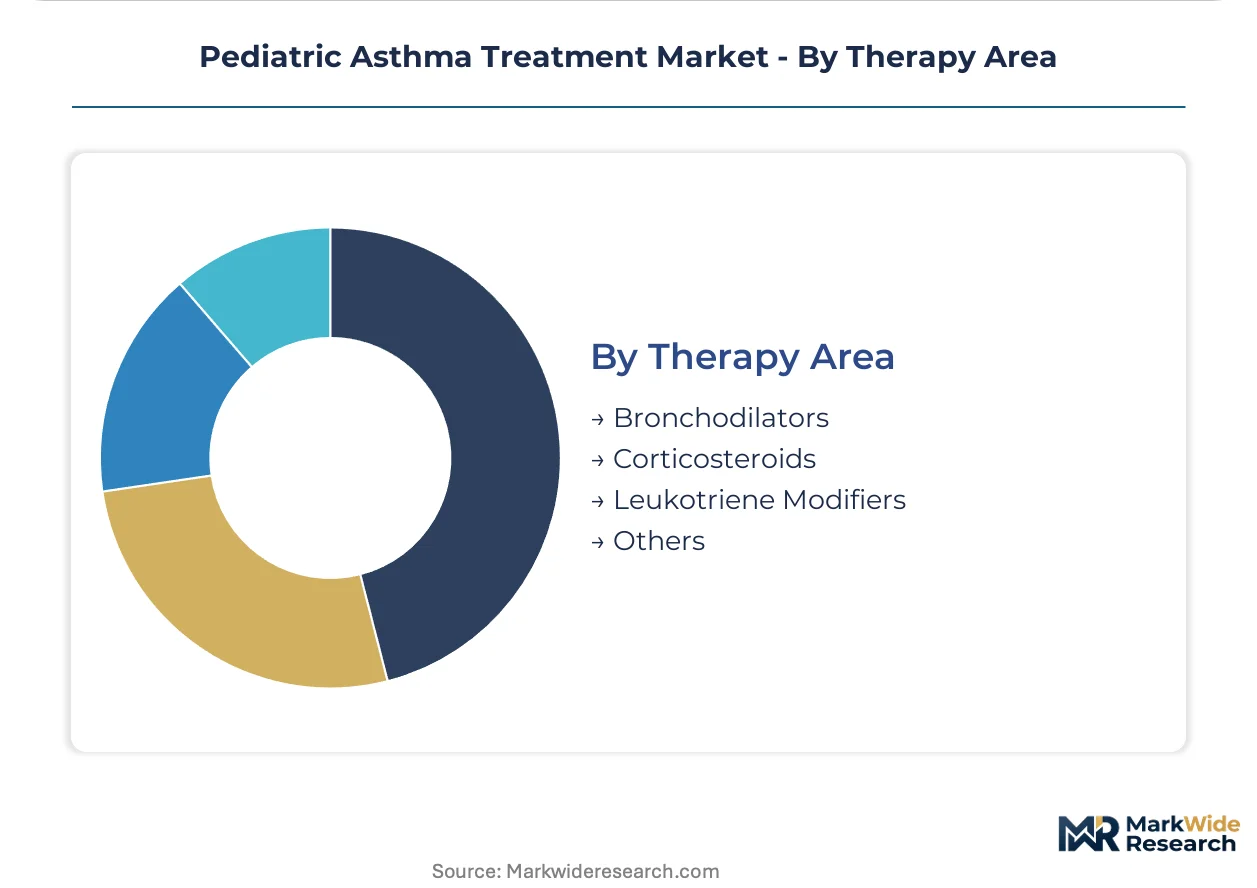
- Corticosteroids:Inhaled anti-inflammatory agents form the maintenance backbone across all severity classifications. United States commercial and Medicaid formularies stratify preferred status by generic availability and device connectivity.
- Leukotriene Modifiers:Oral montelukast availability in generic form compresses pricing in mild-to-moderate segments, constraining adjacent novel therapy pricing power.
- Bronchodilators:Short-acting beta-agonists serve acute rescue indications, with SMART protocols repositioning some long-acting formulations into maintenance-reliever combinations.
- Others:Biologic monoclonal antibodies targeting IL-5, IL-4/13, and IgE pathways occupy distinct prior authorization tiers for severe, refractory cases.
Corticosteroids anchor volume leadership, while biologics within Others are climbing the fastest despite restricted eligibility pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA pediatric study requirements under PREA anchor the United States as the dominant geography, while EMA Paediatric Regulation and Japan's PMDA orphan designations create parallel development tracks across major markets.
United States
Specialist referral networks in Texas and California concentrate biologic-eligible patients into pediatric pulmonology clusters. FDA accelerated approval pathways compress development timelines for severe eosinophilic asthma indications. Large provider networks in Florida and Ohio are converting stable patients to SMART protocols, reshaping prescribing patterns.
Germany
REACH authorization requirements for persistent organic pollutants are pressuring manufacturers to reformulate pressurized inhaler propellants ahead of 2030 deadlines. German chemical producers are accelerating hydrofluoroolefin development timelines. Industrial concentration in the Rhine-Ruhr region maintains supply continuity for HFA-134a alternatives.
Japan
PMDA priority review vouchers for childhood asthma biologics accelerate approval timelines and extend market exclusivity periods. METI industrial policy supports domestic production of connected inhaler devices. The Kanto region around Tokyo hosts the principal concentration of pediatric respiratory specialists qualifying patients for advanced therapies.
India
CDSCO streamlined pediatric trial guidelines and expanding private insurance penetration create entry pathways for combination inhaler platforms. DGFT import regulations shape device availability for nebulizer-dependent infant populations. Maharashtra and Karnataka host the principal private hospital networks driving biologic therapy adoption.
United Kingdom
NICE technology appraisals stratify reimbursement access for biologic versus small-molecule maintenance therapy. The NHS Long Term Plan targets asthma exacerbation reduction through connected inhaler deployment. Greater London's academic medical centers anchor the country's severe asthma phenotype assessment capacity.
Pediatric Asthma Treatment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the pediatric asthma treatment market. Large multinational pharmaceutical groups with respiratory heritage dominate biologic and inhaled corticosteroid portfolios, while generic manufacturers capture volume in leukotriene modifier segments. The competitive structure stratifies into three archetypes: integrated respiratory specialists, biologic-focused innovators, and cost-optimized generic suppliers. Principal competitive moves include portfolio diversification into connected delivery devices and strategic partnerships with digital health platforms for adherence monitoring.
Within the integrated respiratory specialist tier, GlaxoSmithKline and AstraZeneca occupy positions anchored by decades of pediatric development experience. GlaxoSmithKline represents the archetype of heritage-led portfolio breadth spanning maintenance controllers to rescue therapies. AstraZeneca exemplifies biologic specialization strategy targeting severe eosinophilic phenotypes in school-aged populations. Merck & Co. sits within the distinct reimbursement tier occupied by leukotriene modifier platforms, representing cost-accessible maintenance therapy for mild-to-moderate segments.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| AstraZeneca |
| Merck & Co. |
| Teva Pharmaceutical Industries |
| Novartis AG |
| Sanofi |
| Chiesi Farmaceutici |
| F. Hoffmann-La Roche |
| Boehringer Ingelheim |
| Others |
Value Network & Pricing Analysis
Hydrofluoroolefin propellant substitution for legacy hydrofluoroalkane formulations is redrawing manufacturing geography toward German chemical producers while simultaneously compressing input cost differentials between European and Asian metered-dose inhaler suppliers.
Pricing Analysis
United States Medicaid reimbursement rates for pediatric asthma devices run 15-25 percent above German statutory health insurance ceilings, creating arbitrage pressure on cross-border procurement strategies. Pricing stratifies across connected-device premium tiers, standard electronic-dose-counter platforms, and economy mechanical-inhaler categories, with connectivity certification serving as the primary quality-grade differentiator. Cost compression in the leukotriene modifier segment is intensifying because generic montelukast saturation eliminates brand pricing power. Hospital procurement committees exhibit highest price sensitivity, while specialist pediatric pulmonology clinics demonstrate lowest sensitivity due to outcomes-based contracting preferences.
Supply Chain Analysis
Strategic stockpiling of hydrofluoroalkane propellants dominates inventory strategy among metered-dose inhaler manufacturers facing Kigali Amendment phase-down deadlines, contrasting with just-in-time API sourcing for oral solid formulations. Active pharmaceutical ingredient production concentrates in India, China, and Switzerland, with device assembly tethered to Germany, Ireland, and the United States. Propellant chemistry, specialized elastomer seals, and precision-molded plastics constitute critical input dependencies. Single-source vulnerability in HFA-134a manufacturing exposes producers to supply interruption. Distribution runs through hospital purchasing organizations, retail pharmacy chains, and direct-to-clinic specialty distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biologic therapy penetration in school-aged severe asthma populations remains below 30 percent across major markets, creating substantial runway for expansion as specialist referral networks widen access qualification.
For Market Incumbents: Fortify position through backward integration into connected-device manufacturing and captive hydrofluoroolefin propellant supply agreements with Rhine-Ruhr chemical producers. Generic leukotriene modifier erosion threatens maintenance-therapy margins, demanding accelerated biologic label expansion into preschool populations. FDA pediatric study requirements under PREA compress development timelines, rewarding first-mover investments in infant-optimized valved holding chamber platforms. For New Entrants and Emerging Players: Lead with home-based biologic administration protocols targeting rural and suburban patient pools underserved by infusion center geography. India's private hospital networks in Maharashtra and Karnataka represent the most penetrable geography, with CDSCO streamlined trial guidelines lowering regulatory entry barriers. Partner with digital health platforms for Bluetooth-enabled adherence monitoring to secure Medicaid outcomes-based contracting. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed respiratory device specialists holding FDA-cleared infant delivery platforms but lacking biologic therapy portfolios. Long-term viability hinges on capturing share in the combination-therapy escalation pathway as SMART protocols displace monotherapy corticosteroids. Watch FDA accelerated approval decisions for eosinophilic asthma biologics as the inflection indicator for specialist referral network expansion rates.| Strategic Initiative | Industry Significance |
|---|---|
| Biologic Label Expansion | FDA pediatric indications for severe eosinophilic asthma widen addressable populations in school-aged children. |
| Connected Device Development | Bluetooth-enabled inhalers with cellular dose transmission secure Medicaid preferred-drug-list positioning in Texas and California. |
| Propellant Chemistry Transition | Hydrofluoroolefin formulation investment ahead of Kigali Amendment deadlines preserves supply continuity for pressurized devices. |
| Home Administration Training Protocols | Subcutaneous auto-injector caregiver education unlocks rural patient pools beyond infusion center catchment areas. |
| Specialist Network Partnerships | Pediatric pulmonology cluster alliances in Florida and Ohio accelerate SMART protocol conversion and combination therapy share. |
Research Methodology
Operator-level perspectives from pediatric pulmonologists, formulary directors at Medicaid managed care organizations, medical device regulatory affairs leads, and pharmaceutical payer access specialists anchored the qualitative base. Primary interview findings were cross-validated against FDA 510(k) clearance databases, EMA pediatric investigation plan submissions, CMS Medicare Part D utilization data, and hospital GPO contract repositories. Bottom-up patient-volume modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Sensitivity analysis around biologic eligibility expansion rates and propellant phase-down timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, delivery mode, age group, and therapy area, with regional regulatory clusters capturing FDA, EMA, PMDA, and CDSCO pathway differences. CAGRs were derived from log-linear trend fitting to historical utilization trajectories, with inputs including specialist referral network density, private insurance penetration curves, and connected device adoption slopes.
Forecasts assume regulatory continuity in FDA pediatric study requirements, EMA Paediatric Regulation, and Japan's PMDA orphan designation framework; material policy shifts would require re-modeling. Revision becomes warranted when biologic prior authorization approval rates or hydrofluoroolefin manufacturing scale-up timelines cross threshold deviations from baseline assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pediatrics
Paediatric Wheelchairs Market
Pediatrics
Pediatric Home Healthcare Market
Pediatrics
Pediatric MRI Market
Pediatrics
Global Pediatric Radiology Market
Pediatrics
Pediatric Mattress Market
Pediatrics
Pediatric Oncology Treatment Market
Pediatrics
Pediatric HIV Infection Treatment Market
Pediatrics
Pediatric Healthcare Market
Pediatrics
Pediatric Chronic Rhinosinusitis Market
Pediatrics
Pediatric Nasal Cannula Market
Pediatrics
Global Pediatric Neuroblastoma Treatment Market
Pediatrics
OTC Pediatric Healthcare Market
Pediatrics
Paediatric Spasticity Treatment Market
Pediatrics
Middle East and Africa Pediatric Healthcare Market
Pediatrics
Pediatrics Medicine Market
Pediatrics
Paediatric Neuropsychiatric Disorders Treatment Market