
 Pediatric Home Healthcare Market | 2026-2036
Pediatric Home Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Pediatric Home Healthcare Market Intelligence
Asset-light franchising and managed service organization models are reshaping capital deployment across pediatric home healthcare, allowing regional operators to scale without owning clinical assets. Aveanna Healthcare leverages its multi-state platform to sustain geographic density in high-Medicaid states. BAYADA Home Health Care anchors quality metrics that differentiate its nursing recruitment. Angels of Care Pediatric Home Health specializes in complex-care cases that command longer visit durations and higher reimbursement tiers.
Pediatric home healthcare encompasses skilled nursing, therapy, medical equipment provisioning, and care coordination delivered in a child's residence rather than institutional settings, with services typically prescribed by pediatric specialists and supervised by licensed registered nurses. Its primary purpose is to maintain clinical stability for medically fragile children while preserving family unit integrity and reducing inpatient utilization. Nursing Care commands the largest revenue pool due to labor intensity and regulatory staffing mandates, while Telehealth delivery models represent the fastest-expanding channel as payers relax originating-site requirements. Remote Monitoring technology sits at the margin intersection where hardware subsidies and outcomes-based contracts create dual revenue streams for integrated providers.
CMS rules and state Medicaid plans govern reimbursement rates, visit authorizations, and provider enrollment criteria across the United States, directly determining which patient populations access subsidized home care. HIPAA privacy requirements and state nurse licensure compacts shape workforce mobility and technology architecture for multi-state operators. OSHA home healthcare safety guidelines influence worker training investments and liability exposure for employers dispatching staff to uncontrolled residential environments. Stakeholders must monitor how CMS's evolving hospital-at-home waivers and pediatric-specific value-based payment pilots redefine the boundary between reimbursable home services and family-borne caregiving burdens.
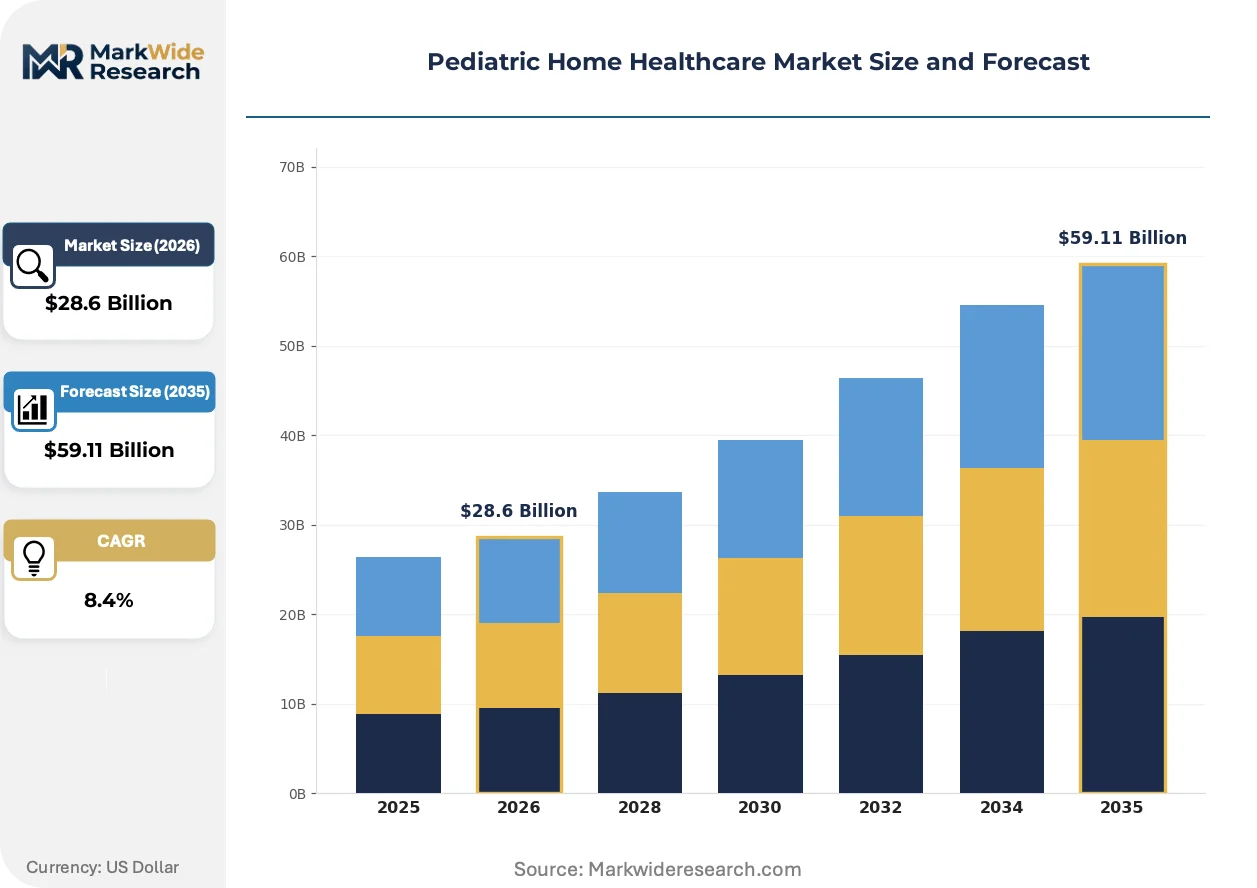
Market Dynamics
Medicaid waiver expansion across high-coverage states is compressing the institutional-to-home care boundary, forcing providers to reconfigure staffing models around episodic reimbursement rather than hourly nursing rates.
Growth Catalysts
- Medicaid 1915(c) Waivers:State-level program flexibility allows medically fragile children to access skilled nursing at home rather than hospitals, expanding eligible populations in Texas, California, and Florida.
- Pulse oximetry and respiratory monitoring:FDA-cleared pediatric devices enable continuous oversight of tracheostomy-dependent patients, reducing emergency department utilization for ventilator alarms.
- Texas Medicaid STAR Kids:The state's dedicated managed care program for children with disabilities creates predictable authorization pathways, concentrating provider investment in Dallas-Fort Worth and Houston corridors.
Market Restraints
- Registered nurse wage compression:Hospital systems in metropolitan Texas markets absorb pediatric specialty nurses through shift differentials, elevating home health agency recruitment costs.
- CMS originating-site requirements:Federal telehealth restrictions limit synchronous video reimbursement to rural health professional shortage areas, constraining urban deployment of remote patient monitoring.
- Family caregiver substitution:Uncompensated parental nursing labor for technology-dependent children displaces formal skilled nursing hours, particularly in states with narrow waiver income eligibility.
Strategic Opportunities
- Hospital-at-home waivers:CMS acute care episode pilots for pediatric populations create reimbursement pathways for home-based IV antibiotics and post-surgical recovery previously confined to inpatient units.
- Behavioral health integration:Convergence of applied behavior analysis and skilled nursing addresses dual-diagnosis children with autism and seizure disorders, opening higher-reimbursement care coordination tiers.
- Direct-to-employer contracting:Self-insured corporations with concentration of Medicaid-eligible employees in Texas manufacturing corridors seek carve-out pediatric home health arrangements.
Industry Challenges
- Pediatric ventilator competency certification:State licensure boards lack standardized training reciprocity, forcing multi-state operators to duplicate clinical education investments across jurisdictions.
- Electronic visit verification mandates:Texas HHSC real-time location tracking requirements introduce IT infrastructure costs that fragment margin structures for sub-scale regional agencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pediatric Home Healthcare Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Nursing Care, Medical Equipment, Therapy Services, Medical Supplies Patient Type: Chronic Illness, Post-Surgical, Developmental Disorders, Disability Delivery Model: Home Health Agencies, Private Duty, Telehealth, Community-Based Services Technology: Remote Monitoring, EHR Systems, Mobile Health Apps, Assistive Devices |
| Companies Covered | Maxim Healthcare Services, Care Options for Kids, Aveanna Healthcare, At Home Healthcare, Pediatric Home Healthcare, BAYADA Home Health Care, Angels of Care Pediatric Home Health, Entrusted Pediatric Home Care, Pediatric Home Service, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pediatric Home Healthcare Market Strategic Shifts & Innovations
Technology convergence between remote physiological monitoring and predictive analytics is restructuring how pediatric home health operators allocate nursing labor across geographically dispersed patient panels.
Bluetooth-enabled pulse oximeters and capnography devices are collapsing the distinction between scheduled nursing visits and continuous oversight. Pediatric pulmonology practices in Texas deploy these sensors for tracheostomy-dependent patients, compressing emergency intervention timelines from hours to minutes. The resulting data streams enable outcomes-based contracts with Medicaid managed care organizations that shift payment from visit volume to stability metrics.
CMS hospital-at-home waivers issued through the Center for Medicare and Medicaid Innovation are expanding reimbursable service intensity for acute-level pediatric care. Texas Medicaid's concurrent adoption of these standards permits home administration of intravenous antibiotics and complex wound care previously requiring inpatient admission. Pediatric home health agencies with hospital partnerships are restructuring intake protocols to capture these higher-acuity discharges.
Family caregivers are assuming technical nursing functions previously restricted to licensed personnel, driven by nursing shortage-induced authorization delays. Texas Medicaid's family-directed services option permits parental training on ventilator management and gastrostomy tube care, displacing skilled nursing hours for stable patients. This behavioral shift concentrates formal nursing deployment on acute exacerbation episodes rather than maintenance monitoring.
Pediatric Home Healthcare Market Segmentation
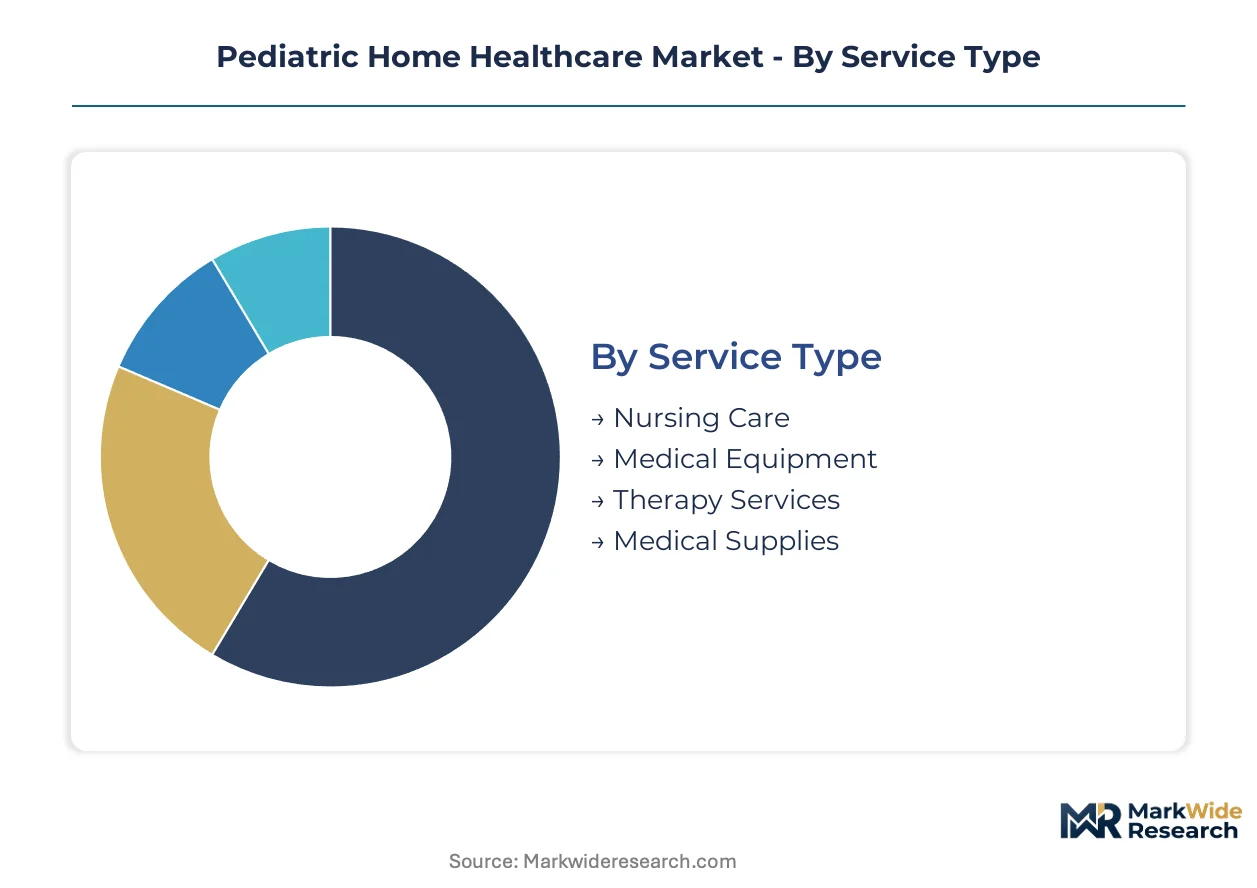
Pediatric home healthcare segmentation reveals distinct reimbursement pathways and clinical intensity profiles that dictate provider investment priorities. Service type and patient acuity determine staffing ratios, while delivery model selection shapes regulatory compliance burdens across state Medicaid programs.
Service Type:
Cost tier differentiation separates labor-intensive skilled services from commoditized supply provisioning, with reimbursement rates scaling directly to clinical complexity and regulatory oversight depth.
- Nursing Care:Licensed registered nurses deliver ventilator management, medication administration, and wound care under physician supervision. Texas Medicaid STAR Kids authorizations concentrate demand in Dallas-Fort Worth and Houston corridors where pediatric pulmonology practices maintain dense referral networks. CMS staffing mandates and state licensure compacts elevate labor costs above other service categories.
- Medical Equipment:Durable medical equipment encompasses ventilators, feeding pumps, oxygen concentrators, and mobility aids with FDA-cleared pediatric specifications. Home medical equipment suppliers in high-Medicaid states capture recurring rental revenue streams tied to authorization renewals. Equipment provisioning operates on thinner margins than skilled services but generates predictable cash flow through multi-month rental cycles.
- Therapy Services:Physical, occupational, and speech therapy address developmental delays and post-surgical rehabilitation needs.
- Medical Supplies:Disposable items including catheters, tracheostomy tubes, and nutritional formulas complete the clinical supply chain.
Nursing Care holds installed capacity. Medical Equipment is rotating up the share rankings.
Patient Type:
Application focus varies sharply across acuity spectrums, with technology-dependent children requiring 24-hour skilled oversight while developmental disorder cases emphasize therapy intensity over nursing hours.
- Chronic Illness:Technology-dependent children with congenital heart defects, neuromuscular disorders, and respiratory insufficiency consume the highest nursing hour volumes per patient. Texas waiver programs specifically target this population for institutional diversion, creating concentrated demand in metropolitan corridors with established pediatric specialty hospitals.
- Developmental Disorders:Autism spectrum disorders and intellectual disabilities drive applied behavior analysis and skilled nursing convergence for dual-diagnosis children. Applied behavior analysis providers in Florida and California are expanding into skilled nursing coordination for seizure management and medication compliance.
- Post-Surgical:Short-duration recovery episodes following cardiac procedures, orthopedic interventions, and organ transplants.
- Disability:Physical and cognitive impairments requiring adaptive equipment and environmental modifications.
Chronic Illness commands the deepest nursing penetration. Developmental Disorders is climbing the fastest.
Delivery Model:
Customer type segmentation distinguishes between institutional referral pathways and family-directed service arrangements, with Medicaid waiver structure determining which models dominate state-by-state.
- Home Health Agencies:Medicare-certified agencies deliver skilled nursing and therapy under physician plans of care with episodic reimbursement. These agencies in Texas maintain hospital discharge partnerships that capture acute-level pediatric cases through CMS hospital-at-home waiver pathways.
- Private Duty:Non-medical and skilled nursing services paid through private insurance, Medicaid waiver self-direction, or out-of-pocket arrangements. Private duty operators in California leverage family-directed services options to bypass traditional agency overhead while maintaining nursing quality through selective recruitment.
- Telehealth:Synchronous video and remote patient monitoring for rural health professional shortage areas.
- Community-Based Services:Respite care and skilled nursing in non-residential settings.
Home Health Agencies anchor the certified infrastructure. Private Duty is gaining share fastest through waiver expansion.
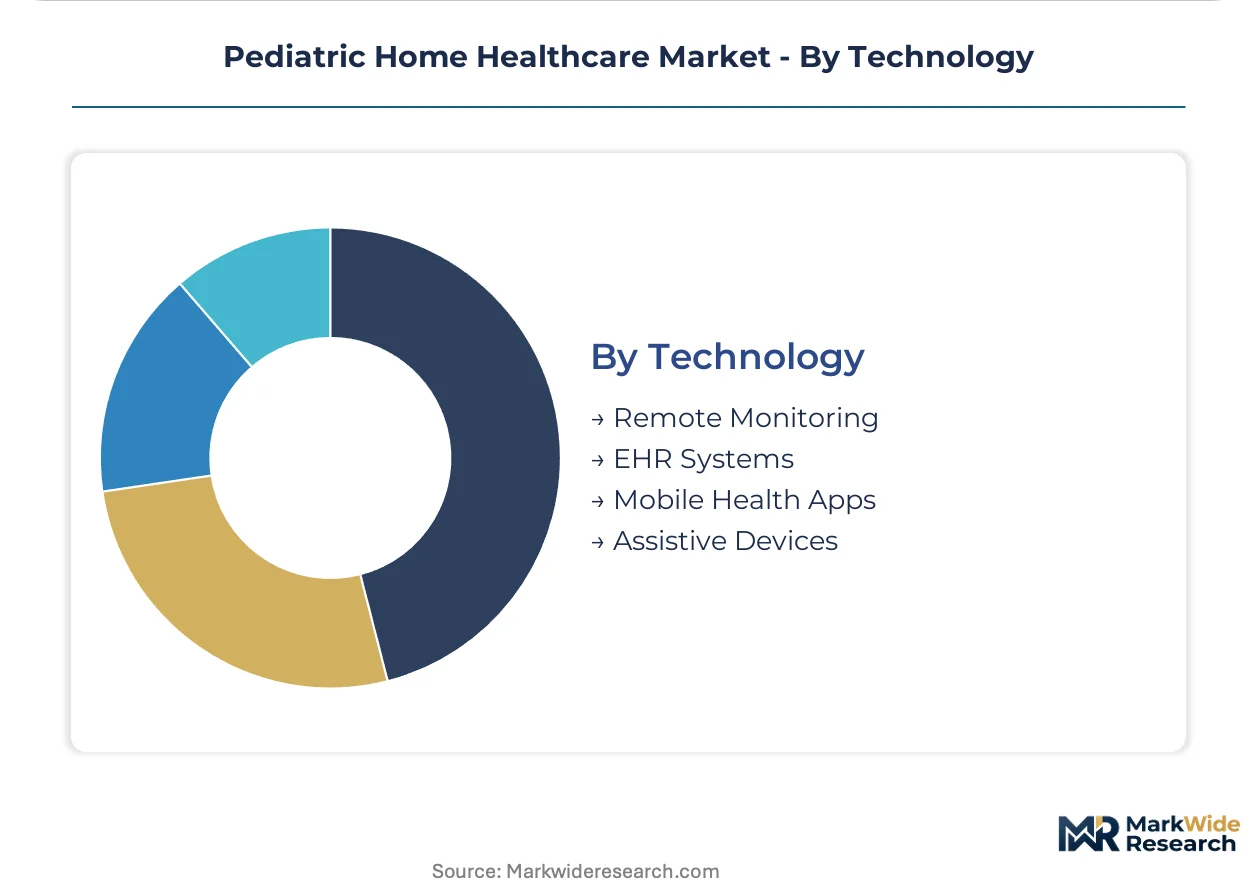
Technology:
Maturity gradients separate established EHR compliance investments from emerging remote monitoring deployments that reshape clinical labor allocation.
- Remote Monitoring:Bluetooth-enabled pulse oximeters, capnography devices, and cardiac monitors transmit continuous physiological data to centralized nursing stations. Pediatric pulmonology practices in Texas deploy these sensors for tracheostomy-dependent patients, compressing emergency intervention timelines and enabling outcomes-based contracts with Medicaid managed care organizations.
- EHR Systems:Electronic health records integrate scheduling, billing, and clinical documentation for multi-state compliance. EHR vendors serving pediatric home health are adapting platforms to Texas HHSC electronic visit verification mandates that require real-time location tracking and visit authentication.
- Mobile Health Apps:Caregiver-facing applications for symptom tracking and care coordination.
- Assistive Devices:Communication aids, environmental controls, and mobility equipment.
EHR Systems holds compliance-mandated deployment. Remote Monitoring is expanding most quickly through outcomes-based contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicaid waiver expansion and pediatric specialty hospital networks are concentrating demand in specific metropolitan corridors across high-coverage states. State-level program flexibility and managed care contracting structures determine where provider investment flows most heavily.
United States
Texas Medicaid STAR Kids and California's Home and Community-Based Services waivers serve technology-dependent children with congenital conditions. CMS hospital-at-home waivers permit acute-level pediatric care reimbursement outside institutional settings. Dallas-Fort Worth and Houston anchor dense provider ecosystems where pediatric pulmonology practices maintain referral networks for ventilator-dependent patients.
Germany
Statutory health insurance funds covering pediatric home nursing for children with severe disabilities drive demand in Baden-Württemberg and Bavaria. The country's national pharmaceutical regulator oversees medical device clearance for home-use respiratory equipment. Berlin-Brandenburg clusters telehealth infrastructure development for rural pediatric specialist access.
United Kingdom
NHS Continuing Care frameworks fund 24-hour skilled nursing for children with complex health needs. The Care Quality Commission regulates domiciliary pediatric services through inspection regimes. London and the Southeast concentrate private duty agencies serving families seeking supplemental nursing hours beyond NHS allocations.
France
HAS guidelines on hospital-at-home pediatric protocols expand reimbursable service intensity for post-surgical recovery. ANSM oversees pediatric medical device safety for home ventilation systems. Île-de-France hosts the highest density of accredited home health agencies serving medically fragile children.
Canada
Provincial health authority funding models in Ontario and British Columbia support family-directed care options for technology-dependent children. Health Canada regulates pediatric home medical equipment through pre-market licensing requirements. Toronto and Vancouver metropolitan areas concentrate nursing agencies with hospital discharge partnerships.
Pediatric Home Healthcare Market Key Industry Players
On the supply side, the industry is consolidating around multi-state platforms and specialized regional operators rather than fragmented local agencies. National players leverage geographic density in high-Medicaid states to capture authorization volume, while sub-scale agencies face electronic visit verification compliance costs that erode margins. Two strategic archetypes dominate: asset-light franchising models that scale without clinical asset ownership, and integrated platform operators that combine skilled nursing with durable medical equipment provisioning. Competitive moves center on Medicaid managed care contracting victories and hospital discharge partnership formations that secure high-acuity patient referrals.
Within the integrated platform tier, Aveanna Healthcare and BAYADA Home Health Care exemplify multi-state operators that sustain geographic density through standardized recruitment and quality metric systems. Angels of Care Pediatric Home Health occupies a specialized position serving complex-care cases that command longer visit durations and elevated reimbursement tiers. These three entities represent how scale and specialization diverge as viable competitive strategies within state-constrained reimbursement environments.
| Leading Market Players |
|---|
| Maxim Healthcare Services |
| Care Options for Kids |
| Aveanna Healthcare |
| At Home Healthcare |
| Pediatric Home Healthcare |
| BAYADA Home Health Care |
| Angels of Care Pediatric Home Health |
| Entrusted Pediatric Home Care |
| Pediatric Home Service |
| Others |
Cost & Logistics Intelligence
Undercapacity in Texas pediatric nursing labor pools elevates agency wage premiums while compressing margins for multi-state operators attempting price discipline. This utilization squeeze forces providers to choose between market share retention and profitability, reshaping procurement priorities toward technology substitutes and family-directed care models.
Pricing Analysis
Certification level creates the primary spread between premium and standard service tiers, with ventilator-competent registered nurses commanding reimbursement rates substantially above baseline pediatric RNs. Three-tier pricing structure across premium, standard, and economy levels reflects state Medicaid waiver generosity, with Texas STAR Kids authorizations permitting higher acuity billing codes than California's narrower eligibility bands. Cost compression in standard nursing tiers is intensifying because hospital systems absorb specialty pediatric nurses through shift differentials. Self-pay families in metropolitan Dallas-Fort Worth corridors demonstrate highest price sensitivity, while Medicaid managed care organizations exhibit inelastic demand due to mandated coverage floors.
Supply Chain Analysis
Contract manufacturing concentration for FDA-cleared pediatric pulse oximeters and capnography devices rests with specialized medical device foundries in Minnesota, Massachusetts, and Ireland. Component sourcing draws from semiconductor fabs in Taiwan for sensor chips, medical-grade plastics from Germany, and battery cells from South Korea. Single-source vulnerability runs through FDA 510(k) clearance timelines that extend 12-18 months for design modifications. Distribution runs through durable medical equipment suppliers maintaining hospital discharge partnerships, with regional home health agencies acting as downstream fulfillment nodes for consumables and disposable supplies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story justified by regulatory entrenchment: state Medicaid enrollment criteria and waiver program structures create switching costs that lock in patient populations and authorization pathways for established operators.
For Market Incumbents: Build data-network moats by integrating remote monitoring platforms with Medicaid managed care reporting requirements, capturing outcomes metrics that secure contract renewals. Hospital discharge partnerships in Texas metropolitan corridors represent the priority lever for high-acuity patient acquisition. Family-directed services expansion threatens skilled nursing volume; counter by embedding training protocols that maintain clinical oversight while reducing per-patient labor intensity. Electronic visit verification mandates from Texas HHSC fragment sub-scale competitors—invest in compliance infrastructure to widen the operational gap. For New Entrants and Emerging Players: Georgia and North Carolina waiver program expansions present the most penetrable geographic white space, with Medicaid 1915(c) flexibility increasing but pediatric home health infrastructure remaining underdeveloped relative to patient population growth. Target technology-dependent children with tracheostomy and ventilator dependence in secondary Texas markets outside Dallas-Fort Worth and Houston, where incumbent density thins. Pursue applied behavior analysis and skilled nursing convergence for dual-diagnosis autism and seizure disorder cases, a segment climbing fastest with limited specialized competition. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because electronic visit verification mandates and HIPAA-compliant IT infrastructure costs disproportionately burden sub-scale regional agencies, forcing distressed exits that national platforms can absorb. Acquisition target archetype: 50-200 nurse regional operators with dense Texas or California Medicaid contracts but underinvested technology stacks. Watch CMS hospital-at-home waiver permanence as the signal to detect inflection—pediatric-specific acute care reimbursement outside institutional settings would revalue home health agency asset bases substantially.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership Formation | Secures high-acuity discharge referrals through CMS hospital-at-home waiver pathways in Texas. |
| Remote Monitoring Platform Integration | Enables outcomes-based contracts with Medicaid managed care organizations that shift payment from volume to stability. |
| Ventilator Competency Certification Investment | Creates billing code access for highest-reimbursement nursing tiers while building regulatory moats. |
| Family-Directed Services Protocol Development | Captures waiver expansion growth while reducing per-patient labor costs through parental training programs. |
| Multi-State Licensure Compact Expansion | Accelerates nurse workforce mobility across high-Medicaid states without duplicating education investments. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with pediatric home health agency executives, Medicaid managed care contracting officers, hospital discharge planners, and biomedical equipment procurement managers; and secondary validation through CMS Medicare cost reports, Texas HHSC STAR Kids utilization data, FDA 510(k) device clearance databases, and state Medicaid waiver program filings. Bottom-up triangulation across patient authorization volumes, nursing hour productivity metrics, and reimbursement rate schedules anchored market sizing, while top-down cross-checks against durable medical equipment rental revenue cycles and telehealth platform deployment statistics verified segment splits.
Forecast inputs encompassed service type segmentation across nursing care, medical equipment, therapy services, and telehealth delivery; patient acuity tiers from technology-dependent chronic illness through post-surgical recovery; and delivery model differentiation between Medicare-certified home health agencies and private duty arrangements. CAGRs were derived from regression analysis of historical Medicaid waiver expansion rates, pediatric specialty hospital discharge growth patterns, and remote monitoring adoption curves across the analysis window. Industry-specific inputs included Texas HHSC electronic visit verification mandate compliance costs and CMS hospital-at-home waiver pilot expansion trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by national platforms or sudden Medicaid reimbursement rate cuts would shift outcomes beyond modeled ranges. Regulatory uncertainty surrounding pediatric-specific value-based payment pilots and family caregiver substitution thresholds represent primary revision risks. Quarterly review of Texas Medicaid STAR Kids authorization volumes, CMS Innovation Center waiver announcements, and pediatric ventilator device 510(k) submission trends is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pediatrics
Pediatric Oncology Treatment Market
Pediatrics
Autism Service Platform Market
Pediatrics
Paediatric Neuropsychiatric Disorders Treatment Market
Pediatrics
Paediatric Influenza Treatment Market
Pediatrics
Pediatric Tube Feeding Market
Pediatrics
Pediatric Nasal Cannula Market
Pediatrics
Pediatric Asthma Treatment Market
Pediatrics
Global Pediatric Radiology Market
Pediatrics
Pediatric Brain Tumor Market
Pediatrics
Pediatric Perfusion Products Market
Pediatrics
Pediatric Obesity Management Market
Pediatrics
Pediatric Catheter Market
Pediatrics
Pediatric Craniosynostosis Treatment Market
Pediatrics
Pediatric Palliative Care Drugs Market
Pediatrics
Paediatric Wheelchairs Market
Pediatrics
Paediatric Spasticity Treatment Market