
 Autism Service Platform Market | 2026-2036
Autism Service Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Autism Service Platform Market Insights
Board-certified behavior analyst workforce shortages are rotating clinical capacity toward platform-mediated care models. CentralReach leverages cloud-based practice management to sustain multi-state provider networks. RethinkFirst anchors employer-sponsored autism benefit programs through digital coaching infrastructure. Therapy Brands competes with consolidated electronic health record workflows tailored to applied behavior analysis clinics.
An autism service platform constitutes a software ecosystem that coordinates assessment protocols, session documentation, caregiver communication, and outcome measurement across distributed care teams, typically integrating video-based data capture and stimulus-response logging to support discrete trial training and naturalistic developmental behavioral interventions. Therapy Solutions within the product type dimension command premium positioning due to their direct linkage with insurance billable hours, while Assessment Tools face margin compression from open-source screening instruments. Hybrid Models across the delivery mode spectrum are absorbing the fastest growth as payers formalize reimbursement for blended in-person and telehealth encounters.
US Medicaid agencies, state-level department of education special education divisions, and HIPAA compliance frameworks collectively determine platform certification requirements and data interoperability standards for autism service providers. The FDA's evolving digital therapeutics oversight pathway may extend to adaptive skill-building applications with embedded algorithmic personalization. Stakeholders must monitor whether state autism insurance mandates will mandate real-time outcome reporting as a condition of network participation.
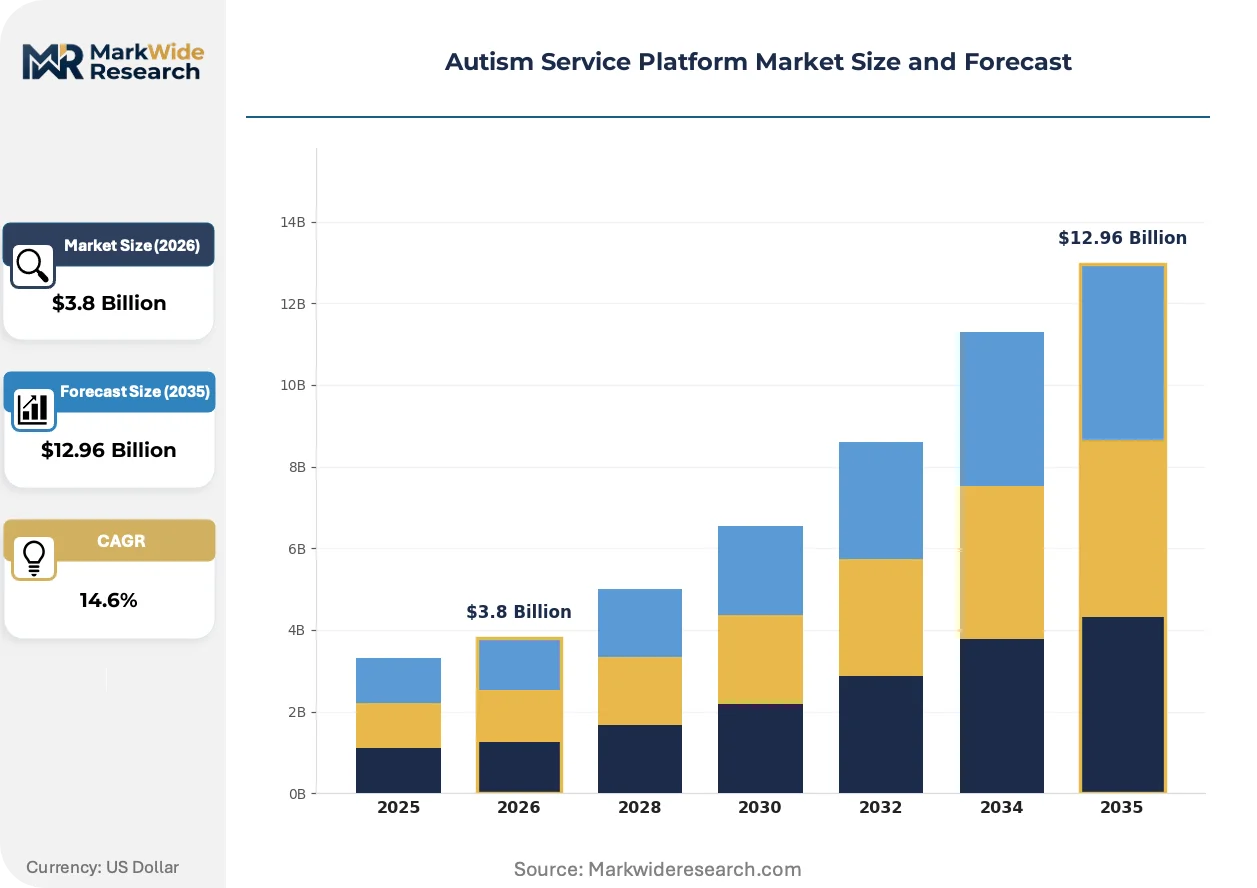
Market Dynamics
Medicaid reimbursement policy changes across US state agencies are compressing provider margins and forcing platform consolidation, as real-time outcome reporting mandates reshape vendor selection criteria for autism service networks.
Growth Catalysts
- State Autism Insurance Mandates:Thirty-seven US states now require commercial coverage for applied behavior analysis, expanding the addressable base for digital therapy coordination systems.
- HIPAA-Compliant Cloud Infrastructure:Federally certified data environments enable multi-state provider networks to share assessment protocols without jurisdictional friction.
- Board-Certified Behavior Analyst Shortages:Clinical workforce gaps are rotating capacity toward platform-mediated care models that extend specialist reach across distributed patient populations.
Market Restraints
- Reimbursement Rate Compression:Medicaid fee schedules in California, Texas, and Florida have flattened billing rates for remote behavioral interventions, squeezing platform vendor margins.
- Open-Source Screening Instruments:Free diagnostic tools distributed through academic medical centers are displacing proprietary assessment modules in initial evaluation workflows.
- State-Level Procurement Fragmentation:Regional center networks in California operate under distinct technical specifications that block standardized platform deployment.
Strategic Opportunities
- Employer-Sponsored Autism Benefits:Fortune 500 self-insured plans are adding digital coaching infrastructure as a covered benefit, creating direct-to-employer sales channels.
- FDA Digital Therapeutics Pathway:Adaptive skill-building applications with embedded algorithmic personalization may qualify for expedited regulatory review, opening prescription-based revenue models.
- Hybrid Encounter Reimbursement:Payers in New York and Pennsylvania have formalized billing codes for blended in-person and telehealth sessions, validating platform investments in integrated scheduling systems.
Industry Challenges
- Interoperability Certification Timelines:State department of education special education divisions require custom data exchange validation that extends sales cycles by eight to fourteen months.
- Caregiver Technology Literacy Gaps:Platform adoption depends on training protocols for family members who coordinate between clinical sessions, creating implementation friction in low-bandwidth households.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autism Service Platform Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Assessment Tools, Therapy Solutions, Support Services, Educational Resources Delivery Mode: Online Platforms, Mobile Applications, In-Person Sessions, Hybrid Models End User: Parents, Educational Institutions, Therapists, Healthcare Providers Technology: AI-Driven Tools, Analytics Software, Teletherapy Solutions, Interactive Media |
| Companies Covered | CentralReach, RethinkFirst, Therapy Brands, Catalyst Healthcare, AccelQ, Bluesprig, Action Behavioral Centers, ACES ABA, Center for Social Dynamics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autism Service Platform Market Trends and Innovations
Artificial intelligence is penetrating autism service platforms through stimulus-response logging and predictive session planning, compressing the gap between standardized protocols and individualized treatment adjustment.
Natural language processing engines trained on clinical session transcripts are decomposing the traditional role of human data entry specialists in applied behavior analysis clinics. Mid-sized provider networks in Ohio and Illinois are deploying these tools to reduce documentation overhead by half. The technology is decomposing labor cost structures that previously constrained clinic expansion into underserved counties.
The FDA's evolving oversight framework for software-as-a-medical-device is tightening validation requirements for adaptive skill-building applications with embedded personalization algorithms. Developers must now submit algorithmic change control protocols before commercial distribution. Pediatric digital health startups are responding by segregating US market versions from international releases to manage compliance scope.
Regional center procurement officers in California are consolidating vendor relationships from an average of twelve platform contracts per network to three preferred partners with full-stack capabilities. This concentration is displacing point-solution vendors who specialized exclusively on assessment or billing modules. The shift is most visible in Los Angeles and San Diego county networks, where multi-year enterprise agreements now dominate RFP outcomes.
Autism Service Platform Market Segmentation
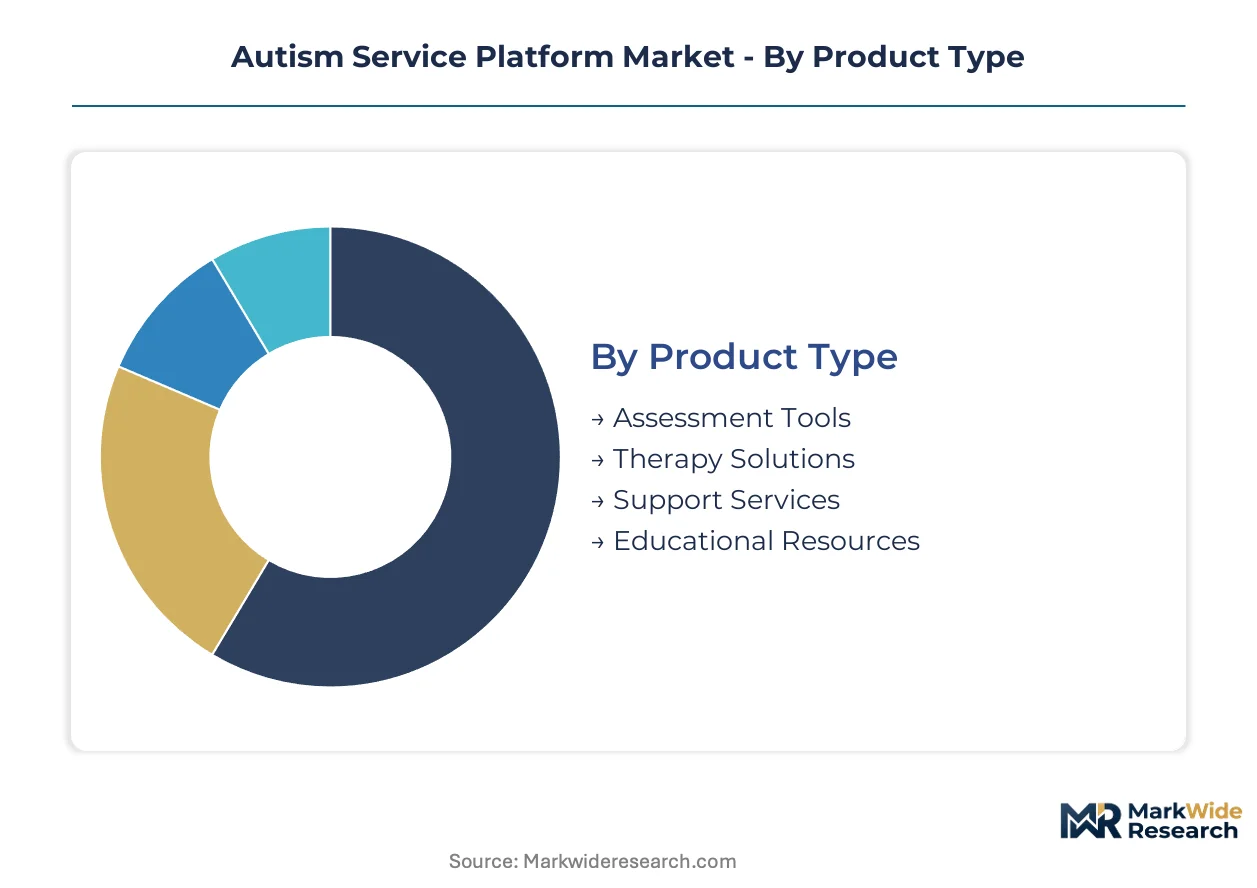
Platform vendors configure feature modules around reimbursement pathways and care team workflows. Segment boundaries blur where Medicaid billing rules force hybrid encounter documentation across multiple categories.
Product Type:
Substitution pressure from open-source instruments compresses margins in standardized assessment workflows while billable therapy modules defend revenue concentration.
- Therapy Solutions:These platforms coordinate session documentation, caregiver communication, and outcome measurement for discrete trial training and naturalistic developmental behavioral interventions. California's regional center networks and Texas Medicaid managed care organizations concentrate procurement here due to direct linkage with insurance-reimbursable hours.
- Assessment Tools:Modules for initial screening and diagnostic protocol administration face displacement from free instruments distributed through academic medical centers. School districts in Florida and Ohio still require proprietary validation for special education eligibility determinations, sustaining niche demand.
- Support Services:Caregiver training portals and care coordination dashboards extend platform stickiness beyond clinical sessions.
- Educational Resources:Curriculum-aligned skill-building content serves individualized education program compliance requirements.
Therapy Solutions retains volume leadership; Hybrid Models holds the steepest expansion curve.
Delivery Mode:
Cost tier stratification separates enterprise-grade scheduling systems from lightweight caregiver-facing applications, with reimbursement policy determining viable price points.
- Hybrid Models:Integrated scheduling and documentation systems manage blended in-person and telehealth encounters. New York and Pennsylvania Medicaid programs have formalized billing codes for this modality, accelerating payer validation of platform investments.
- Online Platforms:Browser-based clinical workstations dominate multi-site provider networks in Illinois and Georgia. HIPAA-compliant cloud infrastructure enables data sharing across state lines without jurisdictional friction.
- Mobile Applications:Caregiver-facing tools for stimulus-response logging and session coaching operate on lower-margin pricing tiers.
- In-Person Sessions:Traditional clinic-based documentation workflows persist where broadband infrastructure limits telehealth adoption.
Online Platforms retains volume leadership; Hybrid Models gains share fastest.
End User:
Application complexity varies sharply between institutional procurement with eighteen-month sales cycles and direct-to-consumer subscription models.
- Healthcare Providers:Applied behavior analysis clinics and developmental pediatric practices require full-stack electronic health record integration. Board-certified behavior analyst workforce shortages in Arizona and Colorado rotate capacity toward platform-mediated care models.
- Educational Institutions:School district special education divisions mandate custom data exchange validation that extends vendor onboarding timelines. State department of education technical specifications in California block standardized deployment.
- Parents:Direct-purchase caregiver training modules face technology literacy barriers in low-bandwidth households.
- Therapists:Individual practitioner subscriptions concentrate in solo practices without enterprise IT support.
Healthcare Providers retains volume leadership; Educational Institutions shows the steepest expansion trajectory.
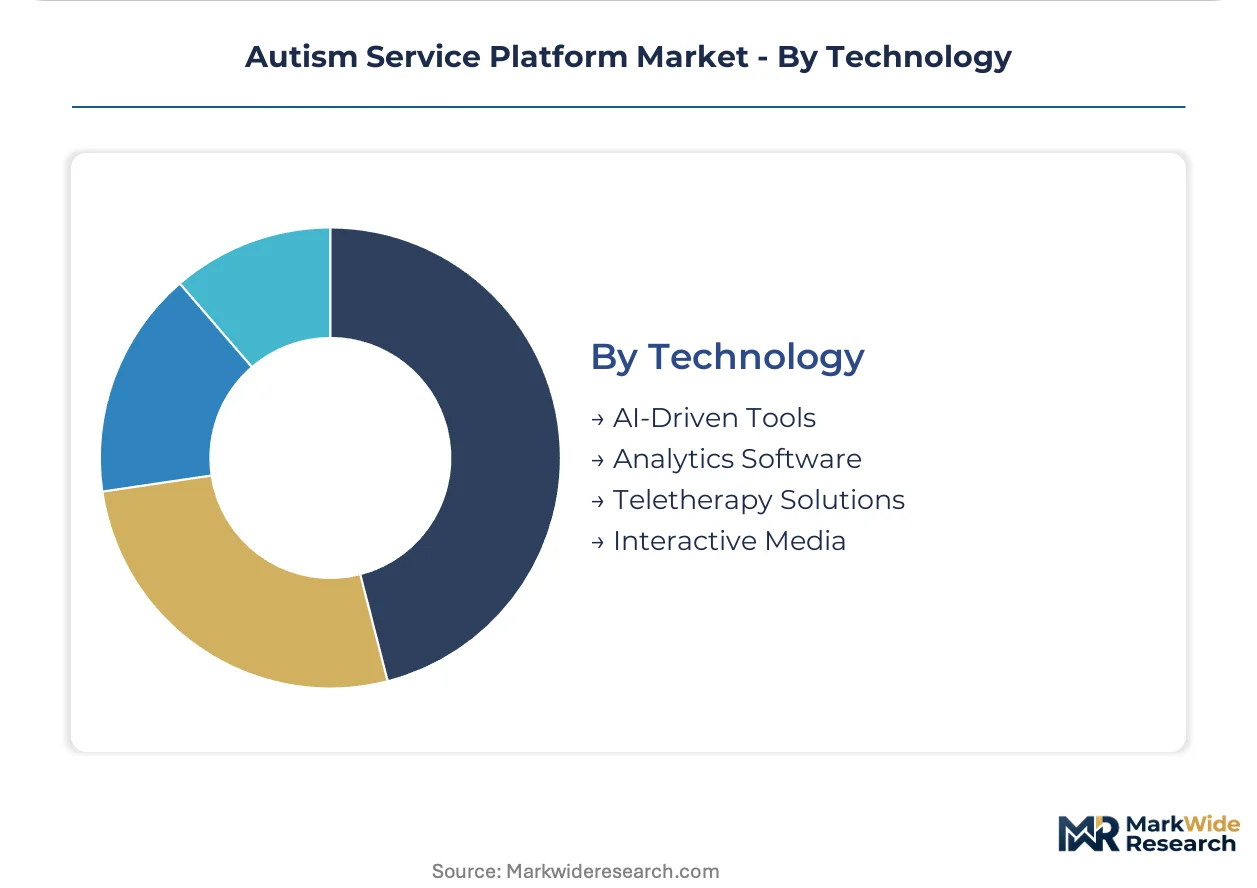
Technology:
Supply concentration in algorithmic personalization engines separates venture-backed developers from legacy workflow tool vendors.
- AI-Driven Tools:Predictive session planning and stimulus-response logging compress gaps between standardized protocols and individualized treatment adjustment. FDA software-as-a-medical-device oversight tightens validation requirements for adaptive skill-building applications.
- Teletherapy Solutions:Video-based data capture with integrated documentation serves remote behavioral intervention billing requirements. Medicaid reimbursement rate compression in California, Texas, and Florida squeezes vendor margins.
- Analytics Software:Outcome measurement dashboards satisfy state autism insurance mandate reporting requirements.
- Interactive Media:Gamified skill-building interfaces target pediatric engagement but face uncertain prescription-based revenue models.
Teletherapy Solutions retains volume leadership; AI-Driven Tools climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform deployment patterns diverge sharply by reimbursement infrastructure maturity. The United States concentrates hybrid encounter billing adoption, while European markets emphasize GDPR-compliant data exchange for cross-border provider networks.
United States
Medicaid managed care organizations in California, Texas, and Florida drive procurement volume through formalized telehealth billing codes. HIPAA compliance frameworks enable multi-state provider networks to share assessment protocols without jurisdictional friction. Los Angeles and San Diego county regional centers consolidate vendor relationships toward three preferred partners with full-stack capabilities.
Canada
Provincial health authorities in Ontario and British Columbia expand digital therapy coordination for autism spectrum disorder services. Health Canada oversight aligns with provincial privacy commissioners on cross-jurisdictional data sharing standards. Toronto-based provider networks pilot blended in-person and virtual encounter models under Ontario Autism Program reforms.
Germany
Statutory health insurance funds test platform-mediated care models for behavioral intervention coordination. BfArM digital health application pathways create regulatory clarity for adaptive skill-building software. Berlin and Munich clusters concentrate startup development for algorithmic personalization engines.
United Kingdom
NHS England integrated care boards evaluate digital therapy platforms for autism diagnostic pathway acceleration. MHRA software-as-a-medical-device guidance shapes validation requirements for AI-driven assessment tools. London and Southeast England health technology clusters attract venture investment for predictive session planning applications.
Australia
National Disability Insurance Scheme planners incorporate platform-based outcome reporting into funding authorization workflows. TGA digital health oversight extends to adaptive skill-building applications with embedded personalization. Sydney and Melbourne provider networks deploy hybrid scheduling systems across dispersed rural populations.
Autism Service Platform Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in autism service platform supply. Consolidation pressure from Medicaid reimbursement compression favors vendors with full-stack electronic health record integration over point-solution specialists. Three archetypes dominate: cloud-native practice management suites, employer benefit infrastructure providers, and consolidated electronic health record workflow vendors. M&A activity concentrates among mid-sized platforms seeking geographic scale, while strategic partnerships with regional center networks secure multi-year procurement contracts.
Within the integrated cloud-native tier, CentralReach and Therapy Brands exemplify platform breadth through multi-state provider network enablement. RethinkFirst anchors employer-sponsored benefit program infrastructure. These three occupy positions across distinct go-to-market vectors—clinical practice management, payer-facing benefit administration, and electronic health record consolidation—rather than competing directly for identical procurement decisions.
| Leading Market Players |
|---|
| CentralReach |
| RethinkFirst |
| Therapy Brands |
| Catalyst Healthcare |
| AccelQ |
| Bluesprig |
| Action Behavioral Centers |
| ACES ABA |
| Center for Social Dynamics |
| Others |
Pricing and Supply Chain Analysis
Open-source screening instruments replacing proprietary assessment modules simultaneously relocate value capture toward billable therapy coordination and compress margins in standardized diagnostic workflows across California regional centers and Texas Medicaid networks.
Pricing Analysis
Multi-year enterprise agreements dominate procurement decisions in Los Angeles and San Diego county regional centers, with three-tier pricing structure across premium, standard, and economy levels anchored to full-stack capability depth. Price differentiation hinges on HIPAA certification tier and after-sales implementation support bundled into per-seat subscriptions. Cost compression in assessment modules intensifies because academic medical centers distribute free diagnostic tools. School districts in Florida and Ohio exhibit highest price sensitivity due to constrained special education budgets, while Fortune 500 self-insured plans show lowest sensitivity to per-employee-per-month pricing.
Supply Chain Analysis
FDA software-as-a-medical-device validation timelines constitute the critical chokepoint determining commercial release sequencing for adaptive skill-building applications with embedded algorithmic personalization. Cloud infrastructure supply concentrates in the United States through federally certified data environments, with algorithmic personalization engines drawing from venture-backed development clusters in Berlin and London. Single-source vulnerability sits with proprietary natural language processing engines trained on clinical session transcripts. Distribution runs through direct sales teams targeting regional center procurement officers and channel partnerships with electronic health record consolidation vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Board-certified behavior analyst scarcity constrains clinical capacity expansion and rotates competitive advantage toward platform vendors that automate documentation overhead and extend specialist reach across underserved counties.
For Market Incumbents: Fortify multi-state provider network density through acquisition of mid-sized platforms seeking geographic scale, while deepening algorithmic personalization capabilities to defend against open-source screening displacement. Consolidate vendor relationships within California regional centers before procurement officers complete their shift from twelve contracts to three preferred partners.
For New Entrants and Emerging Players: Caregiver-facing mobile applications for stimulus-response logging represent the most penetrable white-space segment, as incumbent platforms under-serve low-bandwidth households with technology literacy gaps. Target direct-to-employer sales channels through Fortune 500 self-insured plans adding digital coaching infrastructure. Pursue strategic partnerships with Ontario and British Columbia provincial health authorities expanding digital therapy coordination.
For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native practice management suites with full-stack electronic health record integration rather than point-solution specialists facing displacement. Long-term viability across the analysis window favors vendors capturing hybrid encounter reimbursement validation from New York and Pennsylvania Medicaid programs. Monitor FDA algorithmic change control protocol submissions as inflection indicator for prescription-based revenue model viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidated electronic health record workflows satisfy California regional center full-stack requirements. |
| Strategic Partnership | Multi-year enterprise agreements with Los Angeles county procurement officers secure recurring revenue bases. |
| Geographic Expansion | Ontario Autism Program reforms in Canada create entry pathways for hybrid scheduling system vendors. |
| Acquisition of Specialist Firm | Mid-sized platform targets in Ohio and Illinois deliver natural language processing documentation automation. |
| Product Launch | FDA software-as-a-medical-device pathway qualification enables prescription-based adaptive skill-building revenue. |
Research Methodology
Initial hypotheses were tested against primary input from board-certified behavior analysts, regional center procurement officers, Medicaid managed care organization contract managers, and applied behavior analysis clinic operations directors and refined through secondary validation against CMS Medicare reimbursement databases, state autism insurance mandate legislative records, FDA software-as-a-medical-device guidance documents, and special education division technical specification filings. Bottom-up sizing of provider network deployments triangulated against top-down Medicaid expenditure allocation estimates.
Variance decomposition across product type, delivery mode, end user, and technology segmentation dimensions structured the analytical framework over the projection horizon. CAGRs derived from logistic adoption curves fitted to telehealth billing code formalization timelines and board-certified behavior analyst workforce growth projections. Hybrid encounter reimbursement policy trajectories in New York and Pennsylvania informed encounter volume assumptions.
Underlying assumptions cover Medicaid fee schedule stability and FDA oversight pathway clarity, with deviation risk concentrated in state-level procurement fragmentation and open-source instrument substitution acceleration. Revision becomes warranted when caregiver technology literacy barriers erode faster than platform onboarding protocol adaptation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pediatrics
Pediatric Mattress Market
Pediatrics
Global Cerebral Palsy Treatment Market
Pediatrics
Pediatric HIV Infection Treatment Market
Pediatrics
Paediatric Influenza Treatment Market
Pediatrics
OTC Pediatric Healthcare Market
Pediatrics
Paediatric Wheelchairs Market
Pediatrics
Pediatric Palliative Care Drugs Market
Pediatrics
Paediatric Neuropsychiatric Disorders Treatment Market
Pediatrics
Global Pediatric Radiology Market
Pediatrics
Pediatric Tube Feeding Market
Pediatrics
Pediatric Craniosynostosis Treatment Market
Pediatrics
Middle East and Africa Pediatric Healthcare Market
Pediatrics
Global Pediatric Neuroblastoma Treatment Market
Pediatrics
Pediatric Nasal Cannula Market
Pediatrics
Pediatric Obesity Management Market
Pediatrics
Global Pediatric Home Healthcare Services Market