
 Pediatric Brain Tumor Market | 2026-2036
Pediatric Brain Tumor Market Size, Share, and Industry Trends Forecast 2026-2036
Pediatric Brain Tumor Market Outlook
North American biopharma manufacturing capacity for pediatric oncology is restructuring around precision medicine platforms. Roche Holding AG leverages its neuro-oncology portfolio to sustain leadership in targeted therapy development. Novartis AG anchors its position through CAR-T manufacturing scale and pediatric trial infrastructure. Pfizer Inc. competes via radioligand therapy investments and academic medical center partnerships.
Pediatric brain tumors comprise malignant and benign neoplasms arising in the central nervous system of patients under 18 years, requiring multimodal treatment protocols that integrate surgical resection margins, histopathological grading, and molecular profiling for risk stratification. These conditions drive specialized therapeutic development addressing blood-brain barrier penetration and age-appropriate dosing formulations. Targeted therapy segments command premium positioning as BRAF inhibitors and MEK inhibitors reshape medulloblastoma and low-grade glioma protocols. Genetic testing technology segments show accelerating uptake as liquid biopsy platforms and next-generation sequencing panels enter standard diagnostic workups. Chemotherapy retains volume dominance but faces margin compression from biosimilar entry and combination regimen complexity.
FDA pediatric study requirements under the Pediatric Research Equity Act and EMA's Paediatric Investigation Plans mandate age-appropriate trial data, shaping development timelines and orphan exclusivity strategies for sponsors. WHO essential medicines listings and national childhood cancer plans in Germany, France, and Japan standardize access protocols and reimbursement thresholds for high-cost interventions. Stakeholders must monitor biomarker-validated trial designs and decentralized manufacturing investments to capture positioning in this indication-specific ecosystem.
Market Dynamics
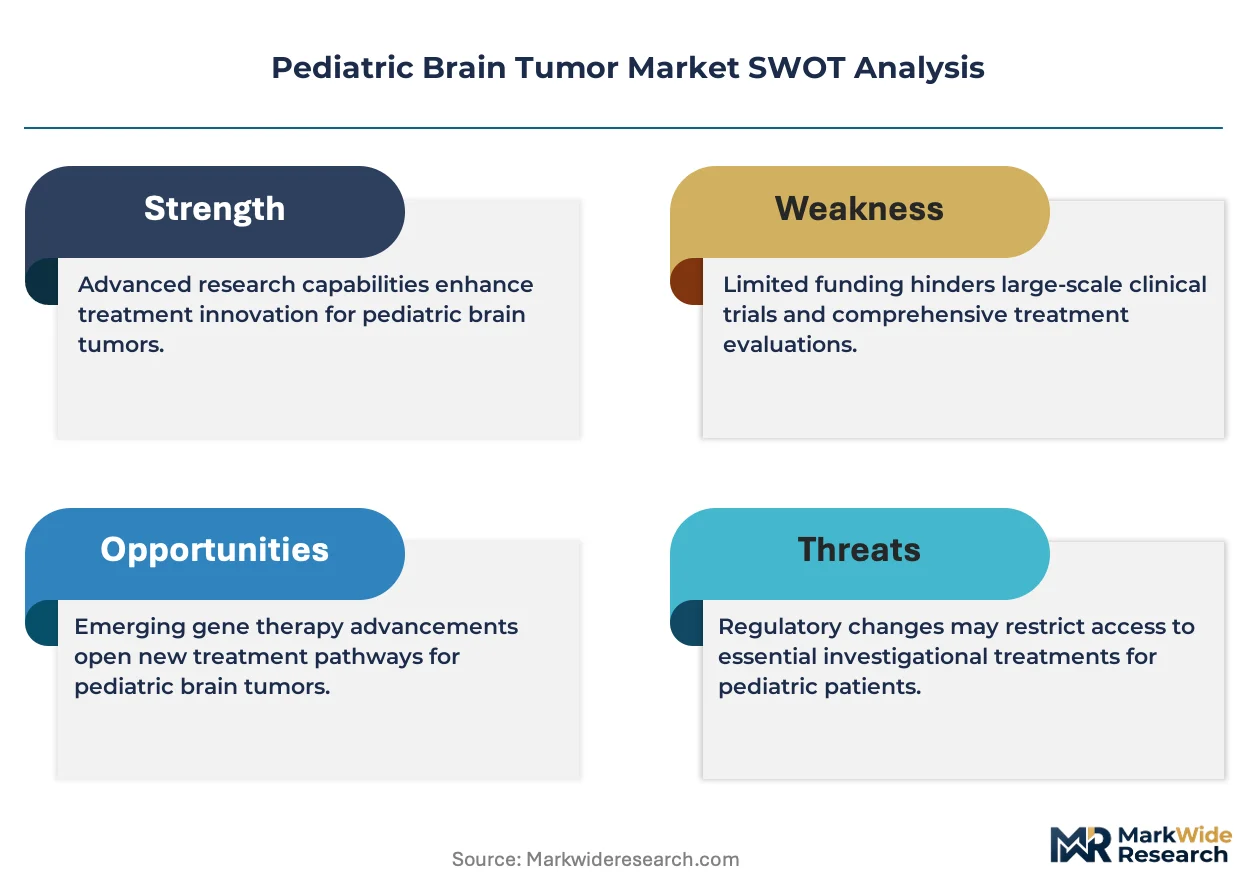
FDA pediatric investigation plans and EMA Paediatric Investigation Plans are compressing development timelines while mandating age-appropriate formulations, forcing sponsors to restructure trial protocols around molecular stratification rather than histology alone.
Growth Catalysts
- Orphan drug exclusivity pathways:FDA and EMA accelerated review mechanisms reduce time-to-market for rare pediatric indications, incentivizing biopharma investment in medulloblastoma and ependymoma subtypes.
- Liquid biopsy platform adoption:Next-generation sequencing panels for cerebrospinal fluid analysis enable real-time treatment monitoring without invasive tissue sampling, expanding diagnostic utility in academic medical centers.
- CAR-T manufacturing scale:Dedicated pediatric cell therapy facilities in Boston, Houston, and Memphis reduce vein-to-vein time and support multi-site trial enrollment.
Market Restraints
- Blood-brain barrier penetration limitations:Small-molecule design constraints restrict therapeutic efficacy for diffuse intrinsic pontine glioma, compressing addressable patient populations for novel agents.
- Single-source isotope dependency:Radioligand therapy production concentrates at three North American cyclotron facilities, creating supply vulnerability for pediatric neuroblastoma protocols.
- Biomarker assay standardization gaps:Variable BRAF fusion detection methods across clinical laboratories delay treatment initiation and complicate trial eligibility screening.
Strategic Opportunities
- Decentralized manufacturing investments:Point-of-care CAR-T production in European pediatric oncology hubs reduces logistics costs and cold-chain failure risk for time-sensitive therapies.
- Combination regimen development:MEK inhibitor plus BRAF inhibitor protocols for low-grade glioma create new addressable segments beyond monotherapy-resistant populations.
- WHO essential medicines listing expansion:Inclusion of high-cost targeted therapies in national childhood cancer plans standardizes reimbursement in Germany, France, and Japan.
Industry Challenges
- Pediatric neuro-oncology trial design complexity:Age-appropriate dosing cohorts and neurocognitive endpoint validation extend protocol development timelines and increase regulatory submission preparation costs.
- Multi-site data integration friction:Incompatible electronic health record systems across St. Jude Children's Research Hospital, Dana-Farber, and MD Anderson complicate centralized safety monitoring and adaptive trial modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pediatric Brain Tumor Market |
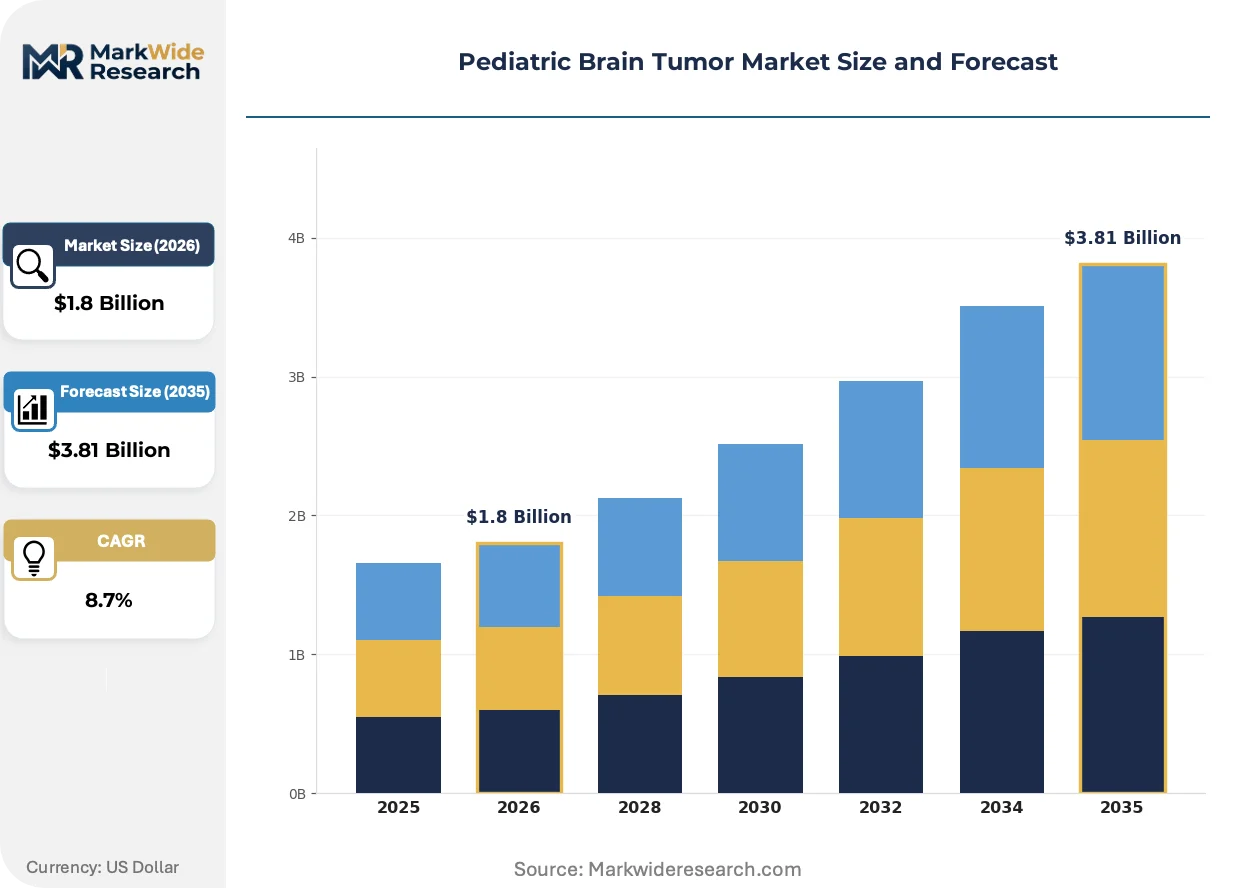
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Radiation Therapy, Surgery, Targeted Therapy End User: Pediatric Hospitals, Oncology Clinics, Research Institutions, Outpatient Facilities Technology: Imaging Technology, Genetic Testing, Biomarkers, Radiation Delivery Systems Application: Clinical Trials, Treatment Planning, Patient Monitoring, Research Studies |
| Companies Covered | Roche Holding AG, Novartis AG, Pfizer Inc., Bristol-Myers Squibb Company, Merck & Co., Inc., Eli Lilly and Company, AstraZeneca plc, Amgen Inc., Sanofi S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pediatric Brain Tumor Market Strategic Shifts
Precision medicine platforms are fragmenting treatment protocols into molecularly defined subgroups, displacing histology-based regimens and demanding new manufacturing, diagnostic, and clinical trial infrastructure investments across pediatric neuro-oncology.
Liquid biopsy technology for cerebrospinal fluid circulating tumor DNA analysis is decentralizing molecular monitoring capabilities from centralized reference laboratories to hospital-based pathology departments. Pediatric hospitals in Boston and Houston are adopting these platforms for real-time treatment response assessment. This shift is compressing turnaround times for BRAF fusion detection and enabling faster protocol adaptation in adaptive trial designs.
EMA's Paediatric Investigation Plans and FDA's Pediatric Research Equity Act are mandating age-appropriate formulation development for all new oncology indications, regardless of adult prevalence. Sponsors must now submit pediatric study plans before Phase II completion, restructuring portfolio prioritization around drugs with blood-brain barrier penetration potential. Low-grade glioma and medulloblastoma segments are responding with dedicated pediatric formulation teams and taste-masked liquid dosage investments.
Academic medical centers are consolidating procurement of molecular diagnostic services through single-source agreements with reference laboratories, displacing fragmented hospital-based testing menus. This concentration is reshaping vendor relationships in the United States, where Dana-Farber, St. Jude, and MD Anderson negotiate multi-year sequencing contracts. Pediatric neuro-oncology departments in these institutions are standardizing on harmonized NGS panels to enable cross-trial biomarker comparison.
Pediatric Brain Tumor Market Segmentation
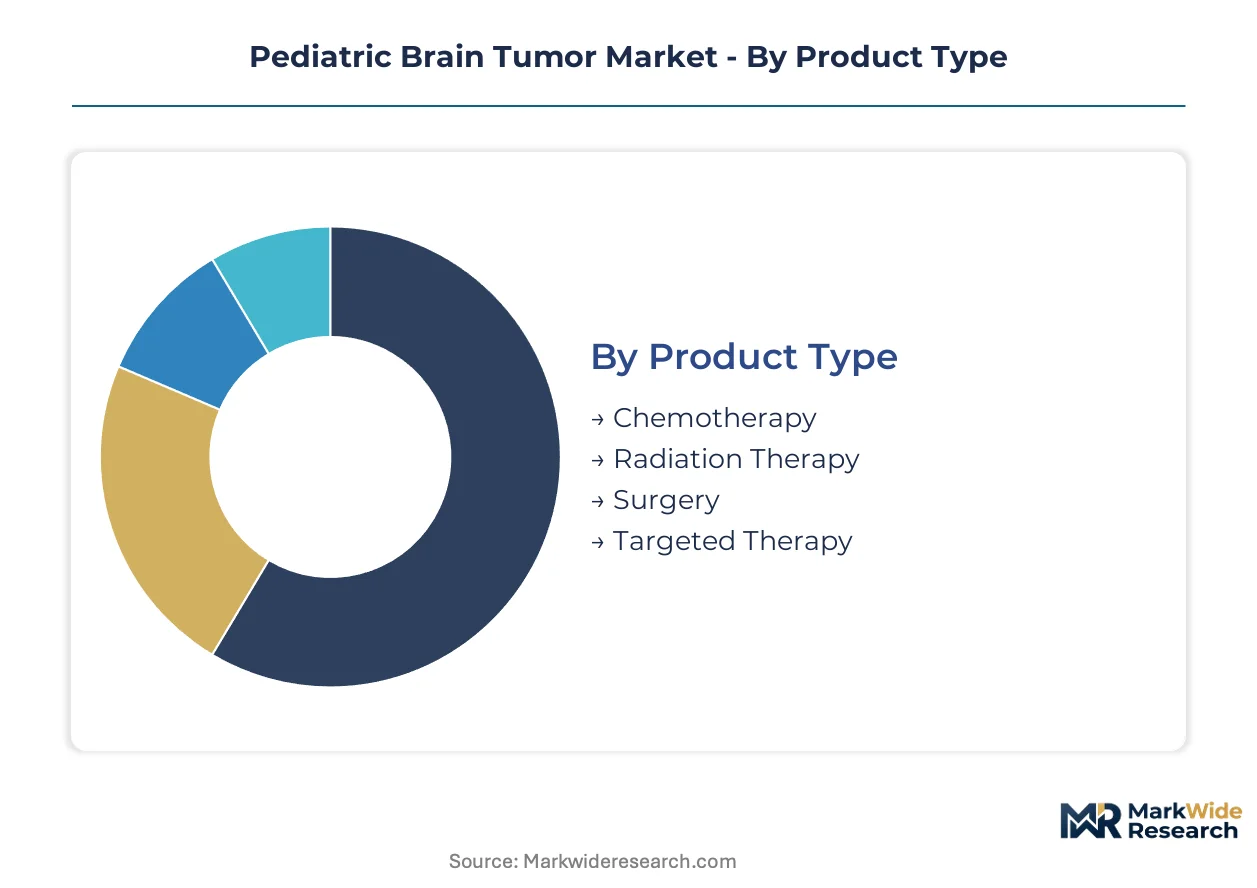
Pediatric brain tumor treatment protocols fragment across four distinct dimensions, each commanding specialized infrastructure investments. Product type and technology segments drive manufacturing capacity location decisions, while end-user and application categories shape distribution and service delivery models.
Product Type:
Supply concentration for active pharmaceutical ingredients and radiopharmaceuticals clusters around FDA-inspected facilities in the United States and EMA-authorized sites in Germany and Switzerland.
- Chemotherapy:Alkylating agents and platinum compounds retain volume leadership through established infusion protocols. Demand concentrates in St. Jude Children's Research Hospital and Dana-Farber Cancer Institute networks, constrained by neurotoxicity monitoring requirements and age-adjusted dosing complexity.
- Targeted Therapy:BRAF inhibitors and MEK inhibitors penetrate the blood-brain barrier through small-molecule engineering. Pediatric hospitals in Boston and Houston prioritize these agents for low-grade glioma protocols, driven by biomarker-validated patient selection and reduced systemic toxicity profiles compared to conventional chemotherapy.
- Radiation Therapy:Proton beam facilities require capital-intensive cyclotron infrastructure concentrated at three North American academic medical centers.
- Surgery:Resection margins depend on intraoperative MRI and fluorescence-guided technologies available at referral centers in Memphis and Houston.
Today's leader: Chemotherapy. Tomorrow's challenger: Targeted Therapy.
End User:
Procurement authority and reimbursement pathways diverge sharply across institutional types, with pediatric hospitals commanding centralized purchasing power unavailable to smaller outpatient settings.
- Pediatric Hospitals:Dedicated neuro-oncology units in Boston, Houston, and Memphis integrate surgical, medical, and radiation oncology under single-site governance. These institutions negotiate direct manufacturer contracts for CAR-T therapies and radioligand agents, bypassing wholesale distribution.
- Oncology Clinics:Community-based infusion centers in the United States handle stable-phase chemotherapy administration. Volume concentrates in metropolitan referral corridors where academic medical center overflow creates satellite treatment capacity.
- Research Institutions:St. Jude Children's Research Hospital and similar centers maintain captive manufacturing partnerships for investigational cell therapies.
- Outpatient Facilities:Ambulatory surgery centers in Texas and Massachusetts perform diagnostic biopsies and port placements, referring complex resections to pediatric hospital networks.
Pediatric hospitals capture the steepest expansion trajectory as neuro-oncology service lines deepen. Outpatient facilities face margin compression from reimbursement code consolidation.
Technology:
Capital deployment for diagnostic and therapeutic platforms favors modular systems with pediatric-specific software configurations over universal devices requiring workflow adaptation.
- Genetic Testing:Next-generation sequencing panels for BRAF fusion detection and methylation profiling migrate from centralized reference laboratories to hospital-based pathology departments. Dana-Farber and MD Anderson have adopted in-house liquid biopsy platforms for cerebrospinal fluid analysis, compressing turnaround times from weeks to days.
- Imaging Technology:Intraoperative MRI and PET-MRI hybrid systems enable real-time resection guidance. Procurement concentrates at pediatric hospitals with dedicated neurosurgical suites in Houston and Boston, constrained by shielding requirements and anesthesia compatibility.
- Biomarkers:Circulating tumor DNA assays for treatment monitoring require harmonized detection thresholds across clinical trial sites.
- Radiation Delivery Systems:Proton therapy gantries and Gamma Knife installations cluster at single-institution hubs due to footprint and staffing requirements.
Genetic Testing is gaining share fastest as molecular stratification displaces histology-based protocols. Radiation Delivery Systems face utilization pressure from targeted therapy alternatives.
Application:
Revenue recognition timing and contractual risk allocation differ fundamentally between immediate patient care and longitudinal research commitments.
- Clinical Trials:FDA pediatric investigation plans and EMA Paediatric Investigation Plans mandate age-appropriate enrollment. Trial concentration in Boston, Houston, and Memphis reflects existing patient referral patterns and established institutional review board relationships with oncology sponsors.
- Treatment Planning:Multidisciplinary tumor boards integrate imaging, pathology, and molecular data into risk-stratified protocols. Software platforms from academic medical center spinouts dominate this segment, with Dana-Farber and St. Jude licensing proprietary algorithms to community hospitals.
- Patient Monitoring:Remote neurocognitive assessment tools expand addressable populations beyond metropolitan referral centers.
- Research Studies:Longitudinal biobanking and natural history studies require sustained funding commitments from NIH and foundation sources.
Clinical Trials anchor current revenue. Treatment Planning represents the most rapid adoption curve as artificial intelligence tools enter regulatory review.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping pediatric neuro-oncology clinical trial placement, as sponsors migrate studies toward jurisdictions with streamlined pediatric investigation pathways and consolidated referral networks. EMA's Paediatric Investigation Plans and FDA's Pediatric Research Equity Act create divergent cost-of-compliance profiles that influence site selection and manufacturing investment location.
United States
Pediatric hospitals in Boston, Houston, and Memphis anchor the world's densest concentration of dedicated neuro-oncology units and CAR-T manufacturing infrastructure. FDA pediatric study requirements under PREA mandate age-appropriate formulations, compressing development timelines for sponsors targeting medulloblastoma and ependymoma indications. Dana-Farber Cancer Institute and St. Jude Children's Research Hospital negotiate direct manufacturer contracts, bypassing wholesale distribution for radioligand and cell therapy products.
Germany
The country's national childhood cancer plan standardizes reimbursement thresholds for high-cost targeted therapies, reducing access variability across federal states. EMA Paediatric Investigation Plans align with national health technology assessment processes, accelerating orphan drug pathways for BRAF inhibitor combinations. Heidelberg and Berlin pediatric oncology hubs concentrate proton therapy capacity and liquid biopsy platform adoption for real-time treatment monitoring.
Switzerland
Swissmedic pediatric regulatory pathways leverage EMA centralized procedures while maintaining national flexibility for early-access programs. Roche Holding AG anchors Basel-region neuro-oncology R&D investment, sustaining precision medicine platform development for low-grade glioma protocols. The country's contract manufacturing organizations serve as EMA-authorized production nodes for pediatric formulation batches destined across European markets.
Japan
PMDA pediatric review incentives under the Sakigake designation system attract sponsor investment for blood-brain barrier-penetrating small molecules. Tokyo and Osaka academic medical centers integrate molecular stratification into standard diagnostic workups, displacing histology-based protocols. METI funding for next-generation sequencing infrastructure accelerates hospital-based pathology department adoption of BRAF fusion detection panels.
United Kingdom
NHS England specialized commissioning frameworks concentrate pediatric brain tumor surgery at designated tertiary centers in London, Manchester, and Birmingham. The MHRA pediatric investigation plan implementation mirrors EMA requirements while offering national trial facilitation services. Academic medical center spinouts from London and Cambridge license proprietary treatment planning algorithms to community hospitals, expanding algorithm-driven risk stratification.
Pediatric Brain Tumor Market Competitive Environment
United States-based pharmaceutical conglomerates anchor one tier of competitive positioning; Swiss and German specialists hold differentiated positions in precision medicine platforms and pediatric formulation development. Market structure concentrates around integrated oncology portfolios with blood-brain barrier penetration capabilities, though mid-scale biotech specialists retain footholds in CAR-T and radioligand niches. Three archetypes dominate: diversified pharma majors with neuro-oncology franchises, cell therapy specialists with pediatric manufacturing scale, and targeted therapy developers with biomarker-validated pipelines. Competitive moves center on academic medical center partnership consolidation and decentralized manufacturing investments for time-sensitive therapies.
Within the diversified pharma tier, Roche Holding AG and Novartis AG exemplify integrated neuro-oncology platform strategies, with the former leveraging diagnostic-to-therapeutic vertical linkages and the latter anchoring pediatric CAR-T manufacturing infrastructure. Pfizer Inc. occupies a distinct position through radioligand therapy investments and cyclotron facility partnerships. These three Swiss and US-based entities represent the dominant competitive archetypes: precision medicine integrators, cell therapy scale operators, and radiopharmaceutical network builders.
| Leading Market Players |
|---|
| Roche Holding AG |
| Novartis AG |
| Pfizer Inc. |
| Bristol-Myers Squibb Company |
| Merck & Co., Inc. |
| Eli Lilly and Company |
| AstraZeneca plc |
| Amgen Inc. |
| Sanofi S.A. |
| Others |
Value Chain & Pricing Dynamics
Captive manufacturing partnerships between pediatric oncology hubs and radiopharmaceutical suppliers anchor both supply security and pricing power for time-sensitive therapies. This integration pattern concentrates procurement leverage at Dana-Farber, St. Jude, and MD Anderson while compressing margins for wholesale distributors excluded from direct contracting.
Pricing Analysis
Distributor margins for chemotherapy agents face compression as pediatric hospitals negotiate direct manufacturer contracts for CAR-T and radioligand products. Three-tier pricing structure across premium targeted therapies, standard alkylating agents, and economy supportive-care drugs reflects biomarker validation status and blood-brain barrier penetration capability. Cost compression in the chemotherapy tier intensifies because biosimilar entry and combination regimen complexity erode brand premiums. Community oncology clinics exhibit highest price sensitivity due to reimbursement code consolidation, while academic medical centers prioritize clinical efficacy over acquisition cost.
Supply Chain Analysis
Returns and refurbishment flows for proton therapy equipment create secondary market dynamics that extend asset lifecycles and depress new equipment pricing. Active pharmaceutical ingredient production concentrates in the United States, Germany, and Switzerland, with EMA-authorized sites serving European pediatric formulation batches. Cyclotron isotopes, BRAF inhibitor raw materials, and specialized cell culture media constitute critical input dependencies. Single-source isotope vulnerability at three North American cyclotron facilities creates supply risk for neuroblastoma radioligand protocols. Distribution runs through direct hospital contracts for advanced therapies and wholesale channels for standard chemotherapy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pediatric brain tumor therapeutics offer margin expansion through biomarker-validated premium pricing and manufacturing scale efficiencies that reduce per-dose production costs for cell therapies.
For Market Incumbents: Hedge against biosimilar erosion in chemotherapy by deepening CAR-T manufacturing scale in Boston and Houston. Secure cyclotron facility partnerships to mitigate single-source isotope dependency for radioligand portfolios. Prioritize formulation development investments that satisfy FDA pediatric study requirements ahead of Phase II completion timelines. For New Entrants and Emerging Players: Capture white-space opportunity in decentralized point-of-care CAR-T production for European pediatric hubs underserved by current cold-chain logistics. Target liquid biopsy platform adoption in hospital-based pathology departments as reference laboratories lose molecular testing share. Pursue academic medical center licensing agreements for treatment planning algorithms as the fastest penetration pathway. For Investors and Strategic Acquirers: Roll-up economics work for precision medicine platform specialists because molecular stratification fragments treatment protocols into addressable subpopulations requiring dedicated diagnostic-therapeutic pairings. Five-to-ten year viability hinges on biomarker-validated pipeline depth rather than histology-based drug repositioning. Monitor FDA pediatric investigation plan submission rates as the inflection signal for sponsor commitment to this indication.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker-Validated Trial Design | FDA pediatric investigation plans now mandate molecular stratification over histology alone, reshaping enrollment protocols. |
| Decentralized CAR-T Manufacturing | Point-of-care production in European pediatric hubs reduces vein-to-vein time and cold-chain failure risk. |
| Liquid Biopsy Platform Integration | Cerebrospinal fluid circulating tumor DNA analysis enables real-time treatment monitoring without invasive tissue sampling. |
| Academic Medical Center Partnership | Direct contracts with Dana-Farber and St. Jude bypass wholesale distribution for high-value radioligand therapies. |
| Pediatric Formulation Development | Taste-masked liquid dosage investments address PREA requirements for age-appropriate drug delivery. |
Study Parameters
Bottom-up pediatric hospital procurement modeling reconciled against top-down pharmaceutical manufacturing capacity tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Triangulation between demand-side prescribing patterns and supply-side production runs ensures statistical integrity across the dataset.
Historical trendline analysis of treatment protocol adoption rates and therapeutic class revenue recognition patterns informs the projection framework. Segmentation dimensions include product type, technology platform, end-user institution category, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to biomarker penetration trajectories and manufacturing capacity expansion schedules across the projection horizon. Blood-brain barrier penetration rates and pediatric trial enrollment velocity serve as industry-specific forecast inputs.
Regulatory pathway delays, biomarker assay standardization failures, and isotope supply disruptions are the dominant revision risks to the outlook. Forecasts reflect assumptions regarding PREA compliance timelines and EMA paediatric investigation plan approval rates. Practitioners should monitor FDA pediatric study plan submission volumes and cyclotron facility utilization rates for early signals of supply constraint or regulatory friction.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pediatrics
Pediatric MRI Market
Pediatrics
Pediatric Catheter Market
Pediatrics
Pediatric Nasal Cannula Market
Pediatrics
Pediatric Healthcare Market
Pediatrics
Pediatric Perfusion Products Market
Pediatrics
Pediatric Asthma Treatment Market
Pediatrics
Pediatric HIV Infection Treatment Market
Pediatrics
Pediatric Dental Market
Pediatrics
Middle East and Africa Pediatric Healthcare Market
Pediatrics
Paediatric Wheelchairs Market
Pediatrics
Global Pediatric Home Healthcare Services Market
Pediatrics
OTC Pediatric Healthcare Market
Pediatrics
Paediatric Influenza Treatment Market
Pediatrics
Pediatric Craniosynostosis Treatment Market
Pediatrics
Pediatric Palliative Care Drugs Market
Pediatrics
Pediatric Oncology Treatment Market