
 Pediatric Dental Market | 2026-2036
Pediatric Dental Market Size, Share, and Industry Trends Forecast 2026-2036
Pediatric Dental Market Intelligence
Premium-grade biocompatible material standards is unwinding legacy cost structures across pediatric restorative and orthodontic applications. Danaher Corporation leverages integrated instrument-to-consumable workflows to sustain pricing power in pediatric preventive kits. Henry Schein anchors North American distribution density through exclusive clinic supply contracts. Envista Holdings Corporation differentiates via specialized pediatric imaging hardware that reduces radiation exposure thresholds.
Pediatric dental care encompasses diagnostic, preventive, and therapeutic oral health services tailored to patients from infancy through adolescence, incorporating fluoride varnish formulations with ppm specifications, resin-based sealant chemistries, and nickel-titanium orthodontic archwires engineered for mixed dentition biomechanics. The primary commercial purpose centers on intercepting caries progression and guiding craniofacial development before permanent dentition maturation. Preventive care services generate the most stable recurring revenue streams, while orthodontic treatments capture the highest per-patient lifetime value. Digital imaging technology is displacing conventional radiography fastest among urban pediatric clinic networks seeking throughput gains.
FDA clearance pathways for Class II dental devices and laser dentistry systems govern market access timelines and clinical validation requirements for manufacturers. The American Dental Association's guideline publications on sedation monitoring protocols directly shape liability coverage and clinic accreditation standards. Stakeholders must monitor how teledentistry reimbursement parity legislation evolves across state Medicaid programs to determine capital allocation between physical chair expansion and remote consultation infrastructure.
Market Dynamics
Digital imaging systems are compressing diagnostic timelines across pediatric clinic networks, while FDA Class II device clearance pathways reshape product launch cadences for manufacturers serving this specialty.
Growth Catalysts
- Medicaid Reimbursement Expansion:State-level teledentistry parity legislation in the United States is unlocking remote consultation infrastructure investments among pediatric dental service organizations.
- Biocompatible Material Mandates:Evolving EPA oversight of resin-based sealant chemistries is accelerating formulation upgrades toward BPA-free alternatives in preventive care protocols.
- Orthodontic Demand Concentration:Mixed dentition biomechanics expertise is clustering in urban pediatric specialty networks, concentrating high-lifetime-value patient capture.
Market Restraints
- Nickel-Titanium Input Volatility:Archwire raw material supply concentrates among a limited set of specialty metallurgical suppliers, exposing orthodontic manufacturers to price fluctuation risk.
- Radiation Exposure Liability Thresholds:State dental board sedation monitoring protocols impose escalating malpractice coverage costs on clinics deploying traditional radiography systems.
- Fluoride Varnish Substitution Pressure:Silver diamine fluoride protocols approved by select state Medicaid programs are displacing conventional varnish applications in caries-arrest scenarios.
Strategic Opportunities
- Underpenetrated Rural Networks:Mobile pediatric dental units equipped with portable digital imaging hardware can capture untreated caries prevalence in non-urban United States counties.
- Laser Dentistry Convergence:Integration of soft-tissue laser systems with AI-assisted caries detection software creates premium service tier differentiation for pediatric specialists.
- DSO Supply Contract Consolidation:Exclusive distribution arrangements with dental service organizations enable instrument-to-consumable bundling across multi-clinic pediatric networks.
Industry Challenges
- Pediatric Sedation Certification Bottlenecks:Advanced training requirements for oral conscious sedation are constraining specialist supply expansion in high-demand metropolitan markets.
- Legacy Practice Management Integration:Digital imaging hardware deployment requires costly electronic health record reconfiguration in established independent pediatric clinics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pediatric Dental Market |
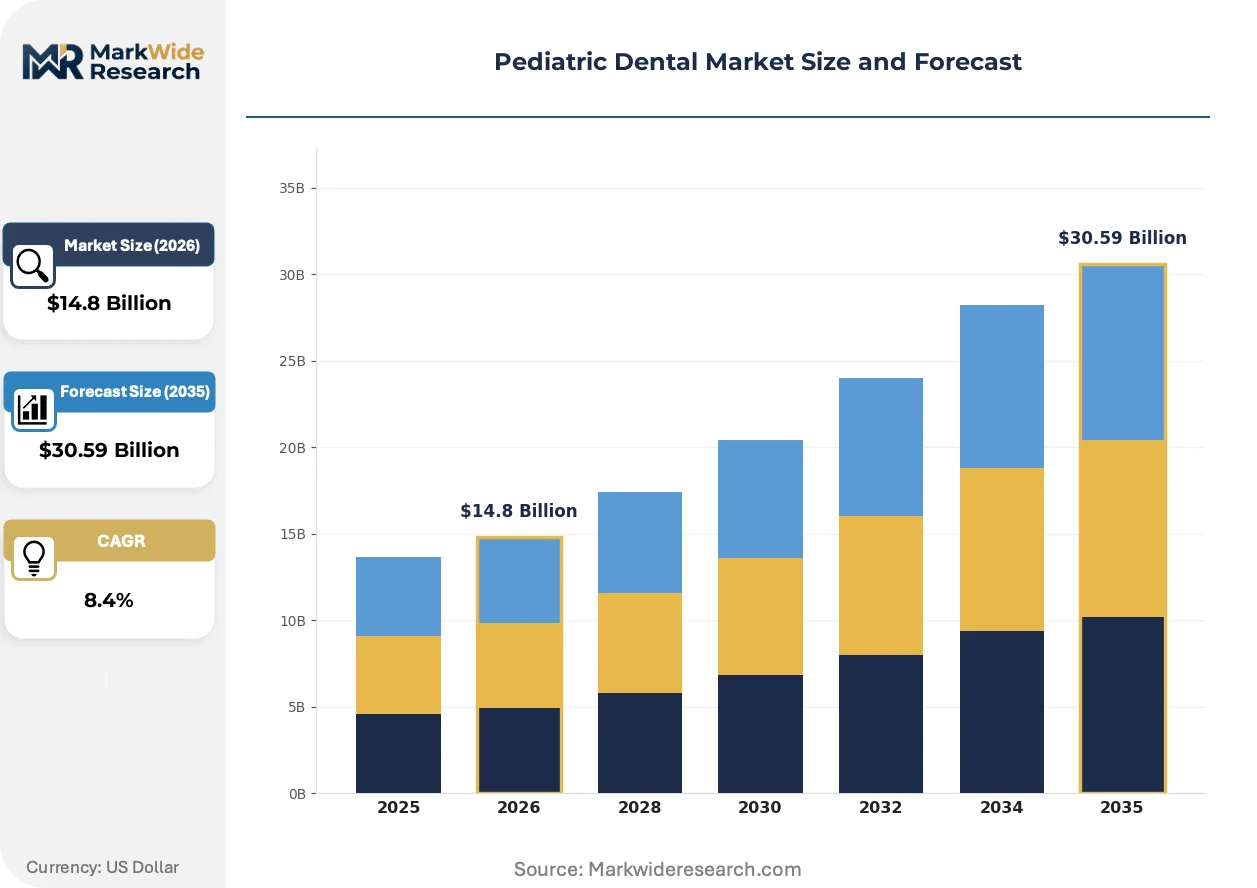
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $30.59 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toothpaste, Mouthwash, Dental Kits, Sealants Service Type: Preventive Care, Orthodontic Treatments, Restorative Services, Emergency Care End User: Parents, Schools, Pediatric Clinics, Hospitals Technology: Digital Imaging, Laser Dentistry, Sedation Techniques, Tele dentistry |
| Companies Covered | Danaher Corporation, Straumann Holding AG, Dentsply Sirona, Patterson Companies, Henry Schein, 3M Company, Envista Holdings Corporation, Zimmer Biomet Holdings, Align Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pediatric Dental Market Strategic Shifts & Innovations
Artificial intelligence-assisted diagnostic tools are rewiring clinical decision support in pediatric oral health, compressing specialist referral timelines while elevating preventive intervention precision.
Cone-beam computed tomography systems engineered for pediatric craniofacial dimensions are bifurcating the imaging market between high-throughput urban clinics and resource-constrained community health centers. Leading pediatric dental service organizations in the United States are deploying these systems to capture orthodontic treatment planning revenue previously referred to external imaging centers. The technology is bifurcating competitive positioning around radiation dose optimization versus capital equipment accessibility.
EPA's emerging framework for dental amalgam separator compliance is mandating wastewater filtration infrastructure investments across clinic networks. The regulation imposes capital expenditure requirements that disproportionately burden independent practitioners compared to consolidated dental service organizations. Pediatric specialists in California and New York are responding through group purchasing organization participation to defray equipment installation costs.
Subscription-based preventive care membership models are displacing traditional fee-for-service structures among commercially insured pediatric populations. Direct-to-employer contracting by pediatric dental networks is bypassing traditional payer intermediaries in Texas and Florida markets. This channel compression is most visible in metropolitan corridors where large self-insured employers concentrate.
Pediatric Dental Market Segmentation
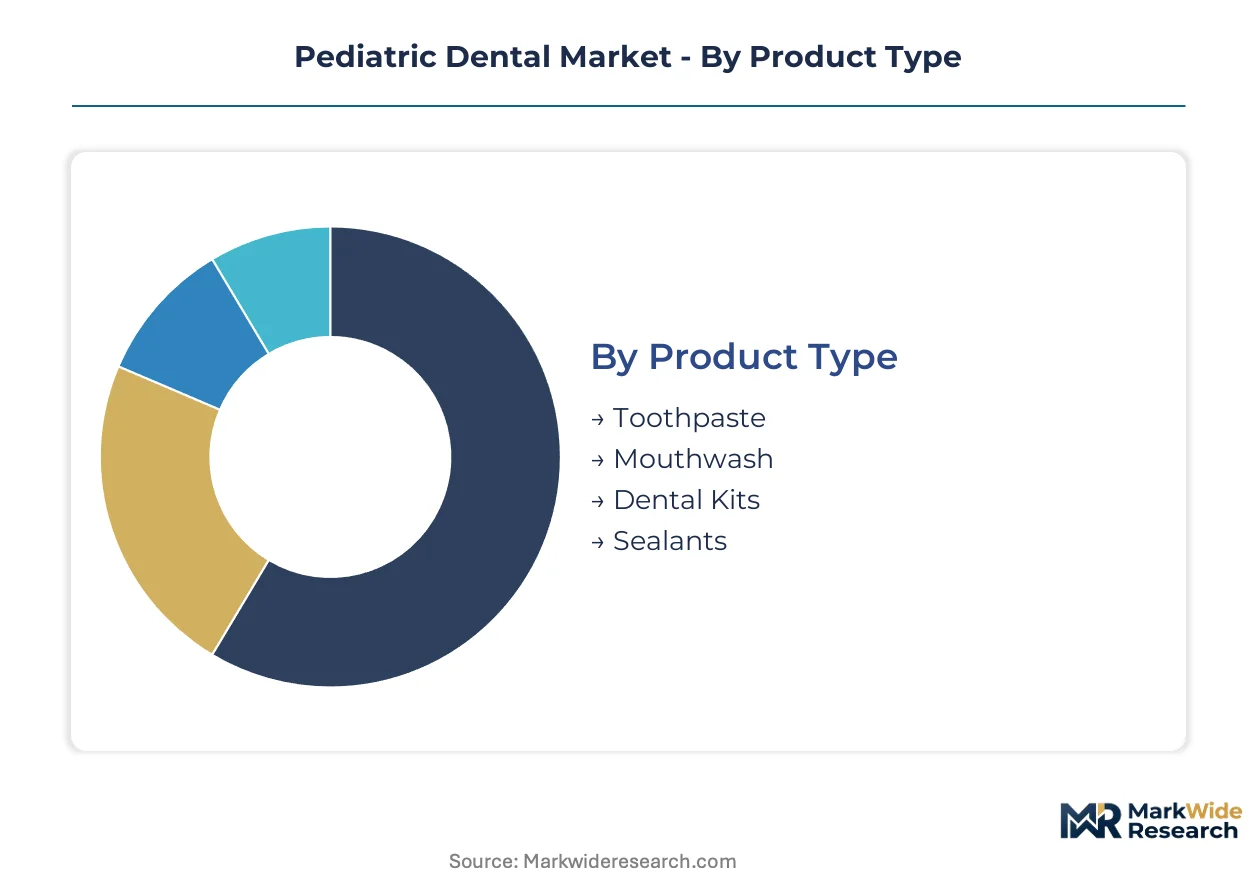
Pediatric dental market segmentation reveals distinct substitution pressures reshaping competitive boundaries across product, service, and technology categories. Understanding where substitute threats concentrate enables stakeholders to defend positioning and allocate capital against displacement risks.
Product Type:
Substitution pressure from alternative caries prevention modalities is fragmenting demand across pediatric oral care product categories, with silver diamine fluoride protocols and prescription-strength formulations eroding conventional product boundaries.
- Toothpaste:Fluoride concentration formulations ranging from 500 ppm to 1,100 ppm dominate daily home care protocols. Demand clusters in mass retail channels and pediatric clinic dispensing programs, pressured by prescription fluoride gel substitutes for high-caries-risk patients.
- Mouthwash:Alcohol-free formulations with cetylpyridinium chloride or essential oil chemistries target compliance-sensitive pediatric populations. School-based prevention programs in Texas and Florida drive institutional procurement volume.
- Dental Kits:Bundled toothbrush-timer-floss combinations support compliance tracking for orthodontic patients.
- Sealants:Resin-based and glass ionomer chemistries deliver occlusal surface protection in clinic settings.
Toothpaste retains volume leadership; sealants hold the steepest expansion curve.
Service Type:
Cost tier stratification across pediatric dental services determines margin capture potential, with preventive protocols commanding stable reimbursement while orthodontic and restorative interventions face escalating input cost pressures.
- Preventive Care:Prophylaxis, fluoride varnish application, and oral hygiene instruction generate recurring revenue with Medicaid reimbursement stability. Pediatric Dental Service Organizations in the United States scale this category through hygienist-staffed hygiene-only appointments.
- Orthodontic Treatments:Early interceptive appliances and comprehensive fixed appliance therapy capture highest per-patient lifetime value. Mixed dentition expertise concentrates in urban specialty networks facing nickel-titanium archwire cost volatility.
- Restorative Services:Composite resin and stainless steel crown placements address caries progression in primary dentition.
- Emergency Care:Trauma management and pulpal therapy address acute presentations.
Preventive care commands volume leadership; orthodontic treatments gain share fastest.
End User:
Customer type diversity across pediatric dental demand creates channel-specific procurement patterns, with institutional purchasers negotiating differently than individual consumers.
- Parents:Primary decision-makers for product purchases and appointment scheduling, influenced by pediatrician referrals and school screening mandates. Direct-to-employer contracting in self-insured markets is compressing traditional payer intermediaries.
- Schools:Sealant program sites and screening coordination hubs for untreated caries identification in non-urban counties.
- Pediatric Clinics:Specialized service delivery sites with sedation certification and orthodontic capability.
- Hospitals:Operating room dental rehabilitation venues for severe early childhood caries under general anesthesia.
Parents drive volume leadership; pediatric clinics show the steepest expansion trajectory.
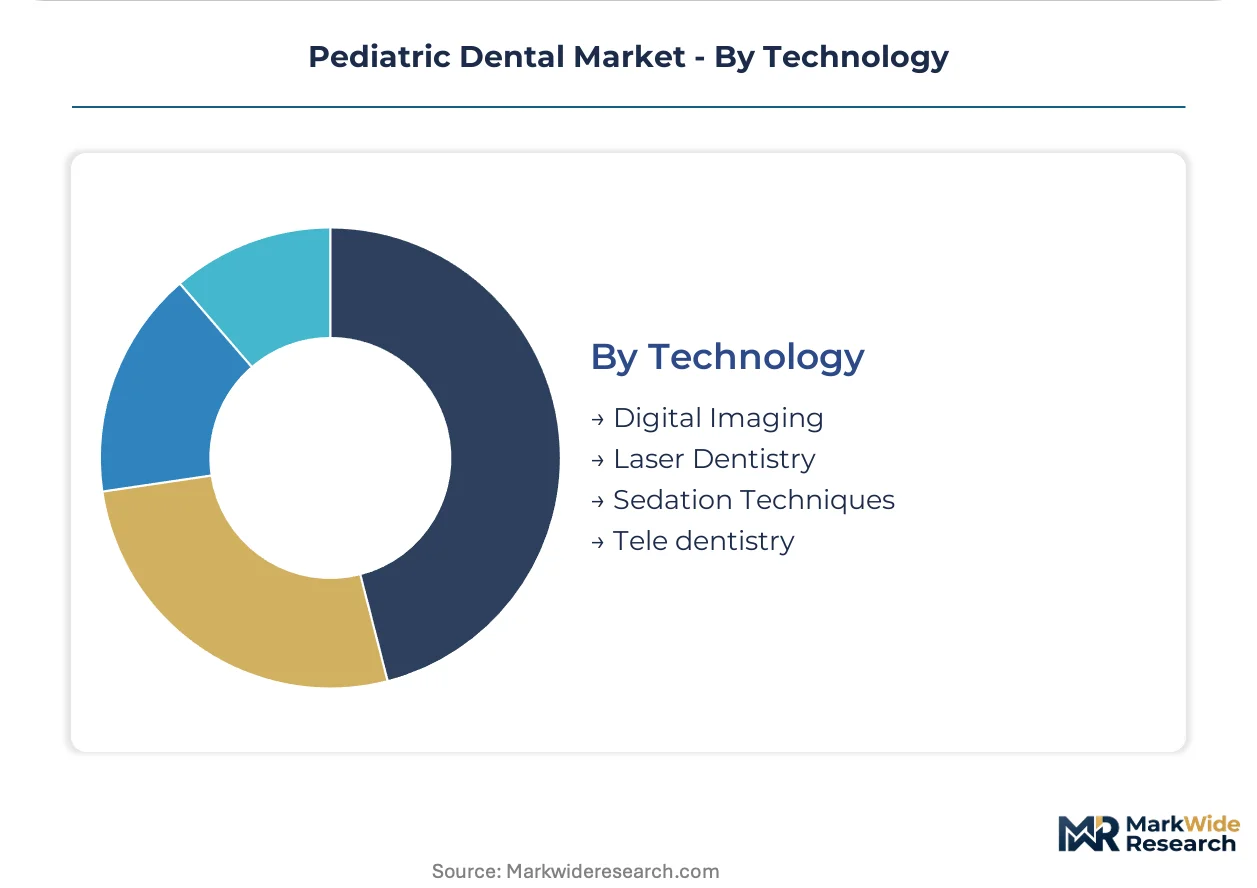
Technology:
Application-specific technology deployment in pediatric dentistry varies by clinical setting throughput requirements and capital accessibility constraints.
- Digital Imaging:Cone-beam computed tomography and intraoral scanners reduce radiation exposure while compressing diagnostic timelines. Urban clinic networks deploy these systems to capture orthodontic treatment planning revenue previously referred externally.
- Laser Dentistry:Soft-tissue diode systems enable frenectomy and exposure procedures with reduced anesthesia requirements. Integration with AI-assisted caries detection software creates premium service tier differentiation.
- Sedation Techniques:Oral conscious sedation and nitrous oxide administration require specialized certification constraining specialist supply expansion.
- Tele dentistry:Remote consultation platforms unlock rural market access under state-level Medicaid parity legislation.
Digital imaging retains volume leadership; tele dentistry holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pediatric dental supply chains concentrate heavily in the United States, where integrated dental service organizations drive procurement volume. Manufacturing of nickel-titanium archwires and digital imaging systems clusters in select industrial corridors across North America, Europe, and Asia-Pacific.
United States
DSO networks in Texas and Florida negotiate exclusive supply contracts that compress distributor margins. FDA Class II device clearance pathways govern market access timelines for digital imaging hardware manufacturers. Pediatric specialty clusters in Houston and Miami deploy cone-beam computed tomography systems to capture orthodontic treatment planning revenue internally.
Germany
Precision metallurgical suppliers in Baden-Württemberg produce nickel-titanium alloys for orthodontic archwire applications. CE marking requirements under EU MDR shape product launch cadences for dental device manufacturers. Stuttgart-area engineering firms specialize in radiation dose optimization technologies for pediatric craniofacial imaging systems.
China
Domestic manufacturing of fluoride varnish formulations scales to meet institutional procurement contracts across provincial health systems. NMPA medical device registration requirements extend validation timelines for foreign imaging hardware entrants. Shanghai-based dental service chains expand pediatric specialty networks through acquisition of independent practitioner clinics.
Japan
PMDA approval pathways for laser dentistry systems create differentiated market access conditions versus Western regulators. Tokyo metropolitan pediatric clinics lead adoption of AI-assisted caries detection software integrated with intraoral scanners. Osaka-area manufacturers supply glass ionomer sealant chemistries to school-based prevention programs across Asia-Pacific.
India
State-level school screening mandates in Maharashtra and Karnataka drive institutional demand for portable dental kits. CDSCO medical device rules govern import licensing for digital radiography systems deployed in urban pediatric networks. Bengaluru-based dental chains consolidate through private equity backing to capture orthodontic patient lifetime value.
Pediatric Dental Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the pediatric dental market. Integrated conglomerates with instrument-to-consumable workflows command premium pricing in preventive care categories, while specialized orthodontic manufacturers compete on nickel-titanium alloy engineering precision. Three archetypes dominate: diversified healthcare conglomerates with dental divisions, pure-play dental device specialists, and regional distribution consolidators. Competitive moves center on exclusive DSO supply contracting and backward integration into biocompatible material formulation.
Among diversified healthcare conglomerates, Danaher Corporation and 3M Company exemplify the integrated instrumentation model, while Henry Schein anchors North American distribution density through clinic supply relationships. Straumann Holding AG occupies a specialized position in orthodontic and implantology segments. These three entities represent distinct strategic postures—technology integration, procurement scale, and clinical specialization—without any single archetype commanding unified market leadership.
| Leading Market Players |
|---|
| Danaher Corporation |
| Straumann Holding AG |
| Dentsply Sirona |
| Patterson Companies |
| Henry Schein |
| 3M Company |
| Envista Holdings Corporation |
| Zimmer Biomet Holdings |
| Align Technology |
| Others |
Cost & Logistics Intelligence
Capacity utilization at nickel-titanium alloy foundries in Baden-Württemberg and precision imaging sensor fabs in East Asia shapes both supply concentration and price floors across pediatric dental product tiers. Scale advantages in preventive consumables manufacturing compress margins for mid-tier entrants while premium orthodontic archwire producers retain pricing power through metallurgical IP.
Pricing Analysis
FDA Class II device clearance pathways dictate the pricing tier structure across pediatric dental equipment categories, separating premium imaging systems with reduced radiation exposure from standard diagnostic hardware. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Cost compression in economy-tier preventive kits is intensifying because of silver diamine fluoride substitution pressure from state Medicaid programs. School-based procurement managers show highest price sensitivity; specialized pediatric dental service organizations demonstrate lowest sensitivity due to lifetime value capture from orthodontic patient retention.
Supply Chain Analysis
Container availability fluctuations on Asia-Pacific to North America trade lanes expose orthodontic manufacturers to inbound logistics cost volatility for nickel-titanium raw material. Supply concentrates in Germany for precision metallurgical components, China for fluoride varnish formulations, and Japan for glass ionomer sealant chemistries. Raw material dependencies include nickel-titanium alloys for archwires, rare-earth phosphors for digital sensors, and resin monomers for sealant formulations. Single-source vulnerability concentrates in specialty nickel-titanium suppliers serving orthodontic wire producers. Distribution runs through exclusive dental service organization contracts and group purchasing organization aggregators in Texas and Florida.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in rural pediatric dental access gaps created by teledentistry reimbursement parity expansion across state Medicaid programs. This demand-side shift creates service niches outside urban specialty network dominance.
For Market Incumbents: Secure exclusive supply contracts with expanding dental service organizations to lock in instrument-to-consumable bundling revenue. Anchor backward integration into BPA-free sealant formulation capacity to defend against EPA-driven material substitution threats. Capture orthodontic treatment planning revenue internally through cone-beam computed tomography deployment before referral relationships erode.
For New Entrants and Emerging Players: Mobile pediatric dental unit deployment in non-urban United States counties addresses the service-layer gap where incumbents under-serve untreated caries prevalence. Target school-based sealant program procurement in Texas and Florida through direct institutional contracting. Pursue AI-assisted caries detection software integration with portable imaging hardware as the go-to-market angle for premium service tier positioning.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized pediatric imaging hardware producers with radiation dose optimization IP. Long-term viability hinges on consolidation capture within orthodontic patient lifetime value chains rather than commoditized preventive consumables. Acquisition target archetype: regional dental service organizations with sedation certification infrastructure and mixed dentition expertise. Watch state Medicaid teledentistry parity legislation velocity as the inflection indicator for remote consultation infrastructure valuation.
| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive DSO Supply Contracting | Locks in multi-clinic procurement volume across Texas and Florida pediatric networks. |
| BPA-Free Sealant Formulation Upgrade | Aligns product portfolios with EPA emerging oversight of resin-based chemistries. |
| Cone-Beam CT System Deployment | Captures orthodontic treatment planning revenue previously referred to external imaging centers. |
| AI-Assisted Caries Detection Integration | Creates premium service tier differentiation for pediatric specialists in urban markets. |
| Mobile Unit Rural Network Expansion | Addresses untreated caries prevalence in non-urban United States counties with portable hardware. |
Research Approach
A standing panel of pediatric dental clinic operators, orthodontic supply procurement managers, biomedical equipment engineers, and state Medicaid program administrators provided ongoing calibration across primary interview cycles. This stakeholder input combined with secondary validation from FDA 510(k) clearance databases, CMS Medicare pediatric dental utilization files, and state-level teledentistry legislation tracking systems. Bottom-up clinic capacity modeling and top-down dental service organization revenue aggregation enabled triangulation across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including service type, product chemistry, technology deployment model, and end-user procurement channel. CAGRs derived from procedure volume elasticity assumptions and reimbursement rate trajectory modeling. Industry-specific forecast inputs incorporated nickel-titanium alloy price indices and digital imaging hardware replacement cycle data.
Forecasts assume regulatory continuity in FDA device clearance pathways and state Medicaid program structures; material policy shifts would require re-modeling. Specific risk factors include EPA dental amalgam separator compliance timeline acceleration and nickel-titanium supply concentration disruption. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pediatrics
Pediatric Catheter Market
Pediatrics
Pediatric Healthcare Market
Pediatrics
Pediatric Chronic Rhinosinusitis Market
Pediatrics
Autism Service Platform Market
Pediatrics
Pediatric Perfusion Products Market
Pediatrics
Pediatric Brain Tumor Market
Pediatrics
OTC Pediatric Healthcare Market
Pediatrics
Pediatric Tube Feeding Market
Pediatrics
Pediatric Obesity Management Market
Pediatrics
Global Cerebral Palsy Treatment Market
Pediatrics
Pediatric Mattress Market
Pediatrics
Pediatric Asthma Treatment Market
Pediatrics
Paediatric Wheelchairs Market
Pediatrics
Pediatric Growth Hormone Deficiency Market
Pediatrics
Global Pediatric Home Healthcare Services Market
Pediatrics
Pediatric MRI Market