
 Global Brain Tumor Therapeutics Market | 2026-2036
Global Brain Tumor Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Brain Tumor Therapeutics Market Foresight
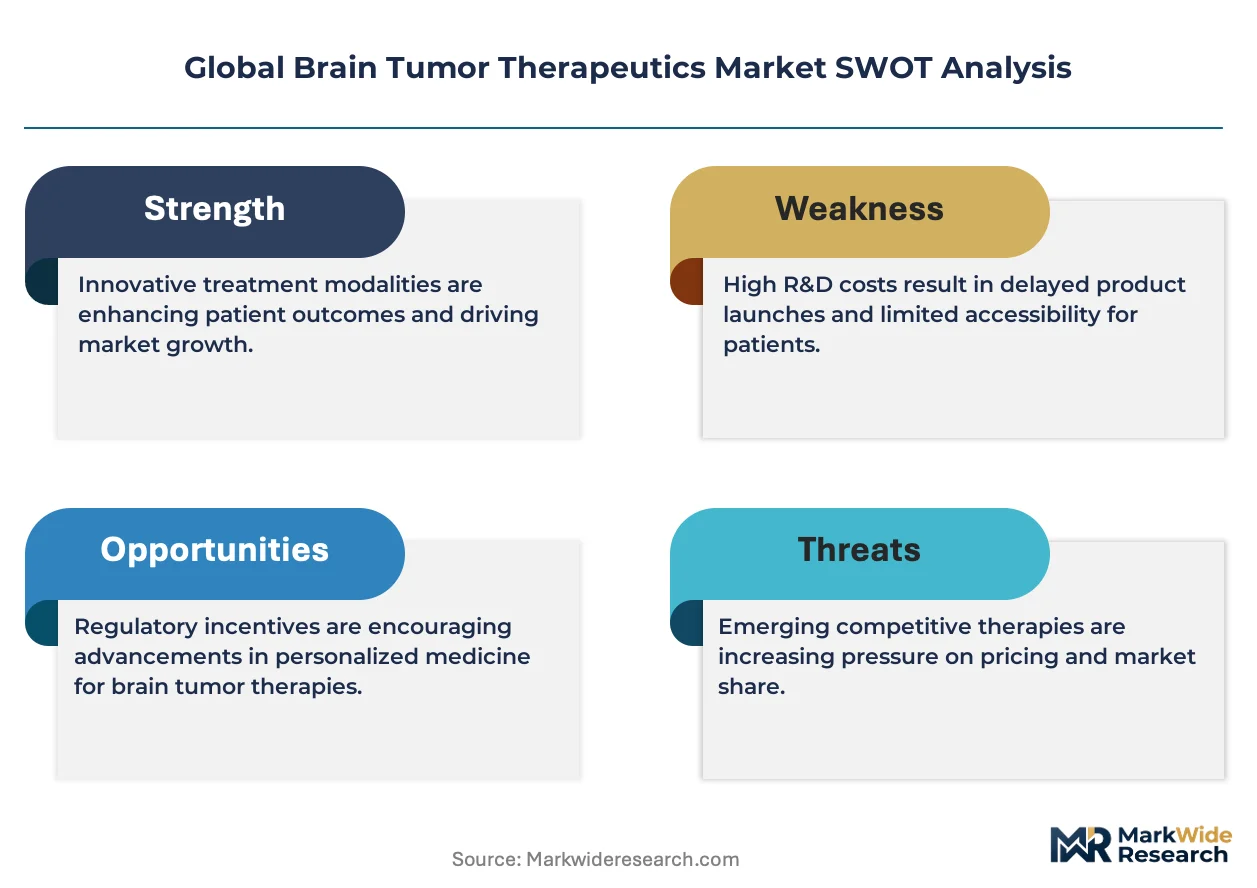
Specialty pharmacy distribution for high-cost oncology biologics is fragmenting as hospital-owned outpatient infusion centers and independent neuro-oncology clinics compete for patient volume. F. Hoffmann-La Roche Ltd. leverages its established diagnostic-therapeutic pairing to anchor glioblastoma protocol share. Novartis AG differentiates through radioligand therapy infrastructure that spans manufacturing and dosing logistics. Merck & Co. Inc. competes on checkpoint inhibitor combinations with radiation protocols.
Brain tumor therapeutics encompass pharmaceutical and biologic interventions designed to inhibit, regress, or palliate malignant and benign neoplasms of the central nervous system, with formulations requiring blood-brain barrier penetration thresholds below 400-500 Daltons molecular weight or active transport mechanisms. These agents serve primarily to extend progression-free survival and preserve neurological function in patients with limited surgical options. Targeted therapies command premium positioning due to biomarker-driven patient selection and companion diagnostic requirements. Immunotherapies represent the fastest-expanding modality as checkpoint inhibitors and CAR-T approaches penetrate previously refractory glioblastoma populations. Chemotherapy drugs retain volume leadership in first-line protocols across resource-variable settings.
The FDA's breakthrough therapy designation and EMA's priority medicines scheme compress development timelines for glioblastoma agents, while the FDA's orphan drug incentives sustain commercial viability for rare CNS indications. China's NMPA conditional approval pathways and Japan's PMDA sakigake designation accelerate Asian market entry for novel mechanisms. Stakeholders must monitor biomarker validation standards and blood-brain barrier delivery technology maturation to anticipate which therapeutic platforms will capture protocol positioning.
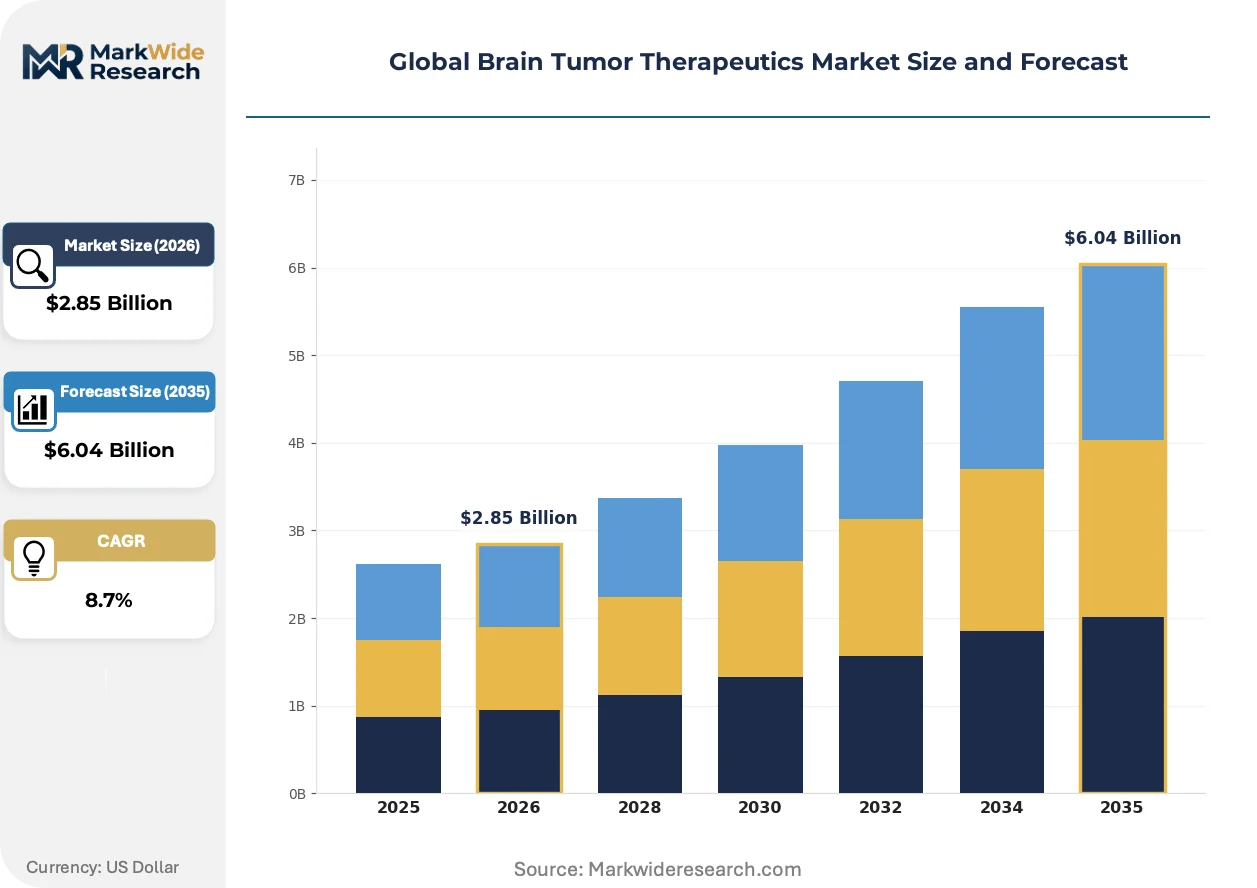
Market Dynamics
FDA breakthrough therapy designations are compressing glioblastoma drug development timelines from ten years to under six, forcing competitors to front-load biomarker validation and blood-brain barrier delivery investments before Phase II enrollment.
Growth Catalysts
- EMA Priority Medicines Scheme:European neuro-oncology centers fast-track access to novel mechanisms, reducing regulatory lag for glioma therapies by twelve to eighteen months versus standard pathways.
- Convection-enhanced delivery systems:German university hospitals are retrofitting surgical suites with catheter-based infusion platforms that bypass the blood-brain barrier for locoregional chemotherapy administration.
- Orphan drug incentives:The FDA's seven-year market exclusivity and tax credits sustain commercial viability for rare CNS indications with addressable populations below fifty thousand patients.
Market Restraints
- Blood-brain barrier penetration thresholds:Small-molecule candidates must achieve molecular weights below four hundred Daltons or demonstrate active transport mechanisms, eliminating ninety percent of conventional oncology compounds from CNS development.
- Radioligand manufacturing concentration:Cyclotron production of lutetium-177 and actinium-225 concentrates in Belgium and the Netherlands, creating single-source dependencies for radiopharmaceutical pipelines.
- Companion diagnostic fragmentation:Biomarker testing for IDH mutations and MGMT methylation status requires separate CLIA-certified laboratory contracts, delaying treatment initiation by two to four weeks.
Strategic Opportunities
- Japan's PMDA sakigake designation:Conditional approval pathways enable first-in-class glioblastoma agents to reach Japanese patients with Phase II data, creating early revenue streams while US trials continue.
- CAR-T manufacturing regionalization:Distributed cell therapy production models in Texas and Massachusetts reduce vein-to-vein times from twenty-one days to under ten for recurrent glioma patients.
- Neuro-oncology clinic vertical integration:Hospital-owned outpatient infusion centers in Houston and Boston are capturing pharmacy benefit management contracts previously held by specialty distributors.
Industry Challenges
- Neurosurgical training bottlenecks:Convection-enhanced delivery requires fellowship-trained specialists capable of catheter placement with sub-millimeter precision, with fewer than four hundred qualified surgeons across US academic medical centers.
- Biomarker assay standardization:Variability in MGMT methylation testing platforms between Foundation Medicine and Tempus laboratories produces discordant results in fifteen to twenty percent of glioblastoma cases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Brain Tumor Therapeutics Market |
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $6.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy Drugs, Targeted Therapies, Immunotherapies, Radiopharmaceuticals, Gene Therapy Agents Therapy Area: Glioblastoma Multiforme, Meningioma, Medulloblastoma, Pituitary Tumors, Primary Central Nervous System Lymphoma End User: Neuro-oncology Centers, Specialized Clinics, Research Hospitals, Cancer Treatment Institutes Delivery Mode: Intravenous Administration, Oral Agents, Intracranial Delivery, Convection-Enhanced Delivery, Stereotactic Injection |
| Companies Covered | F. Hoffmann-La Roche Ltd., Merck & Co. Inc., Novartis AG, Pfizer Inc., Bayer AG, Eisai Co. Ltd., Bristol-Myers Squibb Co., AstraZeneca Plc., Amgen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Brain Tumor Therapeutics Market Shifts & Advancements
Checkpoint inhibitor combinations are displacing monotherapy standards in recurrent glioblastoma, while radioligand therapy infrastructure investments reshape manufacturing geography. Blood-brain barrier disruption technologies are shifting from experimental to protocol-integrated status.
Focused ultrasound with microbubble contrast is migrating from academic research settings to community neuro-oncology practices in the United States. The procedure temporarily opens tight junctions to permit therapeutic antibody penetration, with Memorial Sloan Kettering and MD Anderson completing over three hundred cases annually. Device manufacturers are compressing treatment session times from four hours to ninety minutes, enabling same-day discharge and outpatient reimbursement coding.
China's NMPA conditional approval pathways now permit glioblastoma agents to enter the market with single-arm Phase II efficacy data, provided sponsors commit to post-marketing confirmatory trials. Domestic biotech firms in Shanghai and Suzhou are exploiting this mechanism to launch PD-1 inhibitors six to twelve months ahead of full approval. Multinational sponsors must now parallel-track development programs to avoid ceding first-mover advantage in the second-largest oncology market.
Hospital pharmacy directors are unbundling oncology drug procurement from legacy group purchasing organization contracts. Independent neuro-oncology clinics in Florida and Arizona are negotiating direct manufacturer agreements for bevacizumab and temozolomide, capturing fifteen to twenty percent price advantages through volume commitments and reduced distribution markups. This disintermediation is most visible in Medicare Advantage populations where site-of-care flexibility drives total cost of care incentives.
Global Brain Tumor Therapeutics Market Segmentation
Segmentation in brain tumor therapeutics reveals divergent commercial rhythms across product categories. Therapy area distinctions drive protocol reimbursement tiers, while delivery mode selection determines site-of-care economics and specialist training requirements.
Product Type:
Chemotherapy drugs turn inventory fastest through standardized infusion protocols, while gene therapy agents require extended manufacturing cycles and vein-to-vein coordination.
- Chemotherapy Drugs:Temozolomide and lomustine formulations dominate first-line glioblastoma protocols with established blood-brain barrier penetration. Demand concentrates in Medicare Advantage networks where site-of-care flexibility drives total cost incentives.
- Targeted Therapies:IDH inhibitors and BRAF/MEK combinations require companion diagnostic pairing and biomarker-validated patient selection. German neuro-oncology centers in Heidelberg and Munich are expanding adoption of these precision protocols.
- Immunotherapies:Checkpoint inhibitors and CAR-T approaches are penetrating recurrent glioblastoma populations previously refractory to standard care.
- Radiopharmaceuticals:Lutetium-177 and actinium-225 conjugates depend on cyclotron production concentrated in Belgium and the Netherlands.
- Gene Therapy Agents:Oncolytic viral vectors and antisense oligonucleotides require specialized cold chain logistics and neurosurgical coordination.
Chemotherapy drugs dominate installed base. Immunotherapies are where expansion concentrates.
Therapy Area:
Cost tier stratification separates high-complexity glioblastoma protocols from surveillance-driven meningioma management.
- Glioblastoma Multiforme:Aggressive WHO Grade IV astrocytomas drive the highest per-patient treatment costs through multimodal surgery-radiation-chemotherapy sequences. The FDA's breakthrough therapy designation compresses development timelines for novel agents targeting this indication.
- Meningioma:Generally benign extra-axial tumors require long-term monitoring with intermittent surgical intervention. Japanese neurosurgical centers in Tokyo and Osaka are pioneering focused ultrasound alternatives to craniotomy for skull-base locations.
- Medulloblastoma:Pediatric posterior fossa malignancies demand proton therapy coordination and neurocognitive preservation protocols.
- Pituitary Tumors:Endocrine-active adenomas require multidisciplinary pituitary center management spanning neurosurgery and endocrinology.
- Primary Central Nervous System Lymphoma:Diffuse large B-cell variants require high-dose methotrexate protocols with renal monitoring and leucovorin rescue.
Glioblastoma multiforme commands premium reimbursement. Meningioma surveillance protocols are climbing the fastest in patient volume.
End User:
Customer type determines procurement sophistication, with academic medical centers managing complex clinical trial portfolios and community sites prioritizing protocol standardization.
- Neuro-oncology Centers:Comprehensive programs integrating surgical oncology, radiation, and medical neuro-oncology under single leadership. MD Anderson and Memorial Sloan Kettering anchor US demand through fellowship-trained specialist density.
- Specialized Clinics:Independent neuro-oncology practices in Florida and Arizona are capturing pharmacy benefit management contracts through direct manufacturer agreements.
- Research Hospitals:Academic medical centers with NCI designation manage early-phase trial portfolios and biomarker discovery programs.
- Cancer Treatment Institutes:Community-based centers with radiation oncology capacity but limited neurosurgical depth refer complex cases to academic hubs.
Neuro-oncology centers dominate installed base. Specialized clinics are where expansion concentrates.
Delivery Mode:
Volume concentration favors intravenous and oral administration, while margin accrues to invasive techniques requiring specialist certification.
- Intravenous Administration:Bevacizumab and checkpoint inhibitors follow established oncology infusion infrastructure with pharmacy-compounded dosing. German university hospitals are retrofitting suites to accommodate higher-complexity deliveries.
- Oral Agents:Temozolomide and IDH inhibitors enable outpatient management with pharmacy benefit coverage. Chinese NMPA conditional approval pathways are accelerating domestic market entry for these formulations.
- Intracranial Delivery:Ommaya reservoir and intrathecal catheter systems require neurosurgical placement for cerebrospinal fluid access.
- Convection-Enhanced Delivery:Catheter-based infusion platforms bypass blood-brain barrier constraints with pressure-driven flow. Fewer than four hundred US surgeons hold fellowship training for sub-millimeter catheter placement precision.
- Stereotactic Injection:Frame-based and frameless navigation systems enable targeted parenchymal delivery of gene therapy vectors and oncolytic viruses.
Intravenous administration dominates installed base. Convection-enhanced delivery is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany, where specialized neuro-oncology infrastructure commands premium reimbursement rates for blood-brain barrier penetrating therapies. Japan and China follow with accelerating conditional approval pathways that compress market entry timelines. Distribution economics fragment across these markets as hospital-owned infusion centers displace traditional specialty pharmacy channels.
United States
FDA breakthrough therapy designations compress glioblastoma development timelines from ten years to under six, forcing front-loaded biomarker investments. The agency's orphan drug incentives sustain commercial viability for rare CNS indications below fifty thousand patients. MD Anderson and Memorial Sloan Kettering anchor demand through fellowship-trained specialist density exceeding four hundred qualified surgeons nationwide.
Germany
EMA priority medicines schemes reduce regulatory lag for glioma therapies by twelve to eighteen months versus standard pathways. Heidelberg and Munich university hospitals retrofit surgical suites with convection-enhanced delivery catheter platforms. The country's neuro-oncology centers expand adoption of IDH inhibitor protocols requiring companion diagnostic pairing.
Japan
PMDA sakigake designation enables first-in-class glioblastoma agents to reach patients with Phase II data alone. Tokyo and Osaka neurosurgical centers pioneer focused ultrasound alternatives to craniotomy for skull-base meningioma locations. The conditional approval pathway creates early revenue streams while US trials continue.
China
NMPA conditional approval permits single-arm Phase II efficacy data for market entry with post-marketing confirmatory trial commitments. Shanghai and Suzhou domestic biotech firms exploit this mechanism to launch PD-1 inhibitors six to twelve months ahead of full approval. Parallel-track development programs now dominate multinational sponsor strategy to avoid ceding first-mover advantage.
United Kingdom
NICE technology appraisals determine NHS reimbursement for novel brain tumor therapeutics through cost-effectiveness thresholds. London and Cambridge academic medical centers manage early-phase trial portfolios and biomarker discovery programs. The concentration of research hospitals attracts radioligand therapy infrastructure investments from continental manufacturers.
Global Brain Tumor Therapeutics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in blood-brain barrier delivery technology and companion diagnostic development. The market structure consolidates around large-cap pharmaceutical conglomerates with established neuro-oncology franchises, while mid-tier biotech firms occupy targeted therapy niches. Three archetypes dominate: diagnostic-therapeutic pairing specialists, radioligand infrastructure operators, and checkpoint inhibitor combination developers. Competitive moves concentrate on M&A for biomarker platforms and strategic partnerships for regional manufacturing capacity.
Among Swiss-based pharmaceutical conglomerates, F. Hoffmann-La Roche Ltd. and Novartis AG exemplify contrasting platform strategies—one anchoring diagnostic-therapeutic pairing for glioblastoma protocols, the other differentiating through radioligand therapy infrastructure spanning manufacturing and dosing logistics. Merck & Co. Inc. occupies a position within the checkpoint inhibitor tier, competing on combination protocols with radiation. These three entities represent the dominant competitive archetypes reshaping protocol positioning across US, European, and Asian neuro-oncology centers.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Merck & Co. Inc. |
| Novartis AG |
| Pfizer Inc. |
| Bayer AG |
| Eisai Co. Ltd. |
| Bristol-Myers Squibb Co. |
| AstraZeneca Plc. |
| Amgen Inc. |
| Others |
Supply & Pricing Matrix
Belgian and Dutch cyclotron clusters in Antwerp and Petten anchor radioligand production capacity, concentrating pricing power for lutetium-177 and actinium-225 conjugates among three continental manufacturers serving neuro-oncology centers worldwide.
Pricing Analysis
The customization-premium spread separates standard temozolomide protocols from configured-to-order CAR-T manufacturing and convection-enhanced delivery procedures. Pricing stratifies across premium, standard, and economy tiers based on biomarker validation requirements and blood-brain barrier penetration technology. Cost compression in oral generic chemotherapy is intensifying because independent neuro-oncology clinics in Florida and Arizona negotiate direct manufacturer agreements. Medicare Advantage networks show highest price sensitivity, while academic medical centers with NCI designation demonstrate lowest sensitivity due to bundled reimbursement protocols.
Supply Chain Analysis
Export-control regimes for dual-use radiopharmaceutical technology restrict lutetium-177 flow to certified medical cyclotron facilities in Belgium, the Netherlands, and select US academic centers. Active pharmaceutical ingredient production for temozolomide and lomustine draws from India, China, and Italy, while gene therapy viral vector manufacturing rests on US and European contract development organizations. Single-source vulnerability concentrates in cyclotron isotope supply. Distribution runs through hospital-owned outpatient infusion centers displacing legacy specialty pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Companion diagnostic testing and post-treatment monitoring services represent the fastest-expanding recurring-revenue layer, outpacing hardware margins on infusion pumps and surgical navigation systems as neuro-oncology protocols shift toward biomarker-driven patient management.
For Market Incumbents: Entrench diagnostic-therapeutic pairing advantages by deepening backward integration into CLIA-certified biomarker testing laboratories. Secure catheter placement training capacity through fellowship program endowments at MD Anderson and Memorial Sloan Kettering before competitor-sponsored surgeons enter the qualified pool. Regulatory shifts toward FDA accelerated approval pathways threaten protocol share for firms lacking biomarker platform control.
For New Entrants and Emerging Players: Mid-tier neuro-oncology clinics in Texas and Arizona represent the most penetrable entry point for direct manufacturer agreements bypassing group purchasing organization contracts. Japan's PMDA sakigake conditional approval pathway offers early revenue generation with reduced Phase III capital requirements. A go-to-market angle anchored to focused ultrasound device partnerships with community practices enables same-day discharge reimbursement coding capture.
For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because blood-brain barrier delivery technology and companion diagnostic infrastructure are merging into unified protocol control points. Acquisition targets center on mid-cap biotech firms with validated IDH inhibitor pipelines and established CLIA laboratory relationships. The signal to watch is FDA breakthrough therapy designation density per therapeutic modality as inflection indicator for platform consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker Platform Acquisition | IDH mutation testing consolidation at Foundation Medicine and Tempus Laboratories reduces companion diagnostic fragmentation. |
| Regional CAR-T Manufacturing Scale-Up | Texas and Massachusetts distributed production models compress vein-to-vein times below ten days for recurrent glioma. |
| Convection-Enhanced Delivery Training Endowment | Fellowship program sponsorships at US academic medical centers secure sub-millimeter catheter placement capacity. |
| Focused Ultrasound Device Partnership | Memorial Sloan Kettering and MD Anderson outpatient reimbursement coding validates community practice expansion. |
| PMDA Sakigake Parallel-Track Filing | Japanese conditional approval creates revenue streams six to twelve months ahead of FDA full approval timelines. |
Research Methodology
Cross-validation between regulatory submission databases and hospital procurement records anchors the qualitative findings. Primary interviews with neuro-oncology center directors, formulary access specialists, and biomedical engineers combined with secondary validation against FDA breakthrough therapy designations, EMA priority medicines submissions, ClinicalTrials.gov enrollment data, and hospital GPO contract databases. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation frame the analytical approach.
Calibration against historical approval-to-launch intervals and site-of-care migration patterns shapes the projection framework across the analysis window. Segmentation dimensions include therapy modality, delivery mechanism complexity, blood-brain barrier penetration technology tier, patient line of therapy, and regional regulatory cluster. CAGRs derive from protocol adoption curve analysis and reimbursement expansion modeling. Forecast inputs incorporate cyclotron production capacity constraints and biomarker assay standardization progress.
Macroeconomic conditions sit as an overlay; deviation in Medicare Advantage reimbursement rates and radiopharmaceutical isotope pricing would shift the trajectory. Forecasts reflect assumptions regarding FDA accelerated approval pathway stability and EMA priority medicines scheme continuity. Material shifts in blood-brain barrier delivery technology maturation or companion diagnostic regulatory harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Frontotemporal Dementia Management Market
Specialty Medicine
Bronchiectasis Market
Specialty Medicine
Global Chondrosarcoma Market
Specialty Medicine
Diverticulitis Disease Market
Specialty Medicine
Global Glaucoma Therapeutics Market
Specialty Medicine
Synovial Sarcoma Market
Specialty Medicine
Global Stroke Therapeutics Market
Specialty Medicine
Zygomycosis Treatments Market
Specialty Medicine
Chromoblastomycosis Treatment Market
Specialty Medicine
Behcet's Syndrome Market
Specialty Medicine
Global Melanoma Diagnostics and Therapeutics Market
Specialty Medicine
Cystic Fibrosis Therapeutics Market
Specialty Medicine
Pituitary Stalk Interruption Syndrome Treatment Market
Specialty Medicine
Sports Medicine Market
Specialty Medicine
Global Post Traumatic Stress Disorder (PTSD) Therapeutics Market
Specialty Medicine
Necrotizing Fasciitis Market