
 Pea Hull Fiber Market | 2026-2036
Pea Hull Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Pea Hull Fiber Market Analytics
Mechanical fractionation is narrowing the cost gap between pea hull fiber and established cereal fibers like wheat bran and oat fiber. Roquette Frères leverages its vertically integrated pea processing network in France and Canada to secure captive hull supply. Cosucra Groupe Warcoing anchors its fiber positioning through non-GMO and organic certification tiers that command premium placement in European retail channels.
Pea hull fiber comprises the outer seed coat of Pisum sativum, typically containing 65-75% total dietary fiber with a balanced ratio of insoluble to soluble fractions, and functions primarily as a bulking agent, moisture binder, and clean-label texturizer in reduced-calorie and gluten-free formulations. Functional Fibers dominate current volume as formulators substitute pea hull for modified starches in meat analogues and baked goods, while Hydrocolloids extract the highest margin per kilogram through specialized gelling applications in dairy alternatives. Powder form leads industrial uptake due to seamless dispersion in standard mixing equipment, though Flakes are gaining traction in granola and savory snack applications where visual texture differentiation matters.
The FDA's 2016 Nutrition Facts rule and subsequent 2021 guidance on isolated fibers shape which pea hull fiber variants qualify for fiber gram declarations on U.S. labels, directly influencing formulation decisions by Food Manufacturers and Pharmaceutical Companies. In Europe, EFSA health claim assessments under Regulation 1924/2006 determine whether pea fiber can carry digestive health or glycemic response messaging, with EFSA's 2011 Article 13.1 general function claims process setting the evidentiary bar. Stakeholders must monitor evolving fiber definition harmonization between FDA and Codex Alimentarius frameworks, as divergent standards threaten to fragment export compliance requirements for multi-territory product lines.
Market Dynamics
Mechanical fractionation advances are compressing conversion costs for pea hull fiber, narrowing the historic premium over commodity cereal fibers and enabling broader substitution in mainstream food manufacturing.
Growth Catalysts
- Clean-label mandates:EFSA's evolving stance on fiber health claims under Regulation 1924/2006 is prompting European formulators to seek minimally processed texturizers that qualify for digestive wellness messaging.
- Plant-based meat expansion:Food manufacturers in meat analogue production are substituting pea hull fiber for modified starches to achieve moisture retention without synthetic additives.
- Pea protein infrastructure:United States processing capacity expansion is generating captive hull byproduct streams that lower raw material procurement costs for fiber extractors.
Market Restraints
- Input cost volatility:Yellow pea prices fluctuate with Canadian prairie weather patterns and export demand to Asian markets, compressing processor margins.
- Supply concentration:Roquette Frères and Cosucra Groupe Warcoing control substantial European pea fractionation capacity, creating bottleneck risk for independent fiber suppliers.
- Regulatory fragmentation:Divergent FDA and Codex Alimentarius fiber definitions force multi-territory product lines to maintain parallel formulation specifications.
Strategic Opportunities
- Pet nutrition penetration:Underdeveloped use of pea hull fiber in companion animal digestive health formulations offers expansion beyond human food applications.
- Organic certification tiers:Premium placement in European retail channels rewards suppliers achieving non-GMO and organic status under EU regulatory frameworks.
- Flake format innovation:Visual texture differentiation in granola and savory snacks is driving equipment investments for non-powder fiber presentations.
Industry Challenges
- Specialized milling expertise:Fine particle size control for consistent hydration properties requires operators trained in air classification and pin milling techniques.
- Dual certification timelines:Simultaneous pursuit of FDA-compliant fiber declarations and EFSA health claim authorizations extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pea Hull Fiber Market |
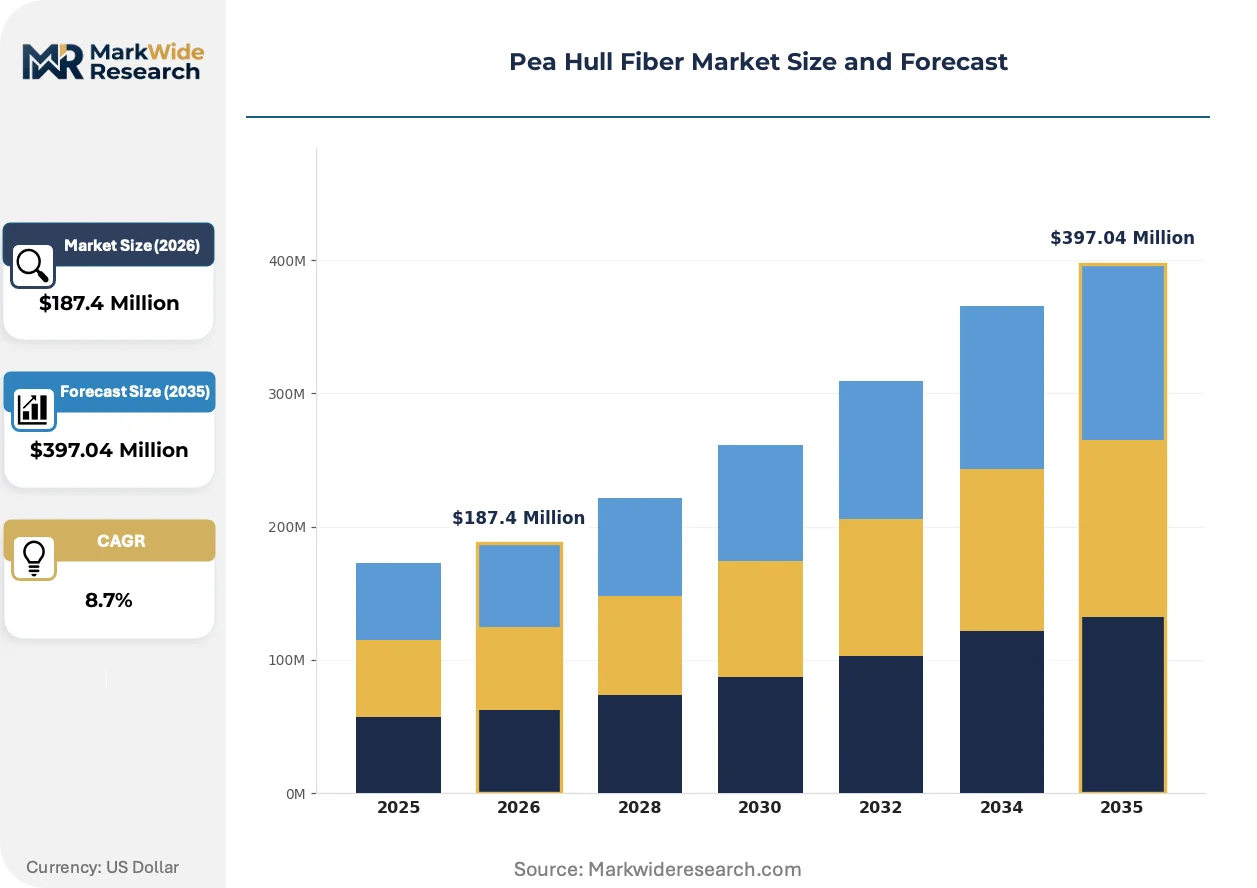
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocolloids, Functional Fibers, Dietary Supplements, Animal Feed Application: Nutraceuticals, Food Processing, Cosmetics, Textiles Form: Powder, Granules, Flakes, Extracts End User: Food Manufacturers, Pharmaceutical Companies, Cosmetic Brands, Feed Millers |
| Companies Covered | Roquette Frères, Cosucra Groupe Warcoing, Ingredion Incorporated, A&B Ingredients, Vestkorn Milling, AGT Food and Ingredients, Farbest Brands, Shandong Jianyuan Group, Puris Protein, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pea Hull Fiber Market Evolving Landscape
Processing technology convergence with sustainability metrics is reshaping competitive advantage in pea hull fiber extraction, while regulatory clarity on fiber definitions is accelerating formulation standardization.
Air classification systems integrated with optical sorting are rendering obsolete traditional sieving methods that produced inconsistent fiber length distributions. Meat analogue manufacturers in the United States and Netherlands are adopting these systems at pilot scale. The structural consequence is a compression in quality variability premiums that previously separated commodity and specialty-grade fiber suppliers.
EFSA's ongoing assessments under Regulation 1924/2006 for glycemic response claims are creating a bifurcation in fiber marketing strategies. Suppliers with clinical trial investments can pursue premium positioning, while those without face relegation to commodity texturizer status. European dairy alternative formulators are most affected, with several reformulating to maximize demonstrable physiological effect data.
Direct contracting between pea protein processors and fiber specialists is replacing spot market purchasing in North American supply chains. Large food manufacturers are securing multi-year offtake agreements that guarantee hull supply from specific extraction facilities. This pattern is most visible in the United States, where Roquette's Manitoba facility and similar operations are negotiating captive supply arrangements with meat analogue producers.
Pea Hull Fiber Market Segmentation
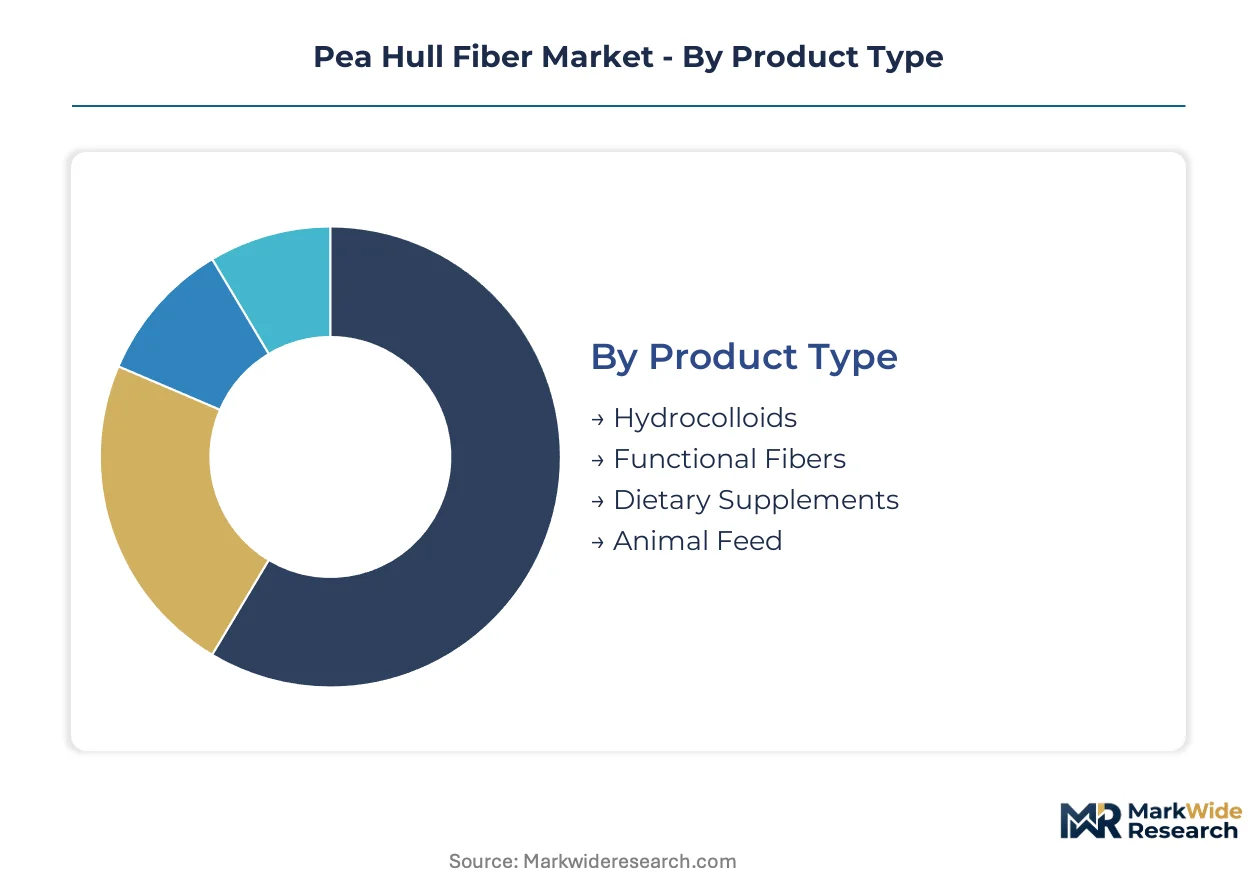
Pea hull fiber procurement patterns diverge sharply across end-use specifications, with food manufacturers prioritizing clean-label functionality while pharmaceutical buyers enforce tighter particle size tolerances. Understanding these segment-specific requirements reveals where margin capture concentrates and where commoditization pressures build.
Product Type:
Cost tier differentiation separates commodity-grade fiber from clinically validated variants that command formulation premiums.
- Functional Fibers:Comprising 65-75% total dietary fiber with balanced insoluble-to-soluble ratios, this segment serves meat analogue manufacturers in the United States and Netherlands seeking moisture retention without modified starches. Roquette Frères and Cosucra Groupe Warcoing have anchored supply contracts with plant-based protein processors.
- Hydrocolloids:Extracted soluble fractions deliver specialized gelling properties for dairy alternatives, achieving the highest margin per kilogram through EFSA-aligned glycemic response positioning. European dairy alternative formulators are reformulating to maximize demonstrable physiological effect data.
- Dietary Supplements:Capsule-grade fiber with microbial specification limits targets digestive health positioning under FDA fiber declaration rules.
- Animal Feed:Coarser fractions bypass food-grade milling costs to serve companion animal digestive health formulations, an underdeveloped application with expansion potential.
Functional Fibers holds installed capacity. Hydrocolloids is rotating up the share rankings.
Application:
Volume concentration tracks regulatory clarity on fiber health claims across jurisdictions.
- Food Processing:Gluten-free bakery and reduced-calorie formulations absorb the largest volume, with United States manufacturers substituting pea hull for wheat bran and oat fiber as mechanical fractionation narrows cost gaps. Clean-label mandates from major retailers are accelerating this displacement.
- Nutraceuticals:Prebiotic positioning requires clinical trial investments to secure EFSA Article 13.1 general function claims, creating a bifurcation between premium-positioned suppliers and commodity texturizers.
- Cosmetics:Microplastic-free exfoliant applications leverage pea hull fiber's physical abrasiveness under EU Green Deal sustainability pressures.
- Textiles:Emerging use in biodegradable fiber blends targets industrial nonwoven applications with lower purity requirements.
Food Processing anchors current procurement volumes. Nutraceuticals is climbing the fastest as clinical evidence investments mature.
Form:
Customer equipment compatibility dictates format selection across industrial versus artisanal scale operations.
- Powder:Standard particle sizes enable seamless dispersion in conventional mixing equipment, dominating industrial uptake among large food manufacturers with established pneumatic conveying systems.
- Flakes:Visual texture differentiation drives equipment investments for granola and savory snack applications where appearance matters, with specialty snack producers in the United States piloting optical-sorted flake presentations.
- Granules:Intermediate particle distribution serves pet nutrition compounders requiring controlled hydration rates in extrusion processes.
- Extracts:Concentrated soluble fiber fractions target pharmaceutical-grade specifications with enhanced purity protocols.
Powder maintains dominant installed base. Flakes is gaining share fastest through snack segment equipment upgrades.
End User:
Supply chain configuration varies by buyer scale and certification requirements.
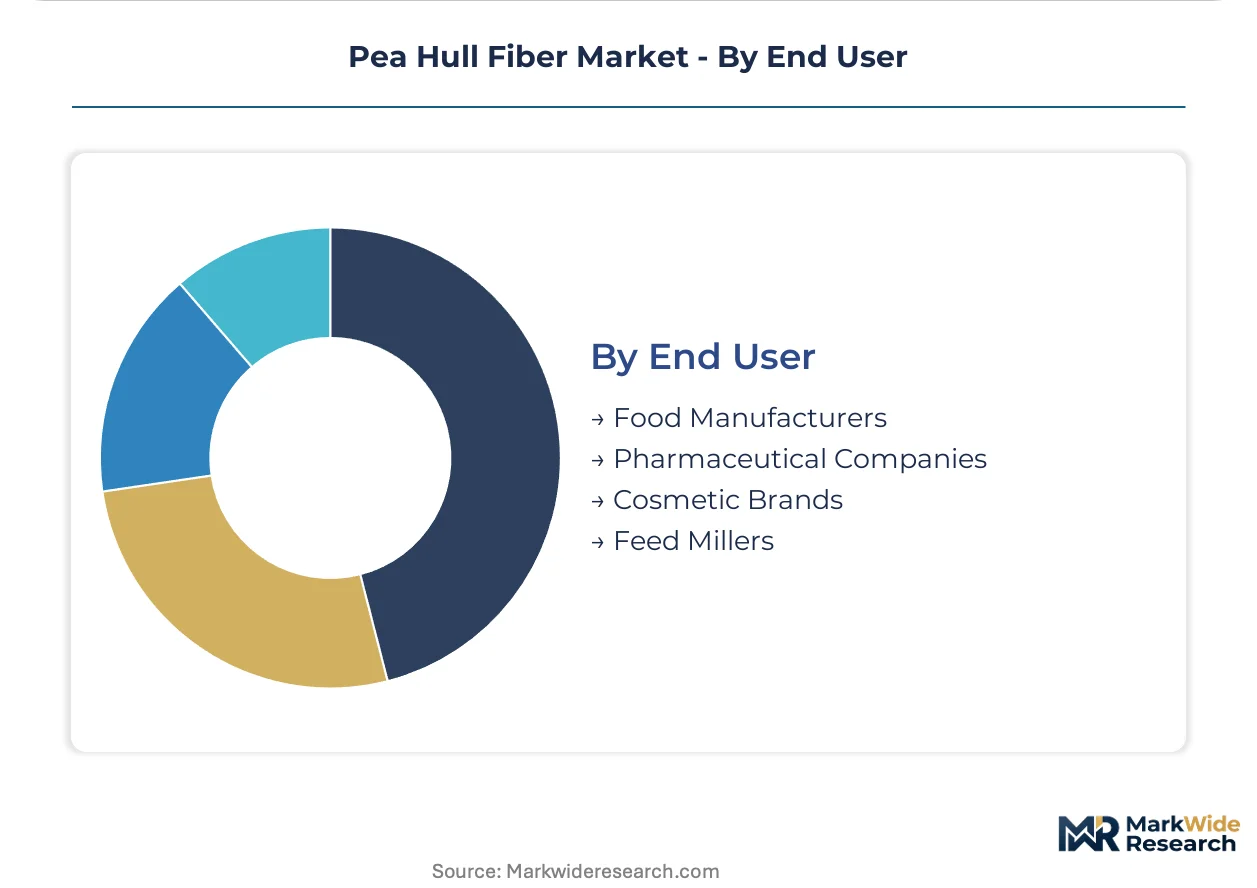
- Food Manufacturers:Direct multi-year offtake agreements with pea protein processors are replacing spot market purchasing, with meat analogue producers securing captive hull supply from Manitoba and France extraction facilities.
- Pharmaceutical Companies:Dual certification timelines for FDA fiber declarations and EFSA health claim authorizations extend product launch cycles, favoring suppliers with dedicated regulatory affairs capabilities.
- Cosmetic Brands:Sustainability scorecard requirements under EU CSRD reporting frameworks are prioritizing suppliers with verified carbon footprint data.
- Feed Millers:Price-sensitive procurement concentrates on co-product streams from pea starch extraction, with less stringent microbiological specifications than food-grade channels.
Food Manufacturers command the deepest supply relationships. Pharmaceutical Companies is expanding most quickly as clinical validation investments convert to approved health claims.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food manufacturers in North America and Western Europe command the deepest procurement relationships, while Asian processors are scaling extraction capacity to serve domestic plant-based protein demand.
United States
Meat analogue producers in Minneapolis and Chicago have secured multi-year offtake agreements with Manitoba extraction facilities. FDA fiber declaration rules under the 2016 Nutrition Facts framework clarify which isolated fibers qualify for gram declarations, reducing formulation uncertainty. Roquette's Portage la Prairie facility anchors North American supply.
France
Clean-label bakery formulators in Paris and Lyon substitute pea hull for modified starches in reduced-calorie applications. EFSA assessments under Regulation 1924/2006 determine digestive health claim eligibility, with Article 13.1 processes setting evidentiary requirements. Roquette Frères leverages its Lestrem processing network for captive hull supply.
Canada
Prairie pea protein infrastructure generates abundant hull byproduct streams that lower raw material costs for fiber extractors. Canadian Food Inspection Agency alignment with FDA fiber definitions simplifies cross-border formulation compliance. Manitoba's Portage la Prairie cluster concentrates fractionation investment.
Belgium
Cosucra Groupe Warcoing anchors European fiber positioning through non-GMO and organic certification tiers commanding premium retail placement. EFSA health claim authorizations under EU regulatory frameworks determine glycemic response messaging eligibility. The Wallonia region hosts specialized milling operations serving dairy alternative formulators.
China
Domestic pea protein processors in Shandong Province are scaling hull fiber extraction to reduce import dependence. SAMR fiber labeling standards under GB national standards create compliance requirements distinct from FDA and EFSA frameworks. Qingdao-based compounders serve regional snack manufacturers seeking clean-label texturizers.
Pea Hull Fiber Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply arrangements. The market structure concentrates around vertically integrated pea processors and independent fiber extractors serving niche certification tiers. Three archetypes dominate: captive supply operators with protein-fiber co-production, premium-certified specialists targeting organic retail channels, and commodity-grade suppliers competing on particle size consistency. Capacity expansion and multi-year offtake contracting represent the dominant competitive moves.
Among European integrated processors, Roquette Frères and Cosucra Groupe Warcoing exemplify the captive supply archetype through co-located protein and fiber extraction. Shandong Jianyuan Group occupies a position within Asia-Pacific capacity scaling. These three entities represent contrasting geographic and structural approaches to hull fiber market participation.
| Leading Market Players |
|---|
| Roquette Frères |
| Cosucra Groupe Warcoing |
| Ingredion Incorporated |
| A&B Ingredients |
| Vestkorn Milling |
| AGT Food and Ingredients |
| Farbest Brands |
| Shandong Jianyuan Group |
| Puris Protein |
| Others |
Value Network & Pricing Analysis
Canadian prairie yellow pea production concentration feeds directly into margin capture at North American extraction facilities, where protein-fiber co-production economics determine downstream pricing power for ingredient suppliers.
Pricing Analysis
Cost-plus contracts with Canadian prairie yellow pea indexation dominate procurement between fiber extractors and food manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-aligned clinical-grade fiber from clean-label commodity texturizers and feed-grade co-products. Pricing pressure stems from mechanical fractionation advances compressing conversion costs and narrowing historic premiums over wheat bran and oat fiber. Food manufacturers exhibit highest price sensitivity in meat analogue applications, while pharmaceutical buyers tolerate premium positioning for validated glycemic response claims.
Supply Chain Analysis
Export-control regimes on specialized air classification and optical sorting equipment from German and Japanese suppliers limit processing capacity scaling in emerging markets. Raw material flows draw from Canadian prairie pea protein infrastructure, French co-processing networks, and Shandong Province extraction facilities. Supply chain risk centers on single-source vulnerability for EFSA-validated clinical trial data supporting health claim authorizations. Distribution runs through direct multi-year offtake agreements between pea protein processors and fiber specialists, displacing spot market purchasing in North American and European channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pea hull fiber market sits in a cyclical recovery phase as plant-based protein infrastructure investment from the early 2020s matures into operational hull byproduct streams, releasing captive supply for fiber extraction.
For Market Incumbents: Build regulatory data moats through simultaneous FDA fiber declaration and EFSA Article 13.1 health claim pursuit. Anchor backward integration into Canadian prairie pea protein processing to secure hull supply against emerging Asian capacity. Defend margin position by investing in organic and non-GMO certification tiers that command premium placement in European retail channels threatened by commodity-grade imports. For New Entrants and Emerging Players: Pursue pet nutrition compounders as an underdeveloped white-space target with less stringent microbiological specifications than human food channels. Target flake format production for granola and savory snack manufacturers seeking visual texture differentiation. Enter through equipment partnerships with optical sorting technology providers to bypass capital-intensive air classification development. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed European fiber specialists holding EFSA-validated clinical trial portfolios but lacking North American manufacturing footprint. Long-term viability hinges on regulatory data assets appreciating as FDA-Codex harmonization pressures mount. Watch for inflection in direct contracting velocity between Manitoba extraction facilities and Minneapolis meat analogue producers as a signal of supply security premium emergence.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Hull Supply Agreement | Roquette's Manitoba facility secures multi-year offtake with meat analogue producers, locking in raw material access. |
| EFSA Clinical Trial Investment | Cosucra's glycemic response positioning commands premium pricing through demonstrable physiological effect data. |
| Optical Sorting Equipment Upgrade | Specialty snack producers pilot flake presentations with Japanese optical-sorted systems for texture differentiation. |
| Organic Certification Tier Expansion | Wallonia milling operations achieve EU organic status to access premium retail channel placement. |
| Pet Nutrition Formulation Partnership | Companion animal digestive health applications offer volume expansion beyond saturated human food channels. |
Research Methodology
A standing panel of pea protein extraction facility managers, food manufacturer procurement directors, EFSA regulatory affairs consultants, and pet nutrition compounders provided ongoing calibration across the research cycle. Primary fieldwork combined structured interviews with secondary validation through FDA fiber guidance documents, EFSA Article 13.1 health claim registers, Canadian Food Inspection Agency alignment notices, and customs trade data on yellow pea hull movements. Bottom-up capacity modeling triangulated against top-down demand estimates from meat analogue and dairy alternative formulation trends.
Scenario-bracketing around regulatory harmonization outcomes and plant-based protein demand elasticity shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type tier, application end-use, form factor, and certification status alongside regional regulatory cluster variations. CAGRs derived from installed capacity trajectories and substitution elasticity estimates for cereal fiber displacement, with specific inputs from mechanical fractionation cost compression curves and EFSA health claim authorization timelines.
Macroeconomic conditions sit as an overlay; deviation in Canadian prairie weather patterns and Asian yellow pea export demand would shift the trajectory. Forecasts reflect assumptions on regulatory clarity persistence and protein-fiber co-production economics. Material shifts in FDA-Codex fiber definition harmonization or EFSA glycemic response claim rejections would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Plant Based Thickener Market
Ingredients
Mustard Flour Market
Ingredients
Malted Wheat Flour Market
Ingredients
Food Minerals Market
Ingredients
Citrus Fiber Market
Ingredients
Glucose (Dextrose) Market
Ingredients
North America Algae Omega-3 Ingredients Market
Ingredients
Low Fat Cooking Oil Market
Ingredients
Interesterified CBE Market
Ingredients
Desiccated Coconut Powder Market
Ingredients
Savory Ingredients Market
Ingredients
Wheat Malt Market
Ingredients
Bouillon Cubes Market
Ingredients
Waxy Maize Starch Market
Ingredients
Carotenes Market
Ingredients
Vegetable Glycerin Market