
 Low Fat Cooking Oil Market | 2026-2036
Low Fat Cooking Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Cooking Oil Market Analytics
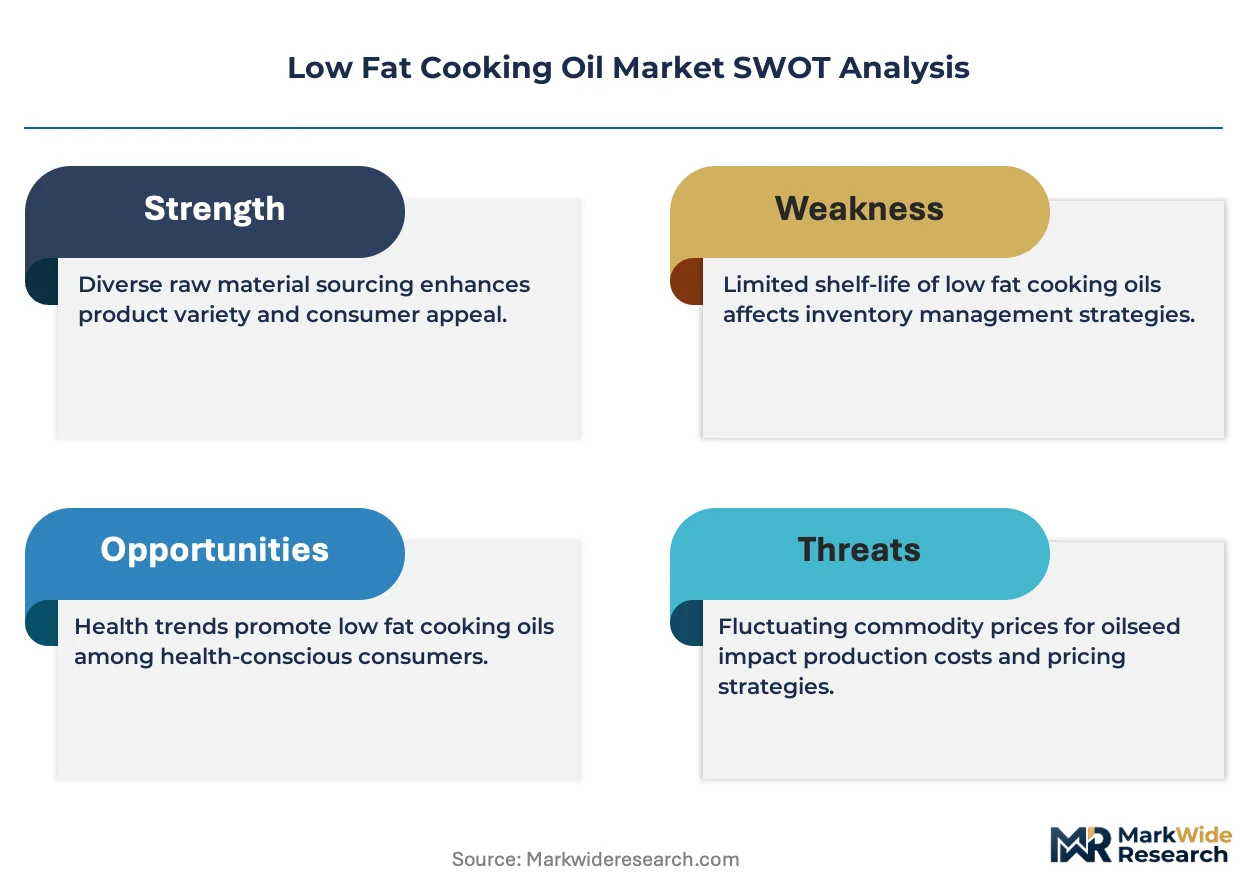
Refined oil margin pools is tilting from commodity bulk sales toward branded retail and food-service contracting. Cargill Incorporated leverages its North American crush capacity to secure supply agreements with quick-service chains. Bunge Global SA anchors South American soybean origination for low-linolenic oil output. Wilmar International Ltd dominates Asian palm-olein fractionation, giving it feedstock flexibility across price cycles.
Low fat cooking oil comprises vegetable oils engineered through blending, fractionation, or enzymatic modification to deliver reduced saturated fat content while maintaining oxidative stability above 180°C smoke points; processors achieve this by interesterifying high-oleic sunflower or canola bases with palm olein fractions. Olive oil occupies the premium household tier in European and Mediterranean markets, sustained by origin-protected labeling and perceived cardiovascular benefits. Canola oil leads North American food-service volume, where high-oleic variants compete on fry-life extension and trans-fat compliance. Sunflower oil represents the fastest-growing category in India and Eastern Europe, as price-sensitive buyers shift from traditional mustard or groundnut sources without accepting palm oil's saturated fat profile.
The FDA's trans-fat elimination mandate and updated Nutrition Facts labeling requirements shape U.S. product reformulation timelines, while the EU's F-Gas Regulation and Farm-to-Fork Strategy pressure processors toward lower-emission refining and sustainable sourcing disclosures. India's FSSAI enforces revised edible oil quality standards and packaging label rules that favor low-fat claims with verified fatty-acid profiles. Stakeholders must monitor how carbon-border adjustment mechanisms and deforestation-free supply-chain mandates in Europe and North America redirect sourcing patterns for palm and soybean feedstocks.
Market Dynamics
Enzymatic interesterification technology is compressing the cost premium between low-fat specialty oils and commodity grades, forcing refiners to recalibrate margin strategies around functional performance rather than basic nutritional claims.
Growth Catalysts
- F-Gas Regulation:The EU's phasedown of hydrofluorocarbon refrigerants in refining infrastructure accelerates capital redeployment toward enzymatic processing lines with lower thermal footprints.
- Quick-service chains:North American food-service operators are locking in multi-year supply agreements for high-oleic canola to secure fry-life performance and trans-fat compliance under FDA labeling mandates.
- Palm olein fractionation:Malaysian and Indonesian refiners are expanding mid-fraction capacity to supply the hardstock requirements of structured low-fat blends without hydrogenation.
Market Restraints
- Crude palm oil volatility:Feedstock costs swing with Indonesian export duty adjustments and Malaysian ringgit fluctuations, compressing blender margins on fixed-price retail contracts.
- Single-origin dependence:High-oleic sunflower seed supply concentrates in Black Sea origins, exposing processors to geopolitical disruption and quality inconsistency.
- Oxidative stability ceiling:Current enzymatic modification limits smoke-point extension beyond 200°C for certain bakery applications, capping penetration into industrial frying segments.
Strategic Opportunities
- Eastern European households:Polish and Romanian consumers are pivoting from traditional lard and butter toward sunflower-based low-fat alternatives as cardiovascular screening programs expand.
- Carbon-border adjustment:The EU's CBAM creates first-mover advantage for South American crushers certifying deforestation-free soybean supply chains for low-linolenic oil export.
- Direct-to-institutional platforms:Cloud-based procurement portals are disintermediating traditional distributor networks for hospital and school cafeteria bulk purchasing.
Industry Challenges
- Enzyme biochemist scarcity:Refineries struggle to recruit talent capable of optimizing lipase reactor conditions for custom fat-structured outputs.
- Dual certification timelines:Simultaneous pursuit of EU organic claims and FDA qualified health claims extends product launch cycles by 18-24 months.
- Legacy hydrogenation asset stranding:Plants with sunk capital in partial hydrogenation lines face write-down pressure as trans-fat regulations tighten across multiple jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Cooking Oil Market |
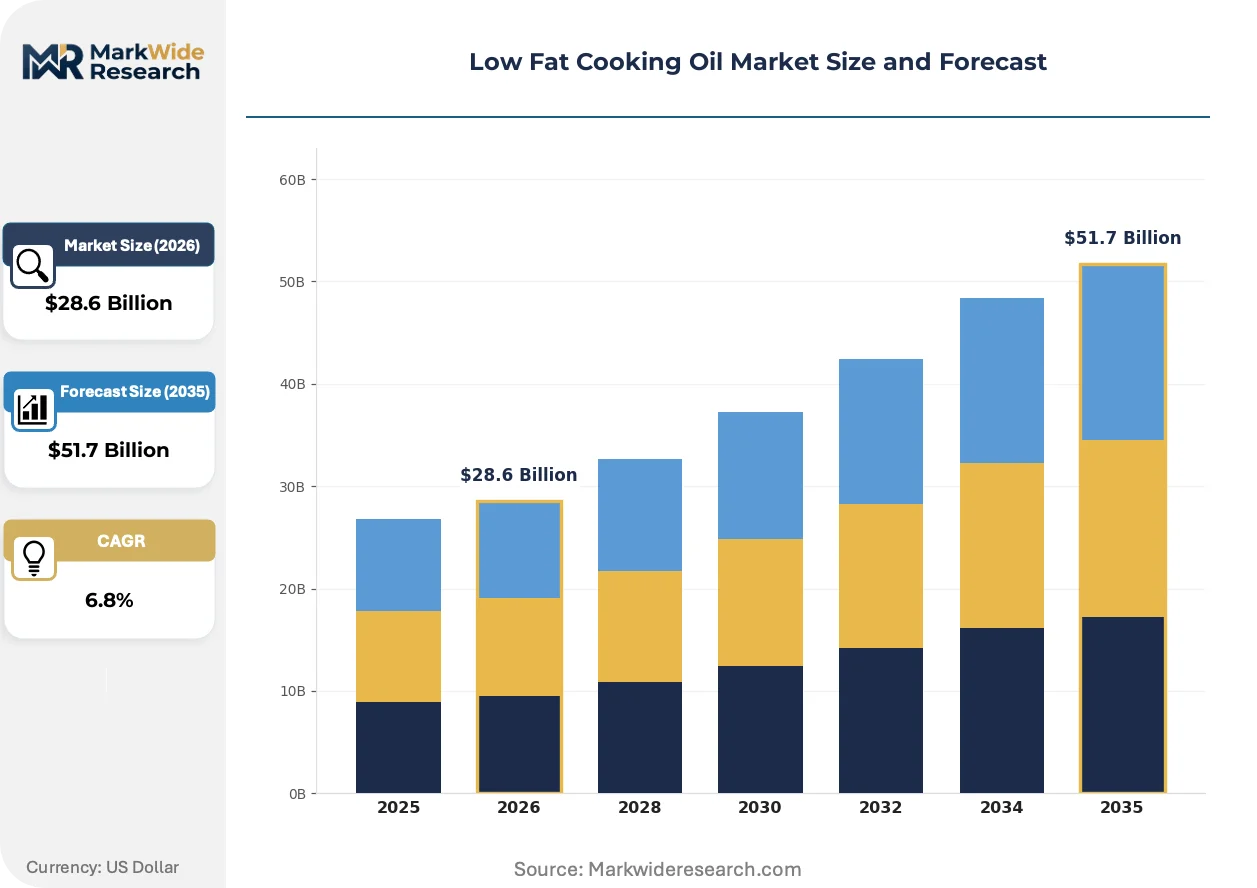
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Olive Oil, Canola Oil, Sunflower Oil, Peanut Oil Packaging Type: Bottle, Tetra Pack, Can, Pouch End User: Households, Restaurants, Food Service, Catering Distribution Channel: Supermarkets, Grocery Stores, Online Retail, Specialty Stores |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland, Bunge Global SA, Wilmar International Ltd, Louis Dreyfus Company, Fuji Oil Holdings Inc., Olam Agri, Musim Mas Group, Adani Wilmar Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Cooking Oil Market Evolving Landscape
Processing technology and procurement logic are diverging from volume-maximizing commodity models toward precision-formulation systems that align fat functionality with end-use thermal stress and label-positioning requirements.
Enzymatic interesterification is migrating from niche premium applications to mainstream food-service supply. This technology rearranges fatty acid positions on glycerol backbones without creating trans fats, enabling tailored melting profiles. Quick-service chains in North America are specifying enzymatically modified high-oleic canola for fryer systems. The cost compression from scaled enzyme production is eroding the price gap with chemically interesterified alternatives.
The FDA's updated Nutrition Facts labeling requirements and trans-fat elimination mandate are compressing reformulation timelines for legacy product portfolios. Processors must disclose added sugars and revise serving-size baselines, forcing simultaneous label and fat-system redesigns. Packaged food manufacturers with nationwide distribution face the steepest compliance costs and shortest runway for supplier qualification.
Urban Indian households are consolidating purchases around modern trade formats that privilege verified low-fat claims with fatty-acid profile disclosure. Supermarket chains in Mumbai and Delhi are allocating premium shelf space to brands with FSSAI-certified nutritional panels. This channel shift disadvantages traditional kirana stores lacking cold-chain infrastructure for high-oleic variants with shorter shelf lives.
Low Fat Cooking Oil Market Segmentation
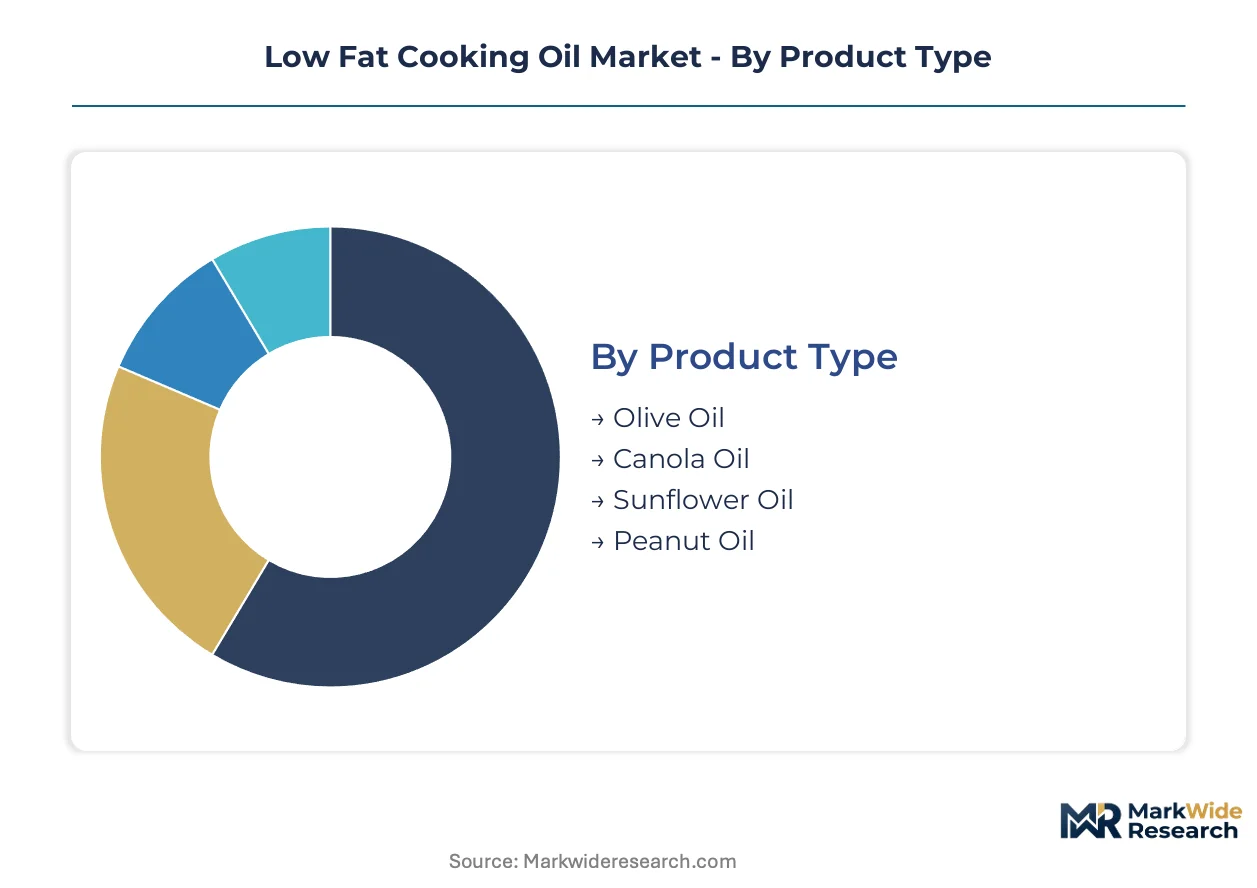
Low fat cooking oil procurement patterns diverge sharply between retail households seeking shelf-stable convenience and food-service operators optimizing fry-life economics. Segmentation reveals how enzymatic modification technologies and packaging innovations map to distinct price-performance requirements across these buyer archetypes.
Product Type:
After-sales service intensity concentrates in technical support for enzymatic modification troubleshooting and fryer-system compatibility guidance, with high-oleic variants demanding specialized handling protocols.
- Olive Oil:Cold-pressed extraction preserves polyphenol content above 200 mg/kg, delivering superior oxidative stability for Mediterranean cuisine applications. European Union origin-protected labeling commands premium positioning in Italian and Spanish retail channels where cardiovascular health claims drive repeat purchase.
- Canola Oil:High-oleic cultivars achieve 75% monounsaturated fat content through seed breeding programs, enabling fry-life extension to 7+ days in commercial operations. North American quick-service chains specify this grade for trans-fat compliance under FDA mandates.
- Sunflower Oil:Mid-oleic hybrids balance cost and performance for Eastern European household fryers.
- Peanut Oil:Refined variants with 450°F+ smoke points serve Asian restaurant wok stations requiring thermal stability.
By volume, canola oil leads North American food-service procurement. By growth pace, sunflower oil is expanding most quickly in Indian urban households shifting from traditional mustard sources.
Packaging Type:
Cost tier stratification separates premium oxygen-barrier formats from commodity bulk supply, with institutional buyers optimizing per-unit economics against spoilage risk.
- Bottle:PET and glass formats with nitrogen flushing extend shelf life to 18 months for retail premium positioning. Indian modern trade chains allocate eye-level placement to transparent bottles showcasing oil clarity as a quality signal.
- Tetra Pack:Aseptic carton technology eliminates light and oxygen exposure, enabling ambient distribution in tropical climates without refrigeration infrastructure. Southeast Asian processors favor this format for export logistics efficiency.
- Can:Tin-plated steel containers dominate Middle Eastern bulk import channels.
- Pouch:Flexible laminate structures reduce freight cost per liter for price-sensitive emerging market penetration.
By volume, bottle formats dominate household retail. By growth pace, pouch packaging is gaining share fastest in South Asian value-tier distribution.
End User:
Application-specific formulation requirements separate consumer taste preference from industrial fry-life metrics, with procurement scale determining supplier negotiation leverage.
- Households:Urban Indian buyers consolidate purchases around FSSAI-verified nutritional panels in modern trade formats, privileging brands with fatty-acid profile disclosure. Supermarket cold-chain infrastructure enables high-oleic variants with shorter shelf lives.
- Restaurants:Independent operators prioritize smoke-point consistency across menu items, driving specification of enzymatically modified blends. Malaysian palm-olein fractionation supplies the hardstock for these structured formulations.
- Food Service:Multi-unit chains negotiate multi-year supply agreements locking in fry-life performance.
- Catering:Event-volume volatility favors flexible procurement terms over long-term contracting.
By volume, food service leads commercial offtake. By growth pace, household direct-to-consumer channels are climbing the fastest as e-commerce penetration deepens.
Distribution Channel:
Customer type fragmentation between convenience-seeking urban professionals and price-comparison rural buyers shapes channel investment priorities and margin capture.
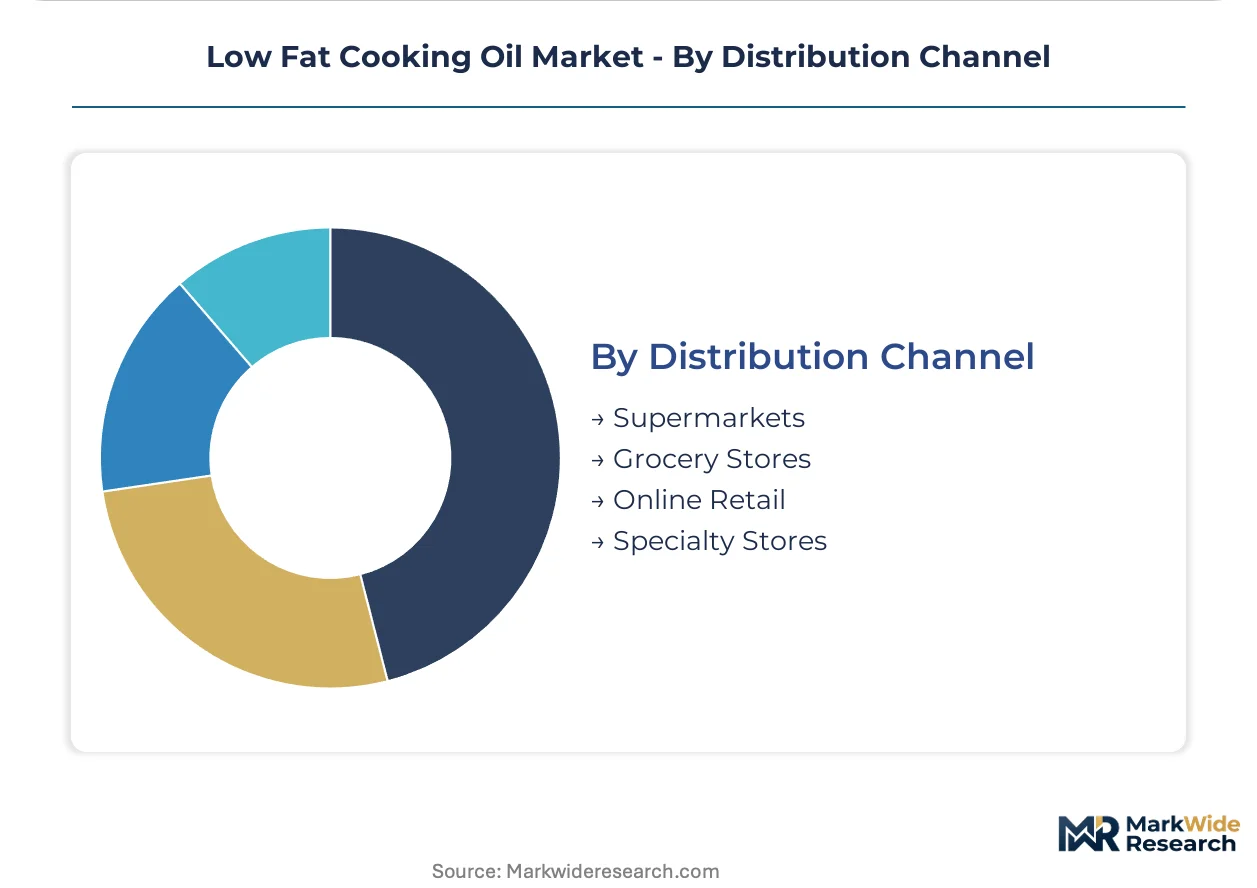
- Supermarkets:Modern trade formats in Mumbai and Delhi allocate premium shelf space to certified low-fat claims, with category managers demanding FSSAI-compliant labeling. Cold-chain infrastructure enables high-oleic sunflower variants with 12-month shelf windows.
- Grocery Stores:Traditional kirana networks in secondary Indian cities lack temperature control, restricting distribution to stable commodity grades and disadvantaging premium enzymatically modified products.
- Online Retail:Direct-to-consumer platforms enable subscription replenishment models for urban households.
- Specialty Stores:Organic and gourmet retailers curate origin-protected olive oil portfolios for Mediterranean diet adherents.
By volume, supermarkets dominate urban household procurement. By growth pace, online retail is expanding most quickly in tier-one Indian cities with same-day delivery infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies: Indian urban households exhibit acute price sensitivity to palm olein fluctuations, while European buyers absorb premiums for origin-protected olive oils with minimal volume contraction.
United States
Quick-service chains dominate procurement volume, locking in multi-year supply agreements for high-oleic canola to meet FDA trans-fat elimination mandates. The FDA's updated Nutrition Facts labeling requirements compress reformulation timelines for legacy portfolios. Chicago and Minneapolis-St. Paul anchor North American crush capacity, where refiners convert soybean origination into low-linolenic oil output for food-service distribution.
Germany
Food manufacturers prioritize carbon footprint verification for export eligibility under impending EU carbon-border adjustment mechanisms. The EU F-Gas Regulation accelerates capital redeployment toward enzymatic processing lines with lower thermal footprints. Hamburg and Rotterdam refineries lead interesterification technology adoption, supplying structured low-fat blends to bakery and confectionery processors across the continent.
India
Urban household consolidation around modern trade formats privileges FSSAI-certified nutritional panels with disclosed fatty-acid profiles. India's FSSAI enforces revised edible oil quality standards and packaging label rules that favor verified low-fat claims. Mumbai and Delhi supermarket chains allocate premium shelf space to high-oleic sunflower variants, displacing traditional kirana store distribution.
Indonesia
Mid-fraction palm olein capacity expansion targets hardstock requirements for enzymatically modified blends without hydrogenation. Indonesian export duty adjustments on crude palm oil generate feedstock cost volatility that compresses blender margins on fixed-price retail contracts. Surabaya and Medan refineries upgrade fractionation infrastructure to supply structured fat inputs to Indian and Chinese blenders.
Netherlands
European import gateway functions concentrate enzymatic interesterification technology deployment for re-export to deforestation-sensitive markets. The EU Farm-to-Fork Strategy pressures processors toward sustainable sourcing disclosures and lower-emission refining. Rotterdam's port complex anchors palm-olein fractionation for hardstock supply to German and French food manufacturers reformulating away from trans fats.
Low Fat Cooking Oil Market Competitive Landscape
Capability concentration sits with enzymatic technology specialists; scale advantage sits with integrated crushers with origination control across multiple feedstocks. The market structures around three tiers: global traders with crush assets, Asian palm-olein fractionators with feedstock flexibility, and regional branded oil packagers with modern trade distribution. Dominant competitive moves include backward integration into seed breeding programs and strategic partnerships with quick-service chains for fry-life performance guarantees.
Within the integrated trading tier, Cargill Incorporated and Bunge Global SA represent North American and South American origination anchors respectively. Wilmar International Ltd occupies a position exemplifying Asian palm-olein dominance through fractionation flexibility. Adani Wilmar Ltd anchors Indian branded retail competition with modern trade penetration capabilities.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland |
| Bunge Global SA |
| Wilmar International Ltd |
| Louis Dreyfus Company |
| Fuji Oil Holdings Inc. |
| Olam Agri |
| Musim Mas Group |
| Adani Wilmar Ltd |
| Others |
Value Network & Pricing Analysis
The Rotterdam-Singapore palm olein freight corridor compresses blender margins when Indonesian export duty adjustments spike feedstock costs, while downstream price differentiation hardens around enzymatic modification tiers versus commodity grades.
Pricing Analysis
Technical service contracts for enzymatic reactor optimization anchor lifetime value in food-service accounts. Three-tier pricing structure across premium enzymatic blends, standard interesterified grades, and economy commodity oils stratifies the market. Price differentiation hinges on fry-life performance certification and FSSAI fatty-acid profile disclosure. Pricing pressure stems from crude palm oil volatility triggered by Indonesian duty swings. Quick-service chains show lowest price sensitivity due to multi-year performance guarantees, while Indian urban households in modern trade exhibit acute elasticity.
Supply Chain Analysis
Tariff exposure between Indonesia and India dominates supply chain risk calculus for palm olein hardstock procurement. Geographic concentration centers on Indonesian and Malaysian mid-fraction refineries, Ukrainian and Russian high-oleic sunflower seed belts, and Canadian canola crush complexes. Raw material dependencies include crude palm oil, high-oleic sunflower seeds, and low-linolenic soybean varieties. Single-source vulnerability concentrates in Black Sea sunflower origins. Distribution runs through Rotterdam port complexes for European re-export and Mumbai-Delhi cold-chain networks for Indian modern trade.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The low fat cooking oil market is cycling through a recovery phase as food-service operators rebuild fryer-system inventories following pandemic-era demand destruction and FDA compliance deadlines force reformulation waves.
For Market Incumbents: Build enzymatic technology moats through captive lipase reactor capacity in Rotterdam and Singapore hubs. Secure multi-year supply agreements with North American quick-service chains to lock in fry-life performance tiers. Invest in FSSAI certification infrastructure for Indian modern trade shelf access. Defend against margin compression by backward integration into palm-olein fractionation assets in Surabaya and Medan.
For New Entrants and Emerging Players: Eastern European household markets in Poland and Romania offer underpenetrated white-space as cardiovascular screening programs expand. Target cloud-based procurement portals for hospital and school cafeteria direct sales, bypassing legacy distributor networks. Lead with mid-oleic sunflower blends priced between premium enzymatic grades and commodity palm olein. Anchor initial volume through Romanian supermarket chains before scaling westward.
For Investors and Strategic Acquirers: Asian palm-olein fractionators with feedstock flexibility across Indonesian and Malaysian price cycles represent the priority acquisition archetype. Long-term viability rests on enzymatic processing scale advantages and deforestation-free certification infrastructure. Monitor EU carbon-border adjustment implementation timelines as the inflection signal for South American crusher valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Processing Scale-Up | Rotterdam refineries deploying lipase reactors capture food-service premium tiers from trans-fat compliance deadlines. |
| Backward Integration into Seed Breeding | Canadian crushers controlling high-oleic canola genetics secure fry-life performance specifications from quick-service chains. |
| Deforestation-Free Certification Program | EU Farm-to-Fork Strategy compliance enables continued access to carbon-border-adjusted European food manufacturing demand. |
| Direct-to-Institutional Platform Launch | Cloud procurement portals disintermediate traditional distributors for hospital and school cafeteria bulk purchasing contracts. |
| Mid-Fraction Palm Olein Expansion | Indonesian refineries upgrading Surabaya capacity supply hardstock for enzymatically modified blend formulations. |
Research Methodology
A spread of perspectives from refinery operations managers, quick-service chain procurement directors, enzymatic technology suppliers, and Indian modern trade category buyers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade databases, FSSAI regulatory filings, FDA guidance documents, and EU Farm-to-Fork Strategy implementation trackers. Bottom-up volume triangulation across product-grade, packaging-format, and end-user segments was cross-checked against top-down macroeconomic elasticity models.
Demand-supply-balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include oil type, enzymatic modification tier, packaging format, distribution channel, and end-user procurement scale. CAGRs were derived from fitted growth curves calibrated to historical volume trajectories and elasticity-adjusted demand projections. Industry-specific forecast inputs incorporated palm olein price volatility regimes and trans-fat regulatory compliance timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Malaysian mid-fraction refiners or accelerated enzyme cost compression by biotechnology suppliers would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Starches/Glucose Market
Ingredients
Food Ingredients Market
Ingredients
Germany Protein Market
Ingredients
Farnesene Market
Ingredients
Camelina Oil Market
Ingredients
Global Egg Yolk Oil Market
Ingredients
Cocoa Derivatives Market
Ingredients
Rapid-Set Gelatin Market
Ingredients
Grape Seed Extracts Market
Ingredients
Egg White Powder Market
Ingredients
Phytosterols Market
Ingredients
Birch Sap Market
Ingredients
Halal and Kosher Empty Capsules Market
Ingredients
Global Vitamin Ingredients Market
Ingredients
Corn-Based Ingredients Market
Ingredients
Cheese Powder Market