
 Glucose (Dextrose) Market | 2026-2036
Glucose (Dextrose) Market Size, Share, and Industry Trends Forecast 2026-2036
Glucose (Dextrose) Market Foresight
The capital-intensity divergence between integrated wet-mill operators and specialized fractionation houses is bifurcating competitive returns in glucose refining. Tate & Lyle PLC leverages its British corn wet-milling infrastructure to sustain pharmaceutical-grade dextrose output across European and North American supply corridors. Cargill Incorporated anchors its glucose portfolio through backward integration into North American corn origination and in-house enzyme technology platforms.
Glucose, commonly designated dextrose when in its monohydrate or anhydrous crystalline form, denotes a simple monosaccharide with the molecular formula C₆H₁₂O₆, typically manufactured via enzymatic hydrolysis of starch derived from corn, wheat, or cassava feedstocks. The compound serves as a fundamental energy substrate in parenteral nutrition, a bulking agent in solid oral dosages, and a fermentation feedstock for biochemical production. Powder and liquid product types dominate volume throughput, though pharmaceutical-grade crystalline variants command disproportionate margin pools due to USP and EP certification requirements. Food and beverage application segments retain mature volume leadership, while pharmaceutical and nutritional supplement end uses are expanding fastest as parenteral nutrition protocols and sports nutrition formulations multiply.
FDA enforces identity and purity specifications for dextrose under 21 CFR, while EMA's European Pharmacopoeia sets comparable monograph standards for intravenous-grade material, and India's CDSCO aligns with IP-grade requirements for domestic pharmaceutical manufacturing. These frameworks shape demand by mandating dedicated production lines, analytical testing protocols, and documentation trails that elevate barriers for non-specialist refiners. Stakeholders must monitor evolving pharmacopeial harmonization efforts and bio-based chemical feedstock subsidies that could redirect commodity glucose flows between food, pharmaceutical, and industrial channels.
Market Dynamics
Pharmaceutical-grade dextrose certification requirements are bifurcating production economics, forcing refiners to choose between commodity food-grade volumes and high-margin USP/EP-grade crystalline output with dedicated analytical protocols.
Growth Catalysts
- CDSCO IP-grade mandates:India's pharmaceutical regulator tightened purity thresholds for intravenous dextrose, accelerating domestic bulk consumption from local wet-mill operators serving hospital formulators.
- PLI scheme subsidies:India's production-linked incentive schemes for active pharmaceutical ingredients and medical devices are channeling capital toward captive dextrose refining capacity.
- Enzymatic hydrolysis advances:Improved glucoamylase specificity is raising starch-to-glucose conversion yields, lowering unit costs for pharmaceutical-grade crystallization.
Market Restraints
- Corn price volatility:Feedstock costs swing with North American planting cycles and ethanol policy, compressing margins for non-integrated fractionators lacking origination assets.
- EMA monograph compliance costs:European Pharmacopoeia documentation trails and dedicated production line requirements erect barriers for Asian exporters seeking IV-grade certification.
- Isomaltulose substitution:Low-glycemic alternative sweeteners are capturing sports nutrition and functional beverage formulations previously dependent on dextrose.
Strategic Opportunities
- Brazilian ANVISA certification gap:Limited domestic pharmaceutical-grade dextrose capacity creates import substitution potential for certified exporters meeting Brazilian injectable standards.
- Fermentation feedstock pivot:Biochemical producers seeking bio-based platform chemicals are contracting dedicated glucose streams, diverting volume from commodity food channels.
- Direct hospital procurement:Large health systems are consolidating parenteral nutrition purchasing, creating volume commitments that bypass traditional distributor markups.
Industry Challenges
- Analytical chemistry talent scarcity:USP and EP certification requires specialized chromatography and spectroscopy expertise that competes with broader pharmaceutical QC labor markets.
- Multi-pharmacopeia validation timelines:Simultaneous FDA, EMA, and CDSCO approval processes extend product launch cycles by 18-24 months for new crystalline dextrose entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glucose (Dextrose) Market |
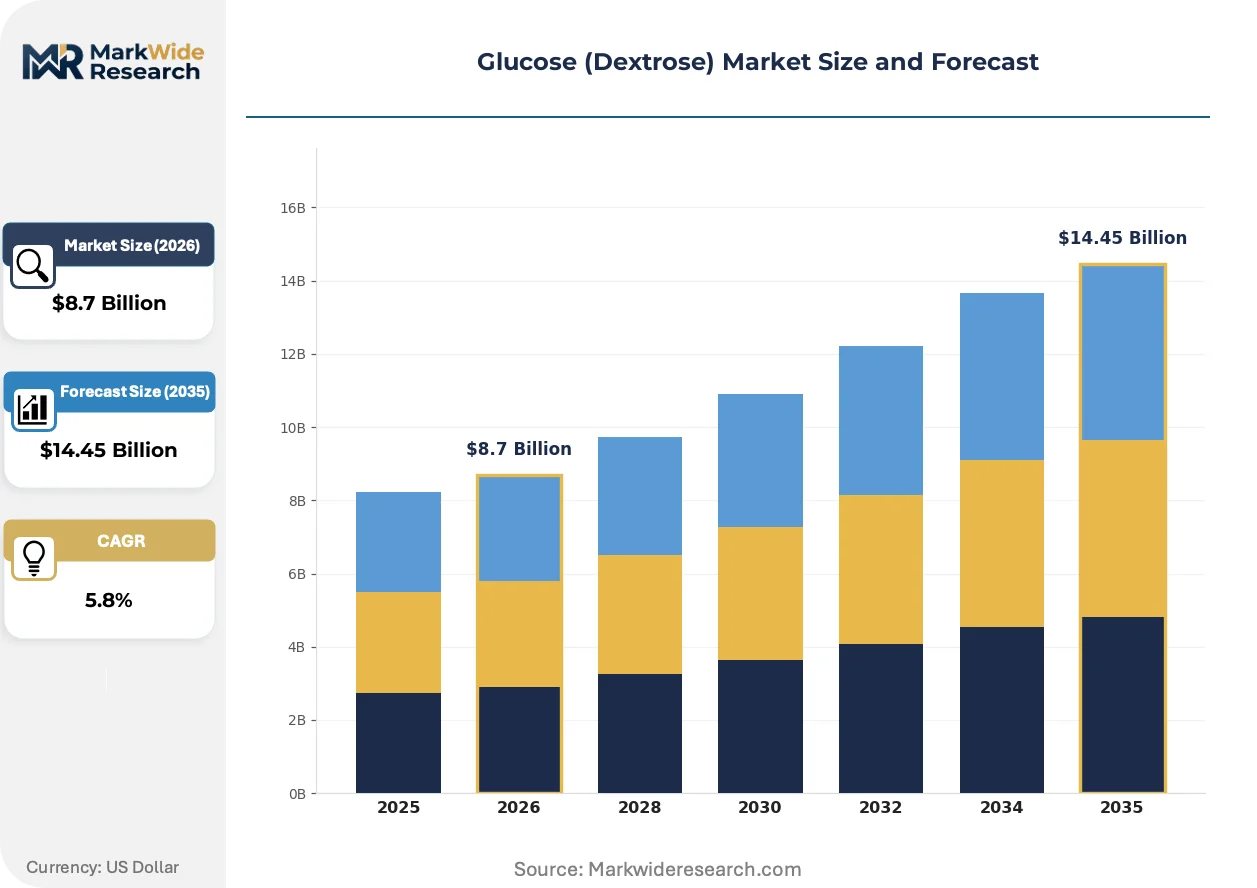
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Syrup, Granules, Tablets Application: Food & Beverage, Pharmaceutical, Cosmetic Products, Nutritional Supplements, Chemical Industry End User: Food Manufacturers, Pharmaceutical Companies, Personal Care Brands, Supplement Producers, Industrial Manufacturers Packaging Type: Bags, Bottles, Drums, Sachets, Bulk Containers |
| Companies Covered | Tate & Lyle PLC, Tereos S.A., Archer Daniels Midland Company, Grain Processing Corporation, AGRANA Beteiligungs-AG, Cargill Incorporated, Roquette Frères, Südzucker AG, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glucose (Dextrose) Market Shifts & Advancements
Continuous processing technologies and real-time release testing are compressing batch cycle times, while regulatory harmonization efforts attempt to streamline multi-jurisdiction certification burdens for pharmaceutical-grade material.
Membrane filtration systems are displacing traditional centrifugation and evaporation stages in glucose refining. Parenteral nutrition formulators in Germany and Switzerland are adopting membrane-polished dextrose to reduce endotoxin variability. This displacement is compressing capital requirements for new pharmaceutical-grade entrants while raising purity consistency thresholds that legacy thermal processes struggle to match.
EMA's revised European Pharmacopoeia monograph for dextrose monohydrate introduced tightened endotoxin and organic volatile impurity limits in 2024. Refiners must now validate dedicated production trains with segregated packaging lines, elevating compliance costs. Hospital procurement consortia in France and the Netherlands are responding by consolidating supplier lists to those with demonstrated multi-batch EP certification.
Buyer consolidation among parenteral nutrition compounders is compressing supplier negotiation cycles and unbundling technical service offerings. Large hospital networks in the United States are shifting from distributor-mediated purchasing to direct mill contracts with guaranteed volume tiers. This pattern is most visible in the Midwest, where integrated health systems now contract directly with corn wet-mill operators for annual dextrose monohydrate commitments.
Glucose (Dextrose) Market Segmentation
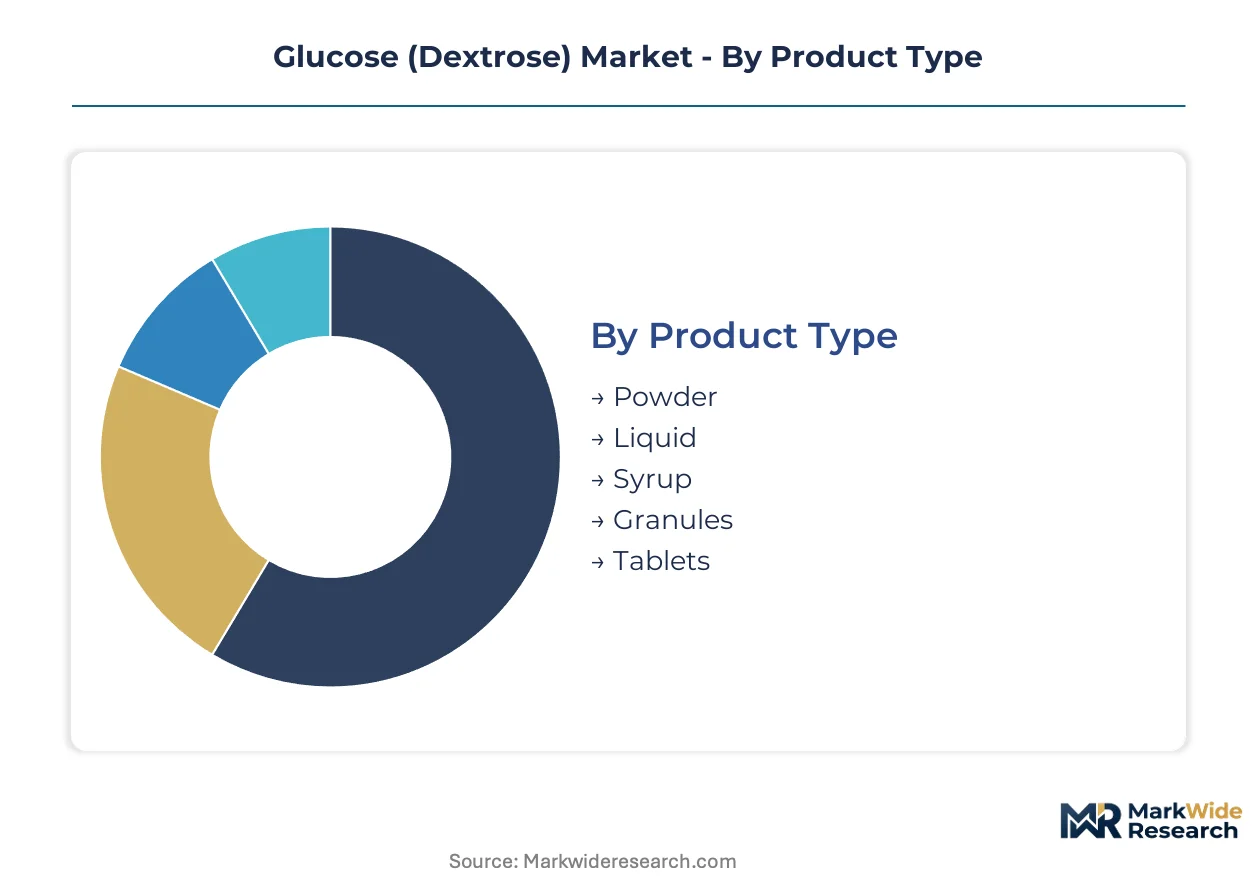
Glucose segmentation determines channel economics, as pharmaceutical-grade crystalline material commands dedicated distribution while commodity syrup flows through bulk tanker networks. Distinct purity tiers create non-overlapping customer bases with incompatible procurement protocols.
Product Type:
Powder and liquid variants split across incompatible supply chains, with crystalline grades requiring climate-controlled warehousing and tanker deliveries demanding dedicated pumping infrastructure.
- Powder:Crystalline dextrose monohydrate and anhydrous forms serve parenteral nutrition compounders and solid dosage manufacturers. USP-grade powder from Indian wet-mill operators is displacing European supply in Middle Eastern hospital procurement.
- Liquid:Aqueous glucose solutions at various DE ratings feed fermentation bioreactors and beverage formulations. Brazilian ethanol producers contract dedicated tanker volumes, bypassing bagged alternatives.
- Syrup:High-maltose corn syrups and blended glucose-fructose streams serve confectionery softening and ice cream manufacture. FSSAI-mandated label declarations are reshaping Indian food processor sourcing.
- Granules:Agglomerated crystalline forms improve flowability for direct-compression tableting. German pharmaceutical compounders specify EP-certified granular dextrose for high-speed production lines.
- Tablets:Pre-compressed glucose excipients and energy tablets target sports nutrition and clinical hypoglycemia management. Direct-to-consumer channels in North American pharmacy retail are expanding tablet SKUs.
Powder dominates installed base. Liquid is where expansion concentrates.
Application:
End-use fragmentation creates margin stratification, with injectable-grade pharmaceutical applications tolerating price premiums that food manufacturers reject.
- Food & Beverage:Mature volume channel spanning confectionery, baking, and beverage sweetening. Clean-label reformulation pressures in Western European retail are redirecting some volume toward isomaltulose alternatives.
- Pharmaceutical:Parenteral nutrition, IV solutions, and oral dosage excipients demand multi-pharmacopeia certification. CDSCO's tightened IP-grade specifications are consolidating Indian hospital supplier lists to domestic refiners with dedicated production trains.
- Cosmetic Products:Humectant and stabilizer functions in skincare and haircare formulations. South Korean personal care manufacturers specify non-GMO corn-derived glucose for premium export lines.
- Nutritional Supplements:Sports nutrition and clinical nutrition powders. Direct-to-consumer protein brands in the United States are specifying low-microbiological-load dextrose for ready-to-mix formulations.
- Chemical Industry:Fermentation feedstock for bio-based platform chemicals and enzymatic conversions. Biochemical producers in the Netherlands are contracting multi-year glucose streams for succinic acid production.
Food & Beverage retains volume leadership. Pharmaceutical is climbing the fastest.
End User:
Customer scale determines contract structure, with multinational pharmaceutical companies negotiating direct mill relationships while regional food processors purchase through distributor tiers.
- Food Manufacturers:Confectionery, bakery, and dairy processors purchasing commodity-grade material. Indian biscuit producers under PLI scheme incentives are expanding captive glucose refining capacity.
- Pharmaceutical Companies:Formulators of injectable solutions and solid dosages requiring USP/EP certification. Large hospital networks in the United States Midwest now contract directly with wet-mill operators.
- Personal Care Brands:Cosmetic and hygiene product manufacturers specifying cosmetic-grade purity. French luxury skincare houses audit glucose suppliers for allergen and residual protein documentation.
- Supplement Producers:Sports nutrition and clinical nutrition compounders. German powder blenders are consolidating supplier bases to reduce endotoxin variability in parenteral-grade inputs.
- Industrial Manufacturers:Biochemical and biofuel producers seeking fermentation feedstock. Brazilian industrial biotechnology clusters are absorbing glucose volumes previously destined for ethanol channels.
Food Manufacturers represent the deepest installed demand. Pharmaceutical Companies are where margin expansion concentrates.
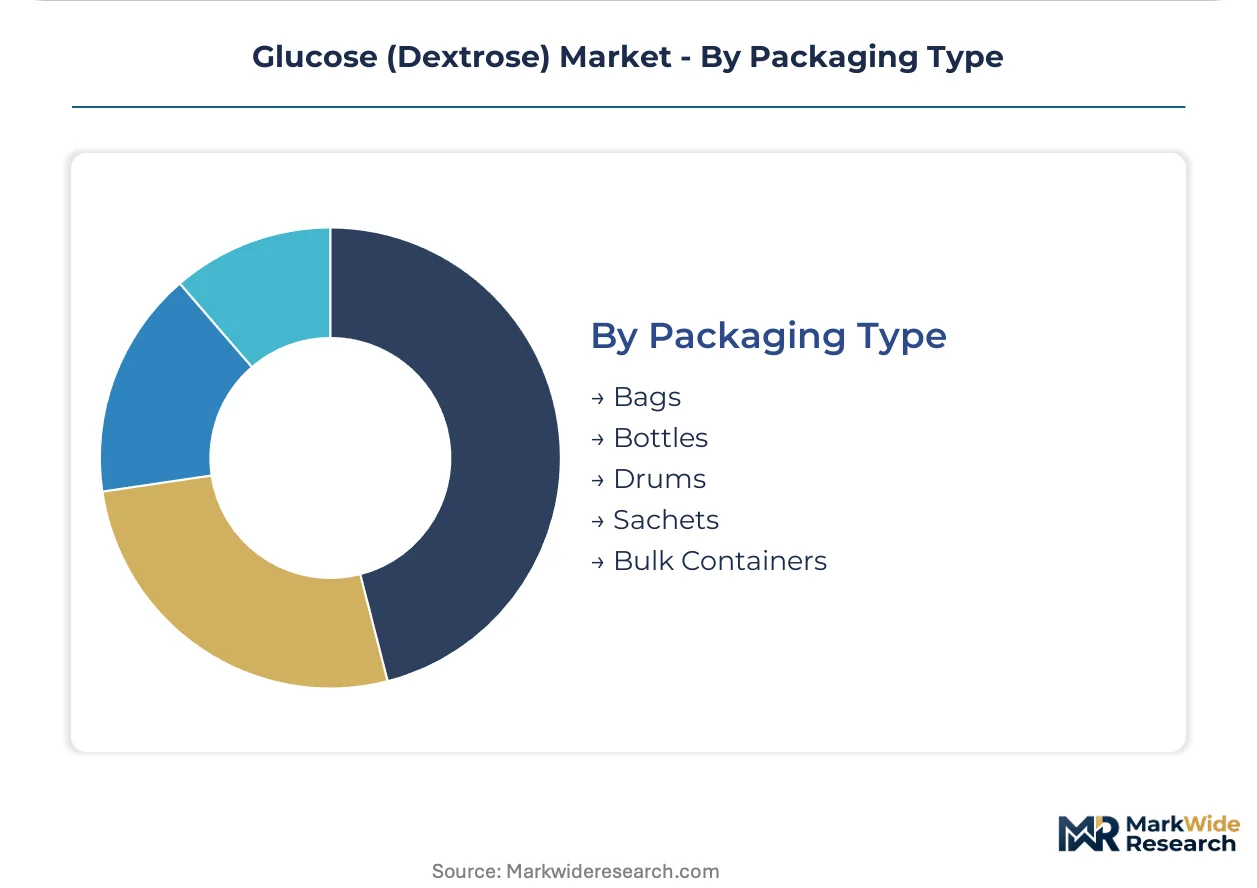
Packaging Type:
Packaging selection tracks customer scale and contamination sensitivity, with multi-wall bags serving mid-tier processors and bulk tankers feeding continuous manufacturing.
- Bags:Multi-ply paper and PE-lined sacks for food and pharmaceutical powder. Indian pharmaceutical distributors specify triple-bag pharmaceutical-grade dextrose for humidity protection during monsoon logistics.
- Bottles:Rigid containers for liquid glucose and syrup retail formats. Brazilian retail channels are expanding PET bottle SKUs for household baking applications.
- Drums:Steel and fiber drums for liquid and high-purity solid grades. Swiss parenteral nutrition compounders require steam-sterilizable drums with lot-specific certificates of analysis.
- Sachets:Single-serve portions for clinical and sports nutrition. Japanese hospital feeding protocols are standardizing 25g glucose sachets for hypoglycemia emergency kits.
- Bulk Containers:Flexitanks and ISO tank containers for liquid glucose and industrial syrup. Biochemical producers in the Netherlands are contracting dedicated flexitank volumes for fermentation feedstock.
Bags dominate current throughput. Bulk Containers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian hospital procurement teams exhibit the highest price elasticity for pharmaceutical-grade dextrose, while Swiss parenteral nutrition compounders absorb substantial premiums for EP-certified crystalline material. German buyers occupy a mid-point, trading volume scale against documentation rigor.
United States
Midwest hospital networks now contract directly with corn wet-mill operators for annual dextrose monohydrate commitments, bypassing distributor markups entirely. FDA enforces identity and purity specifications under 21 CFR, mandating dedicated production lines for IV-grade material. Chicago-area integrated health systems are consolidating parenteral nutrition purchasing into multi-year volume agreements.
India
Domestic pharmaceutical manufacturing and government production-linked incentive schemes are accelerating bulk dextrose consumption from local wet-mill operators. CDSCO tightened IP-grade purity thresholds for intravenous dextrose, consolidating hospital supplier lists to domestic refiners. Maharashtra-based pharmaceutical clusters are expanding captive glucose refining capacity under PLI scheme capital deployment.
Germany
Parenteral nutrition formulators are adopting membrane-polished dextrose to reduce endotoxin variability in high-speed production lines. EMA's European Pharmacopoeia sets monograph standards for intravenous-grade material, with 2024 revisions tightening endotoxin limits. North Rhine-Westphalia hospital procurement consortia are consolidating supplier lists to those with demonstrated multi-batch EP certification.
Brazil
Ethanol producers contract dedicated tanker volumes of aqueous glucose solutions, bypassing bagged alternatives entirely. ANVISA certification requirements for pharmaceutical-grade dextrose create import substitution potential for certified exporters meeting Brazilian injectable standards. São Paulo industrial biotechnology clusters are absorbing glucose volumes previously destined for fuel ethanol channels.
Switzerland
Parenteral nutrition compounders specify EP-certified granular dextrose with steam-sterilizable drum packaging and lot-specific certificates of analysis. Swissmedic aligns with European Pharmacopoeia standards for intravenous-grade material, elevating documentation requirements. Basel-area pharmaceutical formulators are contracting membrane-filtered crystalline grades to reduce batch-to-batch variability.
Glucose (Dextrose) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with backward integration into corn origination and enzyme technology platforms separating the two groups. The upper tier commands pharmaceutical-grade certification through captive wet-milling infrastructure, while specialists rely on toll processing or regional starch sourcing. Strategic archetypes include integrated agricultural processors, European fractionation houses, and Asian pharmaceutical-grade entrants. Dominant competitive moves encompass capacity expansion in Indian pharmaceutical corridors and membrane filtration technology licensing for endotoxin reduction.
Within the integrated processor tier, Tate & Lyle PLC and Cargill Incorporated exemplify the agricultural-origination model, leveraging British and North American corn wet-milling infrastructure respectively to sustain pharmaceutical-grade output across regional supply corridors. Roquette Frères occupies a position among European fractionation specialists, representing the dedicated refiner archetype that competes through multi-pharmacopeia certification depth rather than feedstock control.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Tereos S.A. |
| Archer Daniels Midland Company |
| Grain Processing Corporation |
| AGRANA Beteiligungs-AG |
| Cargill Incorporated |
| Roquette Frères |
| Südzucker AG |
| Ingredion Incorporated |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Midwest hospital networks and corn wet-mill operators lock in both supply access and price visibility for pharmaceutical-grade dextrose monohydrate, insulating buyers from spot corn volatility while securing dedicated production train capacity. These agreements compress distributor markups and establish volume-tiered pricing floors that commodity food-grade processors cannot access.
Pricing Analysis
After-sales revenue from analytical testing services and lot-specific certificate of analysis documentation drives lifetime value for pharmaceutical-grade refiners. Three-tier pricing structure across USP-certified, EP-certified, and food-grade crystalline dextrose separates premium intravenous material from standard oral excipients and economy fermentation feedstock. Pricing pressure stems from corn feedstock volatility and enzymatic hydrolysis yield improvements that lower unit production costs. Food manufacturers exhibit highest price sensitivity, while Swiss parenteral nutrition compounders absorb substantial premiums for membrane-polished EP-certified granular grades.
Supply Chain Analysis
Inventory buffers and extended lead times for multi-pharmacopeia validation compress working capital efficiency for new pharmaceutical-grade entrants. Supply concentrates in the United States, India, and Germany, with corn wet-milling infrastructure anchoring North American output and Maharashtra-based refiners expanding under PLI scheme capital deployment. Raw material dependencies center on corn origination, glucoamylase enzyme supply, and membrane filtration equipment. Single-source vulnerability runs through concentrated enzyme technology platforms. Distribution runs through direct mill contracts for large hospital networks and distributor tiers for regional food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical-grade dextrose sits in early-cycle expansion as CDSCO IP-grade mandates and PLI scheme subsidies accelerate domestic Indian capacity buildout. Parenteral nutrition protocol proliferation and sports nutrition formulation growth extend addressable demand beyond traditional clinical boundaries.
For Market Incumbents: Fortify pharmaceutical-grade certification moats by investing in dedicated membrane filtration production trains and expanding captive corn origination in North American supply corridors. Isomaltulose substitution in sports nutrition and emerging Indian wet-mill competitors threaten margin pools. Backward integration into enzyme technology platforms and direct hospital procurement relationships provide defensive leverage. For New Entrants and Emerging Players: Contract analytical chemistry services for USP and EP certification represent a service-layer gap where incumbents under-serve mid-tier pharmaceutical compounders. Brazilian ANVISA certification gaps and direct-to-consumer glucose tablet channels in North American pharmacy retail offer penetrable white-space targets. Position through membrane-polished dextrose for endotoxin-sensitive parenteral nutrition applications. For Investors and Strategic Acquirers: European fractionation houses with demonstrated multi-pharmacopeia certification depth but lacking feedstock control present acquisition target archetypes with consolidation upside. Long-term viability hinges on biochemical fermentation feedstock pivots diverting volume from commodity food channels. Watch for CDSCO harmonization with EMA monograph standards as inflection indicator for Indian pharmaceutical-grade capacity rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Maharashtra-based wet-mill operators deploy PLI scheme capital to capture CDSCO-mandated IP-grade demand. |
| Backward Integration | Corn origination assets insulate Tate & Lyle and Cargill from feedstock volatility compressing non-integrated fractionator margins. |
| Long-term Supply Agreement | Midwest hospital networks bypass distributor markups through direct annual dextrose monohydrate commitments with wet-mill operators. |
| Joint Venture | Membrane filtration technology licensing partnerships reduce capital requirements for new pharmaceutical-grade entrants. |
| Green Manufacturing Transition | Enzymatic hydrolysis yield improvements lower unit costs and reduce thermal processing energy intensity. |
Research Methodology
Initial hypotheses were tested against primary input from pharmaceutical formulation executives, hospital procurement managers, corn wet-mill plant operators, and regulatory affairs specialists, and refined through secondary validation against FDA 21 CFR filings, EMA European Pharmacopoeia monograph revisions, CDSCO IP-grade notifications, and SEC 10-K disclosures from listed agricultural processors. Bottom-up volume modeling across powder, liquid, syrup, granule, and tablet product types triangulated with top-down value estimates derived from trade flow analysis and hospital procurement database aggregation.
Variance-decomposition across the projection horizon isolates contribution from pharmaceutical-grade certification tier, end-use application fragmentation, and regional regulatory cluster dynamics. CAGRs were derived through segmented growth rate reconciliation with macroeconomic feedstock assumptions. Forecast inputs incorporate enzymatic hydrolysis yield trajectories, PLI scheme capital deployment schedules, and membrane filtration adoption curves in parenteral nutrition formulation.
Underlying assumptions cover CDSCO-EMA harmonization timelines and corn planting cycle stability, with deviation risk concentrated in bio-based chemical feedstock subsidies redirecting commodity glucose flows. Forecasts reflect these assumption layers with explicit sensitivity to regulatory revision triggers. Revision becomes warranted when ANVISA pharmaceutical-grade certification requirements cross implementation thresholds or when isomaltulose substitution rates in sports nutrition exceed modeled penetration bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Sesame Seed Extract Market
Ingredients
Freeze-Dried Pea Isolates Market
Ingredients
Apple Extract Market
Ingredients
Casein and Caseinates Market
Ingredients
Tapioca Market
Ingredients
Diastatic Malt Market
Ingredients
Lupin Flour Market
Ingredients
Yeast and Yeast Extract Market
Ingredients
South America Algae Omega-3 Ingredients Market
Ingredients
Guar Gum Market
Ingredients
Soy and Milk Protein Ingredients Market
Ingredients
South America Fermented Ingredients Market
Ingredients
Cooking Coconut Milk Market
Ingredients
Africa Food Ingredients Market
Ingredients
Casein Glycomacropeptide Market
Ingredients
Potato Flour Market