
 Food Minerals Market | 2026-2036
Food Minerals Market Size, Share, and Industry Trends Forecast 2026-2036
Food Minerals Market Analysis
Functional beverage manufacturers are redrawing procurement priorities for chelated mineral complexes, shifting share from conventional food processors toward ready-to-drink and sports nutrition brands. DSM Nutritional Products leverages its micronutrient premix technology to anchor supply relationships with beverage innovators. Balchem Corporation sustains R&D intensity in mineral encapsulation systems that protect bioavailability through pasteurization. Cargill, Incorporated controls broad distribution infrastructure connecting agricultural mineral sources to downstream formulators.
Food minerals comprise inorganic elements essential for human metabolic function, typically supplied as salts, chelates, or oxides with specified elemental assay percentages and particle size distributions for homogeneous dispersion in matrices. Calcium dominates product type value pools due to bone health positioning across dairy alternatives and senior nutrition, while zinc competes for fastest-growing status in immune-support formulations. Powder form leads manufacturing throughput for industrial-scale fortification, though liquid concentrates gain share in beverage applications where dispersion kinetics determine processing economics.
The FDA governs GRAS determinations and nutrient content claims for fortified foods in the United States, while EFSA evaluates novel mineral sources and health claim substantiations across European markets, with both agencies tightening evidentiary standards for bioavailability assertions. FSSAI in India mandates minimum and maximum mineral levels in packaged foods, creating compliance thresholds for import access. Stakeholders must monitor divergent premarket notification pathways between jurisdictions to avoid formulation lock-in that limits geographic expansion.
Market Dynamics
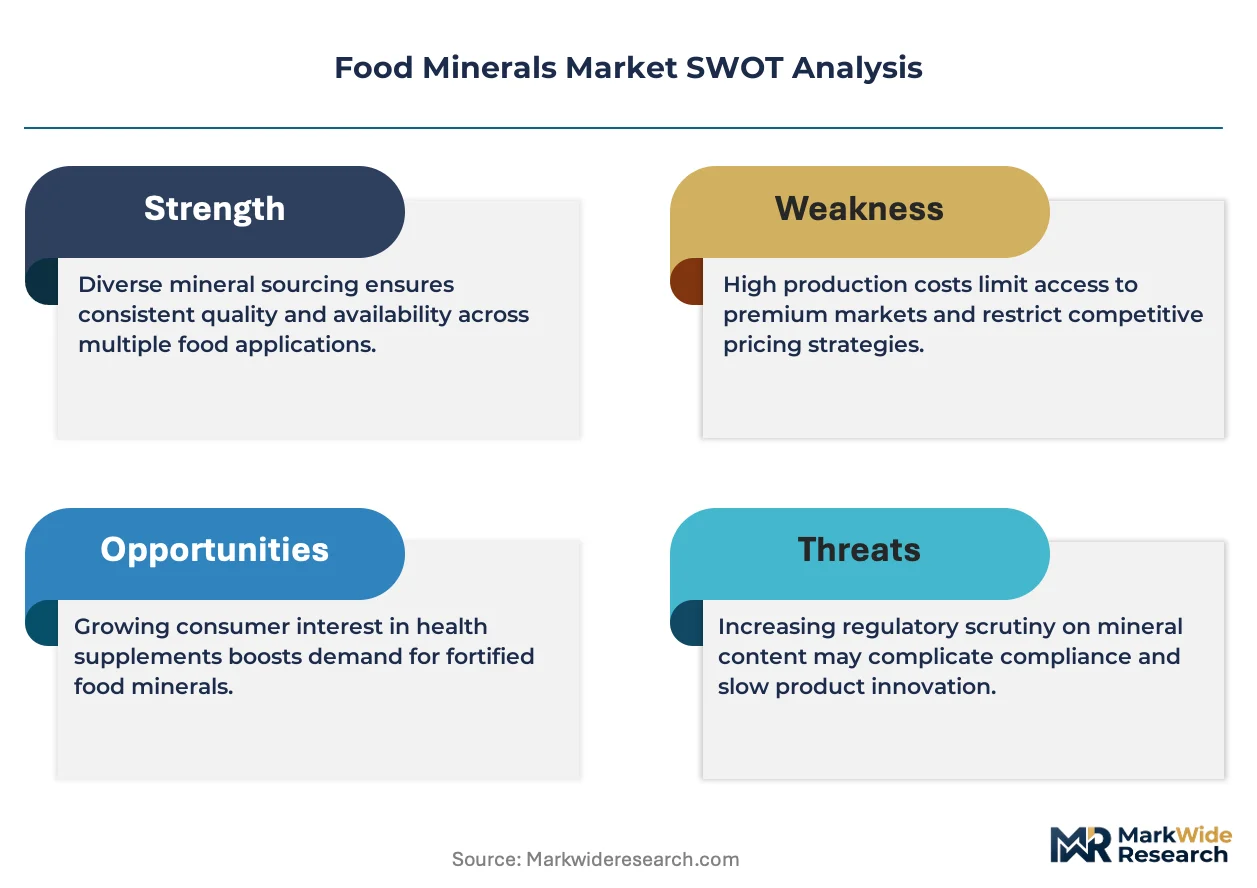
Precision nutrition clusters in Germany's Rhine-Neckar region are recalibrating mineral sourcing strategies as FDA and EFSA tighten bioavailability evidentiary standards, forcing formulators to rebuild supply relationships around certified premix suppliers rather than commodity mineral traders.
Growth Catalysts
- EFSA Novel Food authorizations:Accelerated approvals for algae-derived calcium and marine magnesium sources are unlocking new raw material streams for fortification programs targeting senior nutrition and plant-based dairy alternatives.
- Sports nutrition vertical:Ready-to-drink protein beverages and electrolyte recovery formulations are expanding mineral premix volumes as brands compete on recovery-positioning claims requiring chelated zinc and magnesium complexes.
- India FSSAI fortification mandates:Mandatory iron, zinc, and vitamin premixing in wheat flour and edible oils across 12 states is creating import demand for mineral complexes meeting Bureau of Indian Standards particle size specifications.
Market Restraints
- Phosphate rock supply concentration:Moroccan and Chinese state-controlled producers dominate elemental phosphorus feedstock for calcium phosphate fortification, exposing processors to export quota volatility and shipping corridor disruptions.
- Ferrous sulfate price instability:Steel industry off-gas recovery yields fluctuate with electric arc furnace operating rates, compressing margins for iron-fortified cereal and flour producers locked into annual supply contracts.
- GRAS determination timelines:FDA's extended safety evaluation periods for novel organic mineral chelates delay commercialization by 18-36 months, freezing R&D capital in pre-revenue formulations.
Strategic Opportunities
- Brazil ANVISA harmonization:Pending alignment with Codex Alimentarius mineral maximum levels would streamline export registration for premix suppliers currently navigating state-level sanitary surveillance fragmentation.
- Direct-to-consumer mineral testing:At-home micronutrient status diagnostics paired with personalized supplement subscriptions are creating demand for pharmaceutical-grade mineral APIs beyond traditional food manufacturing channels.
- Cell-cultured meat fortification:Emerging cultivated protein producers require custom mineral media formulations for muscle tissue scaffolding, opening technical partnerships between chelate specialists and bioreactor operators.
Industry Challenges
- Analytical method standardization:Divergent AOAC and ISO protocols for mineral bioavailability measurement create conflicting label substantiation across export markets, forcing duplicate testing expenditure.
- Encapsulation equipment retrofitting:Transitioning from spray-dried to lipid-based mineral protection systems requires fluidized bed reactor investments that mid-scale processors cannot amortize against contract manufacturing volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Minerals Market |
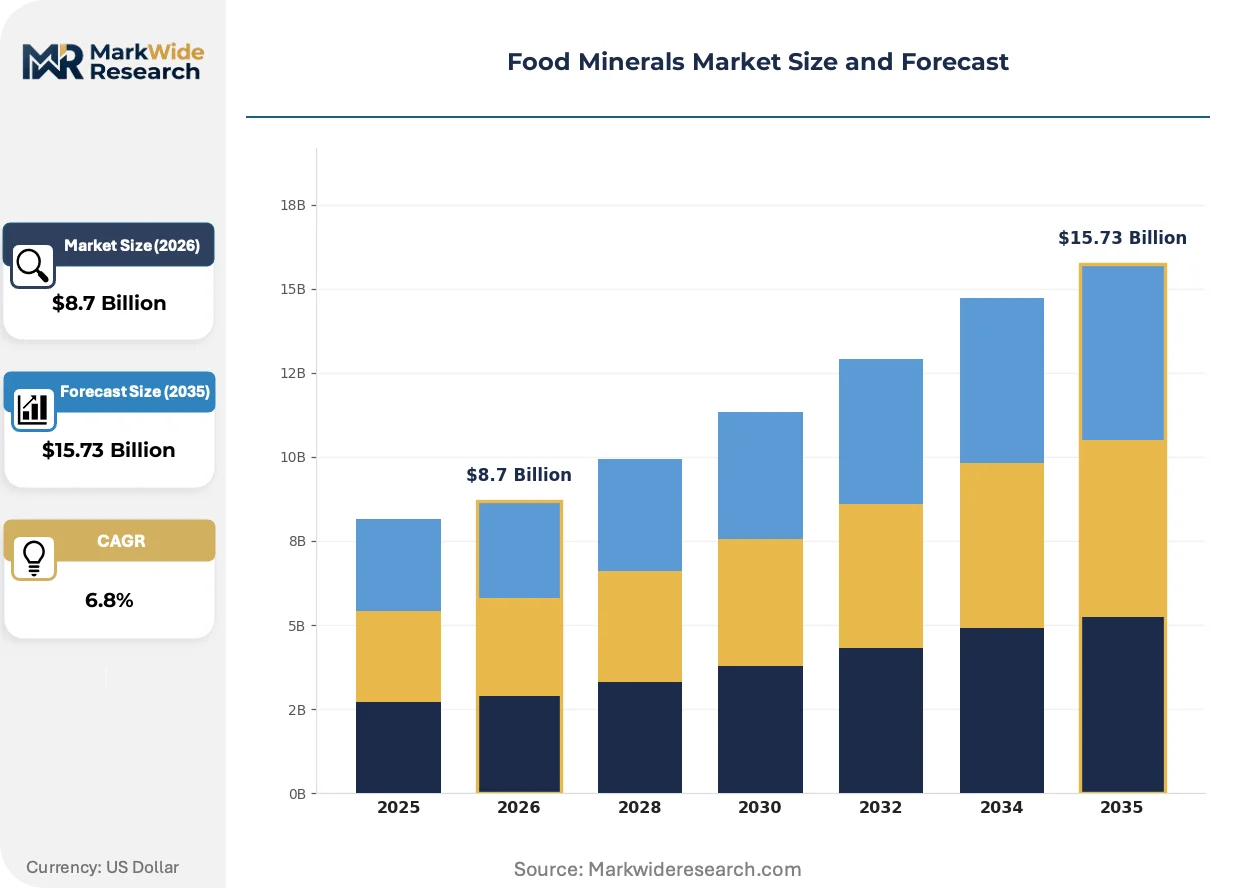
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium, Iron, Magnesium, Zinc Form: Powder, Liquid, Granules, Tablet End User: Food Industry, Dietary Supplements, Pharmaceuticals, Animal Feed Packaging Type: Bottles, Pouches, Boxes, Blisters |
| Companies Covered | BASF, DSM Nutritional Products, Balchem Corporation, SPI Pharma, Inc., Cargill, Incorporated, Waitaki Bio, Sigma Minerals Limited, Bayer, Glanbia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Minerals Market Emerging Trajectories
Mineral delivery technology is fragmenting along processing-temperature lines as beverage pasteurization requirements harden, while regulatory agencies on three continents simultaneously elevate substantiation thresholds for absorption claims.
Lipid-based mineral encapsulation is bifurcating the premix supplier landscape. Spray-chilled and fluidized bed coating systems protect zinc and iron bioavailability through UHT treatment regimes above 135°C. Premium-positioned infant formula and medical nutrition brands are absorbing 15-25% raw material cost premiums for these protected complexes. The technology is compressing commodity oxide and sulfate market share in temperature-sensitive applications.
EFSA's 2023 updated guidance on health claim substantiation for mineral absorption is tightening clinical trial design requirements. Randomized controlled studies must now demonstrate statistically significant serum concentration increases against placebo, not merely compliance with nutrient reference values. Iron-fortified breakfast cereal and supplement brands targeting European markets are restructuring clinical programs to incorporate stable isotope methodology.
Ingredient procurement for mineral premixes is consolidating through preferred supplier agreements rather than spot-market purchasing. Large beverage and dairy manufacturers are signing 24-36 month offtake contracts with DSM and Balchem that bundle technical support, regulatory dossier access, and volume pricing. This displacement of traditional mineral traders is most visible in North American sports nutrition and German precision nutrition manufacturing clusters.
Food Minerals Market Segmentation
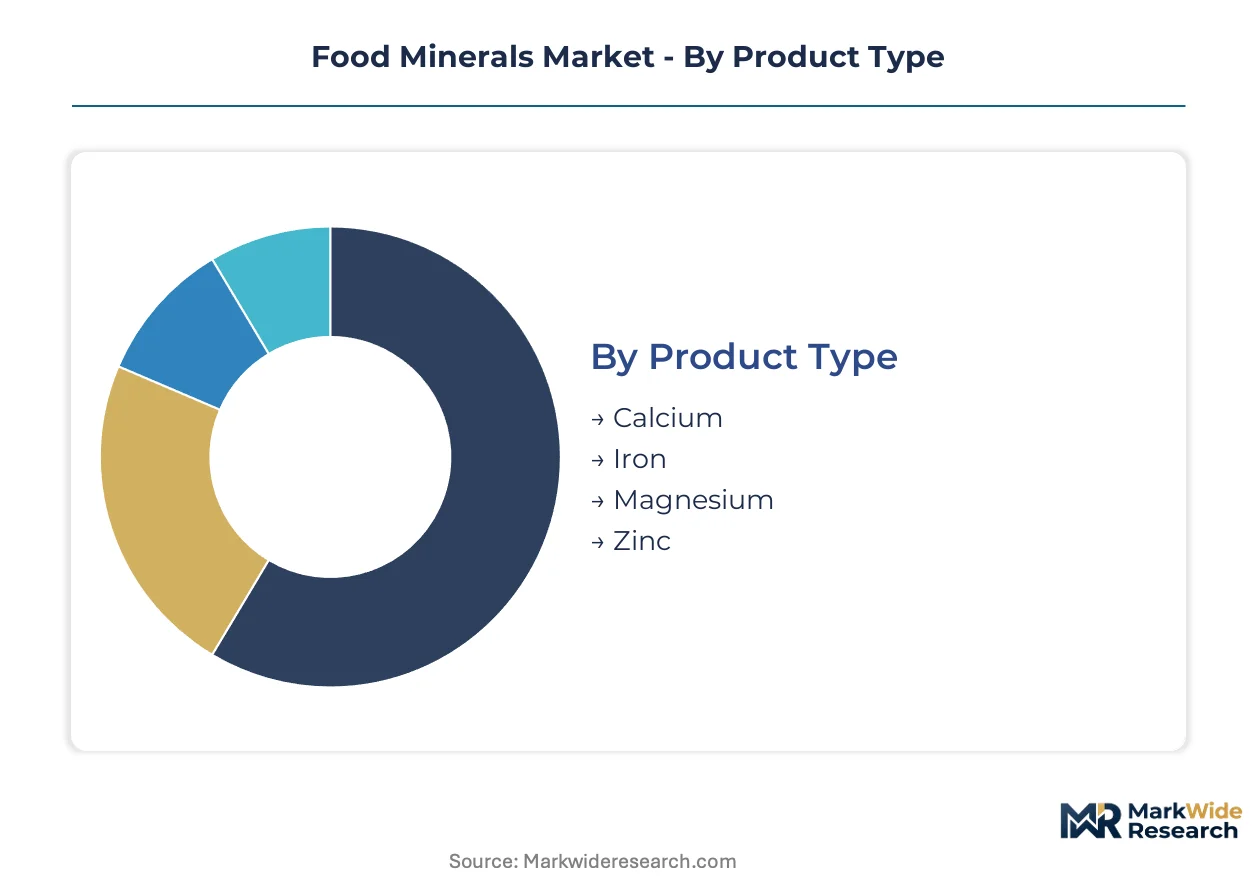
Segmentation in food minerals reveals how bioavailability requirements and processing constraints fragment procurement strategies. Manufacturers align mineral form and packaging with specific end-use temperature regimes and shelf-life demands.
Product Type:
Margin pools concentrate in chelated complexes that command premium positioning in medical nutrition and infant formula, while commodity salts compete on volume in mass-market fortification.
- Calcium:Dominates value pools through bone health positioning across dairy alternatives and senior nutrition. Demand concentrates in Germany's precision nutrition cluster around Mannheim and Heidelberg as FDA and EFSA tighten bioavailability evidentiary standards.
- Zinc:Chelated zinc complexes compete for fastest-growing status in immune-support formulations. Sports nutrition brands in North America absorb 15-25% raw material cost premiums for protected complexes that survive UHT pasteurization.
- Iron:Ferrous sulfate and bisglycinate variants serve cereal fortification and anemia-prevention programs. India's FSSAI mandates in 12 states are driving import demand for complexes meeting Bureau of Indian Standards specifications.
- Magnesium:Marine-derived and oxide forms target muscle recovery and sleep-positioning supplements. EFSA novel food authorizations for marine sources are unlocking new raw material streams.
The dominant share belongs to Calcium, while Zinc is closing the gap fastest.
Form:
Processing temperature tolerance determines form selection, with dispersion kinetics in beverage applications creating distinct cost-to-serve economics.
- Powder:Leads manufacturing throughput for industrial-scale fortification. Spray-dried mineral salts serve wheat flour and edible oil premixing under India's FSSAI mandates.
- Liquid:Concentrates gain share in beverage applications where dispersion kinetics determine processing economics. Lipid-based encapsulation protects bioavailability through pasteurization above 135°C.
- Granules:Intermediate form for tableting operations and direct-compression supplement manufacturing. Flow properties suit high-speed packaging lines.
- Tablet:Finished dosage form bypasses food matrix integration for direct-to-consumer supplement channels. At-home micronutrient testing is expanding pharmaceutical-grade mineral API demand.
Powder commands the largest volume position, though Liquid is expanding most quickly in temperature-sensitive applications.
End User:
Customer concentration varies by regulatory exposure, with pharmaceutical-grade specifications filtering procurement tiers.
- Food Industry:Dairy alternatives and ready-to-drink beverages drive chelated mineral procurement. Functional beverage manufacturers are redrawing priorities toward mineral fortification programs.
- Dietary Supplements:Direct-to-consumer subscriptions paired with at-home testing are creating demand beyond traditional food manufacturing channels.
- Pharmaceuticals:Medical nutrition and infant formula brands absorb premium pricing for encapsulated complexes with validated bioavailability dossiers.
- Animal Feed:Premix specifications for livestock and pet nutrition follow parallel fortification logic with lower purity thresholds.
Food Industry holds the established volume base, while Pharmaceuticals is climbing the fastest on regulatory premium capture.
Packaging Type:
Moisture sensitivity and shelf-life requirements segment packaging selection across distribution channels.
- Bottles:HDPE and glass containers serve liquid concentrates and high-value supplement tablets. Child-resistant closures add compliance cost for iron-containing products.
- Pouches:Flexible packaging dominates powder premixes for industrial food manufacturing. Barrier properties protect hygroscopic mineral salts.
- Boxes:Secondary packaging for blister strips and sachet bundles. Retail shelf presence drives branding investment.
- Blisters:Unit-dose compliance packaging for pharmaceutical and medical nutrition segments. Aluminum-foil barriers extend stability for oxidation-sensitive forms.
Pouches capture the dominant industrial position, while Blisters are gaining share fastest in pharmaceutical-grade channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's mineral bulk handling infrastructure underwrites Europe's import dominance for calcium carbonate and magnesium oxide feedstocks, connecting Moroccan phosphate rock deposits to German precision nutrition manufacturers.
Germany
Mannheim and Heidelberg anchor the Rhine-Neckar precision nutrition cluster where chelated mineral premix R&D concentrates. EFSA novel food authorizations for algae-derived calcium are tightening bioavailability evidentiary standards, forcing formulators to rebuild supply relationships around certified premix suppliers.
United States
Sports nutrition brands in California and Texas drive demand for zinc and magnesium complexes surviving UHT pasteurization. FDA GRAS determination timelines for novel organic mineral chelates delay commercialization by 18-36 months, freezing R&D capital in pre-revenue formulations.
India
Maharashtra and Gujarat process wheat flour and edible oil fortification premixes under FSSAI mandates across 12 states. Bureau of Indian Standards particle size specifications for iron and zinc complexes are creating import demand for certified mineral suppliers.
Brazil
São Paulo and Rio Grande do Sul concentrate beverage manufacturing awaiting ANVISA harmonization with Codex Alimentarius mineral maximum levels. State-level sanitary surveillance fragmentation currently complicates export registration for premix suppliers.
China
Shandong and Jiangsu provinces house steel industry off-gas recovery operations yielding ferrous sulfate for iron fortification. SAMR and GB standards govern mineral additive specifications, though phosphate rock supply concentration exposes processors to export quota volatility.
Food Minerals Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and regulatory dossier depth, creating a tiered structure where scale-driven commodity suppliers coexist with niche premix innovators. The vendor base fragments along processing-temperature capabilities and encapsulation technology ownership. Three archetypes dominate: integrated chemical conglomerates with backward mineral sourcing, dedicated nutrition specialists with clinical validation capabilities, and regional traders with distribution infrastructure. M&A activity targets mineral encapsulation IP, while strategic partnerships lock in beverage manufacturing offtake.
Within the nutrition specialist tier, DSM Nutritional Products and Balchem Corporation exemplify premix suppliers bundling technical support with regulatory dossier access. BASF represents the integrated chemical archetype with captive mineral feedstock positions. Cargill, Incorporated anchors the distribution-focused segment connecting agricultural mineral sources to downstream formulators.
| Leading Market Players |
|---|
| BASF |
| DSM Nutritional Products |
| Balchem Corporation |
| SPI Pharma, Inc. |
| Cargill, Incorporated |
| Waitaki Bio |
| Sigma Minerals Limited |
| Bayer |
| Glanbia |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory positions among German precision nutrition manufacturers signal how supply-chain concentration translates directly into premix pricing power, with chelated mineral complexes commanding sustained premiums over commodity salts.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade mineral APIs from standard food-grade salts and economy oxide feedstocks. Certification level — specifically EFSA novel food authorization status and FDA GRAS determination — drives the widest price spreads, with bioavailability-validated chelates absorbing 15-25% raw material premiums. Pricing pressure stems from ferrous sulfate volatility tied to steel industry off-gas recovery yields. Mass-market cereal fortifiers exhibit highest price sensitivity, while infant formula and medical nutrition brands demonstrate lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Strategic stockpile preferences dominate phosphate rock procurement, with processors maintaining 60-90 day buffers against Moroccan and Chinese state-controlled export quota volatility. Raw material dependencies center on elemental phosphorus feedstock, marine magnesium harvests, and algae-derived calcium biomass. Single-source vulnerability concentrates in Moroccan phosphate rock deposits feeding calcium phosphate fortification. Distribution runs through Rotterdam bulk handling infrastructure connecting North African mineral deposits to German precision nutrition clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against synthetic mineral complexes and novel nano-delivery formats threatening conventional chelate positions.
For Market Incumbents: Consolidate supply relationships through 24-36 month offtake contracts bundling technical support and regulatory dossier access. Deepen backward integration into marine mineral harvesting and algae cultivation to secure EFSA novel food authorization pipelines. Lock in beverage manufacturing partnerships before encapsulation technology commoditizes.
For New Entrants and Emerging Players: Anchor in Brazil's pending ANVISA harmonization window, where state-level sanitary surveillance fragmentation currently blocks established premix suppliers. Target direct-to-consumer mineral testing subscriptions paired with personalized supplement formulations. Lead with pharmaceutical-grade mineral API positioning to bypass commodity salt competition.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because EFSA and FDA bioavailability evidentiary standards are freezing out commodity traders and consolidating share among dossier-rich specialists. Acquisition targets should display validated clinical programs using stable isotope methodology. Watch for FDA GRAS determination timeline compression as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Dossier Investment | EFSA novel food authorizations for marine magnesium unlock premium positioning in senior nutrition. |
| Encapsulation Technology Acquisition | Lipid-based mineral protection systems defend bioavailability through UHT pasteurization above 135°C. |
| Long-term Supply Agreement | Twenty-four to thirty-six month offtake contracts with beverage manufacturers displace spot-market mineral traders. |
| Backward Integration | Captive algae cultivation and marine harvesting secure raw material streams for novel calcium sources. |
| Joint Venture | Technical partnerships with cell-cultured meat producers open custom mineral media formulation channels. |
Methodological Framework
A standing panel of premix procurement directors, regulatory affairs leads at fortified food manufacturers, encapsulation R&D heads, and beverage formulation scientists provided ongoing calibration against secondary validation through customs trade data, EFSA novel food registers, FDA GRAS notifications, and Bureau of Indian Standards filings. Bottom-up mineral premix volume estimates triangulated against top-down fortified food production data.
Consistency checks against external benchmarks validated value outputs across the projection horizon. Segmentation dimensions modeled included mineral form (chelated, salt, oxide), end-use temperature regime, and regional regulatory cluster. CAGRs derived from mineral premix volume trajectories indexed to fortified food and dietary supplement production forecasts, with explicit modeling of FSSAI mandate rollout timing and EFSA authorization velocity.
Material uncertainties — phosphate rock export quota volatility, FDA GRAS determination timeline shifts, and ferrous sulfate price instability tied to electric arc furnace operating rates — sit outside the modeled envelope. Forecasts reflect assumptions documented in the analysis framework. Practitioners should keep alternative scenarios live as bioavailability substantiation standards and novel mineral source approvals evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Lupin Flour Market
Ingredients
Rendered Products Market
Ingredients
Lupine Peptides Market
Ingredients
North America Dairy Ingredients Market
Ingredients
Europe Potato Protein Market
Ingredients
Kairomones Market
Ingredients
Asia-Pacific Fats and Oil Market
Ingredients
Isoamyl Laurate Market
Ingredients
Middle East & Africa Prebiotic Ingredients Market
Ingredients
Oat Grass Powder Market
Ingredients
Yeast and Yeast Extract Market
Ingredients
Pet Food Premix Market
Ingredients
Hops Derivative Market
Ingredients
PHO Oils Market
Ingredients
Bromelain Ingredient Market
Ingredients
Casein Hydrolysate Market