
 Citrus Fiber Market | 2026-2036
Citrus Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Citrus Fiber Market Analysis
Multi-source citrus peel procurement is restructuring supply security for European and North American ingredient houses. Fiberstar Inc. leverages dual-hemisphere sourcing agreements to buffer against Mediterranean harvest volatility. Herbstreith & Fox GmbH anchors its position through backward integration into Spanish and Italian citrus processing streams.
Citrus fiber denotes the insoluble and soluble cellulosic material extracted from citrus fruit albedo and flavedo layers, typically comprising 60-80% dietary fiber with water-holding capacities exceeding 8:1 by weight, and functions primarily as a texturizing agent, fat mimetic, and shelf-life extender across formulated foods. Orange fiber dominates volume throughput due to year-round raw material availability from juice industry byproduct streams, while grapefruit fiber commands narrower premium positioning in nutraceutical capsules where bitter bioflavonoid retention adds functional distinction. Powder form leads food industry adoption for dry-blend compatibility, though liquid suspensions are gaining traction in beverage applications requiring clean-label mouthfeel modification without hydrocolloid gums.
REACH compliance and EFSA novel food consultations govern citrus fiber market access across the European Union, while FDA GRAS self-determination pathways shape U.S. commercialization timelines for new extraction variants. USDA organic certification and EU organic regulation 2018/848 increasingly filter contract eligibility for clean-label supply chains. Stakeholders must track evolving fiber content claim thresholds under Codex Alimentarius and national labeling frameworks to avoid reformulation exposure.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing reformulation timelines for food manufacturers, forcing ingredient houses to secure certified citrus fiber supply chains ahead of tightened additive disclosure mandates.
Growth Catalysts
- Clean-label bakery reformulation:German and French manufacturers are extending wheat flour with citrus fiber to meet EU organic regulation 2018/848 certification thresholds.
- REACH compliance pathways:Streamlined ECHA registration for citrus-derived ingredients is accelerating market access for novel extraction variants across member states.
- Juice industry byproduct recovery:Valencia and São Paulo processing corridors are capturing previously discarded albedo streams for fiber valorization.
Market Restraints
- Mediterranean harvest volatility:Spanish and Italian orange crop fluctuations create raw material availability gaps that ripple through European supply chains.
- EFSA novel food consultation timelines:Protracted safety assessments for new citrus fiber variants delay commercialization by 18-36 months.
- Hydrocolloid substitution pressure:Guar and locust bean gum price corrections in India are recapturing some clean-label bakery applications.
Strategic Opportunities
- Beverage mouthfeel modification:Liquid citrus fiber suspensions are penetrating functional drink formulations seeking to eliminate hydrocolloid gums.
- USDA organic certification arbitrage:North American contract manufacturers are sourcing certified organic citrus fiber to capture premium private-label bakery contracts.
- Nutraceutical capsule differentiation:Grapefruit fiber's bitter bioflavonoid retention is commanding specialized positioning in dietary supplement formulations.
Industry Challenges
- Dual certification complexity:Simultaneous EU organic regulation and USDA organic compliance requires parallel audit trails that strain quality assurance bandwidth.
- Extraction technology capex:Supercritical CO2 and enzymatic processing equipment demands capital deployment that mid-tier ingredient houses struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Citrus Fiber Market |
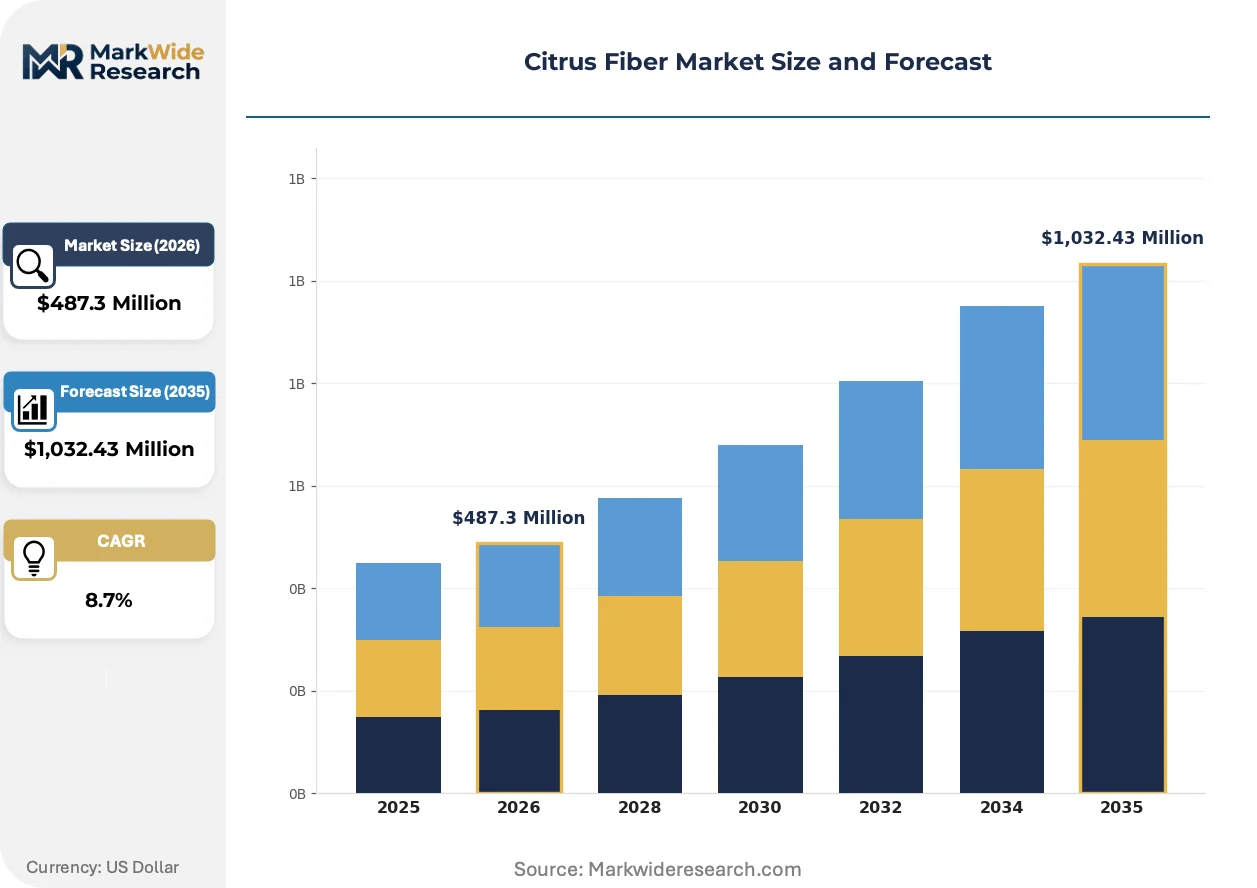
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orange Fiber, Lemon Fiber, Grapefruit Fiber, Pomelo Fiber Application: Food Industry, Beverage Industry, Dietary Supplements, Pharmaceuticals Form: Powder, Granules, Liquid, Capsules End User: Food Manufacturers, Nutraceutical Companies, Cosmetic Brands, Bakeries |
| Companies Covered | Herbstreith & Fox GmbH, DuPont de Nemours Inc., Fiberstar Inc., Naturex, Florida Food Products Inc., CP Kelco, Ceamsa, Ingredion Incorporated, Cargill Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Citrus Fiber Market Emerging Trajectories
Active reformulation across European food manufacturing is compressing traditional hydrocolloid dominance, with citrus fiber extraction technologies and certification-driven procurement models converging to reshape ingredient selection protocols.
Enzymatic extraction protocols are expanding into commercial-scale deployment, replacing conventional mechanical pressing with targeted pectinase and cellulase treatments that preserve water-holding capacity. Mid-tier Spanish and Italian processors are retrofitting existing juice lines, compressing capital requirements versus greenfield supercritical CO2 installations. This technology is expanding into nutraceutical-grade applications where bioflavonoid retention commands measurable price premiums.
EFSA's evolving fiber content claim thresholds are forcing reformulation transparency across EU member states, with draft guidance on dietary fiber definitions creating compliance uncertainty for blended ingredients. Bakery and meat analog manufacturers face dual pressure to meet Codex Alimentarius standards while anticipating national labeling framework divergences. German and French regulators are moving fastest, compressing timeline flexibility for cross-border formulation standardization.
Direct contracting between food manufacturers and citrus processors is displacing traditional ingredient distributor intermediation, with Rotterdam and Barcelona logistics hubs enabling just-in-time albedo sourcing. Large bakery groups are establishing preferred supplier relationships with Spanish cooperatives, capturing traceability data required by EU Green Deal procurement mandates. This pattern concentrates most visibly in clean-label private-label manufacturing serving northern European retail chains.
Citrus Fiber Market Segmentation
Citrus fiber procurement strategies diverge sharply across certification tiers, with organic and conventional supply chains demanding parallel audit infrastructures. Manufacturers must align segment selection with end-use regulatory exposure, particularly where EFSA novel food consultations or USDA organic thresholds apply.
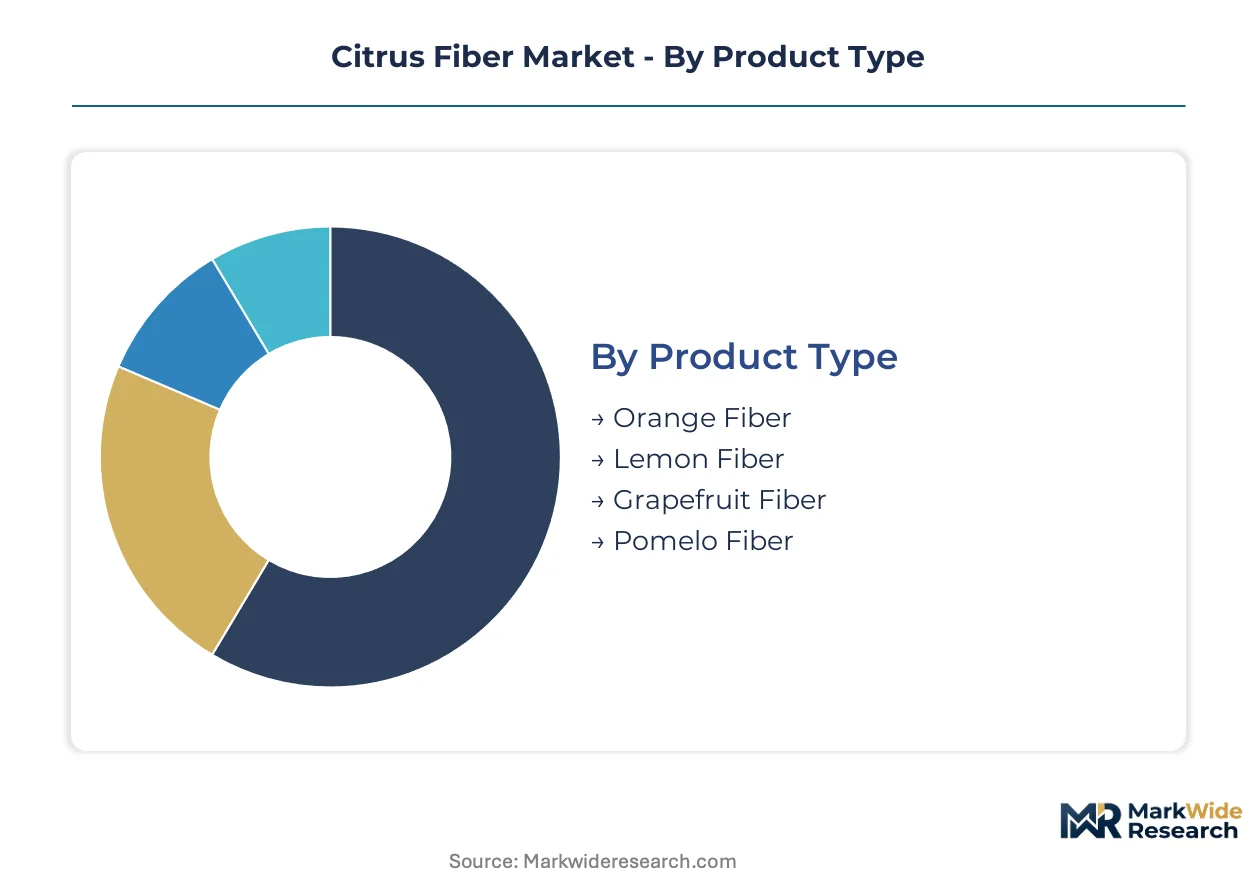
Product Type:
Certification burden varies by citrus variety: orange fiber navigates streamlined GRAS pathways in the US, while grapefruit fiber triggers extended EFSA safety assessments due to bioflavonoid complexity.
- Orange Fiber:Comprising 60-80% dietary fiber from albedo and flavedo layers with water-holding capacity exceeding 8:1 by weight. German and French bakery manufacturers dominate procurement volumes, driven by EU organic regulation 2018/848 reformulation mandates for clean-label flour extension.
- Grapefruit Fiber:Retains bitter bioflavonoid compounds that command specialized positioning. Nutraceutical capsule formulators in North America absorb premium pricing for differentiated dietary supplement applications where functional distinction outweighs taste masking costs.
- Lemon Fiber:Higher acidity profile limits bakery compatibility but penetrates beverage mouthfeel modification where tartness aligns with flavor systems.
- Pomelo Fiber:Emerging supply from Southeast Asian processing corridors, constrained by inconsistent organic certification availability.
Leading the category by volume: Orange Fiber. Growing fastest: Grapefruit Fiber.
Application:
Margin structure separates segments: food industry contracts run on volume scale, while pharmaceutical applications sustain price premiums through GMP compliance overhead.
- Food Industry:Clean-label bakery reformulation across Rotterdam and Barcelona logistics corridors absorbs the majority of powder-form supply. EU Green Deal procurement mandates compress reformulation timelines for wheat flour extension applications.
- Beverage Industry:Liquid suspensions eliminate hydrocolloid gum dependencies in functional drink formulations. Mouthfeel modification demand concentrates in North American contract manufacturing serving private-label retail chains.
- Dietary Supplements:Capsule and tablet applications require nutraceutical-grade extraction protocols with bioflavonoid retention specifications.
- Pharmaceuticals:Excipient-grade fiber faces the steepest regulatory barriers, with novel drug delivery applications triggering multi-jurisdiction approval sequences.
Highest volume concentration: Food Industry. Steepest margin expansion: Pharmaceuticals.
Form:
Supply chain configuration dictates form selection: powder dominates dry-blend infrastructure, while liquid investments require dedicated suspension handling systems.
- Powder:Standard particle size distributions optimize for bakery and meat analog dry blending. Spanish and Italian processors retrofit existing juice lines to capture albedo valorization without greenfield capital deployment.
- Liquid:Pre-hydrated suspensions reduce manufacturing step complexity for beverage formulators eliminating guar and locust bean gum dependencies. Enzymatic extraction protocols preserve water-holding capacity through targeted pectinase treatments.
- Granules:Intermediate moisture formats suit dietary supplement tableting operations where flow characteristics override hydration speed.
- Capsules:Pre-dosed units command premium positioning in direct-to-consumer nutraceutical channels, with grapefruit fiber variants leveraging bitter bioflavonoid marketing claims.
Dominant form by throughput: Powder. Fastest adoption trajectory: Liquid.
End User:
Procurement sophistication separates tiers: multinational food manufacturers enforce dual certification, while regional bakeries operate on single-standard compliance.
- Food Manufacturers:Large bakery groups establish direct contracting with Spanish cooperatives, capturing traceability data required by EU Green Deal mandates. Preferred supplier relationships displace traditional ingredient distributor intermediation.
- Nutraceutical Companies:Capsule and tablet formulators prioritize grapefruit fiber for bioflavonoid retention, absorbing extended EFSA novel food consultation timelines for product differentiation.
- Cosmetic Brands:Topical and ingestible beauty applications represent emerging demand, constrained by REACH registration requirements for dermal exposure claims.
- Bakeries:Artisan and industrial operators drive clean-label flour extension adoption, with German and French facilities leading organic certification penetration.
Primary volume anchor: Food Manufacturers. Fastest certification adoption: Bakeries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spanish and Italian citrus groves supply the dominant raw material streams feeding European and North American fiber extraction facilities. Valencia's albedo processing corridors and Sicily's flavedo recovery operations anchor continental supply security. Brazilian São Paulo state provides counter-seasonal orange peel volumes to buffer Mediterranean harvest gaps.
Germany
Clean-label bakery manufacturers in Bavaria and North Rhine-Westphalia drive orange fiber procurement for wheat flour extension. The country's national food regulator enforces strict EU organic regulation 2018/848 compliance timelines. Hamburg logistics clusters coordinate just-in-time albedo sourcing from Spanish cooperatives.
United States
North American contract manufacturers absorb certified organic citrus fiber for private-label bakery contracts. FDA GRAS self-determination pathways accelerate commercialization timelines for novel extraction variants. California beverage formulators deploy liquid suspensions to eliminate hydrocolloid gum dependencies in functional drinks.
France
Artisan and industrial bakeries in Île-de-France and Auvergne-Rhône-Alpes lead organic certification penetration for flour reformulation. ANSM disclosure requirements tighten additive labeling rules under EU Green Deal alignment. Lyon food manufacturing corridors concentrate procurement from Barcelona logistics hubs.
Spain
Valencia and Andalusia processing corridors capture juice industry byproduct streams for albedo valorization. The country's national agricultural ministry coordinates with ECHA on streamlined REACH registration for citrus-derived ingredients. Barcelona logistics hubs enable direct contracting between cooperatives and northern European bakery groups.
Italy
Sicilian and Calabrian citrus processors retrofit existing juice lines for fiber extraction without greenfield capital deployment. EFSA novel food consultation timelines govern commercialization of grapefruit fiber variants with bioflavonoid retention. Emilia-Romagna food manufacturers source traceable supply for EU Green Deal procurement mandates.
Citrus Fiber Market Vendor Landscape
Backward integration into citrus processing streams dominates the current landscape, with ingredient houses securing captive albedo supply from Mediterranean juice operations. The vendor base stratifies across three tiers: multinational hydrocolloid diversifiers, mid-tier regional processors with cooperative partnerships, and specialized nutraceutical-grade extractors. Technology licensing and preferred supplier relationships constitute the primary competitive moves, compressing distributor intermediation in Rotterdam and Barcelona corridors.
Within the European specialist tier, Herbstreith & Fox GmbH and Ceamsa exemplify processors leveraging geographic proximity to Spanish and Italian citrus groves. Fiberstar Inc. represents the dual-hemisphere sourcing archetype, anchoring supply security through counter-seasonal procurement agreements. Among diversified ingredient conglomerates, DuPont de Nemours Inc., Cargill Inc., and Ingredion Incorporated occupy positions spanning multiple hydrocolloid and fiber categories.
| Leading Market Players |
|---|
| Herbstreith & Fox GmbH |
| DuPont de Nemours Inc. |
| Fiberstar Inc. |
| Naturex |
| Florida Food Products Inc. |
| CP Kelco |
| Ceamsa |
| Ingredion Incorporated |
| Cargill Inc. |
| Others |
Supply Flow & Price Mechanics
Family-owned Mediterranean citrus cooperatives anchor supply discipline through retained albedo ownership, compressing margin capture for ingredient distributors while enforcing quality premiums on certified organic streams. Their counter-seasonal contracting with Brazilian processors buffers price volatility from Spanish and Italian harvest gaps, embedding regional sourcing loyalty into procurement economics.
Pricing Analysis
Warranty and certification bundling separates nutraceutical-grade grapefruit fiber from commodity orange fiber tiers, with EFSA novel food consultation support included in premium contracts. Three-tier pricing structure across premium, standard, and economy levels reflects organic certification grade and bioflavonoid retention specifications. Cost compression in standard-grade powder forms is intensifying because Indian hydrocolloid price corrections recapture clean-label bakery applications. Artisan bakeries in Germany and France exhibit highest price sensitivity, while North American nutraceutical capsule formulators absorb premiums for functional differentiation.
Supply Chain Analysis
Direct-to-manufacturer channels handle large bakery group demand through preferred supplier relationships with Spanish cooperatives, displacing traditional ingredient distributor intermediation. Raw material streams draw from Valencia and São Paulo processing corridors, with Sicilian flavedo recovery operations feeding nutraceutical-grade extraction. Supply chain vulnerability centers on Mediterranean harvest volatility, where Spanish and Italian orange crop fluctuations ripple through European availability. Distribution runs through Rotterdam and Barcelona logistics hubs enabling just-in-time albedo sourcing for northern European food manufacturing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into citrus processing streams constitutes the decisive competitive race, with ingredient houses capturing captive albedo supply from juice industry byproduct recovery operations to defend margin position.
For Market Incumbents: Cement supply security through dual-hemisphere sourcing agreements that buffer Mediterranean harvest volatility, while retrofitting existing juice lines for enzymatic extraction to compress capital requirements versus greenfield supercritical CO2 installations. Hydrocolloid substitution pressure from Indian guar and locust bean gum price corrections demands accelerated certification investment to maintain clean-label bakery contract eligibility. For New Entrants and Emerging Players: Enter via liquid suspension formulations for North American beverage mouthfeel modification applications, where hydrocolloid gum elimination demand concentrates among private-label contract manufacturers. Southeast Asian pomelo fiber sourcing offers white-space potential constrained by organic certification gaps, with enzymatic extraction technology licensing providing lower-capex market entry. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier Spanish and Italian processors with cooperative partnerships and retrofittable juice line infrastructure, positioned for EU Green Deal procurement mandate capture. Long-term viability hinges on simultaneous EU organic regulation and USDA organic compliance capability, with EFSA novel food consultation backlog resolution serving as the critical inflection signal for grapefruit fiber premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Citrus Processing | Captive albedo supply from Valencia and São Paulo juice corridors secures raw material traceability for EU Green Deal compliance. |
| Enzymatic Extraction Technology Deployment | Retrofitted Italian and Spanish juice lines preserve water-holding capacity while compressing capital deployment versus supercritical CO2. |
| Dual Organic Certification Investment | Parallel EU regulation 2018/848 and USDA organic audit trails unlock premium private-label bakery contract eligibility. |
| Liquid Suspension Product Line Expansion | Pre-hydrated formats penetrate California beverage formulators eliminating guar and locust bean gum dependencies. |
| Direct Manufacturer Contracting | Preferred supplier relationships with German and French bakery groups displace distributor intermediation in Rotterdam logistics corridors. |
Methodological Framework
Document review covered EFSA novel food consultation records, EU organic regulation compliance databases, and juice industry byproduct utilization reports, complemented by interviews with ingredient procurement managers at German and French bakery groups, technical directors at Spanish citrus cooperatives, and regulatory affairs leads navigating REACH registration pathways. Secondary validation drew from customs trade data on citrus peel derivatives, SEC filings of diversified ingredient conglomerates, and ECHA registration timelines. Bottom-up demand modeling from end-use application volumes triangulated against top-down supply capacity estimates from Mediterranean and Brazilian processing corridors.
Segment-level value outputs reflect disaggregation across citrus variety, certification tier, application, and form factor dimensions, with growth trajectories derived from clean-label reformulation adoption curves and hydrocolloid substitution elasticity. Modeled inputs incorporated EU Green Deal procurement mandate implementation schedules, EFSA fiber content claim threshold evolution, and enzymatic extraction technology deployment rates across Spanish and Italian retrofit installations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EFSA novel food consultation timeline extensions or Mediterranean climate volatility affecting Spanish and Italian harvest yields. Projections assume sustained EU organic regulation enforcement and USDA organic certification arbitrage continuation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Native Starch Market
Ingredients
Stabilized Starch Market
Ingredients
Confectionery Ingredients Market
Ingredients
South America Fermented Ingredients Market
Ingredients
Global Autolyzed Yeast Extract Market
Ingredients
North America Dairy Protein Ingredients Market
Ingredients
Glucuronolactone Market
Ingredients
Feed Premix Market
Ingredients
Citrus Based Dietary Fibers Market
Ingredients
Peanut Flour Market
Ingredients
Encapsulated Salt Market
Ingredients
Desiccated Coconut Powder Market
Ingredients
Food Botanicals Market
Ingredients
Global Natural Gum Market
Ingredients
Cocoa Fiber Market
Ingredients
Rice Bran Fatty Alcohols Market