
 Waxy Maize Starch Market | 2026-2036
Waxy Maize Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Waxy Maize Starch Market Outlook
Modular ingredient bundling is restructuring how food manufacturers procure waxy maize starch, with buyers increasingly specifying pre-blended modified-native combinations rather than single-ingredient orders. Cargill leverages its captive corn supply and wet-milling infrastructure across the American Midwest to dominate bulk native starch contracts. Roquette Frères differentiates through specialty modified grades for pharmaceutical binding applications, while Ingredion Incorporated extends its formulation services downstream to capture value beyond commodity powder sales.
Waxy maize starch consists of nearly pure amylopectin derived from a specific maize mutant variety, containing less than one percent amylose compared to conventional corn starch's twenty-five percent; this molecular structure delivers exceptional freeze-thaw stability and clarity in gelled systems, making it indispensable for refrigerated sauces, puddings, and injectable drug carriers. Modified starch commands the deepest margin pools as food and pharmaceutical buyers pay premiums for cross-linked and stabilized grades that withstand extreme processing conditions, while native starch remains the high-volume workhorse in paper sizing and basic food thickeners where cost sensitivity limits formulation experimentation. Powder form leads all configurations due to its ease of dispersion and long shelf life, though granule and pellet formats are gaining traction in automated pharmaceutical tableting lines where flowability and dust control determine manufacturing efficiency.
The FDA governs food-grade starch through GRAS self-affirmation and food additive petitions, while the EPA regulates corn processing effluent under Clean Water Act permits that constrain mill expansion in water-stressed regions; the USDA's BioPreferred program additionally steers procurement toward domestically sourced biobased ingredients in federal contracts. Stakeholders must monitor how the EPA's evolving effluent limitation guidelines and state-level nutrient trading programs reshape the cost structure of wet-milling operations that supply this feedstock.
Market Dynamics
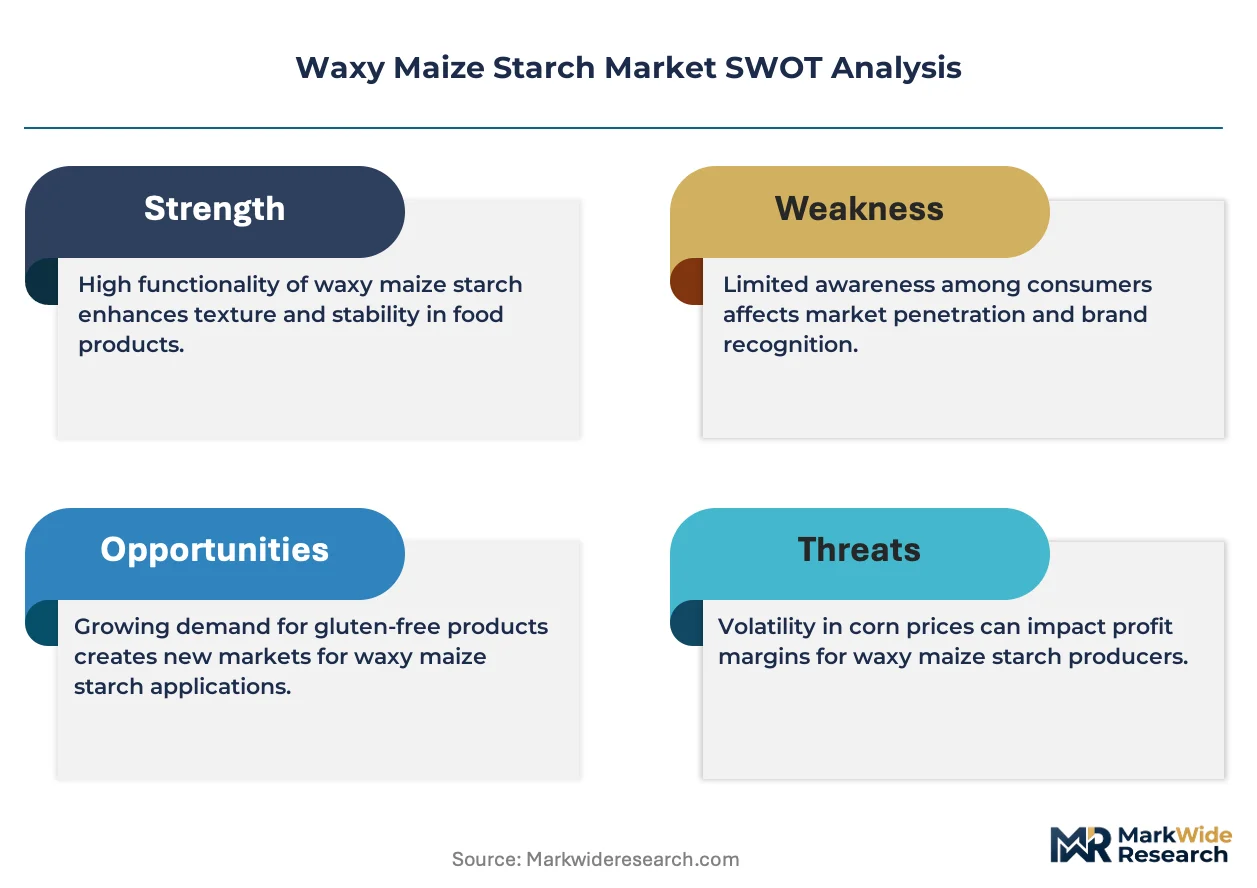
Clean-label ingredient mandates from the FDA and USDA are forcing food manufacturers to reformulate with recognizable starches, compressing demand cycles for waxy maize derivatives as buyers audit supply chains for genetically unmodified and minimally processed alternatives.
Growth Catalysts
- USDA BioPreferred program:Federal procurement mandates steer institutional foodservice contracts toward domestically sourced biobased thickeners, creating guaranteed offtake volumes for Midwest wet-millers.
- Injectable drug delivery:Pharmaceutical formulators specify cross-linked waxy maize for parenteral suspensions due to its pyrogen-free profile and amylopectin clarity, expanding the addressable market beyond oral dosage forms.
- Midwest corn processing clusters:Iowa and Illinois wet-milling infrastructure concentrates enzymatic modification capabilities, shortening lead times for modified starch grades versus imported alternatives.
Market Restraints
- Yellow dent corn price volatility:Feedstock costs swing with ethanol policy and weather patterns, compressing margins for native starch producers who cannot pass through input spikes in commoditized paper sizing markets.
- EPA effluent limitations:Clean Water Act permits constrain mill expansion in water-stressed Great Plains regions, capping capacity additions where groundwater access is already contested by agricultural irrigation.
- Tapioca starch substitution:Southeast Asian cassava processors offer amylopectin alternatives with non-GMO labeling advantages, displacing waxy maize in premium European clean-label applications.
Strategic Opportunities
- Cell-cultured meat scaffolding:Alternative protein startups require edible, thermoreversible gels for muscle fiber support, opening a novel high-value application segment for specialty modified grades.
- Indian pharmaceutical excipient demand:CDSCO's tightening of drug master file requirements for imported excipients creates entry paths for US-modified starch with pre-validated regulatory packages.
- Continuous enzymatic modification:Plug-flow reactor technology is converging with real-time viscosity monitoring to enable just-in-time specialty production, reducing working capital tied to inventory.
Industry Challenges
- GRAS self-affirmation documentation:FDA's escalating scrutiny of novel modification chemistries extends validation timelines for cross-linked variants, delaying commercialization by 18-24 months.
- Wet-milling process engineering expertise:Retiring cohorts of starch fractionation specialists constrain operational debottlenecking at legacy facilities in the Corn Belt.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waxy Maize Starch Market |
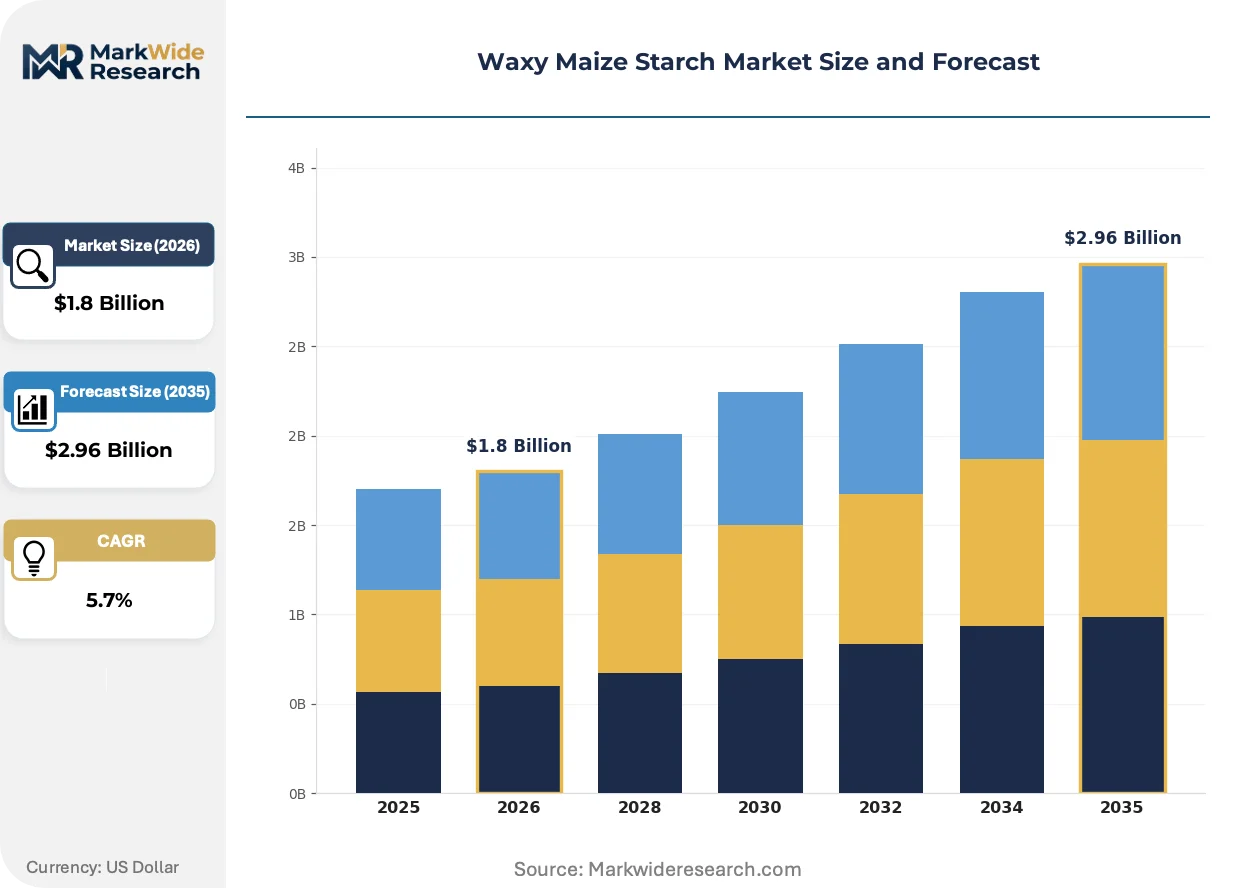
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Native Starch, Modified Starch, Blends, Organic Starch Application: Food & Beverage, Paper Products, Personal Care, Pharmaceuticals End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Firms, Industrial Users Form: Powder, Granule, Flake, Pellet |
| Companies Covered | Tate & Lyle, Grain Processing Corporation, Cargill, AGRANA, Emsland Group, Archer Daniels Midland Company, Roquette Frères, Tereos, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waxy Maize Starch Market Strategic Shifts
Enzymatic modification platforms and real-time rheology monitoring are compressing product development cycles, while regulatory disclosure requirements reshape how manufacturers validate and communicate starch functionality to downstream formulators.
Dual-modification protocols combining cross-linking with hydroxypropylation are converging with high-pressure processing lines in ready-meal manufacturing, enabling starches that withstand retort sterilization without syneresis. Food technologists at refrigerated sauce producers specify these hybrid grades to eliminate stabilizer blends. The structural consequence is margin compression for single-modification commodity suppliers who lack pilot-scale dual-reactor capacity.
REACH's updated requirements for polymer registration are forcing European importers to document starch modification chemistries in granular detail, shifting sourcing preference toward EU-based compounders with pre-filed dossiers. Industrial food buyers in Germany and France now audit supply chains for SVHC compliance. This regulatory friction most acutely affects Asian exporters who must establish EU legal entities to maintain market access.
Modular specification systems allow buyers to define viscosity curves and freeze-thaw cycles rather than purchasing by generic grade names, disintermediating traditional distributor technical service roles. Large contract manufacturers in the United States now contract directly with wet-millers for application-specific batches. This pattern concentrates procurement leverage among multi-site food processors with in-house rheology laboratories.
Waxy Maize Starch Market Segmentation
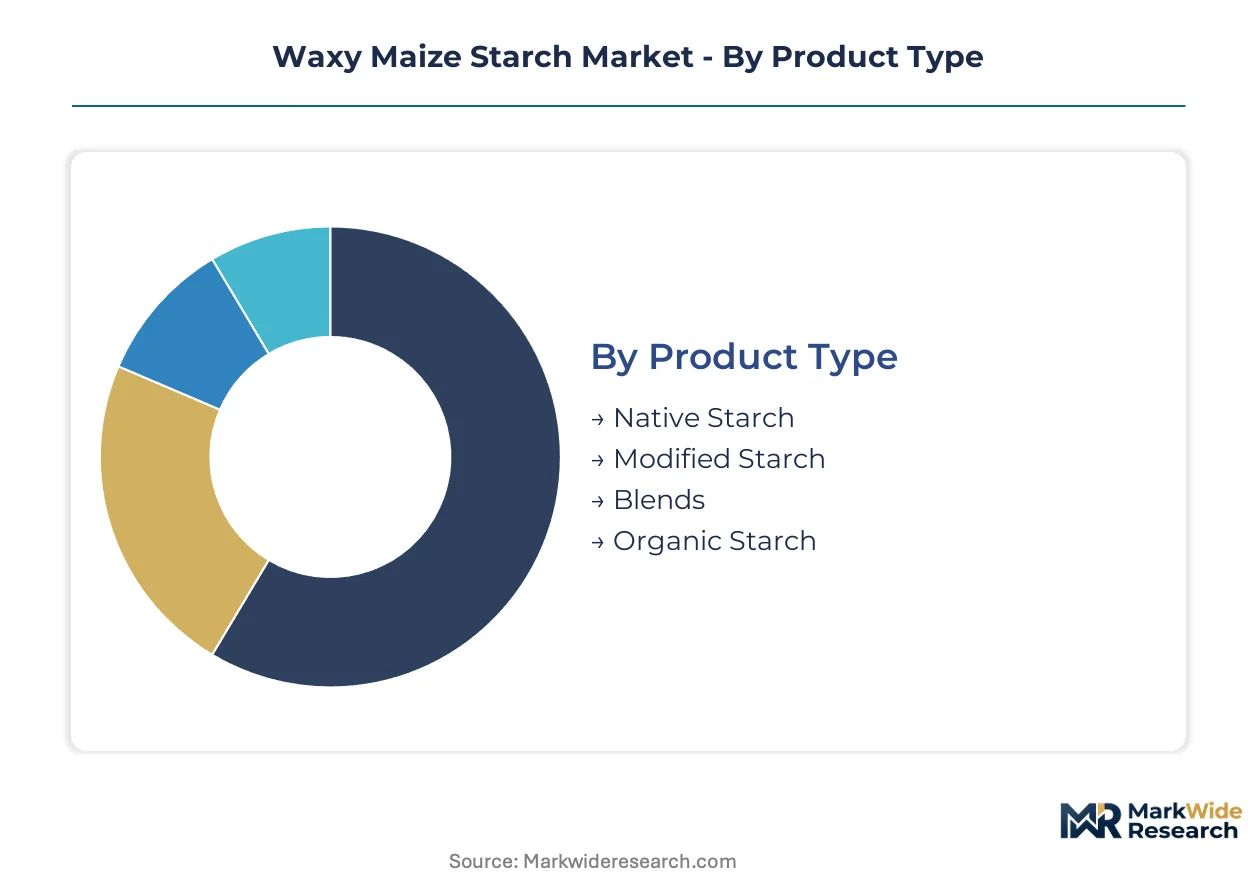
Waxy maize starch exhibits sharp performance gradients across product tiers, with modification chemistry and physical form determining margin capture in food versus pharmaceutical channels. Segment boundaries blur as buyers specify hybrid grades that combine native cost structures with modified functionality.
Product Type:
Volume concentrates in commodity native grades, while premium pools deepen around cross-linked and stabilized variants that withstand extreme processing.
- Modified Starch:Cross-linked and hydroxypropylated grades deliver freeze-thaw stability and clarity under retort conditions. Pharmaceutical formulators in parenteral suspension applications pay substantial premiums for pyrogen-free validated lots, while refrigerated sauce manufacturers specify hybrid modifications to eliminate stabilizer blends.
- Native Starch:Nearly pure amylopectin from waxy maize mutants offers basic thickening at commodity price points. Paper sizing mills in the American Midwest absorb high tonnage where cost sensitivity limits formulation experimentation, though margin compression intensifies during yellow dent corn price spikes.
- Blends:Pre-mixed modified-native combinations streamline procurement for mid-tier food processors lacking in-house formulation laboratories.
- Organic Starch:Certified non-GMO supply chains command positioning premiums in European clean-label applications where REACH documentation requirements favor traceable sourcing.
Today's leader: Modified Starch. Tomorrow's challenger: Organic Starch.
Application:
End-use concentration tracks regulatory intensity, with FDA-scrutinized pharmaceutical channels generating the steepest margin premiums.
- Food & Beverage:Clean-label mandates from the FDA and USDA compress demand cycles as manufacturers audit supply chains for minimally processed alternatives. Dual-modification protocols enable retort-stable refrigerated sauces without syneresis.
- Pharmaceuticals:Injectable drug delivery specifications favor cross-linked waxy maize for parenteral suspensions. CDSCO's tightening of drug master file requirements for imported excipients creates entry paths for US-modified starch with pre-validated regulatory packages.
- Paper Products:Commodity sizing applications absorb native starch volume where feedstock cost pass-through remains constrained.
- Personal Care:Cosmetic formulators leverage amylopectin clarity in transparent gel systems, though volumes trail food and pharmaceutical channels.
Pharmaceuticals captures the steepest expansion trajectory as parenteral applications multiply.
End User:
Procurement sophistication diverges sharply between specification-driven pharmaceutical firms and price-sensitive industrial buyers.
- Food Manufacturers:Large contract manufacturers with in-house rheology laboratories now contract directly with wet-millers for application-specific batches, disintermediating traditional distributor technical service roles.
- Pharmaceutical Firms:Formulation scientists demand documented pyrogen-free profiles and validated modification chemistries, extending validation timelines but locking in supplier relationships.
- Cosmetic Companies:Mid-tier personal care brands prioritize sensory performance in transparent gel systems over cost minimization.
- Industrial Users:Paper mills and basic thickeners absorb native starch volume with limited specification complexity.
Direct procurement concentrates among Food Manufacturers; Pharmaceutical Firms deepen supplier integration.
Form:
Physical configuration determines manufacturing efficiency in automated processing lines versus traditional batch operations.
- Powder:Dominates due to ease of dispersion and extended shelf stability. Bulk handling infrastructure across Midwest wet-milling clusters reinforces cost advantages.
- Pellet:Gaining traction in automated pharmaceutical tableting lines where flowability and dust control determine manufacturing efficiency.
- Granule:Intermediate flow properties serve specialty food applications requiring controlled hydration kinetics.
- Flake:Limited adoption in instant dissolution applications where rapid dispersion outweighs handling convenience.
Powder maintains volume dominance; Pellet expands fastest in pharmaceutical automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial wet-milling for waxy maize starch originated in the American Corn Belt during the mid-twentieth century, establishing Iowa and Illinois as the foundational production geography. Today, capacity clusters persist where corn supply density intersects with fractionation expertise, though regulatory divergence and end-use specialization are redistributing value capture across national boundaries.
United States
Midwestern wet-millers in Cedar Rapids and Decatur command enzymatic modification infrastructure that shortens lead times for cross-linked pharmaceutical grades. The USDA BioPreferred program steers federal foodservice contracts toward domestically sourced biobased thickeners, locking in offtake volumes. Iowa's corn processing corridor concentrates native starch output for paper sizing mills where feedstock cost pass-through remains contested.
China
Domestic pharmaceutical formulators are expanding parenteral suspension applications that specify amylopectin clarity, driving import substitution efforts for modified starch. The National Medical Products Administration tightens drug master file documentation for excipient sourcing, favoring suppliers with pre-validated regulatory packages. Shandong Province's starch derivative clusters are scaling continuous enzymatic modification reactors to capture specialty margin pools.
Germany
REACH's updated polymer registration requirements force importers to document modification chemistries in granular detail, shifting preference toward EU-based compounders with pre-filed dossiers. ECHA's scrutiny of novel cross-linking agents extends validation timelines for hybrid grades. The Cologne-Düsseldorf industrial corridor hosts formulation service providers that bundle modified-native starch combinations for mid-tier food processors.
India
CDSCO's tightening of drug master file requirements for imported excipients creates entry paths for US-modified starch with validated regulatory packages. Domestic pharmaceutical contract manufacturers in Hyderabad and Ahmedabad are auditing supply chains for pyrogen-free amylopectin sources. Maharashtra's food processing belt is adopting pre-blended modified-native combinations to streamline clean-label reformulation.
Brazil
São Paulo-based food manufacturers are substituting tapioca starch for waxy maize in premium clean-label applications where non-GMO positioning commands retail premiums. ANVISA's alignment with international pharmaceutical excipient standards is accelerating validation requirements for imported modified grades. The Campinas research corridor is piloting cell-cultured meat scaffolding applications that require thermoreversible gel functionality.
Waxy Maize Starch Market Competitive Environment
Premium-margin players sit above commodity-margin players across modification complexity and regulatory validation depth. The structure consolidates around three to five integrated wet-millers with captive corn supply, while specialty compounders occupy niche positions in pharmaceutical and clean-label channels. Strategic archetypes include Midwest-anchored bulk native producers, European-modified grade specialists, and formulation-service integrators. Competitive moves concentrate on backward integration into seed genetics and downstream partnership structures with pharmaceutical contract manufacturers.
Within the integrated agribusiness tier, Cargill and Archer Daniels Midland Company occupy positions defined by captive corn supply and wet-milling infrastructure density across the American Midwest. Tate & Lyle exemplifies the specialty-modified archetype through its positioning in cross-linked and stabilized grades for pharmaceutical and food applications. Roquette Frères anchors the European compounder segment, representing the regulatory dossier capability that REACH compliance demands. These three entities collectively illustrate how geographic origin and corporate structure map onto margin-tier positioning in a market where enzymatic modification expertise and validation documentation determine procurement decisions.
| Leading Market Players |
|---|
| Tate & Lyle |
| Grain Processing Corporation |
| Cargill |
| AGRANA |
| Emsland Group |
| Archer Daniels Midland Company |
| Roquette Frères |
| Tereos |
| Ingredion Incorporated |
| Others |
Value Chain & Pricing Dynamics
Family-owned Midwest wet-millers anchor supply discipline through captive corn supply and multi-generational processing expertise, translating into pricing power that resists commodity volatility in pharmaceutical-grade contracts while ceding ground to Asian tapioca processors in clean-label food segments.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, food-modified, and industrial-native levels stratifies margin capture by certification intensity and modification complexity. Price differentiation hinges on FDA pyrogen-free validation and REACH dossier completeness. Cost compression in commodity native grades intensifies because yellow dent corn price swings outpace pass-through capacity. Paper sizing mills exhibit highest price sensitivity; pharmaceutical formulators show least.
Supply Chain Analysis
Pharmaceutical-grade qualification gating through FDA GRAS self-affirmation and CDSCO drug master file requirements restricts viable supplier pools. Production concentrates in the United States, China, and Germany where enzymatic modification infrastructure clusters. Feedstock draws from Iowa and Illinois corn belts, Shandong cassava processors, and European compounder networks. Single-source vulnerability sits with Midwest wet-milling concentration for cross-linked grades. Distribution runs through direct miller-to-manufacturer contracts disintermediating traditional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA tightening of ingredient disclosure requirements and REACH polymer registration mandates compound demand for validated, traceable supply chains.
For Market Incumbents: Hedge against tapioca starch substitution by securing non-GMO certification pipelines and backward integration into identity-preserved corn seed genetics. Prioritize pyrogen-free validation investment to lock pharmaceutical contracts against emerging Asian compounders. For New Entrants and Emerging Players: Capture white space in Indian pharmaceutical excipient channels where CDSCO documentation gaps disadvantage established importers. Target cell-cultured meat scaffolding applications requiring thermoreversible gel functionality. Lead with formulation service bundling rather than commodity powder sales. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier modified starch compounders lacking dual-modification reactor capacity but holding REACH pre-filed dossiers. Long-term viability centers on enzymatic modification IP and regulatory validation depth rather than feedstock scale. Watch EPA effluent limitation enforcement in Great Plains states as inflection signal for capacity-constrained pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Modification Capacity Expansion | Enables hybrid cross-linked hydroxypropylated grades for retort-stable refrigerated sauces. |
| Pharmaceutical Validation Investment | Secures pyrogen-free certification for parenteral suspension applications under FDA scrutiny. |
| Identity-Preserved Corn Supply Agreement | Locks non-GMO feedstock traceability for European clean-label compliance under REACH. |
| Continuous Enzymatic Modification Licensing | Reduces working capital through plug-flow reactor technology with real-time viscosity monitoring. |
| Formulation Service Partnership | Captures downstream value through direct technical collaboration with multi-site food processors. |
Study Parameters
Direct dialogue with wet-milling operations managers, pharmaceutical formulation scientists, food manufacturer procurement leads, and regulatory affairs directors grounded qualitative findings. Secondary validation drew from FDA GRAS notices, EPA Clean Water Act permit databases, ECHA REACH dossiers, and USDA BioPreferred program records. Bottom-up capacity modeling triangulated against top-down demand segmentation across modification grades and end-use channels.
Segmented outputs across native, modified, and organic product tiers by food, pharmaceutical, paper, and personal care applications tracked volume and value trajectories across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating corn price volatility, regulatory validation timelines, and substitution dynamics from tapioca and potato starch alternatives. Modeled inputs included enzymatic modification capacity utilization, pyrogen-free certification throughput, and clean-label reformulation intensity.
EPA effluent guideline revision, CDSCO excipient documentation tightening, and cell-cultured meat commercialization scale-up are the dominant revision risks to baseline assumptions. A model refresh is warranted upon material change in pharmaceutical validation timeline enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Cocoa Beans Market
Ingredients
Desiccated Coconut Powder Market
Ingredients
Prenatal Vitamin Ingredients Market
Ingredients
Global Dairy Protein Ingredients Market
Ingredients
Global Malt Ingredients Market
Ingredients
Non-GMO Soya Market
Ingredients
Global Whey Protein Ingredients Market
Ingredients
Corn Oil Market
Ingredients
Pulses Ingredients Market
Ingredients
Organic Starch Market
Ingredients
Horehound Extract Market
Ingredients
Soy Derivatives Market
Ingredients
Egg Albumin Protein Market
Ingredients
Vegetable Extract Market
Ingredients
Mediterranean Marine Ingredients for Pet Health Market
Ingredients
Yeast Flakes Market