
 Mustard Flour Market | 2026-2036
Mustard Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Mustard Flour Market Insights
Canadian prairie milling capacity is decoupling from traditional commodity mustard channels as specialty flour grades command premium placement. McCormick & Company leverages its spice blending infrastructure to secure long-term supply contracts with mustard processors. G.S. Dunn Dry Mustard Millers anchors its position through proprietary stone-milling techniques that preserve volatile oil content. Cargill competes by integrating backward into Canadian and Ukrainian seed origination networks.
Mustard flour consists of finely ground Brassica juncea or Sinapis alba seeds, typically containing 25-35% protein and 25-30% fixed oil with allyl isothiocyanate providing pungency; manufacturers temper seeds to control enzymatic activity before grinding to preserve functional heat and emulsification properties for condiment and prepared food applications. Yellow mustard flour dominates volume in North American sauce production, where its milder heat profile suits mass-market yellow mustard formulations. Brown mustard flour leads growth in Asian food service channels, where higher allyl isothiocyanate content delivers the sharp pungency expected in regional condiments. Black mustard flour occupies niche positions in Ayurvedic nutraceutical applications, where traditional medicine protocols specify B. nigra sourcing.
The FDA governs mustard flour as a Generally Recognized As Safe food ingredient under 21 CFR, while the USDA National Organic Program certifies organic production chains that supply premium retail and natural food channels. India's FSSAI enforces pesticide residue limits on imported and domestic mustard seed that directly determine export eligibility for flour mills. Stakeholders must monitor evolving EU MRL harmonization proposals and India's PLI scheme expansion into food processing infrastructure, as these will reshape competitive access to the fastest-growing demand corridors.
Market Dynamics
Clean-label sauce production in the United States is compressing supply chains toward single-origin, traceable mustard flour grades, forcing mills to segregate processing lines and certify enzymatic preservation protocols that mass-market channels previously ignored.
Growth Catalysts
- Clean-label mandates:FDA labeling transparency requirements for prepared foods are pulling natural emulsifier demand toward mustard flour as egg yolk replacement in mayonnaise and dressing formulations.
- India:The FSSAI's pesticide residue enforcement is professionalizing seed sourcing networks, enabling export-grade flour mills to capture premium placement in European condiment manufacturing.
- Allyl isothiocyanate stabilization:Advanced tempering technologies are extending functional shelf life, unlocking Asian food service channel expansion for high-pungency brown mustard flour grades.
Market Restraints
- Seed concentration:Canadian prairie origination dominance creates weather-driven input volatility that specialty flour mills cannot hedge through futures markets.
- REACH compliance:The European Union's food-contact material framework imposes migration testing costs that exclude smaller Indian processors from direct EU supply contracts.
- Enzyme deactivation:Heat treatment precision requirements limit small-batch artisan production scalability, capping premium segment supply response.
Strategic Opportunities
- Ayurvedic nutraceuticals:Black mustard flour demand for traditional medicine protocols in India and diaspora markets remains undersupplied by certified organic channels.
- PLI scheme expansion:India's production-linked incentive infrastructure investments into food processing clusters will reduce logistics costs for export-oriented flour mills.
- Direct-to-manufacturer platforms:Digital procurement networks are disintermediating traditional spice trading houses, enabling condiment manufacturers to specify exact pungency profiles.
Industry Challenges
- Volatile oil analysis capability:Gas chromatography expertise for allyl isothiocyanate quantification is concentrated in third-party labs, creating certification bottlenecks for new mill entrants.
- Organic transition timelines:USDA National Organic Program certification requires three-year field history documentation that locks prospective suppliers into extended conversion investments.
- Stone-mill maintenance:Proprietary grinding equipment for heat-sensitive processing demands specialized mechanical knowledge that vocational training programs rarely address.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mustard Flour Market |
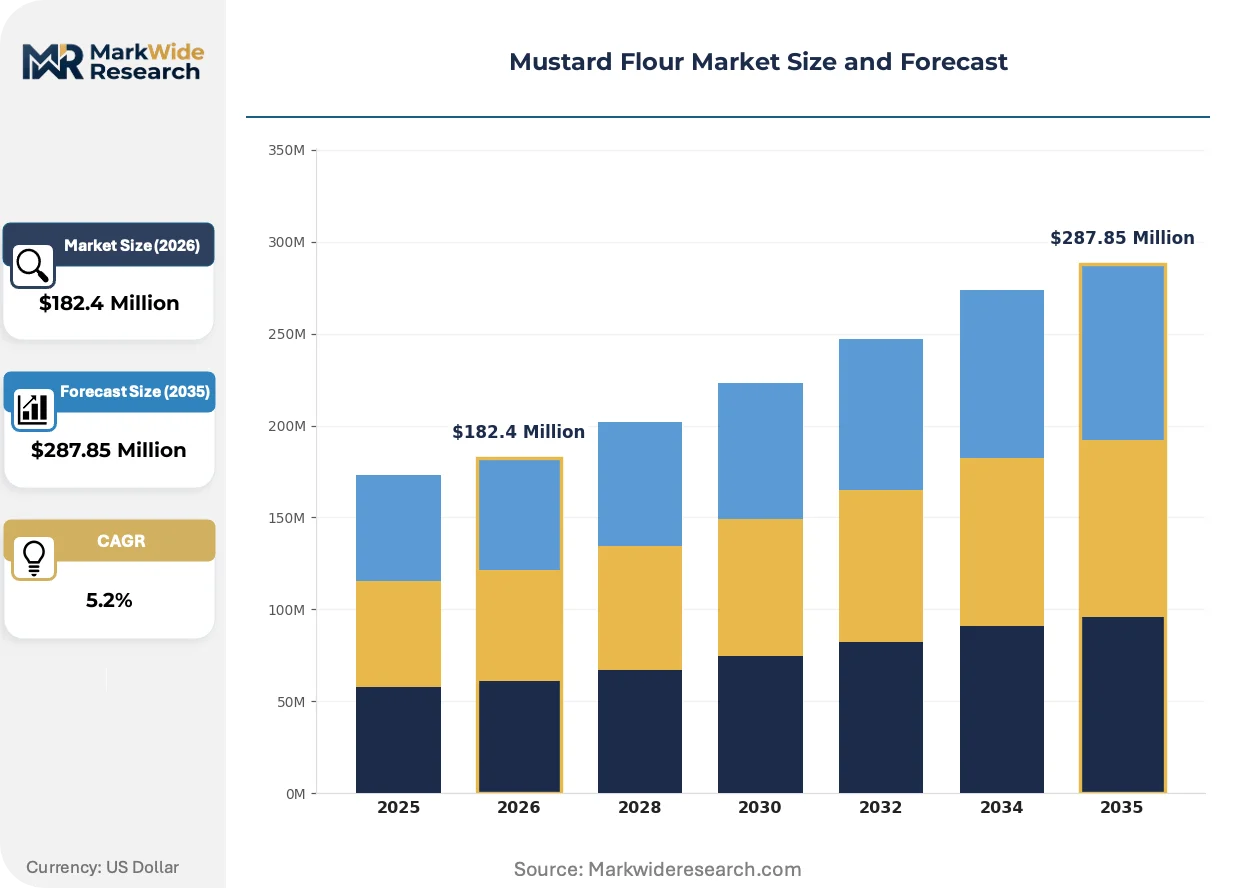
| Market Size in 2026 | $182.4 Million |
| Market Size in 2035 | $287.85 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yellow Mustard Flour, Brown Mustard Flour, Black Mustard Flour, Whole Mustard Flour End User: Food Industry, Food Service, Retail, Nutraceuticals Packaging Type: Bags, Tubs, Bulk Containers, Sachets Application: Food Additive, Culinary Uses, Sauce Production, Spices |
| Companies Covered | McCormick & Company, Cargill, Unilever, G.S. Dunn Dry Mustard Millers, Olam International, Archer Daniels Midland Company, Kraft Heinz Company, Bunge Limited, Ddev Spices Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mustard Flour Market Trends and Innovations
Processing technology and regulatory precision are converging to fragment the mustard flour market into grade-specific supply channels that reward enzymatic preservation expertise over commodity scale.
Near-infrared spectroscopy for real-time allyl isothiocyanate content verification is electrifying quality control protocols at receiving docks. Large condiment manufacturers are deploying these systems to reject out-of-specification flour batches before they enter production, compressing tolerance for blending-based standardization and forcing upstream mills to tighten process control investments.
REACH framework amendments on food-contact material migration limits are tightening documentary requirements for mustard flour packaging. European sauce producers are now demanding complete supply chain substance declarations, and Indian export mills are responding by segregating storage and transport assets to prevent cross-contamination with non-compliant materials.
Specification-driven procurement contracts are displacing spot-market purchasing in North American sauce manufacturing. Procurement teams at major condiment brands are locking multi-year supply agreements with defined pungency ranges and enzymatic activity floors, and this pattern is most visible in Midwestern production facilities where just-in-time inventory systems cannot accommodate flour variability.
Mustard Flour Market Segmentation
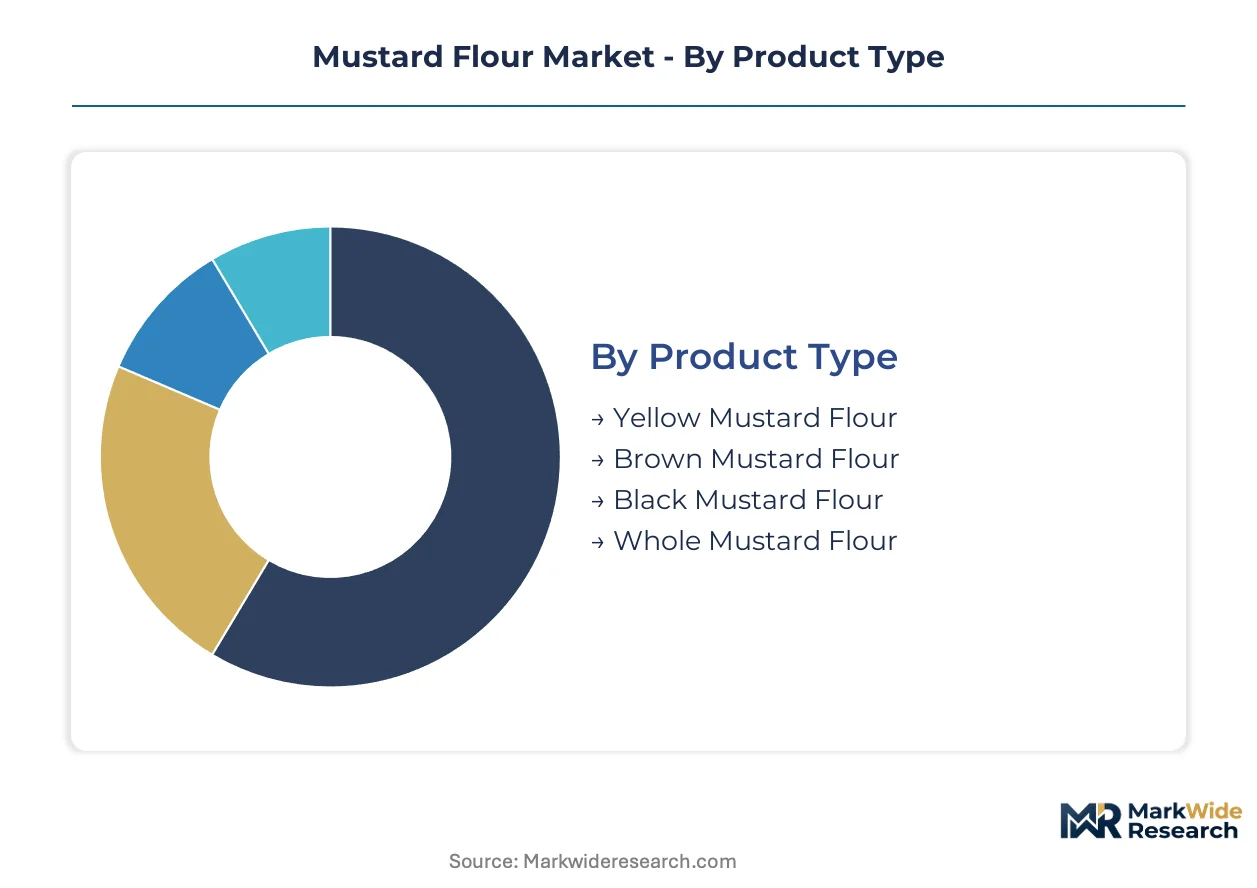
Mustard flour segmentation reflects divergent processing requirements across condiment manufacturing, food service, and nutraceutical channels. Specification precision determines pricing tiers and supply chain access.
Product Type:
Customization intensity spans from standardized commodity grades to enzyme-preserved specialty flours with certified volatile oil content.
- Yellow Mustard Flour:Derived from Sinapis alba seeds with 25-30% fixed oil and mild allyl isothiocyanate pungency. North American sauce manufacturers specify this grade for mass-market yellow mustard formulations where heat tolerance and emulsification stability matter. FDA GRAS status under 21 CFR enables broad food additive deployment without premarket approval.
- Brown Mustard Flour:Ground from Brassica juncea seeds delivering sharper pungency through higher glucosinolate conversion. Asian food service channels in India and diaspora markets drive specification contracts for this grade, where tempering technology investments now extend functional shelf life for export logistics.
- Black Mustard Flour:Traditional Ayurvedic protocols specify B. nigra sourcing for medicinal applications. Certified organic channels remain undersupplied relative to nutraceutical demand in India.
- Whole Mustard Flour:Coarse grind retains seed hull fiber and complete protein fraction. Artisan condiment producers and clean-label sauce startups specify this grade for visual texture differentiation.
Most installed capacity flows through Yellow Mustard Flour. Expansion is steepest in Brown Mustard Flour.
End User:
Customer sophistication tiers separate specification-driven procurement from price-sensitive spot purchasing.
- Food Industry:Condiment manufacturers and prepared food processors dominate volume through multi-year supply agreements with defined pungency ranges. McCormick and Cargill procurement teams enforce near-infrared spectroscopy verification at receiving docks, rejecting out-of-specification batches before production entry.
- Food Service:Regional restaurant chains and institutional caterers purchase through distributor networks with limited traceability requirements. Indian food service channels show fastest specification upgrading as FSSAI enforcement professionalizes sourcing.
- Retail:Grocery and natural food channels split between private-label commodity grades and certified organic premium positioning. USDA National Organic Program certification commands three-year field history documentation that locks suppliers into extended conversion timelines.
- Nutraceuticals:Ayurvedic medicine manufacturers and dietary supplement formulators source black mustard flour through specialized organic channels with traditional medicine protocol compliance.
Food Industry captures the dominant revenue share. Nutraceuticals is gaining share fastest.
Packaging Type:
Logistics economics and contamination risk shape format selection across supply chain stages.
- Bags:Multi-wall paper or woven polypropylene dominates mid-volume food manufacturing procurement. REACH framework amendments on food-contact material migration limits now require complete substance declarations for European sauce producer contracts.
- Tubs:Rigid plastic containers serve retail and food service segments requiring repeated access and moisture protection. Indian export mills are segregating storage assets to prevent cross-contamination with non-compliant materials.
- Bulk Containers:Tote bins and flexible intermediate bulk containers enable just-in-time inventory systems at Midwestern condiment production facilities. Specification-driven contracts are displacing spot-market purchasing in this format.
- Sachets:Single-serve portions target food service condiment packets and airline catering. Unit economics limit adoption outside high-volume institutional channels.
Most throughput moves through Bulk Containers. Sachets is climbing the fastest.
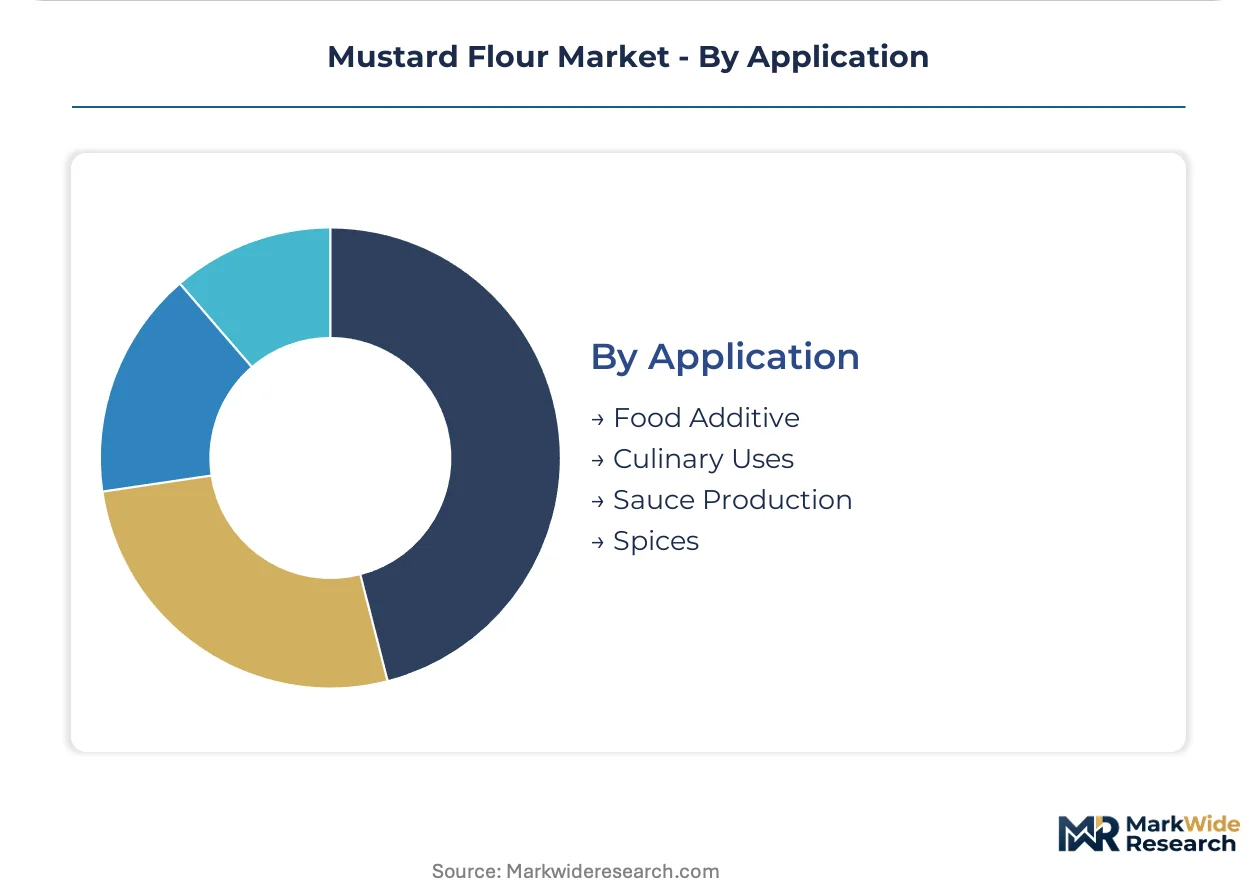
Application:
Functional requirements separate emulsifier-grade specifications from flavoring and coloring uses.
- Food Additive:Mustard flour functions as natural emulsifier and stabilizer in mayonnaise and dressing formulations. FDA labeling transparency requirements are pulling demand toward egg yolk replacement applications.
- Culinary Uses:Direct cooking applications in Indian, Chinese, and European traditional recipes. Regional pungency preferences drive brown versus yellow grade selection.
- Sauce Production:Clean-label mandates in United States sauce manufacturing are compressing supply chains toward single-origin, traceable grades. Stone-milling techniques that preserve volatile oil content command premium placement.
- Spices:Blending into curry powders and seasoning mixes. Indian mustard seed processing clusters supply domestic spice brands with commodity-grade flour.
Most volume converts through Sauce Production. Food Additive is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping mustard flour production geography as REACH compliance costs in Europe push smaller processors toward Indian clusters where FSSAI enforcement creates dual-tier export eligibility.
United States
Clean-label sauce mandates from FDA labeling transparency requirements are compressing supply chains toward single-origin, traceable grades. Midwestern condiment production facilities now enforce near-infrared spectroscopy verification at receiving docks. Chicago-area milling infrastructure anchors specification-driven procurement contracts that displace spot-market purchasing.
Canada
Prairie origination dominance in Saskatchewan and Alberta creates weather-driven input volatility that specialty flour mills struggle to hedge. USDA National Organic Program certification requirements lock prairie processors into three-year field history documentation for premium retail channels. Winnipeg-based storage and transport assets are segregating to prevent cross-contamination with non-compliant materials.
India
FSSAI pesticide residue enforcement is professionalizing seed sourcing networks in Rajasthan and Gujarat processing clusters. The PLI scheme expansion into food processing infrastructure will reduce logistics costs for export-oriented flour mills in these states. Mumbai and Delhi-NCR supply domestic spice brands while capturing premium placement in European condiment manufacturing.
Germany
REACH framework amendments on food-contact material migration limits impose documentary requirements that exclude smaller Indian processors from direct EU supply contracts. Stone-milling techniques for volatile oil preservation command premium placement among artisan condiment producers in Bavaria. Frankfurt-area sauce manufacturers are locking multi-year supply agreements with defined pungency ranges.
United Kingdom
Post-BREXIT regulatory divergence from EU MRL harmonization proposals creates uncertainty for mustard flour import specifications. London-based natural food channels split between private-label commodity grades and certified organic premium positioning. Midlands distribution networks are upgrading traceability systems to meet evolving documentary requirements.
Mustard Flour Market Competitive Landscape
Canadian prairie producers anchor the upstream origination tier; Indian processing specialists hold the export-grade manufacturing tier. The vendor base splits between integrated agricultural conglomerates and dedicated mustard millers with proprietary tempering capabilities. Three archetypes dominate: seed-origin controllers, enzymatic preservation specialists, and spice-blending integrators. Competitive moves concentrate on backward integration into origination networks and multi-year supply contract capture.
Among North American spice-blending integrators, McCormick & Company and Kraft Heinz Company exemplify the procurement-scale archetype that leverages existing infrastructure to secure long-term supply contracts. Cargill represents the agricultural-commodity conglomerate model with captive origination networks spanning Canadian and Ukrainian seed sources. G.S. Dunn Dry Mustard Millers occupies the specialist-miller position where proprietary processing techniques anchor premium-tier positioning.
| Leading Market Players |
|---|
| McCormick & Company |
| Cargill |
| Unilever |
| G.S. Dunn Dry Mustard Millers |
| Olam International |
| Archer Daniels Midland Company |
| Kraft Heinz Company |
| Bunge Limited |
| Ddev Spices Private Limited |
| Others |
Pricing and Supply Chain Analysis
Family-owned stone-milling specialists in Canada and India anchor premium-tier pricing discipline through proprietary tempering technologies that commodity-scale competitors cannot replicate, while private-equity-rolled-up spice processors in the United States compress distributor margins through direct-to-manufacturer procurement platforms. This ownership fragmentation creates divergent supply behaviors: heritage mills defend enzymatic preservation premiums while integrated conglomerates leverage captive origination networks to standardize contract pricing.
Pricing Analysis
Distributor margins in European condiment manufacturing absorb REACH compliance testing costs that exclude smaller Indian processors from direct supply contracts. Three-tier pricing structure across premium, standard, and economy levels stratifies by volatile oil certification and organic accreditation under USDA National Organic Program standards. Price differentiation hinges on near-infrared spectroscopy verification capability, with FDA labeling transparency requirements intensifying cost compression in mass-market yellow mustard flour tiers. Food service channels in India exhibit highest price sensitivity; Ayurvedic nutraceutical buyers demonstrate lowest sensitivity due to protocol-mandated B. nigra sourcing requirements.
Supply Chain Analysis
Mustard seed supply rests on Canadian prairie origination in Saskatchewan and Alberta, Indian processing clusters in Rajasthan and Gujarat, and Ukrainian export corridors disrupted by geopolitical volatility. Raw material dependencies include Brassica juncea and Sinapis alba seed stocks, gas chromatography certification capacity for allyl isothiocyanate quantification, and segregated storage assets compliant with EU food-contact material frameworks. Single-source vulnerability concentrates in Canadian weather-driven input volatility that specialty mills cannot hedge through futures markets. Distribution runs through Midwestern condiment production facilities employing just-in-time inventory systems, Mumbai and Delhi-NCR domestic spice brand networks, and Frankfurt-area sauce manufacturer direct contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where FSSAI pesticide residue enforcement costs in India remain substantially below REACH migration testing investments required for direct European supply access.
For Market Incumbents: Acquire gas chromatography certification capabilities to eliminate third-party lab bottlenecks that constrain new mill entrants. Secure long-term supply contracts with defined pungency ranges before PLI scheme infrastructure investments flood Indian export corridors with additional capacity. Near-infrared spectroscopy deployment at receiving docks represents the critical defensive lever against specification variability. For New Entrants and Emerging Players: Premium-to-economy price-point gaps in certified organic black mustard flour create immediate white-space opportunity given undersupply relative to Ayurvedic nutraceutical demand. Target Rajasthan and Gujarat processing clusters where PLI scheme logistics cost reductions will compress export timelines. Digital procurement platform integration offers the most penetrable go-to-market angle for disintermediating traditional spice trading houses. For Investors and Strategic Acquirers: Valuations sit cheapest among Indian export-grade mills with FSSAI-compliant sourcing networks and nascent European contract pipelines. Long-term viability across the analysis window favors processors with backward integration into seed origination and proprietary tempering technology portfolios. Watch EU MRL harmonization proposals as the inflection signal that will reshape competitive access to premium condiment manufacturing channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Origination | Cargill's Ukrainian and Canadian networks demonstrate captive supply advantages against spot-market volatility. |
| Proprietary Tempering Technology Investment | G.S. Dunn's stone-milling techniques preserve volatile oil content that commands premium placement in clean-label channels. |
| Near-Infrared Spectroscopy Deployment | McCormick's receiving dock verification systems reject out-of-specification batches before production entry. |
| PLI Scheme Infrastructure Capture | Rajasthan and Gujarat mills will reduce logistics costs for export-oriented production serving European sauce manufacturers. |
| Organic Certification Pipeline Development | USDA National Organic Program three-year field history documentation locks suppliers into extended conversion investments that barrier late entrants. |
Research Methodology
Bottom-up condiment manufacturer and food service channel modeling reconciled against top-down mustard seed origination and milling capacity tracking forms the analytical core of this study. Primary interviews with procurement directors at major sauce brands, FSSAI compliance officers at Indian export mills, stone-milling equipment specialists, and Ayurvedic medicine formulators combined with secondary validation from FDA GRAS filings, USDA National Organic Program certification databases, EU REACH substance declarations, and Indian customs export records. Triangulation across these sources ensures segment-level volume and value estimates reflect actual procurement contract structures rather than theoretical demand projections.
Historical trendline analysis of pungency specification premiums, organic accreditation price differentials, and regional logistics cost structures informed the projection framework. Segmentation dimensions modeled include product type, end-user sophistication tier, packaging format, and application function across the analysis window. CAGRs derive from fitted growth curves adjusted for PLI scheme infrastructure investment timelines and EU MRL harmonization proposal trajectories. Industry-specific forecast inputs encompass allyl isothiocyanate stabilization technology adoption rates and clean-label sauce formulation substitution elasticities for egg yolk emulsifiers.
Caveats apply where FSSAI enforcement intensity, REACH framework amendment finalization, or Canadian prairie weather volatility could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory implementation schedules and seed origination yield stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Bean Ingredients Market
Ingredients
Buckwheat–Mediterranean Grain Blend Ingredients Market
Ingredients
Colombia Food Ingredients Market
Ingredients
L-Arabinose Market
Ingredients
White Mulberry Leaves Extract Market
Ingredients
Mastic Gum Market
Ingredients
Cheese Ripening Enzymes Market
Ingredients
Rendered Products Market
Ingredients
Animal and Marine Fats and Oils Market
Ingredients
Asia-Pacific Plant Protein Ingredients Market
Ingredients
Vegetable Concentrates Market
Ingredients
North America Corn Starch Market
Ingredients
North America Soy Protein Market
Ingredients
Global Egg Yolk Oil Market
Ingredients
Bovine Gelatin Market
Ingredients
Sea Buckthorn Berry Extract Market