
 Vegetable Glycerin Market | 2026-2036
Vegetable Glycerin Market Size, Share, and Industry Trends Forecast 2026-2036
Vegetable Glycerin Market Outlook
The EU Green Deal is rebalancing vegetable glycerin procurement toward certified-sustainable palm and soybean feedstocks. Cargill, Incorporated leverages its integrated oilseed crush and refining footprint to secure feedstock traceability from farm to glycerin. BASF sustains technical leadership in high-purity pharmaceutical-grade output through continuous saponification process upgrades. Wilmar International anchors Asia-Pacific supply with backward integration into Indonesian palm plantations and port-adjacent refining assets.
Vegetable glycerin is a colorless, odorless, viscous polyol compound with the chemical formula C3H8O3, typically containing minimum 99.5% glycerol content for USP-grade material, produced via hydrolysis, saponification, or transesterification of triglyceride feedstocks. It functions primarily as a humectant, solvent, and bodying agent across food, pharmaceutical, and cosmetic formulations. Pharmaceutical-grade glycerin commands the strongest margin pool due to stringent USP and EP monograph compliance, while cosmetic-grade output is expanding fastest as K-beauty and clean-label skincare brands reformulate away from petrochemical alternatives. Food-grade volumes remain mature in developed markets but find new outlets in sugar-reduced confectionery and plant-based meat systems.
The US FDA enforces food-additive and excipient purity standards under 21 CFR, while the EPA monitors glycerin-derived biodiesel co-product pathways under the Renewable Fuel Standard. Europe's ECHA administers REACH registration for glycerin imports, and the EU F-Gas Regulation indirectly shapes demand by pressuring refrigerant glycerin alternatives. Stakeholders must monitor feedstock certification schemes and regulatory divergence between pharmacopeia standards to avoid compliance-driven supply disruptions.
Market Dynamics
Feedstock certification mandates and pharmacopeia purity convergence are restructuring procurement priorities across the vegetable glycerin value chain. Buyers now require chain-of-custody documentation from plantation to refined product.
Growth Catalysts
- REACH registration tiers:ECHA's substance evaluation protocols are compelling importers to upgrade purification infrastructure, expanding addressable market for EP-grade material.
- Clean-label cosmetics:K-beauty and indie skincare formulators are substituting petrochemical humectants with vegetable-derived alternatives in waterless balm and serum categories.
- Palm oil traceability:Malaysian and Indonesian refineries achieving RSPO and ISCC certification are securing preferred-supplier status with multinational consumer goods houses.
Market Restraints
- Crude glycerin price volatility:Biodiesel co-product oversupply fluctuations in Argentina and Brazil destabilize refined product input costs.
- Feedstock concentration:Southeast Asian palm oil dominance creates single-origin exposure for buyers seeking supply resilience.
- USP-EP monograph divergence:Differing heavy metals and chloride thresholds between pharmacopeias force dual-certification overhead for pharmaceutical suppliers.
Strategic Opportunities
- Indian pharmaceutical excipient demand:CDSCO's tightening import quality surveillance is creating opening for domestic USP-grade production capacity.
- Cell-cultured meat media:Alternative protein startups require pharmaceutical-grade glycerin as cryoprotectant and nutrient carrier in serum-free formulations.
- EU Green Deal procurement rules:Public-sector tender specifications now preference certified-sustainable feedstocks, advantaging early certifiers.
Industry Challenges
- Continuous process engineering talent:Saponification and thin-film evaporation expertise resides with aging specialist workforces in European and Japanese refineries.
- Multi-pharmacopeia compliance timelines:Simultaneous USP, EP, and JP filing requirements extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegetable Glycerin Market |
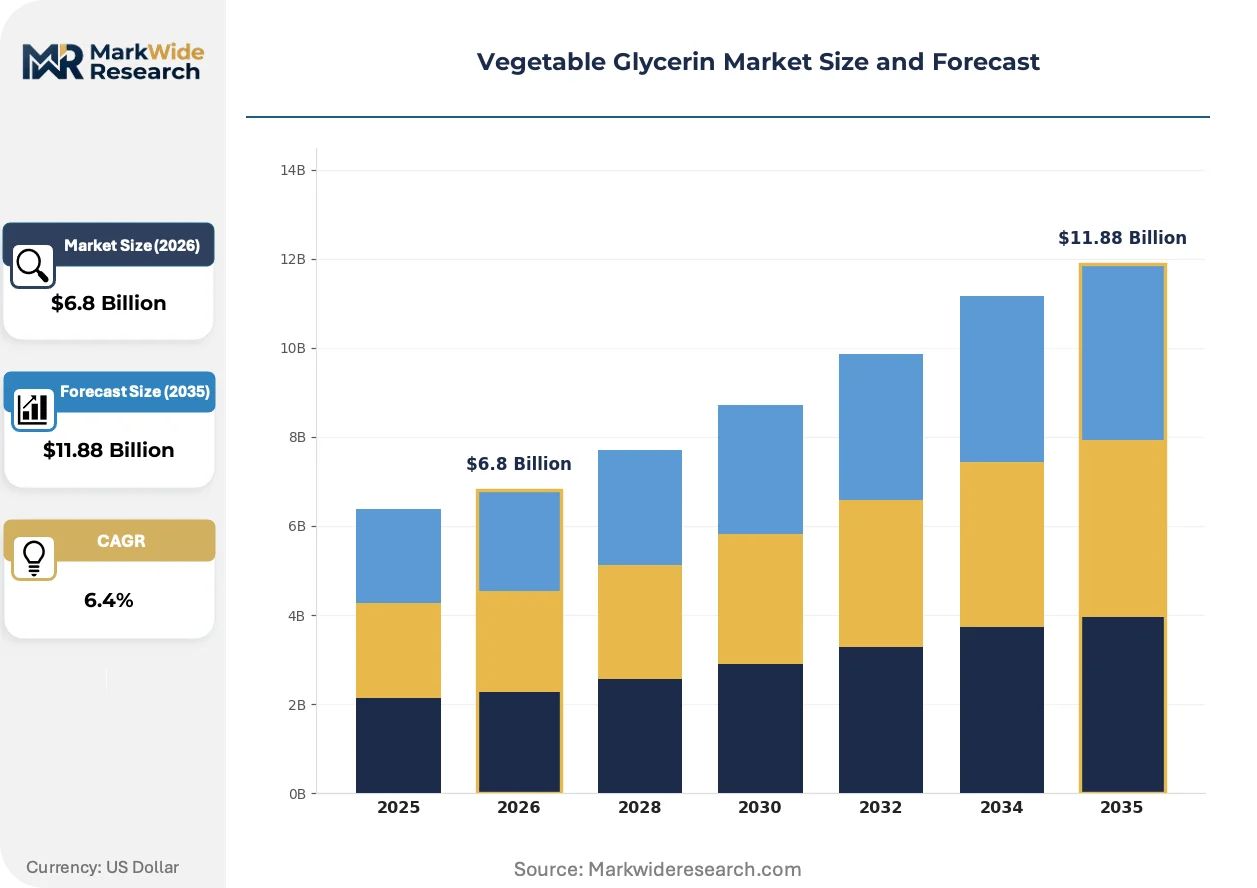
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Cosmetic Grade, Industrial Grade Application: Food Industry, Personal Care Products, Pharmaceuticals, Industrial Applications End User: Food Manufacturers, Cosmetics Companies, Pharmaceutical Firms, Chemical Industries Packaging Type: Bottles, Drums, Bulk Containers, Pails |
| Companies Covered | Cargill, Incorporated, Procter & Gamble, BASF, Dutch Glycerin Refinery (DGR), Avril Group, VVF L.L.C., The Dow Chemical Company, Emery Oleochemicals, Wilmar International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegetable Glycerin Market Strategic Shifts
Digital traceability infrastructure and modular purification systems are compressing certification timelines while enabling smaller-batch pharmaceutical production. These shifts are redrawing scale economies in glycerin refining.
Membrane filtration and molecular distillation hybrid systems are automating impurity removal to sub-ppm levels previously requiring multi-stage crystallization. Mid-scale Indian and Brazilian refiners are retrofitting existing saponification lines with these skids. The technology is automating quality assurance labor and shrinking batch-to-batch variation penalties.
EPA's Renewable Fuel Standard pathway documentation and ECHA's SCIP database requirements are converging on mass-balance accounting for co-product glycerin. Refiners must now maintain parallel certification streams for fuel-attributed and non-fuel-attributed output. Food-grade and pharmaceutical-grade segments face the steepest compliance cost escalation.
Direct refiner-to-formulator contracting is displacing merchant distributor networks in cosmetic-grade volumes. Indie beauty brands in California and Seoul are negotiating annual offtake agreements with certified Indonesian and Malaysian producers. This channel compression is most advanced in premium clean-label segments where provenance storytelling commands shelf price premiums.
Vegetable Glycerin Market Segmentation
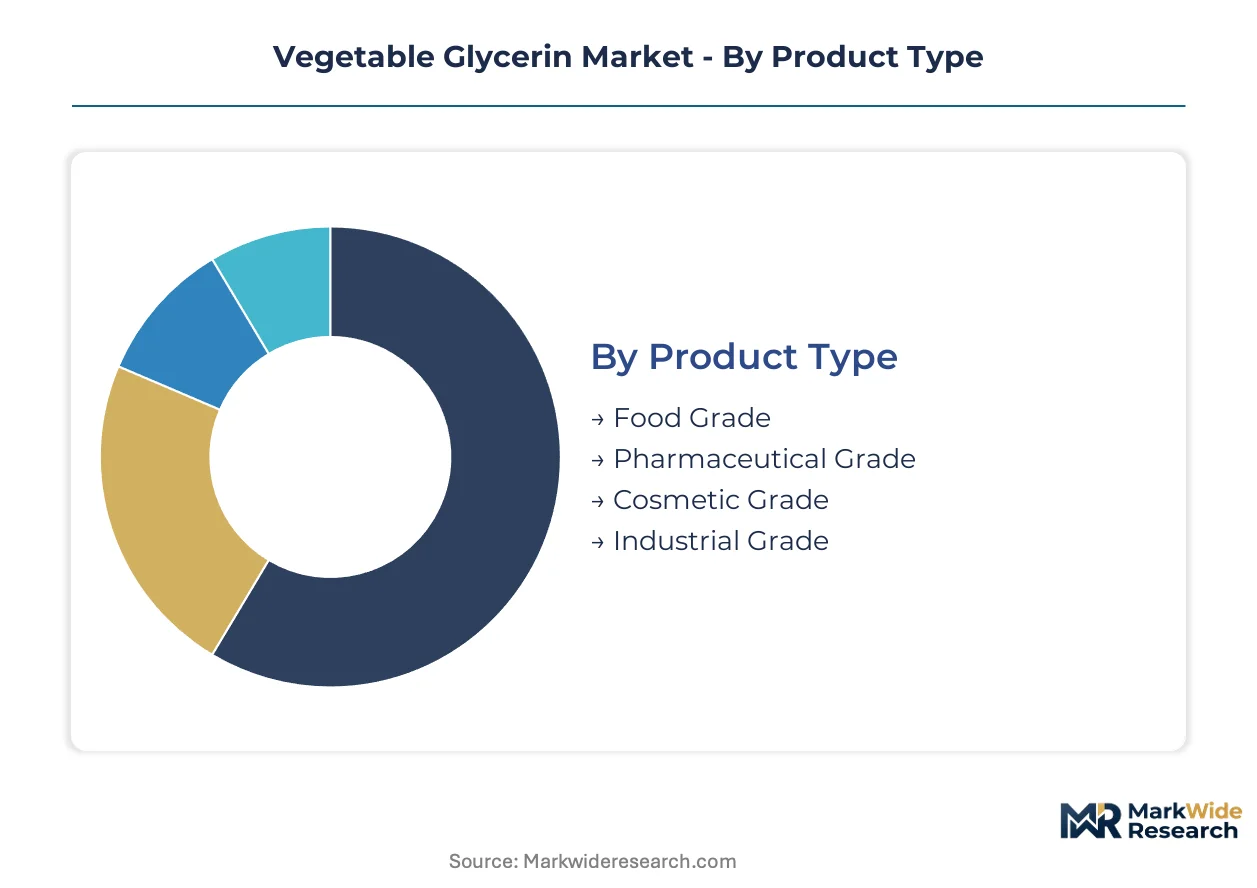
Vegetable glycerin pricing and procurement complexity vary dramatically across purity tiers and end-use specifications. Capital deployment decisions hinge on whether refiners target mass-market food volumes or pharmaceutical-grade premium positioning.
Product Type:
Pharmaceutical-grade facilities demand the heaviest upfront investment due to multi-stage crystallization, thin-film evaporation, and continuous quality monitoring systems required for USP and EP compliance.
- Pharmaceutical Grade:Minimum 99.5% glycerol content with heavy metals and chloride thresholds governed by USP and EP monographs. Demand concentrates in parenteral formulations and excipient applications across Germany, Switzerland, and the US Midwest, where CDSCO and FDA inspections enforce batch-level documentation. Certification timelines extend 18-24 months for multi-pharmacopeia filing.
- Cosmetic Grade:High-purity output tailored for humectant and solvent functions in waterless balms and serums. K-beauty formulators in Seoul and California indie brands are driving procurement of RSPO-certified feedstock glycerin for clean-label positioning. Direct refiner-to-formulator contracting is displacing traditional distributor networks in this tier.
- Food Grade:FDA 21 CFR-compliant material for confectionery humectancy and sugar-reduced applications.
- Industrial Grade:Lower-purity output for refrigerant alternatives and chemical intermediates.
Most installed capacity flows through Food Grade. Expansion is steepest in Cosmetic Grade.
Application:
Personal care product formulators represent the most fragmented customer base, requiring flexible batch sizing and rapid certification turnaround that favors modular purification investments.
- Personal Care Products:Moisturizers, serums, and waterless balms leverage glycerin's humectant properties. K-beauty brands in South Korea and clean-label skincare startups in California are substituting petrochemical alternatives, with provenance storytelling commanding shelf price premiums.
- Food Industry:Sugar-reduced confectionery and plant-based meat systems employ glycerin for moisture retention and texture modulation. Mature demand in the US and Western Europe contrasts with emerging applications in alternative protein formulations.
- Pharmaceuticals:Excipient and cryoprotectant functions in parenteral and oral dosage forms.
- Industrial Applications:Refrigerant alternatives under EU F-Gas Regulation pressure and chemical synthesis feedstock.
Food Industry absorbs the largest volume share. Personal Care Products are climbing the fastest.
End User:
Pharmaceutical firms impose the most stringent supplier qualification protocols, requiring dedicated quality systems and audit trails that raise effective capital barriers to entry.
- Pharmaceutical Firms:USP and EP compliance for excipient and active ingredient carrier applications. CDSCO's tightening import surveillance in India is creating openings for domestic USP-grade capacity.
- Cosmetics Companies:Clean-label and RSPO-certified sourcing requirements from multinational consumer goods houses.
- Food Manufacturers:FDA-regulated humectant applications across confectionery and processed foods.
- Chemical Industries:Industrial-grade offtake for refrigerant alternatives and chemical intermediates.
Food Manufacturers command the greatest volume. Pharmaceutical Firms show the steepest margin expansion.
Packaging Type:
Bulk container infrastructure requires the most substantial logistics capital, with port-adjacent tankage and specialized handling equipment creating regional supply moats.
- Bulk Containers:Rail and tanker-trailer deliveries to large-scale food and pharmaceutical manufacturers. Malaysian and Indonesian refineries with port-adjacent assets anchor Asia-Pacific supply.
- Drums:Intermediate volumes for mid-scale cosmetics and chemical processors.
- Bottles:Small-batch pharmaceutical and specialty cosmetic applications.
- Pails:Artisan food producers and indie beauty formulators.
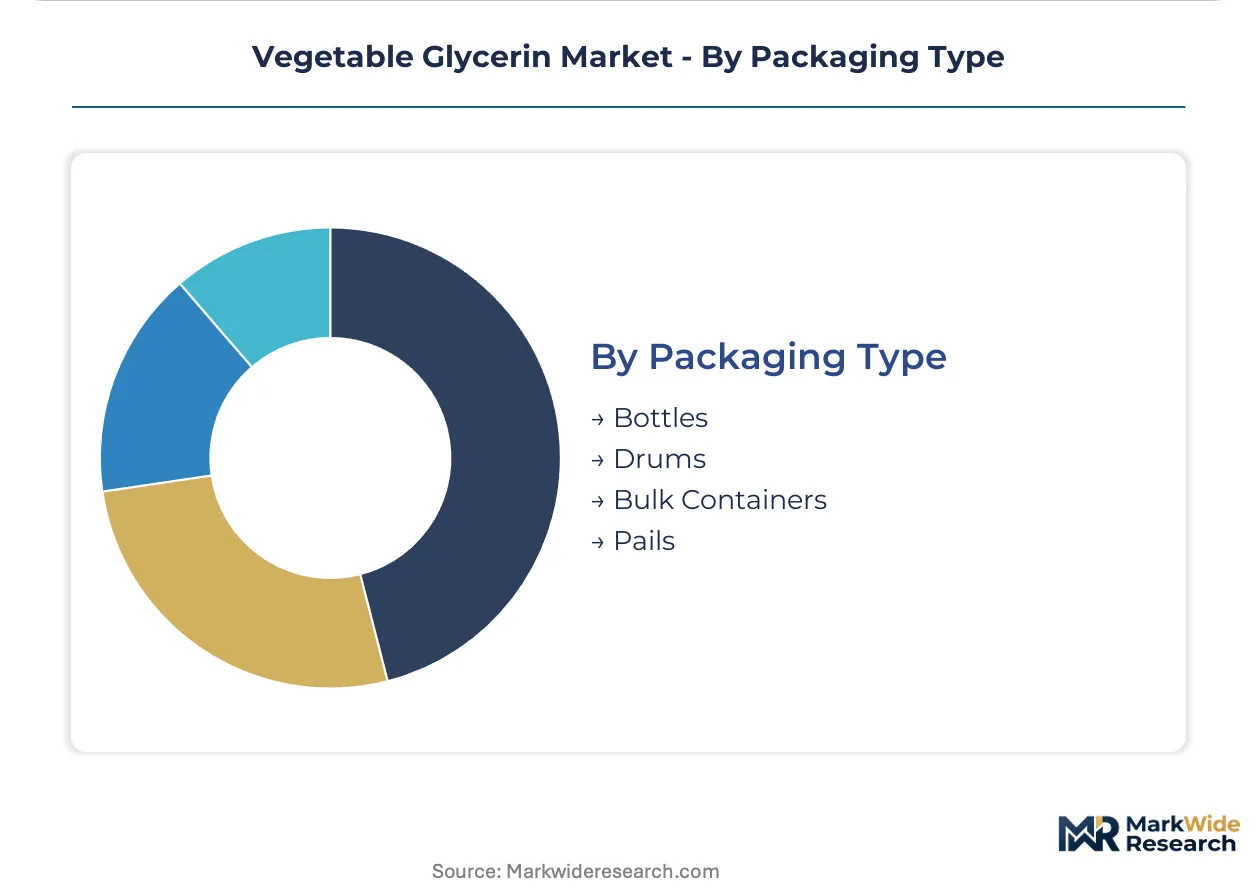
Most glycerin moves through Bulk Containers. Bottles are gaining share fastest in pharmaceutical small-batch production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized process engineering talent concentrates in aging European and Japanese refinery workforces, while Southeast Asian plantation-to-refinery integration captures feedstock cost advantages. Malaysia and Indonesia anchor upstream supply through port-adjacent processing assets. Germany, Switzerland, and the United States dominate pharmaceutical-grade downstream demand.
United States
Midwest pharmaceutical clusters and California clean-label cosmetics drive USP-grade and RSPO-certified procurement. FDA enforces 21 CFR food-additive and excipient standards with batch-level documentation requirements. Port-adjacent tankage in Houston and New Jersey supports bulk container logistics for food manufacturers.
Germany
Parenteral formulation demand from Rhine-Ruhr pharmaceutical manufacturers sustains EP-grade consumption. ECHA administers REACH registration tiers compelling importers to upgrade purification infrastructure. BASF's Ludwigshafen complex exemplifies continuous saponification process leadership for high-purity output.
Malaysia
RSPO-certified plantation holders supply major consumer goods multinationals with traceable feedstock. The country's national standards body enforces halal certification requirements for glycerin exports to Muslim-majority markets. Port-adjacent refineries in Port Klang leverage backward integration into Peninsular Malaysian palm estates.
Indonesia
Wilmar International's plantation-to-refinery network anchors Asia-Pacific supply with captive feedstock security. The Ministry of Environment and Forestry monitors plantation expansion under national sustainability commitments. Sumatran and Kalimantan refining clusters serve direct contracts with Seoul and California indie beauty brands.
India
CDSCO's tightening import quality surveillance creates openings for domestic USP-grade production capacity. Maharashtra and Gujarat pharmaceutical excipient demand outpaces local refined supply. Mumbai-Pune corridor refiners are retrofitting saponification lines with membrane filtration skids to capture CDSCO compliance premiums.
Vegetable Glycerin Market Competitive Environment
Capital-heavy producers compete with asset-light formulators across tiered purity segments. The vendor base separates between integrated plantation-refinery operators and merchant purification specialists. Three archetypes dominate: Southeast Asian feedstock-integrated refiners, European pharmaceutical-grade specialists, and diversified oleochemical conglomerates with multi-regional footprints. Capacity expansion and direct refiner-to-formulator contracting represent the dominant competitive moves, displacing traditional distributor networks in premium cosmetic segments.
Among plantation-integrated operators, Wilmar International and Cargill, Incorporated exemplify feedstock traceability strategies from estate to refined product. BASF occupies a position within the pharmaceutical-grade specialist tier, leveraging continuous process engineering for EP and USP compliance. These three anchors demonstrate how certification depth and geographic integration separate premium positioning from commodity competition.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Procter & Gamble |
| BASF |
| Dutch Glycerin Refinery (DGR) |
| Avril Group |
| VVF L.L.C. |
| The Dow Chemical Company |
| Emery Oleochemicals |
| Wilmar International |
| Others |
Value Chain & Pricing Dynamics
Multinational consumer goods houses concentrating procurement through direct refiner-to-formulator contracts have compressed margins for merchant distributors while elevating price premiums for RSPO-certified and USP-grade material. This buyer consolidation is forcing pricing stratification across pharmaceutical, cosmetic, and food-grade tiers based on certification depth rather than volume scale.
Pricing Analysis
Three-tier pricing structure across pharmaceutical, cosmetic, and industrial grades anchors the market, with differentiation driven by USP-EP compliance costs and RSPO certification premiums. Price compression in crude glycerin feedstock—stemming from biodiesel co-product oversupply in Argentina and Brazil—transmits downstream with uneven intensity. Food-grade buyers exhibit the highest price sensitivity due to commoditized applications, while pharmaceutical firms accept steep premiums for multi-pharmacopeia documentation.
Supply Chain Analysis
Refurbishment and re-refining of off-specification glycerin batches creates secondary supply flows that compete with virgin material in industrial applications. Upstream concentration in Malaysian and Indonesian palm plantations feeds port-adjacent refining clusters in Port Klang and Sumatra. The supply chain rests on triglyceride feedstock security, saponification catalyst availability, and thin-film evaporation equipment lead times. Single-origin exposure to Southeast Asian palm oil presents tariff and sustainability-audit vulnerability. Distribution runs through bulk tanker contracts to large food and pharmaceutical manufacturers, with drum and bottle formats serving fragmented cosmetics processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vegetable glycerin market functions as a geographic-arbitrage play where Indian pharmaceutical excipient demand outpaces local USP-grade supply, while European REACH compliance costs push purification investment toward lower-cost jurisdictions with equivalent technical capability.
For Market Incumbents: Deepen backward integration into certified-sustainable palm and soybean feedstocks to defend margin position against merchant refiners exposed to crude glycerin volatility. BASF's continuous saponification upgrades demonstrate how process engineering investment preserves pharmaceutical-grade pricing power. Prioritize CDSCO compliance infrastructure to capture Indian domestic production premiums before import surveillance tightens further. For New Entrants and Emerging Players: Launch via direct-to-formulator contracting with Seoul and California indie beauty brands, bypassing distributor networks where incumbents hold entrenched relationships. Cell-cultured meat media applications represent the most penetrable white-space target, requiring pharmaceutical-grade glycerin for cryoprotectant functions in serum-free formulations. Position around modular membrane filtration skids to compress batch-to-batch variation penalties that plague aging European refinery assets. For Investors and Strategic Acquirers: Plantation-integrated oleochemical conglomerates are the most active acquirer in this space, seeking port-adjacent refining assets that anchor Asia-Pacific supply security. The five-to-ten-year viability window favors targets with captive feedstock and dual USP-EP certification capability. Monitor CDSCO import rejection rates and EU Green Deal tender specifications for early signals of compliance-premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Feedstock | Wilmar International's plantation network demonstrates how captive palm oil supply secures preferred-supplier status with multinational consumer goods houses. |
| Modular Purification System Deployment | Membrane filtration skids enable mid-scale Indian refiners to achieve sub-ppm impurity removal without multi-stage crystallization capital. |
| Direct Refiner-to-Formulator Contracting | Channel compression in cosmetic-grade volumes displaces merchant distributors where provenance storytelling commands shelf price premiums. |
| Multi-Pharmacopeia Compliance Investment | Dual USP-EP filing capability opens parenteral formulation demand from Rhine-Ruhr pharmaceutical manufacturers and Midwest excipient clusters. |
| Digital Traceability Infrastructure | Mass-balance accounting systems satisfy EPA Renewable Fuel Standard and ECHA SCIP database requirements for co-product glycerin attribution. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with refinery operations directors, pharmaceutical procurement managers, cosmetics formulators, and RSPO certification auditors. Secondary validation draws from FDA 21 CFR filings, ECHA REACH registration databases, customs trade flows, and FEDIOL industry statistics. Bottom-up capacity modeling and top-down demand triangulation reconcile segmentation outputs.
Granularity extends to grade-tier, end-use industry, packaging format, and regional production hub levels across the projection horizon. CAGRs derive from elasticity-adjusted consumption modeling against feedstock cost trajectories. Forecast inputs include biodiesel co-production ratios, pharmacopeia monograph revision timelines, and CDSCO inspection intensity indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under crude glycerin price volatility and sudden REACH substance evaluation escalations. Practitioners should monitor Argentine biodiesel policy shifts and EU F-Gas Regulation refrigerant substitution rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
India Protein Market
Ingredients
South America Protein Market
Ingredients
Wheat Starch Derivative Market
Ingredients
Bakery Ingredients Market
Ingredients
Asia-Pacific Dairy Ingredients Market
Ingredients
Tuna and Algae Omega-3 Ingredient Market
Ingredients
Coconut Oil Based Products Market
Ingredients
Sea Salt Market
Ingredients
Interesterified CBE Market
Ingredients
Sunflower Oil Market
Ingredients
Honey Powder Market
Ingredients
Broccoli Powder Market
Ingredients
Yeast and Yeast Extract Market
Ingredients
Injection Grade Soybean Oil Market
Ingredients
Baobab Powder Market
Ingredients
Volatile Fatty Acids Market