
 Paper Pleated Cups Market | 2026-2036
Paper Pleated Cups Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Pleated Cups Market Analytics
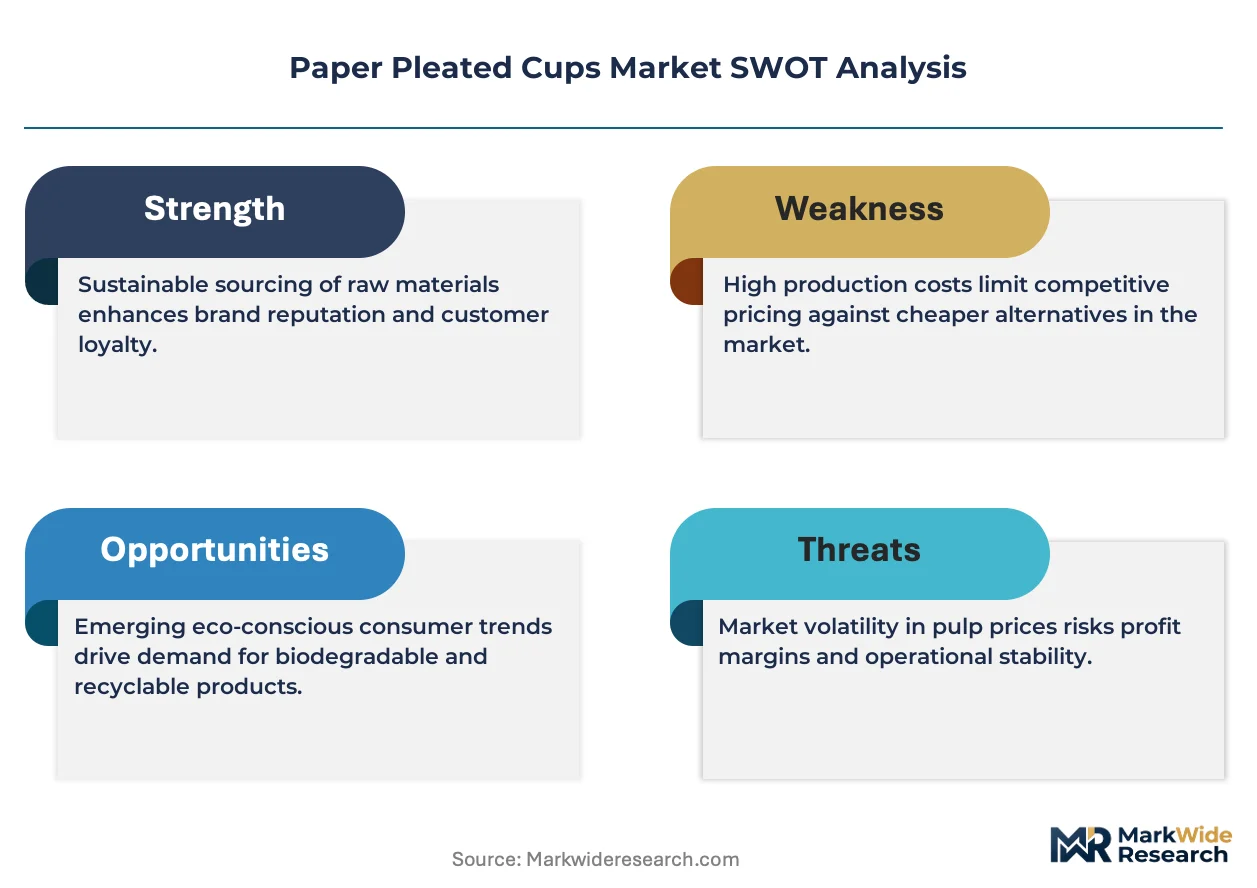
EU Single-Use Plastics Directive is realigning the cost-of-entry calculus for pleated cup manufacturers serving European foodservice channels. Huhtamaki Oyj leverages its integrated fiber-based packaging network to preempt compliance-driven sourcing shifts. Dart Container Corporation anchors its position through manufacturing scale across North American converting facilities. Graphic Packaging International, LLC differentiates via coated-paperboard technology leadership in hot-fill applications.
Paper pleated cups are cylindrical containers fabricated from pleated paperboard, typically lined with polyethylene or polylactic acid barriers to resist liquid penetration and maintain structural integrity at temperatures ranging from frozen beverages to near-boiling coffee. Their primary commercial purpose is to provide insulated, disposable serving vessels for on-premise and takeaway foodservice operations. Hot cups command the dominant share of value given thermal-barrier requirements and premium material specifications, while PLA coated paper represents the fastest-expanding material category as composting infrastructure matures in regulated jurisdictions. Custom-printed cups concentrate margin pools through brand-owner willingness to pay for differentiated shelf and street presence.
FDA food-contact substance regulations govern liner chemistry and migration limits for U.S.-destined products, while EFSA and REACH frameworks constrain additive portfolios across European supply chains. BIS certification requirements in India and GB standards in China create divergent compliance pathways that fragment qualification costs for multi-regional suppliers. Stakeholders must monitor how extended producer responsibility schemes in the EU and pending state-level packaging legislation in the U.S. reshape material specifications and recycling economics before committing capital to substrate transitions.
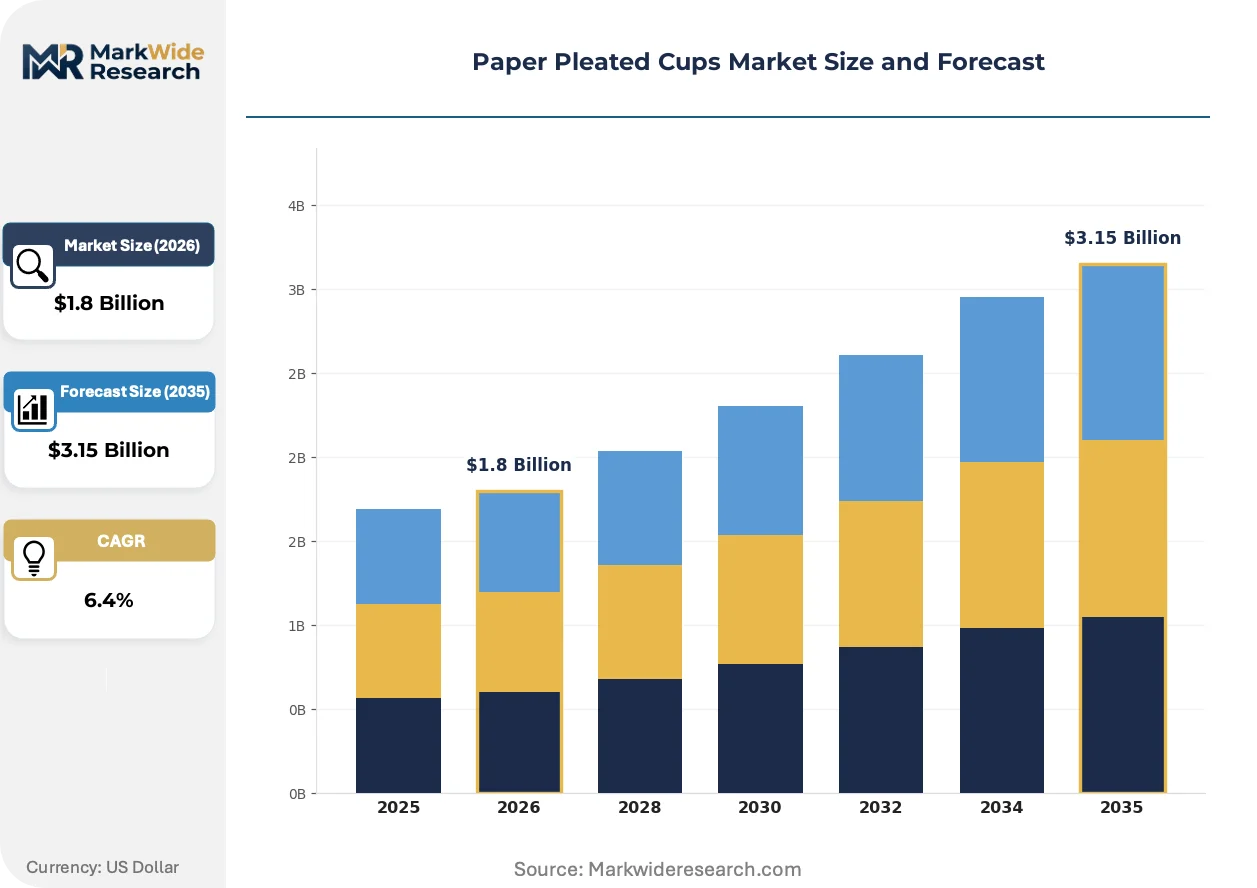
Market Dynamics
Material substitution mandates across European foodservice channels are compressing the polyethylene-lined installed base while polylactic acid and aqueous barrier chemistries scale through qualified supply chains. This regulatory compression is redrawing qualification timelines and capex allocation for substrate converters.
Growth Catalysts
- EU Single-Use Plastics Directive:The framework bans selected plastic items and mandates biodegradable alternatives, forcing quick-service restaurants to source fiber-based pleated cups. German municipal composting infrastructure validates premium coated-paper uptake.
- Hot-fill thermal barrier specifications:Coffee chains require cups maintaining integrity at near-boiling temperatures, driving material innovation toward multi-layer paperboard with enhanced insulation properties.
- Quick-service restaurant channel concentration:North American burger and coffee chains are consolidating procurement around certified fiber-based packaging, creating volume anchors for specialized converters.
Market Restraints
- Pulp price volatility:Kraft paperboard input costs fluctuate with Nordic softwood supply cycles, compressing converter margins during raw material spikes.
- Barrier coating technical limitations:Current aqueous coatings lack the grease resistance of polyethylene liners, restricting deployment in fried-food applications.
- Composting infrastructure fragmentation:Industrial composting facility scarcity outside Germany and select Nordic municipalities limits addressable market for PLA-lined products.
Strategic Opportunities
- Indian foodservice expansion:Quick-service penetration in tier-two cities creates demand for cost-optimized pleated cups as BIS certification requirements mature.
- Extended Producer Responsibility schemes:EU packaging levies incentivize lightweight, recyclable designs that reduce fee obligations for brand owners.
- Custom-printed differentiation:Digital printing convergence with short-run converting enables micro-lot branding for regional coffee roasters and event catering.
Industry Challenges
- FDA migration testing timelines:New barrier chemistries require 12-18 month food-contact substance notification cycles, delaying product launches for U.S.-destined lines.
- Compostability certification complexity:Divergent OK Compost, BPI, and Cedar Grove standards create multi-jurisdiction qualification burdens for substrate suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Pleated Cups Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Cups, Cold Cups, Takeaway Cups, Custom-Printed Cups Material: Recycled Paper, Virgin Paper, PLA Coated Paper, Biodegradable Paper Size: Small, Medium, Large, Extra Large End User: Cafes, Restaurants, Food Trucks, Events |
| Companies Covered | Huhtamaki Oyj, Dart Container Corporation, Graphic Packaging International, LLC, Koch Industries, Inc., Seda Group, Inc., WestRock Company, International Paper, Genpak, LLC, Lollicup USA Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Pleated Cups Market Evolving Landscape
Barrier chemistry innovation is compressing the performance gap between conventional plastic linings and bio-based alternatives. Three interconnected developments are reshaping material specifications and procurement criteria across foodservice channels.
Aqueous barrier coatings are electrifying the hot-cup segment by eliminating polyethylene layers while maintaining liquid resistance. Coffee chains in Scandinavia are piloting these cups at scale. The technology is electrifying supplier R&D roadmaps as converters race to match thermal performance with compostable end-of-life credentials.
REACH framework amendments are constraining per- and polyfluoroalkyl substance use in food-contact materials across European supply chains. The regulatory tightening is forcing reformulation of grease-resistant coatings. Hot-fill applications with fatty content are most affected, with manufacturers accelerating fluorine-free chemistry development to maintain market access.
Direct procurement from substrate specialists is displacing distributor-mediated buying among multi-location restaurant operators. Large coffee chains are establishing approved vendor lists with technical qualification requirements. This pattern is most visible in Germany and the Netherlands, where sustainability scorecards now govern supplier selection alongside unit economics.
Paper Pleated Cups Market Segmentation
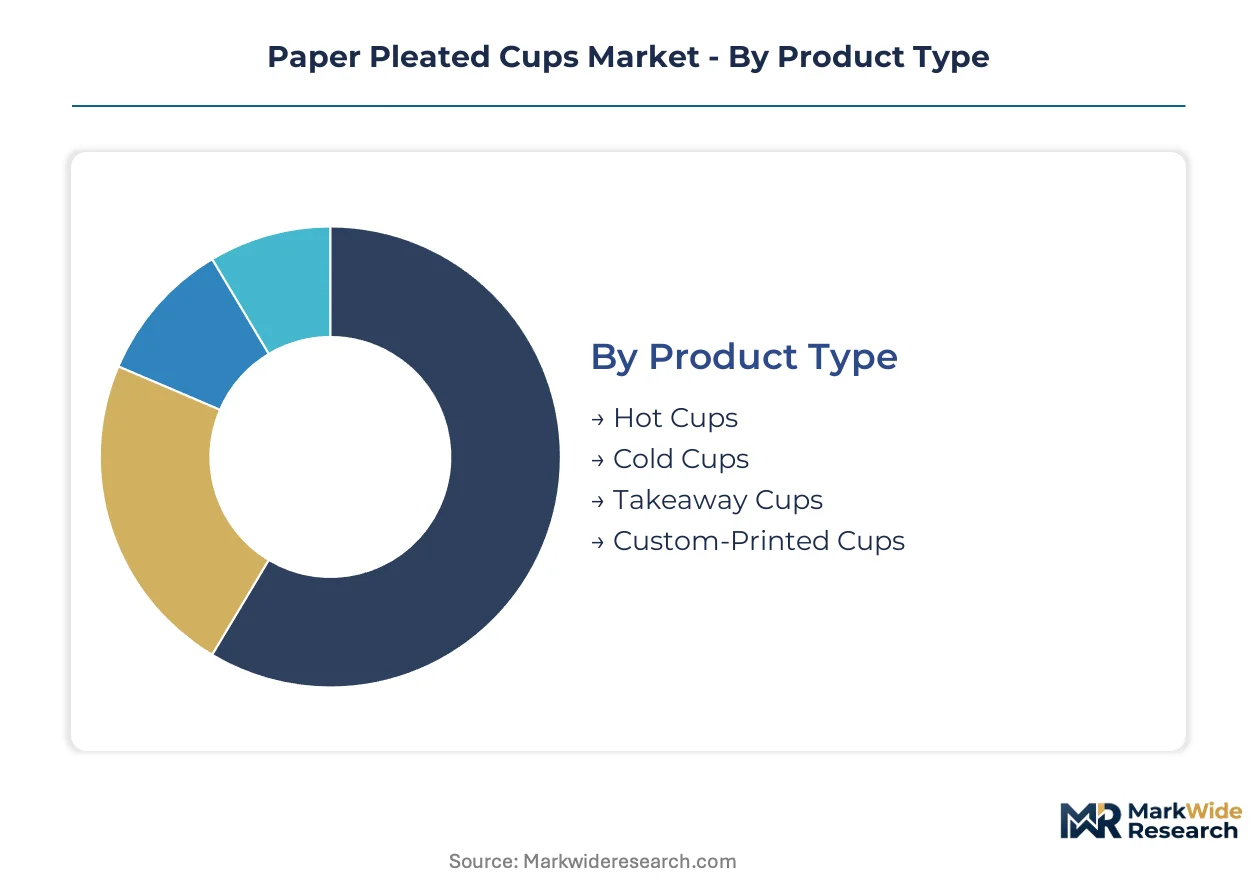
Pleated cup procurement decisions cascade through material specifications, thermal performance requirements, and branding imperatives. Each segmentation axis carries distinct margin profiles and qualification barriers that reshape competitive positioning across foodservice channels.
Product Type:
Thermal performance specifications and end-use temperature requirements define the primary product architecture.
- Hot Cups:Multi-layer paperboard construction with polyethylene or polylactic acid barriers maintains structural integrity at near-boiling temperatures. Coffee chains in Germany and Scandinavian markets concentrate procurement here, driven by EU Single-Use Plastics Directive compliance timelines and premium thermal specifications.
- Cold Cups:Single-wall pleated designs with aqueous or minimal barrier coatings serve frozen beverages and chilled applications. Quick-service restaurant chains across North American markets deploy these for soft drink and iced coffee programs where insulation demands are lower.
- Takeaway Cups:Standardized formats optimized for lid compatibility and stack density in delivery logistics.
- Custom-Printed Cups:Digital and flexographic branding surfaces for regional coffee roasters and event catering.
Mature deployment sits with Hot Cups. Newer deployment is concentrated in Custom-Printed Cups.
Material:
Substrate chemistry determines compostability credentials, barrier performance, and regulatory compliance pathways across jurisdictions.
- PLA Coated Paper:Polylactic acid barrier layers derived from corn starch deliver biodegradable end-of-life performance in industrial composting environments. German municipal composting infrastructure validates premium uptake, though facility scarcity elsewhere constrains addressable market expansion.
- Recycled Paper:Post-consumer fiber content meets extended producer responsibility scheme incentives in EU packaging levies. Cost-optimized specifications serve Indian tier-two city quick-service penetration as BIS certification requirements mature.
- Virgin Paper:Nordic softwood kraft paperboard provides consistent fiber length and structural reliability for high-speed converting lines.
- Biodegradable Paper:Emerging aqueous barrier formulations eliminate plastic linings entirely while maintaining liquid resistance.
Volume concentration favors Virgin Paper. Steepest expansion trajectory belongs to PLA Coated Paper.
Size:
Portion standardization and beverage category norms drive dimensional clustering across foodservice formats.
- Medium:12-16 ounce capacity captures standard coffee and soft drink servings across quick-service and cafe channels. North American burger chains consolidate procurement around this format, creating volume anchors for specialized converters with certified fiber-based packaging lines.
- Large:20-24 ounce specifications serve fountain beverage and specialty coffee applications with higher liquid volumes.
- Small:8-10 ounce formats concentrate in espresso-based drinks and children's portions.
- Extra Large:32+ ounce capacities serve movie theater and convenience store fountain programs.
Procurement scale peaks with Medium. Premium margin capture shifts toward Large.
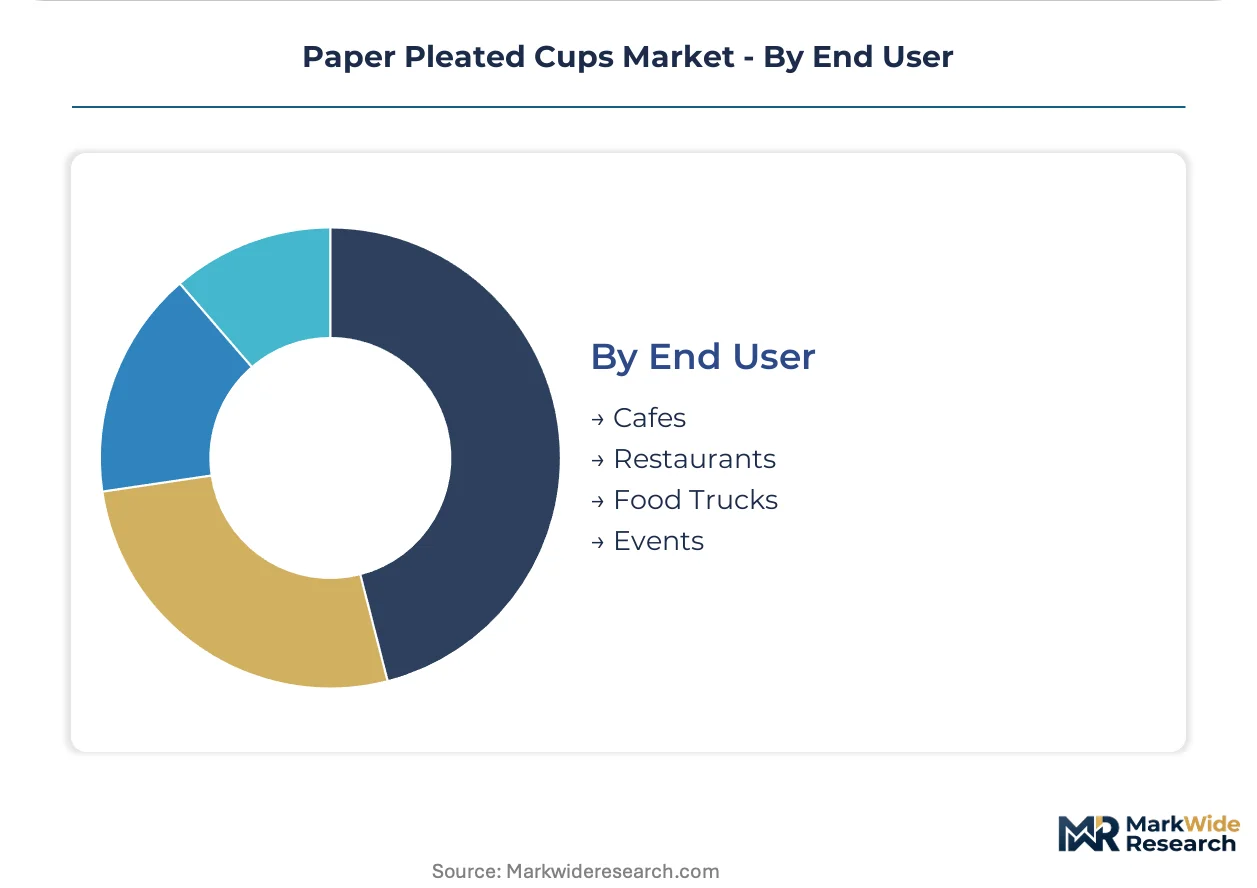
End User:
Channel-specific operational requirements reshape durability, branding, and logistics specifications.
- Cafes:Brand-differentiated custom printing and thermal barrier specifications for specialty coffee service. Direct procurement from substrate specialists displaces distributor-mediated buying among multi-location operators, with sustainability scorecards governing supplier selection alongside unit economics in Germany and the Netherlands.
- Restaurants:Standardized formats with cost-optimized specifications for high-volume turnover environments.
- Food Trucks:Stack density and lid compatibility priorities for mobile service constraints.
- Events:Short-run digital printing enables micro-lot branding for regional catering and festival applications.
Contract stability concentrates with Restaurants. Margin expansion potential sits with Events.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Single-Use Plastics Directive has concentrated pleated cup manufacturing investment in German industrial zones, where municipal composting infrastructure validates premium substrate uptake and extended producer responsibility schemes reshape procurement economics.
Germany
Quick-service restaurant chains in Berlin and Hamburg are consolidating fiber-based packaging procurement around certified PLA-lined formats. REACH amendments constrain per- and polyfluoroalkyl substance use in grease-resistant coatings, forcing aqueous barrier reformulation. The Bavarian converting corridor anchors specialized capacity for hot-fill thermal specifications serving pan-European coffee chains.
United States
FDA food-contact substance notification cycles spanning 12-18 months delay new barrier chemistry launches for domestic foodservice channels. Coffee chains across the Pacific Northwest and Northeast Corridor are establishing approved vendor lists with technical qualification requirements. Georgia and Illinois host high-volume converting facilities supplying burger chains with standardized medium-format pleated cups.
India
Quick-service penetration in tier-two cities drives demand for cost-optimized pleated cups as BIS certification requirements mature. The FSSAI framework governs food-contact material safety alongside central packaging standards. Maharashtra and Gujarat industrial clusters concentrate domestic converting capacity for regional foodservice operators.
China
GB standards for food-contact paper products create divergent compliance pathways that fragment qualification costs for export-oriented suppliers. Yangtze River Delta manufacturing zones supply both domestic cafe chains and international quick-service brands. Shanghai municipal regulations on single-use plastics accelerate domestic substrate transitions toward biodegradable alternatives.
United Kingdom
Post-Brexit regulatory divergence from EU packaging levies creates uncertainty for extended producer responsibility implementation timelines. London cafe density sustains premium custom-printed cup demand with sustainability scorecards governing supplier selection. Midlands converting facilities serve national quick-service distribution networks with medium-format standardized specifications.
Paper Pleated Cups Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across substrate chemistry and thermal performance tiers. The vendor base organizes around three strategic archetypes: integrated fiber-based packaging networks, scale-driven North American converters, and coated-paperboard technology leaders. Dominant competitive moves include manufacturing capacity expansion across certified composting corridors and strategic partnerships with quick-service procurement consortia.
Among integrated packaging networks, Huhtamaki Oyj occupies a position exemplifying fiber-based substrate leadership. Dart Container Corporation anchors the scale-driven archetype through North American converting concentration. Graphic Packaging International, LLC represents technology-forward positioning in coated-paperboard applications.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| Dart Container Corporation |
| Graphic Packaging International, LLC |
| Koch Industries, Inc. |
| Seda Group, Inc. |
| WestRock Company |
| International Paper |
| Genpak, LLC |
| Lollicup USA Inc. |
| Others |
Value Network & Pricing Analysis
Nordic softwood pulp futures cascade through three-tier pricing structures across premium, standard, and economy levels, with kraft paperboard converters in Germany and the United States passing raw material volatility into contract renegotiation cycles. Buyers face compressed lead-time premiums as EU Single-Use Plastics Directive compliance deadlines concentrate procurement around certified PLA-lined formats.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent above contract baselines reward converters with certified composting corridor capacity, while spot inventory discounts attract price-sensitive quick-service restaurant procurement teams in Indian tier-two cities. Price differentiation hinges on certification tier—OK Compost and BPI credentials command sustained premiums—and volume scale, with annual offtake commitments above five million units unlocking standard-tier access. Pricing pressure stems from pulp price volatility compressing converter margins during Nordic supply disruptions. Quick-service restaurant chains exhibit highest price sensitivity, while specialty coffee roasters in Germany and the Netherlands absorb premiums for custom-printed differentiation.
Supply Chain Analysis
Container freight rates from Shanghai to Rotterdam and Savannah anchor total delivered cost structures for substrate importers, with Yangtze River Delta manufacturing zones feeding both domestic Chinese cafe chains and international quick-service brands. Supply concentrates in Germany, the United States, and China, with Bavarian converting corridors and Georgia-Illinois industrial clusters anchoring regional capacity. Raw material dependencies center on Nordic softwood kraft paperboard, polylactic acid resin from Thai and US biopolymer plants, and aqueous barrier chemistry inputs. Single-source vulnerability in PLA resin supply creates qualification risk for European converters. Distribution runs through quick-service restaurant procurement consortia and approved vendor lists with technical qualification requirements displacing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The paper pleated cups market has become a vertical-integration race as converters pursue captive supply of certified composting corridor capacity to preempt substrate scarcity and secure procurement consortium membership.
For Market Incumbents: Anticipate aqueous barrier coating technical limitations eroding polyethylene-lined volume share by accelerating fluorine-free chemistry R&D partnerships with Scandinavian coffee chains. Anchor backward integration into Nordic softwood pulp supply through long-term offtake agreements with Finnish and Swedish mills, insulating margin structures from raw material spike cycles. Defend position by locking multi-year approved vendor list status with pan-European quick-service procurement consortia before FDA migration testing timelines delay competitor launches. For New Entrants and Emerging Players: Regional coffee roasters in German secondary cities represent the most penetrable buyer archetype, as direct procurement patterns from substrate specialists create entry points outside distributor-mediated channels. Tier-two Indian quick-service penetration offers white-space expansion as BIS certification requirements mature and cost-optimized specifications displace unorganized sector supply. Pursue digital printing convergence with short-run converting to enable micro-lot branding for event catering applications, leveraging sustainability scorecard governance in Dutch procurement selection criteria. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap aqueous barrier specialists with qualified German composting corridor access, as REACH amendment compliance costs strain undercapitalized substrate converters. Long-term viability over the next decade hinges on industrial composting infrastructure maturation beyond German and Nordic municipal networks. Watch BPI and Cedar Grove certification harmonization progress as the signal indicating PLA-lined product addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nordic Pulp Supply | Long-term offtake agreements with Finnish mills insulate converters from kraft paperboard price volatility cycles. |
| Aqueous Barrier Coating Scale-Up | Fluorine-free chemistry development maintains REACH compliance for hot-fill applications with fatty content. |
| Composting Corridor Capacity Expansion | Certified facility investment in Bavaria validates premium PLA-coated paper uptake under EU packaging levies. |
| Digital Printing Convergence | Short-run converting enables micro-lot branding for regional coffee roasters and event catering channels. |
| Approved Vendor List Qualification | Technical certification with quick-service procurement consortia displaces distributor-mediated buying patterns. |
Research Methodology
Multi-period observation of kraft paperboard futures pricing, PLA resin import volumes, and quick-service restaurant procurement contract awards anchored the trend analysis, supplemented by interviews with converting plant managers, quick-service sustainability procurement leads, aqueous barrier R&D directors, and Nordic pulp supply specialists. Secondary validation drew from customs trade databases, EU Single-Use Plastics Directive implementation tracking, BPI and OK Compost certification registries, and SEC filings of diversified packaging conglomerates. Bottom-up volume builds across material, product type, and end-use segments triangulated against top-down macroeconomic demand indicators.
Input-output matrices modeled pulp-to-converter-to-foodservice channel value flows across the projection horizon, with segmentation dimensions spanning thermal performance tier, substrate chemistry, compostability certification status, and geographic regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating EU packaging levy implementation schedules and FDA food-contact substance notification cycle durations. Forecast inputs included industrial composting facility buildout pipelines and quick-service restaurant unit expansion trajectories in Indian tier-two cities.
Revisions become necessary when REACH framework amendments accelerate per- and polyfluoroalkyl substance bans, when Nordic softwood supply disruptions exceed historical volatility bands, or when US state-level packaging legislation diverges from federal FDA pathways. Forecasts reflect modeling assumptions about composting infrastructure maturation timelines and barrier coating technical performance thresholds. Stakeholders should weight assumptions against their own operating context and qualification burden capacities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Kraft Paper SOS Bag Market
Paper & Paperboard Packaging
Push-Up Paperboard Tube Market
Paper & Paperboard Packaging
Fluting Paper Market
Paper & Paperboard Packaging
Disposable Paper Plates Market
Paper & Paperboard Packaging
Wax-Coated Paper Market
Paper & Paperboard Packaging
Middle East Corrugated Packaging Market
Paper & Paperboard Packaging
Paper Cups Market
Paper & Paperboard Packaging
Qatar Paper Packaging Products Market
Paper & Paperboard Packaging
GCC Paper Cup Market
Paper & Paperboard Packaging
Global VCI Paper Market
Paper & Paperboard Packaging
Coated Paper Packaging Box Market
Paper & Paperboard Packaging
Beverage Filter Paper Market
Paper & Paperboard Packaging
Coffee Filter Paper Market
Paper & Paperboard Packaging
Tissue and Hygiene Paper Packaging Market
Paper & Paperboard Packaging
Coated Recycled Boxboard Market
Paper & Paperboard Packaging
Flowpack Paper Packaging Market