
 Global Food Contact Papers Market | 2026-2036
Global Food Contact Papers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Food Contact Papers Market Analysis
Quick-service restaurant chains are consolidating their purchasing power around food contact papers with certified grease resistance and microwave-safe properties. International Paper Company leverages its North American pulp integration to supply high-volume quick-service accounts with consistent caliper and barrier performance. Mondi Plc anchors European demand through its recycled-content kraft papers that meet EN 13432 compostability thresholds. Smurfit Kappa Group competes on converting flexibility, offering custom-printed greaseproof solutions for regional bakery brands.
Food contact papers comprise barrier-treated cellulose sheets engineered to prevent grease migration, moisture loss, and flavor contamination during storage, transport, and reheating of packaged foods. These papers typically incorporate fluorochemical-free sizing agents or plant-based wax coatings to achieve oil-kit values above 12 while maintaining heat seal compatibility up to 200°C for oven-ready applications. Parchment paper leads product type value pools due to its dual-use baking and wrapping functionality in both commercial and home kitchens. Biodegradable material variants represent the fastest-expanding material segment as EU Green Deal compliance deadlines and US state-level extended producer responsibility laws reshape procurement specifications across food retailers and processing units.
FDA food contact notification requirements govern substance migration limits in the United States, while EFSA and REACH jointly regulate chemical constituents across EU member states. Japan's Food Sanitation Act and positive list system for food contact materials create additional compliance layers for exporters serving the METI-supervised market. Stakeholders must monitor evolving PFAS restrictions in multiple jurisdictions and align R&D spending with emerging compostability certification schemes before regulatory divergence fragments specification standards.
Market Dynamics
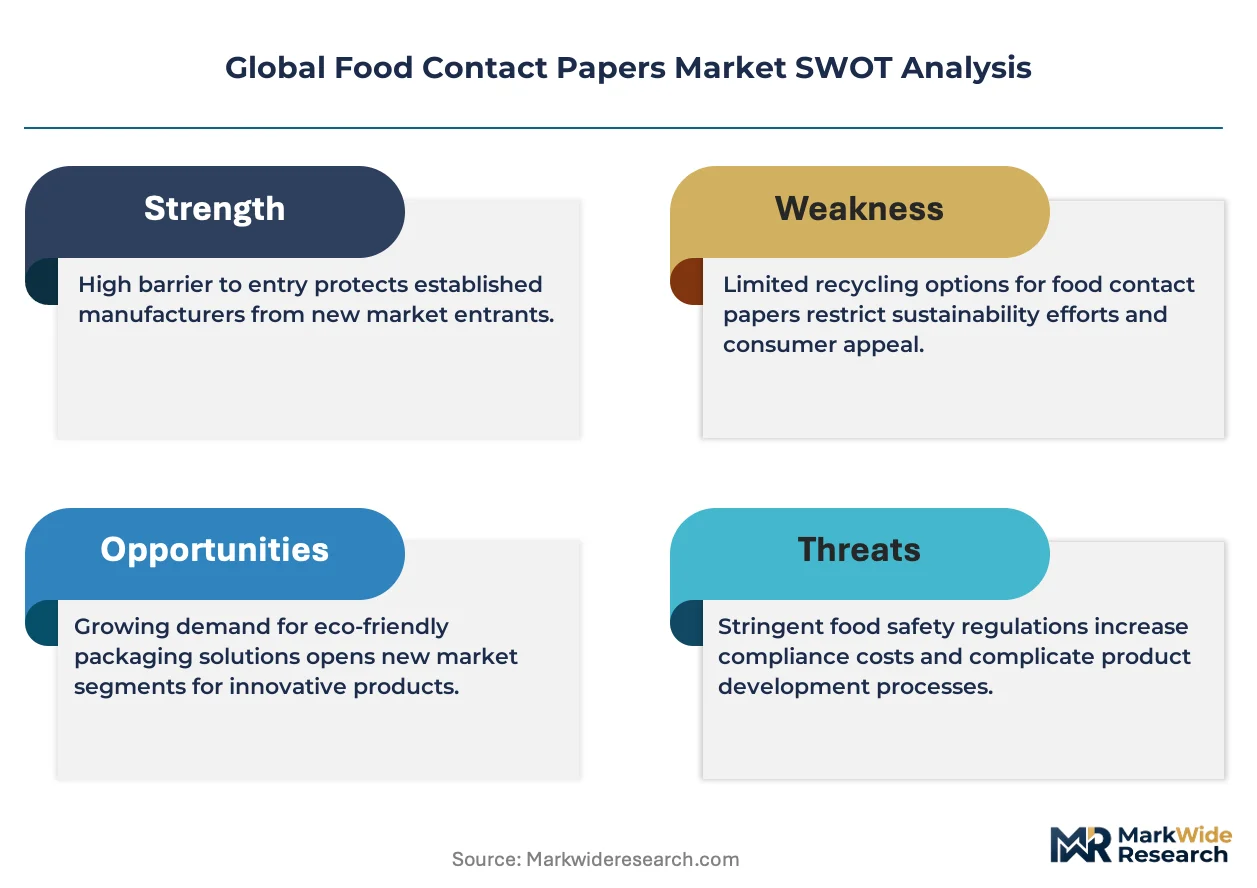
EU Green Deal compliance deadlines are compressing converter R&D cycles as food retailers demand certified compostable alternatives to fluorinated barrier papers before 2035 phase-out mandates take effect.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Tightening fluorinated compound restrictions force converters toward biodegradable sizing agents and plant-based wax coatings that achieve oil-kit values above 12 without PFAS chemistry.
- Quick-service restaurant expansion:North American and Western European chains consolidate purchasing around greaseproof and parchment paper with microwave-safe properties up to 200°C for oven-ready applications.
- German bakery sector transition:Artisan-to-industrial production shifts create specialized demand for barrier papers with precise caliper consistency and heat seal compatibility.
Market Restraints
- Pulp cost volatility:Hardwood and softwood fiber prices fluctuate with energy and logistics costs, squeezing converter margins on long-term quick-service contracts with fixed pricing clauses.
- Fluorochemical alternative scarcity:Food-safe barrier chemistry without PFAS remains limited to a handful of certified suppliers, creating supply concentration risk in specialty sizing agents.
- Performance gap in high-grease applications:Current biodegradable coatings fail to match fluorinated papers in extended hot-hold scenarios above 90 minutes, restricting use in fried food segments.
Strategic Opportunities
- India food processing expansion:FSSAI modernization of food contact material standards creates first-mover advantage for EN 13432-certified exporters as domestic quick-service chains scale.
- Home baking equipment convergence:Air fryer and steam oven penetration in US and EU households drives dual-use parchment paper demand for both baking and wrapping functions.
- Extended producer responsibility laws:US state-level mandates in California, Maine, and Oregon reward compostable packaging with reduced fee structures, tilting retailer procurement specifications.
Industry Challenges
- PFAS testing and certification backlog:Third-party laboratories face 16-24 week queues for total organic fluorine analysis, delaying product launches and contract renewals.
- Heat seal compatibility integration:Biodegradable coatings require retrofitting of existing converting lines designed for fluorochemical sizing, demanding capital outlay with uncertain payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Food Contact Papers Market |
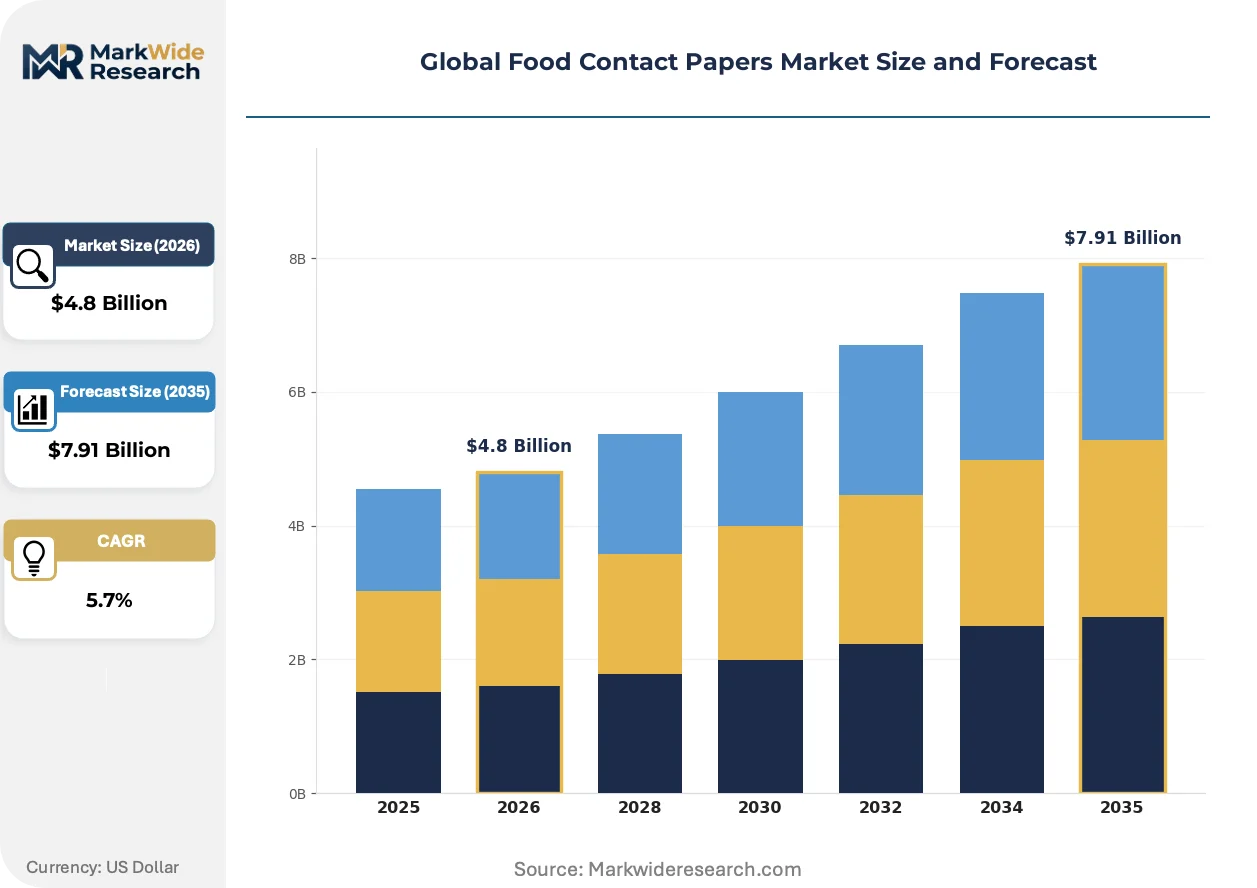
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waxed Paper, Greaseproof Paper, Parchment Paper, Laminated Paper Material: Pulp, Polyester, Polyethylene, Biodegradable Material End User: Food Retailers, Bakeries, Restaurants, Food Processing Units Distribution Channel: Online Retail, Supermarkets, Wholesale Distributors, Specialty Stores |
| Companies Covered | International Paper Company, Mondi Plc, WestRock Company, Amcor plc, Smurfit Kappa Group, Nordic Paper, Ahlstrom-Munksjo Oyj, Georgia-Pacific LLC, Twin Rivers Paper Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Food Contact Papers Market Emerging Trajectories
Barrier paper technology is fragmenting into application-specific platforms as regulatory divergence between jurisdictions forces converters to maintain multiple product lines rather than single global specifications.
Fluorine-free sizing chemistry is modularizing around core platform technologies that can be tuned for specific oil resistance, heat tolerance, and compostability requirements. Quick-service chains in Germany and France pilot these platforms for fried chicken and pastry applications with 12-18 month validation cycles. This modularity is compressing development timelines by allowing converters to reconfigure base formulations rather than engineer from raw materials for each customer specification.
REACH restrictions on per- and polyfluoroalkyl substances are tightening substance migration limits for food contact materials across EU member states. EFSA guidance on total organic fluorine thresholds is forcing reformulation of legacy barrier papers before 2027 enforcement windows. German and French food retailers are responding by requiring EN 13432 compostability certification as a procurement gate, effectively filtering non-compliant suppliers from approved vendor lists.
Consolidated buying by quick-service chains is compressing supplier bases as procurement teams demand single-source accountability for both barrier performance and end-of-life certification. Regional bakery brands in Italy and Spain lose negotiating leverage against integrated converters who control pulp supply and converting capacity. This concentration is most visible in France, where three buying groups now control over half of foodservice paper procurement, dictating specification standards that smaller converters struggle to meet.
Global Food Contact Papers Market Segmentation
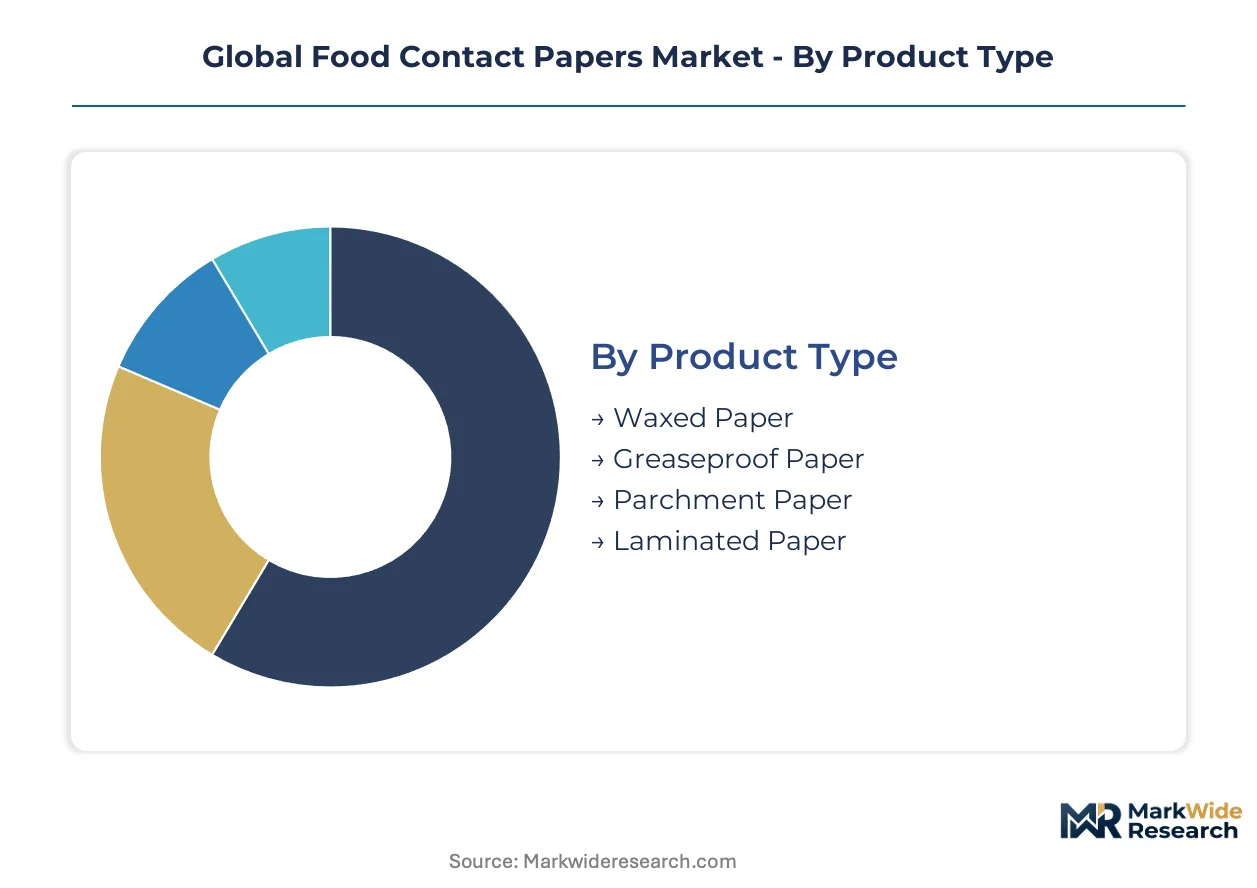
Food contact papers require precise barrier engineering calibrated to end-use thermal and grease-exposure profiles. Segmentation reveals where capital deployment concentrates and which specifications command procurement priority across converter operations.
Product Type:
Parchment paper demands the heaviest upfront investment in fluorine-free sizing chemistry and precision calendering equipment to achieve oil-kit values above 12.
- Parchment Paper:Dual-layer cellulose sheets undergo acid treatment or silicone coating to create non-stick surfaces for baking and wrapping. German quick-service chains specify this grade for oven-ready applications up to 200°C, driving volume through centralized buying groups.
- Greaseproof Paper:Dense, refined pulp sheets achieve grease resistance through mechanical beating rather than chemical sizing. Artisan-to-industrial bakery transitions in France and Italy concentrate demand for certified microwave-safe variants with heat seal compatibility.
- Waxed Paper:Plant-based or paraffin coatings provide moisture barriers for cold-hold applications.
- Laminated Paper:Multi-layer constructions bond cellulose with polymer films for extended shelf-life packaging.
Most installed capacity flows through Parchment Paper. Expansion is steepest in Greaseproof Paper.
Material:
Converter margins vary sharply by feedstock, with biodegradable alternatives requiring new extrusion and coating lines that legacy fluorochemical equipment cannot retrofit.
- Biodegradable Material:Plant-based waxes and polysaccharide coatings replace PFAS chemistry to meet EU Green Deal mandates. California's extended producer responsibility laws reward these materials with reduced fee structures, tilting US retailer procurement specifications toward compostable alternatives.
- Pulp:Hardwood and softwood fiber integration determines barrier consistency and caliper control. Japanese food processors specify unbleached kraft grades under METI-supervised Food Sanitation Act requirements, creating premium tier demand for FSC-certified supply chains.
- Polyester:Film laminates provide high-temperature stability for industrial foodservice applications.
- Polyethylene:Extrusion coatings seal moisture in frozen and refrigerated food packaging.
Biodegradable Material is climbing the fastest as regulatory deadlines compress reformulation timelines.
End User:
Contract structures diverge by buyer scale, with quick-service chains demanding single-source accountability that regional bakeries cannot match.
- Restaurants:Quick-service chains consolidate purchasing around certified grease resistance and microwave-safe properties. North American accounts specify consistent caliper for automated packaging lines, while Western European operators prioritize EN 13432 compostability certification as a procurement gate.
- Bakeries:German artisan-to-industrial transitions create specialized demand for barrier papers with precise thickness control and heat seal compatibility. Smaller Italian and Spanish brands lose leverage against integrated converters who control pulp supply and converting capacity.
- Food Retailers:Supermarket private labels specify dual-use parchment for home baking equipment convergence.
- Food Processing Units:Industrial scale operations require high-volume, fixed-price contracts that expose converters to pulp cost volatility.
Restaurant procurement concentrates the highest volume commitments. Food Retailers are expanding specifications fastest.
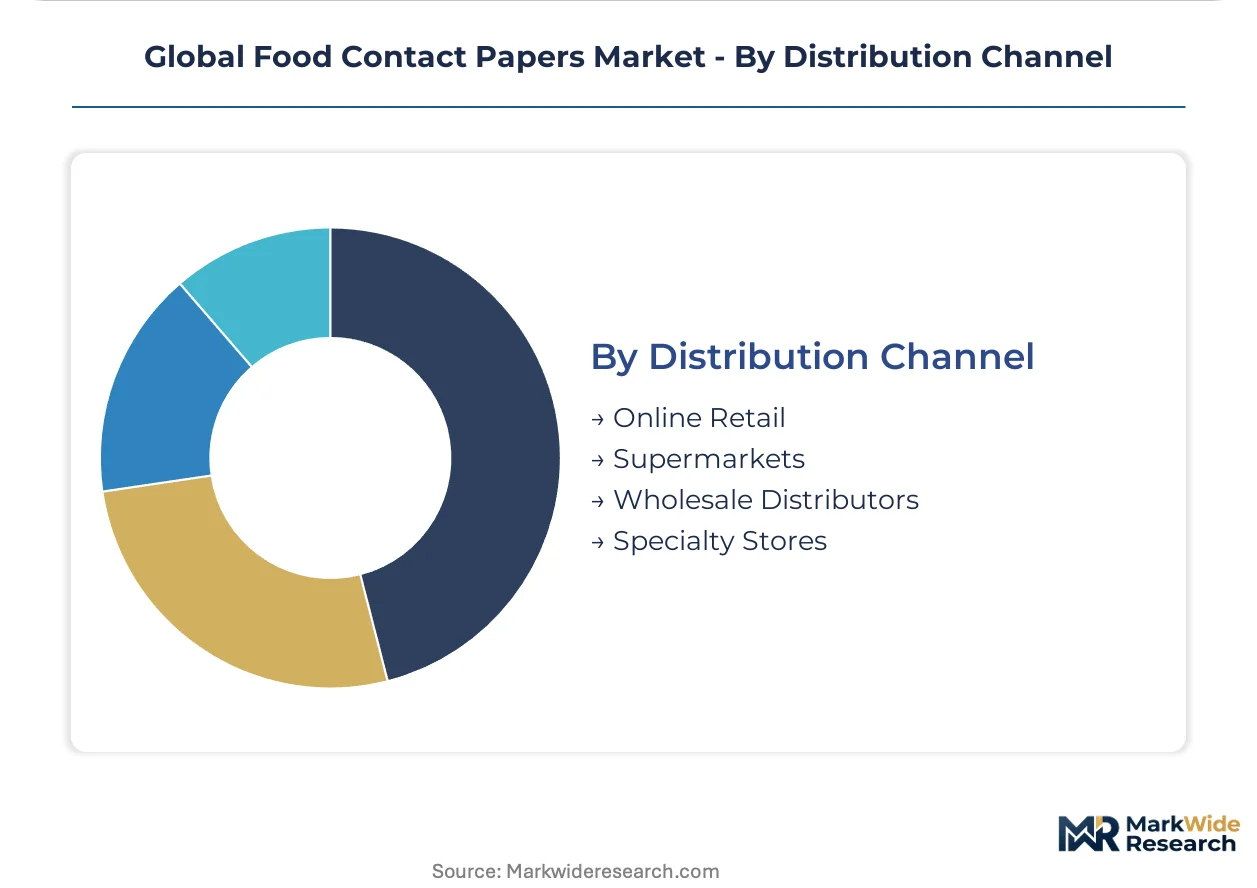
Distribution Channel:
Channel selection determines specification complexity, with wholesale distributors managing the broadest SKU portfolios and online retail demanding standardized e-commerce packaging.
- Wholesale Distributors:Regional and national distributors stock converted rolls and sheets for foodservice and industrial accounts. German and French buying groups route over half their foodservice paper procurement through these channels, dictating barrier performance and certification standards.
- Supermarkets:Retail chains specify private-label parchment and greaseproof paper for home baking segments. US air fryer and steam oven penetration drives dual-use product demand through grocery shelf placement.
- Online Retail:E-commerce platforms standardize packaging formats for direct-to-consumer fulfillment.
- Specialty Stores:Culinary supply retailers stock premium grades for professional and enthusiast bakers.
Wholesale Distributors handle the largest volume flows. Online Retail is gaining share fastest among smaller bakery and restaurant accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping converter location decisions as EU Green Deal compliance costs widen the gap between European and North American production economics. Mills in the United States and Canada capture displaced volume from brands seeking to avoid REACH-mandated reformulation expenses.
United States
Quick-service chains headquartered in Chicago and Atlanta consolidate purchasing around FDA-compliant greaseproof grades with microwave-safe certification. EPA state-delegated programs in California and Maine enforce extended producer responsibility laws that reward compostable packaging with reduced fee structures. Georgia-Pacific operates integrated pulp-to-converting facilities in the Southeast, supplying high-volume accounts with consistent caliper control.
Germany
Artisan-to-industrial bakery transitions in Bavaria and North Rhine-Westphalia create specialized demand for barrier papers with precise thickness tolerance. EFSA guidance on total organic fluorine thresholds forces reformulation of legacy products before enforcement windows tighten. Smurfit Kappa maintains converting flexibility at its Hesse facilities, serving regional brands with custom-printed greaseproof solutions.
France
Three buying groups now control over half of foodservice paper procurement, dictating EN 13432 compostability certification as a vendor-list gate. ANSM enforces migration limits on food contact materials through post-market surveillance programs. Industrial bakeries around Lyon and Paris pilot fluorine-free sizing platforms for fried pastry applications with extended validation cycles.
India
FSSAI modernization of food contact material standards creates first-mover advantage for EN 13432-certified exporters as domestic quick-service chains scale in Mumbai and Bangalore. The PLI scheme for food processing infrastructure accelerates cold-chain packaging demand. Regional converters in Gujarat and Maharashtra retrofit lines to serve emerging quick-service accounts with barrier-treated kraft grades.
Japan
METI-supervised Food Sanitation Act requirements and the positive list system for food contact materials create compliance layers for imported barrier papers. Unbleached kraft specifications from Kansai food processors command premium tiers for FSC-certified supply chains. Ahlstrom-Munksjo anchors technical specialty demand through its filtration and food-grade paper operations serving Tokyo-area industrial bakeries.
Global Food Contact Papers Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated pulp producers capturing quick-service volume while regional converters retain bakery flexibility. The vendor base concentrates around three to five integrated groups controlling North American and European capacity. Strategic archetypes include pulp-integrated majors, specialty converters with certification depth, and regional players with custom-printing capabilities. Dominant competitive moves center on backward integration into hardwood fiber supply and technology licensing for fluorine-free barrier chemistry.
Among North American pulp-integrated groups, International Paper Company and Georgia-Pacific LLC exemplify the scale-driven archetype with captive fiber supply and high-volume contract structures. Mondi Plc and Smurfit Kappa Group occupy positions within the European converter tier, leveraging recycled-content capabilities and converting flexibility respectively. Nordic Paper represents the specialty-grade segment with concentrated exposure to greaseproof and parchment specifications. These anchors demonstrate how geographic integration and certification depth determine competitive positioning across procurement consolidation waves.
| Leading Market Players |
|---|
| International Paper Company |
| Mondi Plc |
| WestRock Company |
| Amcor plc |
| Smurfit Kappa Group |
| Nordic Paper |
| Ahlstrom-Munksjo Oyj |
| Georgia-Pacific LLC |
| Twin Rivers Paper Company |
| Others |
Supply Flow & Price Mechanics
EU Green Deal phase-out mandates for fluorinated compounds gate qualified supply access and premium-tier pricing power, as converters lacking EN 13432 certification face exclusion from German and French buying group vendor lists while certified suppliers command 15-20% markups on compostable barrier grades.
Pricing Analysis
Distributor margins compress the final price to regional bakeries, while direct-to-chain contracts for quick-service accounts bypass wholesale markups entirely. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification tier and volume commitment, with FSC-certified biodegradable grades at the top. Cost compression in standard fluorine-free grades is intensifying because pulp fiber volatility squeezes fixed-price contract profitability. Regional bakery brands exhibit highest price sensitivity, while consolidated quick-service chains leverage scale for locked-in supply agreements.
Supply Chain Analysis
Dual-sourcing requirements from French and German buying groups mandate multi-supplier qualification for fluorine-free sizing chemistry, preventing single-source dependency. Hardwood and softwood fiber supply concentrates in Sweden, Finland, and Canada, while plant-based wax coatings draw from Malaysian and Indonesian palm derivative markets. Single-source vulnerability in certified PFAS-free sizing agents creates supply concentration risk. Distribution runs through wholesale distributors serving foodservice accounts, with direct mill-to-chain relationships capturing high-volume quick-service flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in biodegradable barrier grades where regulatory compliance creates scarcity value and pulp integration insulates against fiber cost volatility.
For Market Incumbents: Anchor market position through backward integration into hardwood fiber supply and captive production of fluorine-free sizing chemistry. Invest in EN 13432 certification depth to defend against specialty converters with modular barrier platforms. Control converting capacity in Germany and France where buying group consolidation intensifies procurement leverage. For New Entrants and Emerging Players: Wholesale distributors represent the most accessible channel partner type for regional bakery accounts underserved by integrated majors. Target India's quick-service expansion as domestic chains scale in Mumbai and Bangalore before FSSAI standards fully mature. Lead with EN 13432-certified greaseproof grades to bypass incumbent certification backlogs. For Investors and Strategic Acquirers: Roll-up economics work for regional specialty converters with custom-printing capabilities because buying group consolidation is displacing fragmented bakery suppliers from approved vendor lists. Focus on 5-10 year viability windows for fluorine-free chemistry platforms. Monitor PFAS testing laboratory queue lengths as the signal for certification bottleneck intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hardwood Fiber Supply | Captive pulp integration insulates International Paper and Georgia-Pacific from spot market volatility. |
| Fluorine-Free Sizing Chemistry Licensing | Technology transfer agreements accelerate converter compliance with EFSA total organic fluorine thresholds. |
| EN 13432 Certification Investment | Compostability certification gates access to French buying group procurement lists. |
| Custom-Printing Converting Flexibility | Regional brand customization commands premium positioning against standardized quick-service grades. |
| Geographic Expansion into India | FSSAI modernization creates first-mover positioning for certified exporters to domestic quick-service chains. |
Methodological Framework
Bottom-up quick-service and bakery demand modeling reconciled against top-down pulp supply and converting capacity tracking forms the analytical core of this study. Primary interviews with paper mill procurement directors, quick-service chain packaging engineers, wholesale distributor category managers, and regulatory compliance officers combined with secondary validation from customs trade data, FEFCO industry reports, FDA food contact notifications, and EFSA scientific opinions. This dual approach enables triangulation between end-use consumption patterns and upstream production economics.
Historical trendline analysis of parchment and greaseproof paper shipments established baseline growth trajectories across the projection horizon. The analytical framework models volume and value through product type, material composition, end-user segment, and distribution channel dimensions, with additional calibration for regulatory compliance tier. CAGRs derive from regression-adjusted growth rates applied to segment-specific demand elasticities, incorporating pulp cost indices and quick-service expansion pipelines as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PFAS regulatory acceleration, biodegradable coating performance breakthroughs, and pulp fiber supply disruptions. Deviation in EU enforcement timeline for total organic fluorine thresholds would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Stationery Films Packaging Market
Paper & Paperboard Packaging
Asia-Pacific Paper Cone Market
Paper & Paperboard Packaging
Mailer Box Market
Paper & Paperboard Packaging
France Paper Packaging Market
Paper & Paperboard Packaging
Machine Glazed Kraft Paper Market
Paper & Paperboard Packaging
Wax-Coated Paper Market
Paper & Paperboard Packaging
Australia Paper Packaging Market
Paper & Paperboard Packaging
North America Paper Bags Market
Paper & Paperboard Packaging
South Africa Paper Packaging Market
Paper & Paperboard Packaging
Paper Bottles Market
Paper & Paperboard Packaging
Non-Tacky Transfer Paper Market
Paper & Paperboard Packaging
South East Asia Corrugated Packaging Market
Paper & Paperboard Packaging
Corrugated Board Market
Paper & Paperboard Packaging
Composite Paper Cans Market
Paper & Paperboard Packaging
Global Multi Depth Corrugated Boxes Market
Paper & Paperboard Packaging
China Corrugated Packaging Market