
 South East Asia Corrugated Packaging Market | 2026-2036
South East Asia Corrugated Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
South East Asia Corrugated Packaging Market Outlook
Vietnam's northern industrial corridor is reconfiguring regional supply dynamics as new containerboard mills come online near Haiphong and Bac Ninh. SCG Packaging Public Company Limited leverages its integrated pulp-to-box network across Thailand and Vietnam to sustain margin control. Smurfit WestRock anchors regional volume through its recycled fiber collection and box plant network. Oji Holdings Corporation differentiates via high-performance coated linerboard grades for electronics export packaging.
South East Asia corrugated packaging consists of fluted paperboard sheets laminated between flat linerboards, typically constructed from recycled Kraft fibers with burst strengths ranging from 150 to 350 lb/in² to protect goods through humid tropical logistics. Its primary purpose is to provide stackable, printable, and cost-efficient protective containment for manufactured products moving through multi-modal distribution. Recycled paperboard dominates material flows due to established waste collection infrastructure and buyer sustainability mandates, while virgin paperboard occupies premium tiers requiring superior print fidelity. Die-cut box formats are gaining share among electronics and pharmaceutical end users demanding exact-fit protection with reduced void fill.
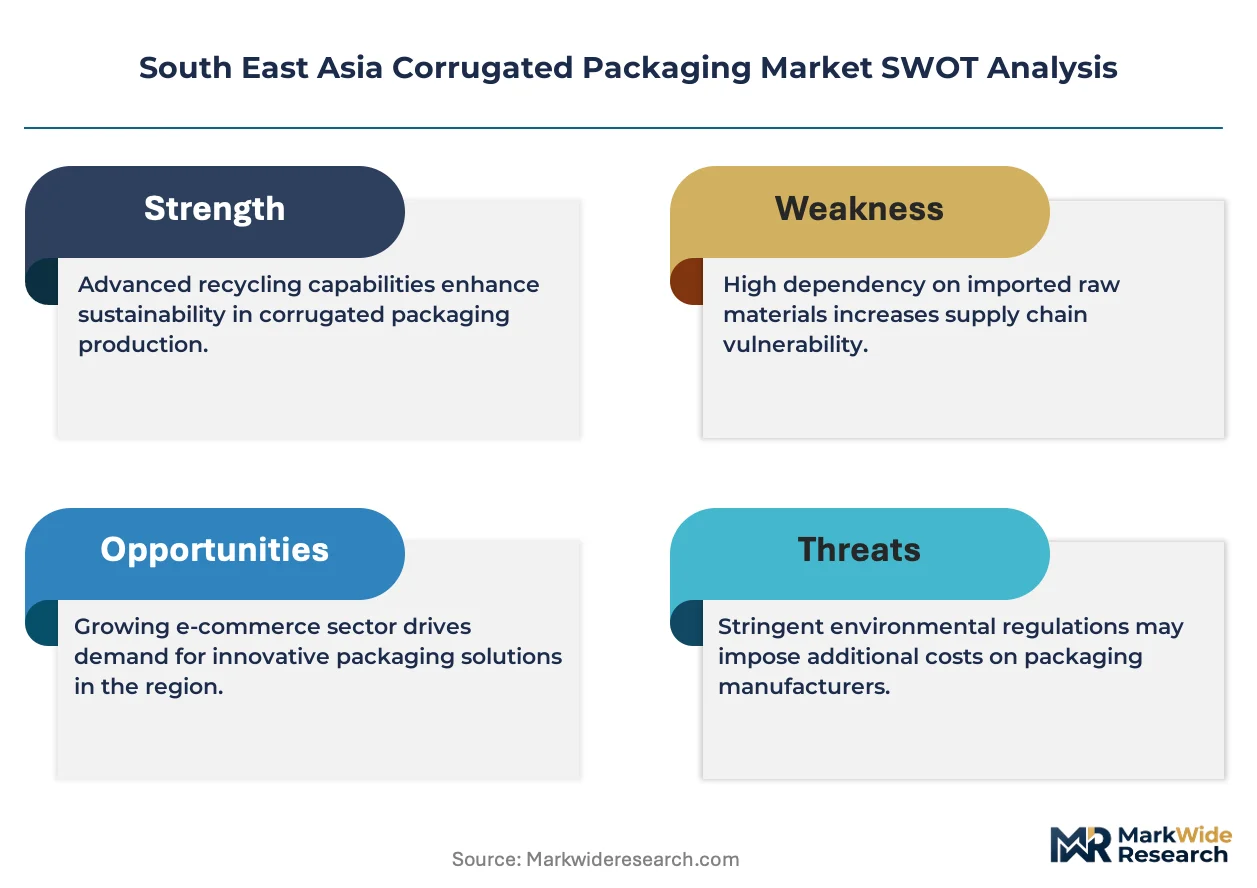
Thailand's Board of Investment, Vietnam's Ministry of Natural Resources and Environment circular economy directives, and Indonesia's SNI packaging standards collectively elevate compliance costs while favoring operators with certified recycling chains and emissions monitoring systems. These frameworks effectively restrict informal recyclers from supplying major brand owners and redirect procurement toward integrated producers with verified chain-of-custody documentation. Stakeholders must monitor how ASEAN harmonization of packaging extended producer responsibility rules reshapes feedstock access and capital deployment priorities across the region.
Market Dynamics
E-commerce fulfillment volumes are compressing order-to-delivery windows across Thailand, Vietnam, and Indonesia, forcing corrugated converters to relocate box plants adjacent to fulfillment centers rather than traditional manufacturing zones. This geographic reconfiguration is redrawing procurement radii and feedstock sourcing patterns across the region.
Growth Catalysts
- Thailand's Board of Investment green manufacturing incentives:Tax holidays and import duty exemptions for recycled fiber processing equipment are accelerating capital deployment toward circular production systems.
- Electronics clustering in Vietnam's northern provinces:Samsung, Foxconn, and Intel suppliers generate sustained demand for high-performance coated linerboard with precise dimensional stability requirements.
- Digital print integration:Water-based inkjet systems enable short-run customization for seasonal consumer goods without plate changeover delays.
Market Restraints
- Old corrugated container (OCC) price volatility:Thai and Vietnamese mills compete for limited regional recovered fiber supply against Chinese buyers, creating input cost instability.
- Indonesian SNI packaging standards compliance:Mandatory certification timelines extend 8-14 months, freezing informal recyclers out of formal supply chains.
- Plastic corrugated substitution in fresh produce:Polypropylene twin-wall sheets offer superior moisture resistance for seafood and tropical fruit exports.
Strategic Opportunities
- Myanmar and Cambodia logistics infrastructure:Underdeveloped domestic box manufacturing creates import-dependent markets for Thai and Vietnamese integrated producers.
- Pharmaceutical cold chain expansion:Temperature-validated insulated corrugated shippers address vaccine and biologics distribution requirements across ASEAN.
- Vietnam's circular economy directives:Extended producer responsibility frameworks mandate post-consumer collection targets that favor operators with verified chain-of-custody systems.
Industry Challenges
- Skilled die-cut tooling technicians:Precision rotary die maintenance and CAD nesting optimization require training pipelines that regional technical institutes have not scaled.
- Legacy ERP integration with IoT sensors:Real-time moisture monitoring and predictive maintenance systems clash with installed MES architectures at mid-tier converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South East Asia Corrugated Packaging Market |
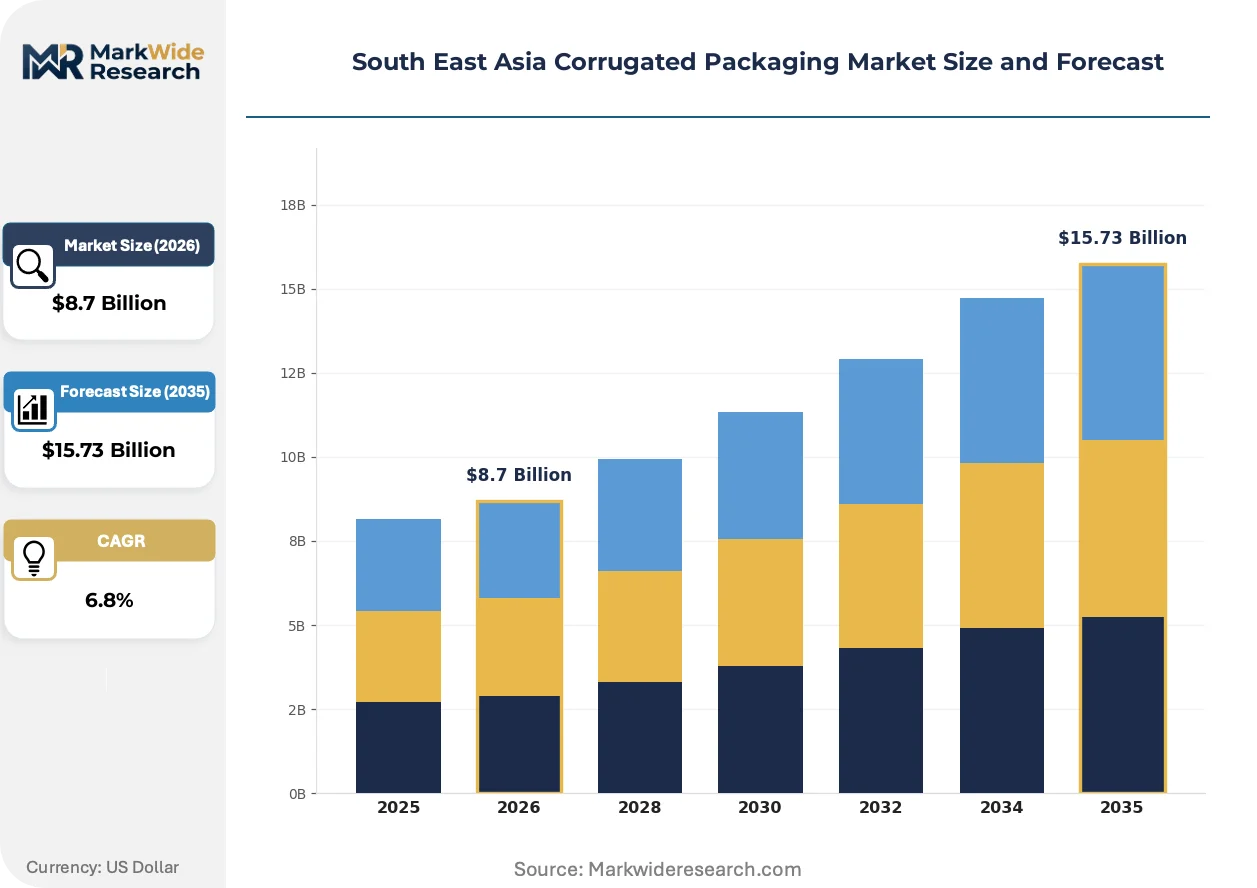
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular Slotted Container, Half Slotted Container, Letterbox Container, Die-Cut Box End Use Industry: Food & Beverage, Electronics, Pharmaceutical, Consumer Goods Material: Recycled Paperboard, Virgin Paperboard, Composite Materials, Coated Paperboard Design Type: Flat Pack, Foldable, Custom Shape, Multi-Depth |
| Companies Covered | Toppan Inc., Thai Packaging & Printing Public Company Limited, SCG Packaging Public Company Limited, Trio Paper Mills Sdn. Bhd., Harta Packaging Industries (Selangor) Sdn Bhd, Rengo Co., Ltd., Smurfit WestRock, Sarnti Packaging Co., Ltd., Oji Holdings Corporation, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South East Asia Corrugated Packaging Market Strategic Shifts
Digital workflow integration and regulatory tightening around fiber provenance are converging to reshape how corrugated packaging is specified, produced, and tracked across South East Asian supply chains.
AI-driven prepress optimization is digitizing artwork adaptation and structural design workflows. Electronics exporters in Bac Ninh and Haiphong industrial zones now demand 24-hour turnaround on packaging prototypes. This compression is eliminating manual proofing stages and collapsing traditional supplier response times.
Thailand's Board of Investment carbon accounting requirements and Vietnam's Ministry of Natural Resources and Environment circular economy directives are mandating Scope 3 emissions disclosure. Brand owners now require mass-balance documentation for recycled fiber content. Integrated producers with certified recycling chains are capturing procurement contracts that informal competitors cannot access.
Consolidated buying by regional e-commerce platforms is displacing fragmented distributor networks. Shopee and Lazada logistics subsidiaries now contract directly with box plants for standardized fulfillment packaging. This channel compression is most visible in Bangkok and Ho Chi Minh City metropolitan zones where platform-operated sorting centers concentrate volume.
South East Asia Corrugated Packaging Market Segmentation
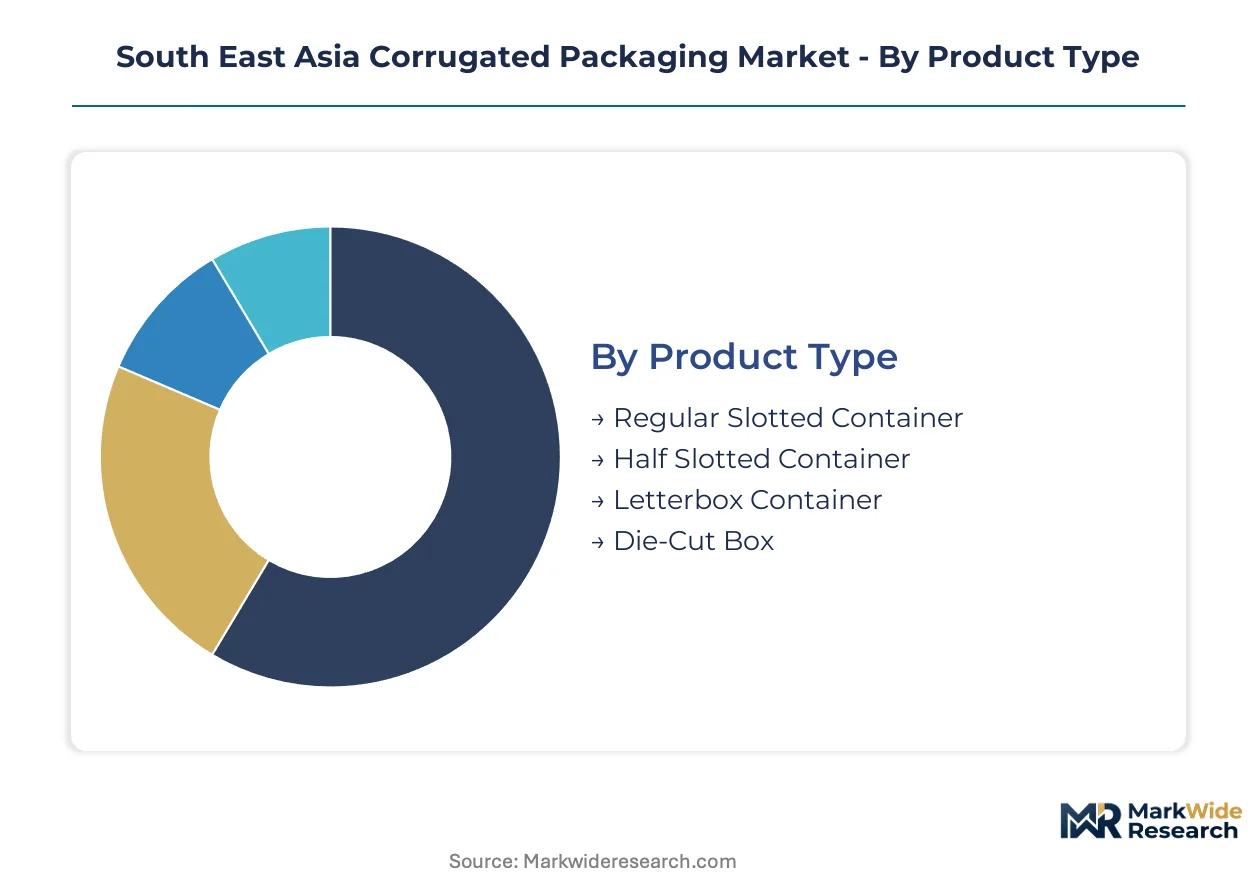
Corrugated packaging specifications vary sharply across South East Asian supply chains, with electronics exporters demanding precision-engineered formats while food distributors prioritize cost-efficient standardization. Understanding these segment boundaries reveals where converter investments in tooling and certification yield differentiated returns.
Product Type:
After-sales-service intensity diverges dramatically across box formats, with die-cut tooling requiring dedicated technician support while standard slotted containers run on generic maintenance schedules.
- Regular Slotted Container:The foundational RSC format employs four flaps meeting at the center with standard 0201 style construction, delivering maximum manufacturing efficiency through rotary die-cutters without setup changeovers. Vietnam's northern electronics corridors source RSCs in bulk for component staging totes, though Samsung suppliers increasingly specify exact-fit alternatives for finished-goods export.
- Die-Cut Box:Precision-cut formats eliminate void space through CAD-optimized nesting algorithms, reducing dimensional weight charges for air-freighted electronics from Bac Ninh and Haiphong industrial zones. Foxconn suppliers mandate die-cut specifications with ±0.5mm tolerance for high-value semiconductor packaging.
- Half Slotted Container:Open-top designs with single flap sets suit palletized bulk goods where top access speeds warehouse handling.
- Letterbox Container:Slim-profile formats align with e-commerce platform dimensional templates for last-mile efficiency in Bangkok and Ho Chi Minh City fulfillment networks.
By volume, Regular Slotted Container leads. By growth pace, Die-Cut Box is ahead.
End Use Industry:
Cost tier stratification separates commodity food-grade specifications from premium electronics and pharmaceutical validation requirements.
- Electronics:High-performance linerboard with coated surfaces protects moisture-sensitive components through humid tropical logistics, with Intel suppliers in Ho Chi Minh City demanding ESD-dissipative treatments and VCI corrosion inhibitors. Thai and Vietnamese mills compete for these contracts through certified fiber provenance documentation.
- Food & Beverage:Grease-resistant barriers and FDA-compliant coatings address seafood and tropical fruit export requirements, though polypropylene substitution gains share in fresh produce cold chains.
- Pharmaceutical:Temperature-validated insulated shippers with phase-change materials serve vaccine distribution across ASEAN cold chain expansion.
- Consumer Goods:Seasonal demand spikes from Shopee and Lazada promotional cycles drive short-run digital print adoption.
Food & Beverage commands volume share. Electronics exhibits the steepest expansion trajectory.
Material:
Supply concentration around recycled fiber collection networks determines which mills capture formal procurement contracts from sustainability-mandated brand owners.
- Recycled Paperboard:Established OCC collection infrastructure across Thailand and Vietnam feeds integrated mills with verified chain-of-custody documentation, satisfying Thailand's Board of Investment circular economy incentives. Chinese buyers compete aggressively for limited regional recovered fiber supply.
- Coated Paperboard:Clay-coated surfaces enable high-fidelity flexographic printing for consumer electronics branding requirements.
- Virgin Paperboard:Superior burst strength and print fidelity serve premium tiers where fiber provenance certification matters less than performance specifications.
- Composite Materials:Hybrid constructions combining fiber with moisture barriers address niche pharmaceutical and fresh produce applications.
Recycled Paperboard dominates tonnage. Coated Paperboard is climbing fastest.
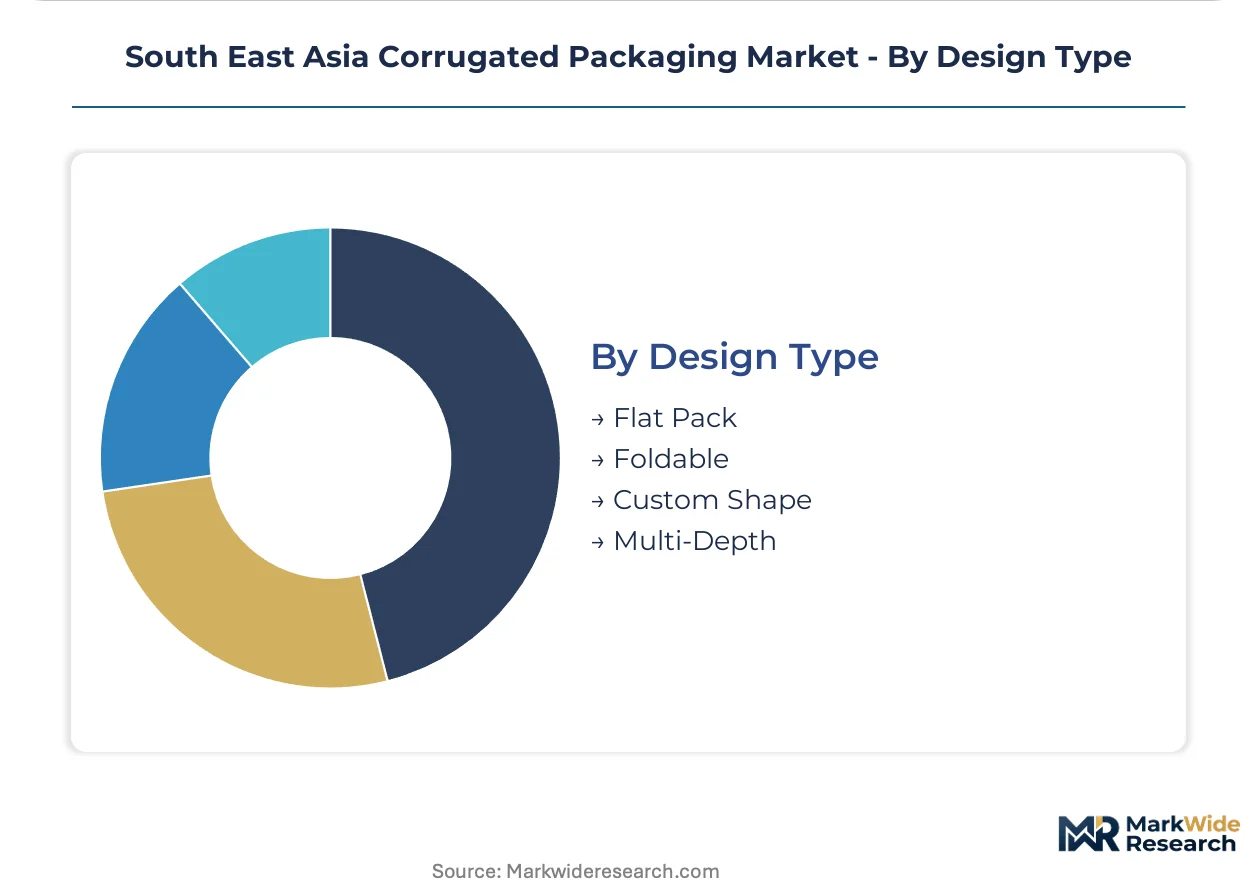
Design Type:
Customer type segmentation separates platform-standardized formats from bespoke enterprise specifications.
- Flat Pack:Knock-down designs minimize storage cube and shipping cost for importers in Myanmar and Cambodia where domestic manufacturing remains underdeveloped.
- Foldable:Pre-scored constructions enable rapid assembly without tooling at destination fulfillment centers.
- Custom Shape:Brand-differentiated structural designs require dedicated die investments and longer procurement cycles.
- Multi-Depth:Adjustable height formats reduce SKU proliferation for e-commerce platforms managing diverse product dimensions.
Flat Pack leads on volume throughput. Multi-Depth formats are gaining share fastest among platform logistics operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's Ministry of Natural Resources and Environment anchors regulatory momentum across the region through circular economy directives that mandate post-consumer collection targets and emissions disclosure frameworks.
Vietnam
Electronics exporters in Bac Ninh and Haiphong industrial zones generate sustained demand for high-performance coated linerboard with precise dimensional stability requirements. The Ministry of Natural Resources and Environment circular economy directives mandate extended producer responsibility frameworks that favor operators with verified chain-of-custody systems. Samsung and Foxconn suppliers in northern provinces are compressing packaging prototype turnaround times to 24 hours.
Thailand
The Board of Investment green manufacturing incentives accelerate capital deployment toward recycled fiber processing capacity with tax holidays and import duty exemptions. Thailand's Board of Investment carbon accounting requirements now mandate Scope 3 emissions disclosure from packaging suppliers. SCG Packaging leverages its integrated pulp-to-box network across Bangkok and eastern seaboard manufacturing zones to sustain margin control.
Indonesia
Shopee and Lazada logistics subsidiaries contract directly with box plants for standardized fulfillment packaging in Jakarta and Surabaya metropolitan zones. Indonesian SNI packaging standards compliance timelines extend 8-14 months, freezing informal recyclers out of formal supply chains. Polypropylene twin-wall sheets gain share in fresh produce cold chains for seafood and tropical fruit exports.
Malaysia
Trio Paper Mills and Harta Packaging Industries anchor recycled paperboard supply for consumer goods distribution through Selangor and Penang manufacturing corridors. The country's national environmental regulator enforces waste collection infrastructure standards that elevate compliance costs for uncertified operators. Die-cut box formats gain share among electronics and pharmaceutical end users in Penang's semiconductor cluster.
Myanmar and Cambodia
Underdeveloped domestic box manufacturing creates import-dependent markets for Thai and Vietnamese integrated producers. Flat pack and knock-down designs minimize storage cube for importers where domestic manufacturing remains underdeveloped. Yangon and Phnom Penh logistics infrastructure gaps force reliance on cross-border supply from established regional producers.
South East Asia Corrugated Packaging Market Competitive Environment
Capability concentration sits with integrated pulp-to-box networks; scale advantage sits with multi-country recycled fiber collection systems. The vendor base organizes around three archetypes: integrated producers with certified recycling chains, regional converters with platform logistics contracts, and specialty coated linerboard suppliers. Dominant competitive moves include geographic relocation of box plants adjacent to fulfillment centers and backward integration into recovered fiber collection networks.
Within the integrated producer tier, SCG Packaging Public Company Limited and Smurfit WestRock exemplify operators with multi-country network coverage. Oji Holdings Corporation occupies a position among specialty coated linerboard suppliers serving electronics export packaging requirements. These three companies represent the strategic archetypes reshaping procurement patterns as brand owners mandate mass-balance documentation and verified fiber provenance.
| Leading Market Players |
|---|
| Toppan Inc. |
| Thai Packaging & Printing Public Company Limited |
| SCG Packaging Public Company Limited |
| Trio Paper Mills Sdn. Bhd. |
| Harta Packaging Industries (Selangor) Sdn Bhd |
| Rengo Co., Ltd. |
| Smurfit WestRock |
| Sarnti Packaging Co., Ltd. |
| Oji Holdings Corporation |
| Others |
Value Chain & Pricing Dynamics
Recovered fiber collection concentration across Thailand and Vietnam feeds directly into margin capture at integrated linerboard mills. Chinese buyers competing for limited regional OCC supply compress converter margins while rewarding operators with captive collection networks.
Pricing Analysis
Price spreads between Bangkok and Ho Chi Minh City box plants reflect logistics cost differentials and local OCC availability rather than quality tiering. Pricing stratifies across premium, standard, and economy tiers based on certification grade and fiber provenance documentation. Cost compression in standard-grade RSCs is intensifying because Chinese mills bid aggressively for regional recovered fiber. E-commerce platforms exhibit highest price sensitivity through consolidated volume tenders, while pharmaceutical cold chain buyers prioritize validated performance over unit cost.
Supply Chain Analysis
Old corrugated container supply draws from collection networks across Thailand, Vietnam, and Indonesia where informal aggregators compete with mill-owned collection fleets. Raw material dependencies center on recovered fiber grades, starch adhesives, and water-based inks. Single-source vulnerability sits with Chinese buyers who can outbid regional mills during price spikes. Distribution runs through converter-owned box plants positioned adjacent to fulfillment centers rather than traditional industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as e-commerce platform procurement bypasses distributor networks and demands specialized formats. This channel compression rewards agile operators with digital print capabilities and rapid prototyping infrastructure.
For Market Incumbents: Harden fiber security through backward integration into collection networks before Chinese buyers lock up regional OCC supply. Defend against plastic corrugated substitution in fresh produce by certifying moisture-resistant barrier coatings. Prioritize die-cut tooling technician training pipelines to sustain precision-format margins.
For New Entrants and Emerging Players: Pursue Myanmar and Cambodia import-dependent markets with flat-pack knock-down designs that minimize shipping cube. Target pharmaceutical cold chain validation as the most penetrable premium segment. Enter through temperature-qualified shipper partnerships with ASEAN vaccine distributors.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-tier Vietnamese converters lacking chain-of-custody certification but holding platform logistics contracts. Five-to-ten-year viability hinges on regulatory compliance capex rather than volume scale. Watch Vietnam's Ministry of Natural Resources and Environment EPR enforcement timelines as the signal for feedstock access inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recovered Fiber Collection | Captive OCC supply insulates Thai and Vietnamese mills from Chinese buyer competition. |
| Die-Cut Tooling Technician Training Programs | CAD nesting optimization capabilities address Foxconn supplier tolerance requirements. |
| Temperature-Validated Shipper Certification | Phase-change material integration captures ASEAN vaccine distribution contracts. |
| Digital Print Workflow Investment | Water-based inkjet systems enable 24-hour prototype turnaround for electronics exporters. |
| Fulfillment Center Adjacent Plant Relocation | Shopee and Lazada direct contracting rewards geographic proximity to sorting centers. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of trade customs data, mill capacity disclosures, and regulatory filings across Thailand, Vietnam, and Indonesia. Primary interviews engaged corrugated plant managers, procurement leads at electronics exporters, sustainability officers at brand owners, and logistics directors at e-commerce platforms. Secondary sources include Thailand Board of Investment incentive announcements, Vietnam Ministry of Natural Resources and Environment circular economy directives, Indonesian SNI standards documentation, and ASEAN trade flow databases. Bottom-up volume estimates triangulate against top-down demand aggregation from end-use industries.
Forecast inputs incorporate product type evolution, material grade shifts, and end-use industry growth patterns across the projection horizon. Segmentation dimensions modeled include box format specifications, linerboard material grades, design types, and geographic production clusters. CAGRs derive from trend extrapolation adjusted for regulatory phase-in schedules and capacity expansion timelines. Industry-specific inputs include e-commerce fulfillment center buildout pipelines and electronics export volume trajectories from northern Vietnamese industrial zones.
Macroeconomic conditions sit as an overlay; deviation in regional currency volatility, energy costs, or Chinese recovered fiber import policy would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement timelines and platform procurement consolidation. Cross-checking against mill utilization rates and OCC spot price indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Wax-Coated Paper Market
Paper & Paperboard Packaging
Cardboard Tubs Market
Paper & Paperboard Packaging
Egypt Paper Packaging Market
Paper & Paperboard Packaging
Mottled Test Liner Market
Paper & Paperboard Packaging
Waxing Base Paper Market
Paper & Paperboard Packaging
Sublimation Paper Market
Paper & Paperboard Packaging
Tissue and Hygiene Paper Packaging Market
Paper & Paperboard Packaging
Wrapping Paper Market
Paper & Paperboard Packaging
Australia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Machine Glazed Paper Market
Paper & Paperboard Packaging
Kraft Paper Bags Market
Paper & Paperboard Packaging
Paperboard Bowl Market
Paper & Paperboard Packaging
Indonesia Paper Packaging Market
Paper & Paperboard Packaging
Plywood Box Market
Paper & Paperboard Packaging
Postage Stamp Paper Market
Paper & Paperboard Packaging
India Paper and Paperboard Packaging Market