
 Coated Sack Kraft Paper Market | 2026-2036
Coated Sack Kraft Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Coated Sack Kraft Paper Market Outlook
Food packaging is expanding its share of coated sack kraft paper offtake as consumer brands reduce plastic dependency. Mondi Group leverages integrated pulp-to-paper operations across European mills to sustain cost-advantaged supply of barrier-coated grades. BillerudKorsnäs specializes in high-performance packaging papers with tailored grease and moisture resistance for premium food applications. Segezha Group anchors supply to Russian and CIS agricultural markets through extensive forestry holdings and domestic converting networks.
Coated sack kraft paper consists of unbleached or semi-bleached kraft pulp sheets treated with functional coatings such as polyethylene, wax, or bio-based barriers to achieve moisture resistance and heat-sealability for demanding packaging environments. The substrate typically ranges from 70 to 120 grams per square meter, with coating weights adjusted to specific barrier requirements for cement, chemicals, or food contact. Valve and square bottom formats dominate industrial applications where filling speed and pallet stability matter, while flat and gusseted configurations serve retail and agricultural channels where cost efficiency prevails. Heavyweight and specialty grades capture margin pools in chemical and food packaging segments where failure costs exceed material premiums, whereas lightweight and recycled grades compete on tonnage in bulk cement and mineral shipping.
FDA food contact regulations and EPA emissions standards shape product formulation and mill compliance investments in the United States, while REACH and EU Packaging and Packaging Waste Regulation mandate recyclability disclosures and restrict certain coating chemistries across European markets. The EU Green Deal and associated circular economy action plans are pressing converters to demonstrate fiber sourcing traceability and post-consumer recyclability for coated constructions. Stakeholders must monitor evolving bio-based coating performance against incumbent polyethylene barriers and assess capital allocation between specialty grade expansion and recycled fiber integration.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are forcing converters to abandon plastic laminates in favor of recyclable coated kraft constructions, restructuring procurement priorities across European food and industrial packaging channels.
Growth Catalysts
- REACH chemical restrictions:European coating formulators are accelerating bio-based barrier development to replace polyethylene chemistries facing registration scrutiny.
- Bakery sector migration:Artisan and industrial bread producers are adopting grease-resistant coated kraft for direct food contact applications previously served by plastic films.
- German converting cluster density:Concentrated paper machinery and coating capacity in the Rhineland-Palatinate and Baden-Württemberg regions enable rapid specialty grade scale-up.
Market Restraints
- Softwood pulp price volatility:Nordic and Baltic timber supply disruptions transmit directly to unbleached kraft furnish costs, compressing converter margins.
- Coating chemistry concentration:Polyethylene extrusion equipment and resin supply chains remain dominated by petrochemical majors with limited paper industry integration.
- Heat-seal performance gap:Bio-based barrier coatings still exhibit seal strength and moisture transmission deficiencies against incumbent PE standards in high-humidity cement applications.
Strategic Opportunities
- Polish packaging expansion:Underdeveloped domestic coated kraft capacity relative to Central European food export growth creates import substitution potential.
- EU Green Deal circular economy procurement:Public sector food service contracts now mandate demonstrable fiber traceability and post-consumer recyclability.
- Digital printing convergence:Water-based inkjet systems paired with microporous coatings enable short-run customized packaging for regional food brands.
Industry Challenges
- Barrier chemist talent scarcity:Formulation expertise spanning paper physics, polymer science, and food contact compliance concentrates at a handful of European research institutes.
- Multi-standard certification timelines:Simultaneous FDA, EU 10/2011, and BfR compliance documentation extends product launch cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coated Sack Kraft Paper Market |
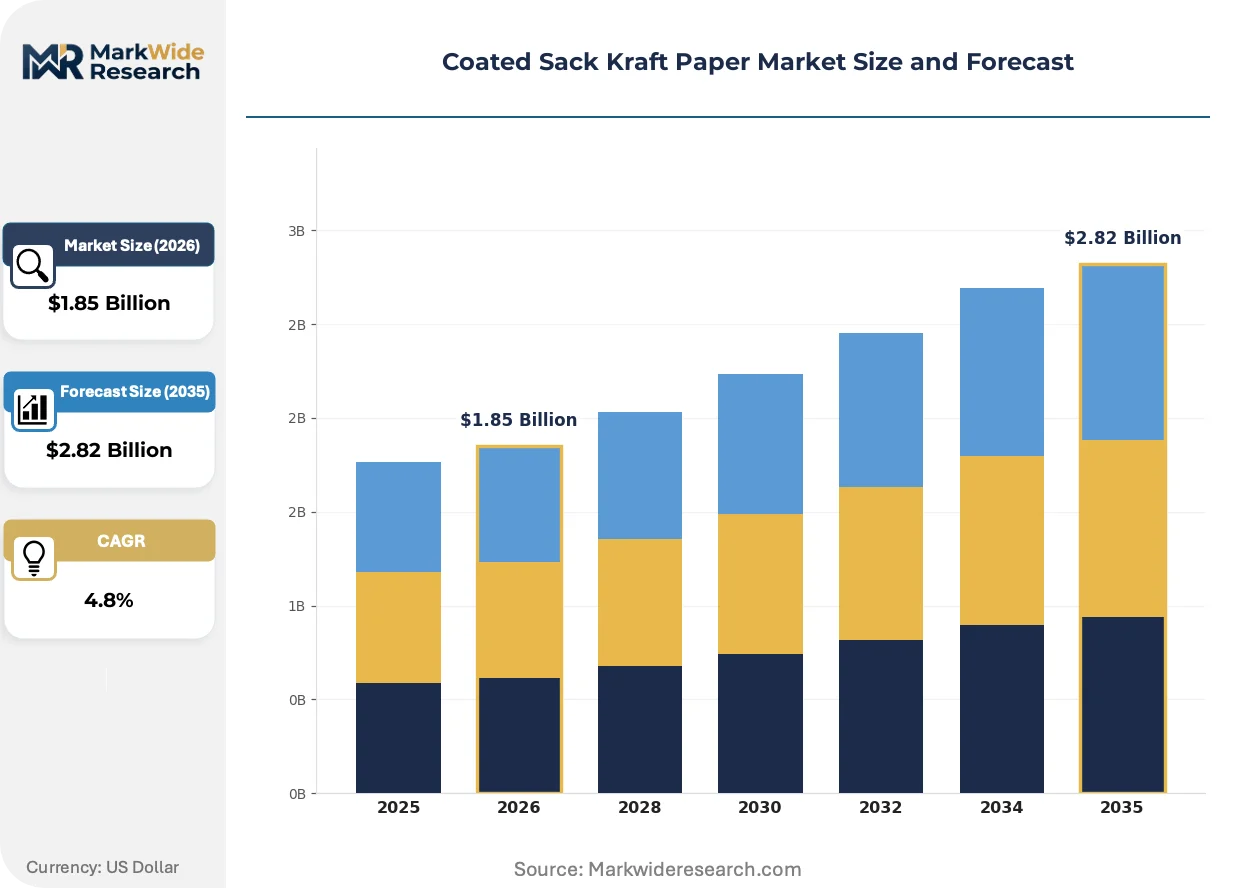
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.82 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat, Gusseted, Square Bottom, Valve End User: Agriculture, Food Packaging, Cement, Chemical Grade: Heavyweight, Lightweight, Specialty, Recycled Application: Shipping, Storage, Retail, Industrial |
| Companies Covered | Mondi Group, WestRock Company, Segezha Group, International Paper Company, Smurfit Kappa Group, Canfor Corporation, BillerudKorsnäs, Nordic Paper, Gascogne Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coated Sack Kraft Paper Market Strategic Shifts
Bio-based coating chemistry is overtaking conventional polyethylene barriers as the dominant R&D priority, while regulatory disclosure requirements and buyer procurement centralization reshape competitive access patterns.
Water-based dispersion coatings incorporating modified starch and plant-derived waxes are overtaking solvent-based and extruded polyethylene systems in European food packaging specifications. Premium chocolate and coffee roasters in Belgium and Switzerland are qualifying these constructions for direct product contact. The shift is overtaking legacy coating equipment investments and forcing mill capital allocation toward aqueous dispersion lines.
EU Packaging and Packaging Waste Regulation extended producer responsibility frameworks now mandate recyclability testing and labeling for all coated paper constructions placed on European markets. Industrial packaging converters must demonstrate fiber recovery rates above defined thresholds through accredited laboratory protocols. Cement and chemical shippers in Germany and France are prioritizing suppliers with pre-certified circular construction documentation.
Consolidated procurement by pan-European food retail chains is compressing supplier qualification cycles and favoring multi-site certified producers. Regional coating mills without pan-European logistics footprints are losing access to annual framework agreements. The pattern is most visible in Nordic and Benelux markets where centralized buying functions at Ahold Delhaize and Coop Denmark dominate packaging specification authority.
Coated Sack Kraft Paper Market Segmentation
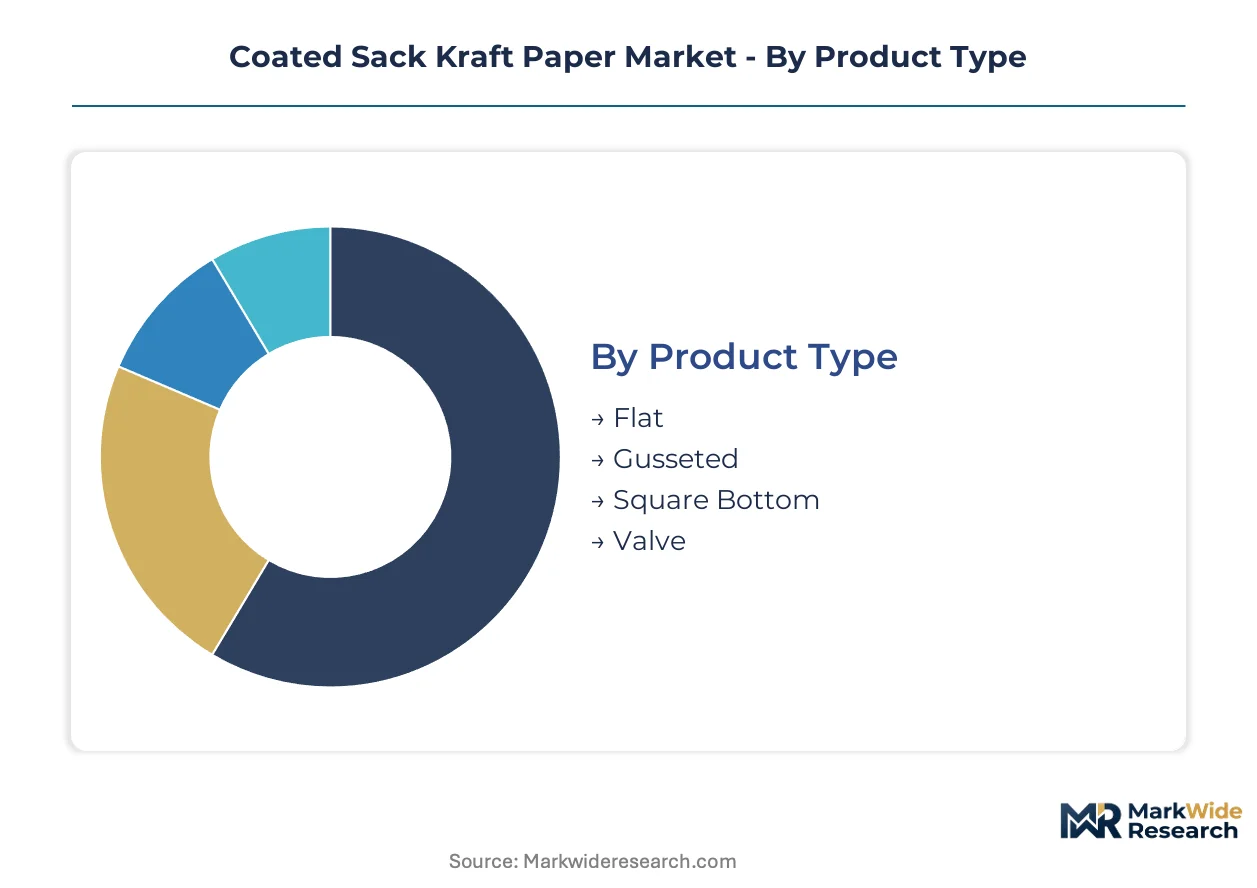
Coated sack kraft paper producers allocate capital across divergent equipment configurations depending on which segment mix they target. Bag geometry, barrier requirements, and end-use certification standards each demand distinct coating lines and converting machinery.
Product Type:
Valve and square bottom formats require the heaviest upfront investment in automated bottom-forming and sealing equipment.
- Valve:Self-closing valve constructions incorporate precision-formed filling apertures with integrated adhesive strips for rapid cement and mineral discharge. German cement distributors in North Rhine-Westphalia specify valve formats for automated filling lines where throughput exceeds 2,000 bags per hour. REACH-compliant coating chemistries for valve constructions face stricter scrutiny due to dust exposure risks during handling.
- Square Bottom:Cross-bottom sealed constructions deliver pallet stability through flat base profiles that interlock during stacking. Belgian chocolate and Swiss coffee roasters specify square bottom formats for retail shelf presentation where vertical display matters. The format commands coating equipment with precise creasing and bottom-sealing stations that add 30-40% to line capital costs versus flat configurations.
- Flat:Single-sheet constructions serve cost-sensitive agricultural seed and feed applications where manual filling prevails. Polish grain exporters favor flat formats for containerized shipping to Middle Eastern markets.
- Gusseted:Side-folded constructions expand volume capacity for irregular bulk materials like fertilizer blends. French agrochemical distributors specify gusseted formats for seasonal product variations.
Most installed capacity flows through Valve configurations. Expansion is steepest in Square Bottom as food brands abandon plastic laminate alternatives.
End User:
Customer procurement patterns split between specification-driven food contact compliance and price-driven bulk commodity shipping.
- Food Packaging:Direct-contact bakery and dry goods applications demand FDA and EU 10/2011 compliant barrier coatings with documented migration testing. Italian pasta producers and Spanish olive oil packers are consolidating supplier bases to mills with dual-certification capabilities. BfR-compliant grease resistance specifications for butter and margarine applications command 15-20% coating weight premiums over standard moisture barriers.
- Cement:High-tonnage construction material shipping prioritizes tear resistance and moisture protection during outdoor storage. Turkish cement exporters through Mediterranean ports specify coated kraft with polyethylene barriers exceeding 20 grams per square meter for humidity protection.
- Agriculture:Seed, feed, and fertilizer applications balance cost efficiency with seasonal weather exposure. Ukrainian grain traders favor lightweight coated grades for Black Sea container routes.
- Chemical:Industrial powder and granule packaging requires chemical-resistant barriers and UN-certified constructions for hazardous material transport. German specialty chemical producers in Ludwigshafen specify multi-ply coated constructions with intermediate barrier films.
Food Packaging commands the highest coating sophistication. Cement retains the largest absolute tonnage.
Grade:
Fiber sourcing and coating complexity create four distinct margin tiers with divergent capital requirements.
- Specialty:Custom-formulated barriers combining grease resistance, oxygen scavenging, and heat-sealability for premium food applications. Modified starch and plant-derived wax dispersions replace polyethylene in Belgian chocolate packaging specifications.
- Heavyweight:Basis weights above 100 grams per square meter serve dense mineral and chemical products where puncture resistance prevents bag failure. Nordic pulp integration supports consistent furnish quality for heavyweight production.
- Lightweight:Sub-90 gram constructions compete on fiber efficiency for bulk cement and construction aggregate shipping. Baltic mills leverage softwood pulp proximity for lightweight grade cost positions.
- Recycled:Post-consumer fiber integration meets EU Green Deal circular economy procurement mandates for public sector food service contracts. French hospital and school catering tenders now specify minimum recycled content thresholds.
Specialty grades absorb the most R&D expenditure. Recycled fiber integration is gaining share fastest among sustainability-mandated buyers.
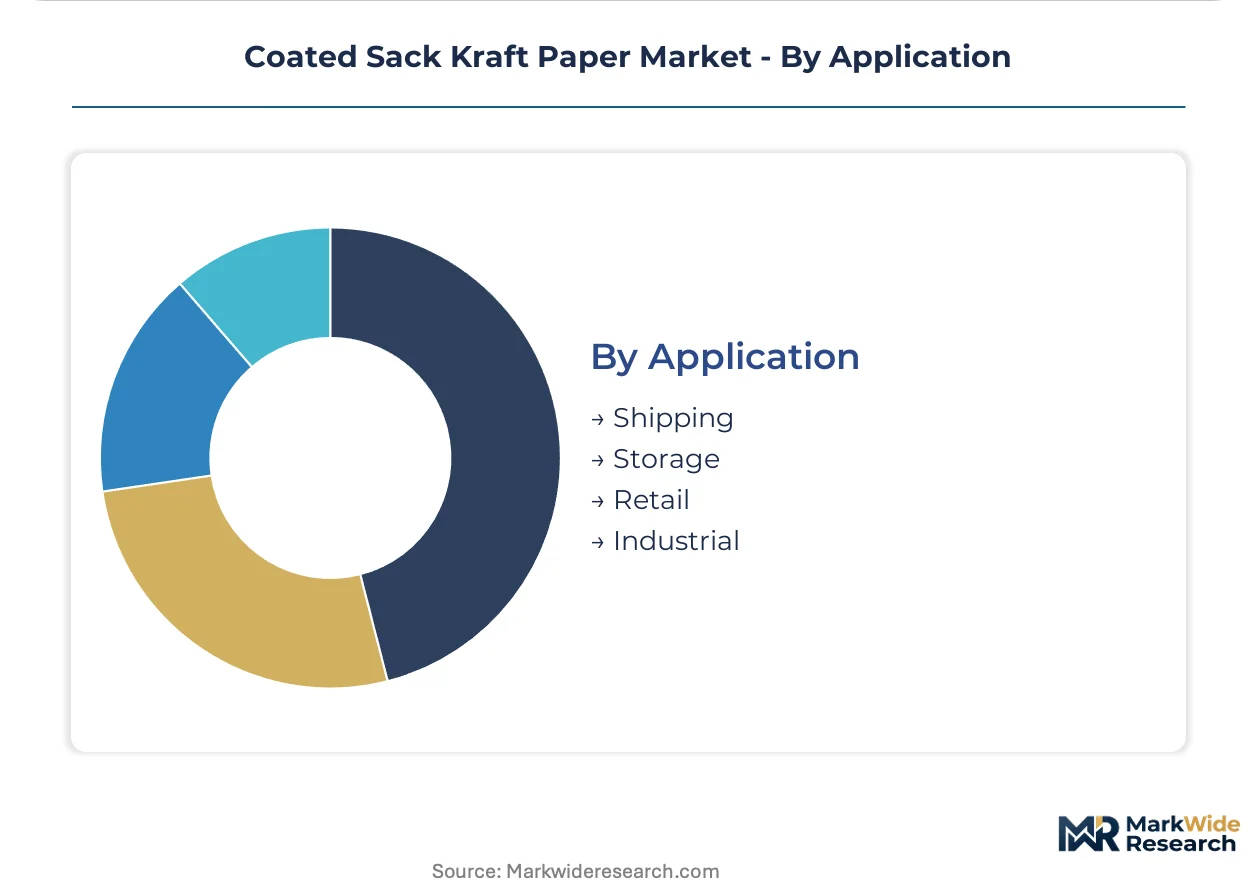
Application:
Downstream use patterns determine coating durability requirements and logistics infrastructure needs.
- Industrial:Automated filling, palletizing, and warehouse storage demand consistent dimensional stability and moisture barriers. German automotive parts suppliers specify industrial-grade coated kraft for just-in-time component sequencing.
- Shipping:Containerized and break-bulk ocean freight requires salt spray resistance and stacking strength for multi-week transit. Rotterdam port logistics providers specify shipping-optimized coatings for transshipment durability.
- Storage:Extended warehouse holding prioritizes UV stability and pest resistance for agricultural commodities. Spanish olive oil cooperatives specify storage-grade barriers for harvest-to-market intervals exceeding six months.
- Retail:Point-of-sale presentation demands printability and consumer handling comfort for direct product contact. Dutch supermarket private label programs specify retail-optimized surface treatments for shelf appeal.
Industrial applications dominate current coating line utilization. Retail specifications are expanding most quickly as brands replace plastic primary packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coating chemistry compliance costs are driving production migration toward jurisdictions with integrated pulp supply and established paper converting infrastructure, narrowing the arbitrage window between Nordic furnish sources and Central European converting clusters.
Germany
Food packaging converters in Baden-Württemberg and Rhineland-Palatinate are absorbing REACH-compliant bio-based coating capacity at rates exceeding domestic specialty grade supply. The EU Packaging and Packaging Waste Regulation mandates recyclability certification for all coated constructions entering German retail channels. Ludwigshafen's chemical packaging cluster now specifies multi-ply coated kraft with documented fiber traceability for hazardous material transport.
United States
Bakery sector procurement from industrial bread producers is displacing plastic laminate alternatives in Midwest and Southeast markets. FDA food contact regulations and EPA emissions standards govern coating formulation and mill compliance investments. Wisconsin and Georgia paper converting corridors are expanding aqueous dispersion coating lines to serve regional food brands seeking short-run customization.
France
Public sector food service contracts under EU Green Deal circular economy frameworks specify minimum recycled content thresholds for coated sack kraft. ANSM and DGCCRF oversight extends to food contact migration testing for bakery applications. The Grand Est and Hauts-de-France regions host cement and agrochemical distribution networks prioritizing pre-certified recyclable constructions.
Belgium
Premium chocolate and coffee roasters in Flanders are qualifying water-based starch and plant-derived wax dispersions for direct product contact specifications. ECHA coordination with national authorities accelerates bio-based barrier registration timelines. The Port of Antwerp logistics cluster supports transshipment-optimized coating grades for Mediterranean cement export routes.
Poland
Central European food export growth is outpacing domestic coated kraft capacity, creating import substitution openings for German and Nordic suppliers. National waste management frameworks align with EU extended producer responsibility mandates for packaging recyclability. The Łódź and Poznań industrial zones are attracting converting investments to serve grain and agricultural chemical distribution networks.
Coated Sack Kraft Paper Market Competitive Environment
Capacity expansion dominates the current landscape as integrated pulp-to-paper operators and independent converters race to install aqueous dispersion coating lines ahead of REACH polyethylene scrutiny. Market structure bifurcates between Nordic and Baltic mills with captive softwood furnish and Central European converters dependent on merchant pulp supply. Two archetypes predominate: vertically integrated forest products groups controlling fiber sourcing through extensive timber holdings, and specialty coating specialists leveraging formulation expertise for food contact compliance. Competitive moves concentrate on backward integration into pulp supply and geographic expansion into underconverted Central European markets.
Within the integrated forest products tier, Mondi Group and BillerudKorsnäs occupy positions anchored by European mill networks and pulp-to-paper operations. Mondi exemplifies the scale-driven archetype with barrier-coated grade supply sustained across multiple production sites. BillerudKorsnäs represents the performance-specialist vector with tailored grease and moisture resistance formulations. Segezha Group anchors the timber-holding model with extensive forestry assets supporting regional supply to agricultural markets.
| Leading Market Players |
|---|
| Mondi Group |
| WestRock Company |
| Segezha Group |
| International Paper Company |
| Smurfit Kappa Group |
| Canfor Corporation |
| BillerudKorsnäs |
| Nordic Paper |
| Gascogne Group |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal circular economy mandates gate qualified supply and premium-tier pricing access for coated sack kraft paper, as mills with demonstrable fiber traceability and post-consumer recyclability certification capture framework agreement premiums from pan-European food retail chains while uncertified regional converters face margin compression.
Pricing Analysis
Distributor margins compress specialty-grade premiums before retail shelf price formation. Three-tier pricing structure across specialty, heavyweight, and lightweight grades separates BfR-compliant food-contact barriers from industrial moisture-resistant constructions. Price differentiation hinges on certification tier and volume scale, with annual offtake commitments above ten thousand tons unlocking direct-mill contract terms. Cost compression in lightweight cement grades is intensifying because Baltic pulp proximity advantages erode as Nordic timber supply disruptions transmit to furnish costs. Cement shippers exhibit highest price sensitivity; Belgian chocolate packers show lowest due to failure-cost premiums exceeding material differentials.
Supply Chain Analysis
Softwood pulp supply rests on Nordic and Baltic timber holdings, with German converting clusters dependent on merchant furnish from Swedish, Finnish, and Estonian mill networks. Coated sack kraft production draws from unbleached kraft pulp, polyethylene resins, and aqueous dispersion chemistries including modified starch and plant-derived waxes. Single-source vulnerability concentrates in petrochemical majors controlling extrusion equipment and barrier resin supply chains with limited paper industry integration. Distribution runs through Rhineland-Palatinate and Baden-Württemberg converting corridors for European food packaging, with Antwerp and Rotterdam port logistics serving Mediterranean cement export routes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polish packaging expansion presents a geographic-arbitrage play, as underdeveloped domestic coated kraft capacity relative to Central European food export growth creates import substitution openings while REACH compliance costs concentrate qualified supply in German and Nordic mill networks.
For Market Incumbents: Acquire aqueous dispersion coating lines ahead of REACH polyethylene scrutiny to secure bio-based barrier capacity. Backward integration into Nordic softwood pulp supply hedges furnish cost volatility from Baltic timber disruptions. Certification investment in dual FDA-EU 10/2011 compliance documentation defends against emerging specialty coating specialists capturing pan-European retail framework agreements. For New Entrants and Emerging Players: Water-based inkjet-compatible microporous coatings offer technology-first entry into short-run customized packaging for regional food brands. Polish grain export packaging and French public sector food service tenders represent the most penetrable white-space targets. A go-to-market angle anchored in EU Green Deal recycled content thresholds differentiates against incumbent polyethylene-dependent supply. For Investors and Strategic Acquirers: Roll-up economics work for specialty coating specialists with BfR-compliant formulation expertise because barrier chemist talent scarcity concentrates at a handful of European research institutes. Long-term viability over a five-to-ten-year window favors targets with aqueous dispersion line installations and pan-European logistics footprints. Watch bio-based barrier seal-strength performance parity against incumbent PE standards as the inflection signal for specialty grade margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Aqueous Dispersion Capacity Expansion | REACH-compliant bio-based coating lines capture food packaging demand from plastic laminate migration. |
| Backward Integration into Pulp Supply | Nordic timber holdings hedge furnish cost volatility and secure consistent specialty grade quality. |
| Dual-Certification Investment | Simultaneous FDA and EU 10/2011 compliance accelerates supplier qualification with pan-European retail chains. |
| Geographic Expansion into Poland | Underconverted Central European capacity serves grain export and agrochemical distribution network growth. |
| Recycled Fiber Integration | Post-consumer content thresholds meet French public sector catering tender requirements under EU Green Deal mandates. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with paper mill operations directors, coating formulation chemists, food packaging procurement managers at retail chains, and cement distributor logistics heads with secondary validation from trade association reports, customs export data, and EU regulatory filings. Bottom-up segment sizing triangulated against top-down macroeconomic demand indicators.
Segment-weighting approaches modeled coated sack kraft paper across product type, end user, grade, and application dimensions throughout the forecast period. CAGRs were derived from installed capacity utilization trends, coating line capital expenditure pipelines, and substitution elasticity estimates for plastic laminate displacement. Industry-specific forecast inputs incorporated REACH chemical registration timelines and EU Packaging and Packaging Waste Regulation extended producer responsibility implementation schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to bio-based barrier technical performance gaps, Nordic timber supply disruption persistence, and pan-European retail procurement centralization velocity. A small set of triggers—including polyethylene registration scrutiny intensity and recycled fiber availability—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Postal Papers Market
Paper & Paperboard Packaging
Asia-Pacific Coated Paper Market
Paper & Paperboard Packaging
Retail Paper Bags Market
Paper & Paperboard Packaging
Global Sack Kraft Paper Market
Paper & Paperboard Packaging
Corrugated Handle Box Market
Paper & Paperboard Packaging
PE Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
Egypt Paper Packaging Market
Paper & Paperboard Packaging
Paperboard Mailer Market
Paper & Paperboard Packaging
Silicone Release Paper Market
Paper & Paperboard Packaging
Ovenable Paperboard Trays Market
Paper & Paperboard Packaging
Coated Recycled Paperboard Market
Paper & Paperboard Packaging
Kraft Paper Bags Market
Paper & Paperboard Packaging
Recycled Paper Packaging Market
Paper & Paperboard Packaging
Indonesia Paper Packaging Market
Paper & Paperboard Packaging
Push-Up Paperboard Tube Market
Paper & Paperboard Packaging
Kraft Paper Shopping Bag Market