
 Super Calendered Kraft Papers Market | 2026-2036
Super Calendered Kraft Papers Market Size, Share, and Industry Trends Forecast 2026-2036
Super Calendered Kraft Papers Market Analytics
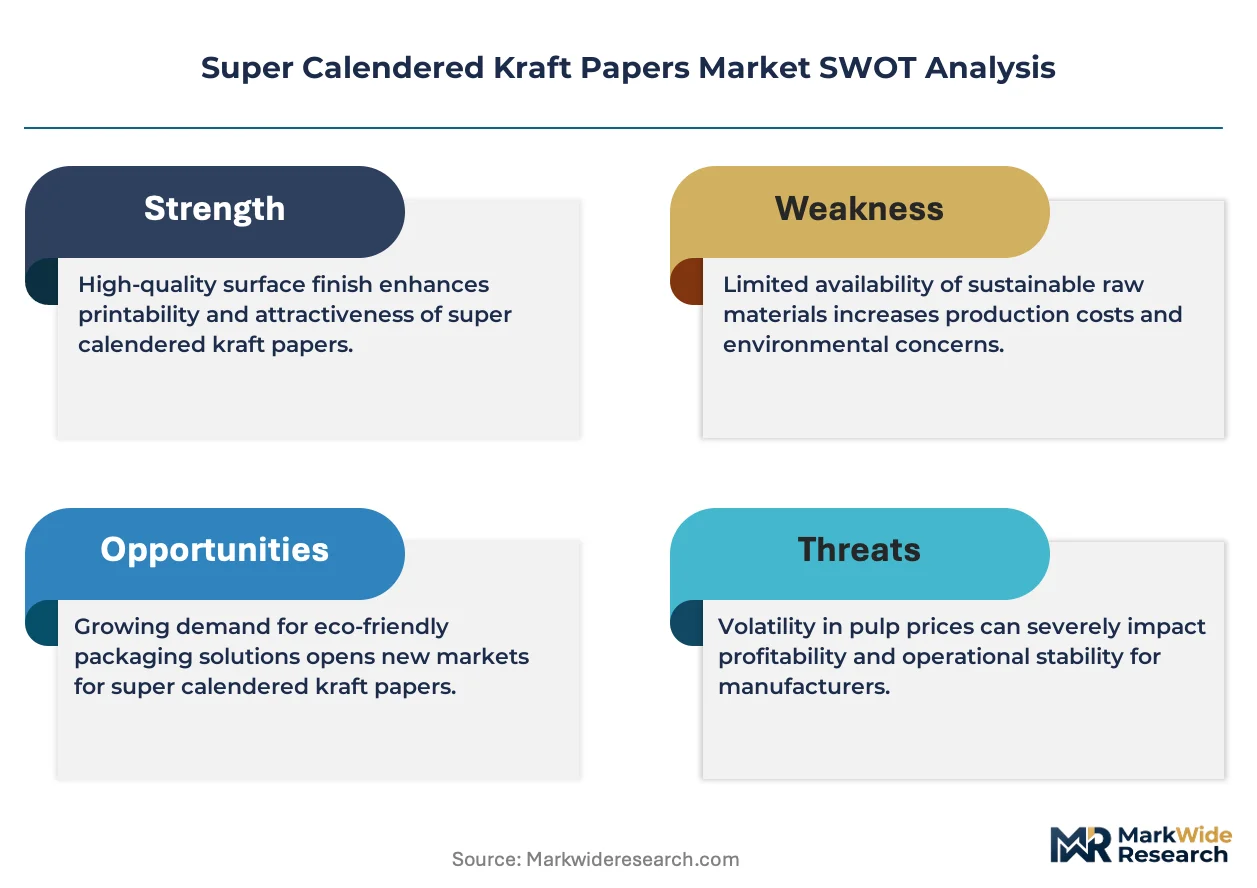
Asset-light leasing arrangements for super calendering equipment is reconfiguring competitive entry barriers, allowing mid-scale converters to access premium-grade output without capital-intensive mill investments. Stora Enso leverages its integrated Nordic pulp base to sustain cost-advantaged supply of high-gloss calendered grades. Mondi Group anchors its position through specialized food-contact certified production lines serving European brand owners. Pixelle competes via tight control over lightweight GSM 60-80 rolls targeting catalog and direct-mail segments.
Super calendered kraft papers are machine-finished cellulose sheets subjected to alternating steel and cotton-nip polishing to achieve surface smoothness below 2 microns, designed primarily for high-resolution printing and protective wrapping applications. Bleached kraft dominates margin pools in cosmetic and pharmaceutical end uses where whiteness and print fidelity command premium positioning. Unbleached kraft leads volume in food packaging applications where natural aesthetics and compostability specifications align with retailer sustainability mandates. Coated kraft represents the fastest-growing structural category as barrier-enhanced formulations displace multi-material laminates in chilled and greasy food segments.
The EPA regulates pulp and paper effluent standards under Cluster Rules that shape mill-level capital allocation toward cleaner super calendering processes. FDA food-contact substance notifications govern the silicone and wax coatings applied to kraft grades destined for direct food interfaces. ISO 9001 and FSC chain-of-custody certifications increasingly function as market-access prerequisites for European and North American buyers. Stakeholders must monitor how pending revisions to extended producer responsibility frameworks in major consuming jurisdictions will redistribute compliance costs between integrated producers and downstream converters.
Market Dynamics
E-commerce fulfillment standards are compressing specification tolerances for protective wrapping materials, forcing converters to upgrade surface smoothness and print registration capabilities without absorbing full capital burdens.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Material traceability mandates across member states are accelerating specification upgrades for food-contact certified grades in Germany and France.
- Barrier-enhanced formulations:Silicone and wax coating advances are displacing multi-material laminates in chilled food segments, opening volume pools for coated kraft producers.
- Pharmaceutical wrapping:Premium confectionery and drug packaging specifications in Germany are concentrating demand for high-gloss bleached grades with sub-2-micron surface smoothness.
Market Restraints
- Nordic pulp supply concentration:Integrated producers with captive softwood pulp access in Finland and Sweden control cost-advantaged feedstock for high-gloss grades.
- EPA Cluster Rules compliance:Effluent standards for super calendering processes require capital-intensive wastewater treatment upgrades at US mill sites.
- Flexible plastic substitution:Polyethylene-based protective films retain cost advantages for moisture-critical applications in Asian export packaging.
Strategic Opportunities
- Asset-light equipment leasing:Mid-scale converters in Italy and Spain are accessing premium-grade super calendering output without mill-level capital deployment.
- Compostable food service:Natural aesthetics and biodegradability specifications in French and Dutch retail chains are expanding unbleached kraft adoption.
- Direct-mail catalog recovery:Lightweight GSM 60-80 roll specifications are stabilizing demand in North American publishing and promotional segments.
Industry Challenges
- FDA food-contact notification timelines:Silicone coating approvals for direct food interfaces extend product development cycles by 12-18 months.
- ISO 9001 and FSC certification maintenance:Chain-of-custody documentation requirements consume dedicated compliance personnel at smaller converter operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Super Calendered Kraft Papers Market |
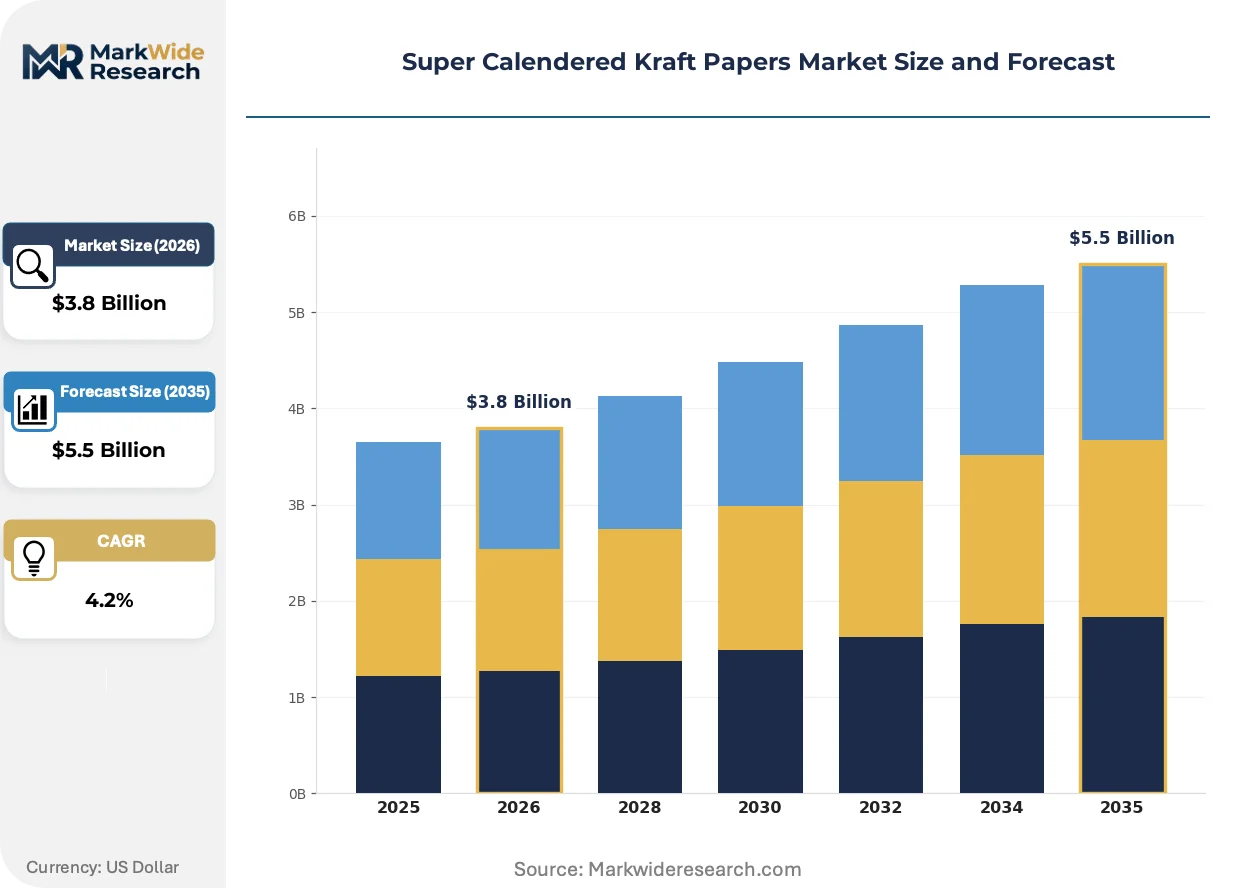
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bleached Kraft, Unbleached Kraft, Coated Kraft, Recycled Kraft End Use Industry: Packaging, Printing, Stationery, Labels Thickness: GSM 60-80, GSM 80-100, GSM 100-120, GSM 120-140 Application: Food Packaging, Cosmetic Containers, Textile Wrapping, Durable Goods |
| Companies Covered | Stora Enso, UPM, WestRock Company, Domtar Corporation, Pixelle, International Paper, Mondi Group, Sappi Limited, Ahlstrom-Munksjo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Super Calendered Kraft Papers Market Evolving Landscape
Digital print compatibility requirements are rewriting surface specification standards across protective and promotional wrapping segments. Equipment leasing models and coating chemistry advances are converging to reshape competitive access.
Precision surface measurement systems using laser profilometry are digitizing quality assurance protocols for super calendered output. High-volume catalog printers in the United States are adopting these systems to reduce makeready waste on 40-inch web presses. Real-time smoothness feedback is digitizing the link between mill production parameters and downstream print registration performance.
REACH restrictions on per- and polyfluoroalkyl substances are accelerating fluorochemical-free barrier coating development for grease-resistant food packaging. European brand owners are reformulating specification sheets to exclude legacy PFAS-containing materials by 2025. German confectionery exporters are absorbing reformulation costs to maintain EU market access under tightening ECHA substance evaluations.
Brand owner consolidation in European food retail is compressing supplier qualification cycles and unbundling after-sales technical service from base material contracts. Large-scale converters in the Netherlands are absorbing design and print optimization functions previously performed by separate creative agencies. This service unbundling is most visible in private-label packaging programs where Aldi and Lidl procurement teams now specify surface chemistry directly.
Super Calendered Kraft Papers Market Segmentation
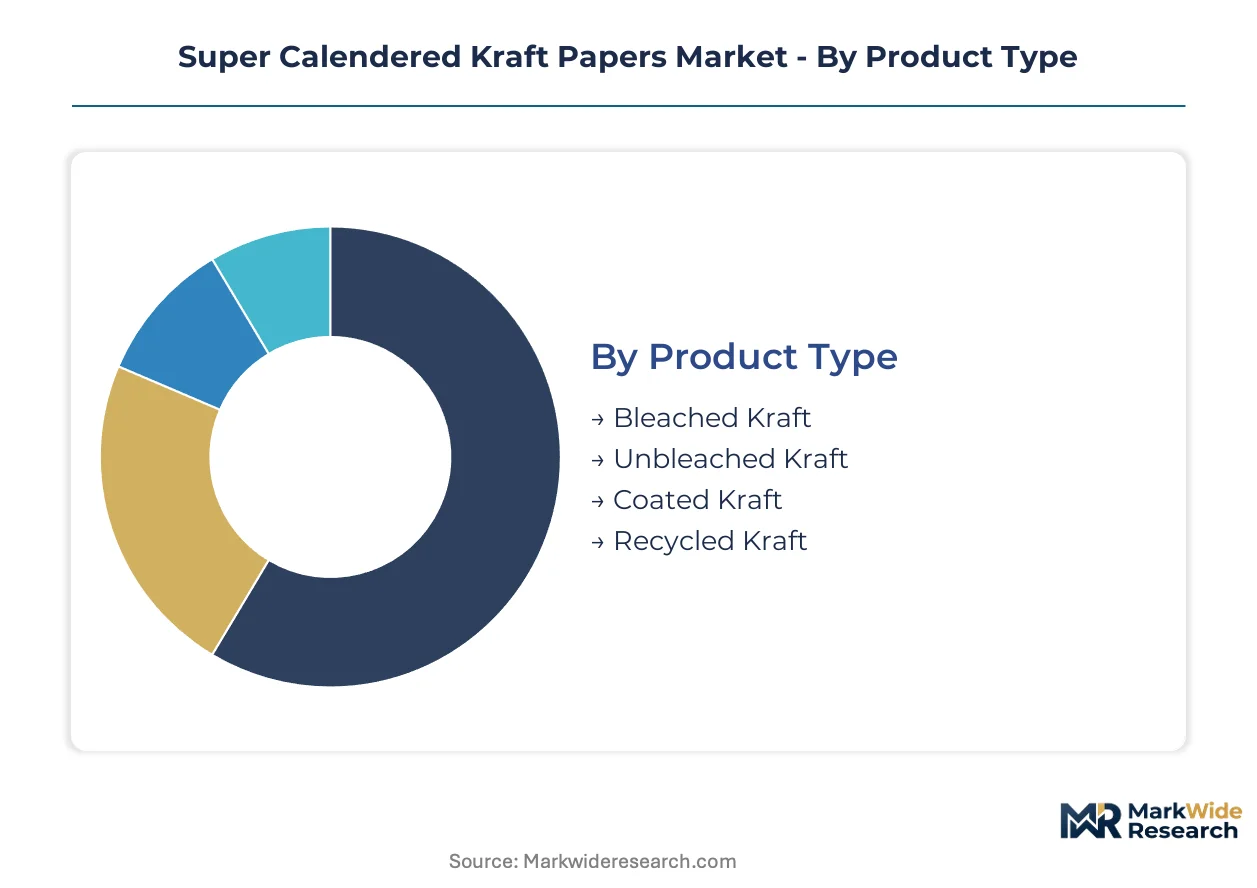
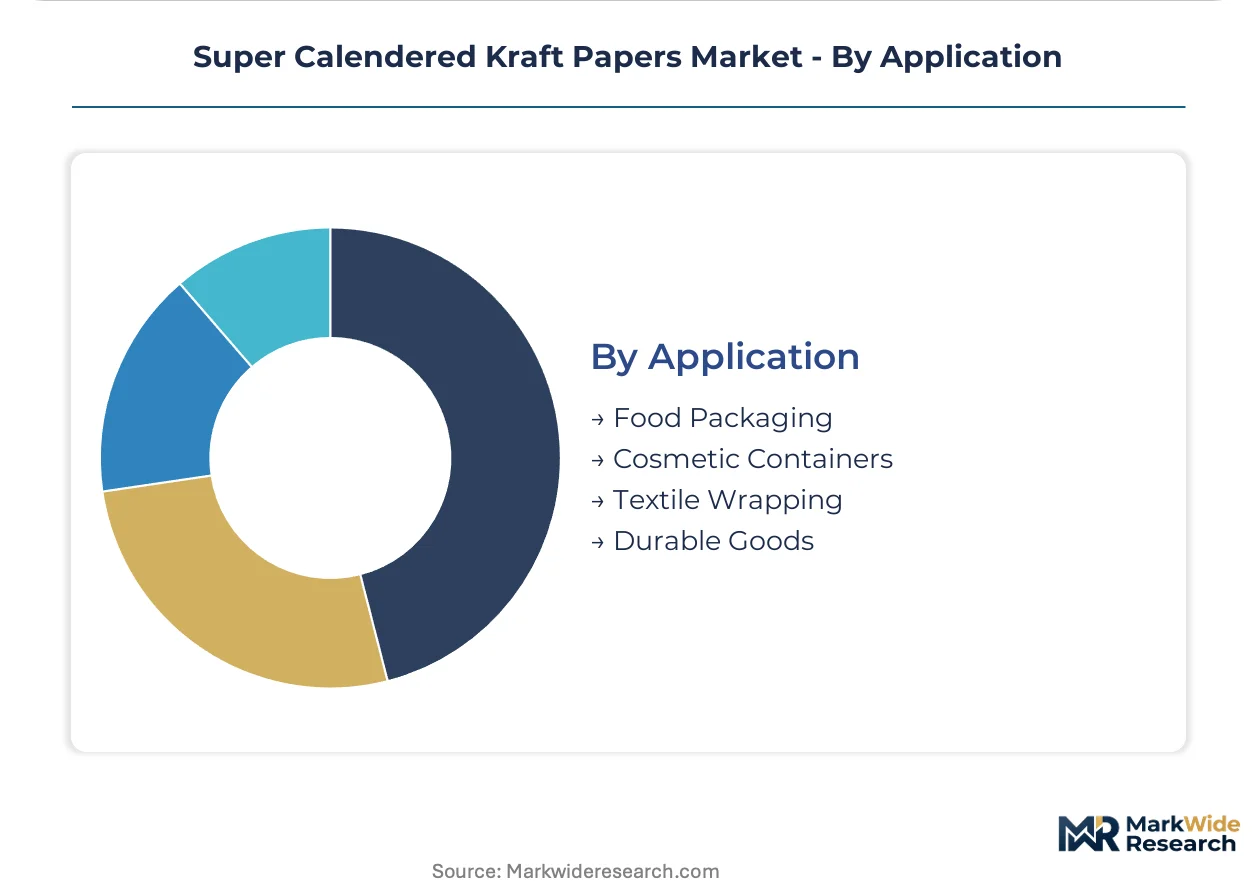
Super calendered kraft papers serve divergent performance requirements across protective wrapping and high-resolution printing. Specification choices cascade through surface smoothness, barrier chemistry, and grammage tolerances that determine machine compatibility and end-use compliance.
Product Type:
Mature grades anchor volume commitments while emerging formulations capture specification upgrades from sustainability mandates.
- Bleached Kraft:Fully delignified cellulose fibers achieve brightness levels above 88 ISO, enabling four-color process printing with sub-2-micron surface smoothness. Pharmaceutical and premium confectionery sectors in Germany concentrate procurement here, driven by FDA food-contact notification requirements for direct packaging interfaces.
- Unbleached Kraft:Retained lignin content delivers natural brown aesthetics and accelerated biodegradation timelines. French and Dutch retail chains specify this grade for compostable food service applications where ECHA REACH compliance excludes synthetic additives.
- Coated Kraft:Silicone and wax barrier layers displace multi-material laminates in chilled food segments.
- Recycled Kraft:Post-consumer fiber integration meets FSC chain-of-custody thresholds for circular packaging claims.
Unbleached kraft handles the majority of throughput; coated kraft is the fastest mover on share.
End Use Industry:
Application-driven cost tiers separate commodity wrapping from precision-printed segments.
- Packaging:Protective wrapping for e-commerce fulfillment demands tear resistance and print registration stability across variable humidity conditions. German logistics hubs specify GSM 80-100 grades for automated packing line compatibility.
- Printing:High-volume catalog and direct-mail production requires consistent caliper for 40-inch web press efficiency.
- Stationery:Premium writing surfaces command elevated smoothness specifications for fountain pen compatibility.
- Labels:Pressure-sensitive adhesive compatibility depends on controlled porosity and dimensional stability.
Packaging commands the dominant volume position; printing applications are expanding most quickly as catalog segments stabilize.
Thickness:
Volume concentration sits at mid-range grammages while specialty segments push specification boundaries.
- GSM 60-80:Lightweight rolls minimize postal surcharges for direct-mail campaigns. North American catalog printers stabilize demand here through specialized leasing arrangements for super calendering equipment.
- GSM 80-100:Balanced stiffness and conformability serves automated food packaging lines.
- GSM 100-120:Enhanced puncture resistance protects durable goods through distribution handling.
- GSM 120-140:Heavy-duty specifications anchor luxury gift and textile wrapping applications.
GSM 80-100 carries the bulk of production volume; GSM 60-80 is climbing the fastest on share recovery in promotional segments.
Application:
Customer-type priorities diverge between compliance-driven food contact and aesthetic-driven premium presentation.
- Food Packaging:Direct-contact grades require FDA notification for silicone coatings and EFSA compliance for grease-resistant formulations. German confectionery exporters absorb reformulation costs to maintain EU market access under tightening substance evaluations.
- Cosmetic Containers:Whiteness and surface gloss support brand differentiation in pharmaceutical and beauty segments.
- Textile Wrapping:Acid-free specifications protect natural fiber integrity during storage and transport.
- Durable Goods:Abrasion-resistant surfaces withstand metal and glass contact without fiber transfer.
Food packaging dominates throughput commitments; cosmetic containers are gaining share fastest on premium positioning trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from Nordic pulp mills balance import demand from German packaging converters and North American catalog printers. Currency fluctuations between euro and dollar zones reshape arbitrage opportunities for coated grade shipments.
Germany
Premium confectionery and pharmaceutical wrapping specifications concentrate procurement in Baden-Württemberg and Bavaria. The EU Packaging and Packaging Waste Regulation tightens material traceability requirements for food-contact certified grades. Stuttgart-based converters upgrade surface smoothness specifications to sub-2-micron tolerances for high-gloss bleached kraft.
United States
High-volume catalog and direct-mail segments stabilize demand for lightweight GSM 60-80 rolls. EPA Cluster Rules compliance drives capital allocation toward cleaner super calendering processes at mill sites. Wisconsin and Michigan paper clusters adopt laser profilometry systems to reduce makeready waste on 40-inch web presses.
France
Compostable food service applications expand unbleached kraft adoption through retail chain procurement. ECHA REACH restrictions on PFAS accelerate fluorochemical-free barrier coating development. Lyon and Paris basin converters absorb reformulation costs to maintain EU market access under tightening substance evaluations.
Sweden
Integrated producers with captive softwood pulp access control cost-advantaged feedstock for high-gloss grades. FSC chain-of-custody certifications function as market-access prerequisites for North American buyers. Stockholm and Gothenburg mill complexes leverage Nordic fiber base to sustain premium-grade output.
Netherlands
Private-label packaging programs at Aldi and Lidl compress supplier qualification cycles and unbundle technical service functions. Large-scale Rotterdam and Amsterdam converters absorb design and print optimization previously performed by creative agencies. Brand owner consolidation in European food retail specifies surface chemistry directly in procurement contracts.
Super Calendered Kraft Papers Market Competitive Landscape
On the supply side, the industry is consolidating around integrated pulp-to-paper producers with captive fiber access and specialized coating capabilities. Nordic mill complexes anchor high-gloss grade production through softwood pulp integration. Strategic archetypes divide between integrated multinationals with full fiber control, regional specialists with equipment leasing flexibility, and coating technology developers. Dominant competitive moves include asset-light equipment leasing arrangements and barrier chemistry reformulation partnerships.
Among Nordic-based integrated producers, Stora Enso and UPM occupy positions anchored by captive pulp supply. Mondi Group exemplifies the food-contact certification specialist tier. Pixelle represents equipment-leasing flexibility through tight control over lightweight GSM specifications.
| Leading Market Players |
|---|
| Stora Enso |
| UPM |
| WestRock Company |
| Domtar Corporation |
| Pixelle |
| International Paper |
| Mondi Group |
| Sappi Limited |
| Ahlstrom-Munksjo |
| Others |
Value Network & Pricing Analysis
Baltic Sea freight corridors linking Finnish pulp terminals to German converter hubs transmit Nordic softwood fiber cost advantages into downstream price stratification across bleached and unbleached grade tiers. This logistics architecture concentrates pricing power with integrated producers while forcing asset-light converters to absorb volatility through equipment leasing structures.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels differentiated by FSC chain-of-custody certification and FDA food-contact notification status. Specialty food packaging converters in Germany exhibit lowest price sensitivity due to regulatory compliance mandates, while catalog printers in North America face intense cost compression from postal surcharge minimization requirements. Pricing pressure stems from polyethylene-based flexible films undercutting moisture-critical applications in Asian export packaging.
Supply Chain Analysis
Extended payment terms from Nordic pulp suppliers to German and Dutch converters have become standard working capital arrangements, with supply-chain finance facilities increasingly bridging 90-120 day cycles. Production concentrates in Finland, Sweden, and Germany, drawing from captive softwood pulp, silicone coating chemicals, and cotton-nip calendering rolls. Single-source vulnerability sits with integrated Nordic fiber access controlling high-gloss grade output. Distribution runs through Rotterdam and Hamburg port complexes serving European converter clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Super calendered kraft papers function as a substitution defense against flexible plastic films and multi-material laminates, with incumbent positioning contingent on barrier coating chemistry advances and compostability certification maintenance.
For Market Incumbents: Harden captive pulp integration through Nordic fiber base expansion and accelerate fluorochemical-free barrier coating R&D to preempt REACH compliance disruption. Prioritize FSC chain-of-custody certification maintenance as Aldi and Lidl procurement teams increasingly specify surface chemistry directly in private-label contracts.
For New Entrants and Emerging Players: Mid-scale converters in Italy and Spain represent the most penetrable entry point via asset-light super calendering equipment leasing arrangements bypassing mill-level capital deployment. Target compostable food service applications in French and Dutch retail chains where unbleached kraft specifications align with tightening ECHA substance evaluations.
For Investors and Strategic Acquirers: Food-contact certification specialists with established FDA notification pathways and integrated coating capabilities offer the strongest acquisition profile for long-term viability across the analysis window. Monitor PFAS regulatory enforcement timelines as inflection indicators for barrier chemistry reformulation cost absorption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Softwood Pulp | Finnish and Swedish fiber base secures cost-advantaged feedstock for high-gloss grade production. |
| Fluorochemical-Free Coating Development | REACH restrictions on PFAS accelerate reformulation partnerships with German confectionery exporters. |
| Equipment Leasing Model Expansion | Asset-light arrangements enable Italian and Spanish converter access to premium-grade output. |
| FSC Chain-of-Custody Certification | North American buyer prerequisites increasingly function as market-access gatekeepers. |
| Laser Profilometry System Adoption | Wisconsin and Michigan mills reduce makeready waste through real-time smoothness feedback digitization. |
Research Methodology
Desk research of trade flow databases, EPA Cluster Rules filings, and ECHA substance evaluation records preceded structured interviews with mill operations managers, food packaging procurement leads at German confectionery exporters, coating chemistry R&D directors, and equipment leasing specialists. Primary fieldwork with Nordic integrated producers and Dutch private-label converters combined with secondary validation against FSC certification registries and FDA food-contact notification databases. Bottom-up volume estimates triangulated against top-down pulp consumption models.
Assumptions held fixed across the projection horizon include EU Packaging and Packaging Waste Regulation enforcement timelines, Nordic softwood pulp supply continuity, and REACH PFAS restriction implementation schedules. Modeled segmentation dimensions encompass product type, end-use industry, grammage tier, and geographic production hub. CAGRs derived from historical price-volume relationships and substitution elasticity parameters, with specific inputs including e-commerce fulfillment standard evolution and catalog segment demand stabilization.
Practitioners should monitor barrier coating approval timelines, extended producer responsibility framework revisions, and flexible plastic film cost trajectories for early signals of forecast deviation. Macroeconomic contraction, regulatory acceleration, or breakthrough barrier technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Parchment Paper Market
Paper & Paperboard Packaging
Europe Mailer Packaging Market
Paper & Paperboard Packaging
Italy Paper Packaging Market
Paper & Paperboard Packaging
Paperboard Mailer Market
Paper & Paperboard Packaging
Australia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Paper Cup Machine Market
Paper & Paperboard Packaging
Canada Paper Packaging Market
Paper & Paperboard Packaging
US Corrugated and Folding Boxboard Market
Paper & Paperboard Packaging
Recycled Paper Packaging Market
Paper & Paperboard Packaging
Shredded Paper Filler Market
Paper & Paperboard Packaging
Global Sack Kraft Paper Market
Paper & Paperboard Packaging
South Korea Paper Packaging Market
Paper & Paperboard Packaging
Postage Stamp Paper Market
Paper & Paperboard Packaging
Kraft Paper SOS Bag Market
Paper & Paperboard Packaging
Packing Paper Market
Paper & Paperboard Packaging
United States Paper Packaging Market