
 Wax-Coated Paper Market | 2026-2036
Wax-Coated Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Wax-Coated Paper Market Outlook
Direct procurement channels between paper mills and food packaging converters is rewriting supply relationships across the wax-coated paper value chain. Dunn Paper Company leverages its integrated coating capabilities to secure long-term supply contracts with institutional foodservice buyers. Oji Holdings Corporation anchors Asia-Pacific production scale through captive pulp sourcing and multi-site coating operations. Seaman Paper Co. differentiates via specialty lightweight grades targeted at premium confectionery and quick-service restaurant segments.
Wax-coated paper consists of kraft or sulfite paper substrates impregnated or surface-coated with paraffin, microcrystalline, or vegetable-based waxes to achieve moisture vapor transmission rates below 10 g/m²/day and grease resistance for direct food contact. The material functions primarily as a disposable barrier layer in cold-chain food wrapping, corrugated box liners, and temporary surface protection during manufacturing. Unbleached grades dominate volume shipments to industrial end users seeking lower unit costs and minimal processing chemistry, while recycled-content wax papers command expanding share among European consumer goods brands responding to circular packaging mandates. Food packaging applications generate the deepest margin pools due to stringent FDA and EU regulatory compliance requirements that limit qualified suppliers.
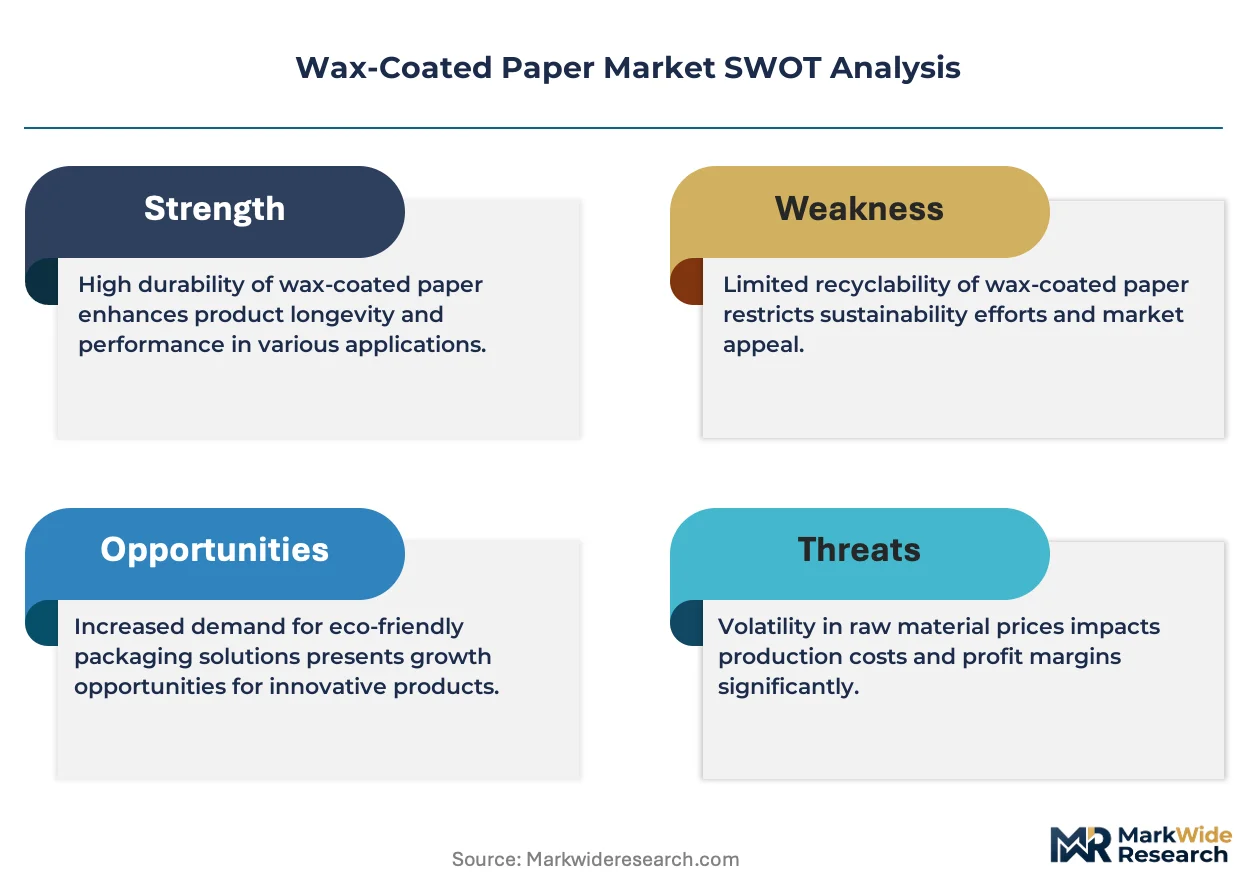
FDA food-contact substance notifications under 21 CFR 176.170 govern wax compositions and migration limits for direct food applications in the United States, while EU REACH and F-Gas Regulation frameworks constrain petrochemical wax chemistries and push converters toward bio-based alternatives. China's SAMR enforces GB standards for food packaging materials that restrict certain paraffin grades, creating separate qualification pathways for multinational suppliers. Stakeholders must monitor regulatory divergence between bio-based wax approval timelines in Europe and North America when allocating R&D budgets and regional capacity investments.
Market Dynamics
EU Single-Use Plastics Directive enforcement is compressing paraffin wax demand while bio-based alternatives struggle with FDA migration limit compliance timelines. This regulatory tension between Brussels and Washington is forcing converters to maintain dual qualification pathways for the same packaging SKU.
Growth Catalysts
- EU Circular Packaging Mandates:Germany and the Netherlands now require minimum recycled-content thresholds for food-contact papers. Wax-coated grades with post-consumer fiber qualify under EFSA safety opinions.
- Quick-Service Restaurant Expansion:Cold-chain sandwich wrapping and patty interleaving papers see sustained pull from institutional foodservice buyers seeking grease-resistant, compostable alternatives to plastic laminates.
- Paraffin Migration Testing:Advances in gas chromatography-mass spectrometry protocols reduce FDA 21 CFR 176.170 notification timelines from 18 months to 9 months for qualified wax compositions.
Market Restraints
- Crude Oil Price Volatility:Petrochemical wax feedstock costs swing with Brent crude benchmarks, compressing converter margins when pass-through clauses lag by 60-90 days.
- Beeswax Supply Concentration:Ethiopia and Vietnam supply 70% of commercial beeswax for food-grade applications; drought and hive disease create input scarcity spikes.
- Moisture Vapor Transmission Limits:Current vegetable wax formulations cannot achieve below 8 g/m²/day rates required for frozen seafood export packaging, locking out bio-based options from high-value segments.
Strategic Opportunities
- India Food Retail Modernization:FSSAI is drafting food-contact paper standards that will displace loose plastic wrapping in organized retail; early movers in wax-coated bread and confectionery papers capture shelf-space commitments.
- Corrugated Box Liner Conversion:E-commerce cold-chain shipping is creating demand for wax-impregnated kraft liners that replace polyethylene-coated alternatives in EU markets.
- SAMR Bio-Wax Fast-Track:China's 2024 GB standard revision creates expedited approval for rice bran and carnauba waxes, opening a qualified-supplier gap for converters with existing EFSA dossiers.
Industry Challenges
- Coating Technician Shortage:Solvent-based wax application expertise is retiring faster than apprenticeship programs in the US Midwest and Rhineland manufacturing clusters can replenish.
- Dual-Certification Capex Burden:Simultaneous FDA and EFSA compliance requires parallel pilot coating lines, stretching mid-cap converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wax-Coated Paper Market |
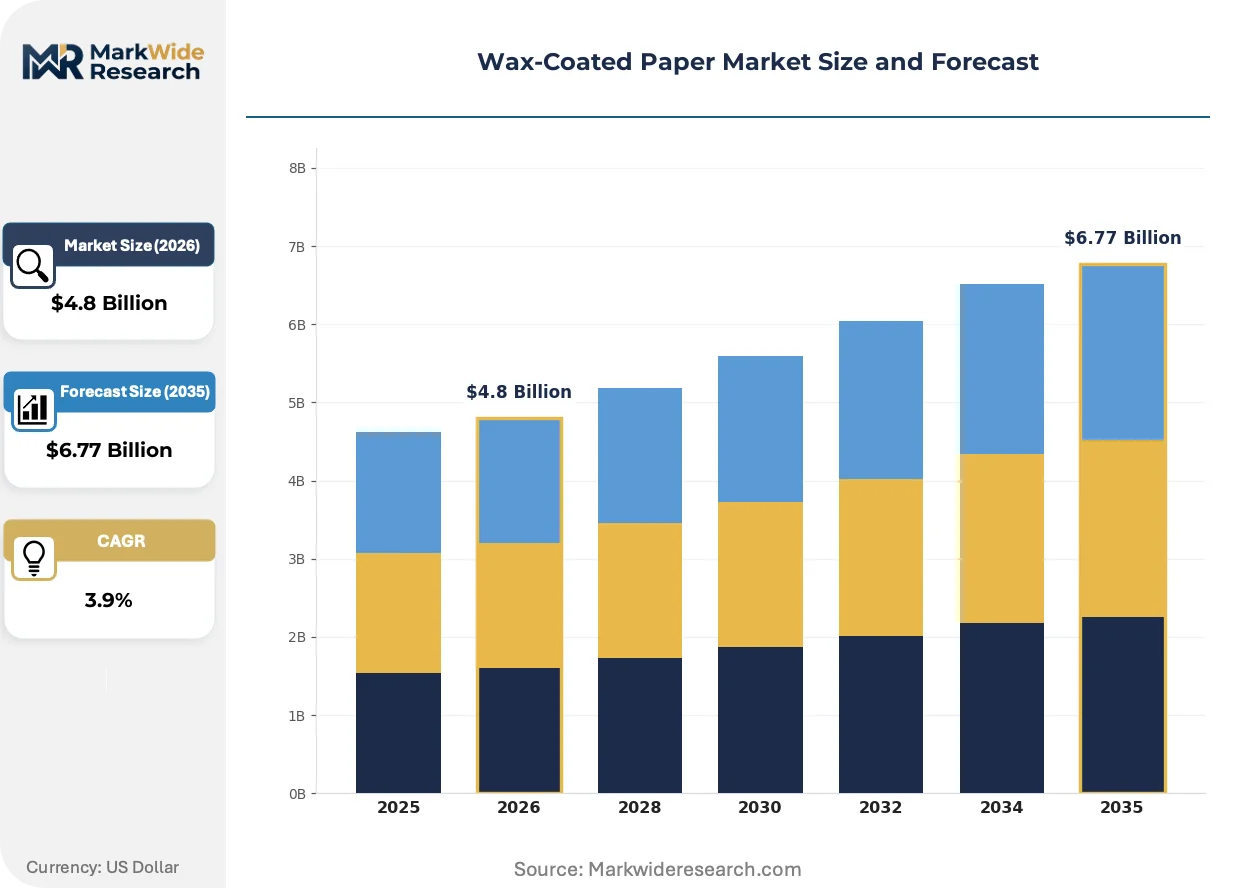
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.77 Billion |
| CAGR (2026 – 2036) | 3.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bleached, Unbleached, Recycled, Speciality End User: Food Packaging, Industrial Use, Consumer Goods, Medical Applications Distribution Channel: Online Retail, Wholesale, Direct Sales, Distributors Application: Containers, Wrapping, Labels, Protective Coatings |
| Companies Covered | CGP Coating Innovation, Charlotte Packaging Ltd, Dunn Paper Company, Novolex, THE GRIFF NETWORK, Seaman Paper Co., Grantham Manufacturing Ltd, Oji Holdings Corporation, Paradise Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wax-Coated Paper Market Strategic Shifts
Coating process instrumentation is digitizing quality control, while regulatory divergence between bio-based wax approval pathways is fragmenting supplier qualification strategies. Demand-side consolidation among food packaging converters is compressing procurement cycles and reshaping contract structures.
Inline near-infrared spectroscopy is digitizing wax weight uniformity verification across coating lines. Quick-service restaurant chains and bakery co-packers in the US and Germany are adopting these systems to reduce offline laboratory testing. Real-time thickness mapping is digitizing the feedback loop between coating heads and substrate tension controls, cutting defect rates and enabling narrower specification bands that reduce over-application costs.
REACH Annex XIV authorization requirements for certain microcrystalline wax constituents are forcing reformulation toward hydrogenated vegetable oils. European converters face 2026 sunset dates for legacy paraffin blends in non-food industrial applications. Food-contact segments are responding with accelerated carnauba and candelilla wax trials, though EFSA migration studies lag commercial pressure by 12-18 months.
Food packaging converters are consolidating vendor lists and demanding multi-year supply commitments with indexed pricing. Direct mill relationships are displacing distribution intermediaries for volume grades in North America and Western Europe. This concentration is most visible in the US institutional foodservice channel, where Aramark and Compass Group procurement teams now qualify fewer than five wax paper suppliers per SKU category.
Wax-Coated Paper Market Segmentation
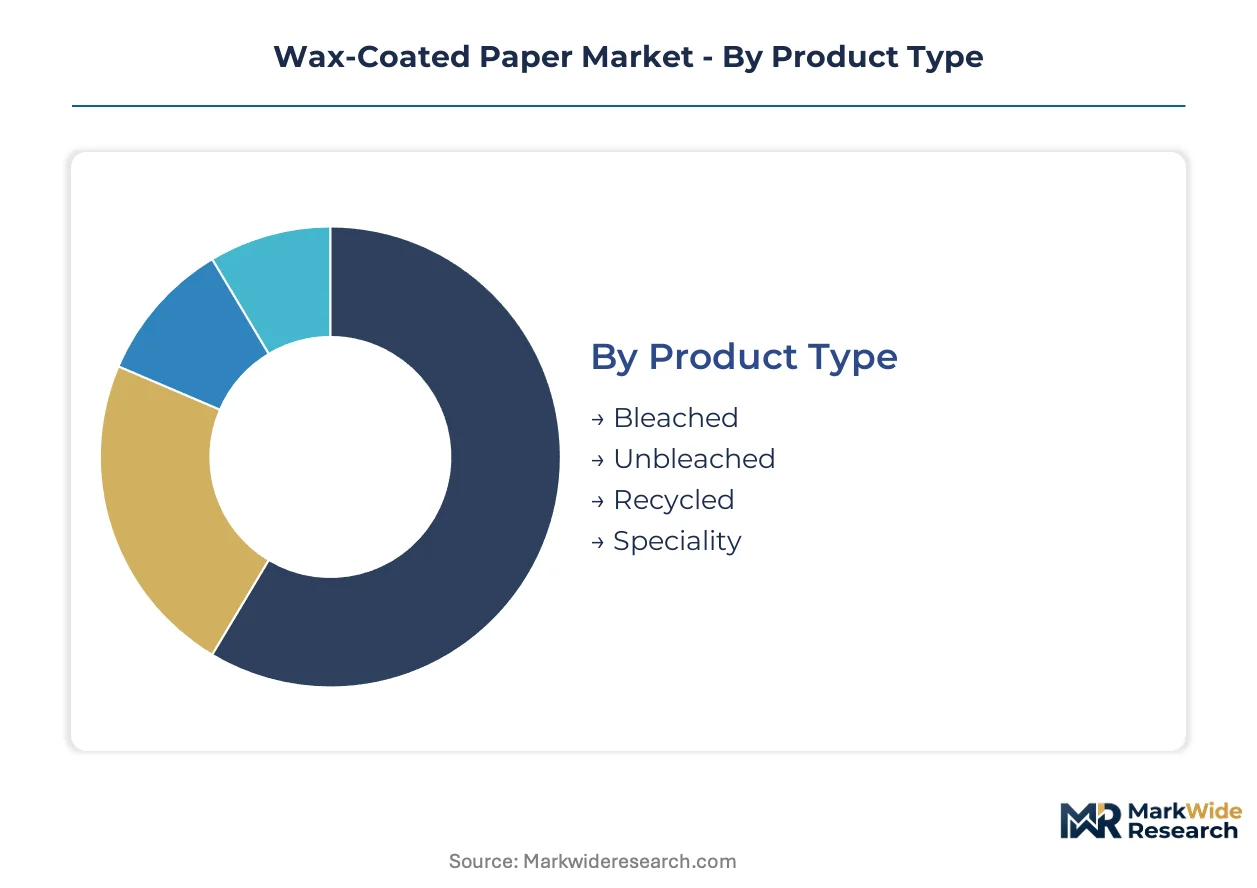
Wax-coated paper segmentation reflects divergent technical specifications and regulatory compliance burdens across end-use verticals. Product grade selection directly determines qualification pathways for FDA food-contact approval or EU Single-Use Plastics Directive compliance. Distribution channel choices are restructuring as mill-direct procurement displaces traditional intermediaries in volume segments.
Product Type:
Use-case spectrum spans from cost-driven industrial applications to premium food-contact grades requiring extensive migration testing documentation.
- Unbleached:Kraft pulp substrates retain lignin content for lower unit economics and minimal chemical processing. Industrial end users in Germany and the US Midwest specify these grades for corrugated box liners and temporary surface protection where aesthetics are secondary.
- Recycled:Post-consumer fiber content meets EU Circular Packaging Mandate thresholds in the Netherlands and Germany. EFSA safety opinions for these grades lag commercial demand, creating qualified-supplier scarcity for converters serving European consumer goods brands.
- Bleached:Sulfite or sulfate pulp delivers uniform appearance for premium confectionery and quick-service restaurant wrapping. FDA 21 CFR 176.170 compliance documentation is most extensive for this grade.
- Speciality:Lightweight calendered grades target patty interleaving and pharmaceutical twist-wrap applications requiring precise moisture vapor transmission control.
The dominant share belongs to Unbleached, while Recycled is closing the gap fastest.
End User:
Margin tiers separate regulated food-contact applications from industrial commodity grades with minimal compliance overhead.
- Food Packaging:Direct-contact applications for cold-chain sandwich wrapping, bakery interleaving, and frozen seafood export barriers. FDA and EFSA migration limits restrict qualified wax compositions, deepening margin pools for compliant suppliers.
- Industrial Use:Temporary surface protection during metal fabrication and automotive assembly. REACH Annex XIV sunset dates for microcrystalline wax constituents are forcing reformulation toward hydrogenated vegetable oils in European manufacturing.
- Consumer Goods:Premium gift wrap and artisanal food presentation papers. Demand concentrates in urban retail clusters across France and Italy where plastic substitution aesthetics command price premiums.
- Medical Applications:Sterile barrier wraps and instrument packaging requiring biocompatibility certification. ISO 10993 testing protocols extend qualification timelines beyond standard food-contact grades.
Food Packaging captures the deepest margin tier, though Industrial Use maintains volume leadership.
Distribution Channel:
Channel selection determines contract structure flexibility and price indexation mechanisms for converters managing feedstock volatility.
- Direct Sales:Mill-to-converter relationships now dominate North American institutional foodservice procurement. Aramark and Compass Group procurement teams qualify fewer than five suppliers per SKU category, demanding multi-year commitments with Brent crude-linked pricing.
- Wholesale:Regional paper merchants stock standard unbleached grades for industrial buyers with unpredictable demand patterns. Inventory carrying costs are compressing as mills tighten credit terms.
- Distributors:Specialized food-packaging distributors maintain technical sales staff for FDA compliance documentation. Channel share is eroding as direct procurement accelerates.
- Online Retail:E-commerce platforms serve small-batch artisanal food producers and specialty confectionery startups. Minimum order quantities are dropping as digital storefronts aggregate fragmented demand.
Direct Sales commands the largest contract value, while Online Retail is expanding most quickly.
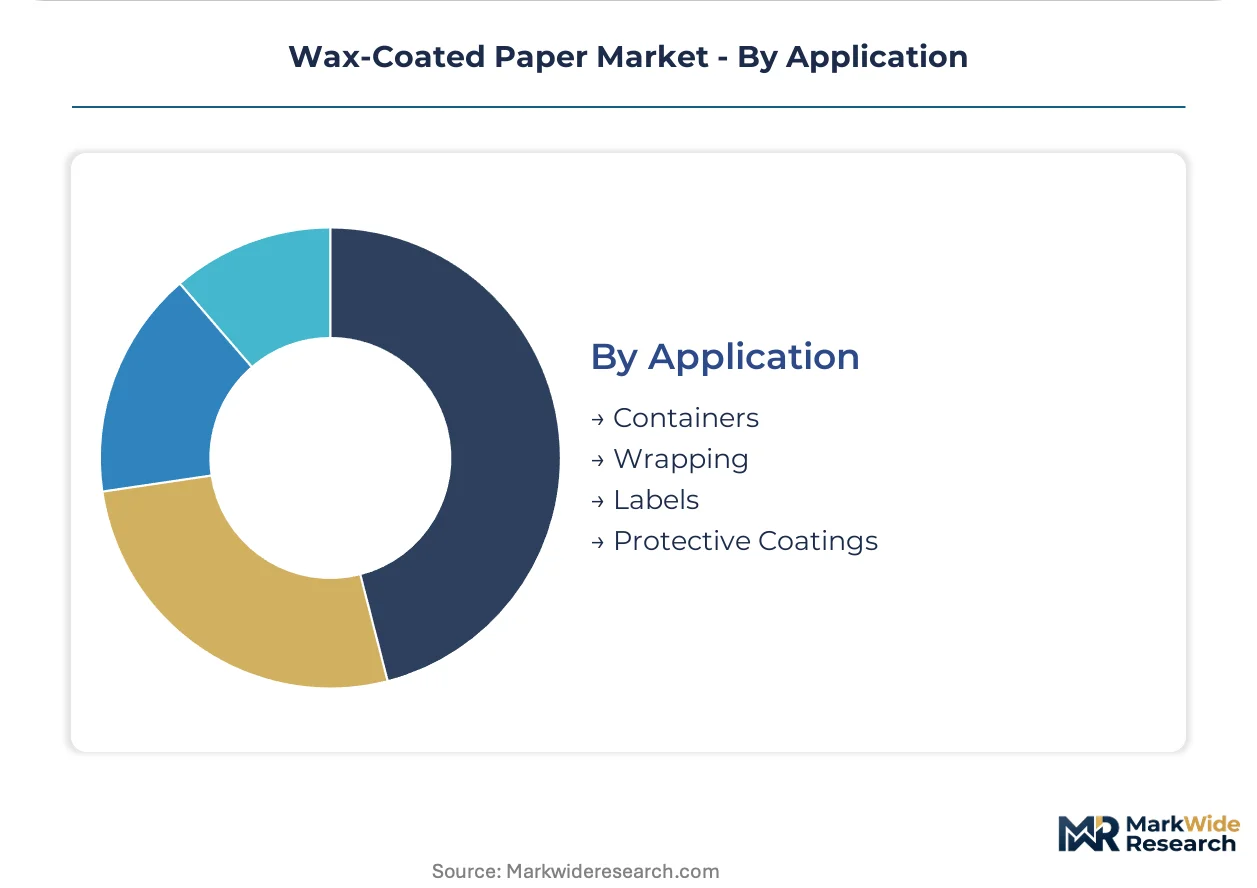
Application:
Functional requirements for moisture barrier performance and grease resistance dictate substrate and wax formulation selection.
- Wrapping:Cold-chain sandwich papers and patty interleaving demand grease resistance below 10 g/m²/day moisture vapor transmission. Quick-service restaurant chains in the US and Germany are adopting inline near-infrared spectroscopy for real-time quality verification.
- Containers:Molded pulp trays and folding carton liners for ready-meal packaging. E-commerce cold-chain shipping is creating demand for wax-impregnated kraft liners replacing polyethylene-coated alternatives in EU markets.
- Labels:Pressure-sensitive adhesive face stocks requiring release coating compatibility. Vegetable wax formulations struggle with printability versus paraffin alternatives.
- Protective Coatings:Temporary corrosion barriers for steel coil and aluminum sheet during transit. Industrial buyers prioritize lowest unit cost over biodegradability credentials.
Wrapping holds the dominant position, while Containers is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power tilts toward European converters facing qualified-supplier scarcity under EFSA migration timelines, while US buyers leverage FDA notification acceleration to compress procurement cycles. This asymmetry reshapes cross-border investment flows as mills calibrate regional capacity.
United States
Institutional foodservice chains drive grease-resistant grade demand through direct mill contracts with indexed Brent crude pricing. FDA 21 CFR 176.170 notification timelines have compressed to nine months for qualified wax compositions, accelerating supplier qualification. Wisconsin and Michigan manufacturing clusters concentrate coating capacity serving quick-service restaurant procurement teams.
Germany
EU Circular Packaging Mandates enforce minimum recycled-content thresholds for food-contact papers, creating qualified-supplier bottlenecks. EFSA safety opinions for post-consumer fiber wax papers lag commercial demand by 12-18 months. The Rhineland manufacturing corridor faces coating technician shortages as solvent-based expertise retires faster than apprenticeship programs replenish.
China
SAMR's 2024 GB standard revision expedites approval for rice bran and carnauba waxes, opening qualified-supplier gaps for converters with existing EFSA dossiers. E-commerce cold-chain shipping generates demand for wax-impregnated kraft liners replacing polyethylene alternatives. Yangtze River Delta coating operations anchor Asia-Pacific production scale through captive pulp sourcing.
India
FSSAI drafting of food-contact paper standards will displace loose plastic wrapping in organized retail, creating first-mover advantages for wax-coated bread and confectionery papers. Quick-service restaurant expansion in Mumbai and Delhi-NCR drives cold-chain sandwich wrapping demand. Maharashtra and Gujarat industrial zones concentrate emerging converter capacity.
Netherlands
Recycled-content wax paper demand concentrates here as EU Single-Use Plastics Directive enforcement tightens. EFSA safety opinions for post-consumer fiber grades create qualified-supplier scarcity for converters serving European consumer goods brands. Rotterdam logistics hubs facilitate distribution to German and French packaging converters.
Wax-Coated Paper Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream. The vendor base stratifies between integrated paper mills with captive coating capabilities and mid-cap converters dependent on toll coating relationships. Three archetypes dominate: vertically integrated pulp-to-coating operators, specialty lightweight grade specialists, and regional merchant converters serving industrial buyers. Capacity expansion and direct procurement displacement of distribution intermediaries constitute the dominant competitive moves.
Within the integrated operator tier, Dunn Paper Company and Oji Holdings Corporation exemplify platform control through captive pulp sourcing and multi-site coating operations. Seaman Paper Co. occupies a specialist position targeting premium confectionery and quick-service restaurant segments with lightweight calendered grades. These three anchors illustrate how coating capability depth and regulatory qualification breadth separate tier-one suppliers from commodity converters.
| Leading Market Players |
|---|
| CGP Coating Innovation |
| Charlotte Packaging Ltd |
| Dunn Paper Company |
| Novolex |
| THE GRIFF NETWORK |
| Seaman Paper Co. |
| Grantham Manufacturing Ltd |
| Oji Holdings Corporation |
| Paradise Packaging |
| Others |
Value Chain & Pricing Dynamics
Crude oil price volatility acts as the dominant risk vector compressing converter margins when Brent crude-linked pass-through clauses lag by 60-90 days, simultaneously widening spreads between standard paraffin grades and premium bio-based alternatives while reshaping sourcing strategies toward captive pulp integration and multi-site coating redundancy.
Pricing Analysis
The customization-premium spread separates configured-to-order FDA food-contact grades from standard unbleached industrial specifications. Contract-based long-term offtake dominates institutional foodservice procurement, with price differentiation driven by certification tier and volume scale. Cost compression in commodity paraffin grades is intensifying because bio-based alternatives struggle with migration limit compliance timelines. Quick-service restaurant chains exhibit lowest price sensitivity due to regulatory qualification scarcity, while industrial surface protection buyers prioritize unit economics above all else.
Supply Chain Analysis
EU REACH Annex XIV authorization requirements for microcrystalline wax constituents constrain flows of legacy paraffin blends into European manufacturing. Supply concentrates in the United States, Germany, and China as dominant coating capacity hubs. The chain draws from kraft pulp, paraffin feedstocks, and vegetable wax alternatives including carnauba and candelilla. Single-source vulnerability concentrates in Ethiopian and Vietnamese beeswax supply for food-grade applications. Distribution runs through direct mill-to-converter relationships displacing traditional merchant intermediaries in North America and Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Single-Use Plastics Directive enforcement constitutes a regulatory inflection compressing petrochemical wax demand while bio-based alternatives face protracted approval timelines, creating a high-growth disruption window for qualified converters with parallel FDA and EFSA dossiers.
For Market Incumbents: Pre-empt coating technician shortages accelerating across US Midwest and Rhineland manufacturing clusters by expanding apprenticeship programs and digitizing solvent-based application expertise through inline near-infrared spectroscopy systems. Secure backward integration into captive pulp sourcing to defend margin position against Brent crude volatility, while accelerating carnauba and candelilla wax trials to outpace REACH Annex XIV sunset deadlines. For New Entrants and Emerging Players: Pursue qualified-supplier gaps in recycled-content wax papers for EU consumer goods brands, where EFSA safety opinions lag commercial demand by 12-18 months. Target India's organized retail modernization as FSSAI standards displace loose plastic wrapping, offering first-mover shelf-space commitments in bread and confectionery papers. Deploy technical sales teams capable of navigating dual FDA and EFSA compliance documentation as the primary go-to-market angle. For Investors and Strategic Acquirers: Specialty lightweight grade specialists with existing EFSA dossiers and multi-site coating operations represent the most attractive acquisition target archetype for long-term viability across a 5-10 year window. Monitor SAMR's expedited bio-wax approval pathways as the critical signal indicating which converters can bridge Chinese and European qualification requirements fastest.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Pulp Sourcing | Dunn Paper Company and Oji Holdings Corporation anchor cost control through in-house fiber supply. |
| Dual Certification Investment | Parallel FDA and EFSA compliance pathways stretch mid-cap converter balance sheets but deepen qualified-supplier moats. |
| Inline Spectroscopy Deployment | Real-time wax weight verification cuts defect rates and enables narrower specification bands reducing over-application costs. |
| Bio-Based Wax Reformulation | REACH Annex XIV sunset dates for microcrystalline constituents force accelerated carnauba and candelilla trials. |
| Direct Procurement Consolidation | Aramark and Compass Group vendor list compression to fewer than five suppliers per SKU category locks in multi-year commitments. |
Study Parameters
Cross-validation between primary interviews with coating line supervisors, procurement leads at institutional foodservice buyers, regulatory affairs specialists, and distribution channel partners anchors the qualitative findings against secondary validation from FDA 21 CFR 176.170 filings, EFSA safety opinions, customs and trade data, and SEC 10-K disclosures from integrated paper mills. Bottom-up demand modeling across food packaging, industrial use, and consumer goods segments triangulates with top-down macroeconomic calibration.
Calibration against historical price transmission patterns and regulatory approval timelines shapes the analytical framework across the projection horizon. Segmentation dimensions include product grade tier, end-use vertical, distribution channel structure, and regional regulatory cluster. CAGRs derive from installed coating capacity expansion rates, pulp cost trajectories, and substitution elasticity between wax-coated papers and plastic laminates. Forecast inputs incorporate EFSA migration study completion timelines and SAMR GB standard revision implementation pace.
Sensitivities concentrate around EFSA safety opinion delays for recycled-content grades, Brent crude benchmark swings, and coating technician retirement rates exceeding apprenticeship program throughput. Forecasts reflect assumptions regarding regulatory divergence persistence and bio-based wax formulation performance thresholds. Material shifts in EU Circular Packaging Mandate enforcement intensity or FDA notification timeline compression would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Die Cut Box Market
Paper & Paperboard Packaging
India Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Cold Waxed Paper Cups Market
Paper & Paperboard Packaging
Australia Corrugated Board Packaging Market
Paper & Paperboard Packaging
Impregnated Paper Market
Paper & Paperboard Packaging
Fast Food Wrapping Paper Market
Paper & Paperboard Packaging
Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
Wrapping Paper Market
Paper & Paperboard Packaging
Waxed Paper Packaging Market
Paper & Paperboard Packaging
Paper Edge Protectors Market
Paper & Paperboard Packaging
Letterpress Card Market
Paper & Paperboard Packaging
Paper Cup Machine Market
Paper & Paperboard Packaging
Canada Paper Packaging Market
Paper & Paperboard Packaging
Corrugated Fish Box Market
Paper & Paperboard Packaging
Polycoated Paper Packaging Market
Paper & Paperboard Packaging
Mottled Test Liner Market