
 Pasted Valve Bags Market | 2026-2036
Pasted Valve Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Pasted Valve Bags Market Analytics
Buyer concentration in the cement and construction materials sector is pivoting toward automated packaging lines that demand precision-fitted pasted valve bags. Mondi Group leverages its European manufacturing footprint to supply high-volume cement producers with customized paper-based valve solutions. Smurfit Kappa anchors its position through integrated containerboard and converted bag operations across multiple geographies. International Paper competes on sustainable fiber sourcing, aligning its kraft paper grades with customer carbon-reduction mandates.
Pasted valve bags are multi-wall paper or composite containers with self-sealing valve openings designed for high-speed filling of powdered or granular materials; typical constructions use 2-4 plies of extensible sack kraft paper with PE film barriers to achieve burst strengths exceeding 300 kPa and moisture resistance below 5% water vapor transmission. The bags serve primarily as shipping containers for cement, chemicals, and food ingredients where dust-free discharge and pallet stability matter. Paper material types dominate volume due to established recycling infrastructure, though composite constructions capture margin pools in moisture-sensitive chemical applications. Food industry end users represent the fastest-growing demand segment as pasteurized dairy powders and specialty flours shift from sewn bags to valve-sealed formats for hygienic filling. Capacity segmentation clusters around 25 kg and 50 kg formats, with the latter sustaining pricing power in European construction markets where manual handling regulations limit single-lift weights.
REACH restrictions on fluorinated compounds and heavy metals in packaging materials are forcing European producers toward unbleached kraft and bio-based barrier coatings. FDA food-contact notification requirements govern laminated structures serving North American dairy and ingredient processors, while China's GB standards for food packaging paper impose migration limits that shape export-oriented supplier qualifications. Stakeholders must monitor regulatory divergence between EU packaging waste directives and emerging state-level extended producer responsibility laws in the United States, as compliance costs will increasingly determine regional sourcing decisions and manufacturing location strategies.
Market Dynamics
Automated filling line adoption across cement and construction material plants is compressing the supplier base toward precision-engineered pasted valve bag manufacturers capable of sub-3% fill-weight variance. This technical threshold eliminates regional converters lacking servo-driven conversion equipment.
Growth Catalysts
- REACH fluorinated compound restrictions:European ECHA enforcement is redirecting chemical producers toward bio-based barrier coatings that pasted valve bags accommodate more readily than sewn alternatives.
- China's GB food packaging standards:Export-oriented dairy powder processors are qualifying valve-sealed formats to meet migration limits that sewn bags struggle to satisfy.
- High-speed form-fill-seal integration:German packaging machinery OEMs are specifying pasted valve interfaces as default for new cement plant installations above 2,000 bags per hour.
Market Restraints
- Extensible sack kraft pulp concentration:Nordic pulp mill consolidation has tightened supply of the specific long-fiber grades required for 300 kPa burst strength.
- PE film barrier cost volatility:Ethylene feedstock fluctuations directly compress margins on moisture-resistant composite constructions.
- Manual handling weight limits:European Union ergonomic directives cap single-lift loads at 25 kg, fragmenting demand away from the more efficient 50 kg format.
Strategic Opportunities
- India's FSSAI processed food expansion:Pasteurized spice and dairy powder segments remain underpenetrated by valve-sealed formats relative to sewn multiwall.
- US state-level extended producer responsibility laws:Emerging packaging waste mandates in California and New York favor recyclable paper-based valve bags over plastic alternatives.
- Near-infrared sorting compatibility:Convergence of digital printing identification with automated waste stream sorting opens closed-loop recovery contracts with retail cement distributors.
Industry Challenges
- Servo-driven conversion technician scarcity:European and North American bag converters face recruitment gaps for operators capable of maintaining ±1 mm valve placement tolerance.
- FDA food-contact notification timelines:Laminated structures for North American dairy applications require 120-180 day pre-market clearance cycles that delay customer qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pasted Valve Bags Market |
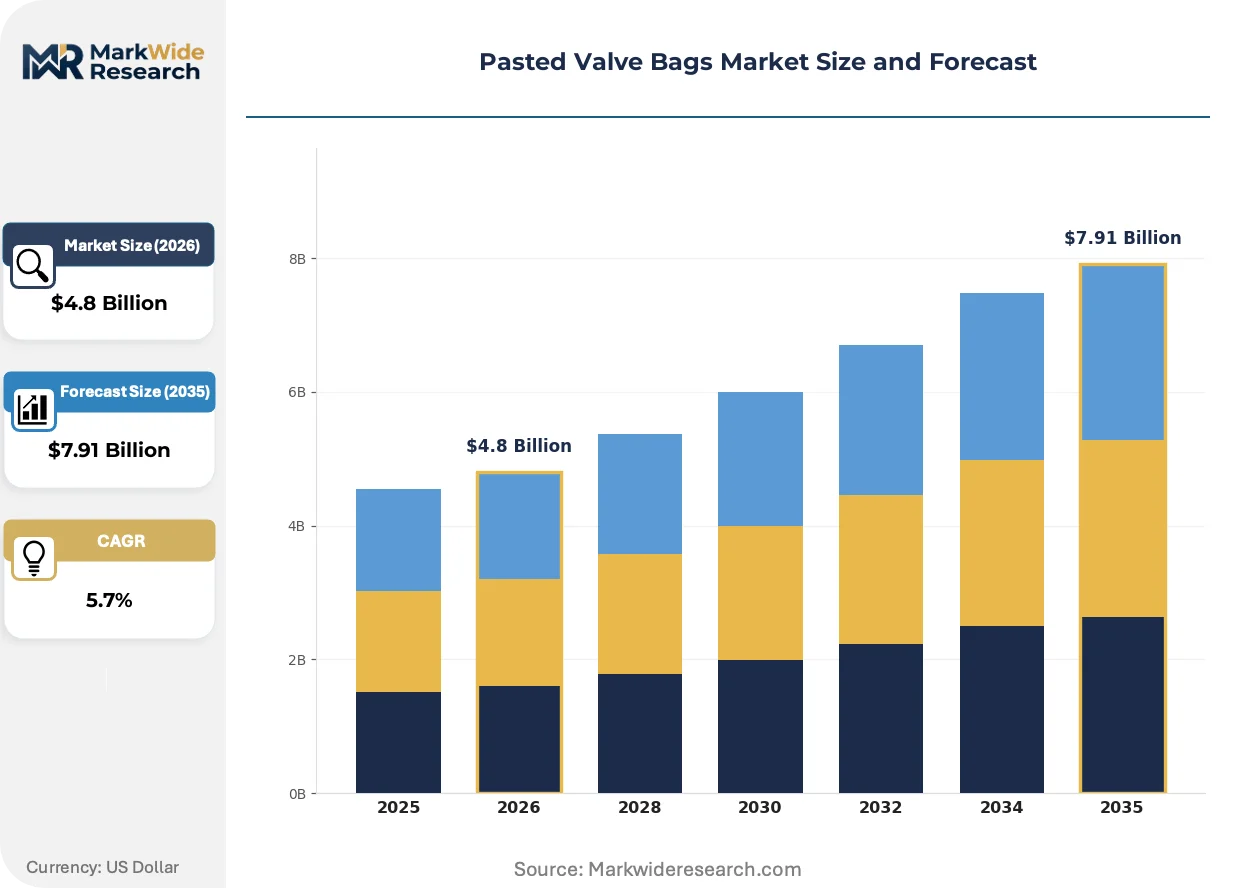
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Paper, Plastic, Jute, Composite End User: Food Industry, Chemical Industry, Agricultural Sector, Construction Capacity: 25 kg, 50 kg, 100 kg, 1 ton Closure Type: Valveless, Sewn, Heat Sealed, Others |
| Companies Covered | Mondi Group, International Paper, Smurfit Kappa, Sealed Air Corporation, Amcor Limited, Novolex, Ahlstrom-Munksjö, Sappi Limited, Schur Star Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pasted Valve Bags Market Evolving Landscape
Digital printing and inline quality verification are converging to transform pasted valve bags from commodity shipping containers into traceable, brand-differentiated packaging assets. This shift repositions the format upstream in customer value chains.
Water-based barrier coating technology is decentralizing moisture protection away from polyethylene film laminates. Scandinavian paper mills are commercializing cellulose-derived treatments that achieve below-5% water vapor transmission without heat-seal layers. Cement producers in Germany and France are piloting these constructions to satisfy carbon-reduction mandates. The technology is decentralizing composite supply chains toward single-material recovery streams that municipal sorting facilities can process.
EU F-Gas Regulation phase-down schedules are accelerating adoption of non-fluorinated grease-resistant treatments in food-contact pasted valve bags. ECHA restriction proposals on per- and polyfluoroalkyl substances are forcing reformulation of barrier coatings by Q4 2025. Italian and Spanish ingredient processors are pre-qualifying alternative constructions to avoid supply disruption. Dairy powder exporters to the European Union face the most compressed compliance timelines.
Consolidated procurement by multinational cement groups is compressing supplier panels toward integrated converters with multi-continent manufacturing footprints. Buyers are unbundling bag supply from machinery maintenance contracts to secure volume pricing leverage. This pattern concentrates contract awards in Germany, China, and the United States where automated filling line density justifies dedicated supply agreements. Regional converters without multinational scale face exclusion from tier-one supplier lists.
Pasted Valve Bags Market Segmentation
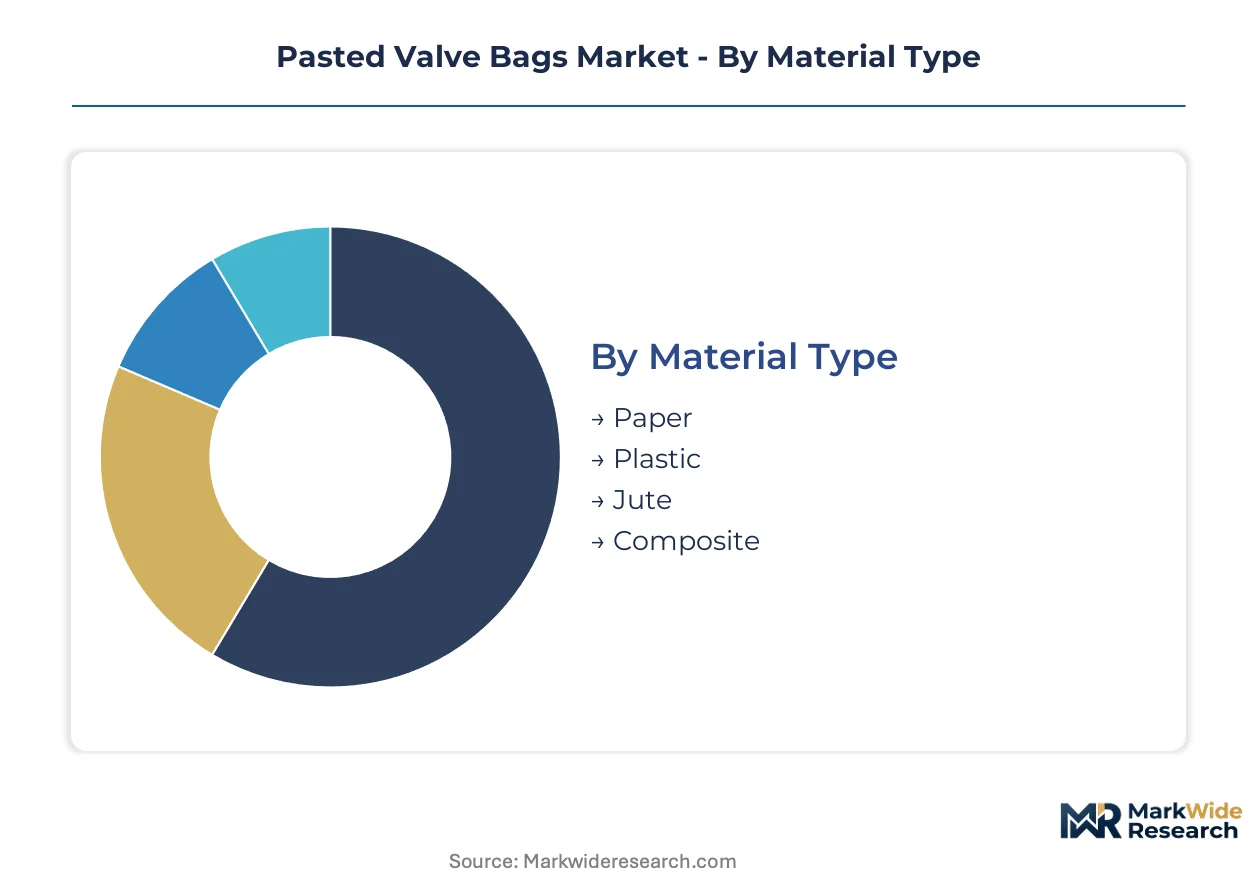
Pasted valve bag specifications diverge sharply across material substrates and end-use requirements. Procurement decisions hinge on barrier performance, filling line compatibility, and regional recycling infrastructure rather than unit cost alone.
Material Type:
Supply of extensible sack kraft pulp concentrates among Nordic long-fiber producers, shaping converter access to high-burst-strength grades.
- Paper:Multi-ply extensible sack kraft constructions dominate cement and construction applications due to established European recycling streams. German and French cement producers specify unbleached grades to satisfy carbon-reduction mandates from major building materials groups.
- Composite:PE film laminates bonded to kraft substrates achieve moisture resistance below 5% water vapor transmission for hygroscopic chemical powders. Scandinavian mills are piloting cellulose-derived barrier coatings that displace polyethylene layers without sacrificing performance.
- Plastic:Woven polypropylene valve bags serve agricultural bulk feed applications where moisture protection exceeds paper capabilities.
- Jute:Natural fiber constructions retain niche demand for specialty agricultural exports requiring biodegradable disposal.
Paper absorbs the bulk of installed capacity; composite is expanding most quickly as chemical processors reformulate barrier specifications.
End User:
Customer procurement patterns split between price-sensitive bulk commodity buyers and specification-driven food processors.
- Construction:Cement multinational procurement panels concentrate contract awards on converters with multi-continent manufacturing footprints. Automated filling lines above 2,000 bags per hour demand sub-3% fill-weight variance that eliminates regional suppliers lacking servo-driven equipment.
- Food Industry:Pasteurized dairy powder and specialty flour processors are shifting from sewn bags to valve-sealed formats. China's GB standards for food packaging paper impose migration limits that shape supplier qualification for export-oriented processors.
- Chemical Industry:REACH fluorinated compound restrictions redirect producers toward bio-based barrier coatings that pasted valve bags accommodate more readily than sewn alternatives.
- Agricultural Sector:Bulk grain and feed operations prioritize unit economics over precision filling, sustaining demand for basic multiwall constructions.
Construction commands the largest volume share; food industry applications are climbing the fastest as hygienic filling requirements tighten.
Capacity:
Regulatory weight limits fragment demand between ergonomic-compliant formats and efficient bulk shipping sizes.
- 50 kg:Standard cement shipping format sustains pricing power in markets without manual handling restrictions. German packaging machinery OEMs specify 50 kg valve interfaces as default for new plant installations.
- 25 kg:European Union ergonomic directives cap single-lift loads, forcing construction sector adoption despite reduced logistics efficiency. Retail cement distributors favor this format for consumer-facing channels.
- 100 kg:Intermediate bulk format serves specialty chemical applications with automated handling infrastructure.
- 1 ton:Bulk bag replacement applications in agricultural commodity storage.
50 kg retains dominant production share; 25 kg is gaining share fastest as regulatory compliance spreads beyond European borders.
Closure Type:
Automation compatibility distinguishes valve-based formats from labor-intensive alternatives in procurement evaluations.
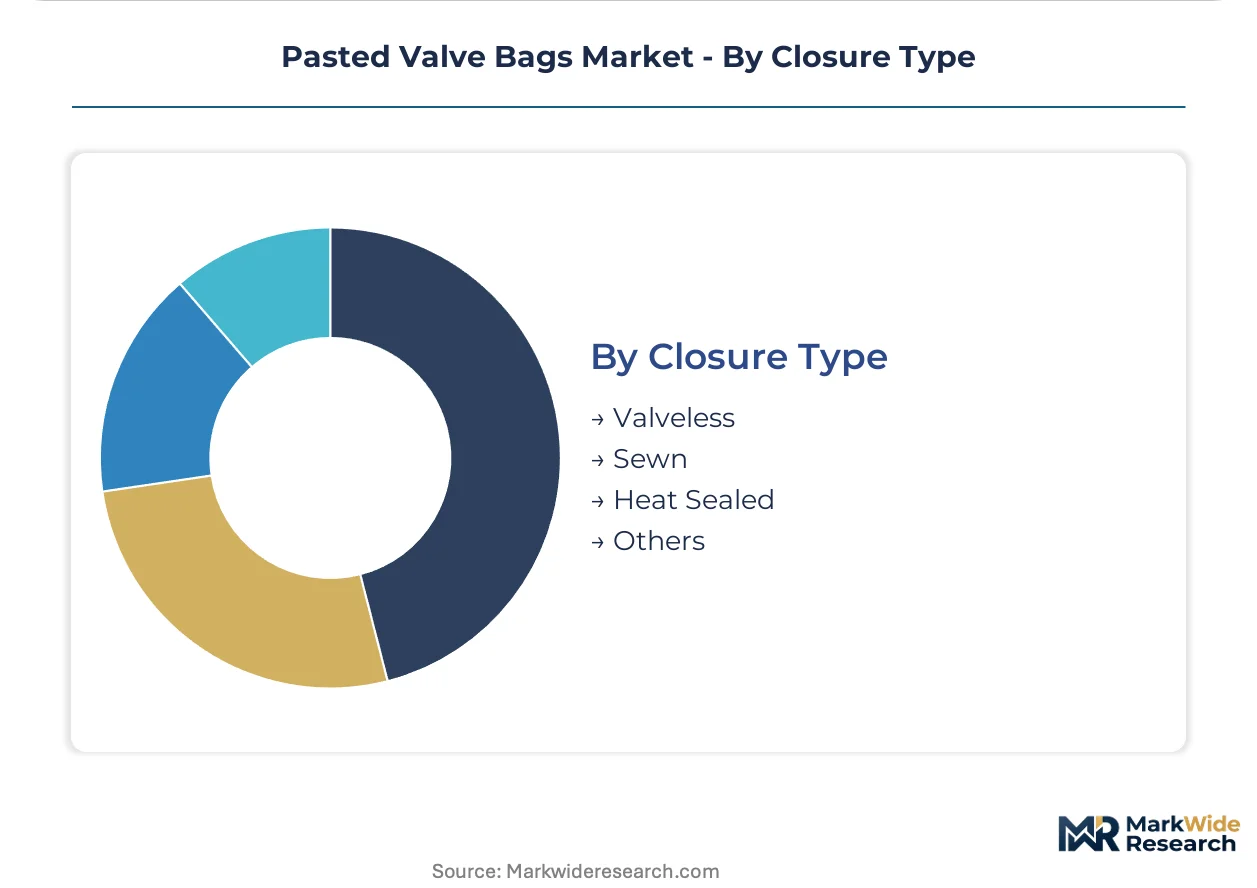
- Valveless:Basic pinch-bottom constructions serve low-value agricultural applications where dust containment is secondary.
- Sewn:Traditional stitched closures retain position in manual filling operations but face displacement from automated lines.
- Heat Sealed:Thermal closure systems integrate with form-fill-seal machinery for high-volume chemical packaging.
- Others:Specialty adhesive and tape-sealed formats for custom applications.
Sewn closures still occupy substantial legacy capacity; heat sealed formats are expanding fastest alongside packaging line automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cement producers in Germany, China, and the United States are driving procurement of precision-fitted pasted valve bags for automated filling lines above 2,000 bags per hour. This demand concentration shapes regional supply strategies and regulatory compliance investments across three distinct manufacturing clusters.
Germany
REACH fluorinated compound restrictions from ECHA are redirecting chemical processors toward bio-based barrier coatings. German cement multinationals specify unbleached kraft grades to satisfy carbon-reduction mandates. The Rhine-Ruhr industrial corridor hosts converter operations supplying high-volume automated plants with sub-3% fill-weight variance specifications.
China
Export-oriented dairy powder processors are qualifying valve-sealed formats to meet GB standards for food packaging paper migration limits. Domestic cement capacity expansion in Shandong and Hebei provinces sustains demand for 50 kg formats. Yangtze River Delta converters are upgrading servo-driven equipment to serve multinational procurement panels.
United States
State-level extended producer responsibility laws in California and New York favor recyclable paper-based valve bags over plastic alternatives. FDA food-contact notification requirements govern laminated structures for dairy and ingredient processors. Gulf Coast petrochemical clusters supply PE film laminates for moisture-resistant composite constructions.
India
FSSAI processed food expansion is penetrating pasteurized spice and dairy powder segments previously dominated by sewn multiwall. Cement sector automation remains below German and Chinese benchmarks, creating retrofit opportunities. Gujarat and Maharashtra industrial zones host regional converters seeking multinational qualification.
France
EU F-Gas Regulation phase-down schedules are accelerating non-fluorinated grease-resistant treatment adoption for food-contact applications. French cement producers pilot cellulose-derived barrier coatings from Scandinavian mills. The Lyon-Grenoble chemical corridor drives specification shifts for hygroscopic powder packaging.
Pasted Valve Bags Market Competitive Landscape
European producers anchor the integrated tier; North American specialists hold positions in sustainable fiber sourcing and food-contact compliance. The supplier base compresses toward converters with multi-continent manufacturing footprints capable of serving consolidated multinational procurement panels. Three archetypes dominate: integrated paperboard converters with captive kraft supply, specialty barrier coating innovators, and regional machinery-integrated fabricators. Competitive moves center on backward integration into extensible sack kraft pulp and strategic partnerships with German packaging machinery OEMs.
Among the integrated paperboard tier, Mondi Group and Smurfit Kappa exemplify European-based converters with multi-continent manufacturing footprints. International Paper occupies a position representing North American sustainable fiber sourcing alignment. These three anchors illustrate how geographic manufacturing spread and regulatory compliance capabilities determine qualification for tier-one supplier lists serving automated cement and food processing lines.
| Leading Market Players |
|---|
| Mondi Group |
| International Paper |
| Smurfit Kappa |
| Sealed Air Corporation |
| Amcor Limited |
| Novolex |
| Ahlstrom-Munksjö |
| Sappi Limited |
| Schur Star Systems |
| Others |
Value Network & Pricing Analysis
EU carbon-reduction mandates for construction materials gate premium-tier pricing access for pasted valve bag converters, forcing cement multinationals to qualify suppliers with certified low-carbon kraft grades while regional players absorb margin compression from unqualified supply.
Pricing Analysis
Volume cement contracts trade at thin margins while food-grade barrier constructions command premium spreads. Three-tier pricing structure across certified sustainable, standard kraft, and basic multiwall levels separates multinational procurement panels from regional construction buyers. Cost compression in standard kraft grades is intensifying because Nordic pulp mill consolidation has tightened long-fiber supply. Agricultural bulk feed operators exhibit highest price sensitivity; dairy powder processors under China's GB standards show lowest.
Supply Chain Analysis
Extensible sack kraft pulp rests on Nordic long-fiber producers in Sweden, Finland, and Norway, with PE film laminates drawing from Gulf Coast petrochemical clusters. Critical inputs include long-fiber softwood pulp, ethylene-based barrier films, and servo-driven conversion equipment. Single-source vulnerability concentrates in high-burst-strength kraft grades from consolidated Scandinavian mills. Distribution runs through multinational cement group procurement panels and regional converter networks serving automated filling line operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around automated filling line density, with servo-driven conversion equipment requirements forcing weaker regional converters out of tier-one supplier qualification.
For Market Incumbents: Hedge against Nordic pulp supply concentration by securing captive long-fiber agreements or alternative bio-based barrier partnerships. Cement multinational procurement consolidation threatens volume access; food-grade FDA notification investment opens defensible margin pools in dairy powder segments. For New Entrants and Emerging Players: The 40-60% price spread between premium certified-sustainable and economy basic kraft constructions offers white-space entry. India's FSSAI-processed food segment remains underpenetrated by valve-sealed formats versus sewn multiwall. Target regional dairy cooperatives with GB-compliant export qualifications as initial beachhead. For Investors and Strategic Acquirers: German packaging machinery OEM specification of pasted valve interfaces as default for new cement installations above 2,000 bags per hour is the leading indicator that servo-capable converter assets will command scarcity premiums. Five-to-ten-year viability favors integrated players with multi-continent manufacturing footprints. Watch ECHA restriction proposal enforcement timelines for per- and polyfluoroalkyl substances as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Extensible Sack Kraft | Captive Nordic long-fiber supply secures burst-strength certification for automated cement lines. |
| Water-Based Barrier Coating Commercialization | Scandinavian cellulose-derived treatments displace PE laminates for EU carbon-mandate compliance. |
| Servo-Driven Conversion Equipment Upgrade | Sub-3% fill-weight variance capability qualifies suppliers for multinational procurement panels. |
| FDA Food-Contact Notification Investment | 120-180 day pre-market clearance cycles create qualification moats in North American dairy. |
| Multi-Continent Manufacturing Footprint Expansion | Germany-China-United States presence matches cement automation density for contract concentration. |
Research Methodology
Multi-period observation of cement plant automation rates, pulp mill consolidation patterns, and regulatory enforcement timelines anchored the trend analysis, supplemented by interviews with packaging machinery OEM specification engineers, cement procurement directors, dairy powder processing executives, and Nordic pulp mill technical sales leads. Secondary validation drew from ECHA restriction proposals, FDA food-contact notification databases, Chinese GB standard migration limit tables, and customs trade flow records. Bottom-up segment sizing triangulated against top-down industry value estimates.
Input-output matrices modeled demand drivers across material substrate, end-use vertical, capacity format, and regional regulatory cluster dimensions throughout the forecast period. CAGRs derived from trend extrapolation of filling line automation adoption, weighted by regional cement capacity expansion and food-grade qualification timelines. Industry-specific forecast inputs included servo-driven equipment installation rates and bio-based barrier coating commercialization curves.
Underlying measurement precision varies by segment; construction automation metrics carry tighter precision than emerging food-grade penetration estimates. Forecasts reflect documented assumptions on regulatory enforcement intensity and pulp supply consolidation trajectories. ECHA per- and polyfluoroalkyl substance restriction implementation, Nordic mill capacity decisions, and Indian FSSAI enforcement scaling warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Drum Liners Market
Bags and Containers
Bag-In-Box Packaging Market
Bags and Containers
Bag in Drum Market
Bags and Containers
Counter Bags Market
Bags and Containers
Global Household Food Storage Containers Market
Bags and Containers
Grip Seal Bags Market
Bags and Containers
Vertical Form Fill Seal Baggers Market
Bags and Containers
Ziplock Food Bags Market
Bags and Containers
Quad Seal Bag Market
Bags and Containers
Woven Sacks Market
Bags and Containers
Bagster Bag Market
Bags and Containers
Inclusion Bags Market
Bags and Containers
Conductive Bags Market
Bags and Containers
Block Sack Market
Bags and Containers
Anti-Static Polyethylene Bag Market
Bags and Containers
Twin Seal Bags Market