
 Sublimation Paper Market | 2026-2036
Sublimation Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Sublimation Paper Market Analytics
Asset-light leasing models for wide-format heat press systems is tilting competitive dynamics toward smaller print shops that previously faced high capital barriers. Felix Schoeller leverages its European coating expertise to sustain premium positioning in high-release formulations. Ahlstrom-Munksjö anchors industrial-scale supply through its specialty paper infrastructure across multiple continents. Jiangyin Mecoxpan New Material dominates volume production by operating integrated pulp-to-coating facilities near China's textile hubs.
Sublimation paper functions as a temporary carrier substrate engineered with controlled porosity and silica-barrier coatings to release dye vapor under heat press conditions above 180°C, transferring permanent images onto polyester-based textiles and polymer-coated hard substrates. Transfer paper and coated paper segments lead current volume, while specialty paper commands the highest margin pools due to custom formulations for rigid substrates and industrial textiles. Application demand concentrates in textiles and promotional products, where small-batch customization and fast turnaround requirements favor inkjet-compatible paper grades over traditional screen-transfer methods.
EPA regulations on volatile organic compound emissions from coating operations shape U.S. manufacturing facility requirements, while REACH and RoHS frameworks in Europe restrict specific chemical additives in thermal-release coatings. China's GB standards and MEE environmental enforcement are tightening wastewater and air emission controls for paper coating plants in the Yangtze River Delta. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional formulation adaptation or unified global product platforms offer superior returns.
Market Dynamics
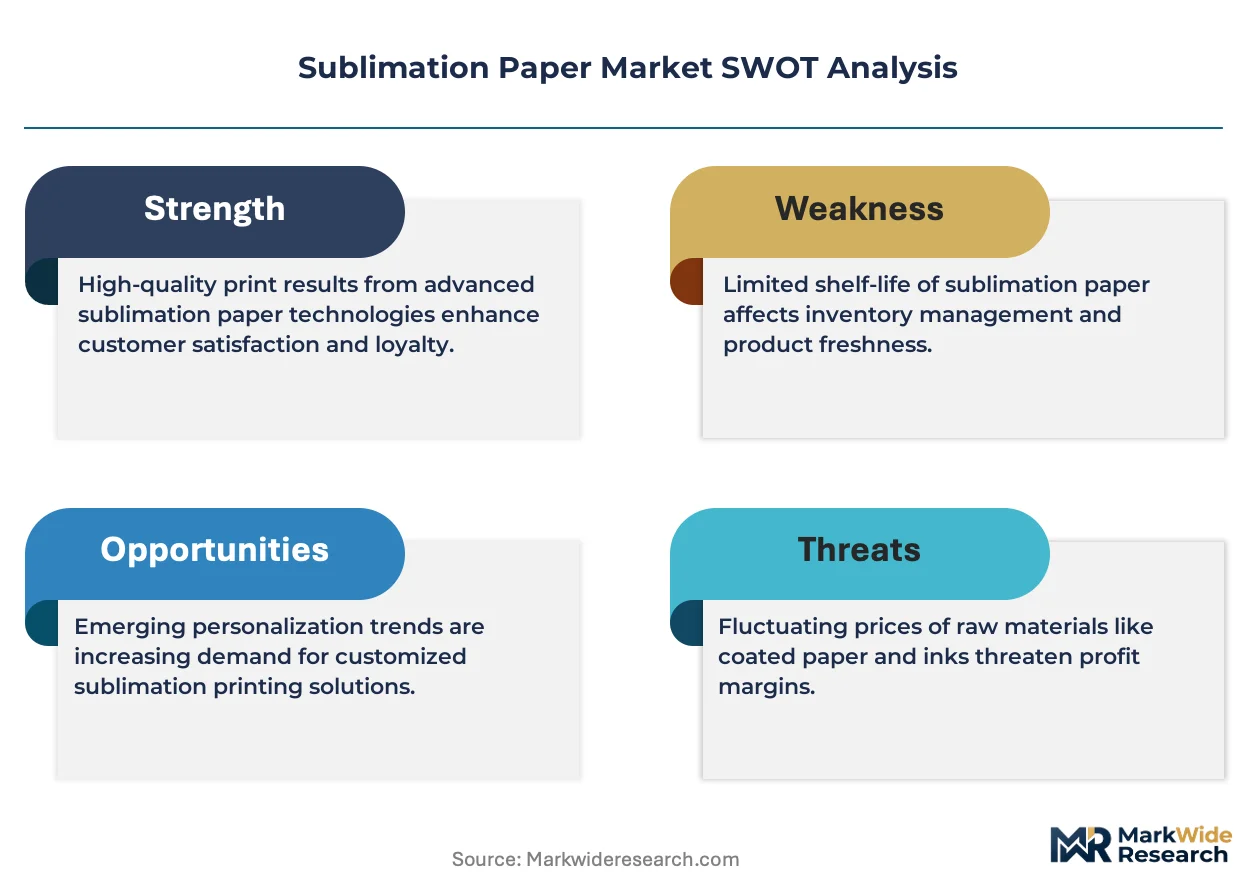
Coating chemistry compliance under REACH and evolving EU Green Deal packaging rules is forcing reformulation investments across the supply base, while China's MEE environmental enforcement tightens wastewater controls in the Yangtze River Delta production belt.
Growth Catalysts
- Apparel Customization Surge:Small-batch sportswear producers are expanding sublimation adoption for team uniforms and fan merchandise. This demand favors inkjet-compatible paper grades with fast turnaround capabilities.
- REACH Chemical Compliance:European coating standards are driving premium-grade formulation upgrades. Manufacturers investing in compliant silica-barrier coatings capture margin pools in rigid substrate applications.
- Heat Press Leasing Models:Asset-light equipment financing is removing capital barriers for smaller print shops. This channel expansion broadens the addressable base for mid-grade transfer paper volumes.
Market Restraints
- Pulp Cost Volatility:Hardwood pulp prices fluctuate with energy and logistics inputs. Coating facilities face margin compression when unable to pass through raw material swings.
- Supply Concentration Risk:China's Zhejiang and Guangdong provinces dominate integrated pulp-to-coating output. Geographic clustering creates vulnerability to regional environmental enforcement actions.
- Polymer-Coating Substitution:Direct-to-garment inkjet systems are encroaching on low-volume textile transfers. Paper-based sublimation faces displacement in sub-50-unit print runs.
Strategic Opportunities
- Industrial Textile Expansion:Polyester-based automotive interiors and architectural soft signage represent underpenetrated end-uses. Custom release coatings for heavy fabrics command premium positioning.
- EU Green Deal Packaging Alignment:Recyclable coating formulations qualify for public procurement preferences. Early movers capture tender advantages in European institutional markets.
- Digital Workflow Convergence:Integration between RIP software and paper calibration profiles reduces waste. Print shops adopting closed-loop color management upgrade to certified paper grades.
Industry Challenges
- Coating Technician Shortage:Silica-barrier formulation expertise concentrates in legacy European and Japanese facilities. Emerging market plants struggle to replicate consistent release characteristics.
- Dual Certification Timelines:Simultaneous EPA VOC compliance and REACH chemical registration extend product launch cycles. Smaller manufacturers lack regulatory affairs bandwidth for parallel filings.
- Legacy Heat Press Integration:Older pneumatic systems lack precise temperature zone control. Paper suppliers field technical support demands for calibration mismatches not of their making.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sublimation Paper Market |
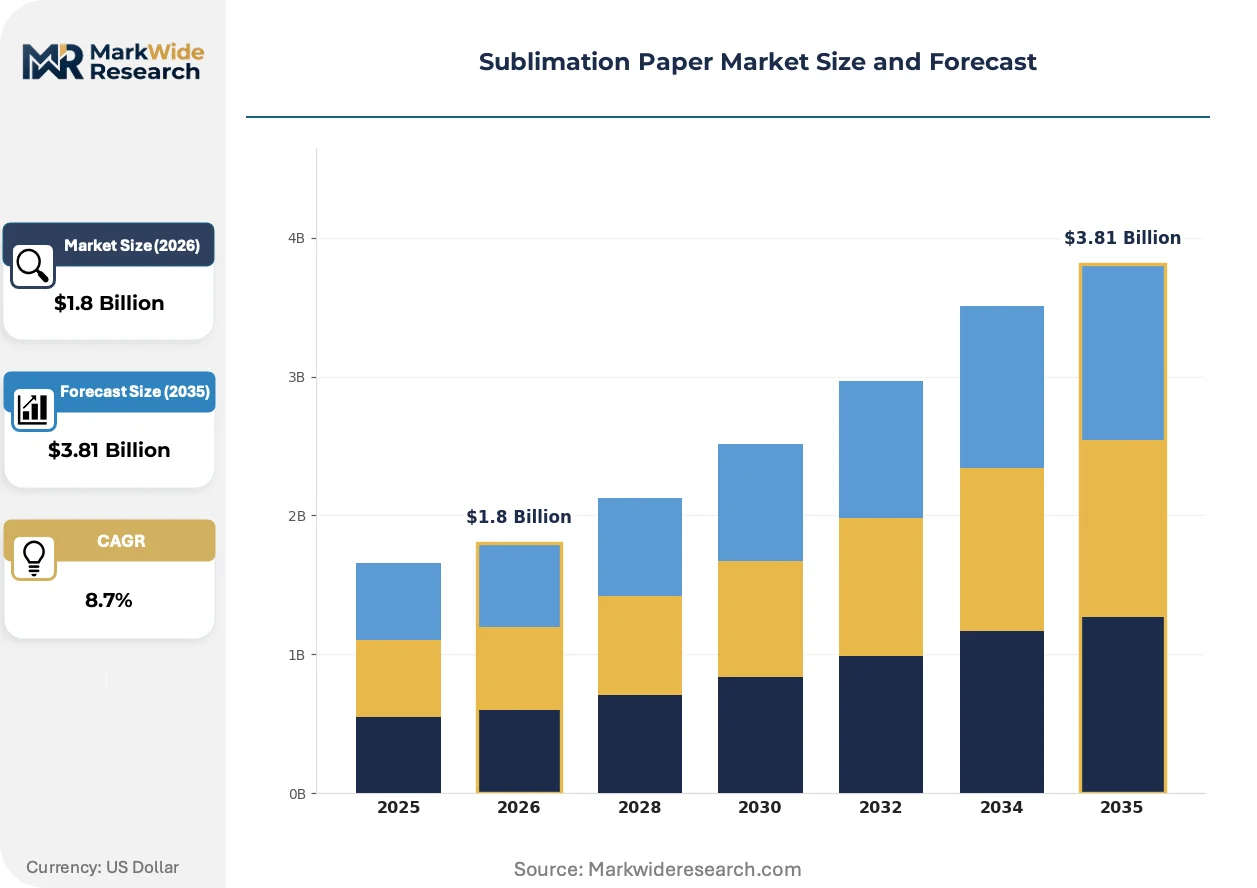
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transfer Paper, Coated Paper, Specialty Paper, Inkjet Paper Application: Textiles, Promotional Products, Personal Items, Home Décor End User: Manufacturers, Small Businesses, Home Users, Artists Distribution Channel: Online Retailers, Specialty Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Felix Schoeller, Jiangyin Mecoxpan New Material, Beaver Paper, Million Ton New Material, A-SUB, Ahlstrom-Munksjö, Sappi, Miquel y Costas & Miquel, Neenah Coldenhove, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sublimation Paper Market Evolving Landscape
Digital workflow integration is compressing the traditional separation between design software, substrate specification, and color output, collapsing what were once distinct procurement decisions into unified platform selections.
AI-driven color profiling is virtualizing the traditional trial-and-error calibration process between paper coatings and ink chemistries. Mid-sized print shops in Germany and the US are adopting cloud-based RIP systems that auto-select paper grades based on image content. This technology is virtualizing the role of experienced press operators in routine job setup, compressing labor costs and error rates simultaneously.
EPA regulations on volatile organic compound emissions from coating operations are tightening facility requirements in Ohio and North Carolina manufacturing zones. Plants must install regenerative thermal oxidizers or switch to water-based coating systems. The transfer paper segment faces the steepest compliance costs due to its thinner coating weights and tighter margin structures.
Consolidated procurement platforms are aggregating what were fragmented paper, ink, and equipment purchases. Large-format print shops now source through distributor-managed vendor programs that bundle sublimation paper with certified heat press schedules. This behavioral shift is most visible in US commercial decorators, where single-source supply agreements are displacing spot-buying relationships with multiple coating mills.
Sublimation Paper Market Segmentation
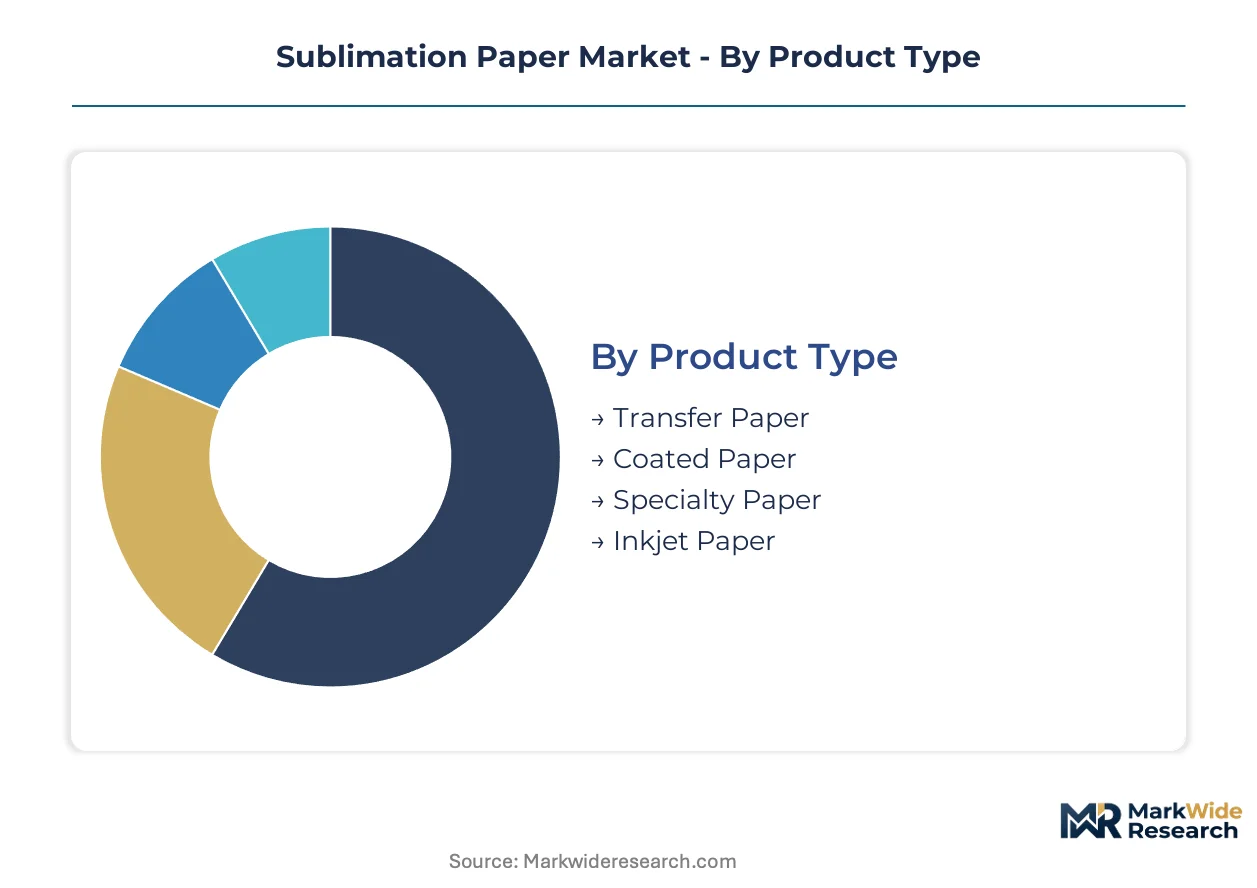
Sublimation paper segmentation reflects the tension between industrial-scale textile production and the democratization of custom printing through accessible inkjet systems. Distinct product grades, application requirements, and procurement channels create parallel demand curves that rarely intersect.
Product Type:
Product categories span from commodity transfer substrates to precision-engineered release papers for rigid polymer applications.
- Transfer Paper:Thin, uncoated or lightly sized substrates designed for single-pass dye release onto polyester textiles. Demand concentrates in China's Zhejiang province where integrated apparel decorators source in pallet quantities for sportswear production.
- Coated Paper:Silica-barrier formulations engineered with controlled porosity to prevent dye strike-through during heat press cycles above 180°C. European automotive soft signage producers in Germany and Poland specify these grades for polyester interior components requiring OEKO-TEX certification.
- Specialty Paper:Custom release coatings for rigid substrates and industrial textiles.
- Inkjet Paper:Microporous topcoats optimized for aqueous dye-sublimation ink absorption at high print speeds.
The dominant share belongs to Transfer Paper, while Specialty Paper is closing the gap fastest.
Application:
End-use segmentation tracks the migration from mass-produced promotional goods to individualized consumer products.
- Textiles:Polyester-based fabrics for apparel, sportswear, and soft furnishings requiring permanent dye penetration. Small-batch team uniform producers in the US and UK favor fast-turnaround inkjet-compatible grades over screen-transfer methods.
- Promotional Products:Corporate merchandise and event giveaways printed on demand. Margin pressure here pushes buyers toward economy-grade transfer papers with standardized release characteristics.
- Personal Items:Phone cases, mugs, and accessories with polymer-coated surfaces.
- Home Décor:Cushion covers, wall art, and furnishings for interior design markets.
Textiles command the volume base, though Personal Items is expanding most quickly as gifting platforms proliferate.
End User:
Customer archetypes range from capital-intensive manufacturers to individual creators operating from home studios.
- Manufacturers:Industrial-scale textile printers and promotional goods suppliers with automated heat press lines. These buyers negotiate annual contracts with coating mills for consistent silica-barrier specifications.
- Small Businesses:Custom decorators and local print shops serving regional markets. Asset-light leasing models for wide-format heat press systems are removing capital barriers for this segment.
- Home Users:Hobbyists and side-business operators purchasing through online retailers.
- Artists:Fine art reproduction specialists requiring archival-grade substrates.
Manufacturers anchor procurement volumes, yet Small Businesses is gaining share fastest as equipment financing broadens market access.
Distribution Channel:
Channel structure reflects the divergence between spot-buying convenience and technical specification support.
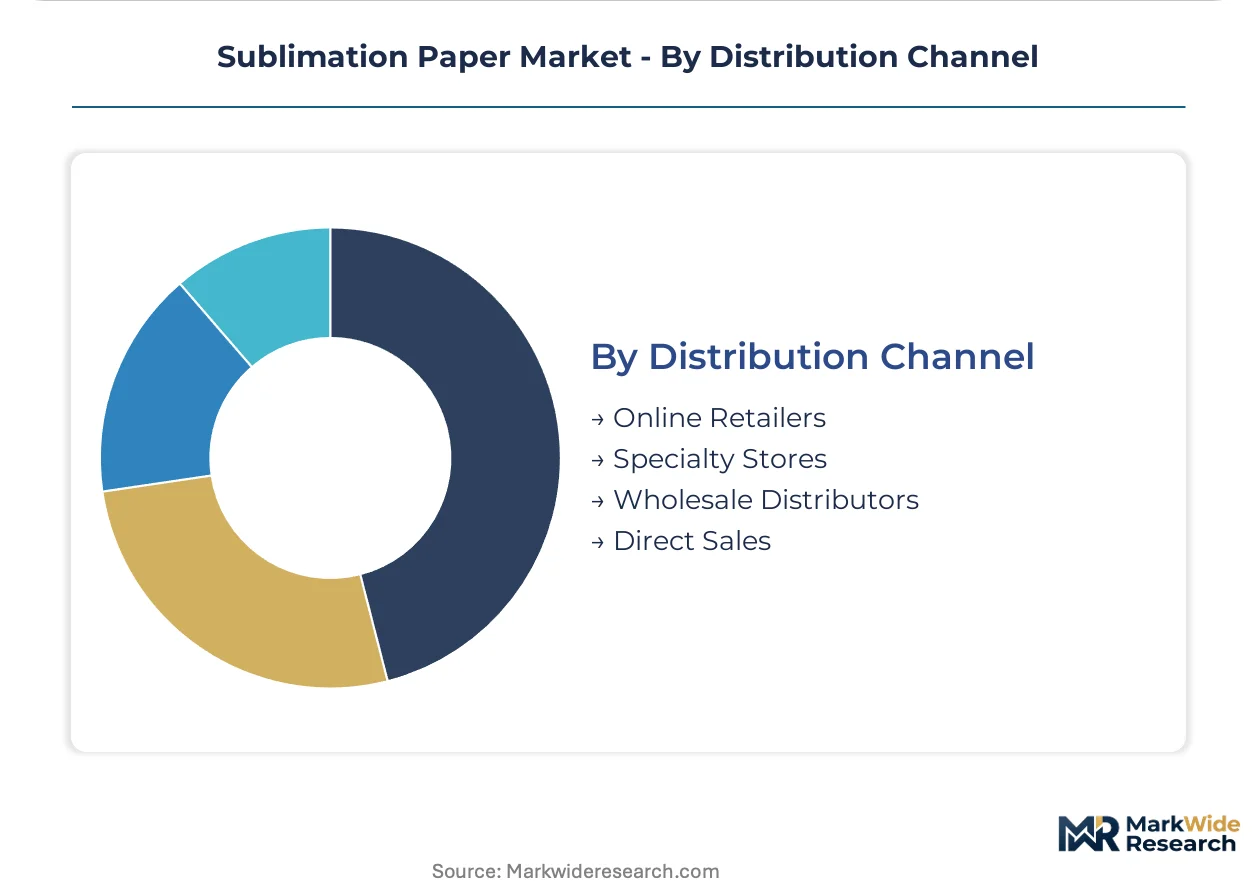
- Online Retailers:E-commerce platforms aggregating paper, ink, and consumable purchases for home users and small shops. Amazon and Alibaba dominate this channel with private-label and third-party coating products.
- Specialty Stores:Regional distributors offering technical calibration support and color management services. These outlets capture premium positioning in Germany and Japan where press operators demand RIP software integration.
- Wholesale Distributors:Volume resellers serving commercial decorators with pallet-level inventory.
- Direct Sales:Mill-direct relationships for large manufacturers with custom formulation requirements.
Online Retailers hold the broadest reach, while Specialty Stores is climbing the fastest as closed-loop color management becomes a competitive differentiator.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial decorators and custom sportswear producers cluster in manufacturing belts with integrated coating capacity and textile printing infrastructure. Buyer archetypes vary by region: large-format print shops dominate North American procurement, while integrated apparel decorators anchor Asian demand.
China
Zhejiang and Guangdong provinces host the densest concentration of pulp-to-coating integrated facilities serving textile printing clusters. MEE environmental enforcement tightens wastewater and air emission controls in the Yangtze River Delta, forcing reformulation investments at paper coating plants. Shaoxing's dye-sublimation hub processes pallet quantities of transfer paper for sportswear export production.
Germany
Automotive soft signage producers in Bavaria and Baden-Württemberg specify OEKO-TEX certified coated papers for polyester interior components. REACH chemical compliance and evolving EU Green Deal packaging rules drive premium-grade silica-barrier formulation upgrades. The Stuttgart industrial corridor anchors technical calibration support and RIP software integration services for mid-sized print shops.
United States
Small-batch team uniform producers across the Southeast and Midwest favor fast-turnaround inkjet-compatible grades over screen-transfer methods. EPA regulations on volatile organic compound emissions tighten facility requirements in Ohio and North Carolina manufacturing zones. Asset-light leasing models for wide-format heat press systems remove capital barriers for regional print shops in Texas and Florida.
India
Promotional goods suppliers in Gujarat and Maharashtra negotiate annual contracts for consistent release specifications in high-volume textile printing. BIS standards and state-level pollution control board enforcement tighten coating chemistry requirements for paper mills in the Delhi-Mumbai industrial corridor. Tiruppur's knitwear cluster imports specialty paper grades for polyester apparel decoration serving export markets.
Japan
Fine art reproduction specialists in the Kanto region require archival-grade substrates with precise release characteristics. METI industrial standards and JIS certification frameworks govern thermal-release coating formulations for rigid substrate applications. Nagoya's automotive textile suppliers source custom-coated papers for interior soft signage components.
Sublimation Paper Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement tiers. The vendor base spans European coating specialists, Chinese integrated pulp-to-paper operators, and North American distribution-focused entities. Three archetypes dominate: silica-barrier formulation specialists with legacy technical expertise, scale-driven integrated manufacturers with captive pulp supply, and distributor-managed platforms bundling paper with equipment financing. Capacity expansion and geographic licensing partnerships represent the dominant competitive moves as players navigate regulatory divergence between jurisdictions.
Among European coating specialists, Felix Schoeller and Ahlstrom-Munksjö occupy positions reflecting premium-tier formulation capabilities. Felix Schoeller exemplifies the silica-barrier specialist archetype through its European coating heritage. Ahlstrom-Munksjö anchors industrial-scale supply infrastructure across multiple continents. Jiangyin Mecoxpan New Material represents the integrated Chinese manufacturer archetype with pulp-to-coating facilities near textile production hubs.
| Leading Market Players |
|---|
| Felix Schoeller |
| Jiangyin Mecoxpan New Material |
| Beaver Paper |
| Million Ton New Material |
| A-SUB |
| Ahlstrom-Munksjö |
| Sappi |
| Miquel y Costas & Miquel |
| Neenah Coldenhove |
| Others |
Value Network & Pricing Analysis
Shaoxing's dye-sublimation hub in Zhejiang province anchors global capacity for transfer paper production, with integrated pulp-to-coating facilities translating upstream scale into downstream pricing leverage for pallet-quantity sportswear exports. This geographic concentration amplifies margin pressure when MEE environmental enforcement triggers reformulation costs that coating mills struggle to pass through to price-sensitive promotional goods buyers.
Pricing Analysis
Certification level creates the primary spread between premium and economy tiers, with OEKO-TEX and REACH-compliant silica-barrier formulations commanding substantial premiums over commodity transfer grades. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by release consistency, inkjet compatibility, and technical support bundling. Pricing pressure stems from direct-to-garment inkjet systems encroaching on sub-50-unit print runs, forcing paper suppliers to absorb coating chemistry compliance costs. Small-batch team uniform producers exhibit highest price sensitivity, while automotive soft signage producers in Germany demonstrate lowest sensitivity due to OE specification requirements.
Supply Chain Analysis
Tariff exposure between China and major Western markets dominates supply chain risk calculations for coating mills dependent on hardwood pulp imports. Production concentrates in China, Germany, and the United States, with China's Yangtze River Delta hosting integrated facilities that draw from regional pulp sources and specialty chemical suppliers. Silica-barrier coatings, controlled-porosity substrates, and release agents constitute critical input dependencies vulnerable to REACH chemical registration delays. Single-source vulnerability concentrates in legacy European and Japanese facilities holding silica-barrier formulation expertise. Distribution runs through consolidated procurement platforms bundling paper with heat press equipment financing, displacing spot-buying relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI-driven color profiling and cloud-based RIP integration are compressing setup times and error rates, creating a technology inflection that rewards paper suppliers with embedded software calibration capabilities.
For Market Incumbents: Pre-empt displacement from direct-to-garment systems by deepening technical support integration with RIP software vendors and auto-calibration platforms. Secure captive pulp supply through backward integration or long-term offtake agreements with hardwood suppliers to defend margin position against raw material volatility. Prioritize REACH-compliant formulation R&D to maintain access to European automotive soft signage contracts. For New Entrants and Emerging Players: Establish a beachhead in industrial textile applications for polyester-based automotive interiors and architectural soft signage, where custom release coatings command premium positioning with limited incumbent specialization. Target mid-sized print shops in the US Southeast and Midwest adopting asset-light heat press leasing models, serving this expanding channel with fast-turnaround inkjet-compatible grades bundled with color management services. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors coating specialists with embedded software calibration capabilities and regulatory affairs bandwidth for parallel EPA-REACH filings. Long-term viability hinges on differentiation through closed-loop color management integration rather than commodity volume scale. Acquisition targets should demonstrate silica-barrier formulation expertise and established OEM relationships in automotive or industrial textile verticals. Monitor direct-to-garment inkjet penetration rates in sub-50-unit print runs as the critical signal for paper-based sublimation displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Water-based coating system investments satisfy EPA VOC requirements in Ohio and North Carolina facilities. |
| Backward Integration | Captive hardwood pulp supply insulates margin structures from energy and logistics input volatility. |
| Platform Integration | RIP software embedding auto-selects paper grades based on image content, reducing operator dependency. |
| Geographic Expansion | European coating capacity addresses REACH compliance without cross-border chemical registration delays. |
| Long-term Supply Agreement | Annual contracts with automotive soft signage producers lock in OEKO-TEX certified volume commitments. |
Research Methodology
Operator-level perspectives from coating plant managers, wide-format print shop owners, heat press equipment distributors, and textile procurement leads anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against customs data, SEC filings from disclosed paper industry participants, MEE environmental enforcement records, and REACH chemical registration databases. Bottom-up volume estimates from end-use application segments triangulated against top-down capacity assessments from major coating facilities.
Scenario-bracketing framed demand projections across the analysis window, with segmentation modeling across product type, application, end user, and distribution channel dimensions. CAGRs derived from regression analysis of historical volume trends adjusted for regulatory inflection points and technology substitution curves. Forecast inputs incorporated pulp cost indices, heat press equipment financing penetration rates, and direct-to-garment inkjet adoption curves in small-batch apparel decoration.
Sensitivities concentrate around MEE enforcement intensity in the Yangtze River Delta, REACH chemical registration timelines for coating reformulations, and direct-to-garment technology cost curves in sub-50-unit print runs. Forecasts reflect assumptions about continued polyester textile demand growth and sustained inkjet printer installed base expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Coated Paper Packaging Box Market
Paper & Paperboard Packaging
Paperboard Packaging Market
Paper & Paperboard Packaging
Insulated Paper Bags Market
Paper & Paperboard Packaging
Unbleached Kraft Paperboard Market
Paper & Paperboard Packaging
Egypt Paper Packaging Market
Paper & Paperboard Packaging
Folding Paperboard Boxes Market
Paper & Paperboard Packaging
Europe Paper Packaging Market
Paper & Paperboard Packaging
Machine Glazed Kraft Paper Market
Paper & Paperboard Packaging
Coated Paper Market
Paper & Paperboard Packaging
Freezer Paper Market
Paper & Paperboard Packaging
North America Paper Bags Market
Paper & Paperboard Packaging
Middle-East and Africa Corrugated Packaging Market
Paper & Paperboard Packaging
Industrial Paper Sacks Market
Paper & Paperboard Packaging
Natural Sack Kraft Papers Market
Paper & Paperboard Packaging
Europe Mailer Packaging Market
Paper & Paperboard Packaging
North America Paper Packaging Market