
 Passive Optical LAN (POL) Market | 2026-2036
Passive Optical LAN (POL) Market Size, Share, and Industry Trends Forecast 2026-2036
Passive Optical LAN (POL) Market Intelligence
The bundling of POL hardware with cloud-based network management software is realigning buyer preferences toward integrated, single-vendor solutions. Huawei Technologies leverages its extensive portfolio to offer end-to-end systems for large-scale deployments. In contrast, CommScope specializes in the physical layer infrastructure, anchoring its position in high-performance cabling. Calix differentiates with its software-defined access platforms targeting telecommunications providers.
Passive Optical LAN is a point-to-multipoint architecture using single-mode fiber and passive optical splitters to deliver data from one source to many endpoints. It replaces traditional copper Ethernet, providing superior bandwidth, security, and a reduced physical footprint. Campus networks and hospitality networks drive significant volume. While Gigabit Passive Optical Networks technology is the current standard, demand for faster Ethernet Passive Optical Networks is growing for data center connectivity.
Network equipment must comply with regulations from bodies like the US Federal Communications Commission (FCC) and China's MIIT. Adherence to European CE marking and global ISO/IEC cabling standards also governs market access and ensures interoperability. Consequently, vendor success hinges on navigating these diverse compliance landscapes while scaling solutions for evolving enterprise network requirements.
Market Dynamics
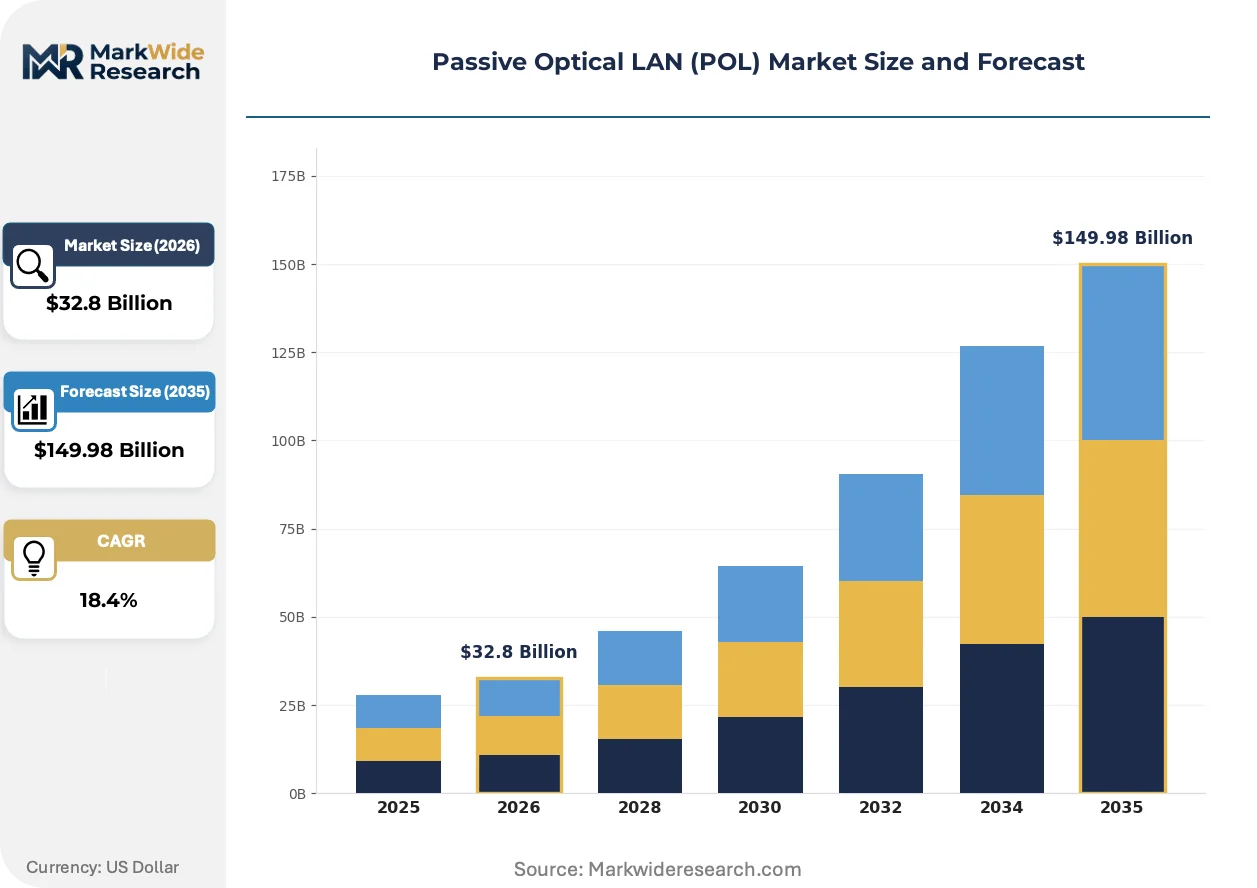
The fundamental expansion of network capacity requirements is the central force shaping the Passive Optical LAN market. This pressure stems from the convergence of bandwidth-intensive services, dense IoT deployments in smart buildings, and the backhaul needs of 5G wireless infrastructure.
Growth Catalysts
- 10G-PON Technology:The transition to 10-Gigabit Passive Optical Networks provides the necessary bandwidth to support next-generation applications in enterprise and campus environments, including high-density Wi-Fi 6/6E and streaming video.
- Hospitality Sector Deployments:Hotels and resorts are increasingly adopting POL to deliver a seamless, high-bandwidth experience for guests, supporting services like IPTV, in-room automation, and secure connectivity for multiple personal devices.
- Smart City Initiatives:Government-led smart city and new campus construction projects, particularly in China, mandate modern fiber infrastructure, creating large-scale, greenfield deployment opportunities for POL systems.
Market Restraints
- High Initial Investment:The upfront capital cost of deploying new single-mode fiber optic cabling can be a significant barrier for retrofitting existing buildings, especially when compared to upgrading existing copper Ethernet infrastructure.
- Technical Skill Gap:A shortage of technicians trained in fiber optic installation, splicing, and testing can lead to project delays and increased labor costs, constraining the pace of POL adoption in some regions.
- Competition from Advanced Copper:Newer copper-based Ethernet technologies can deliver multi-gigabit speeds over existing structured cabling, presenting a viable and less disruptive alternative to POL for certain enterprise upgrade cycles.
Strategic Opportunities
- 5G and Edge Computing Backhaul:The rollout of 5G networks creates a significant opportunity for POL to provide high-capacity, low-latency fiber backhaul for small cells and edge data centers located within buildings and campuses.
- POL and PoE Integration:Converging POL with Power over Ethernet (PoE) technology allows a single fiber and copper hybrid cable to deliver both data and power to endpoints like IP cameras, wireless access points, and VoIP phones, simplifying infrastructure. *Industrial and Manufacturing Verticals: Industrial environments, including factories and logistics centers, represent an underpenetrated segment where POL's immunity to electromagnetic interference and its long reach offer distinct advantages over traditional copper networks.
Industry Challenges
- Legacy System Integration:Integrating a new POL architecture with existing enterprise IT systems, such as network management platforms, security policies, and authentication services, presents a considerable operational challenge for IT staff.
- Interoperability Assurance:While standards from bodies like the ITU-T exist, ensuring seamless interoperability between Optical Line Terminals (OLTs) and Optical Network Terminals (ONTs) from different vendors remains a persistent concern for network operators.
- Compliance Navigation:Adhering to a complex web of international and regional regulations, from FCC emissions standards in the US to CE marking in Europe, adds complexity and cost to product development and market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Passive Optical LAN (POL) Market |
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $149.98 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Network Terminal, Optical Line Terminal, Splitter, Fiber Distribution Hub Technology: Gigabit Passive Optical Networks, Ethernet Passive Optical Networks, Wavelength Division Multiplexing, Time Division Multiplexing Application: Smart Buildings, Data Center Connectivity, Campus Networks, Hospitality Networks, Government Facilities End User: Telecommunications Providers, Education Institutions, Transportation Services, Financial Institutions |
| Companies Covered | ADTRAN, CommScope, Huawei Technologies, Mitsubishi Electric, ZTE Corporation, Cisco Systems, Calix, AFL, Nokia Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Passive Optical LAN (POL) Market Strategic Shifts & Innovations
The market's evolution is defined by a pivot from hardware-centric deployments to software-defined, automated network architectures. This shift prioritizes operational simplicity, centralized control, and the integration of networking with broader IT management frameworks, especially in complex campus and multi-site environments.
Software-Defined Networking (SDN) principles are being applied to POL architectures, abstracting network control from the underlying hardware. Enterprise IT teams are adopting this approach to automate network provisioning, streamline policy enforcement, and gain a unified view of the entire LAN. This technology is rewriting the operational model for campus networks, reducing manual configuration and enabling faster response to changing business needs.
Regulations governing data security and privacy are influencing network infrastructure choices. Mandates like the EU's GDPR and national data sovereignty laws in countries such as India require networks to support robust data segmentation and auditable security controls. The government, healthcare, and financial services sectors are most affected, driving preference for POL solutions that offer inherent security benefits and facilitate compliance.
A notable shift in buyer behavior favors single-vendor, integrated systems that combine POL hardware with cloud-based management software and support services. This disrupts the traditional model where system integrators sourced components from multiple suppliers. This preference for a turnkey solution is most evident in large-scale hospitality and smart city projects where simplified procurement and lifecycle management are key decision criteria.
Passive Optical LAN (POL) Market Segmentation
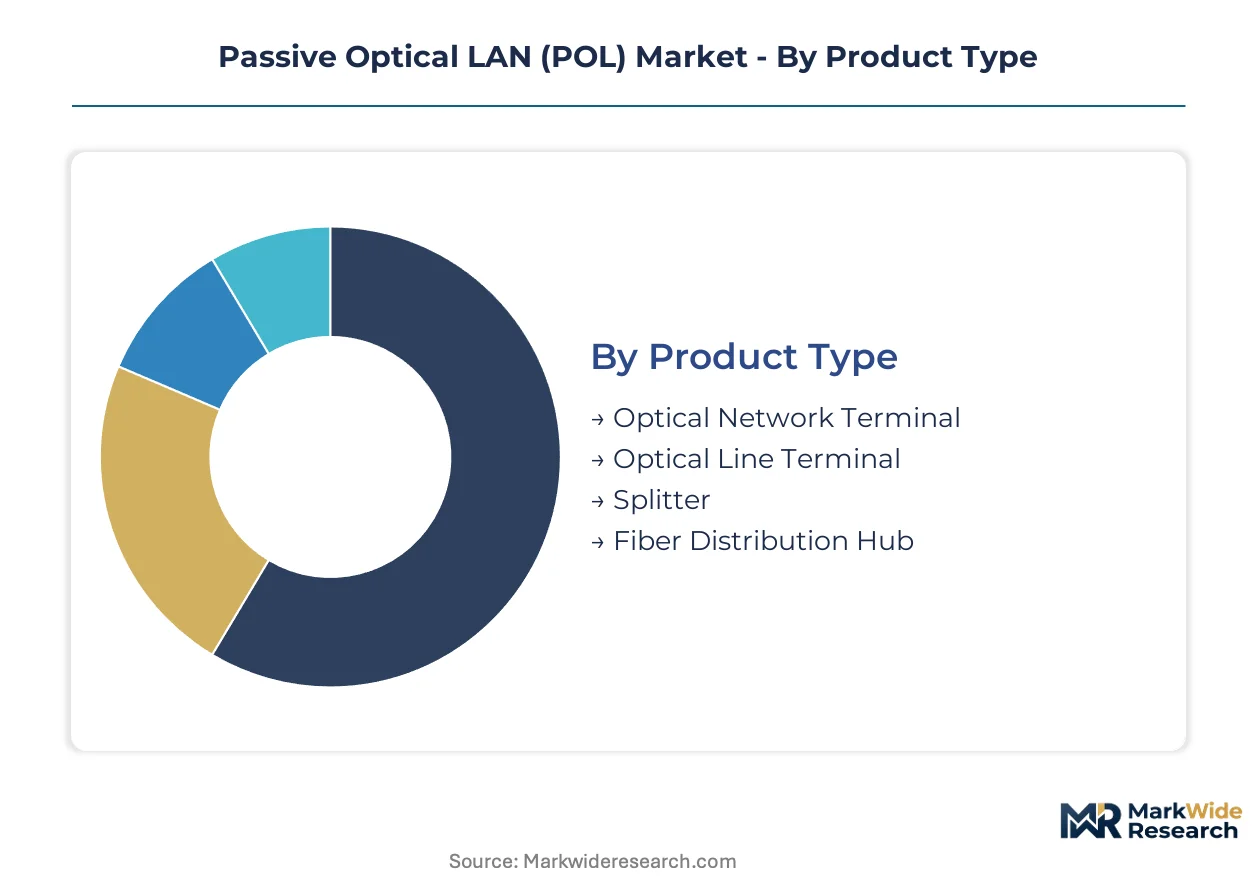
The Passive Optical LAN market structure reflects the diverse operational needs and technological preferences across various industry sectors. Understanding these distinct segments allows stakeholders to tailor solutions that address specific bandwidth demands, deployment scales, and integration complexities, ensuring optimal network performance and cost efficiency.
Product Type:
Buyers differentiate components based on their critical role in data transmission and network architecture.
- Optical Network Terminal:This device terminates the optical fiber line at the end-user's premises, converting optical signals into electrical signals for local area network devices. It is crucial for delivering high-speed internet and services directly to individual users and devices in hospitality and campus environments.
- Optical Line Terminal:Positioned at the central office or data center, the OLT manages the entire Passive Optical Network, broadcasting data downstream and aggregating upstream traffic from multiple ONTs. This core equipment is essential for large-scale deployments, supporting thousands of endpoints across smart city and enterprise networks.
- Splitter:Passive optical splitters divide a single optical fiber into multiple paths, allowing one OLT port to serve numerous ONTs without requiring active electronics. These components are fundamental to the cost-effectiveness and architectural simplicity of POL systems, reducing cabling infrastructure.
- Fiber Distribution Hub:This enclosure provides a centralized point for splicing, connecting, and managing optical fibers within the network, protecting connections and simplifying maintenance. It ensures organized and scalable fiber distribution across large campus and multi-building installations.
Optical Network Terminal leads volumes today; Optical Line Terminal is gaining share fastest.
Technology:
Application-specific requirements drive the selection of underlying Passive Optical LAN technologies.
- Gigabit Passive Optical Networks:GPON is the predominant standard, offering asymmetrical bandwidth with higher downstream speeds, making it suitable for video-centric applications and general enterprise connectivity. It forms the backbone for many current hospitality and smart building deployments.
- Ethernet Passive Optical Networks:EPON provides symmetrical bandwidth and leverages existing Ethernet protocols, making it a preferred choice for data center connectivity and specific industrial applications requiring balanced upload and download speeds. Demand for EPON is growing for high-capacity data transport.
- Wavelength Division Multiplexing:WDM technology allows multiple optical signals at different wavelengths to be transmitted simultaneously over a single fiber, significantly increasing bandwidth capacity. It enables advanced POL architectures to support diverse services and future-proof network infrastructure.
- Time Division Multiplexing:TDM allocates specific time slots for data transmission from various users over a shared optical fiber, ensuring efficient use of bandwidth. This technique is integral to the operation of both GPON and EPON, managing data flow to and from multiple endpoints.
Gigabit Passive Optical Networks exhibits the steepest expansion trajectory in current deployments.
Application:
The volume of data traffic and user density dictate the suitability of Passive Optical LAN solutions for different applications.
- Smart Buildings:POL provides the high-bandwidth backbone for integrated building management systems, IoT devices, and advanced security cameras within modern commercial and residential structures. This application benefits from POL's reduced cabling and power consumption.
- Data Center Connectivity:POL offers a high-density, low-latency solution for connecting servers, storage, and networking equipment within data centers, supporting the increasing demand for faster data transfer. Ethernet Passive Optical Networks are particularly relevant here.
- Campus Networks:Universities, corporate parks, and large institutional campuses leverage POL for its extended reach and ability to consolidate multiple services over a single fiber infrastructure. These deployments often include high-density Wi-Fi 6/6E and integrated security systems.
- Hospitality Networks:Hotels and resorts adopt POL to deliver robust, high-speed internet, IPTV, and in-room automation services to guests, enhancing the overall guest experience. This sector is a significant growth catalyst for the market.
- Government Facilities:POL provides secure, high-capacity networking for various government buildings, including administrative offices and defense installations, where data integrity and reliability are paramount. These projects often align with smart city initiatives.
Hospitality Networks demonstrates the strongest demand acceleration across all applications.
End User:
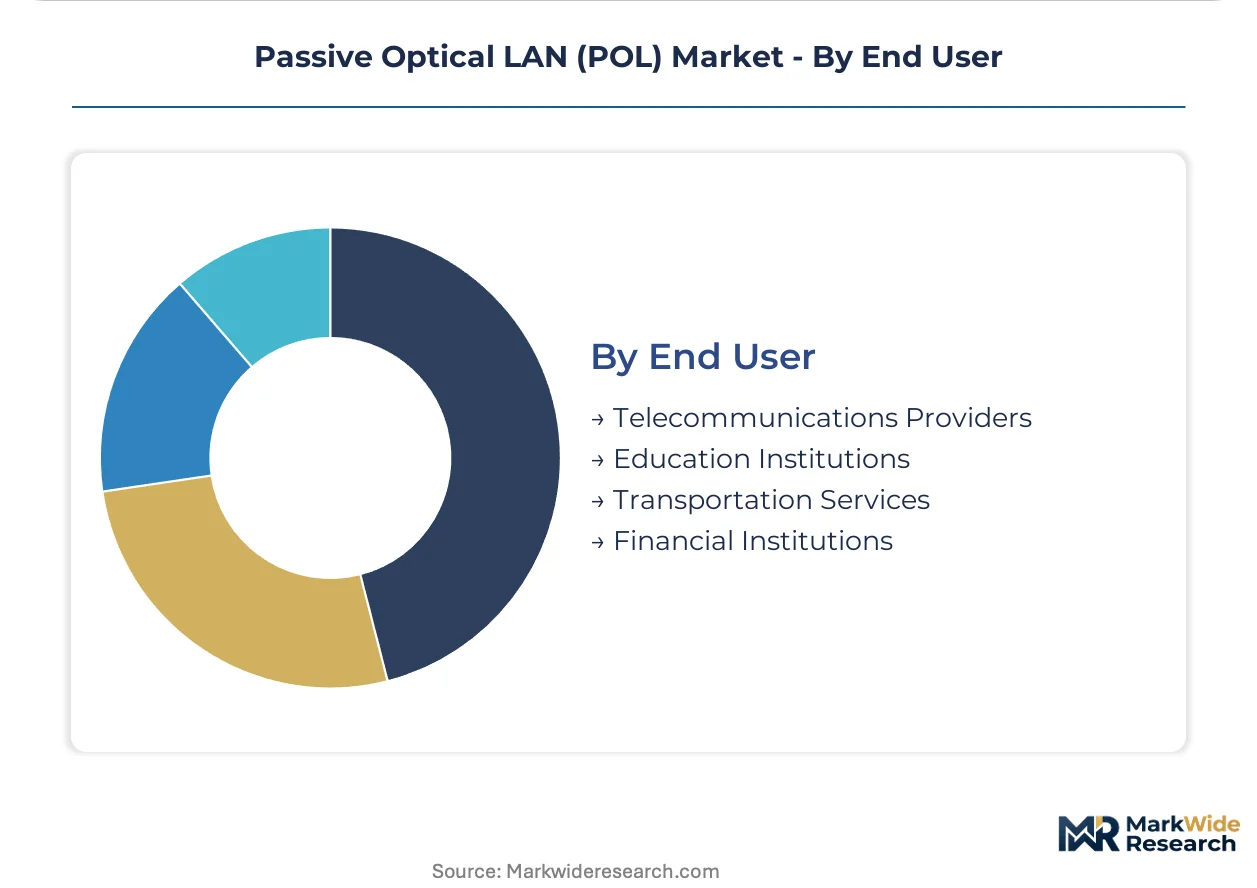
Specific operational demands and regulatory compliance shape the adoption of Passive Optical LAN by different end-user types.
- Telecommunications Providers:These entities deploy POL for last-mile connectivity to businesses and residential customers, expanding their fiber-to-the-home and fiber-to-the-business offerings. They leverage POL for its scalability and operational efficiency.
- Education Institutions:Universities and schools use POL to support dense Wi-Fi environments, e-learning platforms, and administrative functions across extensive campus networks. The technology provides reliable, high-speed access for students and faculty.
- Transportation Services:Airports, railway stations, and logistics hubs utilize POL for surveillance, ticketing systems, and operational control networks, benefiting from its immunity to electromagnetic interference and long-distance capabilities. This segment relies on robust and secure infrastructure.
- Financial Institutions:Banks and trading firms adopt POL for secure, high-bandwidth internal networks, supporting critical data transactions and communication systems. Data security and network reliability are paramount requirements in this sector.
Telecommunications Providers shows the highest growth potential for new POL deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Passive Optical LAN market gained significant traction with the global proliferation of fiber optic infrastructure, particularly as telecommunications providers expanded last-mile connectivity. Early deployments focused on campus environments and large enterprises seeking superior bandwidth. This foundational period established architectural principles driving widespread adoption across diverse sectors.
China
Demand for POL systems in China is strong, driven by extensive new smart city and campus network constructions. The Ministry of Industry and Information Technology (MIIT) mandates modern fiber infrastructure for these large-scale projects. Major urban centers like Shenzhen and Shanghai are seeing significant greenfield deployments for advanced network capabilities.
United States
Enterprises in the United States increasingly adopt POL for campus networks and hospitality, seeking high-bandwidth solutions for dense Wi-Fi and streaming services. Compliance with US Federal Communications Commission (FCC) regulations is essential for network equipment. Technology hubs such as Silicon Valley and Boston integrate POL into new corporate campuses and data centers.
Germany
European adoption of POL in Germany focuses on smart building initiatives and industrial verticals, benefiting from its immunity to electromagnetic interference. Adherence to European CE marking and ISO/IEC cabling standards ensures market access. The industrial heartland of Bavaria utilizes POL for factory automation and logistics centers.
India
India's aggressive smart city initiatives and expanding telecommunications networks spur demand for POL infrastructure. Government policies, including the PLI scheme for telecom equipment, encourage domestic manufacturing and deployment. Cities like Bangalore and Hyderabad witness substantial POL installations to support new commercial developments and educational institutions.
Japan
Modernization efforts in Japan's hospitality sector and data centers drive Passive Optical LAN technology adoption. Japanese Industrial Standards (JIS) ensure quality and performance for optical components within these networks. Tokyo's dense urban environment and surrounding tech parks leverage POL for high-speed, secure internal communications.
Passive Optical LAN (POL) Market Key Industry Players
Premium-margin players sit above commodity-margin players across solution depth, offering integrated hardware and software ecosystems for complex network needs. The Passive Optical LAN market exhibits a tiered structure, with a few large, diversified technology conglomerates competing with specialized infrastructure providers. Strategic archetypes include end-to-end solution providers, physical layer specialists, and software-defined access platform innovators. Dominant competitive moves involve strategic partnerships to expand solution portfolios and continuous portfolio diversification to address evolving enterprise network requirements, alongside targeted geographic expansion.
Within the end-to-end solution provider archetype, Huawei Technologies leverages its extensive portfolio to offer integrated systems for large-scale deployments, spanning hardware and network management software. CommScope, in contrast, anchors its position as a physical layer specialist, focusing on high-performance cabling infrastructure and robust connectivity solutions. Calix differentiates with its software-defined access platforms, targeting telecommunications providers with innovative and programmable solutions for network management. These companies exemplify the varied approaches to market penetration and value capture within the Passive Optical LAN industry.
| Leading Market Players |
|---|
| ADTRAN |
| CommScope |
| Huawei Technologies |
| Mitsubishi Electric |
| ZTE Corporation |
| Cisco Systems |
| Calix |
| AFL |
| Nokia Corporation |
| Others |
Cost & Logistics Intelligence
Publicly traded technology conglomerates often dictate both supply behavior and pricing discipline within the Passive Optical LAN market. Their integrated offerings and global reach influence component availability and solution costs for large-scale deployments.
Pricing Analysis
Project-based pricing dominates the Passive Optical LAN market, reflecting the custom nature of large-scale fiber infrastructure rollouts. Price differentiation stems from solution depth, encompassing integrated hardware and cloud-based management software, and adherence to specific regulatory compliance like FCC or CE marking. Pricing softness reflects competition from advanced copper alternatives for certain enterprise upgrades. Government facilities and financial institutions typically exhibit the least price sensitivity, prioritizing security and reliability, while telecommunications providers are more sensitive to per-unit costs for mass deployments.
Supply Chain Analysis
A shortage of skilled fiber optic technicians in key manufacturing geographies like China, the United States, and Japan impacts installation costs and project timelines. The supply chain for Passive Optical LAN systems draws from critical components such as optical fiber, specialized semiconductors for OLTs and ONTs, and passive optical splitters. Geopolitical tensions represent a structural risk, potentially disrupting the flow of components or technology transfer. Distribution runs through a network of system integrators and direct sales channels to large enterprises and government entities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with initiatives like China's MIIT mandates for smart city fiber infrastructure substantially driving demand and adoption rates.
For Market Incumbents: Extend solution portfolios to include advanced software-defined networking capabilities, addressing the operational complexity of large-scale campus networks. This counters the threat of specialized software providers and enhances long-term customer lock-in. Invest in R&D for 25G-PON and 50G-PON technologies, ensuring future-proof compliance with evolving bandwidth standards.
For New Entrants and Emerging Players: Launch via specialized system integrator partnerships, targeting underpenetrated industrial and manufacturing verticals. These environments value POL's immunity to electromagnetic interference and long-reach capabilities. Focus on developing integrated POL and Power over Ethernet (PoE) solutions, simplifying infrastructure for IoT-dense smart buildings and offering a distinct go-to-market angle.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized component manufacturers and regional system integrators with strong local expertise. The long-term viability remains robust over the next 5-10 years, driven by persistent fiber infrastructure demand. Increased acceleration of 5G backhaul deployments within buildings and campuses serves as a critical signal to watch for sustained market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop 25G-PON/50G-PON Solutions | This initiative ensures future bandwidth capabilities for next-generation enterprise and 5G backhaul applications. |
| Integrate with Cloud Management Platforms | This action simplifies network operations and enhances centralized control for IT teams in complex campus environments. |
| Form Strategic Alliances with 5G Providers | These partnerships secure POL's role in providing high-capacity, low-latency fiber backhaul for expanding 5G networks. |
| Expand into Industrial Verticals | This move capitalizes on POL's immunity to electromagnetic interference, addressing a unique need in factory and logistics settings. |
| Invest in Technician Training Programs | This addresses the critical technical skill gap, accelerating deployment and reducing project delays for new POL installations. |
Research Approach
Direct dialogue with network architects, IT procurement managers, telecom engineers, and smart city planners informed the qualitative grounding of this analysis. Secondary validation drew from FCC filings, MIIT reports, ITU-T standards, and ISO/IEC cabling standards, ensuring comprehensive data triangulation. This approach combined bottom-up market sizing with top-down validation of market trends.
A bottom-up analytical lens informed the forecast framework across the analysis window, segmenting the market by product type (ONT, OLT), technology (GPON, EPON), application (hospitality, smart buildings), and end user (telecom, education). CAGRs were derived from historical market trends and projected growth drivers, with fiber infrastructure investment and 5G rollout pace serving as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of significant geopolitical trade policy shifts or unforeseen technological disruptions. Forecasts reflect assumptions regarding continued fiber optic infrastructure development and stable regulatory environments. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
North America Structured Cabling Market
Network Technology
Global GPS Market
Network Technology
Europe Video Conferencing Hardware Market
Network Technology
Passive Optical Network Market
Network Technology
Sand Lane Systems Market
Network Technology
Global Carrier Ethernet Equipment Market
Network Technology
Network Fault Monitoring Tools Market
Network Technology
DNS DHCP and IPAM Market
Network Technology
Ethernet Backhaul Equipment Market
Network Technology
Indoor Distributed Antenna Systems Market
Network Technology
Wi-Fi As a Service (Waas) Market
Network Technology
Global Intelligent Network Market
Network Technology
Global Network Management Market
Network Technology
Private LTE Market
Network Technology
Global Passive Optical Network (PON) Equipment Market
Network Technology
Network Management Systems (NMS) Market