
 Global GPS Market | 2026-2036
Global GPS Market Size, Share, and Industry Trends Forecast 2026-2036
Global GPS Market Analysis
Aftermarket service revenue is fragmenting across hardware-agnostic platform providers and legacy device manufacturers. Garmin Ltd. leverages its outdoor recreation ecosystem to sustain premium subscription attach rates. Trimble Inc. anchors precision agriculture workflows through in-house production of correction services and display hardware. u-blox competes on module miniaturization for IoT tracking endpoints, while Qualcomm Technologies extends its Snapdragon positioning stack into automotive digital cockpit integrations.
Global Positioning System technology comprises satellite-based radio navigation infrastructure delivering meter-to-centimeter accuracy through triangulation of timing signals broadcast from medium Earth orbit constellations. The system enables geospatial positioning for routing, asset tracking, surveying, and timing synchronization across civilian and military domains. Automotive navigation systems command the largest installed base among product types, though marine GPS units carry higher per-unit margins in commercial fishing and offshore energy segments. Fleet management applications are outpacing personal navigation in value contribution as logistics companies mandate real-time visibility across multi-modal supply chains. GNSS technology leads volume shipments, while differential GPS correction services capture disproportionate margin pools in centimeter-grade use cases.
The US Federal Communications Commission governs spectrum allocation for GPS augmentation services, while the EU's Radio Equipment Directive mandates CE marking for navigation devices sold across member states. Japan's Ministry of Economy, Trade and Industry coordinates QZSS interoperability standards with GPS constellation timing. China's Ministry of Industry and Information Technology enforces BeiDou compatibility as a condition for domestic device certification, effectively segmenting procurement requirements by national constellation policy. Stakeholders must monitor constellation modernization timelines and spectrum reallocation proceedings to anticipate receiver architecture refresh cycles.
Market Dynamics
Fleet management mandates from logistics operators are compressing hardware refresh cycles while forcing receiver architecture upgrades to support multi-constellation interoperability. The EU's Radio Equipment Directive and China's BeiDou integration requirements are creating divergent certification pathways that fragment procurement standards across supply chains.
Growth Catalysts
- Precision Agriculture Expansion:Centimeter-grade correction services are displacing meter-level accuracy in US Midwest and Australian grain belt operations. Variable-rate application workflows require RTK-enabled guidance systems.
- CE Marking Mandates:The EU's Radio Equipment Directive is accelerating device recertification across European logistics fleets. Compliance deadlines are pulling forward replacement demand for non-conforming hardware.
- Multi-Modal Visibility Requirements:Container tracking across rail, road, and maritime nodes demands persistent connectivity. Low-power wide-area modules are penetrating cold-chain monitoring and high-value asset custody applications.
Market Restraints
- Semiconductor Supply Concentration:RF front-end component fabrication concentrates in Taiwanese and South Korean foundries. Geopolitical friction exposes receiver module production to allocation volatility.
- Spectrum Interference Risks:Ligado Networks' terrestrial broadband deployment threatens GPS L-band signal integrity in North American airspace. Aviation and precision timing applications face degraded availability.
- Constellation Fragmentation Costs:Separate BeiDou, Galileo, and NavIC certification requirements multiply testing overhead for global device portfolios. Regional mandates segment R&D investment.
Strategic Opportunities
- Indian Fleet Digitization:Underpenetrated commercial vehicle tracking in India's logistics corridor offers whitespace for hardware-agnostic platform providers. TRAI's telecom framework supports cellular-LPWA hybrid connectivity.
- Autonomous Vehicle Integration:Automotive-grade positioning safety requirements are converging with sensor fusion architectures. Redundant GNSS-IMU stacks are penetrating robotaxi and ADAS L3+ programs.
- Correction Service Unbundling:PPP-RTK subscription models are displacing bundled hardware-service contracts. Precision agriculture OEMs are decoupling display hardware from annual correction fees.
Industry Challenges
- RF Engineering Talent Scarcity:Multi-constellation receiver design requires specialized signal-processing expertise. Competition with 5G baseband and radar sensing programs constrains hiring pipelines.
- Legacy Fleet Integration Complexity:CAN bus protocol fragmentation across European and Brazilian truck platforms complicates telematics retrofit deployment. Middleware adaptation consumes professional services capacity.
- Dual-Use Export Control Compliance:ITAR and EAR classification reviews delay civilian receiver shipments with military-grade anti-jam capabilities. Licensing timelines extend customer qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global GPS Market |
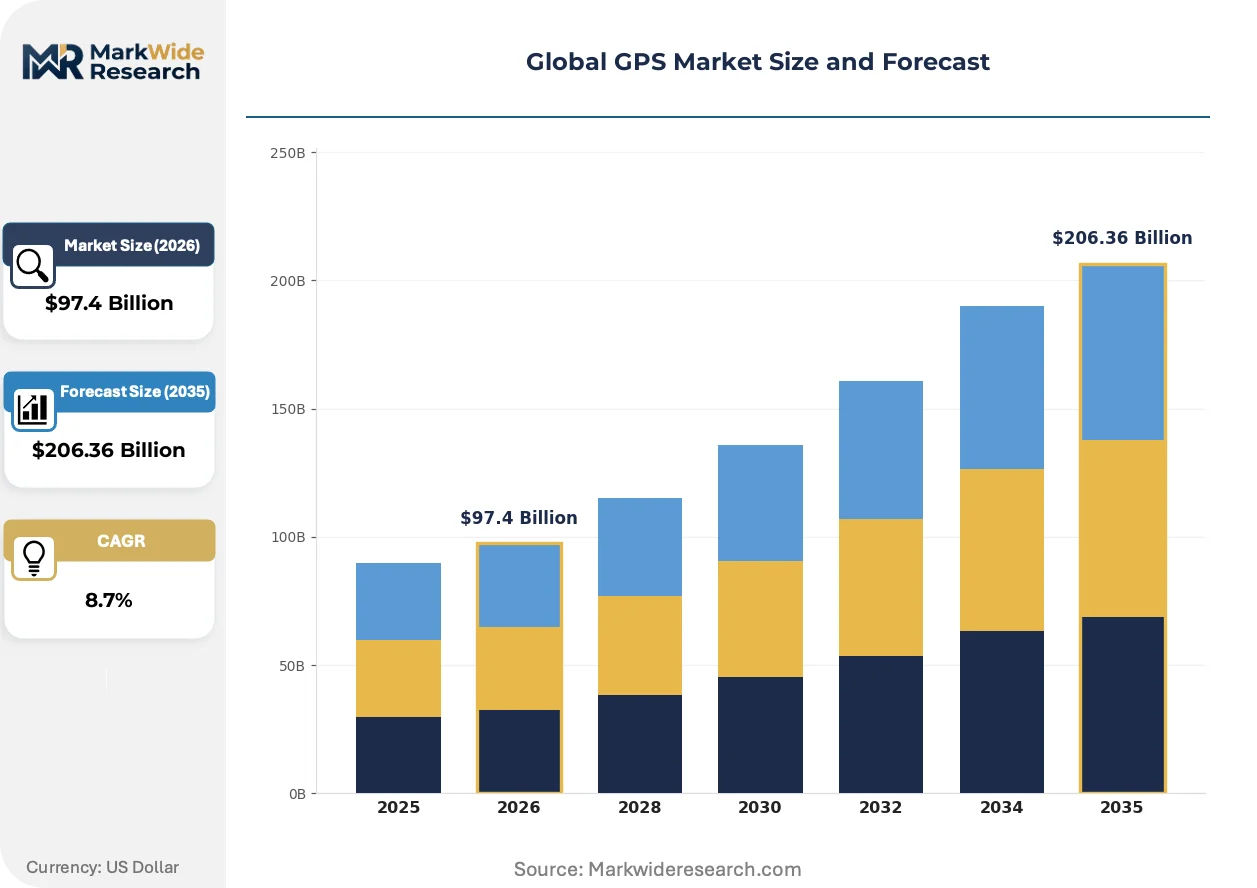
| Market Size in 2026 | $97.4 Billion |
| Market Size in 2035 | $206.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld GPS Devices, Automotive Navigation Systems, Marine GPS Units, Aviation Navigation Systems Application: Personal Navigation, Fleet Management, Agriculture, Military Operations End User: Consumers, Logistics Companies, Agriculture Professionals, Defense Sector Technology: GNSS, Assisted GPS, Differential GPS, Map Matching |
| Companies Covered | Garmin Ltd., TomTom International BV, Qualcomm Technologies, Broadcom, Trimble Inc., u-blox, Quectel Wireless Solutions, Hexagon AB, Sierra Wireless, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global GPS Market Emerging Trajectories
Receiver architectures are bifurcating between mass-market IoT miniaturization and safety-critical automotive redundancy. Correction service business models are unbundling from hardware, while multi-constellation mandates reshape certification investment priorities.
Multi-frequency multi-constellation (MFMC) chipsets are migrating from aviation and surveying equipment into automotive digital cockpits and precision agriculture displays. Tier-1 suppliers in Germany and Japan are qualifying triple-band (L1/L2/L5) receivers for lane-level navigation. The technology is migrating from premium vehicle trims into standard equipment as ADAS safety regulations tighten positioning availability requirements.
China's Ministry of Industry and Information Technology enforces BeiDou-3 compatibility as a condition for domestic smartphone and vehicle navigation certification. Foreign chipset vendors must license B1C/B2a signal interfaces through state-approved technical partnerships. Domestic OEMs are accelerating BDS-only receiver designs to eliminate GPS royalty obligations and satisfy government procurement preferences.
Logistics operators are consolidating telematics vendor relationships from fragmented regional suppliers toward platform-agnostic fleet management suites. Brazilian and German freight carriers are demanding API-native integration with transport management systems rather than proprietary hardware ecosystems. Subscription pricing for software layers is displacing perpetual-license hardware margins in enterprise fleet contracts.
Global GPS Market Segmentation
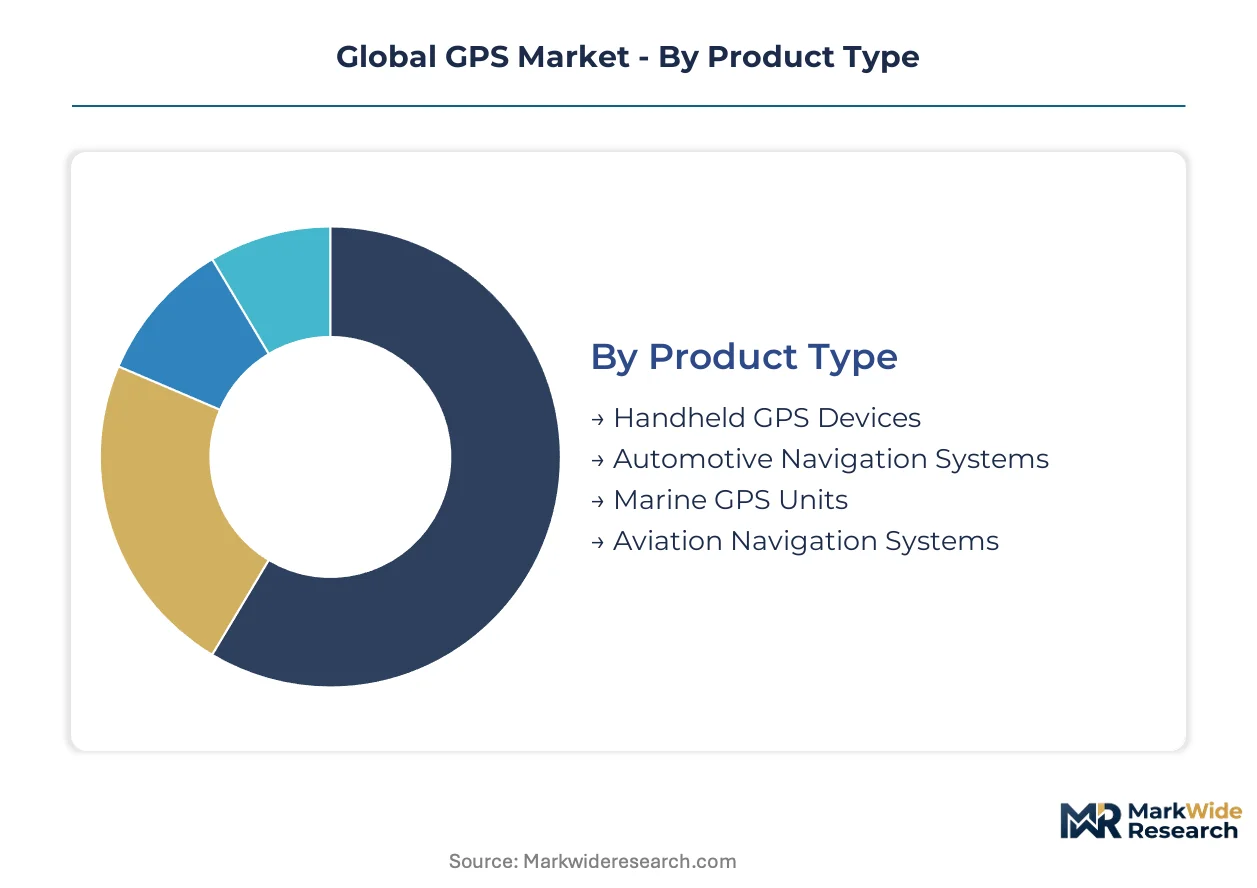
Receiver architecture and service delivery models fragment across precision requirements, power budgets, and constellation mandates. Segmentation reveals where hardware margins concentrate versus where subscription economics dominate.
Product Type:
Cost tier determines margin structure and replacement cadence across civilian and commercial equipment categories.
- Handheld GPS Devices:Battery-powered units with integrated antennas and simplified user interfaces target outdoor recreation and field surveying. Demand concentrates in North American hiking and hunting retail channels where Garmin Ltd. sustains premium pricing through ecosystem lock-in.
- Automotive Navigation Systems:Dashboard-integrated receivers with real-time traffic overlays command the largest installed base among product types. German and Japanese OEMs are qualifying triple-band chipsets for lane-level positioning as ADAS regulations tighten availability requirements.
- Marine GPS Units:Saltwater-resistant enclosures with WAAS and EGNOS augmentation support commercial fishing operations. Higher per-unit margins reflect IP67 sealing and chart-plotter integration requirements.
- Aviation Navigation Systems:TSO-certified receivers with RAIM integrity monitoring serve general aviation and rotorcraft segments. FAA technical standard orders govern software loadable approval timelines.
Automotive Navigation Systems hold installed capacity. Fleet Management is rotating up the share rankings as logistics operators mandate multi-modal visibility.
Application:
Customer workflow integration depth separates consumer routing from enterprise asset tracking economics.
- Personal Navigation:Smartphone-based turn-by-turn guidance has displaced dedicated hardware for civilian routing. Apple and Google map services capture advertising and location data monetization while hardware vendors retreat to offline-capable expedition segments.
- Fleet Management:Real-time vehicle tracking with CAN bus telematics integration dominates value contribution in logistics. Brazilian and German freight carriers are demanding API-native platform integration rather than proprietary hardware ecosystems.
- Agriculture:RTK-enabled guidance systems support variable-rate application workflows in US Midwest and Australian grain belt operations. Correction service unbundling is decoupling display hardware from annual subscription fees.
- Military Operations:Anti-jam and spoof-resistant receivers with M-code capability face ITAR and EAR classification reviews. Dual-use export controls extend customer qualification cycles for civilian suppliers with military-grade features.
Fleet Management commands revenue concentration. Agriculture is expanding most quickly as centimeter-grade services displace meter-level accuracy.
End User:
Procurement authority and technical sophistication shape contract structures across buyer categories.
- Consumers:Price-sensitive purchasers prioritize smartphone integration and subscription-free operation. Retail channel concentration in outdoor recreation sustains premium attach rates for ecosystem vendors.
- Logistics Companies:Enterprise fleet operators mandate multi-constellation interoperability and transport management system API access. Brazilian and German carriers are consolidating vendor relationships from fragmented regional suppliers toward platform-agnostic suites.
- Agriculture Professionals:Farm operators demand RTK correction services bundled with seasonal support contracts. Dealer network relationships determine hardware selection in US Midwest equipment markets.
- Defense Sector:Military procurement requires anti-jam capabilities and sovereign constellation compatibility. China's Ministry of Industry and Information Technology enforces BeiDou-3 compatibility for domestic vehicle navigation certification.
Logistics Companies anchor enterprise spending. Agriculture Professionals are climbing the fastest as precision workflows penetrate grain belt operations.
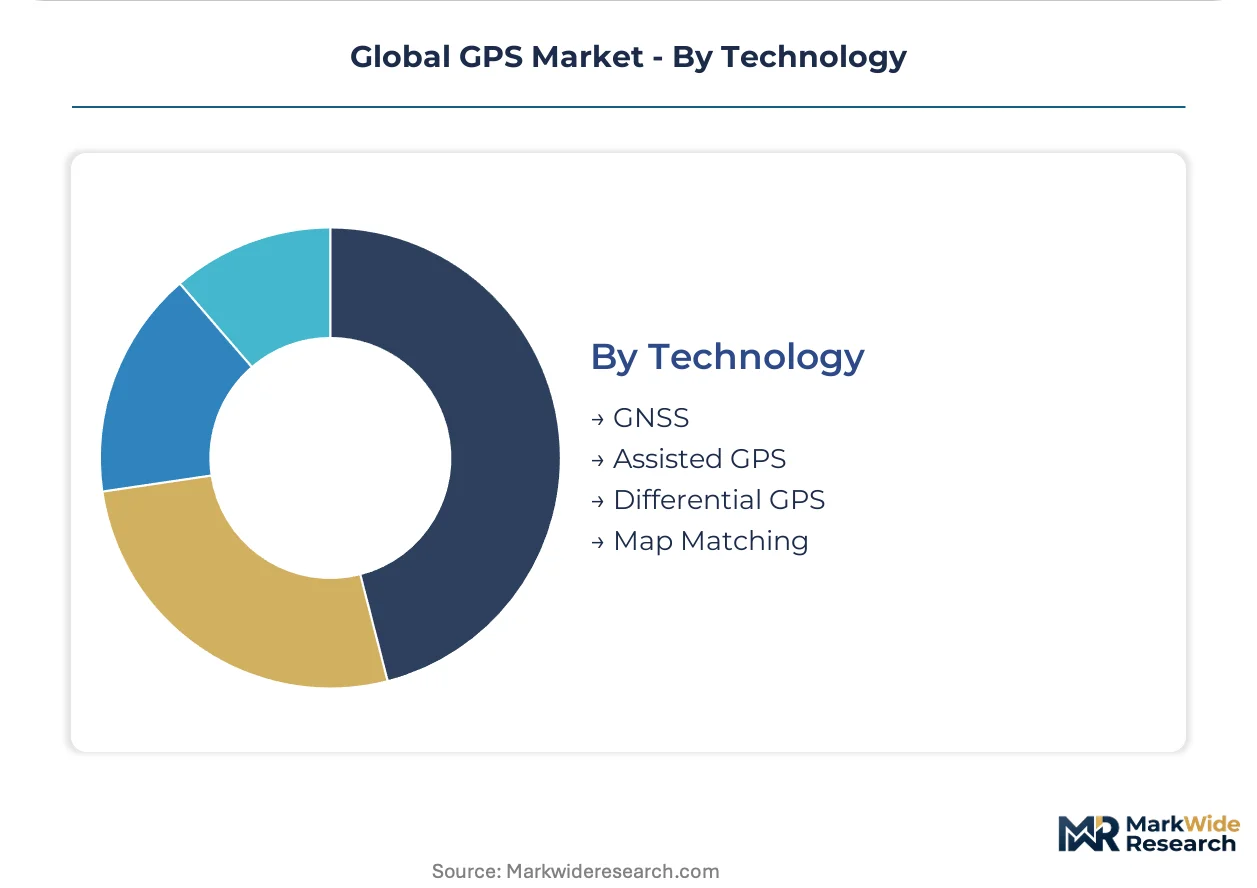
Technology:
Signal processing architecture determines accuracy grade and power consumption trade-offs.
- GNSS:Multi-constellation receivers processing GPS, GLONASS, Galileo, and BeiDou signals deliver meter-level accuracy for mass-market applications. u-blox competes on module miniaturization for IoT tracking endpoints.
- Assisted GPS:Cellular network-supplied ephemeris and almanac data reduce time-to-first-fix in urban canyon environments. Snapdragon positioning stack integration extends into automotive digital cockpit deployments.
- Differential GPS:Correction services using ground reference stations achieve centimeter-grade accuracy for surveying and precision agriculture. Trimble Inc. anchors workflows through in-house production of correction services and display hardware.
- Map Matching:Road network constraint algorithms improve positioning continuity in tunnel and parking structure environments. Tier-1 automotive suppliers in Germany and Japan are qualifying enhanced implementations for lane-level navigation.
GNSS holds installed capacity. Differential GPS is gaining share fastest as PPP-RTK subscription models displace bundled hardware-service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes GPS technology through precision agriculture workflows, while Germany and Brazil prioritize fleet management mandates, and China enforces sovereign constellation compatibility for domestic device certification.
United States
Midwest grain belt operators deploy RTK-enabled guidance systems for variable-rate application workflows. The FAA governs aviation navigation certification through technical standard orders for general aviation receivers. Iowa and Illinois equipment markets concentrate dealer network relationships for seasonal correction service contracts.
Germany
Logistics carriers mandate API-native platform integration across multi-modal supply chains. The KBA coordinates automotive-grade positioning requirements with EU Radio Equipment Directive compliance deadlines. Bavarian freight operators consolidate vendor relationships from fragmented regional suppliers toward hardware-agnostic suites.
China
Domestic OEMs accelerate BeiDou-only receiver designs to eliminate GPS royalty obligations. The MIIT enforces B1C/B2a signal compatibility as a condition for smartphone and vehicle navigation certification. Shenzhen and Shanghai chipset vendors license signal interfaces through state-approved technical partnerships.
Brazil
Commercial vehicle tracking penetration lags in underdeveloped logistics corridors. ANVISA coordinates device certification with telecom regulator frameworks for cellular-LPWA hybrid connectivity. São Paulo freight carriers demand real-time visibility across road-rail-port nodes.
Australia
Grain belt operations adopt centimeter-grade correction services for autosteer systems. The TGA oversees aviation navigation standards with RAIM integrity monitoring requirements. New South Wales and Victoria precision agriculture markets concentrate dealer support networks for RTK subscription models.
Global GPS Market Vendor Landscape
Capability concentration sits with specialized correction service providers and RF module designers; scale advantage sits with semiconductor platform vendors and automotive Tier-1 integrators. The structure tiers between ecosystem-locked premium hardware vendors and hardware-agnostic platform providers. Three archetypes dominate: outdoor recreation ecosystem builders, precision agriculture workflow integrators, and IoT miniaturization specialists. Competitive moves center on multi-constellation certification acceleration and correction service unbundling from display hardware.
Within the ecosystem-locked tier, Garmin Ltd. exemplifies premium subscription attach rate sustainability through outdoor recreation platform depth. Trimble Inc. anchors precision agriculture positioning through captive correction service production. u-blox occupies a position in IoT endpoint miniaturization for low-power tracking applications.
| Leading Market Players |
|---|
| Garmin Ltd. |
| TomTom International BV |
| Qualcomm Technologies |
| Broadcom |
| Trimble Inc. |
| u-blox |
| Quectel Wireless Solutions |
| Hexagon AB |
| Sierra Wireless |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Taiwanese RF front-end foundries compresses margin spreads between automotive-grade receivers and mass-market IoT modules while forcing procurement diversification into South Korean and Japanese alternative sources. This concentration dynamic simultaneously elevates pricing power for certified multi-constellation chipsets and erodes margins for undifferentiated consumer-grade hardware.
Pricing Analysis
Long-term offtake agreements dominate enterprise fleet contracts while spot purchasing persists in consumer retail channels. Pricing stratifies across premium, standard, and economy tiers based on constellation certification depth and correction service bundling. Cost compression in mass-market GNSS modules intensifies as Chinese chipset vendors eliminate GPS royalty obligations through BeiDou-only designs. Logistics companies demonstrate lowest price sensitivity due to regulatory compliance mandates, whereas consumer outdoor recreation buyers exhibit highest elasticity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic sourcing decisions for automotive Tier-1 suppliers. RF front-end component fabrication concentrates in Taiwan and South Korea, with assembly operations drawing from Chinese and Vietnamese facilities. Supply chain risk centers on single-source vulnerability for triple-band receiver baseband processors. Distribution runs through authorized dealer networks in precision agriculture, direct OEM supply agreements in automotive, and retail channels in consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Constellation fragmentation and unbundled correction service models are fragmenting competitive positions, creating specialized niches for hardware-agnostic platform providers and sovereign-compatible chipset vendors.
For Market Incumbents: Entrench multi-constellation certification leadership through accelerated Galileo and BeiDou-3 signal interface investments before regional mandates harden. Deepen backward integration into correction service infrastructure to offset hardware margin erosion from PPP-RTK subscription unbundling. Prioritize API-native platform architectures to defend against logistics operator vendor consolidation toward hardware-agnostic suites. For New Entrants and Emerging Players: Mid-tier fleet management platforms in India's underpenetrated logistics corridor represent the most penetrable entry point given TRAI's supportive telecom framework and cellular-LPWA hybrid connectivity availability. Precision agriculture display hardware decoupled from Trimble-dominated correction services offers whitespace in Australian and US Midwest dealer networks. Lead with seasonal subscription flexibility rather than perpetual-license positioning to displace incumbent equipment financing relationships. For Investors and Strategic Acquirers: The market sits at a certification-intensification phase that favors vertically integrated correction service providers with captive hardware channels. Long-term viability over the next decade rests on constellation policy alignment and automotive safety-grade qualification timelines. Monitor EU Radio Equipment Directive enforcement consistency and China's MIIT certification reciprocity negotiations as inflection indicators for global portfolio exposure rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Constellation Certification Acceleration | EU Radio Equipment Directive and MIIT mandates force receiver architecture refresh cycles ahead of competitor qualification timelines. |
| Correction Service Unbundling | PPP-RTK subscription models displace bundled hardware-service contracts in Trimble-dominated precision agriculture workflows. |
| Automotive Safety-Grade Qualification | Tier-1 suppliers in Germany and Japan demand triple-band receivers for ADAS L3+ lane-level positioning availability. |
| API-Native Platform Integration | Brazilian and German logistics operators consolidate vendor relationships toward transport management system-native architectures. |
| Sovereign Constellation Compatibility | China's BeiDou-3 mandates and India's NavIC requirements segment procurement standards by national satellite policy alignment. |
Methodological Framework
The analysis maps receiver architecture tiers, correction service delivery models, and constellation certification pathways, each validated through RF engineering directors, fleet management procurement leads, precision agriculture dealer principals, and automotive Tier-1 platform engineers. Primary interview intelligence triangulates against customs shipment records, FCC equipment authorization filings, EU CE marking databases, and SEC 10-K segment disclosures. Bottom-up volume estimates from module shipment tracking reconcile with top-down market sizing derived from OEM procurement patterns.
Assumptions around constellation modernization timelines, regulatory enforcement consistency, and semiconductor allocation stability were held fixed across scenarios while correction service pricing elasticity and fleet management SaaS penetration rates were stress-tested. Segmentation modeling incorporates product architecture, application workflow depth, end-user procurement authority, and technology signal-processing grade. CAGRs emerge from logistic curve fitting against historical replacement cycles and regulatory deadline pull-forward effects.
Macroeconomic conditions sit as an overlay; deviation in logistics freight volumes, agricultural commodity prices, or automotive production schedules would shift the trajectory of hardware refresh demand. Forecasts reflect documented assumptions regarding certification timeline adherence and foundry capacity expansion plans. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Virtual Customer Premises Equipment Market
Network Technology
Global Wireless Router Market
Network Technology
Europe Video Conferencing Hardware Market
Network Technology
Low-Power WAN Market
Network Technology
Network Emulator Market
Network Technology
Dark Fiber Market
Network Technology
Global Optical Transport Network (OTN) Market
Network Technology
Unified Network Management Market
Network Technology
Lit Fiber Market
Network Technology
Global Carrier Ethernet Equipment Market
Network Technology
Passive Optical Network Market
Network Technology
UK Fixed Connectivity Market
Network Technology
Carrier Routing Equipment Market
Network Technology
Global Private 5G Network Market
Network Technology
Data Center Switches Market
Network Technology
Ethernet Backhaul Equipment Market