
 Optical Network Terminal (ONT) Equipment Market | 2026-2036
Optical Network Terminal (ONT) Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Network Terminal (ONT) Equipment Market Analysis
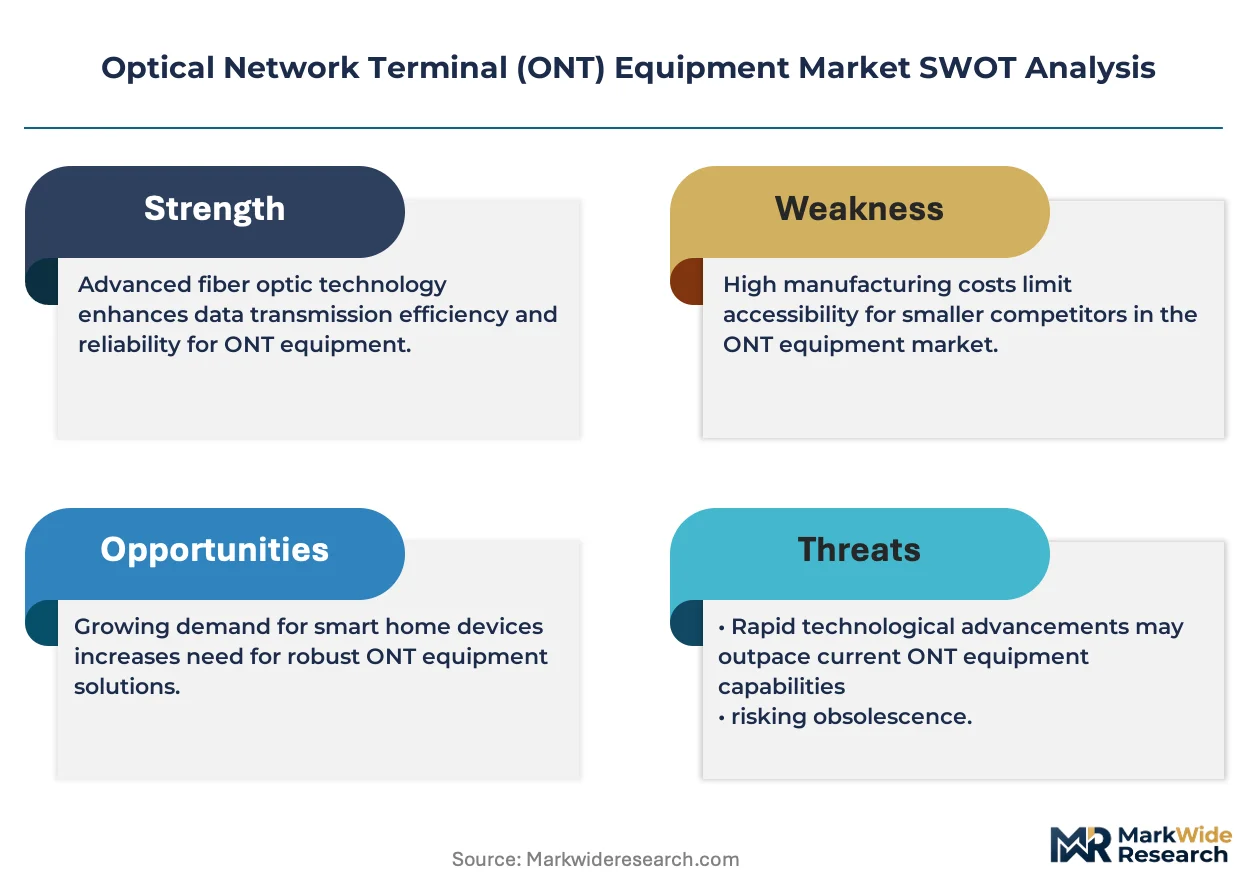
The ONT equipment landscape is pivoting on a widening split between premium XGS-PON units and commodity GPON devices. Huawei Technologies leverages captive silicon design to dominate high-throughput residential deployments. Nokia Corporation differentiates through software-defined ONT platforms that simplify operator provisioning. ZTE Corporation anchors volume production across Asia-Pacific markets with cost-optimized form factors.
An optical network terminal is a customer-premises device that terminates a passive optical network fiber link, converting optical signals to electrical Ethernet or Wi-Fi output at speeds from 1 Gbps to 10 Gbps depending on the PON protocol generation. Its primary purpose is to deliver last-mile broadband connectivity to residential, commercial, and enterprise subscribers. Residential ONT commands the largest shipment volumes though enterprise ONT carries superior margin pools due to managed service attach rates. XGS-PON technology is displacing GPON in new-build networks while EPON persists in legacy cable operator fiber overlays.
The US FCC, China's MIIT, and the EU's F-Gas Regulation each shape ONT demand through equipment certification, spectrum allocation for upstream fiber bands, and restrictions on refrigerants used in outdoor enclosures respectively. ITU-T G.9807 standards compliance governs interoperability and locks out non-certified vendors from operator tenders. Stakeholders must monitor wavelength division multiplexing roadmaps and operator capex cycle timing to align R&D bets with deployment windows.
Market Dynamics
The ONT equipment market pivots on wavelength division multiplexing roadmaps and operator capex cycle timing, with XGS-PON migration compressing procurement windows and locking vendor selection around ITU-T G.9807 certification compliance.
Growth Catalysts
- National broadband mandates:China's MIIT fiberization targets and the US FCC's Broadband Equity Access and Deployment program are accelerating municipal procurement cycles for next-generation PON infrastructure.
- XGS-PON technology migration:Telecom operators are replacing GPON with symmetric 10 Gbps platforms to support 4K video, cloud gaming, and remote work bandwidth requirements.
- F-Gas Regulation compliance:The EU's restrictions on refrigerants in outdoor enclosures are forcing enclosure redesigns that favor thermally efficient ONT form factors.
Market Restraints
- Silicon supply concentration:Captive chip design capabilities concentrate among vertically integrated Asian suppliers, constraining second-tier ONT vendors.
- GPON inventory overhang:Legacy EPON and GPON equipment stockpiles in cable operator warehouses are delaying XGS-PON refresh cycles.
- Interoperability certification costs:ITU-T G.9807 compliance testing and operator lab validation create six-to-nine month vendor onboarding timelines.
Strategic Opportunities
- Enterprise managed services attach:Commercial ONT deployments with SLA-backed Wi-Fi management and security overlays command premium pricing pools.
- Rural fiberization gaps:Germany's Gigabit Strategy and underserved US states present whitespace for utility co-op and municipal broadband ONT tenders.
- Software-defined ONT platforms:Zero-touch provisioning and cloud-native firmware management are converging with SD-WAN architectures.
Industry Challenges
- Optical engineering talent scarcity:PON protocol stack expertise and silicon-photonics integration skills are concentrated among legacy telecom vendors.
- Multi-generational network coexistence:GPON, XGS-PON, and emerging 25G-PON wavelength plans must operate on shared fiber plants without interference.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Network Terminal (ONT) Equipment Market |
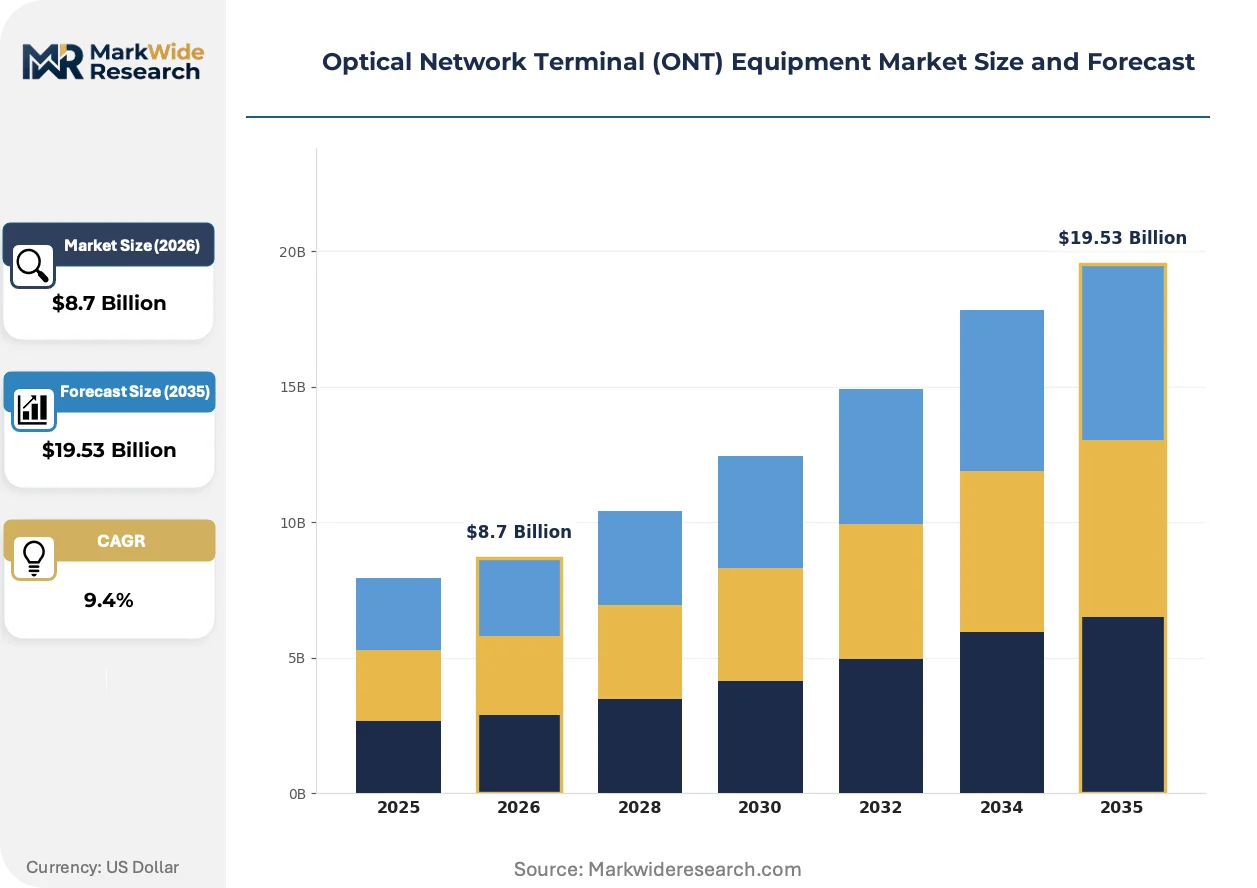
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential ONT, Commercial ONT, Industrial ONT, Enterprise ONT Technology: PON, GPON, XGS-PON, EPON End User: Telecom Operators, Internet Service Providers, Data Centers, Network Integrators Form Factor: Desktop, Wall-mounted, Integrated, Modular |
| Companies Covered | Huawei Technologies, ZTE Corporation, Nokia Corporation, FiberHome Telecommunication Technologies, ADTRAN Holdings, Calix, ADVA Optical Networking, Cisco Systems, Fujitsu Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Network Terminal (ONT) Equipment Market Emerging Trajectories
Wavelength division multiplexing evolution and software-defined network architectures are compressing equipment refresh cycles while fragmenting vendor procurement across specialized silicon, system integration, and managed service layers.
Multi-wavelength PON technology is expanding into operator access networks through ITU-T G.9804 standards development. Tier-1 carriers in China and Germany are trialing 25G-PON and 50G-PON overlays on existing fiber plants. This wavelength stacking is expanding into premium residential and enterprise verticals previously served by dedicated fiber drops.
The EU's F-Gas Regulation is banning hydrofluorocarbon refrigerants in outdoor telecom enclosures by 2030. ONT manufacturers are redesigning thermal management around passive cooling and phase-change materials. Outdoor-rated ONT deployments in Germany and France are shifting toward fanless architectures with extended temperature tolerances.
Subscription-based equipment procurement is displacing upfront capital purchases among municipal and cooperative broadband operators. Network-as-a-service models bundle ONT hardware, installation, and lifecycle management into per-subscriber monthly fees. This financing restructuring is most visible in US rural broadband deployments funded by USDA ReConnect and BEAD programs.
Optical Network Terminal (ONT) Equipment Market Segmentation
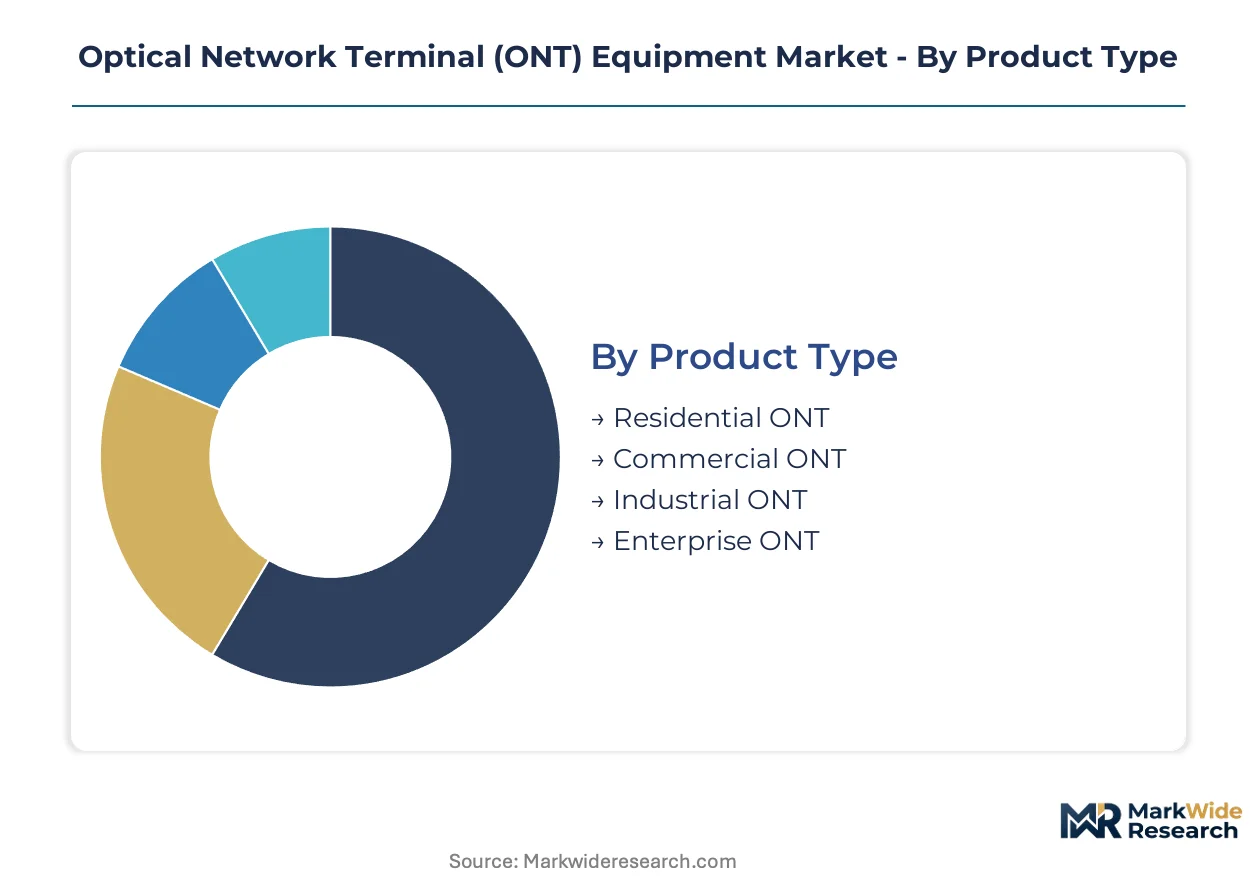
ONT procurement patterns diverge sharply across deployment contexts, with certification requirements varying by subscriber density and environmental exposure. Equipment vendors must align product roadmaps with distinct interoperability mandates and thermal specifications governing each segment category.
Product Type:
ITU-T G.9807 certification governs residential and commercial deployments, while industrial ONT units face additional IP65 enclosure ratings and extended temperature validation. Enterprise-grade equipment carries the heaviest compliance burden through dual-stack IPv4/IPv6 testing and SLA-backed reliability verification.
- Residential ONT:Single-family and multi-dwelling units dominate shipment volumes with GPON and XGS-PON variants. China's MIIT fiberization targets and the US FCC BEAD program are concentrating procurement in municipal broadband tenders across Jiangsu province and Texas counties. Cost-optimized form factors with integrated Wi-Fi 6 dominate this tier.
- Commercial ONT:Small business and retail deployments require managed service overlays with cloud-based provisioning portals. Germany's Gigabit Strategy is accelerating commercial ONT tenders in Bavaria and North Rhine-Westphalia as utility co-ops expand fiber footprints. Premium pricing reflects SLA-backed Wi-Fi management and security firmware subscriptions.
- Industrial ONT:Factory floor and utility substation deployments carry IP65/NEMA 4X enclosure requirements alongside electromagnetic immunity certifications. Demand concentrates in German manufacturing corridors and Chinese smart grid pilots.
- Enterprise ONT:Campus and headquarters deployments integrate with SD-WAN fabrics through zero-touch provisioning APIs. Financial services and healthcare verticals in the United States drive demand for FIPS 140-2 validated encryption modules.
Residential ONT sits at the top of the volume ranking, with Enterprise ONT climbing the fastest.
Technology:
Protocol generation determines silicon sourcing strategy and wavelength plan compatibility with existing fiber plants. GPON and XGS-PON command the largest procurement pools, while EPON persists in cable operator overlays and emerging markets.
- PON:Legacy broadband passive optical network equipment operates at 1.25 Gbps downstream with limited upstream symmetry. Remaining deployments concentrate in Eastern European municipal networks and Latin American cable operator fiber extensions.
- GPON:2.488 Gbps downstream asymmetric platforms retain installed base dominance in China and India. Inventory overhangs in US cable operator warehouses are delaying refresh cycles despite XGS-PON availability.
- XGS-PON:Symmetric 10 Gbps platforms are displacing GPON in new-build networks across Germany, the United States, and China. ITU-T G.9807 compliance locks vendor selection to certified suppliers, compressing procurement windows around operator capex cycles.
- EPON:Ethernet-based passive optical network technology persists in cable operator fiber overlays and Chinese tier-3 city deployments. Lower equipment costs sustain demand in price-sensitive emerging markets.
XGS-PON holds the dominant procurement position, with EPON contracting most rapidly in developed markets.
End User:
Procurement authority and technical specification control vary sharply across customer types, with telecom operators wielding the most stringent certification requirements.
- Telecom Operators:Tier-1 carriers in China, Germany, and the United States drive volume procurement through multi-year framework agreements. ITU-T G.9807 lab validation and field trials create six-to-nine month vendor onboarding timelines.
- Internet Service Providers:Regional and municipal broadband providers favor subscription-based equipment procurement through network-as-a-service models. USDA ReConnect and BEAD program funding is restructuring procurement toward per-subscriber monthly fees.
- Data Centers:Hyperscale facilities deploy ONT variants for campus interconnect and edge node backhaul. Demand concentrates in Northern Virginia, Frankfurt, and Singapore data center clusters.
- Network Integrators:System integration specialists bundle ONT hardware with installation and lifecycle management services. German utility co-ops and US electric cooperatives represent the fastest-expanding customer tier.
Telecom Operators anchor procurement volume, with Network Integrators expanding most quickly in rural fiberization programs.
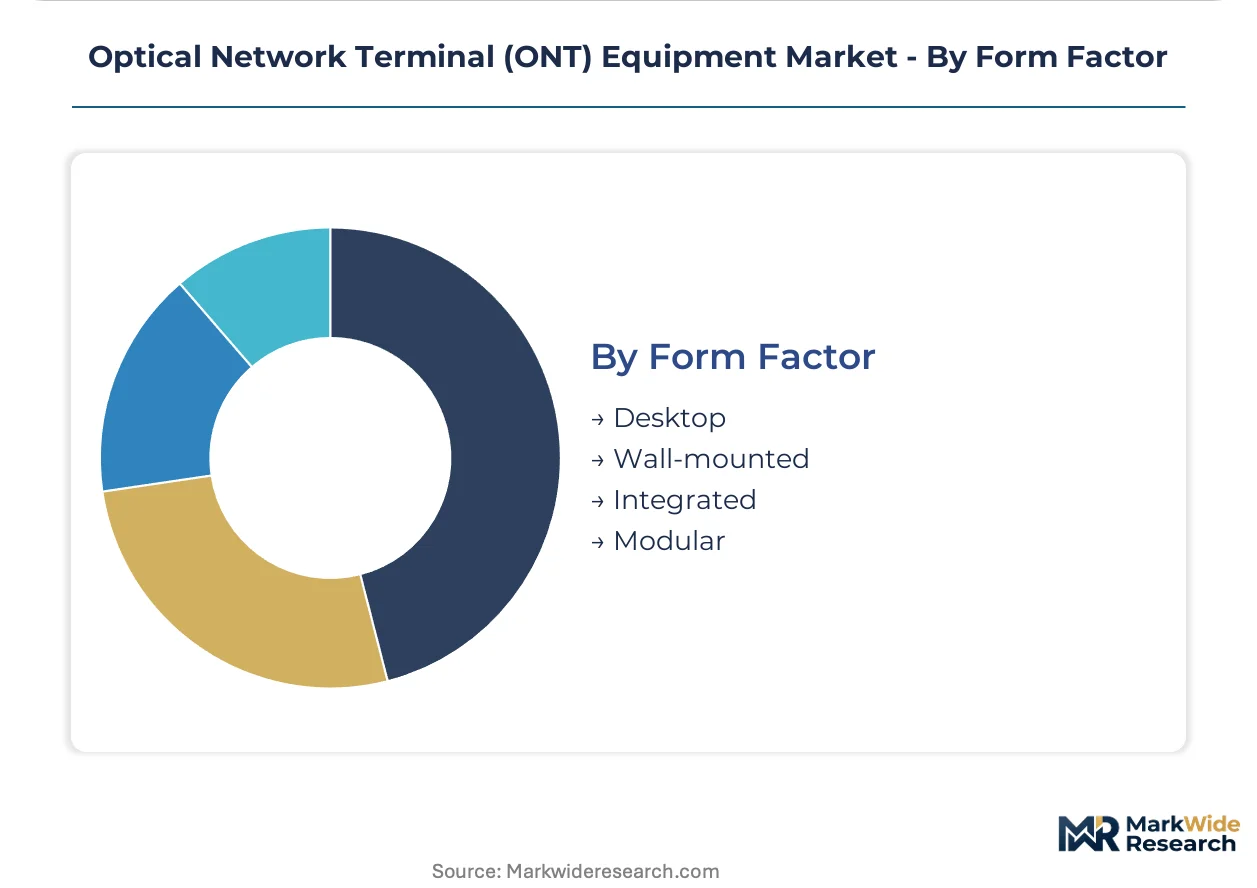
Form Factor:
Thermal management and installation labor requirements differentiate form factor selection, with outdoor-rated variants facing EU F-Gas Regulation compliance deadlines.
- Desktop:Consumer-facing units with external power supplies dominate residential self-install markets. China's e-commerce channels and US retail partnerships sustain this tier.
- Wall-mounted:Space-constrained multi-dwelling unit deployments favor bracket-mounted designs with integrated cable management. German and Japanese building codes drive demand for flush-mount variants.
- Integrated:Optical line terminal and ONT fusion products reduce equipment count in small-cell and enterprise deployments. Chinese manufacturers lead cost optimization for this emerging category.
- Modular:Field-upgradable chassis accommodate PON protocol migration without truck rolls. Enterprise and industrial verticals in Germany and the United States favor this flexibility premium.
Wall-mounted units lead installation volumes, with Modular designs gaining share fastest in enterprise refresh cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical engineering talent pools concentrate in Shenzhen, Espoo, and Stuttgart, anchoring ONT design centers near operator procurement headquarters. Vendor field application engineers cluster in these metros to compress certification timelines.
China
Jiangsu province municipal broadband tenders are absorbing XGS-PON volumes as MIIT fiberization targets accelerate equipment procurement. The country's GB standards compliance framework governs wavelength allocation for upstream fiber bands. Shenzhen's electronics manufacturing corridor hosts captive silicon design operations serving domestic operators.
United States
Texas counties and rural cooperatives are restructuring procurement through USDA ReConnect and FCC BEAD program funding. The FCC's Broadband Equity Access and Deployment program mandates ITU-T G.9807 certification for vendor participation. Northern Virginia data center clusters deploy ONT variants for campus interconnect and edge node backhaul.
Germany
Bavaria and North Rhine-Westphalia utility co-ops are expanding fiber footprints under the Gigabit Strategy. The EU's F-Gas Regulation is banning hydrofluorocarbon refrigerants in outdoor telecom enclosures by 2030. Stuttgart's industrial automation corridor drives demand for IP65-rated industrial ONT units.
Japan
Tokyo and Osaka metro building codes favor wall-mounted flush-mount ONT designs with integrated cable management. METI spectrum allocation policies shape upstream fiber band planning for multi-dwelling unit deployments. Nagoya's manufacturing belt requires electromagnetic immunity certifications for factory floor ONT installations.
South Korea
Seoul Capital Area multi-dwelling units are migrating to Wi-Fi 6 integrated XGS-PON form factors. The MFDS equipment certification framework parallels ITU-T standards for operator tender eligibility. Busan-Ulsan industrial zones pilot 25G-PON overlays for smart factory connectivity.
Optical Network Terminal (ONT) Equipment Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the ONT equipment landscape, with vertically integrated Asian suppliers holding captive silicon advantages and Western vendors relying on fabless semiconductor partnerships. The vendor base stratifies around certification-holding incumbents and modular system integrators. Three archetypes dominate: captive silicon designers, software-defined platform specialists, and subscription-based equipment financiers. Capacity expansion and strategic technology licensing represent the dominant competitive moves as operators compress procurement windows.
Among vertically integrated suppliers, Huawei Technologies and ZTE Corporation exemplify the captive silicon archetype with in-house semiconductor design capabilities. Nokia Corporation occupies a position representing software-defined ONT platforms that simplify operator provisioning workflows. These three anchors reflect the market's structural division between hardware-centric Asian producers and software-weighted Western vendors.
| Leading Market Players |
|---|
| Huawei Technologies |
| ZTE Corporation |
| Nokia Corporation |
| FiberHome Telecommunication Technologies |
| ADTRAN Holdings |
| Calix |
| ADVA Optical Networking |
| Cisco Systems |
| Fujitsu Limited |
| Others |
Supply Flow & Price Mechanics
The EU's F-Gas Regulation ban on hydrofluorocarbon refrigerants gates qualified supply for outdoor-rated ONT enclosures and anchors premium-tier pricing access for thermally efficient, fanless architectures. Equipment vendors must redesign thermal management systems to maintain operator tender eligibility, compressing margin structures for non-compliant producers while rewarding early movers with certification-backed pricing power.
Pricing Analysis
The bundled-versus-unbundled service split separates subscription-based network-as-a-service models from traditional capital purchase structures. Pricing stratifies across ITU-T G.9807 certified premium tiers, standard GPON legacy tiers, and economy EPON residual tiers, with certification level and managed service attach rates as primary differentiation drivers. Cost compression in the GPON tier intensifies because of inventory overhangs in cable operator warehouses. Municipal broadband operators exhibit the highest price sensitivity, while enterprise verticals with SLA requirements show the least.
Supply Chain Analysis
Freight cost volatility from Shenzhen manufacturing clusters to operator distribution hubs in Germany and the United States shapes inventory positioning strategies for ONT vendors. Silicon sourcing draws from captive design operations in China, fabless semiconductor partnerships in Taiwan, and legacy telecom component suppliers in Japan. Single-source vulnerability concentrates in vertically integrated Asian suppliers controlling PON protocol stack chipsets. Distribution runs through tier-1 carrier framework agreements, regional ISP procurement consortia, and network integrator bundling arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with China's MIIT fiberization targets and the US FCC's BEAD program creating sustained equipment demand through mandated deployment timelines.
For Market Incumbents: Cement ITU-T G.9807 certification leadership through accelerated lab validation investments, defending against modular system integrators encroaching on enterprise verticals. Capacity addition in Stuttgart and Espoo design centers compresses field application engineer response times for European operator tenders. Vertical integration into silicon-photonics R&D locks out second-tier vendors dependent on merchant chip supply. For New Entrants and Emerging Players: Software-defined ONT platforms with zero-touch provisioning APIs offer a technology-first wedge into municipal broadband whitespace in underserved US counties and German utility co-op territories. Rural fiberization gaps present the most penetrable geography. A network-as-a-service financing model aligns with USDA ReConnect and BEAD program restructuring of procurement toward per-subscriber monthly fees. For Investors and Strategic Acquirers: Roll-up economics work for modular system integrators because operator procurement fragmentation across specialized silicon, system integration, and managed service layers favors consolidation plays. The five-to-ten year viability window hinges on wavelength division multiplexing roadmap execution. Acquisition targets should demonstrate ITU-T G.9807 certification holdings and established operator lab relationships. The signal to watch is 25G-PON and 50G-PON trial conversion rates among tier-1 carriers.| Strategic Initiative | Industry Significance |
|---|---|
| ITU-T G.9807 Certification Investment | Locks vendor selection for XGS-PON tenders with China MIIT and US FCC BEAD program operators. |
| Software-Defined ONT Platform Development | Converges zero-touch provisioning with SD-WAN architectures for enterprise managed service attach. |
| Silicon-Photonics Integration | Captures captive supply advantages for high-throughput residential deployments against merchant chip competitors. |
| Network-as-a-Service Financing Model | Aligns with USDA ReConnect and BEAD program restructuring toward per-subscriber monthly procurement fees. |
| F-Gas Compliant Thermal Redesign | Maintains EU market access through passive cooling and phase-change material enclosures by 2030 deadline. |
Methodological Framework
Bottom-up operator procurement modeling reconciled against top-down silicon supply tracking forms the analytical core of this study. Primary interviews with tier-1 carrier procurement directors, municipal broadband program managers, network integrator sales executives, and ONT vendor field application engineers combined with secondary validation from FCC BEAD program filings, China MIIT equipment certification databases, EU F-Gas Regulation compliance registries, and ITU-T standards documentation. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map subscriber addition rates, PON protocol migration curves, and operator capex cycle timing against equipment shipments across the projection horizon. Segmentation dimensions modeled include product type, technology generation, end-user category, and form factor, with regional regulatory cluster as an additional industry-specific dimension. CAGRs derive from fitted growth curves applied to base-year estimates, incorporating XGS-PON displacement rates and national broadband mandate enforcement timelines as key forecast inputs.
The model holds under sustained operator fiberization commitments and stable silicon supply; deviation in trade restriction escalation or wavelength standard fragmentation would shift equipment procurement timelines. Forecasts reflect documented assumptions about regulatory enforcement consistency and operator technology migration pacing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Global Premium A2P and P2A Messaging Market
Telecommunications
Transport Stream Switching Market
Telecommunications
Managed M2M Services Market
Telecommunications
United Arab Emirates Telecom Market
Telecommunications
Global SS7 Market
Telecommunications
Oman Telecommunication Market
Telecommunications
Call Control (PBX-IP PBX) Market
Telecommunications
Thailand Telecom Market
Telecommunications
Nigeria Satellite Communications Market
Telecommunications
Thailand ICT Market
Telecommunications
Cloud PBX Market
Telecommunications
Costa Rica Telecom Market
Telecommunications
Cambodia Telecom Tower Market
Telecommunications
Global SMB Telecom Voice and Data Services Market
Telecommunications
Satellite Broadband Communication in Public Safety Market
Telecommunications
Global Small Cell 5G Network Market