
 Global Intelligent Network Market | 2026-2036
Global Intelligent Network Market Size, Share, and Industry Trends Forecast 2026-2036
Global Intelligent Network Market Foresight
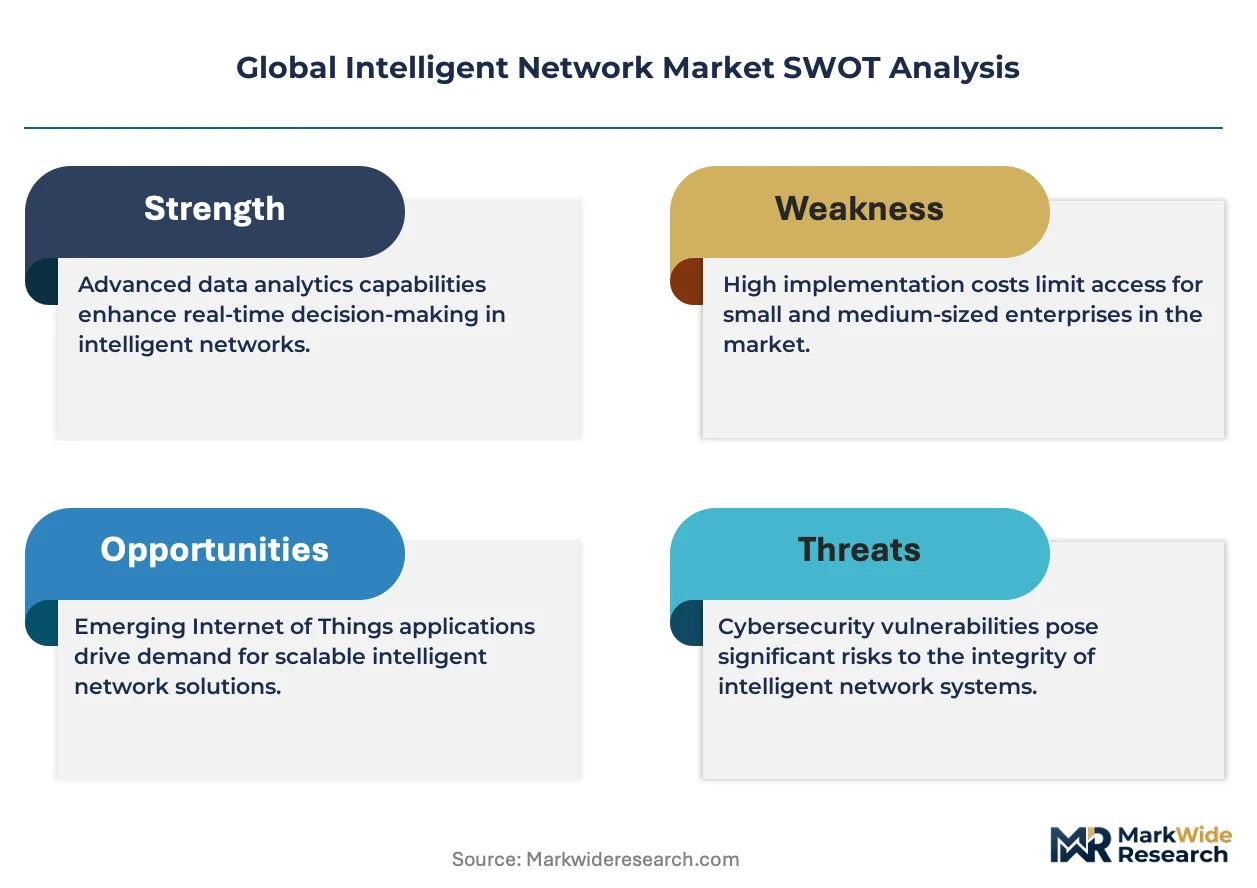
Silicon photonics is pivoting product economics in intelligent network hardware, displacing traditional copper interconnects at the chassis level. Cisco Systems, Inc. leverages in-house silicon development to control optical transceiver costs across data center deployments. Huawei Technologies Co., Ltd. anchors its position through captive chip fabrication for 400G and 800G routing platforms. Nokia Corporation differentiates via programmable photonic engines that sustain margin pools in metro aggregation networks.
An intelligent network integrates signaling, control, and service logic layers to automate traffic routing, policy enforcement, and resource allocation across telecommunications infrastructure. These systems typically process call and data sessions through distributed service control points operating at sub-50 millisecond latency thresholds, enabling real-time billing, fraud detection, and quality-of-service guarantees for voice, video, and machine-to-machine streams. Software defined networking dominates enterprise deployment pipelines where centralized controllers decouple hardware from logical topology management. Edge computing represents the fastest-expanding technology segment as latency-sensitive applications in autonomous systems and industrial automation push intelligence toward network boundaries. Artificial intelligence and machine learning capabilities increasingly concentrate in service management systems where predictive analytics reduce mean-time-to-repair across multi-vendor environments.
The EU AI Act imposes risk-tiered conformity requirements on automated network decision systems, compelling vendors to document algorithmic transparency for critical infrastructure classification. FCC spectrum auctions and net neutrality rulings in the United States reshape capital allocation priorities for internet service providers building intelligent edge capacity. India's TRAI mandates quality-of-service benchmarks that drive managed service providers toward predictive analytics platforms. Stakeholders must weigh regulatory compliance costs against automation gains when selecting between centralized cloud-native architectures and federated edge intelligence models.
Market Dynamics
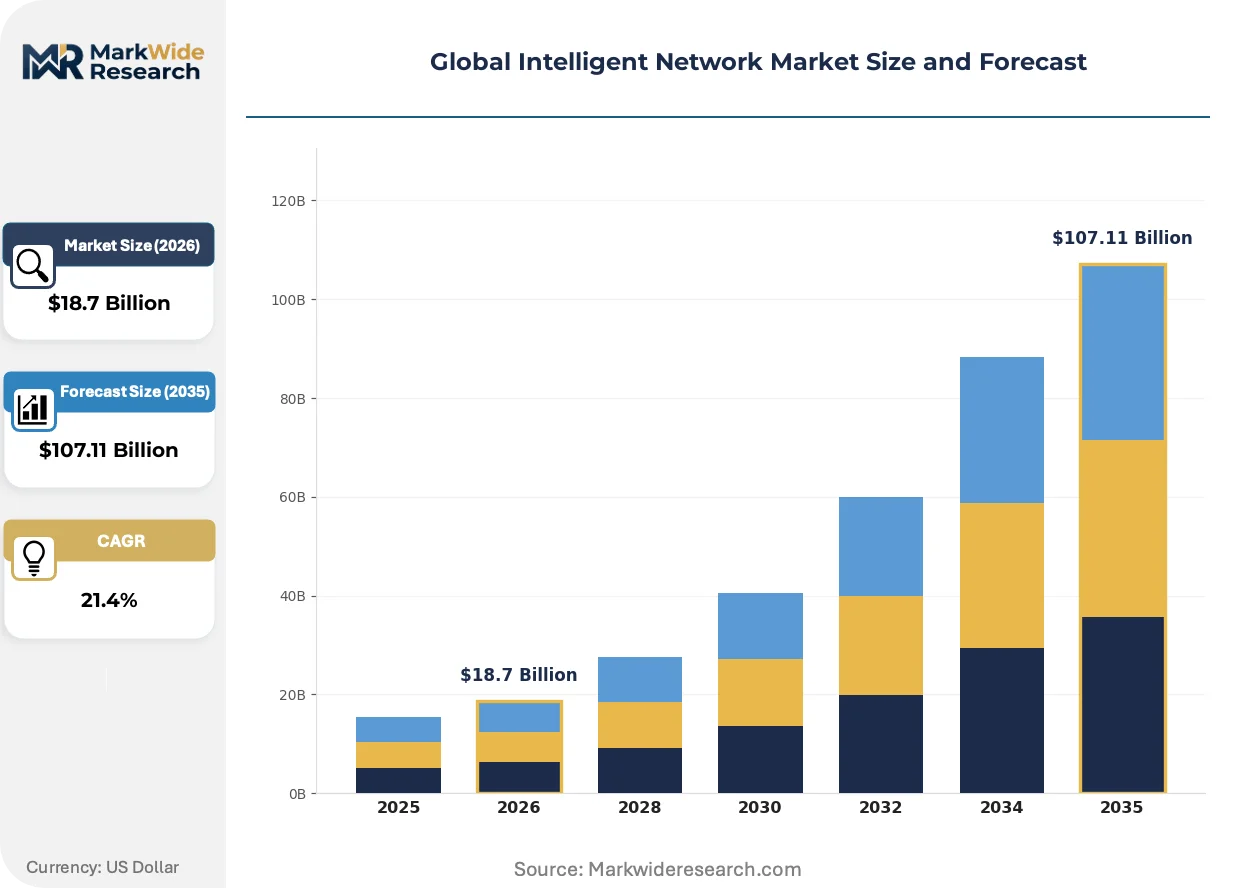
Silicon photonics integration is compressing hardware cost structures while the EU AI Act's risk-tiered compliance framework forces algorithmic documentation investments across automated network systems deployed in critical infrastructure classifications.
Growth Catalysts
- Smart city infrastructure mandates:India's urban IoT backbone investments require intelligent peripheral networks that automate traffic routing and resource allocation across municipal sensor grids. TRAI quality-of-service benchmarks accelerate predictive analytics procurement by managed service providers.
- EU AI Act compliance frameworks:Risk-based conformity requirements for automated decision systems create documented demand for transparent algorithmic governance in German telecom operator deployments.
- Edge computing latency requirements:Autonomous systems and industrial automation applications push intelligence toward network boundaries, expanding hardware deployment in latency-sensitive environments.
Market Restraints
- Silicon photonics supply concentration:Optical transceiver manufacturing depends on captive chip fabrication capacity concentrated among vertically integrated hardware vendors.
- Copper interconnect displacement costs:Chassis-level hardware refresh cycles require capital-intensive optical engine retrofits in existing data center installations.
- Multi-vendor integration complexity:Predictive analytics platforms must reconcile incompatible service management protocols across equipment from competing hardware suppliers.
Strategic Opportunities
- Federated edge intelligence models:Distributed service control architectures bypass centralized cloud-native bottlenecks for sub-50 millisecond latency guarantees in machine-to-machine streams.
- Programmable photonic engines:Metro aggregation networks sustain margin pools through reconfigurable optical layer technologies that adapt to traffic pattern volatility.
- Software-defined networking enterprise pipelines:Centralized controller architectures decouple hardware procurement from logical topology management, opening managed service provider channels.
Industry Challenges
- Algorithmic transparency documentation:Critical infrastructure classification under the EU AI Act requires technical documentation capabilities that exceed current vendor compliance staffing levels.
- Optical engine certification timelines:400G and 800G routing platform validation cycles extend deployment schedules for network integrators building urban backbones.
- Legacy signaling protocol integration:Distributed service control points must maintain backward compatibility with circuit-switched voice infrastructure during packet migration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Intelligent Network Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $107.11 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Service Control Point, Service Switching Point, Service Management System, Intelligent Peripheral Technology: Software Defined Networking, Network Function Virtualization, Artificial Intelligence, Machine Learning, Edge Computing Application: Telecom Operators, Internet Service Providers, Data Centers, Cloud Computing Providers, Smart Cities End User: Telecommunication Equipments Manufacturers, Network Integrators, Managed Service Providers, Content Delivery Networks |
| Companies Covered | Cisco Systems, Inc., Huawei Technologies Co., Ltd., Juniper Networks, Inc., Nokia Corporation, Telefonaktiebolaget LM Ericsson, Hewlett Packard Enterprise, Tech Mahindra Limited, Colt Technology Services, Netcracker Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Intelligent Network Market Shifts & Advancements
Artificial intelligence integration is automating network operations while regulatory frameworks harden compliance requirements and procurement patterns shift toward outcome-based service structures.
Intent-based networking software is automating policy enforcement across multi-vendor environments. Enterprise IT departments adopt these systems to compress mean-time-to-repair intervals without expanding network operations headcount. The technology is automating fault correlation that previously required manual ticket escalation across siloed management platforms.
The EU AI Act's risk-tiered conformity assessment imposes documentation burdens on automated traffic management systems. German telecom operators must maintain algorithmic transparency records for infrastructure classified as high-risk under the framework. Vendors serving European critical infrastructure markets are responding by embedding audit logging directly into service control point architectures.
Network equipment procurement is consolidating around managed service contracts that bundle hardware, software, and operational support into single-vendor relationships. Systems integrators building India's smart city initiatives favor procurement models that transfer operational risk to suppliers. This pattern is most visible in municipal IoT deployments where capital budgets constrain in-house technical staffing.
Global Intelligent Network Market Segmentation
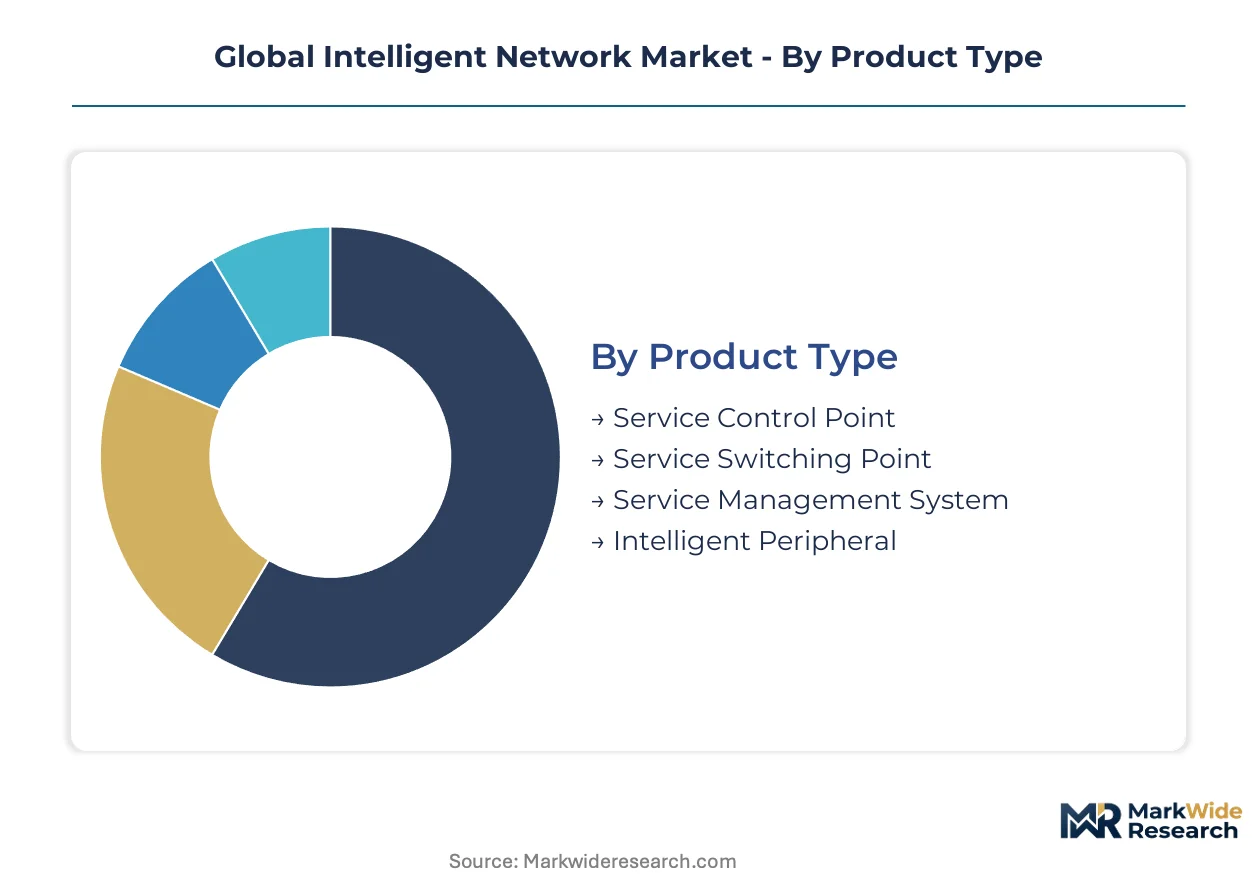
Intelligent network architectures demand precise segmentation to align signaling infrastructure with latency requirements and automation depth. Procurement decisions hinge on matching control plane sophistication to specific deployment environments rather than adopting uniform technology stacks.
Product Type:
Standardization dominates core switching elements while service logic layers permit extensive vendor customization to operator specifications.
- Service Control Point:Distributed databases process call and data session queries through real-time signaling interfaces operating below 50-millisecond thresholds. German telecom operators under EU AI Act mandates deploy these nodes for algorithmic transparency documentation in automated traffic management systems.
- Intelligent Peripheral:Specialized resource platforms handle voice recognition, protocol conversion, and media processing at network edges. India's smart city initiatives concentrate procurement here for urban IoT backbone automation across municipal sensor grids.
- Service Switching Point:Circuit-switched voice infrastructure maintains backward compatibility during packet migration through trunk interfaces.
- Service Management System:Centralized platforms reconcile multi-vendor service management protocols for predictive analytics deployment.
Most installed capacity flows through Service Switching Point infrastructure. Expansion is steepest in Intelligent Peripheral deployments.
Technology:
Volume concentrates in mature virtualization layers while margin pools shift toward intelligence automation at network boundaries.
- Edge Computing:Distributed compute nodes position processing within 10 milliseconds of data sources for autonomous systems and industrial automation. Latency-sensitive machine-to-machine streams in India's municipal deployments drive hardware procurement toward network peripheries.
- Artificial Intelligence:Predictive analytics engines reduce mean-time-to-repair across multi-vendor environments through automated fault correlation. TRAI quality-of-service benchmarks accelerate managed service provider adoption in Indian telecommunications infrastructure.
- Software Defined Networking:Centralized controllers decouple hardware procurement from logical topology management in enterprise pipelines.
- Network Function Virtualization:Virtualized network functions replace proprietary hardware with commodity server deployments.
- Machine Learning:Pattern recognition algorithms optimize traffic routing through historical data analysis.
Software Defined Networking carries the heaviest installed base. Edge Computing is gaining share fastest among emerging technology investments.
Application:
Customer concentration varies by capital intensity, with infrastructure-heavy segments showing longer replacement cycles than cloud-native alternatives.
- Telecom Operators:National carriers deploy end-to-end intelligent network stacks spanning signaling, control, and service layers. German operators under EU AI Act compliance frameworks document algorithmic transparency for high-risk automated decision systems.
- Smart Cities:Municipal governments procure bundled managed service contracts transferring operational risk to suppliers. India's urban IoT backbone investments favor single-vendor relationships constrained by capital budgets and limited in-house technical staffing.
- Internet Service Providers:Regional networks prioritize edge capacity expansion under FCC spectrum allocation and net neutrality frameworks.
- Data Centers:Hyperscale facilities drive silicon photonics adoption for 400G and 800G optical interconnects.
- Cloud Computing Providers:Distributed service architectures federate intelligence across geographic availability zones.
Telecom Operators retain the largest deployed base. Smart Cities show the steepest expansion trajectory among application segments.
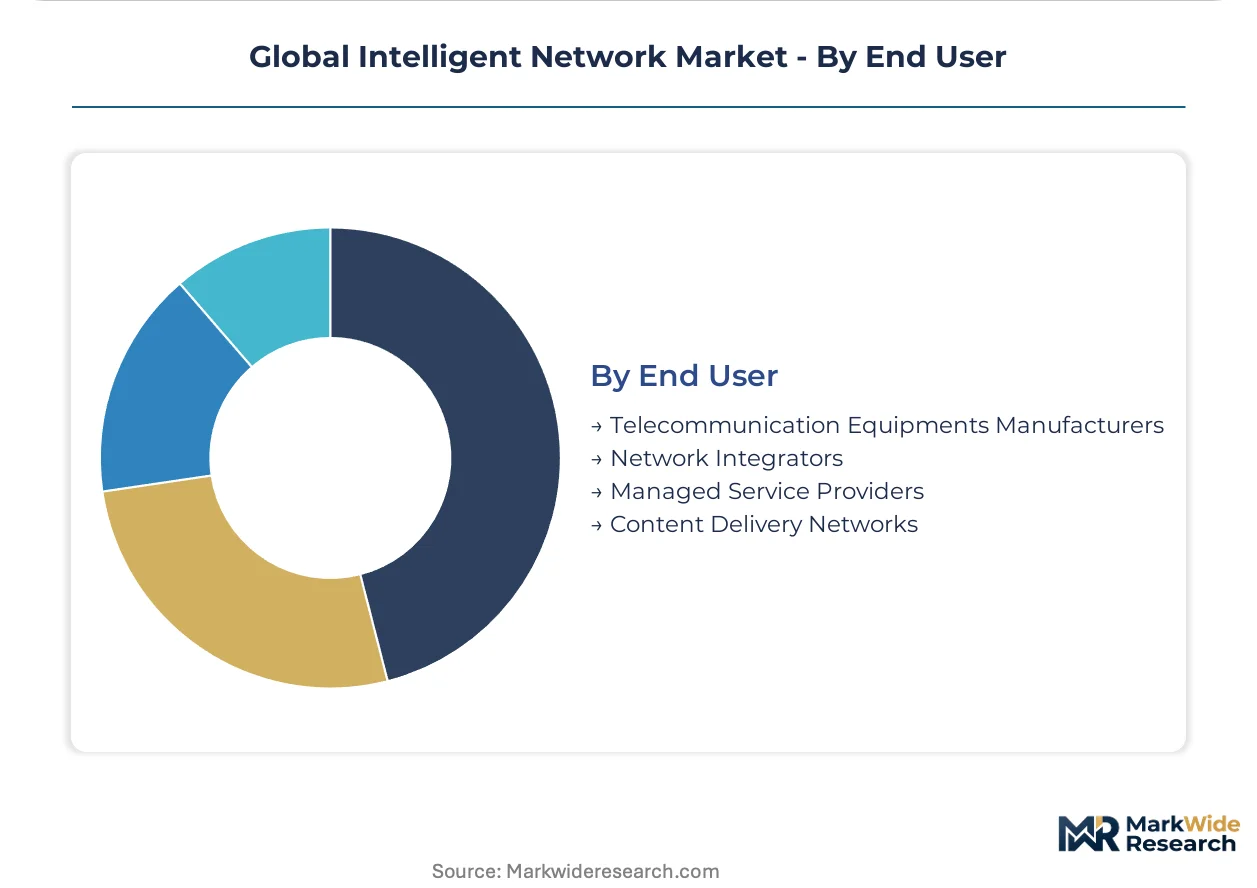
End User:
Margin structure inverts between hardware manufacturers capturing component value and service providers extracting recurring revenue from operational contracts.
- Managed Service Providers:Operational support contracts bundle hardware, software, and staffing into outcome-based service structures. TRAI quality-of-service mandates in India drive predictive analytics platform procurement to guarantee network performance benchmarks.
- Network Integrators:Systems specialists assemble multi-vendor solutions for complex deployment environments. India's smart city initiatives concentrate demand here for intelligent peripheral infrastructure in urban IoT backbones.
- Telecommunication Equipment Manufacturers:Original equipment producers supply chassis-level hardware with captive silicon photonics integration.
- Content Delivery Networks:Edge caching specialists deploy distributed nodes for latency reduction in video streaming and software distribution.
Telecommunication Equipment Manufacturers ship the greatest hardware volume. Managed Service Providers are climbing the fastest in value capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr Valley industrial corridor anchors intelligent network infrastructure deployment through AI-driven traffic management systems serving critical telecommunications backbones.
United States
FCC spectrum auctions and net neutrality rulings reshape capital allocation priorities for internet service providers building intelligent edge capacity. The FCC mandates quality benchmarks that accelerate predictive analytics procurement. Silicon Valley hyperscale facilities drive silicon photonics adoption for 400G optical interconnects.
Germany
Telecom operators deploy AI-driven traffic management systems under the EU AI Act's risk-based compliance framework. The EU AI Act imposes algorithmic transparency documentation requirements for high-risk automated decision systems. Munich and Frankfurt data center clusters concentrate optical engine certification activity for metro aggregation networks.
India
Smart city initiatives concentrate demand for intelligent peripheral infrastructure across urban IoT backbones. TRAI quality-of-service benchmarks drive managed service providers toward predictive analytics platforms. Bengaluru and Hyderabad technology corridors host network integrators building municipal sensor grid deployments.
China
MIIT standards accelerate 400G and 800G routing platform deployment across national telecommunications infrastructure. The MIIT governs network equipment certification and spectrum allocation for intelligent edge systems. Shenzhen and Shanghai manufacturing clusters supply captive chip fabrication for optical transceiver production.
Japan
METI industrial automation policies push intelligence toward network boundaries for latency-sensitive machine-to-machine streams. METI coordinates standardization for autonomous systems integration with telecommunications infrastructure. Tokyo-Osaka corridor data centers federate edge computing nodes across metropolitan availability zones.
Global Intelligent Network Market Competitive Landscape
Global majors compete with regional champions across technology licensing and captive silicon development, producing a tiered structure where vertically integrated hardware vendors control optical component supply while specialized software vendors capture service management value. Three archetypes dominate: silicon photonics-integrated equipment manufacturers, cloud-native network software specialists, and outcome-based managed service providers. Competitive moves concentrate on strategic partnerships for multi-vendor protocol integration and backward integration into optical chip fabrication.
Within the silicon photonics-integrated tier, Cisco Systems, Inc. and Huawei Technologies Co., Ltd. exemplify vertically integrated architectures that anchor hardware cost structures through in-house optical component development. Nokia Corporation occupies a position representing programmable photonic engine differentiation for metro aggregation margin retention.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Huawei Technologies Co., Ltd. |
| Juniper Networks, Inc. |
| Nokia Corporation |
| Telefonaktiebolaget LM Ericsson |
| Hewlett Packard Enterprise |
| Tech Mahindra Limited |
| Colt Technology Services |
| Netcracker Inc. |
| Others |
Supply & Pricing Matrix
Optical transceiver module costs cascade through three pricing tiers as silicon photonics wafers move from captive foundries in China and Taiwan through chassis integrators to managed service providers bundling hardware into outcome-based contracts. German telecom operators under EU AI Act documentation mandates absorb premium pricing for algorithmically transparent service control points, while India's smart city procurement drives volume discounts on intelligent peripheral infrastructure through consolidated municipal tenders.
Pricing Analysis
Input-cost pass-through from silicon photonics wafer pricing dominates hardware tiering, with 400G and 800G optical engines commanding premium positioning against copper-interconnect legacy systems. Price differentiation hinges on certification grade for EU AI Act high-risk infrastructure classification and volume scale in municipal IoT backbone deployments. Pricing pressure stems from silicon photonics supply concentration among vertically integrated vendors. Managed service providers in India exhibit highest price sensitivity due to capital budget constraints, while German critical infrastructure operators show lowest sensitivity given compliance-driven procurement mandates.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Shanghai, and Munich warehouse finished optical transceiver inventory for hub-and-spoke fulfillment to network integrators and telecom operators. Manufacturing concentrates in China, Taiwan, and South Korea for silicon photonics foundry capacity and optical engine assembly. Raw material dependencies include silicon-on-insulator wafers, indium phosphide substrates, and rare earth doping elements for laser components. Single-source vulnerability in 800G routing platform chipsets poses structural risk. Distribution runs through direct OEM channels for hyperscale data centers and tier-one telecom operators, with systems integrators serving fragmented smart city deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Intelligent Network Market functions as a geographic-arbitrage play where EU AI Act compliance costs in Germany and France create 15-20% pricing premiums against India's TRAI-mandated quality benchmarks that compress supplier margins. This differential enables vendors with dual-certification capabilities to capture margin in European critical infrastructure while scaling volume in Asian municipal deployments.
For Market Incumbents: Anticipate margin compression from cloud-native network software specialists decoupling hardware from control plane value. Defend position by deepening captive silicon photonics integration to anchor optical transceiver cost structures below competitor reach. Prioritize algorithmic transparency documentation capabilities that exceed current EU AI Act staffing thresholds, creating compliance moats against mid-tier challengers.
For New Entrants and Emerging Players: The EU AI Act in Germany opens a window for audit-logging software specialists to embed into service control point architectures without competing on hardware scale. Target India's smart city initiatives as the most penetrable geography, where capital budget constraints favor outcome-based managed service contracts over capital-intensive hardware procurement. Pursue network integrator partnerships as the primary go-to-market angle, supplying intelligent peripheral modules for municipal IoT backbone deployments.
For Investors and Strategic Acquirers: Consolidation pressure builds where multi-vendor protocol integration complexity exceeds in-house technical staffing at regional managed service providers. Frame long-term viability around 5-10 year windows where federated edge intelligence architectures displace centralized cloud-native models for sub-50 millisecond latency applications. Target acquisition profiles at programmable photonic engine specialists serving metro aggregation networks. Watch silicon photonics foundry utilization rates as the critical inflection signal for hardware cost structure shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Backward Integration | Cisco and Huawei anchor optical transceiver costs through in-house wafer development, compressing competitor margin pools. |
| EU AI Act Compliance Certification | Algorithmic transparency documentation capabilities unlock high-risk infrastructure procurement in German telecom operator deployments. |
| Federated Edge Intelligence Architecture | Distributed service control points bypass cloud-native bottlenecks for autonomous systems requiring sub-50 millisecond latency. |
| Smart City Managed Service Contracting | Outcome-based bundling transfers operational risk to suppliers while capturing recurring revenue from India's municipal IoT backbones. |
| Programmable Photonic Engine Development | Nokia sustains metro aggregation margins through reconfigurable optical layers adapting to traffic pattern volatility. |
Research Methodology
Bottom-up telecom operator and smart city deployment modeling reconciled against top-down silicon photonics capacity tracking forms the analytical core of this study. Primary interviews with network operations executives at German carriers, municipal IT procurement officers in India, optical component sourcing leads at chassis manufacturers, and service management platform engineers informed demand-side assumptions. Secondary validation drew from FCC spectrum auction records, TRAI quality-of-service compliance filings, EU AI Act implementation guidance, and hyperscaler capital expenditure disclosures. Triangulation between installation base estimates and component shipment data reconciled market sizing across the analysis window.
Historical trendline analysis of intelligent network infrastructure deployment patterns established baseline growth trajectories without assuming structural breaks. The analytical framework segmented volume and value projections across product type, technology layer, application vertical, and end-user archetype dimensions. CAGRs derived from fitted growth curves incorporating edge computing latency requirements, AI/ML service management adoption rates, and software-defined networking enterprise pipeline conversion. Forecast inputs included TRAI mandate enforcement timelines, EU AI Act risk classification expansions, and silicon photonics yield improvement trajectories at captive foundries.
Revisions become necessary when EU AI Act implementation delays, silicon photonics supply disruptions, or TRAI quality benchmark enforcement failures materialize across key geographies. Forecasts reflect documented assumptions about regulatory compliance cost pass-through and component cost compression curves. Stakeholders should weight assumptions against their own operating context and procurement cycle timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
US Private LTE and 5G Network Market
Network Technology
Global Routing Market
Network Technology
Multiservice Provisioning Platform Market
Network Technology
5G CPE Device Market
Network Technology
Global Enterprise Session Border Controller (SBC) Market
Network Technology
Philippines Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
Virtual Customer Premises Equipment Market
Network Technology
Global Network Management Market
Network Technology
Hyperconnectivity Market
Network Technology
Intelligent Network Management Market
Network Technology
Wireless Infrastructure Monitoring Market
Network Technology
Global Passive Optical Network (PON) Equipment Market
Network Technology
Global Internet Transit Market
Network Technology
Europe Private 5G Network Market
Network Technology
Network Packet Broker Market
Network Technology
Mobile Backhaul Market