
 Regulatory Change Management Software Market | 2026-2036
Regulatory Change Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Regulatory Change Management Software Market Analytics
Subscription-based compliance monitoring is consolidating around recurring-revenue platforms that embed regulatory feeds directly into workflow engines. MetricStream leverages its GRC heritage to anchor enterprise deployments across banking and energy verticals. NAVEX Global competes through integrated ethics and compliance modules that extend beyond pure regulatory tracking.
Regulatory change management software automates the ingestion, interpretation, and operationalization of evolving legal and industry mandates through configurable rule engines and natural-language processing pipelines. Cloud-based solutions lead deployment preferences due to elastic scaling during peak regulatory cycles, while artificial intelligence segments capture margin pools through automated impact-assessment engines that reduce manual legal review hours. Hybrid solutions sustain relevance among energy companies and telecommunications operators with segmented data-sovereignty requirements.
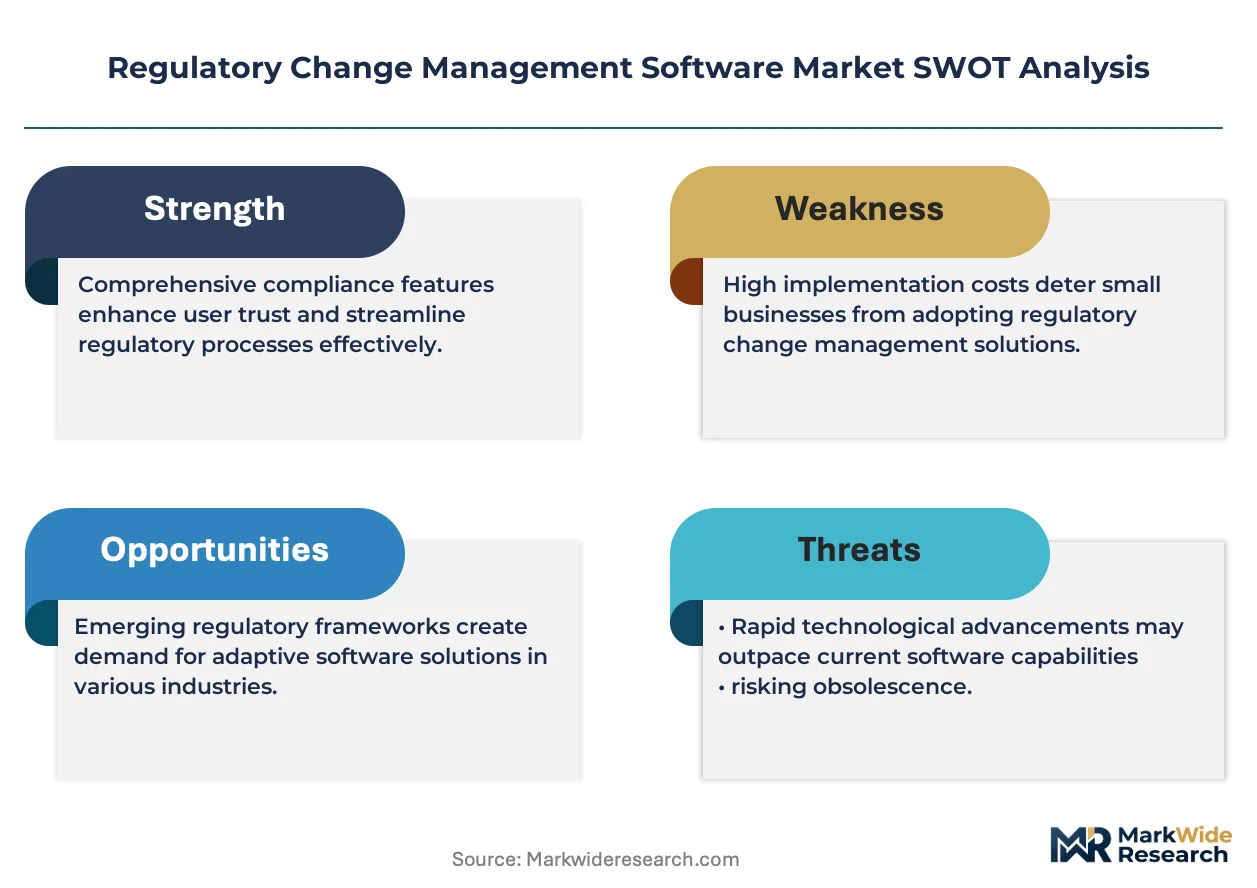
The EU AI Act, GDPR, and SEC climate disclosure rules shape product roadmaps by mandating auditable change trails and real-time compliance dashboards. FDA 21 CFR Part 11 and HIPAA drive healthcare-provider demand for validated systems with electronic signature integrity. Stakeholders must evaluate whether their current platforms can ingest multi-jurisdictional rule feeds without custom integration overhead.
Market Dynamics
Subscription-based compliance platforms are consolidating procurement power by embedding regulatory feeds directly into workflow engines, compressing integration timelines and displacing point solutions.
Growth Catalysts
- EU AI Act enforcement:Financial institutions in Germany and France face mandatory algorithmic audit trails, accelerating procurement of automated impact-assessment engines.
- Cloud-native architectures:Elastic scaling capabilities during peak regulatory cycles enable banks to process 10x volume spikes without infrastructure overhauls.
- GDPR cross-border data rules:Multinational corporations require unified compliance dashboards spanning EU member state variations, driving enterprise platform consolidation.
Market Restraints
- Specialized NLP talent scarcity:Legal-technical hybrid expertise commands premium compensation, inflating implementation costs for mid-market buyers.
- Data sovereignty fragmentation:Energy and telecommunications operators in segmented jurisdictions face hybrid deployment mandates that complicate vendor selection.
- Legacy system entrenchment:Core banking platforms with decades-old codebases resist API-based integration, extending proof-of-concept phases.
Strategic Opportunities
- Healthcare provider segment:FDA 21 CFR Part 11 and HIPAA mandates create validated-system demand with electronic signature integrity requirements.
- API-first distribution:Embedded compliance modules within ERP and CRM marketplaces reduce customer acquisition costs and accelerate land-and-expand cycles.
- SEC climate disclosure rules:Auditable change trails for sustainability reporting open new product lines beyond traditional financial compliance.
Industry Challenges
- Multi-jurisdictional rule harmonization:Platform engineering teams must reconcile conflicting GDPR, HIPAA, and state-level privacy mandates without custom code branches.
- Continuous validation overhead:Healthcare and financial services deployments require documented testing cycles that slow release velocity and inflate maintenance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Regulatory Change Management Software Market |
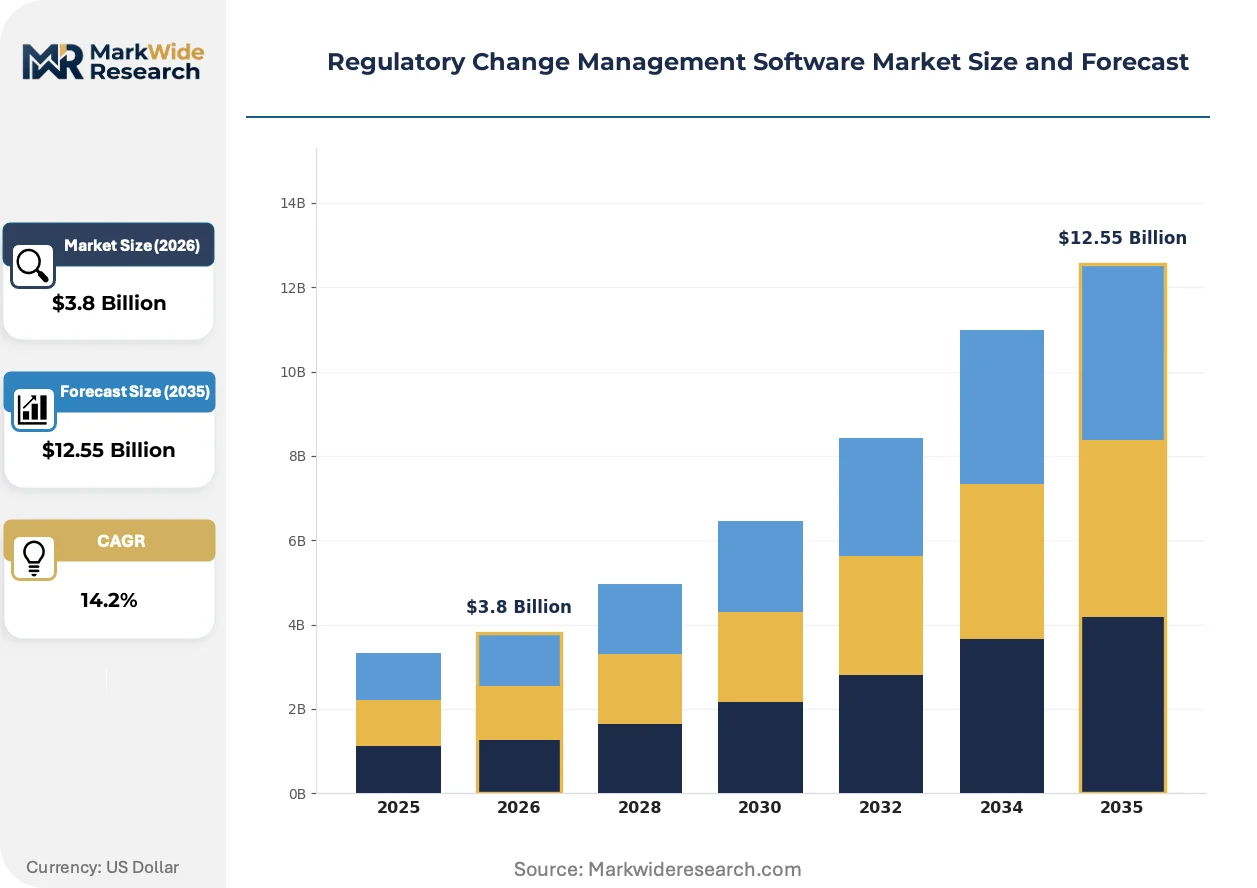
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premise Software, Cloud-Based Solutions, Hybrid Solutions, Mobile Applications End User: Financial Institutions, Healthcare Providers, Energy Companies, Telecommunications Technology: Artificial Intelligence, Blockchain, Data Analytics, Machine Learning Deployment: Public Cloud, Private Cloud, Community Cloud, Local Server |
| Companies Covered | Centraleyes, Diligent, MetricStream, Regology, LogicManager, NAVEX Global, RSA Archer, Mitratech, Enablon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Regulatory Change Management Software Market Evolving Landscape
Natural-language processing pipelines are compressing legal review cycles from weeks to hours, while regulatory intelligence networks automate cross-border mandate tracking.
Regulatory change management software is modularizing through microservices architectures that separate rule ingestion, impact scoring, and workflow orchestration into independently deployable components. Tier-one banks in London and New York are piloting these architectures to swap individual modules without platform-wide downtime. This decomposition is modularizing vendor competitive dynamics, allowing specialized NLP providers to displace incumbent suite offerings in specific functional layers.
The EU AI Act's risk-based classification system mandates automated documentation for high-risk algorithmic systems across credit scoring and insurance pricing. Industrial consequence includes mandatory conformity assessments that software vendors must pre-validate before deployment. Healthcare AI developers in Germany and the Netherlands are responding by integrating audit-trail modules earlier in product development cycles to avoid retrofit costs.
Buyers are compressing vendor evaluation cycles from twelve-month RFP processes to ninety-day pilot-to-production timelines. Procurement teams at US regional banks now prioritize platforms with pre-built connectors to existing GRC suites over best-of-breed functionality. This acceleration is most visible in the United Kingdom, where post-Brexit regulatory divergence has intensified pressure for rapid compliance adaptation.
Regulatory Change Management Software Market Segmentation
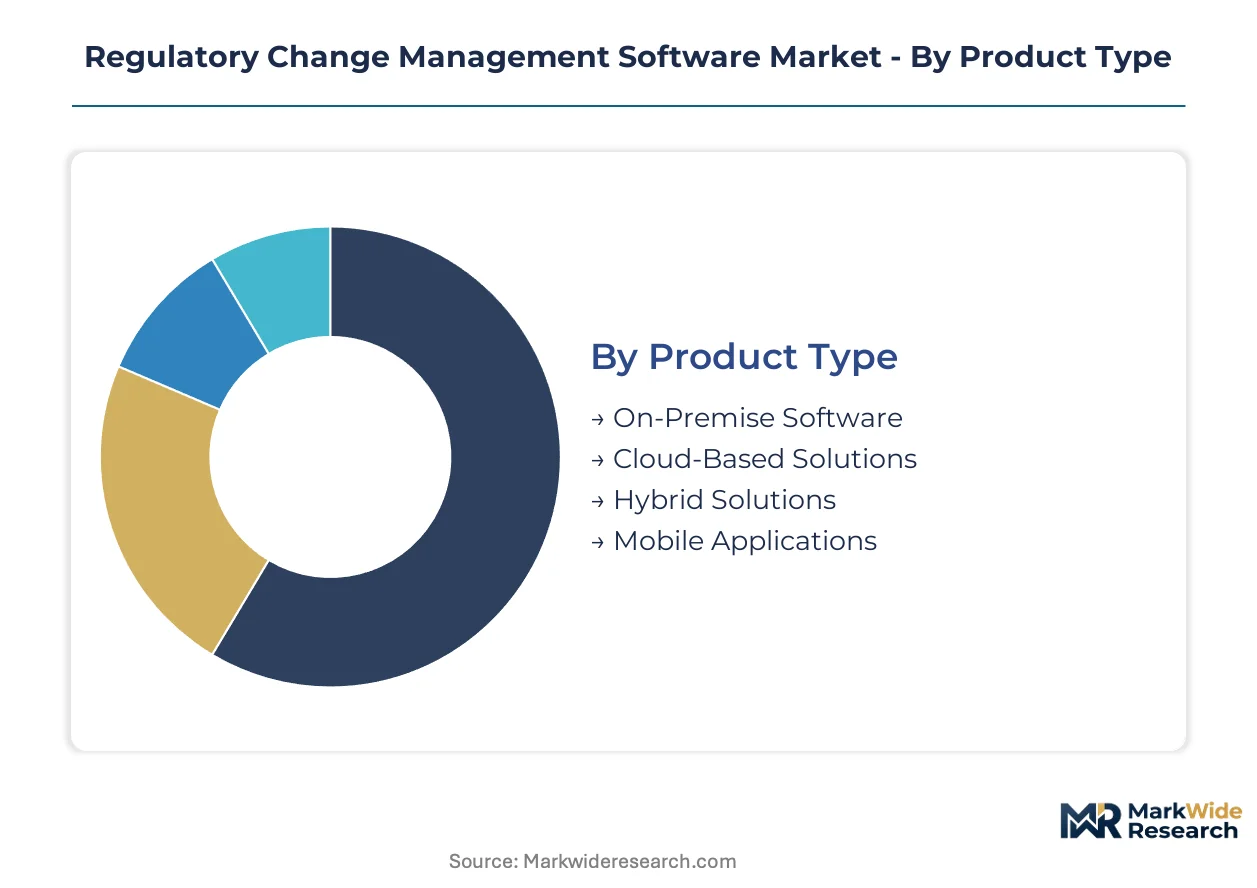
Segmentation in regulatory change management software reveals how procurement patterns diverge across infrastructure maturity, compliance burden intensity, and data sovereignty requirements. Buyers select architectures based on audit frequency, cross-border operational complexity, and integration depth with existing GRC ecosystems.
Product Type:
Upgrade cycles in this category compress when regulatory deadlines force infrastructure decisions before contract renewals mature.
- On-Premise Software:Deployed within client data centers with full hardware control and air-gapped security boundaries. Energy companies in Germany and telecommunications operators in segmented jurisdictions favor this architecture where national data residency laws override cloud convenience.
- Cloud-Based Solutions:Delivered through elastic SaaS architectures that scale compute resources during quarterly reporting peaks. Financial institutions in the United Kingdom and the United States concentrate procurement here, driven by SEC climate disclosure timelines and post-Brexit regulatory divergence pressures.
- Hybrid Solutions:Split workloads between private infrastructure and public cloud orchestration layers. Healthcare providers with HIPAA-validated core systems use this model to isolate patient data while leveraging cloud analytics for regulatory intelligence.
- Mobile Applications:Native and responsive-web interfaces for field compliance officers and audit teams. Banking supervisors in France deploy these for real-time algorithmic audit trail verification under EU AI Act mandates.
Cloud-Based Solutions sits at the top of the volume ranking, with Hybrid Solutions climbing the fastest.
End User:
Cost tier separation in this category tracks with regulatory penalty exposure and compliance staff headcount ratios.
- Financial Institutions:Tier-one banks and insurance carriers with dedicated regulatory affairs departments. Institutions in Germany and France face mandatory EU AI Act algorithmic documentation requirements that accelerate procurement of automated impact-assessment engines.
- Healthcare Providers:Hospital systems, pharmaceutical manufacturers, and clinical research organizations. FDA 21 CFR Part 11 and HIPAA mandates in the United States create demand for validated systems with electronic signature integrity and continuous documentation trails.
- Energy Companies:Utilities and oil-and-gas operators with environmental and safety compliance obligations. Segmented data-sovereignty requirements in multiple jurisdictions drive hybrid deployment preferences over pure cloud alternatives.
- Telecommunications:Mobile network operators and internet service providers with spectrum licensing and consumer privacy duties. Operators in the United Kingdom navigate post-Brexit divergence from EU GDPR enforcement precedents.
Financial Institutions commands the largest absolute spend, while Healthcare Providers gains share fastest as FDA and EMA validation requirements tighten.
Technology:
Application intensity in this category separates vendors with proprietary NLP pipelines from those reselling third-party AI services.
- Artificial Intelligence:Natural-language processing engines that parse regulatory texts and generate impact assessments. Banks in London pilot these systems to compress legal review cycles from weeks to hours during peak filing periods.
- Blockchain:Immutable ledger architectures for audit trail verification and cross-party attestation. Healthcare consortia in the Netherlands explore this for multi-institutional clinical trial documentation under EMA transparency mandates.
- Data Analytics:Business intelligence dashboards aggregating compliance metrics across jurisdictions. Energy companies use these to track environmental permit status across fragmented state and federal requirements.
- Machine Learning:Predictive models forecasting regulatory change probability and operational disruption scores. Insurance pricing teams in France deploy these for EU AI Act risk classification automation.
Artificial Intelligence leads current deployment volumes, with Machine Learning showing the steepest expansion trajectory as risk-prediction use cases mature.
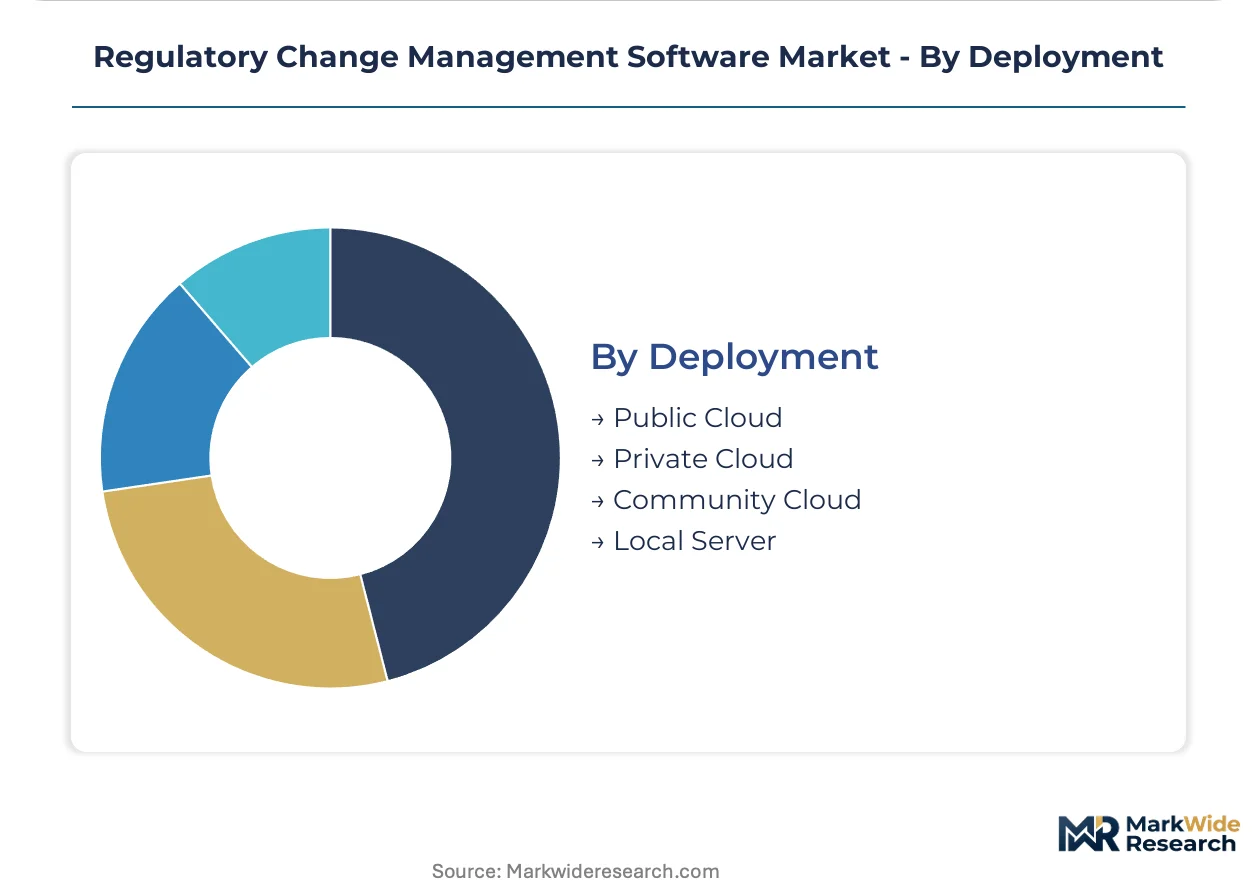
Deployment:
Customer type concentration in this category maps to IT governance maturity and third-party risk tolerance thresholds.
- Public Cloud:Shared infrastructure with multi-tenant isolation and rapid provisioning. Regional banks in the United States favor this model for SEC climate disclosure dashboard deployment without capital expenditure approval cycles.
- Private Cloud:Dedicated single-tenant environments with customized security controls. Healthcare providers in Germany select this architecture for GDPR Article 32 technical and organizational measures compliance.
- Community Cloud:Collaborative infrastructure shared among industry peers with common compliance frameworks. Banking associations in the United Kingdom operate these for collective regulatory intelligence distribution.
- Local Server:Physical hardware installations with no external network dependency. Critical infrastructure operators in segmented jurisdictions mandate this for operational technology isolation requirements.
Public Cloud dominates new contract signings, with Private Cloud expanding most quickly among mid-market buyers seeking GDPR and HIPAA alignment without full on-premise burden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands deeper enterprise penetration than France, though both face identical EU AI Act deadlines. Procurement velocity in the United Kingdom exceeds continental Europe as post-Brexit divergence multiplies compliance workload.
United States
Regional banks and asset managers drive procurement as SEC climate disclosure rules mandate auditable sustainability reporting trails. HIPAA and FDA 21 CFR Part 11 requirements push healthcare providers toward validated systems with electronic signature integrity. Financial services clusters in New York and Chicago concentrate pilot-to-production deployments for automated impact-assessment engines.
Germany
Industrial conglomerates and automotive suppliers prioritize algorithmic audit documentation under EU AI Act risk-based classifications. The national data regulator enforces GDPR Article 32 technical measures that sustain hybrid deployment preferences. Frankfurt's banking quarter anchors enterprise platform consolidation for cross-border compliance dashboards spanning EU member state variations.
United Kingdom
Post-Brexit regulatory divergence from EU enforcement precedents intensifies procurement pressure for rapid adaptation capabilities. Financial conduct authority mandates compress vendor evaluation cycles from twelve-month RFP processes to ninety-day timelines. London's fintech corridor pilots microservices architectures that separate rule ingestion from workflow orchestration.
France
Insurance pricing teams and credit scoring operations deploy automated risk classification systems to satisfy high-risk algorithmic documentation requirements. The national data protection authority coordinates with EU AI Act implementation timelines. Parisian banking supervisors utilize mobile interfaces for real-time audit trail verification during field examinations.
Netherlands
Healthcare consortia and clinical research organizations explore multi-institutional documentation systems under EMA transparency mandates. GDPR cross-border data rules require unified compliance dashboards for multinational pharmaceutical operations. Amsterdam's health technology cluster integrates audit-trail modules earlier in product development cycles to avoid retrofit costs.
Regulatory Change Management Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with enterprise GRC heritage providers anchoring banking deployments while integrated ethics platforms capture adjacent compliance workflows. The vendor base concentrates around three strategic archetypes: rule-engine purists with configurable NLP pipelines, suite vendors embedding regulatory feeds into broader risk management platforms, and API-first specialists distributing through ERP marketplaces. Dominant competitive moves include vertical integration into regulatory intelligence data feeds and geographic expansion through localized compliance content partnerships.
Within the enterprise heritage tier, MetricStream and RSA Archer exemplify GRC-anchored positioning that extends beyond pure regulatory tracking into operational risk and audit management. NAVEX Global occupies a distinct position through integrated ethics and compliance modules that merge policy management with incident reporting. Among specialized rule-engine providers, Regology and LogicManager represent the API-first distribution archetype, embedding compliance capabilities directly into customer workflow engines rather than requiring standalone platform adoption.
| Leading Market Players |
|---|
| Centraleyes |
| Diligent |
| MetricStream |
| Regology |
| LogicManager |
| NAVEX Global |
| RSA Archer |
| Mitratech |
| Enablon |
| Others |
Value Network & Pricing Analysis
Legal-technical hybrid talent costs cascade through implementation pricing tiers, with NLP engineering expertise in Germany and the United Kingdom commanding premium compensation that inflates mid-market deployment quotes. Cloud infrastructure elasticity at the compute layer allows SaaS vendors to absorb volume spikes without passing hardware costs downstream, compressing price floors for financial services buyers in competitive procurement cycles.
Pricing Analysis
Capacity additions in Ireland and the Netherlands are reshaping price floors for EU-hosted cloud deployments as hyperscaler regions expand. Three-tier pricing structure across premium, standard, and economy levels separates enterprise GRC-integrated suites from API-first modules and basic compliance dashboards. Price differentiation hinges on pre-built connector availability to legacy banking cores and validated system certification for HIPAA and FDA 21 CFR Part 11 environments. Pricing pressure stems from procurement teams at US regional banks prioritizing rapid pilot-to-production timelines over feature depth. Mid-market healthcare providers exhibit highest price sensitivity due to constrained IT budgets, while tier-one banks in London show lowest sensitivity given regulatory penalty exposure.
Supply Chain Analysis
Reverse-logistics flows for regulatory intelligence data involve continuous retraining of NLP models against evolving mandate libraries, with deprecated rule versions archived for audit trail reconstruction. Software development concentrates in the United States, Germany, and India, with regulatory content partnerships anchored in Brussels and Washington DC. Raw material dependencies include cloud compute credits, proprietary legal corpus licenses, and compliance framework certifications. Single-source vulnerability manifests in concentrated regulatory feed providers covering EU AI Act and SEC disclosure rule updates. Distribution runs through direct enterprise sales, ERP marketplace integrations, and banking association community cloud arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory Change Management Software functions as a stable compounder anchored by mandatory compliance deadlines that institutionalize recurring procurement regardless of economic cycles.
For Market Incumbents: Deepen regulatory intelligence feed partnerships in Brussels and Washington DC to lock out API-first challengers attempting modular displacement. Anchor enterprise deployments through validated system pre-certification for FDA and HIPAA environments, creating switching costs that extend contract renewals. Defensive consolidation moves should prioritize acquiring specialized NLP providers in London and New York before they capture functional layers within tier-one bank microservices architectures. For New Entrants and Emerging Players: Launch via embedded compliance modules within Salesforce and ServiceNow marketplaces to bypass twelve-month RFP barriers facing standalone platforms. White-space targets include mid-market healthcare providers in the Netherlands and Germany seeking HIPAA-GDPR alignment without full on-premise burden, plus US regional banks with compressed ninety-day procurement timelines. Go-to-market angle should emphasize pre-built connectors to existing GRC suites over best-of-breed functionality claims. For Investors and Strategic Acquirers: Consolidation pressure builds where specialized NLP providers capture algorithmic audit documentation layers within tier-one bank deployments, threatening incumbent suite pricing power. Long-term viability favors vendors with captive regulatory content partnerships and validated system credentials spanning multiple jurisdictions. Acquisition target archetype: API-first platforms with healthcare pre-certification and embedded distribution through ERP marketplaces. Signal to watch: procurement cycle compression at US regional banks accelerating from twelve-month RFP processes to ninety-day pilot timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Intelligence Partnership | Secures exclusive EU AI Act mandate feeds from Brussels-based content aggregators before competitors. |
| Microservices Architecture Deployment | Enables London banks to swap rule-ingestion modules without platform-wide downtime during peak cycles. |
| Pre-Validated System Certification | Accelerates healthcare provider sales by eliminating FDA 21 CFR Part 11 retrofit documentation burdens. |
| ERP Marketplace Integration | Reduces customer acquisition costs through Salesforce and ServiceNow distribution channel presence. |
| Healthcare Audit-Trail Module | Captures Netherlands clinical research demand under EMA transparency mandate implementation timelines. |
Research Methodology
Coverage spans the United States, Germany, the United Kingdom, France, and the Netherlands, with primary inputs from each jurisdiction weighted by procurement volume. Primary interviews combined regulatory affairs directors at tier-one banks, compliance officers at pharmaceutical manufacturers, and IT procurement leads at energy utilities with secondary validation against SEC filings, EMA transparency registers, and EU AI Act implementation guidance. Secondary sources included GDPR enforcement action databases, FDA 21 CFR Part 11 inspection records, and banking association procurement surveys. Bottom-up deployment counts triangulated against top-down enterprise software spend estimates across financial services, healthcare, and energy verticals.
Rate-of-change decomposition separated baseline compliance automation growth from acceleration effects of EU AI Act enforcement timelines and SEC climate disclosure rule implementation. Segmentation dimensions modeled deployment architecture, end-user industry, technology integration depth, and regional regulatory cluster intensity. CAGRs derived from regression against historical procurement velocity during prior regulatory deadline compression periods, with elasticity adjustments for cloud infrastructure scaling efficiency. Industry-specific inputs included algorithmic audit documentation requirement penetration curves and validated system certification backlog durations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU AI Act enforcement or delayed SEC disclosure rule litigation. Forecasts reflect assumptions about regulatory deadline adherence, NLP talent availability, and legacy banking system API accessibility that could shift materially. Practitioners should monitor EU AI Act conformity assessment pre-validation timelines and US regional bank procurement cycle compression rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regulatory Compliance Technology
Global AML Software Market
Regulatory Compliance Technology
Regulatory Reporting Solutions Market
Regulatory Compliance Technology
Compliance and Traceability Solutions Market
Regulatory Compliance Technology
Global Quality and Compliance Management Solution Market
Regulatory Compliance Technology
Aviation Compliance Monitoring Software Market
Regulatory Compliance Technology
Global GDPR Services Market
Regulatory Compliance Technology
GDPR Assessment Tools Market
Regulatory Compliance Technology
Regtech Software Market
Regulatory Compliance Technology
Anti-Money Laundering Systems Market
Regulatory Compliance Technology
Regulatory Information Management System Market
Regulatory Compliance Technology
General Data Protection Regulation (GDPR) Market
Regulatory Compliance Technology
Compliance Testing Solutions Market
Regulatory Compliance Technology
Nordic Regulatory Affairs Market
Regulatory Compliance Technology
Management System Certification Market
Regulatory Compliance Technology
US Anti Money Laundering Solution Market
Regulatory Compliance Technology
Global Anti- Money Laundering Solutions Market