
 Europe Video Conferencing Hardware Market | 2026-2036
Europe Video Conferencing Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Video Conferencing Hardware Market Insights
Software-defined camera intelligence is recalibrating what enterprises purchase as a bundled capability rather than discrete hardware. Cisco Systems Inc. leverages its Webex ecosystem to anchor premium room system deployments across European financial services headquarters. Logitech International S.A. competes through modular peripherals that sustain refresh cycles in hybrid workplace environments. Jabra Inc. specializes in audio endpoints that dominate small-huddle room configurations.
Europe video conferencing hardware encompasses dedicated audiovisual equipment engineered for synchronous remote collaboration, typically integrating 4K imaging sensors, beamforming microphone arrays, and hardware codec units with sub-150ms latency for real-time transmission. Cameras and microphones command the largest installed base, while cloud-based installation types are gaining fastest as IT departments reduce on-premises infrastructure overhead. Corporate end users represent the deepest margin pool due to enterprise-scale refresh programs and managed service attach rates.
GDPR and the EU AI Act impose strict data residency and algorithmic transparency requirements on devices processing biometric or voice data, compelling manufacturers to certify local data handling architectures. CE marking and ETSI standards govern electromagnetic compatibility and radio spectrum usage for wireless-enabled endpoints sold across member states. Stakeholders must weigh regulatory certification timelines against product development cycles when prioritizing feature roadmaps for European deployment.
Market Dynamics
Software-defined camera intelligence and the EU AI Act are forcing European enterprises to recertify entire hardware fleets, compressing replacement cycles while elevating data residency compliance to a primary procurement criterion.
Growth Catalysts
- GDPR biometric processing mandates:Financial services headquarters in Frankfurt and London must replace legacy endpoints with certified hardware, accelerating enterprise refresh programs.
- Hybrid workplace normalization:Corporate real estate teams are permanently downsizing central offices while expanding distributed huddle room footprints across regional satellite locations.
- ETSI electromagnetic standards:Updated radio spectrum certification requirements for wireless-enabled endpoints are disqualifying uncertified imports, protecting incumbent European suppliers.
Market Restraints
- Semiconductor supply concentration:Advanced image signal processors and beamforming DSPs source predominantly from East Asian foundries, exposing European manufacturers to geopolitical logistics disruptions.
- EU AI Act algorithmic transparency requirements:Voice and facial recognition hardware must undergo conformity assessment procedures that extend product launch timelines.
- Cloud-native software substitution:Browser-based video collaboration platforms reduce dependency on dedicated hardware codecs for sub-fifty participant deployments.
Strategic Opportunities
- Central European manufacturing expansion:Poland and Czech Republic offer assembly capacity for CE-marked devices serving EU member states without customs friction.
- Healthcare telemedicine endpoints:Hospital systems in France and Germany are procuring specialized cart-mounted systems for remote specialist consultations.
- CSRD supply chain disclosure requirements:Corporate sustainability reporting mandates favor hardware vendors with documented circular economy programs and repairable designs.
Industry Challenges
- Firmware security engineering talent:European manufacturers compete with automotive and aerospace sectors for embedded systems developers capable of implementing secure boot architectures.
- CE marking documentation burden:Technical file compilation for radio equipment directive compliance consumes six to nine months of pre-market preparation.
- Legacy analog audio integration:Enterprise customers maintaining hybrid estates require seamless interoperability between modern USB-C endpoints and existing XLR infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Video Conferencing Hardware Market |
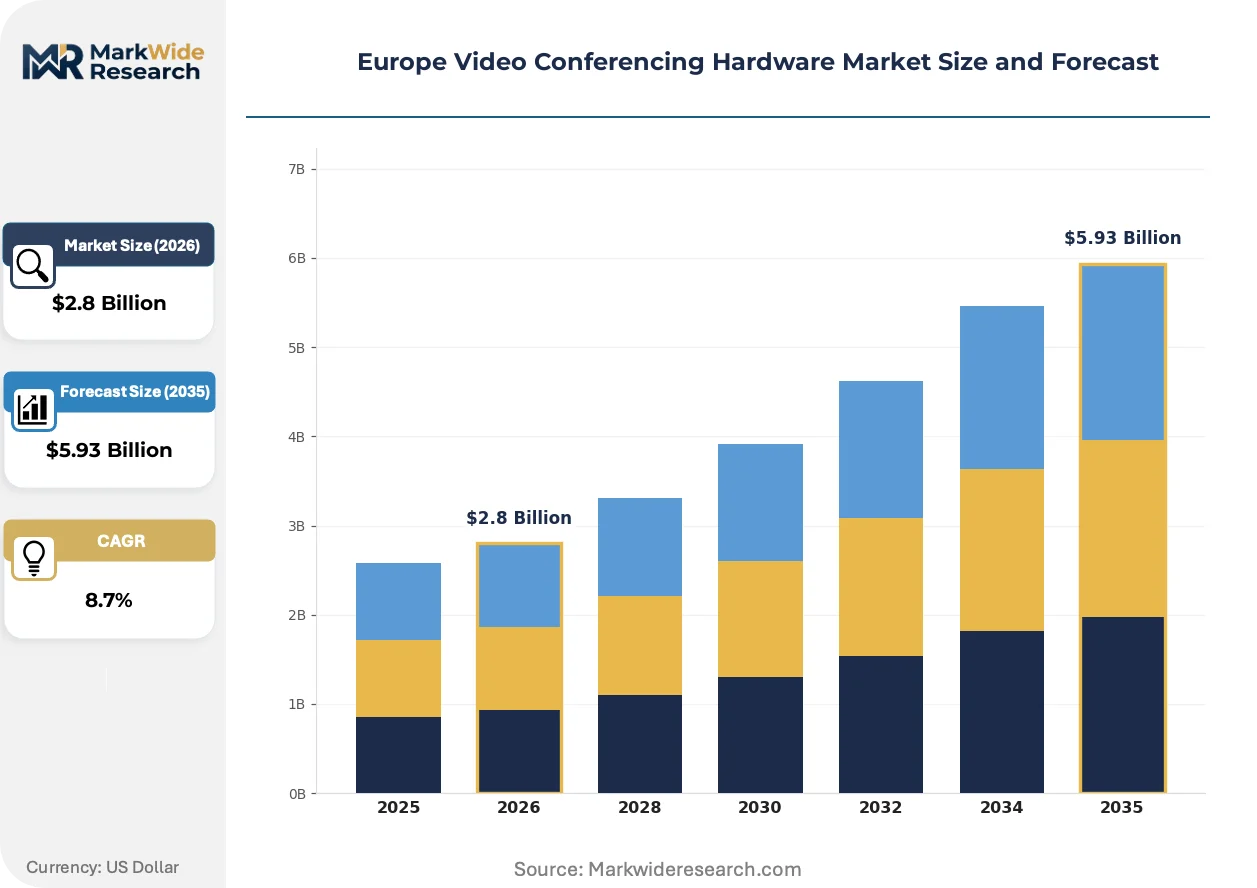
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cameras, Microphones, Speakers, Codec End User: Education, Corporate, Healthcare, Government Installation Type: On-Premises, Cloud-Based, Hybrid, Managed Service Technology: Wi-Fi, Bluetooth, USB, HDMI |
| Companies Covered | Cisco Systems Inc., Logitech International S.A., Jabra Inc., EPOS, Huawei Technologies Co., Ltd., Poly, Hikvision, Sony, Dahua, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Video Conferencing Hardware Market Trends and Innovations
Computational imaging and edge AI are redrawing the boundary between hardware and software value capture, while regulatory pressure on biometric data processing is accelerating architectural shifts in how European organizations deploy collaboration infrastructure.
Intelligent framing algorithms using on-device neural processing are converging with 4K sensor modules to eliminate the need for dedicated camera operator roles in executive boardrooms. Large German automotive manufacturers are standardizing these capabilities across their headquarters and engineering centers. This convergence is compressing the addressable market for standalone camera control systems while expanding attach rates for all-in-one room appliances.
The EU AI Act's risk-based classification system for biometric identification systems is forcing hardware manufacturers to implement technical documentation trails for training data provenance and model performance metrics. Devices deployed in high-risk settings such as government facilities must undergo third-party conformity assessment before market placement. French public sector procurement frameworks now explicitly exclude uncertified endpoints from tender eligibility.
Corporate IT departments are unbundling hardware acquisition from managed service contracts, preferring separate sourcing of endpoints and cloud platform subscriptions. Systems integrators in the United Kingdom are responding with à-la-carte deployment and support offerings that decouple initial capital expenditure from ongoing operational spend. This pattern is most pronounced among mid-market enterprises in the Netherlands and Belgium seeking procurement flexibility.
Europe Video Conferencing Hardware Market Segmentation
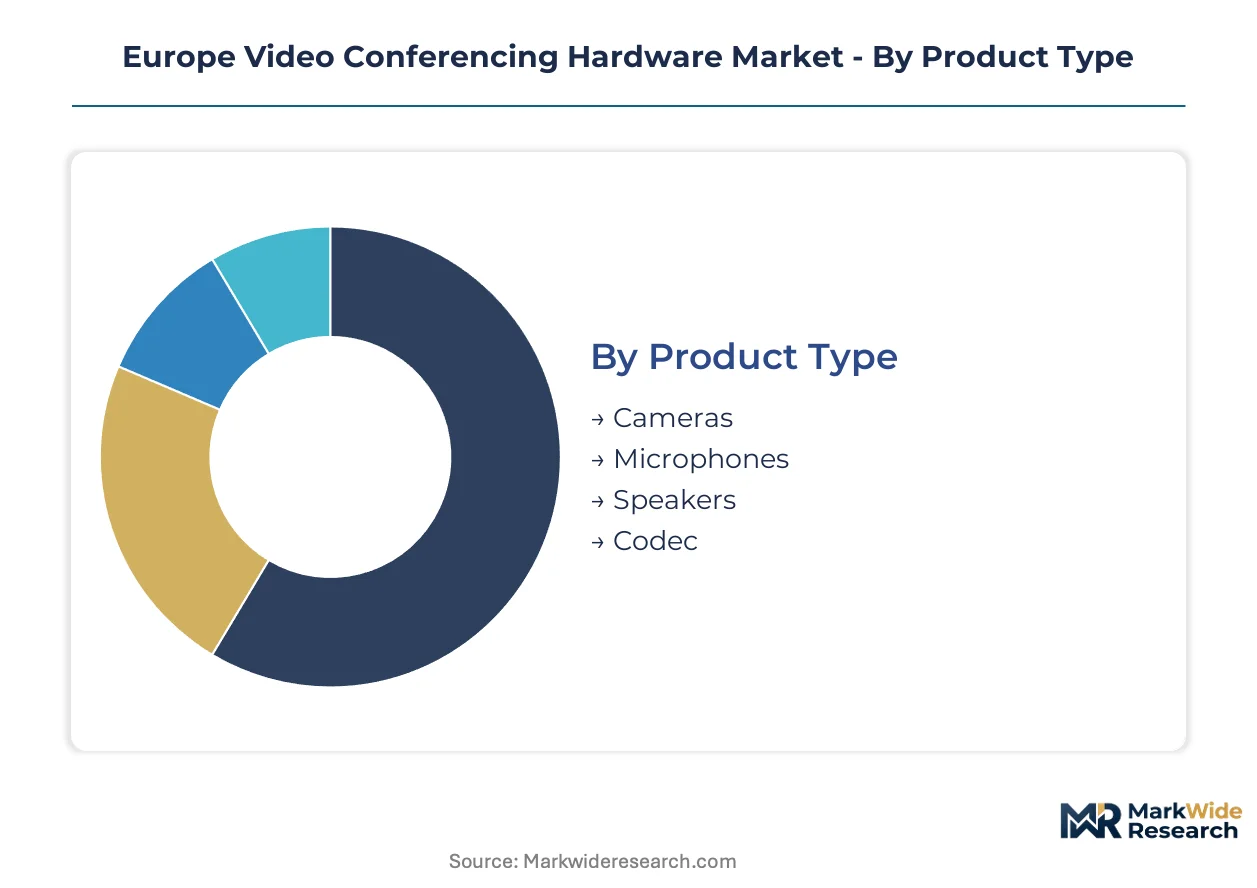
European procurement teams segment hardware investments by compliance architecture, deployment flexibility, and integration burden. Each segmentation axis carries distinct certification requirements under GDPR and the EU AI Act that reshape vendor selection criteria.
Product Type:
Standardization dominates cameras and microphones, while codec units demand extensive customization for enterprise security stacks.
- Cameras:4K imaging sensors with intelligent framing algorithms process biometric data locally to satisfy GDPR residency mandates. German automotive manufacturers and French banking headquarters anchor demand for certified devices with on-device neural processing. CE marking and EU AI Act conformity assessments extend procurement cycles for high-risk deployments.
- Microphones:Beamforming arrays with integrated DSPs capture directional audio in open-plan huddle rooms. United Kingdom financial services firms and Netherlands professional services clusters drive refresh programs as hybrid workplace configurations stabilize. GDPR voice data processing restrictions favor hardware with edge-based transcription rather than cloud relay.
- Speakers:Full-range audio endpoints with acoustic echo cancellation support small-to-medium room footprints.
- Codec:Hardware encoding units with sub-150ms latency enable real-time transmission for executive boardroom installations.
Most installed capacity flows through Cameras. Expansion is steepest in Microphones.
End User:
Corporate deployments concentrate procurement volume, while healthcare and government segments impose the steepest certification barriers.
- Corporate:Enterprise-scale refresh programs across banking, automotive, and professional services sectors sustain the deepest margin pool. Managed service attach rates and multi-year support contracts differentiate vendor relationships. United Kingdom and Germany concentrate headquarters-level deployments requiring high-availability redundancy.
- Healthcare:Telemedicine endpoints with cart-mounted mobility serve remote specialist consultations in French and German hospital systems. Patient data protection under GDPR and national health data laws mandates closed-network architectures with local storage.
- Education:Universities and vocational institutes across Spain and Italy deploy lecture-capture systems for hybrid learning models.
- Government:Public sector procurement frameworks in France exclude uncertified endpoints from tender eligibility under EU AI Act high-risk system classifications.
Corporate accounts absorb the majority of installed units. Healthcare represents the most tightly regulated expansion corridor.
Installation Type:
Cloud-based configurations reduce capital intensity, while hybrid architectures preserve legacy infrastructure investments.
- Cloud-Based:Browser-accessible deployments eliminate on-premises server maintenance and accelerate regional satellite office rollouts. IT departments in Belgium and Netherlands mid-market enterprises favor subscription models that separate endpoint acquisition from platform licensing.
- On-Premises:Dedicated hardware codecs and local control servers satisfy data residency requirements for defense contractors and classified government facilities. Air-gapped installations in Germany require ETSI-certified electromagnetic compatibility for secure campus environments.
- Hybrid:Mixed estates bridge legacy XLR audio infrastructure with modern USB-C endpoints in enterprises maintaining phased migration timelines.
- Managed Service:Systems integrators in the United Kingdom bundle deployment, monitoring, and refresh logistics for organizations without dedicated AV engineering staff.
On-Premises retains the largest legacy footprint. Cloud-Based configurations are climbing the fastest.
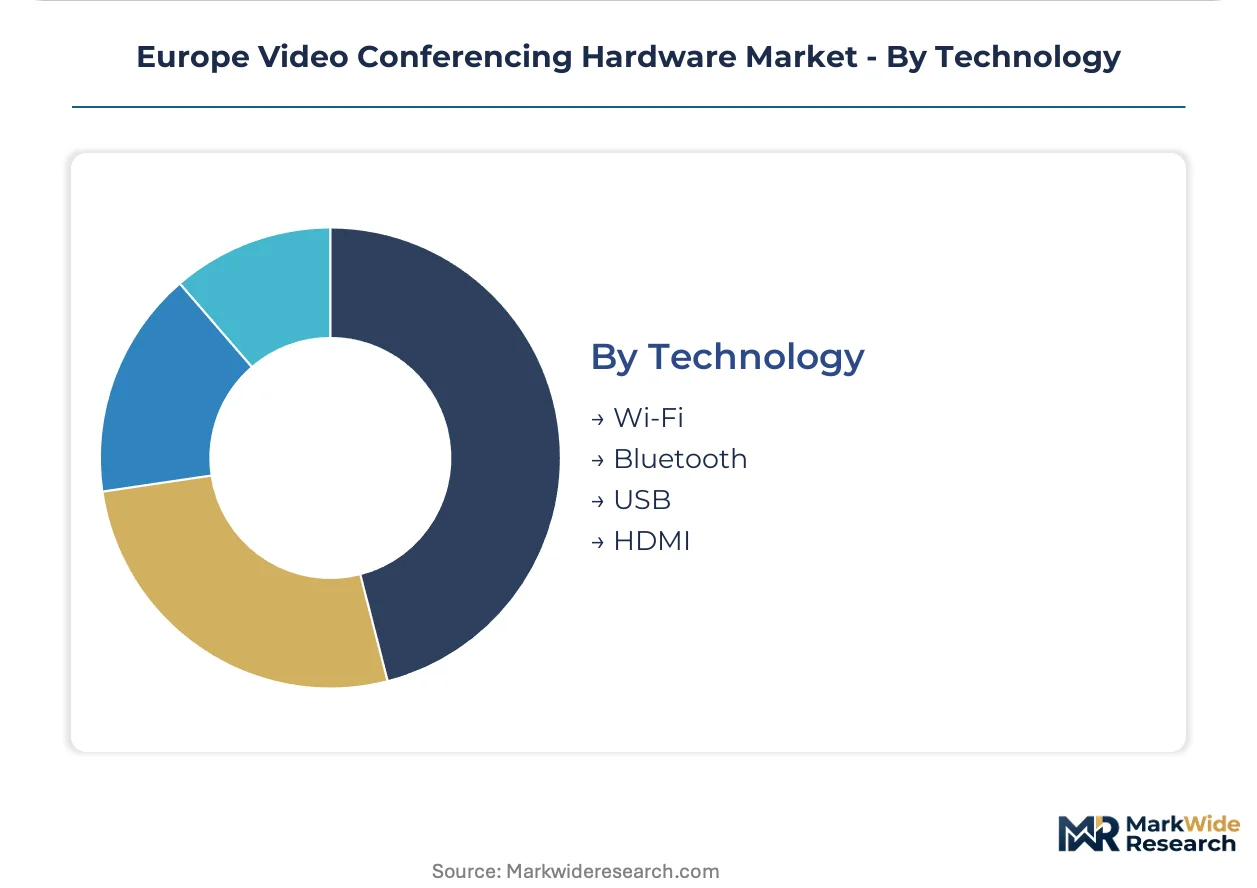
Technology:
Wired connectivity dominates security-sensitive deployments, while wireless protocols expand flexibility in retrofit environments.
- USB:Universal plug-and-play interfaces dominate huddle room peripherals with standardized driver support across operating systems. Logitech and Jabra compete through modular USB ecosystems that sustain refresh cycles without full system replacement.
- HDMI:Direct video transmission without compression artifacts serves executive boardrooms requiring broadcast-quality output. Large room systems in Frankfurt and London financial headquarters standardize on HDMI 2.1 for 4K60 signal integrity.
- Wi-Fi:Wireless video distribution reduces cable infrastructure in historic buildings and temporary meeting spaces.
- Bluetooth:Personal audio pairing supports executive mobile devices and ad-hoc collaboration in open office zones.
USB carries the broadest installed base. HDMI maintains premium positioning in high-stakes environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany outpaces France in enterprise endpoint deployment volume, yet French public sector procurement imposes stricter certification barriers under the EU AI Act.
Germany
Automotive headquarters in Stuttgart and Munich drive demand for intelligent framing cameras with on-device neural processing. The Federal Office for Information Security (BSI) mandates security-by-design certifications for government-adjacent deployments. Frankfurt's financial services corridor anchors the largest concentration of executive boardroom installations requiring sub-150ms latency hardware codecs.
United Kingdom
London's banking sector sustains multi-year refresh programs for beamforming microphone arrays in trading floor environments. The UK Information Commissioner's Office enforces GDPR voice data processing restrictions that favor edge-based transcription hardware. Systems integrators in the City of London bundle à-la-carte deployment services that decouple capital expenditure from cloud platform subscriptions.
France
Parisian hospital systems procure cart-mounted telemedicine endpoints for remote specialist consultations. The Commission nationale de l'informatique et des libertés (CNIL) excludes uncertified biometric devices from public sector tender eligibility. The Île-de-France region concentrates demand for high-risk system deployments undergoing third-party conformity assessment.
Netherlands
Mid-market enterprises in Amsterdam and Rotterdam favor subscription-based procurement models separating endpoint acquisition from platform licensing. The Dutch Data Protection Authority enforces strict data residency requirements for cross-border video traffic. Eindhoven's technology corridor hosts assembly operations for CE-marked peripherals serving Benelux markets without customs friction.
Poland
Shared service centers in Warsaw and Kraków expand distributed huddle room footprints to support nearshored corporate functions. Polish manufacturing zones offer assembly capacity for devices meeting ETSI electromagnetic compatibility standards. The Mazowieckie Voivodeship anchors Central European logistics hubs supplying certified hardware across EU member states.
Europe Video Conferencing Hardware Market Competitive Landscape
Top-tier vendors anchor premium room system deployments, while modular peripheral specialists capture refresh cycle volume in hybrid workplace environments. The market structure concentrates around ecosystem-integrated platforms and component-focused suppliers. Three archetypes dominate: full-stack collaboration platforms, audio-centric endpoint specialists, and imaging sensor module suppliers. Competitive moves center on managed service attach rates and supply chain regionalization into Central European assembly zones.
Within the ecosystem-integrated tier, Cisco Systems Inc. and Logitech International S.A. occupy positions that exemplify divergent approaches to enterprise procurement—platform bundling versus modular refreshability. Jabra Inc. anchors the audio-specialist archetype with a focus on small-huddle room configurations. These three entities represent the competitive vectors shaping vendor selection criteria across European corporate, healthcare, and public sector deployments.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Logitech International S.A. |
| Jabra Inc. |
| EPOS |
| Huawei Technologies Co., Ltd. |
| Poly |
| Hikvision |
| Sony |
| Dahua |
| Others |
Pricing and Supply Chain Analysis
Advanced image signal processors sourced from East Asian foundries cascade through three pricing tiers as they reach European enterprise buyers, with CE marking and EU AI Act certification costs amplifying spreads between certified and uncertified endpoints.
Pricing Analysis
Capacity additions in Poland and Czech Republic assembly zones are reshaping price floors for mid-tier peripherals serving Benelux and German mid-market enterprises. Three-tier pricing structure across premium, standard, and economy levels segments on certification grade and managed service attach rates. Cost compression in economy tiers is intensifying because browser-based software substitutes reduce dependency on dedicated hardware codecs. Corporate headquarters in Frankfurt and London show least price sensitivity, while Netherlands and Belgium mid-market buyers prioritize procurement flexibility over performance specifications.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from automotive headquarters and financial services corridors, while systems integrators serve fragmented mid-market deployments. Semiconductor fabrication concentrates in Taiwan, South Korea, and China, with European manufacturers drawing from East Asian foundries for beamforming DSPs and neural processing units. Single-source vulnerability in advanced imaging sensors exposes assembly operations to geopolitical logistics disruptions. Distribution runs through regional logistics hubs in Mazowieckie Voivodeship and Eindhoven technology corridor for CE-marked devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe video conferencing hardware market functions as a stable compounder, with regulatory recertification cycles under GDPR and the EU AI Act sustaining predictable replacement demand across enterprise installed bases.
For Market Incumbents: Anchor premium positioning through security-by-design certifications from Germany's BSI and France's CNIL, defending against cloud-native software substitution by embedding intelligent framing algorithms with on-device neural processing. Prioritize backward integration into Polish and Czech assembly capacity to eliminate customs friction for EU member state deployments.
For New Entrants and Emerging Players: The price-point gap between Cisco-led premium ecosystems and economy-tier USB peripherals creates entry space for certified mid-market specialists. Target healthcare telemedicine endpoints in French and German hospital systems, where GDPR patient data protection mandates favor closed-network architectures with local storage. Pursue cart-mounted system partnerships with regional medical equipment distributors.
For Investors and Strategic Acquirers: Consolidation pressure builds where firmware security engineering talent scarcity fragments development capabilities across automotive, aerospace, and collaboration hardware sectors. Five-to-ten-year viability favors vendors with documented circular economy programs satisfying CSRD supply chain disclosure requirements. Monitor CE marking timeline compression as signal for regulatory capability differentiation.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Certification | Third-party assessment unlocks French public sector tender eligibility under high-risk system classifications. |
| Central European Manufacturing Expansion | Polish and Czech assembly capacity eliminates customs friction for CE-marked devices across member states. |
| Managed Service Decoupling | Systems integrators in United Kingdom bundle à-la-carte deployment separating capital expenditure from cloud subscriptions. |
| Healthcare Telemedicine Endpoint Development | Cart-mounted systems serve remote specialist consultations in French and German hospital networks. |
| Edge-Based Biometric Processing | On-device neural processing satisfies GDPR data residency mandates without cloud relay exposure. |
Research Methodology
Coverage spans Germany, United Kingdom, France, Netherlands, and Poland, with primary inputs from each market gathered through structured interviews with AV systems integrators, corporate IT procurement officers, hospital biomedical engineers, and regulatory compliance leads at hardware manufacturers. Secondary validation draws from CE marking documentation databases, ETSI electromagnetic compatibility filings, EU AI Act conformity assessment registries, and corporate sustainability reporting disclosures. Bottom-up unit demand estimates triangulate against top-down market sizing from component supplier shipment data.
Granularity-level modeling extends to product type, end user segment, installation architecture, and connectivity technology, with cross-tabulation against country-level regulatory cluster and enterprise size band. CAGRs derive from installed base refresh cycle analysis, replacement rate assumptions, and new deployment penetration across the projection horizon. Industry-specific inputs include GDPR enforcement variance by national data protection authority and EU AI Act implementation timelines by member state.
Caveats apply where semiconductor supply disruptions, algorithmic transparency assessment delays, or cloud-native platform substitution acceleration could materially shift the outlook. Forecasts reflect documented assumptions regarding hybrid workplace stabilization, regulatory certification timeline consistency, and enterprise IT budget allocation patterns. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Mobile Hotspot Router Market
Network Technology
Malaysia Wireless Router Market
Network Technology
Session Border Controller (SBC) Market
Network Technology
DHCP and IP Address Management Market
Network Technology
Global LWAN Market
Network Technology
Network Telemetry Market
Network Technology
Asia Pacific Structured Cabling Market
Network Technology
Global Home Networking Device Market
Network Technology
UK B2B Fixed Connectivity Market
Network Technology
Global Carrier Wi-Fi Equipment Market
Network Technology
Global Network Monitoring Market
Network Technology
GCC Set-Top Box Market
Network Technology
WAN Optimization Controllers Market
Network Technology
Global Network Management Market
Network Technology
Network Devices Market
Network Technology
Mobile Backhaul Market