
 Wi-Fi As a Service (Waas) Market | 2026-2036
Wi-Fi As a Service (Waas) Market Size, Share, and Industry Trends Forecast 2026-2036
Wi-Fi As a Service (Waas) Market Analytics
Wi-Fi Alliance certification under the Wi-Fi 6 and Wi-Fi 6E programs is bifurcating the vendor landscape into qualified and non-qualified equipment suppliers. Cisco Systems leverages its enterprise switching heritage to bundle cloud-managed access points with security subscriptions. Juniper Networks anchors its position through Mist AI, using machine learning to automate radio frequency optimization across large campuses. Huawei Technologies competes on manufacturing scale, producing silicon and access point hardware through captive supply chains that lower unit economics for managed service bundles.
Wi-Fi As a Service delivers wireless network infrastructure through subscription-based managed service agreements, typically encompassing access point hardware, cloud controllers, spectrum optimization software, and tiered service level agreements measured by uptime and throughput per user. Managed Wi-Fi and cloud-based deployment models command the largest contract values as enterprises outsource radio frequency engineering and security patch management to specialized operators. Edge computing deployments represent the fastest-growing structural segment, placing local data processing at branch locations to reduce backhaul latency for latency-sensitive applications.
The FCC governs unlicensed spectrum allocation and device certification in the United States, while ETSI harmonizes radio equipment standards across European member states and the Wi-Fi Alliance enforces interoperability testing globally. These frameworks shape demand by determining which frequency bands and power levels equipment vendors may legally deploy, directly influencing hardware refresh cycles and service contract durations. Stakeholders must monitor pending spectrum auctions and emerging Wi-Fi 7 certification timelines to time infrastructure investments against regulatory clarity.
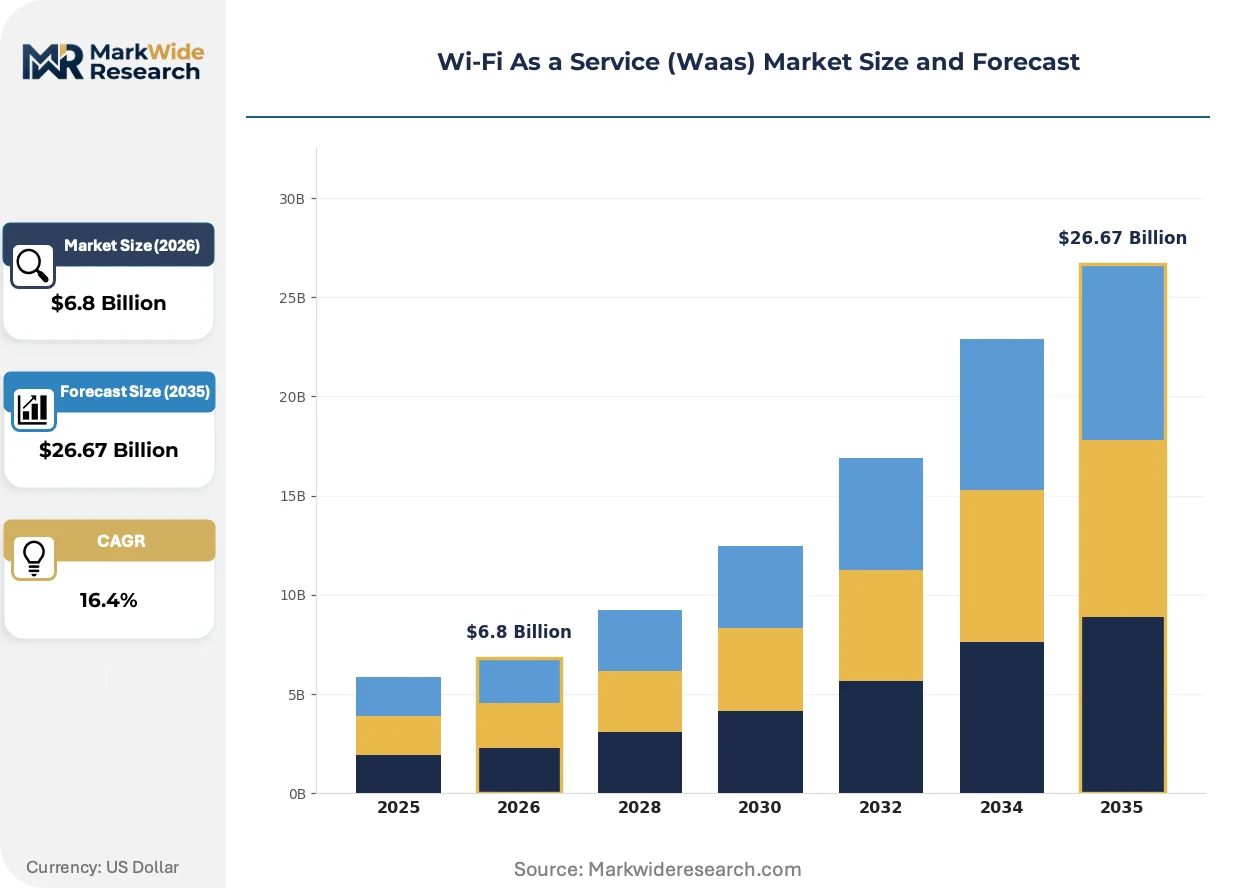
Market Dynamics
Enterprise IT departments are offloading radio frequency engineering to managed service providers as Wi-Fi 6E hardware refresh cycles compress under FCC spectrum reallocation pressure.
Growth Catalysts
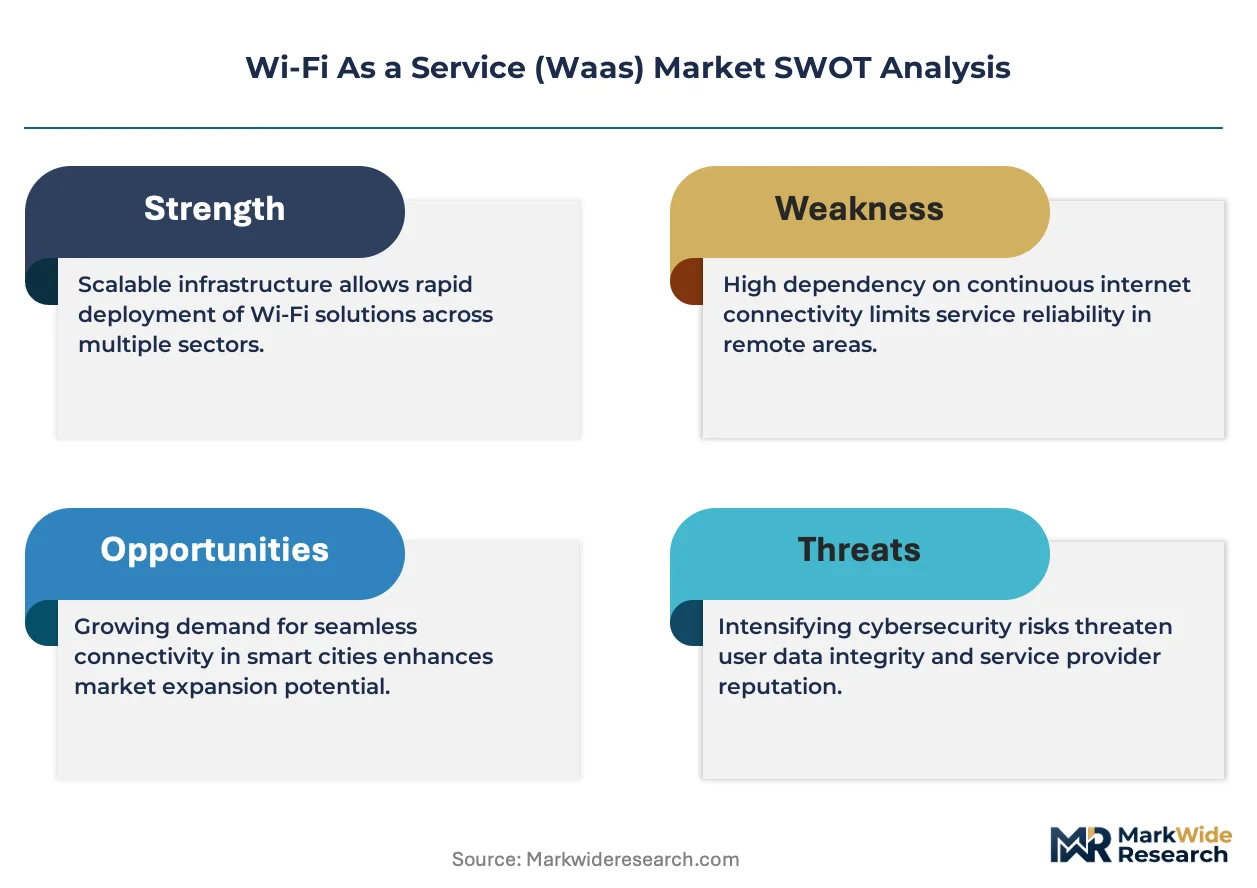
- 6 GHz spectrum liberalization:The FCC's unlicensed 6 GHz allocation in the United States accelerates hardware replacement cycles and expands addressable capacity for dense campus environments.
- Cloud-managed infrastructure maturation:Enterprises in financial services and healthcare are retiring on-premises wireless LAN controllers in favor of subscription-based operational expenditure models.
- Edge computing co-location:Manufacturing and retail branches deploy local compute nodes alongside managed access points to reduce application latency for real-time analytics.
Market Restraints
- Silicon supply concentration:Radio frequency semiconductor fabrication concentrates in Taiwan and South Korea, exposing hardware vendors to geopolitical disruption risk.
- Licensed spectrum competition:Private 5G networks using Citizens Broadband Radio Service in the United States threaten to capture high-value industrial connectivity contracts.
- Certification timeline friction:Wi-Fi Alliance 6E and forthcoming Wi-Fi 7 certification queues delay product launches by six to nine months.
Strategic Opportunities
- Small and medium enterprise underpenetration:Professional services firms and regional healthcare systems in Germany represent untapped demand for turnkey managed Wi-Fi bundles.
- Artificial intelligence integration:Convergence of machine learning-based radio resource management with cloud controllers enables predictive maintenance and automated troubleshooting.
- Operational technology convergence:Industrial IoT sensor networks in Chinese smart factories create demand for unified IT-OT wireless infrastructure under single service contracts.
Industry Challenges
- Radio frequency engineering talent scarcity:Managed service providers struggle to hire certified wireless professionals capable of complex propagation modeling.
- Legacy controller integration complexity:Enterprises maintaining hybrid environments face interoperability failures between new cloud-managed access points and aging on-premises infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wi-Fi As a Service (Waas) Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $26.67 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Public Wi-Fi, Private Wi-Fi, Managed Wi-Fi, Guest Wi-Fi Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Retailers, Enterprises, Hospitality, Educational Institutes Connection Type: Dedicated Line, Broadband, Mesh Network, Satellite |
| Companies Covered | AT&T, Verizon, Cisco Systems, Juniper Networks, Huawei Technologies, Singtel, T-Mobile, Aruba (HPE), CommScope, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wi-Fi As a Service (Waas) Market Evolving Landscape
Artificial intelligence is restructuring how wireless networks self-optimize, shifting value from hardware specifications to predictive software capabilities that preempt performance degradation.
Wi-Fi 6E access points operating across 6 GHz channels is supplanting Wi-Fi 5 hardware in enterprise refresh cycles. Universities and corporate campuses with high-density user populations are prioritizing 6 GHz capacity for video conferencing and virtual reality applications. This transition is compressing service contract durations as buyers anticipate Wi-Fi 7 availability.
The FCC's spectrum reallocation framework for unlicensed 6 GHz use is mandating new power and emission standards for indoor and outdoor deployments. Equipment manufacturers must redesign radio front-ends to comply with automated frequency coordination requirements. United States enterprise buyers are accelerating procurement timelines to secure compliant hardware before certification backlogs extend.
Subscription-based procurement of network infrastructure is displacing capital-intensive hardware ownership among mid-market enterprises. Value-added resellers and systems integrators are capturing recurring revenue streams previously held by distributors. This behavioral shift is most pronounced in United States healthcare and legal services verticals where IT headcount constraints are acute.
Wi-Fi As a Service (Waas) Market Segmentation
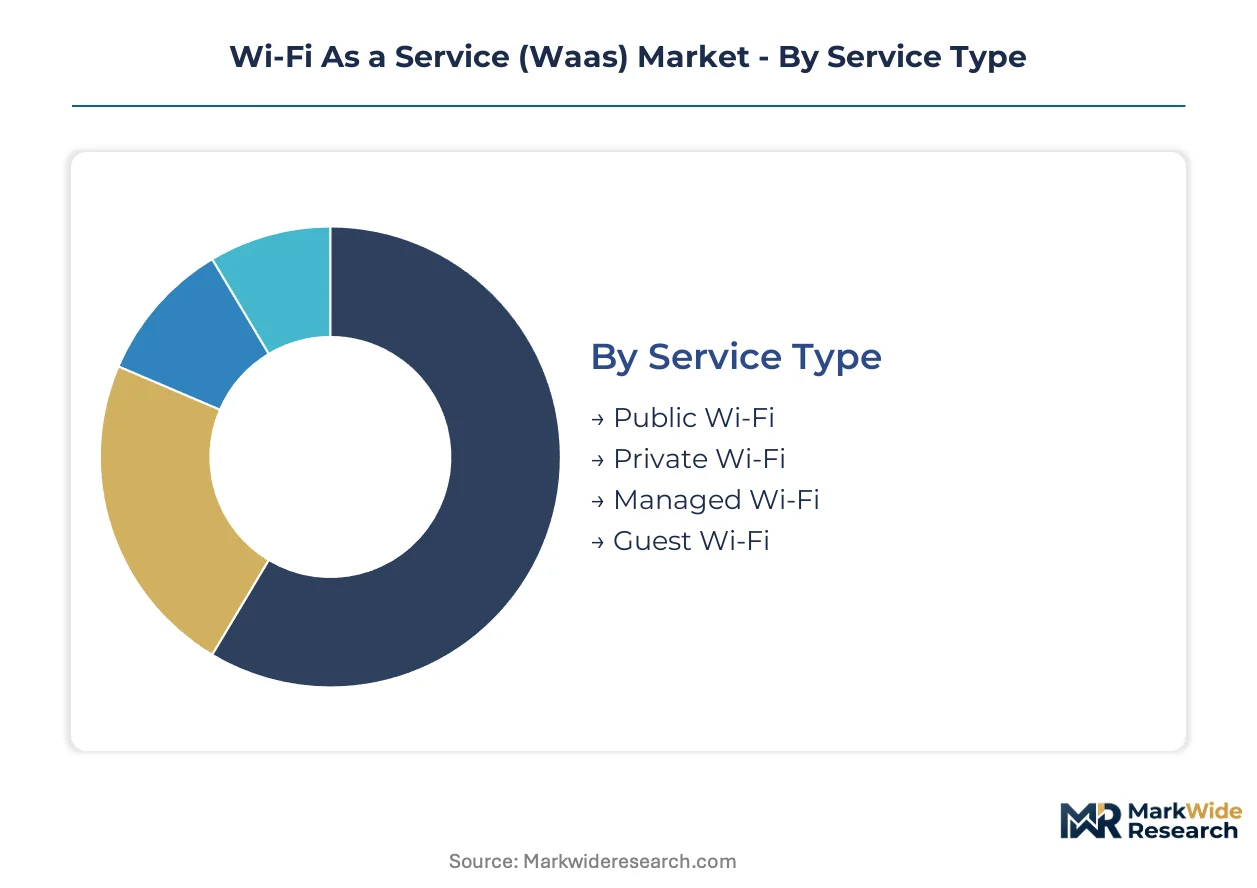
Segmentation in Wi-Fi As a Service reveals how procurement patterns diverge across technical architectures and operational requirements. Service providers configure pricing and SLA tiers around deployment complexity, end-user density, and backhaul reliability rather than hardware specifications alone.
Service Type:
Substitution pressure from private 5G networks and fixed wireless access is reshaping which service types retain pricing power in industrial and campus environments.
- Managed Wi-Fi:Comprehensive subscription bundles encompassing access point hardware, cloud controllers, spectrum optimization, and uptime guarantees. Enterprises in the United States and Germany are consolidating vendor relationships around these full-stack contracts to reduce RF engineering headcount.
- Private Wi-Fi:Dedicated infrastructure deployments with isolated SSIDs and custom security policies for sensitive environments. Financial services firms and healthcare systems in China specify these for compliance with data sovereignty requirements.
- Public Wi-Fi:Open-access networks in transportation hubs and municipal spaces, typically advertising-supported or government-subsidized.
- Guest Wi-Fi:Segmented access layers with captive portals and bandwidth throttling for visitor traffic in hospitality and corporate lobbies.
Managed Wi-Fi anchors the volume base while Private Wi-Fi gains share at the steepest rate.
Deployment Model:
Cost tier stratification separates capital-intensive on-premises ownership from operational expenditure models favored by mid-market buyers with constrained IT budgets.
- Cloud-Based:Controller-less architectures where access points tunnel to regional cloud points of presence. Retailers across the United States are retiring on-premises controllers in favor of subscription models that shift wireless LAN from capex to opex.
- Edge Computing:Local compute nodes co-located with access points to process latency-sensitive applications at branch locations. Manufacturing facilities in Germany deploy these for real-time quality control analytics without backhaul dependency.
- On-Premises:Traditional controller-based deployments with dedicated hardware ownership and internal IT management responsibility.
- Hybrid:Mixed environments bridging legacy on-premises infrastructure with cloud-managed access points during migration phases.
Cloud-Based deployments dominate contract value while Edge Computing expands most quickly among industrial verticals.
End User:
Application-specific requirements drive divergent procurement patterns across verticals with distinct density, security, and uptime demands.
- Enterprises:Large campuses with high-density user populations and multi-building footprints. Corporate headquarters in China specify Wi-Fi 6E hardware refresh cycles to support video conferencing and collaborative applications.
- Educational Institutes:Universities with seasonal enrollment spikes and outdoor coverage requirements. Institutions in the United States prioritize 6 GHz capacity for dormitory streaming and virtual reality lab deployments.
- Retailers:Distributed branch networks requiring consistent SSID policies and POS integration across hundreds of locations.
- Hospitality:Hotels and conference centers with seasonal occupancy variability and guest expectation management challenges.
Enterprises generate the largest absolute contract values while Educational Institutes drive the steepest refresh cycle compression.
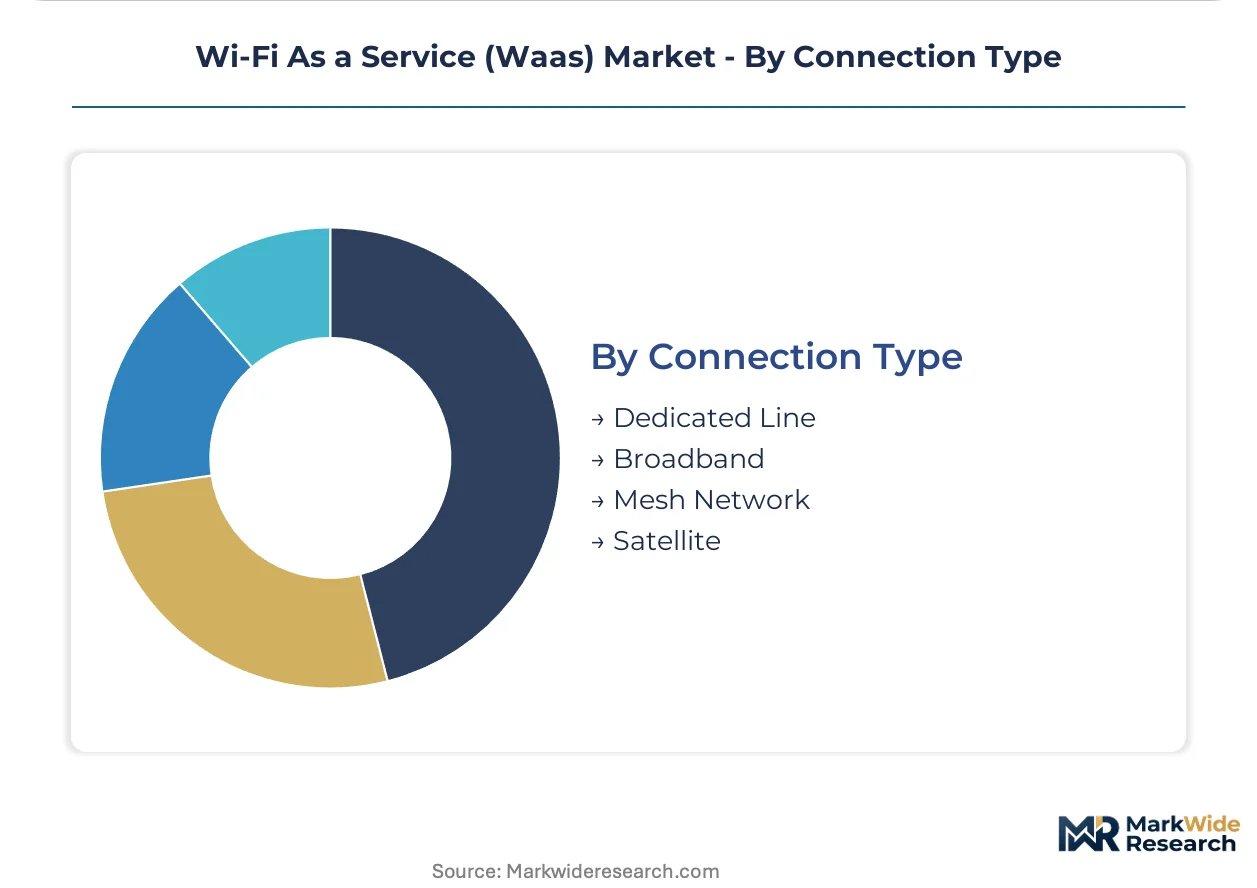
Connection Type:
Supply concentration in fiber backhaul markets is forcing satellite and mesh alternatives into rural and temporary deployment niches.
- Broadband:Consumer-grade cable and DSL circuits for cost-sensitive deployments with moderate reliability requirements. Small enterprises in Germany leverage these for managed Wi-Fi bundles that include ISP procurement.
- Dedicated Line:SLA-backed fiber or Ethernet circuits with guaranteed throughput and latency for mission-critical environments. Financial trading floors in the United States specify these for co-location with cloud-managed access points.
- Mesh Network:Self-healing multi-hop wireless backhaul for outdoor coverage extensions and rapid deployment scenarios.
- Satellite:Low-earth orbit and geostationary links for remote sites beyond terrestrial infrastructure reach.
Broadband underpins the majority of installed access points while Dedicated Line attachments climb fastest in premium enterprise contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FCC's unlicensed 6 GHz spectrum reallocation is accelerating hardware refresh cycles across enterprise campuses, while ETSI harmonization efforts and China's dual carbon goals reshape procurement patterns in their respective jurisdictions.
United States
Financial services firms and healthcare systems are retiring on-premises wireless LAN controllers for subscription-based operational expenditure models. The FCC governs device certification and unlicensed spectrum allocation, mandating automated frequency coordination for 6 GHz deployments. Corporate headquarters in New York and technology campuses in California are compressing contract durations to secure Wi-Fi 6E hardware ahead of Wi-Fi 7 availability.
Germany
Industrial IoT sensor networks in smart factories are creating demand for unified IT-OT wireless infrastructure under single service contracts. ETSI harmonizes radio equipment standards across European member states, determining permissible frequency bands and power levels. Manufacturing facilities in Bavaria deploy edge computing nodes alongside managed access points for real-time quality control analytics without backhaul dependency.
China
Enterprise campuses are expanding managed Wi-Fi contracts to offload IT overhead amid cloud-managed infrastructure investments. MIIT oversees telecommunications standards and spectrum policy under national dual carbon goals that incentivize energy-efficient network equipment. Technology clusters in Shenzhen and Beijing prioritize Wi-Fi 6E hardware refresh cycles to support video conferencing and collaborative applications.
Japan
Educational institutes with seasonal enrollment spikes are prioritizing 6 GHz capacity for dormitory streaming and virtual reality lab deployments. METI coordinates industrial policy and technology standards, influencing procurement timelines for network infrastructure investments. University districts in Tokyo and Osaka specify cloud-managed architectures to reduce radio frequency engineering headcount.
South Korea
Radio frequency semiconductor fabrication concentration exposes hardware vendors to geopolitical disruption risk, prompting diversification efforts. The country's national telecommunications regulator shapes spectrum allocation frameworks for unlicensed use. Technology corridors near Seoul are deploying managed Wi-Fi bundles with captive portal segmentation for hospitality and corporate visitor traffic.
Wi-Fi As a Service (Waas) Market Competitive Landscape
Player mix skews toward diversified technology conglomerates with enterprise networking heritage, creating a tiered structure where full-stack platform vendors hold pricing power over component specialists. Three archetypes dominate: cloud-native wireless specialists leveraging AI-driven automation, vertically integrated equipment manufacturers with captive silicon supply, and telecommunications carriers bundling connectivity with managed infrastructure services. Competitive moves concentrate on strategic partnerships between hardware vendors and systems integrators, plus portfolio diversification into adjacent security and edge computing segments.
Within the telecommunications carrier tier, AT&T and Verizon exemplify network operators expanding beyond connectivity into managed infrastructure subscriptions. Cisco Systems occupies a position representing enterprise switching incumbents bundling cloud-managed access points with security offerings. Juniper Networks sits within the AI-native archetype, anchoring competitive positioning through machine learning-based radio resource management platforms.
| Leading Market Players |
|---|
| AT&T |
| Verizon |
| Cisco Systems |
| Juniper Networks |
| Huawei Technologies |
| Singtel |
| T-Mobile |
| Aruba (HPE) |
| CommScope |
| Others |
Value Network & Pricing Analysis
Captive silicon production at scale anchors cost structures across the Wi-Fi As a Service ecosystem, compressing unit economics for managed service bundles while elevating price floors for vendors without upstream integration. Equipment manufacturers with in-house semiconductor capabilities command margin advantages that translate into aggressive subscription pricing, forcing pure-play software competitors toward premium positioning or channel partnerships.
Pricing Analysis
Certification level under Wi-Fi Alliance 6E and forthcoming Wi-Fi 7 programs creates the primary spread between qualified and non-qualified equipment suppliers. Subscription-based SaaS-tiered models dominate, with cloud-managed bundles commanding premiums over hardware-only transactions. Price differentiation rests on spectrum optimization software sophistication and SLA-backed uptime guarantees. Cost compression in mid-market tiers intensifies as value-added resellers consolidate procurement volumes. Healthcare systems in the United States exhibit lowest price sensitivity due to IT headcount constraints, while regional retailers in Germany show acute sensitivity to per-access-point economics.
Supply Chain Analysis
Taiwan and South Korea anchor radio frequency semiconductor fabrication, with advanced node production concentrating among foundry operators serving Qualcomm, Broadcom, and MediaTek. Access point hardware draws from silicon wafers, RF front-end modules, and power management integrated circuits. Single-source vulnerability in 6 GHz RF filter supply exposes vendors to allocation constraints during certification surges. Distribution runs through systems integrators and value-added resellers who bundle hardware with installation services and ongoing management contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Wi-Fi As a Service market sits in early-cycle expansion as FCC 6 GHz spectrum liberalization triggers hardware refresh waves across enterprise campuses. Cloud-managed infrastructure penetration remains below saturation in mid-market verticals, creating runway for subscription model adoption.
For Market Incumbents: Shield installed base relationships through AI-driven radio resource management integration that raises switching costs. Deepen backward integration into captive silicon supply to defend margin position against Qualcomm and MediaTek reference design competitors. Accelerate Wi-Fi 7 certification investment to preempt hardware replacement cycle compression. Fortify channel control by acquiring regional systems integrators with healthcare and legal services vertical expertise.
For New Entrants and Emerging Players: Differentiate on edge computing co-location capabilities for manufacturing quality control and retail analytics applications. Target professional services firms and regional healthcare systems in Germany where turnkey managed Wi-Fi bundles remain underpenetrated. Pursue operational technology convergence opportunities in Chinese smart factories seeking unified IT-OT wireless infrastructure. Build go-to-market motion through hyperscaler marketplace listings that reduce customer acquisition friction.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors AI-native wireless specialists with machine learning-based automation platforms over hardware-centric incumbents. Long-term viability over the next decade rests on software recurring revenue multiples rather than equipment shipment volumes. Acquisition target archetype: cloud-managed infrastructure providers with vertical-specific SLA frameworks and existing healthcare or financial services customer concentration. Monitor Wi-Fi 7 certification timeline clarity as inflection indicator for hardware refresh cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Wi-Fi 7 Certification Investment | Early certification secures 6 GHz automated frequency coordination compliance ahead of FCC-mandated timelines. |
| AI-Driven Radio Resource Management Integration | Mist AI and comparable platforms automate propagation modeling that addresses certified wireless professional scarcity. |
| Edge Computing Node Co-location | Local compute deployment at branch locations reduces backhaul dependency for German manufacturing quality control. |
| Vertical-Specific SLA Framework Development | Healthcare uptime guarantees and financial services latency commitments differentiate premium subscription tiers. |
| Channel Partner Acquisition | Systems integrator consolidation captures recurring revenue streams previously held by hardware distributors. |
Research Methodology
Desk research of FCC spectrum allocation filings, Wi-Fi Alliance certification databases, and ETSI harmonization standards preceded structured interviews with enterprise IT directors, managed service provider engineering leads, and value-added reseller principals. Secondary validation drew from SEC 10-K networking segment disclosures, hyperscaler infrastructure capex reports, and customs data on wireless equipment trade flows. Bottom-up contract value estimates triangulated against top-down infrastructure spending forecasts across the analysis window.
Variance decomposition across service type, deployment model, and end-user verticals shaped the analytical framework over the projection horizon. Segmentation dimensions modeled encompass managed versus private versus public Wi-Fi architectures, cloud-based versus edge versus on-premises deployment, and enterprise versus educational versus retail end-user categories. CAGRs were derived from install base growth rates, hardware refresh cycle compression factors, and subscription pricing trajectory assumptions. Forecast inputs incorporated FCC 6 GHz adoption curves and Wi-Fi 7 certification queue duration estimates.
The analysis sits within stated boundaries; outcomes outside sustained FCC spectrum liberalization, stable Taiwan-South Korea semiconductor supply, and continued enterprise IT outsourcing trends would require recalibration. Forecasts reflect documented assumptions regarding certification timeline friction and private 5G substitution threats. Recalibration cycles align with material shifts in spectrum policy, geopolitical disruption to silicon supply, and Wi-Fi Alliance standards evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Gigabit Passive Optical Network (GPON) Market
Network Technology
Enterprise Network Equipment Market
Network Technology
United States and European Fiber Optic Cable Market
Network Technology
Global Private 5G Network Market
Network Technology
BYOD Market
Network Technology
North America Enterprise WLAN Market
Network Technology
Wi-Fi Extender Market
Network Technology
Mobile Backhaul Market
Network Technology
Lit Fiber Market
Network Technology
Philippines Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
Global Network Probe Market
Network Technology
Virtual Customer Premises Equipment Market
Network Technology
Global LWAN Market
Network Technology
Mobile Accelerator Market
Network Technology
UK Fixed Connectivity Market
Network Technology
Middle East & Africa Video Conferencing Hardware Market