
 Global Optical Communication and Networking Market | 2026-2036
Global Optical Communication and Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Global Optical Communication and Networking Market Foresight
Data center interconnect demand is consolidating as the dominant revenue pull in optical networking. Huawei Technologies Co., Ltd. leverages its integrated photonics foundry capacity to control cost positions in coherent transceivers. Ciena Corporation anchors North American supply through its WaveLogic platform specialization. Nokia Corporation competes aggressively in passive optical networks across European telecom access upgrades.
Optical communication and networking encompasses the transmission of data as light pulses through fiber-optic cables, waveguides, and free-space links, typically operating at wavelengths between 1260 nm and 1625 nm with modulation formats spanning NRZ to coherent QAM. The primary purpose is to achieve terabit-scale throughput across distances from meters to thousands of kilometers with minimal signal degradation. Transceivers and dense wavelength division multiplexing equipment capture the deepest margin pools as data rates migrate from 100G to 400G and 800G. Optical fiber remains the volume foundation but faces price compression from Chinese oversupply. Wavelength division multiplexing technology leads upgrade cycles as spectrum efficiency becomes the critical bottleneck.
The FCC in the United States mandates broadband infrastructure reporting that steers carrier capex toward fiber-deep architectures, while the EU AI Act and GDPR in Europe impose latency and data-localization requirements that favor optical over electrical switching in AI training clusters. China's MIIT enforces domestic GB standards and dual carbon goals that accelerate silicon photonics substitution for legacy discrete components. Stakeholders must monitor regulatory divergence on encryption-in-transit standards and spectrum allocation rules that could fragment transceiver certification requirements across major economies.
Market Dynamics
AI training clusters are compressing upgrade cycles across optical transport layers, forcing coherent DSP architectures to migrate from 400G to 800G line-side speeds within single product generations rather than the traditional three-to-four-year cadence.
Growth Catalysts
- Hyperscale cloud capex:Amazon Web Services, Microsoft Azure, and Google Cloud are accelerating submarine cable deployments to interconnect continental AI zones, pulling demand for high-count fiber pairs and advanced coherent modulation.
- China's MIIT domestic standards mandate:Beijing's push for indigenous 400G/800G transmission specifications is creating captive demand for silicon photonics foundries and reducing import dependency on foreign transceiver suppliers.
- Coherent DSP architecture advances:7nm and 5nm process nodes from semiconductor foundries are enabling 800G ZR/ZR+ pluggable modules that collapse the cost structure of metro and regional interconnects.
Market Restraints
- Chinese fiber oversupply:State-backed capacity expansions in Hubei and Jiangsu provinces have depressed global fiber pricing, compressing margin pools for Western cable manufacturers dependent on premium product mixes.
- Rare earth element concentration:Erbium and ytterbium supply chains for optical amplifiers concentrate in Chinese refining operations, creating geopolitical exposure for amplifier module vendors.
- Terrestrial spectrum scarcity:Dense wavelength division multiplexing systems are approaching nonlinear Shannon limits in C+L band configurations, forcing costly investments in S-band expansion and Raman amplification.
Strategic Opportunities
- India's BharatNet rural fiber program:The country's national broadband mission is creating volume demand for passive optical network equipment as state-run BSNL tenders multi-million port GPON/XGS-PON deployments.
- Free-space optical convergence with satellite constellations:Ground-to-satellite laser links from Starlink and Project Kuiper are opening new specification requirements for atmospheric compensation and beam-steering subsystems.
- EU AI Act latency mandates:Brussels' data-localization requirements for AI training are favoring optical circuit switching over electrical packet fabrics in European hyperscale facilities.
Industry Challenges
- Coherent optics talent scarcity:The specialized skill set spanning digital signal processing, III-V photonics, and high-speed analog design concentrates in a handful of academic programs and incumbent engineering teams.
- Multi-vendor interoperability certification:The Open ROADM and OpenZR+ initiatives require extended validation cycles across disaggregated transponder, line system, and management plane combinations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Optical Communication and Networking Market |
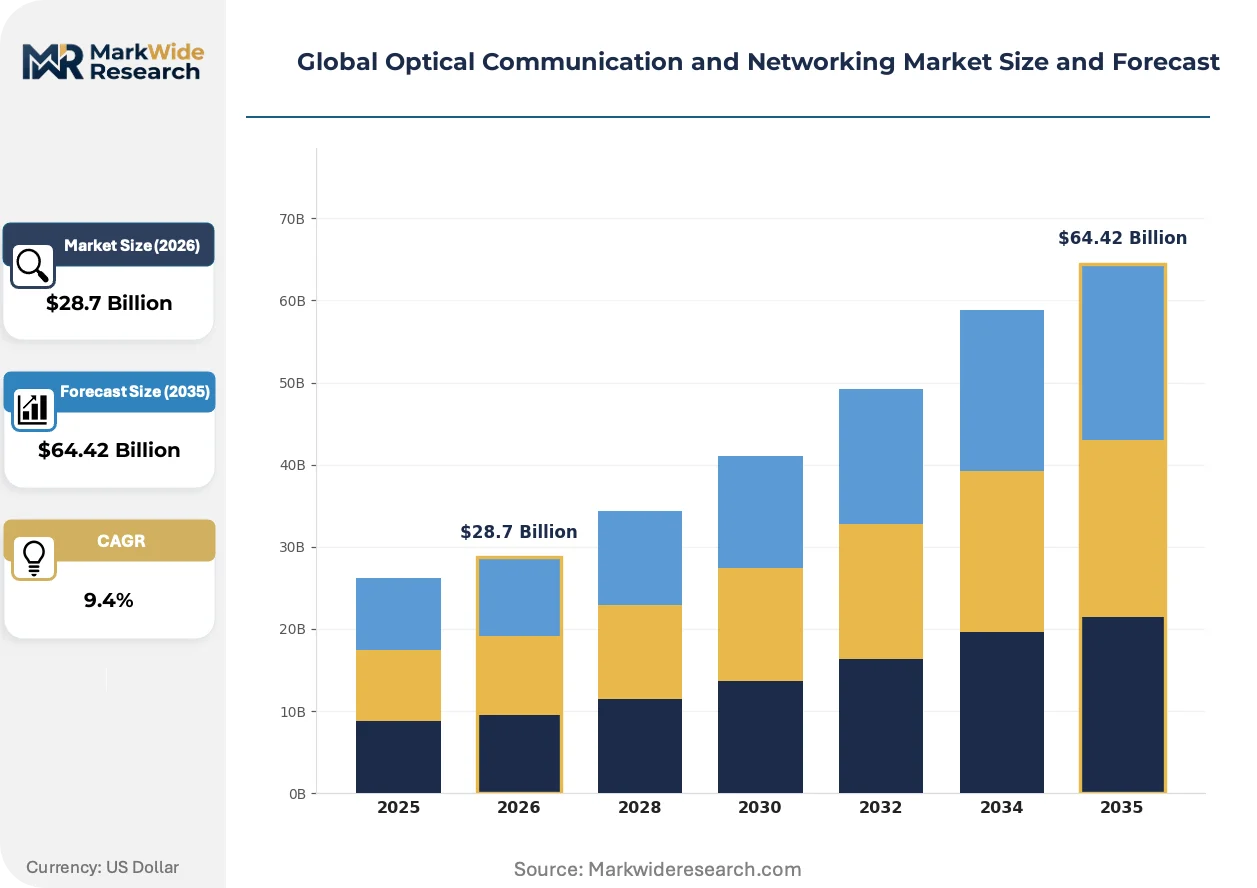
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $64.42 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Fiber, Optical Amplifiers, Transceivers, Optical Switches Technology: Wavelength Division Multiplexing, Time Division Multiplexing, Passive Optical Networks, Dense Wavelength Division Multiplexing End User: Telecom Providers, Data Centers, Enterprises, Government Institutions Application: Telecommunications, Broadband Connectivity, Data Transmission, Internet of Things |
| Companies Covered | Huawei Technologies Co., Ltd., Ciena Corporation, Cisco Systems, Inc., Nokia Corporation, ZTE Corporation, Arista Networks, Inc., Juniper Networks, Inc., Infinera Corporation, ADVA Optical Networking SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Optical Communication and Networking Market Shifts & Advancements
Silicon photonics integration is collapsing the traditional boundaries between optical subsystems, enabling new architectural approaches that bypass discrete component supply chains entirely.
Pluggable coherent transceivers are modularizing around standardized form factors such as QSFP-DD and OSFP, allowing data center operators to decouple optical engine procurement from switch and router platform refresh cycles. Hyperscale buyers are now specifying transceiver interoperability across multiple switch ASIC vendors rather than accepting proprietary optical modules. This shift is compressing R&D amortization periods for component suppliers while accelerating price erosion in 400G and 800G product tiers.
The FCC's infrastructure reporting mandates are steering US carrier capital expenditure toward fiber-deep access architectures that support symmetrical multi-gigabit residential and enterprise services. These requirements are accelerating the displacement of copper-based DSL and HFC plant in favor of XGS-PON and active Ethernet overlays. Rural electric cooperatives and municipal utilities are capturing disproportionate deployment share as incumbent telcos prioritize densification over greenfield extension.
Hyperscale procurement patterns are consolidating around direct transceiver sourcing from module vendors rather than traditional systems-integrator channels. Cloud operators are establishing dedicated supply agreements with silicon photonics foundries and DSP semiconductor suppliers, bypassing optical subsystem vendors. This disintermediation is most visible in North American and Chinese markets where procurement volumes justify dedicated foundry capacity reservations and custom silicon development programs.
Global Optical Communication and Networking Market Segmentation
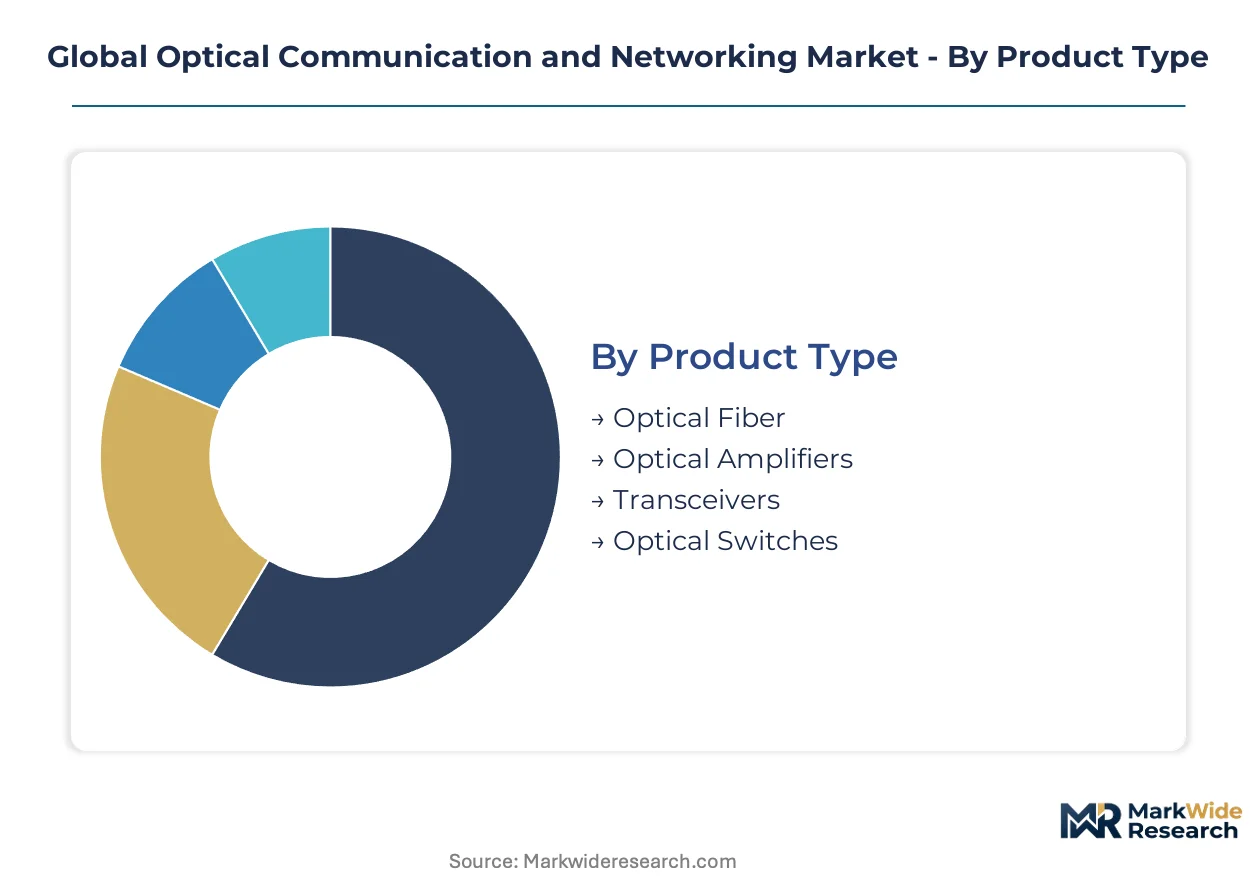
Optical communication markets fragment along technical boundaries that determine procurement patterns and margin structures. Product type and technology categories capture distinct value pools as data rates escalate from 100G to 800G across submarine, metro, and access networks.
Product Type:
Supply concentration in coherent DSP silicon and III-V photonics foundries shapes competitive positioning across hardware categories.
- Transceivers:Pluggable modules integrating silicon photonics with electronic signal processing dominate procurement volumes at hyperscale cloud operators. Demand concentrates in 400G ZR and 800G ZR+ form factors for data center interconnect applications, with China's MIIT domestic standards mandate creating captive supply channels for indigenous vendors.
- Optical Fiber:Silica-based waveguide cable constitutes the volume foundation of physical infrastructure deployment. State-backed capacity expansions in Hubei and Jiangsu provinces have compressed global pricing, forcing Western manufacturers toward premium specialty fiber mixes for submarine and aerospace applications.
- Optical Amplifiers:Erbium-doped and Raman amplification subsystems extend reach in long-haul and submarine systems.
- Optical Switches:Circuit and packet optical switching platforms enable wavelength routing in metro cores and AI training clusters.
Today's leader: Transceivers. Tomorrow's challenger: Optical Fiber.
Technology:
Cost tier differentiation separates legacy access technologies from coherent transport platforms commanding premium pricing.
- Dense Wavelength Division Multiplexing:C+L band coherent systems with 64QAM modulation achieve maximum spectrum efficiency in submarine and long-haul applications. Upgrades to S-band expansion and Raman amplification are gaining share fastest as operators approach nonlinear Shannon limits in conventional configurations.
- Wavelength Division Multiplexing:Metro and regional networks deploy flexible-grid ROADM architectures with 400G line-side speeds. Deployment concentrates in United States hyperscale interconnects, with Amazon Web Services and Microsoft Azure driving multi-terabit fiber pair procurement for continental AI zones.
- Passive Optical Networks:GPON and XGS-PON standards dominate residential and enterprise access deployments.
- Time Division Multiplexing:Legacy SONET/SDH architectures persist in government and utility networks with slow modernization cycles.
Coherent platforms command premium tiers. Access technologies compete on volume economics.
End User:
Customer type determines procurement channel structure, with hyperscale direct sourcing bypassing traditional systems integrators.
- Data Centers:Hyperscale cloud operators and colocation providers specify transceiver interoperability across switch ASIC vendors rather than accepting proprietary modules. Procurement concentrates in North American markets where Amazon Web Services, Microsoft Azure, and Google Cloud maintain dedicated foundry capacity reservations.
- Telecom Providers:Incumbent carriers and mobile operators drive metro fiber and submarine cable investments with regulated capex cycles. FCC broadband infrastructure reporting mandates steer United States carriers toward fiber-deep architectures, accelerating XGS-PON deployment over legacy copper plant.
- Enterprises:Financial services and healthcare verticals deploy private optical networks for latency-sensitive applications.
- Government Institutions:Defense and research networks fund free-space optical and quantum communication pilot programs.
Hyperscale buyers dictate transceiver roadmaps. Telecom carriers anchor submarine and metro volume.
Application:
Application maturity separates established telecommunications infrastructure from emerging IoT connectivity requirements.
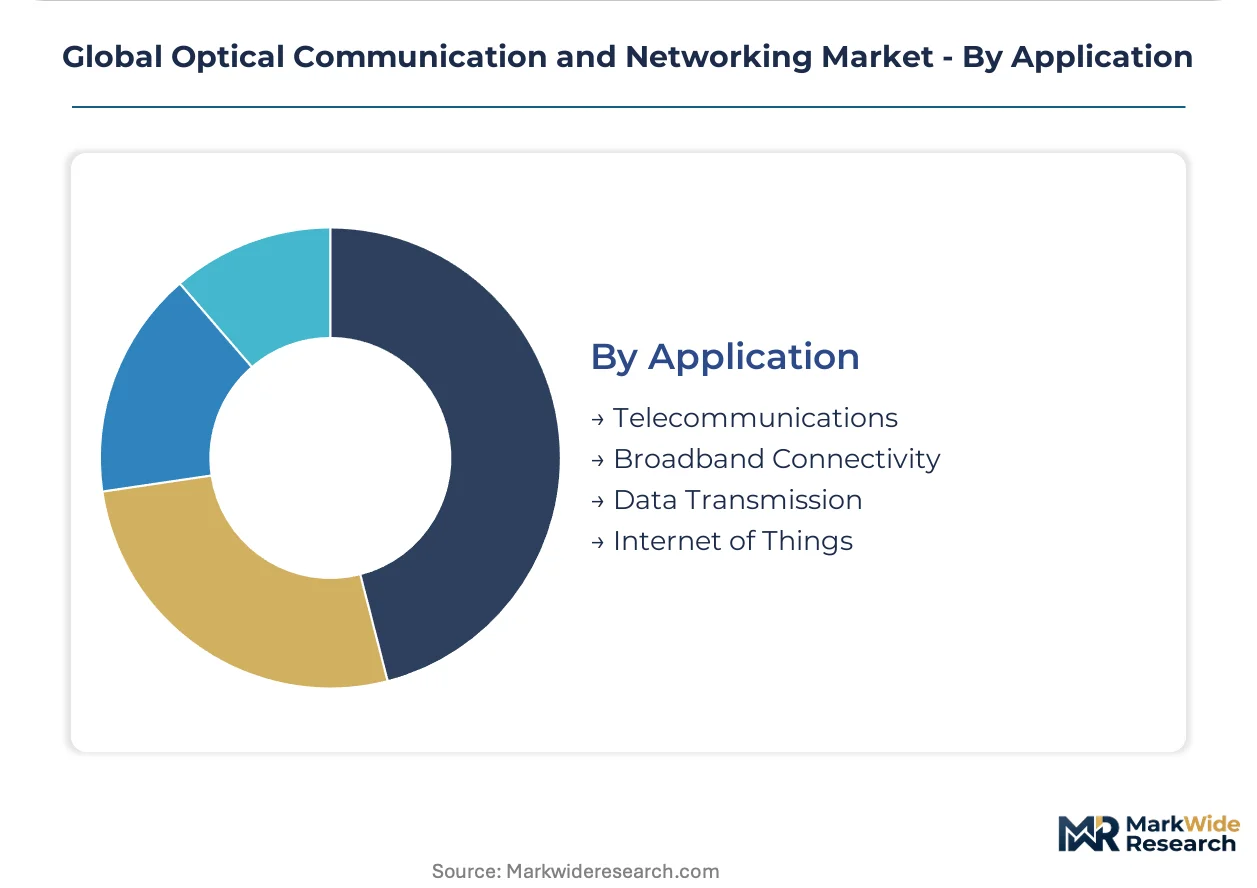
- Data Transmission:Inter-data center and AI training cluster interconnects compress upgrade cycles to 18-24 months versus traditional three-to-four-year cadences. Demand concentrates in submarine cable deployments linking continental AI zones, with advanced coherent modulation pulling high-count fiber pair investments.
- Telecommunications:Mobile backhaul and core transport networks drive coherent 400G/800G line-side upgrades. India's BharatNet rural fiber program creates volume demand for passive optical network equipment as state-run BSNL tenders multi-million port GPON deployments.
- Broadband Connectivity:Residential and enterprise fiber-to-the-premises expansion accelerates XGS-PON and active Ethernet overlays.
- Internet of Things:Industrial and automotive optical sensing applications remain nascent with fragmented standards.
AI-driven data transmission commands R&D investment. Broadband access delivers volume scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping photonics manufacturing geography as compliance-cost differentials between the FCC's infrastructure mandates and China's MIIT domestic-standards push redirect foundry investments toward jurisdictions with streamlined certification pathways.
United States
Hyperscale cloud operators in Northern Virginia and Dallas-Fort Worth metro clusters are pulling submarine cable landings and AI training-fiber deployments at unprecedented density. FCC broadband infrastructure reporting mandates steer carrier capex toward fiber-deep architectures. Greater Phoenix anchors transceiver packaging and test operations serving West Coast cloud campuses.
China
MIIT enforcement of indigenous 400G/800G transmission specifications is creating captive demand for silicon photonics foundries in Wuhan and Suzhou industrial parks. Dual carbon goals accelerate substitution of legacy discrete components with integrated photonics. Yangtze River Delta concentration spans Hubei fiber draw towers to Jiangsu amplifier module assembly.
Germany
EU AI Act latency mandates and GDPR data-localization requirements favor optical circuit switching in Frankfurt and Berlin hyperscale facilities. CE marking and RoHS compliance create premium-tier certification barriers that domestic component vendors exploit. Bavaria's Munich-Stuttgart corridor hosts coherent DSP design houses serving European telecom upgrades.
India
BharatNet rural fiber tenders from state-run BSNL are generating multi-million port demand for passive optical network equipment across Maharashtra and Gujarat. TRAI spectrum allocation rules and BIS certification requirements shape vendor qualification pathways. Bangalore-Telangana corridor concentrates system integration and software-defined optical layer development.
Japan
METI support for 6G optical-wireless convergence research drives free-space optical pilot programs in Tokyo-Osaka corridors. JIS standards and PMDA-equivalent telecom certification maintain quality-tier segmentation that protects domestic coherent transceiver suppliers. Kyushu hosts specialty fiber preform manufacturing for submarine cable applications.
Global Optical Communication and Networking Market Competitive Landscape
Capacity expansion dominates the current landscape as silicon photonics foundries race to capture hyperscale direct-sourcing agreements before traditional systems integrators can restructure procurement channels. The vendor base stratifies across three tiers: integrated platform vendors with captive semiconductor fabrication, modular transceiver specialists dependent on external foundry access, and regional cable manufacturers competing on state-backed fiber volume. Strategic archetypes include foundry-integrated coherent DSP houses, disaggregated pluggable-module pure-plays, and state-supported national champions. M&A activity concentrates on silicon photonics IP portfolios and submarine cable system assets, while geographic expansion targets Indian passive optical network tenders and Middle East smart-city fiber deployments.
Among integrated platform vendors, Huawei Technologies Co., Ltd. and Ciena Corporation exemplify contrasting geographic orientations—one anchored in China's domestic-standards ecosystem, the other in North American carrier supply relationships. Nokia Corporation occupies a position bridging European telecom access upgrades with submarine cable system integration. These three entities represent the dominant archetypes: state-supported vertical integration, specialized coherent transport platforms, and diversified optical-to-radio convergence portfolios.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd. |
| Ciena Corporation |
| Cisco Systems, Inc. |
| Nokia Corporation |
| ZTE Corporation |
| Arista Networks, Inc. |
| Juniper Networks, Inc. |
| Infinera Corporation |
| ADVA Optical Networking SE |
| Others |
Supply & Pricing Matrix
Hyperscale cloud operators in North America and China anchor procurement volumes for 400G and 800G coherent transceivers, compressing channel margins and forcing direct-sourcing models that bypass traditional systems integrators entirely. Their consolidated buying power collapses distributor markups while amplifying price transparency across silicon photonics foundries and DSP semiconductor suppliers.
Pricing Analysis
Distributor margins in optical networking equipment have compressed from traditional double-digit percentages to mid-single digits as hyperscale buyers negotiate direct foundry contracts. Three-tier pricing structure across premium, standard, and economy levels separates submarine-grade coherent modules from metro ZR+ pluggables and access-tier PON optics. Price differentiation hinges on certification grade—CE-marked European variants and FCC-compliant North American SKUs command 15-25% premiums over baseline configurations—and volume scale, with annual procurement commitments above 100,000 units unlocking foundry-direct pricing. Cost compression in 400G transceivers is intensifying because Chinese domestic standards are accelerating indigenous silicon photonics capacity. Telecom carriers exhibit highest price sensitivity due to regulated capex cycles, while defense and research networks demonstrate lowest sensitivity for quantum-secure and free-space optical systems.
Supply Chain Analysis
China's MIIT domestic-content mandates are reshaping sourcing patterns, requiring indigenous silicon photonics foundries in Wuhan and Suzhou to supply state-backed 400G/800G transmission deployments. Geographic supply concentration centers on China for erbium-doped fiber amplifiers and rare-earth refining, Taiwan for coherent DSP semiconductor fabrication, and Japan for specialty fiber preforms. Raw material dependencies draw from erbium and ytterbium supply chains concentrated in Chinese refining operations, III-V photonics wafers sourced from compound semiconductor foundries, and high-purity silica for fiber draw towers. Single-source vulnerability in rare-earth element concentration creates geopolitical exposure for Western amplifier vendors. Distribution runs through direct procurement agreements between hyperscale operators and module vendors, bypassing traditional optical systems integrators in North American and Chinese markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FCC broadband infrastructure mandates and China's MIIT domestic-standards push create sustained equipment refresh demand across fiber-deep access and coherent transport layers.
For Market Incumbents: Extend coherent DSP architecture roadmaps from 400G to 1.6T line-side speeds within compressed 18-24 month cycles to outpace emerging silicon photonics pure-plays. Secure captive foundry capacity reservations in Taiwan and South Korea to defend against supply rationing during hyperscale procurement surges. Anchor certification investments in CE marking and FCC compliance to maintain premium-tier positioning as Chinese vendors capture economy segments through MIIT-mandated domestic deployments. For New Entrants and Emerging Players: Rural electric cooperatives and municipal utilities in the United States represent underserved buyer archetypes capturing disproportionate fiber deployment share as incumbent telcos prioritize densification over greenfield extension. India's BharatNet rural fiber tenders generate multi-million port demand for passive optical network equipment with qualification pathways favoring vendors offering localized system integration in Bangalore-Telangana corridor. Pursue white-label transceiver partnerships with Indian and Middle Eastern system integrators to bypass direct hyperscale procurement barriers. For Investors and Strategic Acquirers: Hyperscale cloud operators are the most active acquirer in this space, establishing dedicated supply agreements with silicon photonics foundries and DSP semiconductor suppliers that bypass traditional optical subsystem vendors. Long-term viability hinges on coherent optics talent scarcity concentrating in a handful of academic programs and incumbent engineering teams, creating defensive moats for DSP design houses with captive semiconductor fabrication. Acquisition target archetypes include silicon photonics IP portfolios with 7nm and 5nm process node tape-outs and submarine cable system assets linking continental AI zones. Monitor OpenZR+ interoperability certification completion rates as the inflection indicator for pluggable coherent module commoditization timing.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Foundry Capacity Reservation | Huawei and Ciena secure dedicated wafer starts at TSMC and GlobalFoundries amid hyperscale demand surges. |
| OpenZR+ Interoperability Certification | ADVA and Infinera validate disaggregated transponder combinations across multi-vendor metro deployments. |
| Submarine Cable System Integration | Nokia anchors trans-Atlantic fiber pair investments linking Northern Virginia and Frankfurt AI clusters. |
| XGS-PON Volume Manufacturing Scale-Up | ZTE and Arista respond to FCC-mandated fiber-deep architectures in US rural electric cooperative territories. |
| Coherent DSP Semiconductor Acquisition | Cisco and Juniper target fabless DSP design houses to verticalize 800G ZR+ module supply chains. |
Research Methodology
Bottom-up hyperscale capex modeling reconciled against top-down silicon photonics foundry output tracking forms the analytical core of this study. Primary interviews with optical network architects at cloud operators, coherent DSP design engineers, submarine cable system procurement managers, and telecom carrier infrastructure planners combined with secondary validation from FCC broadband deployment reports, MIIT domestic standards filings, SEC 10-K hyperscale capex disclosures, and CE marking certification databases. Triangulation across these sources anchors volume estimates for 400G and 800G transceiver shipments.
Historical trendline analysis of coherent modulation migration patterns—from 100G QPSK through 400G 16QAM to 800G 64QAM—informs the projection framework across the analysis window. Segmentation dimensions modeled include product type, technology tier, end-user category, and application maturity, with additional granularity on regulatory framework clusters distinguishing FCC-mandated US deployments from MIIT-governed Chinese specifications and EU AI Act latency-driven European upgrades. CAGRs derive from equipment replacement cycle compression observed in AI training cluster interconnects versus traditional telecom refresh cadences.
Underlying measurement precision varies by segment; data center interconnect and submarine cable applications carry tighter precision than emerging free-space optical and quantum communication pilots. Forecasts reflect assumptions on hyperscale direct-sourcing penetration rates, foundry yield improvements at 5nm process nodes, and rare-earth supply chain stability that could revise projections if trade restrictions intensify or silicon photonics integration accelerates beyond modeled timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Service Provider Router Market
Data Center and Networking
Global Data Center and Network Third-Party Hardware Maintenance Service Market
Data Center and Networking
Global Data Warehouse Market
Data Center and Networking
Global Mobile Content Delivery Network Market
Data Center and Networking
United States Data Center Networking Market
Data Center and Networking
Global Content Delivery Network (CDN) Software Market
Data Center and Networking
DNA Digital Data Storage Market
Data Center and Networking
Network Slicing Market
Data Center and Networking
Philippines Data Center Networking Market
Data Center and Networking
France Data Center Networking Market
Data Center and Networking
South Korea Data Center Server Market
Data Center and Networking
GPU Database Market
Data Center and Networking
Virtual Networking Market
Data Center and Networking
South America Data Center Networking Market
Data Center and Networking
Global Heterogeneous Network Market
Data Center and Networking
Network As a Service (Naas) Market