
 Global Carrier Ethernet Equipment Market | 2026-2036
Global Carrier Ethernet Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Carrier Ethernet Equipment Market Intelligence
The unbundling of hardware and software in network equipment is shifting buyer preference toward more flexible, modular architectures. Cisco Systems, Inc. leverages its extensive portfolio to offer integrated solutions, balancing hardware and software sales. In contrast, Arista Networks, Inc. specializes in software-driven cloud networking, competing on programmability and performance. Ciena Corporation sustains its market position through deep expertise in optical transport and coherent optics technology.
Carrier Ethernet equipment comprises network hardware and software designed to deliver Ethernet services over metropolitan and wide area networks. These systems adhere to standards from bodies like the MEF, ensuring interoperability and defined service levels for business connectivity. The 100 Gigabit Ethernet technology segment leads in revenue due to deployments in data center interconnects and core networks. Mobile backhaul applications are expanding rapidly, driven by global 5G infrastructure upgrades by telecommunication carriers.
Network neutrality rules enforced by regulators like the US Federal Communications Commission (FCC) influence service delivery models. In China, the Ministry of Industry and Information Technology (MIIT) guides technology choices for national carriers, while European standards from ETSI promote interoperability. Vendor selection will increasingly hinge on the ability to support open, programmable networks that adapt to evolving security and automation requirements.
Market Dynamics
The unbundling of network hardware and software is the central force shaping the Carrier Ethernet equipment market. This shift toward disaggregation allows service providers to mix and match components, fostering innovation while pressuring incumbent vendors to adapt their integrated models.
Growth Catalysts
- 5G Mobile Backhaul Expansion:Global telecommunication carriers are upgrading their mobile backhaul infrastructure to support high-bandwidth, low-latency 5G services, directly increasing demand for advanced Carrier Ethernet equipment.
- Data Center Interconnect (DCI):Demand for 100 Gigabit Ethernet and higher speeds is concentrating in high-density data center corridors, particularly within the United States, China, and Germany, to handle massive data flows.
- MEF Standardization:Adherence to standards from bodies like the MEF ensures service interoperability and defined performance levels, giving enterprises the confidence to adopt Ethernet for business-critical WAN connectivity.
Market Restraints
- High Capital Expenditure:The deployment of new fiber optic cables and the upgrade of existing metropolitan network infrastructure to support higher Ethernet speeds require significant upfront investment from service providers.
- Integration Complexity with Legacy Systems:Integrating modern, SDN-enabled Carrier Ethernet platforms with older, pre-existing network equipment presents significant technical and operational challenges for network operators.
- Specialized Component Dependency:The supply chain relies on a limited number of semiconductor firms for critical components like high-speed optical transceivers and advanced network processors, creating potential bottlenecks.
Strategic Opportunities
- Edge Computing Deployments:The growth of edge computing requires robust, low-latency network services closer to end-users, creating a new application frontier for Carrier Ethernet equipment beyond traditional core and metro networks.
- Optical and Ethernet Convergence:Integrating coherent optics and Wavelength Division Multiplexing (WDM) technology directly into Ethernet switches and routers offers a path to simplify network architecture and reduce costs.
- Service Expansion in Developing Economies:Extending business-grade Ethernet services to underserved Tier-2 and Tier-3 cities in large markets such as India and Brazil represents a significant geographic expansion opportunity.
Industry Challenges
- Network Automation Skills Gap:A shortage of network engineers possessing hybrid skills in both traditional routing and modern software development practices (NetDevOps) hinders the adoption of programmable networks.
- Evolving Security Threats:The shift to software-defined and open networks introduces new attack surfaces, requiring continuous development and standardization of security protocols to protect network infrastructure.
- Multi-Vendor Interoperability:Ensuring seamless operation and management across a disaggregated network built with hardware and software from multiple different vendors remains a primary operational hurdle for carriers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Carrier Ethernet Equipment Market |
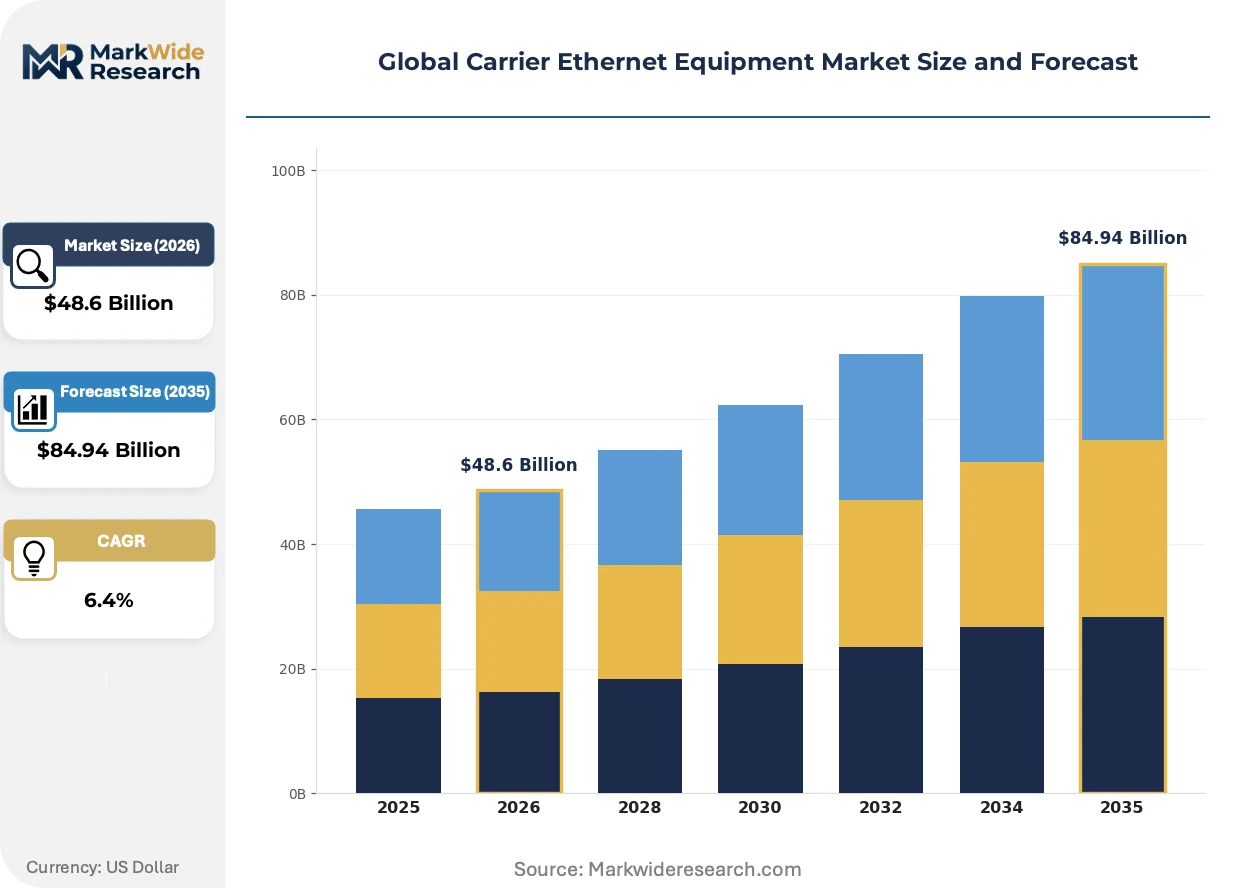
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $84.94 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Network Interface Cards, Optical Transport Equipment, Aggregation Devices Technology: 10 Gigabit Ethernet, 40 Gigabit Ethernet, 100 Gigabit Ethernet, Software Defined Networking, MPLS-TP Application: Data Centers, Cloud Connectivity, Enterprise Networks, Mobile Backhaul, Content Delivery Networks End User Industry: Telecommunication Carriers, Internet Service Providers, Data Hosting Facilities, Managed Service Providers, Wholesale Network Operators |
| Companies Covered | Ciena Corporation, Extreme Networks, Inc., Cisco Systems, Inc., Nokia Corporation, ZTE Corporation, Huawei Technologies Co., Ltd., Arista Networks, Inc., ADVA Optical Networking SE, Juniper Networks Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Carrier Ethernet Equipment Market Strategic Shifts & Innovations
The market's evolution is defined by the transition from rigid, hardware-centric architectures to flexible, software-controlled networks. This fundamental shift prioritizes programmability, automation, and service agility, influencing vendor technology roadmaps and carrier procurement strategies.
Technology Evolution
Network Function Virtualization (NFV) separates network functions like routing and firewalls from proprietary hardware. Service providers and large enterprises are adopting NFV to increase operational agility. The technology is decentralizing network intelligence away from dedicated appliances and into a more flexible, software-based control plane.
Regulatory Shift
Network neutrality regulations, like those from the US Federal Communications Commission (FCC), govern how service providers manage network traffic. These rules impact service delivery models by preventing traffic discrimination. Consequently, equipment must support transparent management and reporting features to help carriers demonstrate compliance.
Demand-Side Shift
A significant behavioral shift sees buyers moving from monolithic, single-vendor systems. They increasingly prefer disaggregated models, purchasing open networking hardware separately from network operating system software. This change is most prominent in hyperscale data center environments and among Tier-1 service providers.
Global Carrier Ethernet Equipment Market Segmentation
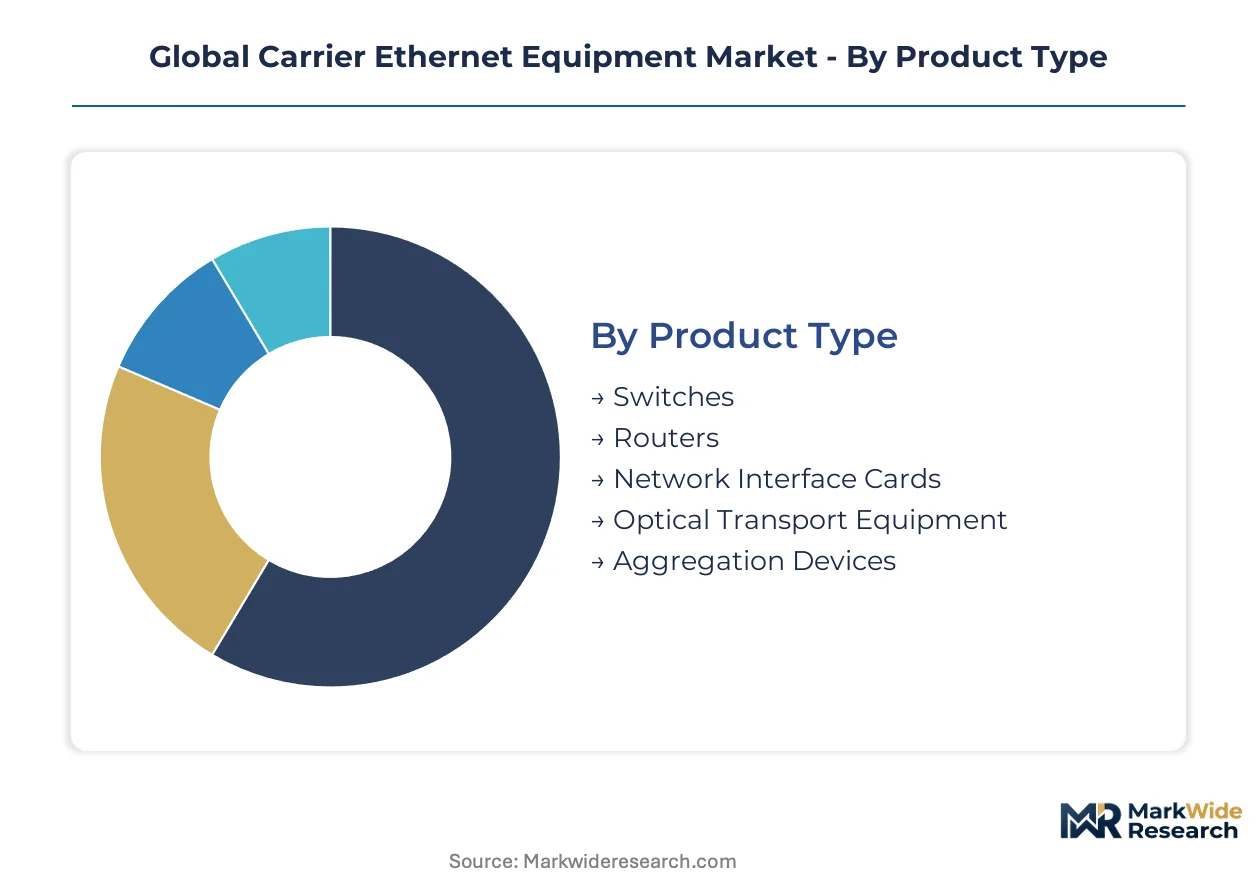
Understanding market segmentation within Carrier Ethernet equipment reveals specific demand patterns and technological priorities. This analysis delineates the distinct product, technology, application, and end-user profiles driving market evolution. Each segment presents unique challenges and opportunities for vendors and service providers.
Product Type:
Certain Carrier Ethernet equipment product types face stringent compliance requirements, such as those for electromagnetic compatibility (EMC) from regulators like the FCC in the US or ETSI in Europe, ensuring operational reliability in diverse network environments.
- Switches:These devices forward data packets between devices on a local area network (LAN) or within a data center, often supporting multiple Gigabit Ethernet ports. Demand concentrates in data center interconnects and enterprise networks in Germany, driven by the need for high-density, low-latency connectivity.
- Routers:Routers connect different networks and forward data packets between them, operating at Layer 3 of the OSI model to manage complex traffic flows. Mobile backhaul infrastructure upgrades in China are driving router demand, requiring robust packet forwarding capabilities for 5G deployments.
- Network Interface Cards:NICs enable devices to connect to a network, handling data transmission at the physical and data link layers.
- Optical Transport Equipment:This equipment transmits data over fiber optic cables using light signals, crucial for long-haul and metro networks.
- Aggregation Devices:These systems consolidate traffic from multiple access points onto a higher-capacity uplink, optimizing network efficiency.
Leading the category by volume: Switches. Growing fastest: Optical Transport Equipment.
Technology:
The cost structure for Carrier Ethernet technologies varies significantly, with higher-speed interfaces commanding premium pricing due to advanced componentry and complex engineering requirements.
- 100 Gigabit Ethernet:This high-speed standard provides 100 Gigabits per second data transfer rates, primarily deployed in core networks and data center interconnects. Demand is high in the United States for hyperscale data centers, facilitating massive data throughput.
- Software Defined Networking:SDN separates the network control plane from the data plane, enabling programmable and automated network management through software. Service providers in Europe are adopting SDN to enhance network flexibility and reduce operational expenditure.
- 10 Gigabit Ethernet:This technology offers 10 Gigabits per second speeds, widely used for enterprise backbone networks and server connectivity.
- 40 Gigabit Ethernet:Providing 40 Gigabits per second, this standard bridges the gap between 10G and 100G, often used for aggregation layers.
- MPLS-TP:MPLS-TP (Multiprotocol Label Switching - Transport Profile) offers connection-oriented packet transport for carrier-grade services.
High-speed 100 Gigabit Ethernet technology dominates current deployments, while Software Defined Networking shows the steepest expansion trajectory.
Application:
The volume of data traffic generated by various applications directly dictates the scale and capacity requirements for Carrier Ethernet equipment, with certain use cases demanding significantly higher throughput.
- Mobile Backhaul:This application connects cellular base stations to the core network, supporting high-bandwidth and low-latency requirements for 5G services. Global 5G network rollouts are rapidly expanding mobile backhaul infrastructure, especially across developing economies.
- Data Centers:Carrier Ethernet facilitates high-speed interconnectivity within and between data centers, handling massive data flows and virtualized workloads. Demand concentrates in major data center hubs like those in the United States and China, requiring robust and scalable solutions.
- Cloud Connectivity:This involves linking enterprise networks to public or private cloud services, ensuring reliable and secure data transfer.
- Enterprise Networks:Businesses utilize Carrier Ethernet for high-speed, reliable connectivity across their branch offices and corporate data centers.
- Content Delivery Networks:CDNs leverage Carrier Ethernet to efficiently distribute digital content closer to end-users, reducing latency and improving streaming quality.
Mobile Backhaul applications represent a significant portion of current demand, with Data Centers also exhibiting strong growth.
End User Industry:
Different end-user industries possess distinct procurement patterns and technical specifications for Carrier Ethernet equipment, driven by their operational models and regulatory environments.
- Telecommunication Carriers:These operators deploy Carrier Ethernet equipment to build their core, metro, and access networks, supporting mobile backhaul and enterprise services. Major carriers like China Mobile and Deutsche Telekom are investing heavily in network upgrades for 5G.
- Internet Service Providers:ISPs utilize Carrier Ethernet to deliver high-speed internet access and managed services to residential and business customers. Demand from ISPs in India is expanding as they extend broadband services to underserved regions.
- Data Hosting Facilities:These facilities use Carrier Ethernet for internal network infrastructure and to provide connectivity services to their tenants.
- Managed Service Providers:MSPs leverage Carrier Ethernet to offer outsourced network management and connectivity solutions to their enterprise clients.
- Wholesale Network Operators:These operators provide raw network capacity and infrastructure to other service providers, relying on scalable Ethernet solutions.
Telecommunication Carriers account for the largest share of equipment purchases, while Internet Service Providers are rapidly expanding their deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global Carrier Ethernet Equipment market exhibits a notable divide between production and consumption, with manufacturing hubs often distinct from high-demand regions. Major investments in network infrastructure upgrades across various geographies drive significant equipment procurement. This dynamic influences regional market characteristics and vendor strategies.
United States
Demand for 100 Gigabit Ethernet technology is high in the United States, driven by hyperscale data centers requiring massive data throughput. The US Federal Communications Commission (FCC) influences service delivery models through network neutrality rules. High-density data center corridors in California and Virginia concentrate demand for robust interconnectivity solutions.
China
China's mobile backhaul infrastructure upgrades are significantly driving router demand, particularly for 5G deployments. The Ministry of Industry and Information Technology (MIIT) guides technology choices for national carriers. Major metropolitan areas like Beijing and Shanghai see substantial investment in high-capacity Ethernet equipment for urban network expansion.
Germany
Germany's enterprise networks and data center interconnects show strong demand for high-density, low-latency switches. European standards from ETSI promote interoperability, influencing equipment design and procurement decisions. The Frankfurt data center cluster is a significant hub, requiring continuous upgrades to Carrier Ethernet infrastructure for digital services.
India
Internet Service Providers in India are rapidly expanding their deployments, extending broadband services to underserved regions. The Telecom Regulatory Authority of India (TRAI) policies encourage network expansion and competition. Tier-2 and Tier-3 cities emerge as new application frontiers for business-grade Ethernet services, driving geographic expansion.
Brazil
Brazil's service expansion in developing economies creates a significant geographic opportunity for Carrier Ethernet equipment. The Agência Nacional de Telecomunicações (ANATEL) regulates telecommunications services, ensuring compliance for network deployments. Major urban centers such as São Paulo and Rio de Janeiro experience increased demand for advanced network solutions.
Global Carrier Ethernet Equipment Market Key Industry Players
The competitive structure tilts toward integrated solution providers who offer extensive portfolios to service providers. The market shows a tiered consolidation, with established vendors alongside specialized software-driven players. Strategic archetypes include hardware-centric incumbents, software-defined innovators, and optical transport specialists. Portfolio diversification and strategic partnerships are dominant competitive moves among these firms.
Within the integrated solutions segment, Cisco Systems, Inc. exemplifies a broad portfolio approach, balancing hardware and software sales for telecommunication carriers. Arista Networks, Inc. occupies a position as a software-driven cloud networking specialist, competing on programmability and performance in data center environments. Ciena Corporation, a US-based company, anchors the market through its deep expertise in optical transport and coherent optics technology. These firms represent distinct strategic vectors within the Carrier Ethernet equipment market, catering to varied network architecture preferences. Their offerings reflect the ongoing disaggregation trend and the need for adaptable network solutions.
| Leading Market Players |
|---|
| Ciena Corporation |
| Extreme Networks, Inc. |
| Cisco Systems, Inc. |
| Nokia Corporation |
| ZTE Corporation |
| Huawei Technologies Co., Ltd. |
| Arista Networks, Inc. |
| ADVA Optical Networking SE |
| Juniper Networks Inc. |
| Others |
Cost & Logistics Intelligence
The unbundling of network hardware and software simultaneously reshapes cost economics and supply concentration within the Carrier Ethernet equipment market. This fundamental shift influences vendor pricing strategies and the sourcing of critical components.
Pricing Analysis
Cost-down pressure on hardware components intensifies as service providers increasingly demand open, disaggregated solutions. The dominant pricing structure remains project-based for large infrastructure deployments, with long-term contracts for ongoing support and software licenses. Price differentiation stems from performance capabilities, such as 100 Gigabit Ethernet speeds, and the level of software programmability offered. Telecommunication carriers, particularly for large-scale 5G rollouts, exhibit high price sensitivity, while hyperscale data centers prioritize performance and reliability.
Supply Chain Analysis
Regional distribution centers facilitate the timely delivery of Carrier Ethernet equipment to major deployment hubs in the United States, China, and Germany. The supply chain draws heavily on specialized component manufacturers, particularly for high-speed optical transceivers and advanced network processors. This specialized component dependency introduces a structural risk, creating potential bottlenecks for critical inputs. Downstream distribution runs primarily through direct sales channels to large telecommunication carriers and value-added resellers for enterprise solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Carrier Ethernet equipment market is undergoing a technology-transition phase, with Software Defined Networking (SDN) increasingly replacing legacy, rigid architectures.
For Market Incumbents: Extend software capabilities to align with disaggregated network architectures. Focus on integrating SDN and Network Function Virtualization (NFV) into existing portfolios to counter the threat from software-driven innovators. Invest in R&D for optical-Ethernet convergence, leveraging deep expertise in optical transport to simplify network architecture and reduce costs. This approach helps maintain market relevance against agile, software-centric competitors.
For New Entrants and Emerging Players: Open networking software platforms represent a technology-first wedge into the Carrier Ethernet market. Target underserved Tier-2 and Tier-3 cities in developing economies like India and Brazil, where demand for business-grade Ethernet services is expanding. A go-to-market angle focused on cost-effective, high-performance solutions with strong multi-vendor interoperability support can capture significant market share in these regions.
For Investors and Strategic Acquirers: Re-rating potential sits with companies specializing in software-driven cloud networking and advanced optical transport, given the accelerating shift towards programmable networks. Long-term viability is supported by sustained demand from global 5G rollouts and data center expansion. Target acquisition archetypes include firms with strong intellectual property in SDN/NFV orchestration or those offering unique coherent optics technology. The signal to watch is the widespread adoption of open-source network operating systems by Tier-1 service providers.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Networking Integration | This enhances network flexibility and automation, meeting evolving service provider demands. |
| Optical-Ethernet Convergence R&D | This simplifies network architecture and reduces operational costs for carriers. |
| Edge Computing Solution Development | This expands application frontiers for Carrier Ethernet equipment beyond core networks. |
| Supply Chain Diversification | This mitigates risks associated with specialized component dependency and geopolitical factors. |
| Multi-Vendor Interoperability Programs | This addresses operational hurdles and supports the market's disaggregation trend. |
Research Approach
Document review covered MEF standards, FCC and ETSI regulatory reports, and public company filings, complemented by interviews with telecommunication carrier executives and network engineers. Primary insights were gathered from data center architects and regulatory affairs specialists. This approach allowed for robust bottom-up and top-down triangulation of market data.
Historical market trends were cross-referenced with expert panel input to project future growth across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, application, end-user industry, and regional regulatory environment. Compound annual growth rates were derived from historical trends and validated through expert projections, incorporating inputs like 5G rollout schedules and data center expansion plans.
Several conditions sit outside the modeled scope, including unforeseen geopolitical conflicts and rapid shifts in global economic policy. Forecasts reflect assumptions regarding technological adoption rates and regulatory stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Network Equipment Market
Network Technology
Netops Market
Network Technology
Wi-Fi As a Service (Waas) Market
Network Technology
Global Network Monitoring Market
Network Technology
Internet Protocol Address Management (IPAM) Market
Network Technology
Industrial Wireline Networking Market
Network Technology
Wi-Fi Router Market
Network Technology
Wi-Fi 6E Router Market
Network Technology
WAN Optimization Controllers Market
Network Technology
Enterprise Network Equipment Market
Network Technology
Network Telemetry Market
Network Technology
Global Network Probe Market
Network Technology
North America Enterprise WLAN Market
Network Technology
Global Carrier Wi-Fi Equipment Market
Network Technology
Microduct Market
Network Technology
Software-Defined Wide Area Network (SD-WAN) Market