
 Industrial Wireless Broken Signal Solutions Market | 2026-2036
Industrial Wireless Broken Signal Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Wireless Broken Signal Solutions Market Outlook
The EU Green Deal is rebalancing capital allocation toward signal-resilient wireless architectures in energy-intensive plants. Siemens AG leverages its automation portfolio to anchor European retrofit demand for industrial repeaters and range extenders. Rockwell Automation competes through its FactoryTalk wireless ecosystem, while Honeywell International Inc. specializes in hazardous-environment signal recovery systems for oil and gas facilities.
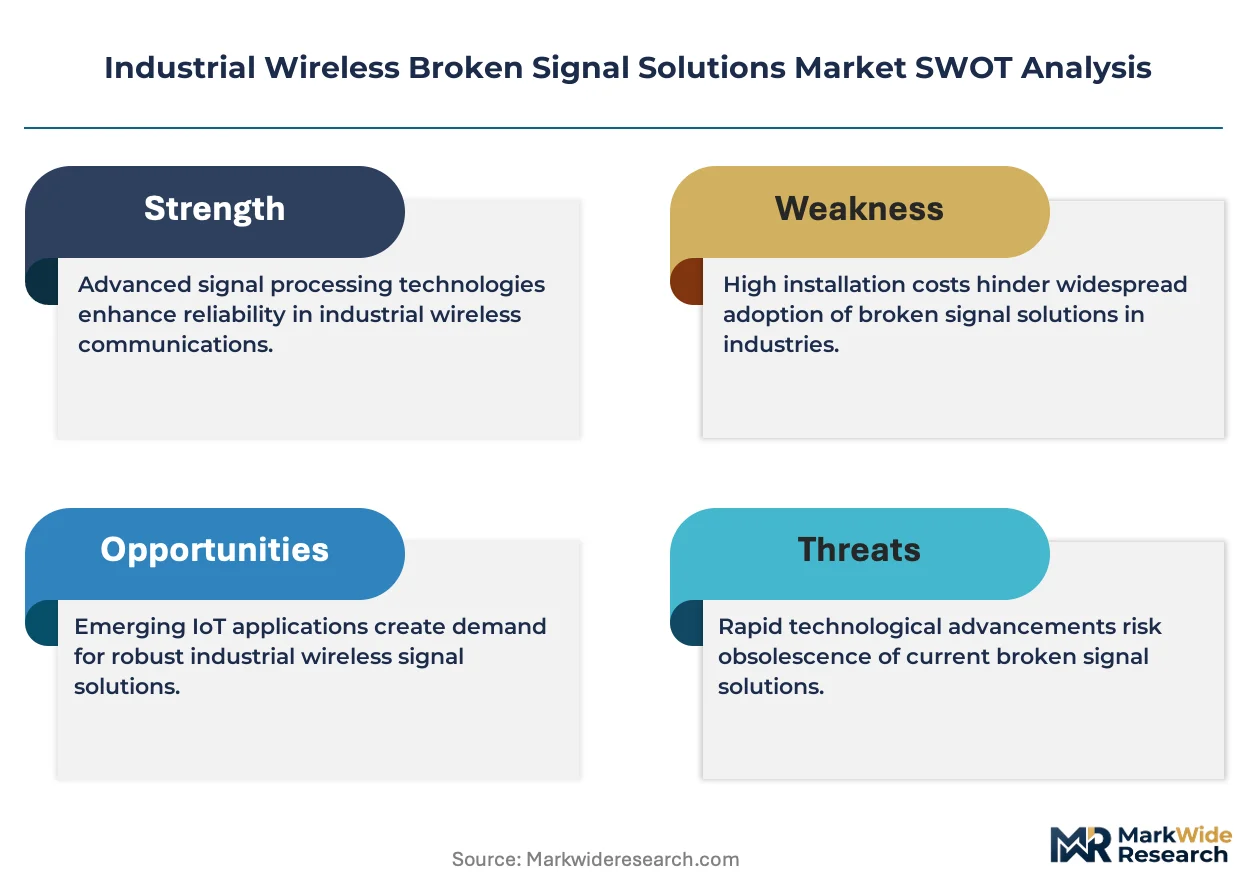
Industrial wireless broken signal solutions encompass hardware and firmware systems designed to detect, amplify, and restore degraded radio frequency transmissions in factory and field environments, typically operating across 2.4 GHz and sub-GHz industrial bands with ingress protection ratings of IP65 or higher to withstand corrosive and high-vibration conditions. The primary purpose is maintaining command-and-control continuity for distributed sensors, actuators, and mobile equipment where cable replacement is impractical. Repeaters and amplifiers capture the largest margin pools due to their deployment density in sprawling manufacturing sites, while LoRa-based signal converters represent the fastest-growing technology segment as utilities and agriculture adopt long-range, low-power telemetry. Edge deployment models are gaining share against cloud-centric alternatives because latency-sensitive broken-signal recovery must execute locally to prevent production-line stoppages.
The Federal Communications Commission shapes spectrum availability for industrial unlicensed bands in the United States, while the European Telecommunications Standards Institute governs harmonized radio equipment directives that determine market access for signal-boosting hardware across EU member states. China's Ministry of Industry and Information Technology enforces GB standards for wireless equipment used in explosive atmospheres, creating compliance barriers for imported broken-signal solutions. Stakeholders must monitor evolving spectrum reallocation proceedings and certify products against emerging cybersecurity frameworks for operational technology networks.
Market Dynamics
Industrial wireless broken signal solutions face mounting pressure from spectrum congestion as 5G private networks and Wi-Fi 6E deployments crowd the 2.4 GHz and 5 GHz bands that factory automation systems depend upon for uninterrupted telemetry.
Growth Catalysts
- EU Green Deal industrial decarbonization mandates:Energy-intensive plants in Germany's Ruhr cluster must retrofit legacy wireless infrastructure with signal-hardened architectures to maintain continuous emissions monitoring and asset tracking compliance.
- Oil and gas field digitization:Pipeline operators across North American shale basins deploy redundant wireless mesh networks with automatic signal recovery to eliminate telemetry dead zones in remote wellhead installations.
- LoRa-based signal converters:Utilities and precision agriculture operations adopt long-range, low-power telemetry modules that extend broken-signal recovery capabilities beyond traditional industrial frequency bands.
Market Restraints
- Semiconductor supply concentration:RF amplifier chip fabrication concentrates in Taiwan and South Korea, exposing repeater manufacturers to foundry capacity constraints and geopolitical shipment disruptions.
- GB standards compliance barriers:China's Ministry of Industry and Information Technology enforces explosive-atmosphere certification requirements that delay market entry for imported signal-boosting hardware by 12-18 months.
- Fiber optic substitution in greenfield sites:New industrial construction increasingly specifies physical layer redundancy through fiber rather than wireless signal recovery systems, compressing addressable market scope in developed economies.
Strategic Opportunities
- India's PLI scheme for industrial automation:Domestic manufacturing incentives attract signal-hardening hardware producers to establish local assembly for chemical and steel plant digitization projects in Gujarat and Maharashtra.
- Edge AI convergence with signal processing:Machine learning inference at the repeater level enables predictive failure detection before complete signal loss, creating premium pricing tiers for intelligent recovery modules.
- Direct-to-plant procurement platforms:Industrial distributors bypass traditional systems integrators through digital marketplaces that bundle broken-signal diagnostics with hardware procurement, shortening sales cycles for retrofit projects.
Industry Challenges
- RF engineering talent scarcity:Design of sub-GHz industrial radios requires specialized expertise in electromagnetic interference mitigation that outpaces university pipeline output across North America and Western Europe.
- Multi-standard certification timelines:Simultaneous FCC Part 15, ETSI EN 300 328, and MIIT SRRC approvals for global product launches extend time-to-revenue by 14-20 months.
- Legacy SCADA integration complexity:Proprietary protocols in decades-old distributed control systems resist seamless handoff to modern wireless signal recovery architectures without costly gateway middleware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Wireless Broken Signal Solutions Market |
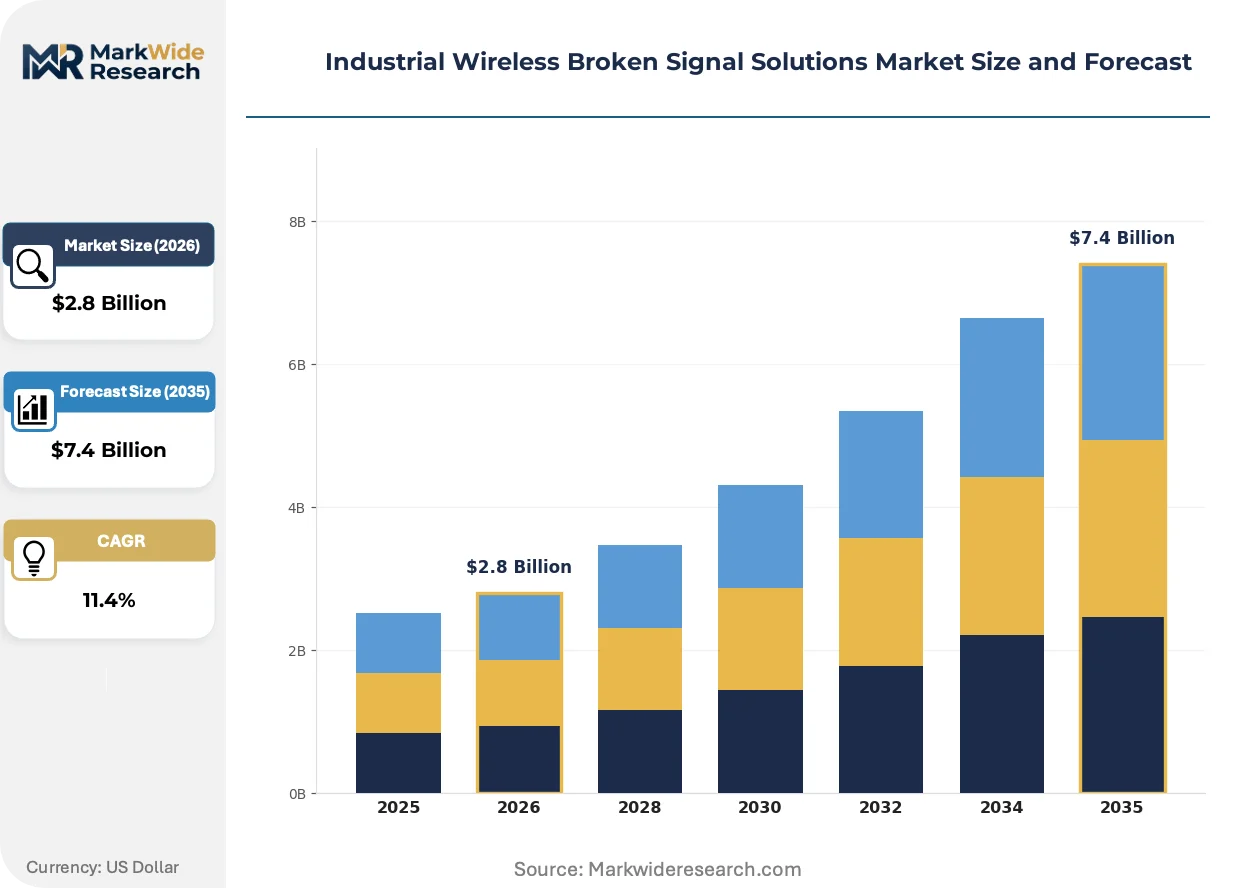
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Repeaters, Amplifiers, Signal Converters, Range Extenders Technology: Wi-Fi, Zigbee, Bluetooth, LoRa End User: Manufacturing, Oil & Gas, Mining, Agriculture Deployment Model: On-Premises, Cloud, Hybrid, Edge |
| Companies Covered | Siemens AG, Rockwell Automation, Honeywell International Inc., ABB Ltd., Schneider Electric SE, Cisco Systems, Inc., Emerson Electric Co., Moxa Inc., Belden Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Wireless Broken Signal Solutions Market Strategic Shifts
Signal recovery architectures are pivoting from reactive amplification to predictive intervention as edge computing capabilities embed directly into industrial repeaters and range extenders.
Mesh-networked intelligent repeaters with embedded spectrum analyzers are rewriting how manufacturing sites manage RF interference. Automotive plants in Stuttgart and Wolfsburg deploy these self-optimizing nodes to maintain sub-10 millisecond latency for mobile robot coordination. The technology compresses mean-time-to-repair for wireless dead zones from hours to seconds by autonomously rerouting traffic through alternative mesh paths.
The Federal Communications Commission's 2023 expansion of unlicensed 6 GHz spectrum for industrial IoT is reallocating capital toward dual-band signal recovery hardware. Factory automation buyers in Texas and Ohio now specify 6 GHz-capable repeaters to future-proof against 2.4 GHz saturation. Equipment vendors accelerate product roadmaps to capture first-mover advantage in this newly liberalized frequency allocation.
Maintenance procurement for wireless infrastructure is consolidating under single-source performance contracts that bundle hardware, firmware updates, and guaranteed uptime service levels. German chemical processors in Ludwigshafen and Leverkusen now contract directly with signal recovery specialists rather than maintaining fragmented vendor relationships. This shift compresses supplier margins while locking in multi-year recurring revenue streams for integrated solution providers.
Industrial Wireless Broken Signal Solutions Market Segmentation
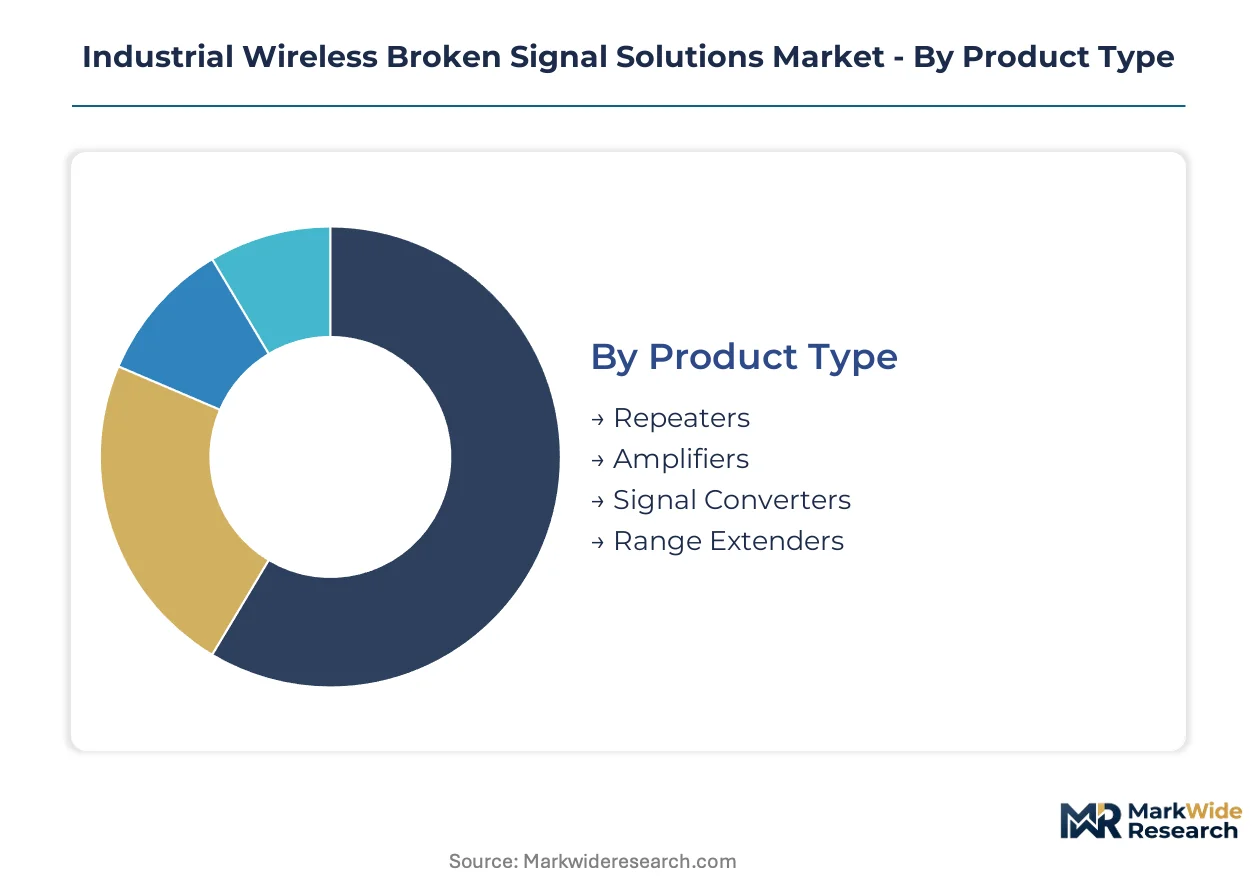
Capital allocation across industrial wireless broken signal solutions varies sharply by segment. Procurement teams weigh upfront hardware costs against operational continuity guarantees when selecting signal recovery architectures for hazardous and high-vibration environments.
Product Type:
Repeaters and amplifiers demand the heaviest capital commitment due to site-wide deployment density and IP65-rated enclosure requirements for corrosive manufacturing floors.
- Repeaters:Mesh-networked nodes with embedded spectrum analyzers capture and regenerate degraded RF transmissions across 2.4 GHz and sub-GHz industrial bands. German automotive plants in Stuttgart deploy these for sub-10 millisecond mobile robot coordination. Demand concentrates in sprawling chemical complexes where cable replacement is impractical.
- Amplifiers:RF power boosters with semiconductor-dependent supply chains from Taiwan and South Korea fabrication facilities. Pipeline operators across North American shale basins install redundant units to eliminate telemetry dead zones in remote wellhead installations. Foundry capacity constraints expose procurement timelines to geopolitical shipment disruptions.
- Signal Converters:Protocol translation modules bridging legacy SCADA systems to modern wireless architectures.
- Range Extenders:Directional antenna systems for linear infrastructure coverage including rail yards and conveyor corridors.
Repeaters absorb the bulk of installed capacity; signal converters are expanding most quickly.
Technology:
Technology selection determines spectrum licensing costs and interference resilience profiles for industrial telemetry networks.
- Wi-Fi:High-throughput 802.11 standards dominate indoor manufacturing floors with existing IT infrastructure. Texas and Ohio factory automation buyers now specify 6 GHz-capable hardware following FCC unlicensed spectrum expansion to future-proof against 2.4 GHz saturation. FCC Part 15 compliance timelines extend global product launches.
- LoRa:Sub-GHz long-range, low-power modulation for utilities and precision agriculture extending broken-signal recovery beyond traditional industrial frequency bands. ETSI EN 300 328 harmonized radio directives govern EU market access for these modules. Agricultural operations in water-stressed regions adopt for irrigation telemetry.
- Zigbee:Mesh-optimized protocol for battery-constrained sensor networks in hazardous area monitoring.
- Bluetooth:Short-range connectivity for mobile equipment diagnostics and technician handheld interfaces.
Wi-Fi carries the largest installed base; LoRa is climbing the fastest.
End User:
End-use verticals impose distinct certification burdens and environmental protection specifications on signal recovery hardware.
- Manufacturing:Automotive and chemical processors require IP65 or higher ingress protection for high-vibration, corrosive production environments. German Ruhr cluster steel and chemical plants digitize asset tracking under EU Green Deal decarbonization mandates, compelling retrofit of legacy wireless with signal-hardened infrastructure. Maintenance procurement is consolidating under single-source performance contracts.
- Oil & Gas:Hazardous-area classified equipment for explosive atmospheres demands GB standards compliance in China, delaying imported hardware market entry. MIIT enforcement creates 12-18 month certification barriers. North American shale operators deploy redundant mesh networks with automatic signal recovery.
- Mining:Underground and open-pit operations with severe multipath interference and equipment mobility requirements.
- Agriculture:Precision farming telemetry for soil moisture and equipment tracking across dispersed acreage.
Manufacturing commands the deepest installed base; oil and gas shows the steepest expansion trajectory.
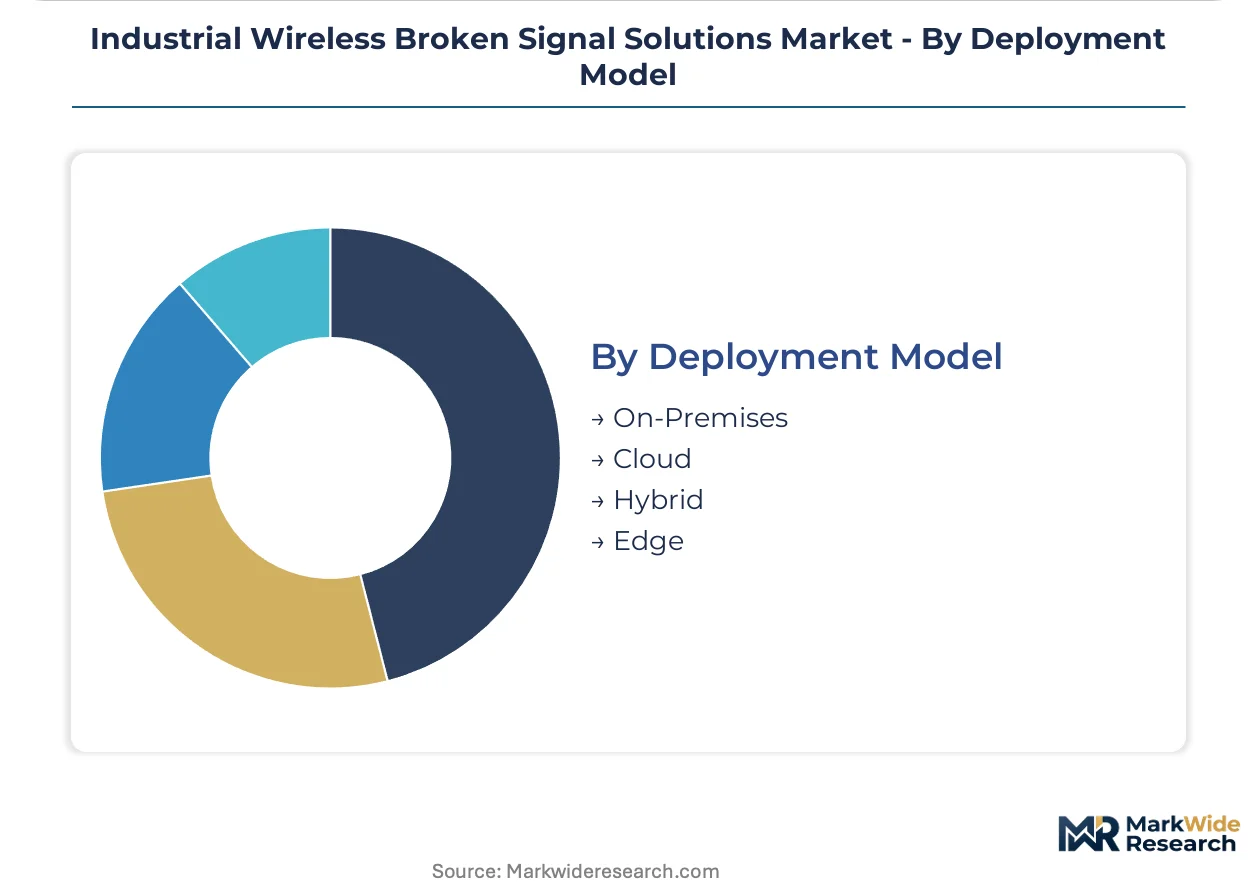
Deployment Model:
Deployment architecture determines latency sensitivity and data sovereignty compliance for command-and-control continuity.
- Edge:Local compute at repeater level enables predictive failure detection before complete signal loss, creating premium pricing tiers for intelligent recovery modules. Machine learning inference executes broken-signal recovery locally to prevent production-line stoppages. Edge deployment models are gaining share against cloud-centric alternatives for latency-sensitive applications.
- On-Premises:Dedicated infrastructure within facility firewalls for air-gapped operational technology networks. German chemical processors in Ludwigshafen and Leverkusen contract directly with signal recovery specialists rather than maintaining fragmented vendor relationships.
- Cloud:Centralized analytics platforms for non-time-critical diagnostics and fleet-wide performance benchmarking.
- Hybrid:Tiered processing splitting real-time recovery from archival analytics across edge and cloud layers.
Edge deployments capture the fastest share gains; on-premises retains the largest footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in German automation hubs and American industrial corridors, while consumption spreads across energy-intensive clusters in China, India, and the Middle East. Foundry-dependent RF amplifier supply chains anchor manufacturing in Taiwan and South Korea, creating geographic asymmetry between component fabrication and system integration.
United States
Shale basin pipeline operators drive demand for redundant mesh networks with automatic signal recovery capabilities. FCC unlicensed spectrum expansion into 6 GHz bands accelerates hardware refresh cycles across Texas and Ohio factory automation buyers. Houston energy corridor facilities deploy hazardous-environment signal recovery systems for remote wellhead telemetry.
Germany
Ruhr industrial cluster chemical and steel plants retrofit legacy wireless infrastructure under EU Green Deal decarbonization mandates. ETSI harmonized radio equipment directives govern market access for signal-boosting hardware across EU member states. Stuttgart automotive plants deploy mesh-networked intelligent repeaters for sub-10 millisecond mobile robot coordination.
China
MIIT enforces GB standards for wireless equipment in explosive atmospheres, creating 12-18 month certification delays for imported signal recovery solutions. Domestic manufacturing of industrial automation components accelerates under dual carbon goals for energy-intensive plant digitization. Yangtze River Delta chemical processors source locally assembled signal-hardening hardware to bypass import barriers.
India
PLI scheme incentives attract signal-hardening hardware producers to establish domestic assembly for chemical and steel plant digitization projects. Central Electricity Authority grid modernization mandates extend wireless telemetry requirements to utility infrastructure. Gujarat and Maharashtra industrial corridors concentrate procurement for retrofit wireless signal recovery systems.
Saudi Arabia
NEOM northwest development and Eastern Province oilfield digitization projects specify redundant wireless architectures for pipeline and refinery monitoring. National Industrial Development Center programs prioritize local content requirements for automation equipment procurement. Jubail industrial city petrochemical complexes deploy signal recovery systems for distributed sensor networks in corrosive processing environments.
Industrial Wireless Broken Signal Solutions Market Competitive Environment
The competitive structure tilts toward diversified industrial conglomerates with captive automation portfolios. Siemens AG and Rockwell Automation anchor the premium tier through integrated control system offerings, while specialized connectivity vendors occupy mid-market positions through protocol-agnostic hardware. Strategic moves concentrate on spectrum-ready product roadmaps and direct-to-plant procurement platform development.
Among diversified European industrial conglomerates, Siemens AG and ABB Ltd. exemplify the automation-anchored archetype, bundling signal recovery hardware with broader control system portfolios. Schneider Electric SE occupies a position within this tier through energy management integration. Honeywell International Inc. and Emerson Electric Co. represent the hazardous-environment specialist archetype, with company names signaling North American origins and industrial process heritage. Cisco Systems, Inc. and Belden Inc. anchor the network infrastructure vector, while Moxa Inc. exemplifies the dedicated industrial connectivity tier with geographic concentration suggested by its name structure.
| Leading Market Players |
|---|
| Siemens AG |
| Rockwell Automation |
| Honeywell International Inc. |
| ABB Ltd. |
| Schneider Electric SE |
| Cisco Systems, Inc. |
| Emerson Electric Co. |
| Moxa Inc. |
| Belden Inc. |
| Others |
Value Chain & Pricing Dynamics
RF engineering talent scarcity in North America and Western Europe widens pricing-tier spreads between premium intelligent recovery modules and economy-grade repeaters, as labor-cost differentials compound semiconductor foundry premiums for advanced signal-processing chipsets.
Pricing Analysis
Margin tightening in economy-tier repeaters reflects foundry capacity constraints at Taiwan and South Korea RF amplifier fabrication facilities. Three-tier pricing structure across premium, standard, and economy levels stratifies by IP65 ingress protection certification and edge AI inference capability. Cost-down pressure on standard-grade hardware accelerates because fiber optic substitution in greenfield industrial sites compresses addressable demand. Procurement teams at German chemical processors exhibit lowest price sensitivity due to EU Green Deal compliance mandates, while Indian PLI scheme beneficiaries drive hardest bargain for domestic assembly contracts.
Supply Chain Analysis
Refurbishment flows for failed mesh-networked repeaters create secondary component streams that feed aftermarket service operations in Texas and Ohio factory automation corridors. RF amplifier chip fabrication concentrates in Taiwan and South Korea, while system integration anchors in German Ruhr automation hubs and American industrial corridors. Foundry-dependent supply chains draw from gallium arsenide substrate suppliers and ceramic packaging facilities. Single-source vulnerability at sub-6 GHz semiconductor foundries exposes procurement timelines to geopolitical shipment disruptions. Distribution runs through direct-to-plant procurement platforms that bundle broken-signal diagnostics with hardware fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a technology-transition phase where edge AI convergence with signal processing displaces reactive amplification architectures in latency-sensitive manufacturing environments.
For Market Incumbents: Anchor premium positioning through captive edge AI inference capabilities embedded at repeater level, countering fiber optic substitution threats in greenfield construction. Deepen backward integration into RF amplifier chip design to mitigate Taiwan and South Korea foundry concentration risks. Secure ETSI EN 300 328 pre-certification for 6 GHz hardware roadmaps ahead of FCC unlicensed spectrum expansion. For New Entrants and Emerging Players: Direct-to-plant procurement platforms offer lowest-friction entry path into fragmented maintenance procurement relationships at German chemical processors. Target India's PLI scheme assembly incentives for chemical and steel plant digitization projects in Gujarat and Maharashtra. Pursue protocol-agnostic signal converter specialization to bypass legacy SCADA integration complexity that stalls diversified incumbent deployments. For Investors and Strategic Acquirers: Re-rating potential sits with edge-AI-enabled repeater specialists given predictive failure detection premium pricing tiers. Long-term viability favors vendors with spectrum-ready 6 GHz hardware roadmaps and direct contracting relationships with energy-intensive plant operators. Monitor FCC spectrum reallocation proceedings and MIIT GB standards enforcement timelines as inflection indicators for import-dependent market access.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Module Integration | Predictive failure detection at repeater level commands premium pricing from German automotive plants. |
| 6 GHz Hardware Roadmap Acceleration | FCC unlicensed spectrum expansion creates first-mover advantage for Texas and Ohio factory buyers. |
| Direct-to-Plant Procurement Platform | Digital marketplaces bypass systems integrators and compress sales cycles for retrofit projects. |
| Backward Integration into RF Design | In-house semiconductor specification reduces exposure to Taiwan and South Korea foundry constraints. |
| India PLI Scheme Local Assembly | Domestic manufacturing incentives unlock chemical and steel plant procurement in Gujarat and Maharashtra. |
Study Parameters
Independent corroboration across maintenance directors at German Ruhr chemical complexes, RF engineering leads at North American shale basin operators, and procurement officers at Indian PLI scheme beneficiaries underwrites the qualitative findings. Primary interviews with plant engineers, OEM procurement teams, and aftermarket service heads combined with secondary validation from FCC spectrum allocation dockets, ETSI harmonized radio equipment directives, MIIT GB standards filings, and SEC 10-K automation segment disclosures. Bottom-up deployment modeling triangulates against top-down industrial automation capex forecasts.
Comparable-period anchoring to historical retrofit wireless infrastructure spending patterns shapes the projection horizon across product type, technology, end-use vertical, and deployment model segmentation dimensions. CAGRs derive from unit economics of repeater deployment density in sprawling manufacturing sites and edge AI module attach rates. Forecast inputs incorporate spectrum reallocation timing assumptions and EU Green Deal decarbonization mandate compliance deadlines.
The model holds under stable semiconductor foundry capacity and regulatory certification timelines; deviation in geopolitical shipment disruptions or MIIT enforcement acceleration would shift hardware availability assumptions. Practitioners should monitor FCC Part 15 proceedings, ETSI EN 300 328 revision cycles, and India PLI scheme allocation announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
5G Wireless Ecosystem Market
Wireless Technologies
Europe Wireless Microphone Market
Wireless Technologies
Global Massive MIMO Market
Wireless Technologies
Femtocell Market
Wireless Technologies
Global in-Building Wireless Market
Wireless Technologies
5G Mmwave Technology Market
Wireless Technologies
Europe Fixed Wireless Access (FWA) Market
Wireless Technologies
Mobile WLAN Access Points Market
Wireless Technologies
Industrial Bluetooth Market
Wireless Technologies
Asia-Pacific Wi-Fi 6 Market
Wireless Technologies
5G Fixed Wireless Access Market
Wireless Technologies
Voice Over LTE (VOLTE) and Voice Over Wi-Fi Market
Wireless Technologies
Latin America Wireless Mesh Networking Market
Wireless Technologies
Wireless USB (WUSB) Devices Market
Wireless Technologies
Global Wireless Health Market
Wireless Technologies
Wigig Market