
 North America Structured Cabling Market | 2026-2036
North America Structured Cabling Market Size, Share, and Industry Trends Forecast 2026-2036
North America Structured Cabling Market Analytics
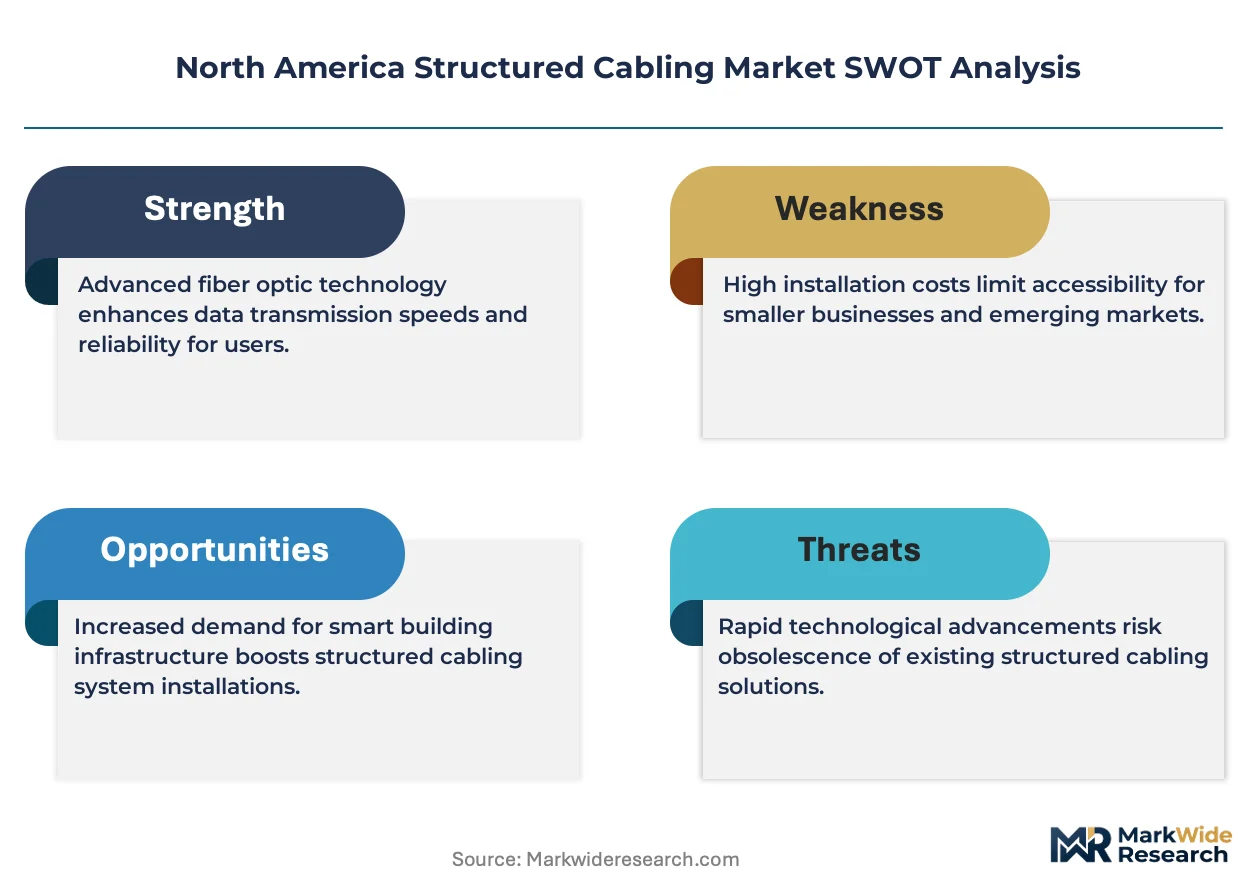
Copper-intensive Category 6A assemblies is decoupling from premium data center specifications as single-mode fiber claims dominant share in new hyperscale builds. Panduit Corp. leverages its vertical integration in fiber connectivity to sustain pricing power in enterprise backbone projects. Belden Inc. anchors its position through specialized broadcast and industrial Ethernet cable portfolios. Corning Incorporated dominates optical fiber supply to major cloud operators across the United States and Canada.
Structured cabling denotes the organized infrastructure of cables, connectors, and distribution hardware that transmits voice, data, and video signals within commercial and industrial buildings, typically engineered to support frequencies up to 500 MHz for copper and wavelengths of 1310–1550 nm for single-mode fiber. Fiber optic cable commands the fastest expansion trajectory among product types as cloud service providers deploy 400G and 800G optical links. Data center application generates the deepest margin pools due to density requirements and low-latency specifications, while commercial building retrofits represent a mature, replacement-driven segment with compressed pricing.
TIA standards, BICSI design methodologies, and NEC fire-rating requirements collectively shape product certification pathways and installation compliance across the United States and Canada. The FCC's broadband infrastructure programs and Canadian CRTC connectivity mandates are channeling public capital toward fiber-to-the-premises deployments that expand addressable demand. Stakeholders must weigh stranded copper assets against accelerated fiber refresh cycles as AI workloads redefine physical layer capacity planning.
Market Dynamics
Hyperscale data center operators across the United States and Canada are accelerating physical layer investments to support AI training clusters, forcing a generational shift from copper-dominant to fiber-centric infrastructure specifications.
Growth Catalysts
- FCC broadband infrastructure programs:Public capital flows into fiber-to-the-premises deployments across underserved U.S. communities, expanding addressable demand for outside plant and premises cabling.
- AI training cluster buildouts:Cloud service providers in Northern Virginia's Data Center Alley and Dallas-Fort Worth metroplex are commissioning 400G and 800G optical links at unprecedented density.
- TIA-942-B standards revisions:Updated data center telecommunications infrastructure guidelines are mandating higher-grade copper and fiber specifications for new construction.
Market Restraints
- Single-mode fiber supply concentration:Optical fiber manufacturing capacity concentrates among a limited set of North American and Asian suppliers, creating vulnerability to allocation constraints during demand surges.
- Copper commodity volatility:Category 6A and lower-grade copper cable assemblies face input cost pressure from fluctuating copper cathode prices, compressing margin stability for legacy product lines.
- Stranded copper asset risk:Enterprise facilities face accelerated depreciation of installed Category 5e and Category 6 infrastructure as AI workloads redefine bandwidth requirements.
Strategic Opportunities
- Canadian CRTC connectivity mandates:Federal broadband universal service objectives are channeling subsidy capital toward rural and remote fiber deployment, creating procurement volume outside major U.S. metro markets.
- Edge computing facility buildouts:Distributed AI inference nodes in secondary U.S. markets require low-latency fiber connectivity between metro and regional data centers.
- Converged infrastructure platforms:Integration of power-over-ethernet with fiber backbone systems is enabling single-contractor deployment models for smart building retrofits.
Industry Challenges
- BICSI-certified designer scarcity:Registered Communications Distribution Designer credential holders remain insufficient relative to project volume in hyperscale and enterprise segments, extending bid-to-award timelines.
- Multi-standard compliance complexity:Simultaneous adherence to NEC fire-rating requirements, TIA performance standards, and local electrical codes creates specification conflict during submittal review.
- Legacy system integration friction:Brownfield commercial buildings require careful coordination between existing copper horizontal cabling and new fiber backbone overlays without service disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Structured Cabling Market |
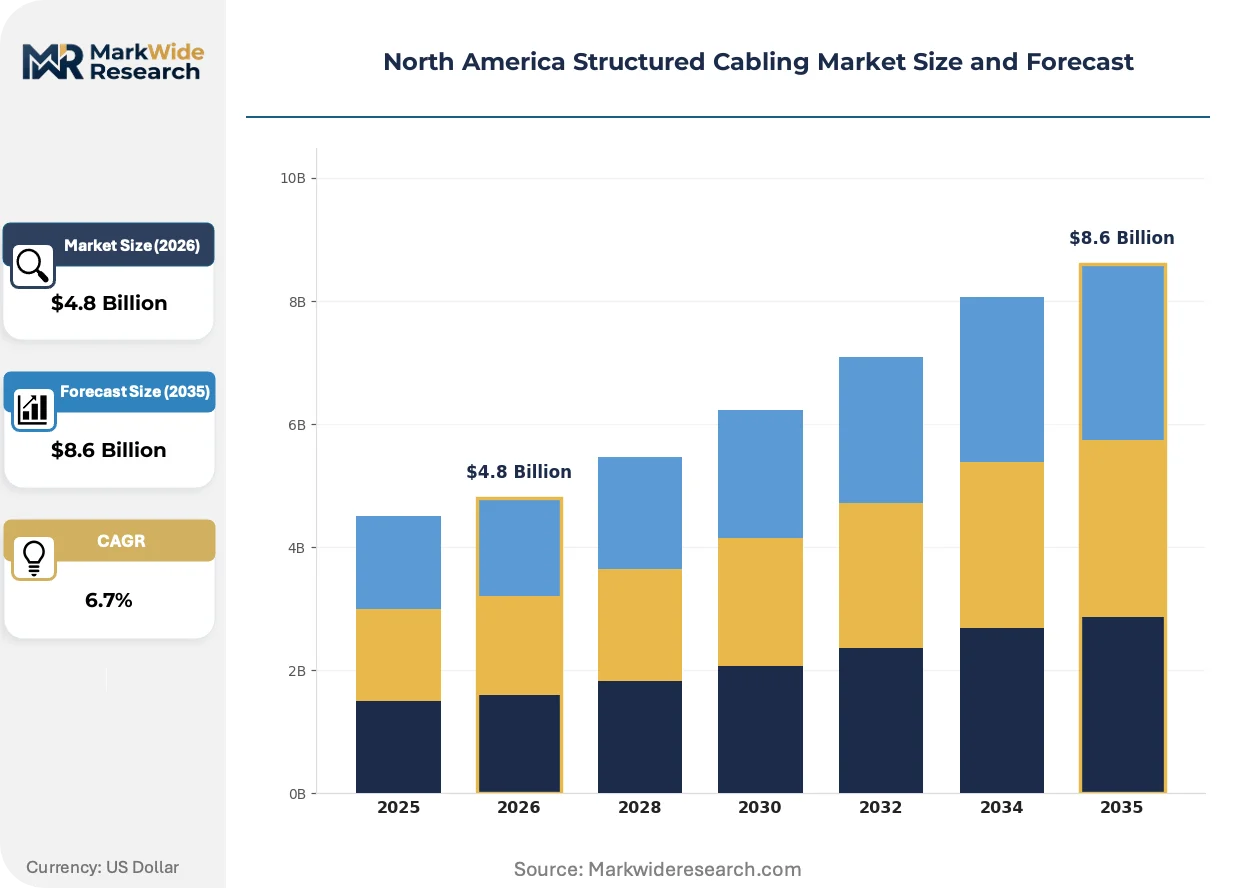
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
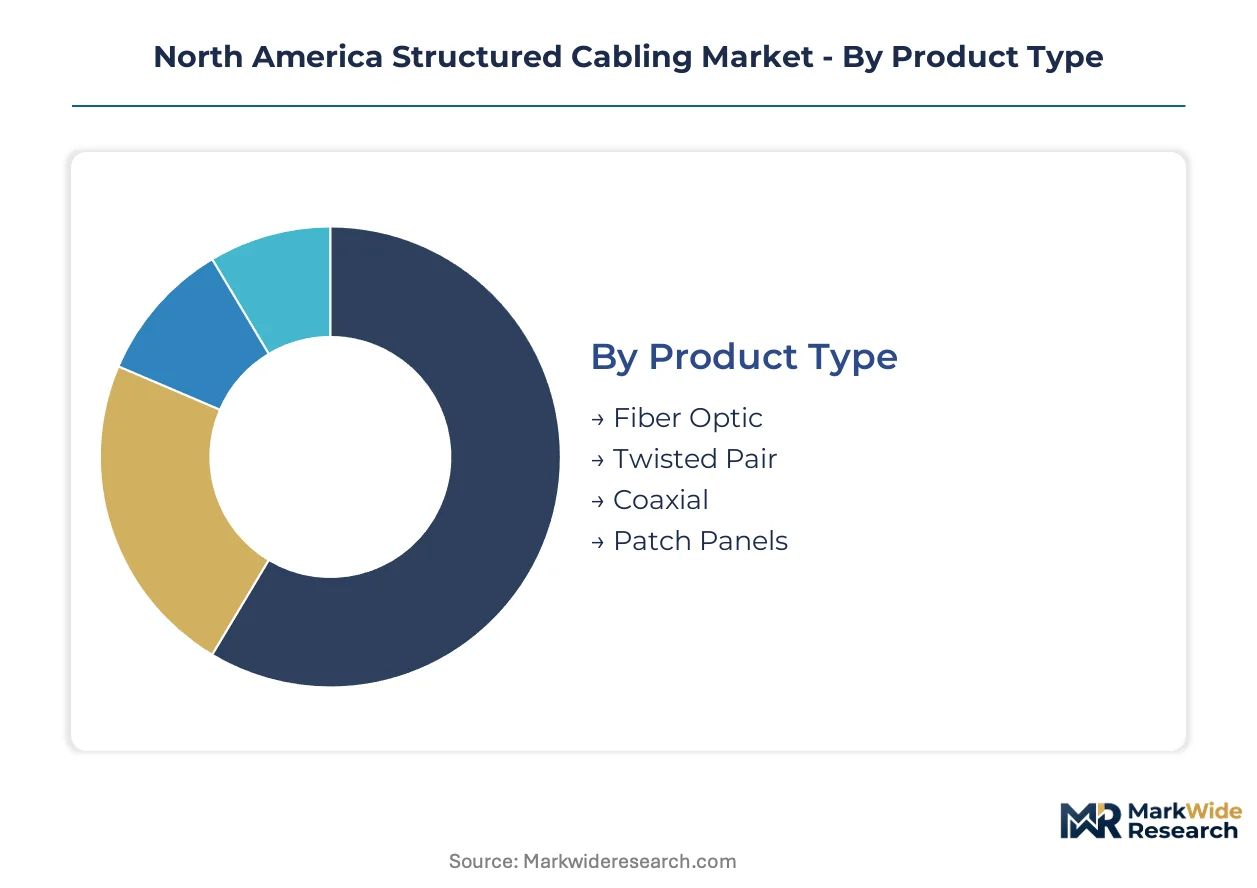
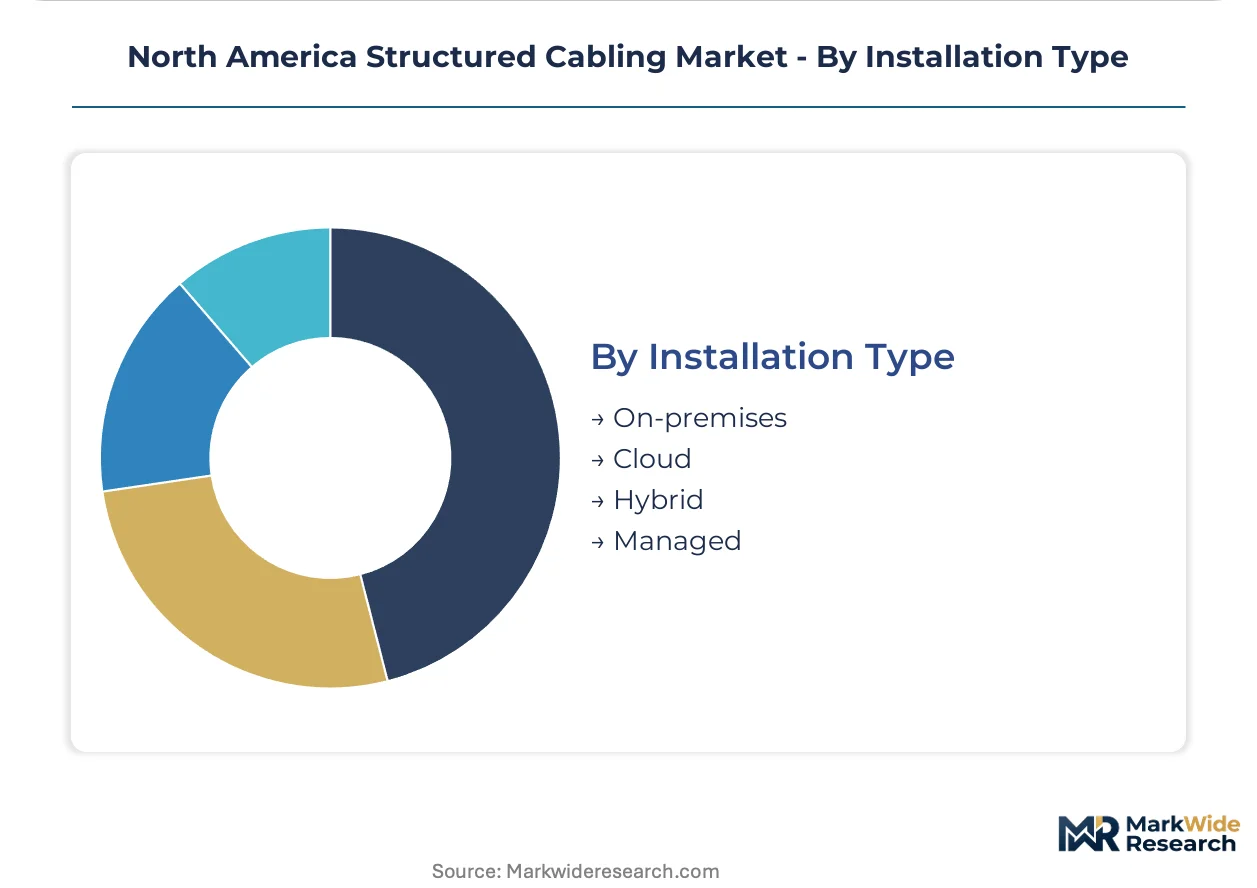
| Segmentation | Product Type: Fiber Optic, Twisted Pair, Coaxial, Patch Panels Application: Data Centers, Telecommunications, Residential, Commercial End User: Enterprises, Service Providers, Government, Educational Institutions Installation Type: On-premises, Cloud, Hybrid, Managed |
| Companies Covered | Panduit Corp., Legrand S.A., Belden Inc., Siemens AG, Schneider Electric SE, CommScope Inc., The Siemon Company, ABB Ltd., Corning Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Structured Cabling Market Evolving Landscape
Physical layer infrastructure across the United States and Canada is undergoing specification bifurcation, with hyperscale facilities adopting single-mode fiber dominance while enterprise retrofits navigate copper-to-fiber transition economics.
Single-mode fiber is unifying high-speed interconnect standards across AI training clusters. Cloud operators in Northern Virginia and Dallas-Fort Worth are specifying OS2 fiber exclusively for new 400G and 800G deployments. This technology is unifying previously fragmented optical link architectures, compressing vendor qualification lists and favoring suppliers with captive fiber draw towers.
Revisions to TIA-942-B telecommunications infrastructure standards are elevating minimum performance tiers for data center cabling. The updated framework mandates enhanced fiber characterization and stricter insertion loss budgets for optical links. Hyperscale operators in the United States are responding by pre-qualifying cable assemblies against draft standards ahead of formal adoption, compressing vendor certification cycles.
Enterprise procurement patterns are consolidating around design-build contractors with vertical capabilities in both copper and fiber. Mid-market commercial building owners in Canada are favoring single-source infrastructure contracts that bundle engineering, material supply, and installation. This consolidation is most visible in Toronto and Vancouver office retrofit markets, where landlord capital improvement budgets favor turnkey execution over multi-vendor coordination.
North America Structured Cabling Market Segmentation
Segmentation in North American structured cabling reveals diverging investment priorities between hyperscale operators pursuing fiber density and enterprise facilities managing copper transition economics. Understanding these splits enables suppliers to align certification roadmaps with distinct procurement timelines and margin profiles across installation types.
Product Type:
Fiber optic cable commands premium positioning while twisted pair retains volume dominance in legacy refresh cycles.
- Fiber Optic:Single-mode OS2 fiber supports 400G and 800G optical links in Northern Virginia's Data Center Alley. Cloud service providers specify this exclusively for new AI training clusters, displacing multimode alternatives in hyperscale specifications.
- Twisted Pair:Category 6A copper assemblies remain the workhorse for enterprise horizontal cabling in commercial building retrofits. Dallas-Fort Worth metroplex office landlords specify this for PoE-powered smart building upgrades where fiber-to-the-desk economics fail.
- Coaxial:Legacy broadband infrastructure in older Canadian multi-dwelling units still deploys hybrid fiber-coaxial drops.
- Patch Panels:High-density fiber patch panels with MPO-16 connectivity dominate hyperscale cross-connect architectures.
Today's leader: Twisted Pair. Tomorrow's challenger: Fiber Optic.
Application:
Data center specifications drive margin expansion while commercial and residential segments compete on installation efficiency.
- Data Centers:Hyperscale facilities in the United States mandate single-mode fiber backbones with strict insertion loss budgets per TIA-942-B draft standards. These installations generate the deepest margin pools due to density requirements and low-latency specifications.
- Telecommunications:FCC broadband infrastructure programs channel subsidy capital toward fiber-to-the-premises deployments across underserved U.S. communities. Outside plant cabling for these projects emphasizes environmental hardening and aerial deployment compatibility.
- Residential:Canadian CRTC connectivity mandates accelerate rural fiber deployment, creating procurement volume outside major metro markets.
- Commercial:Toronto and Vancouver office retrofits favor turnkey design-build contracts bundling copper and fiber infrastructure.
Data Centers extract the highest margins. Telecommunications offers the steepest expansion trajectory through public capital deployment.
End User:
Service providers consolidate procurement around qualified vendors while enterprises fragment spending across maintenance and upgrade cycles.
- Enterprises:Mid-market commercial building owners in Canada face accelerated depreciation of installed Category 5e infrastructure as AI workloads redefine bandwidth requirements. These organizations balance stranded copper asset risk against fiber refresh capital allocation.
- Service Providers:Cloud operators in Dallas-Fort Worth pre-qualify cable assemblies against draft TIA-942-B standards ahead of formal adoption. Their procurement compresses vendor certification cycles and favors suppliers with captive fiber draw towers.
- Government:Federal facilities in the United States require multi-standard compliance across NEC fire-rating requirements and TIA performance standards.
- Educational Institutions:University campus networks in the United States deploy converged infrastructure platforms integrating PoE with fiber backbone systems.
Service Providers concentrate demand among few qualified suppliers. Enterprises disperse spending across fragmented upgrade timelines.
Installation Type:
On-premises deployments retain specification control while cloud and hybrid models shift responsibility to operator-owned facilities.
- On-premises:Enterprise facilities in the United States maintain direct control over cabling infrastructure from demarcation to workstation. These installations require careful coordination between existing copper horizontal cabling and new fiber backbone overlays without service disruption.
- Cloud:Hyperscale operators internalize physical layer design, specifying OS2 fiber exclusively for 400G and 800G interconnects. Their internal standards often exceed TIA-942-B minimums, creating parallel certification tracks.
- Hybrid:Edge computing facilities in secondary U.S. markets require low-latency fiber connectivity between metro and regional data centers.
- Managed:Commercial building owners in Toronto favor single-source infrastructure contracts bundling engineering, material supply, and installation.
On-premises preserves customer specification authority. Cloud installations concentrate design power among operator engineering teams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data Center Alley in Northern Virginia anchors North American structured cabling demand, with hyperscale operators commissioning 400G and 800G fiber interconnects at unprecedented density. The region's infrastructure buildouts cascade procurement volumes across adjacent metro markets and into Canada.
United States
Hyperscale operators in Dallas-Fort Worth and Northern Virginia drive single-mode fiber specifications for AI training clusters. FCC broadband infrastructure programs channel subsidy capital toward fiber-to-the-premises deployments across underserved communities. Cloud facilities in Phoenix and Atlanta adopt TIA-942-B draft standards ahead of formal adoption.
Canada
CRTC connectivity mandates accelerate rural fiber deployment outside Toronto and Vancouver metro markets. Federal universal service objectives channel procurement volume toward prairie provinces and Atlantic Canada. Enterprise retrofits in Calgary and Montreal office districts favor turnkey design-build contracts bundling copper and fiber infrastructure.
Mexico
Nearshoring manufacturing expansion in Querétaro and Nuevo León generates demand for industrial Ethernet cabling in automotive and electronics facilities. Federal telecommunications reform programs promote fiber backbone deployment across central Mexico. Monterrey and Guadalajara emerge as secondary data center markets requiring low-latency connectivity.
North America Structured Cabling Market Competitive Landscape
Global majors compete with regional champions across specification-setting and procurement concentration. The vendor base stratifies into fiber specialists with captive draw towers, diversified connectivity conglomerates with broad copper portfolios, and regional system integrators with installation capabilities. Three archetypes dominate: hyperscale-preferred suppliers, enterprise turnkey providers, and industrial segment specialists. Competitive moves center on pre-qualification against draft TIA standards and backward integration into fiber manufacturing.
Within the fiber-specialist tier, Corning Incorporated and Panduit Corp. exemplify hyperscale-preferred positioning through captive supply chain control. Among diversified connectivity providers, Legrand S.A. and Schneider Electric SE occupy positions spanning enterprise and industrial segments. Belden Inc. represents the industrial-specialist archetype with focused broadcast and factory-automation portfolios.
| Leading Market Players |
|---|
| Panduit Corp. |
| Legrand S.A. |
| Belden Inc. |
| Siemens AG |
| Schneider Electric SE |
| CommScope Inc. |
| The Siemon Company |
| ABB Ltd. |
| Corning Incorporated |
| Others |
Value Network & Pricing Analysis
Single-mode fiber's displacement of copper-dominant architectures across hyperscale data centers simultaneously compresses production economies of scale for legacy cable assemblies and concentrates pricing power among suppliers with captive fiber draw capacity. This technology transition restructures input cost exposure, with copper cathode volatility now decoupled from premium data center specifications while optical fiber manufacturing consolidation shapes margin allocation across the value chain.
Pricing Analysis
Input-cost pass-through from copper cathode markets drives margin volatility in Category 6A and lower-grade assemblies, while single-mode fiber commands contract-based long-term offtake structures with hyperscale operators. Price differentiation hinges on TIA-942-B certification tier and volume scale, with cloud service providers exhibiting lowest price sensitivity due to insertion loss budget requirements. Cost compression in enterprise copper segments intensifies because stranded asset risk accelerates depreciation schedules for installed Category 5e infrastructure.
Supply Chain Analysis
Dual-sourcing requirements from hyperscale operators mandate multi-supplier qualification for OS2 fiber assemblies, yet manufacturing capacity concentrates in the United States, China, and Japan. Raw material dependencies span high-purity silica for fiber preforms, copper cathode for twisted pair, and specialized polymers for cable jacketing. Single-source vulnerability in optical fiber draw towers creates allocation risk during demand surges. Distribution runs through qualified contractor networks with BICSI-certified installation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential in this market rests on fiber density premiums displacing copper refresh economics, with hyperscale procurement concentration rewarding suppliers who pre-qualify against draft TIA standards ahead of formal adoption.
For Market Incumbents: Cement specification-setting authority by backward integration into fiber preform manufacturing and captive draw tower capacity. Defend against emerging entrants from Asian optical component specialists by accelerating TIA-942-B certification cycles. Channel control through exclusive distribution partnerships with BICSI-registered design firms represents the critical defensive lever. For New Entrants and Emerging Players: Enter via Canadian CRTC-subsidized rural fiber deployments, where procurement volume concentrates outside incumbent-dominated U.S. hyperscale markets. Target prairie provinces and Atlantic Canada for outside plant cabling contracts. Bundle environmental hardening expertise with aerial deployment compatibility as the primary go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among regional system integrators with installation capabilities but without captive fiber supply. Long-term viability favors suppliers who bridge enterprise retrofit demand and hyperscale fiber specifications. Watch hyperscale capital expenditure announcements from Northern Virginia and Dallas-Fort Worth operators as the signal indicating inflection in procurement volume.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Preforms | Captive silica supply secures allocation priority during hyperscale demand surges. |
| TIA-942-B Pre-Certification Investment | Early qualification compresses vendor selection cycles for AI training cluster builds. |
| Canadian Rural Deployment Partnership | CRTC subsidy flows create procurement volume outside saturated U.S. metro markets. |
| BICSI-Certified Designer Network Expansion | Scarce RCDD credentials extend bid-to-award timelines without qualified installation partners. |
| Converged Infrastructure Platform Development | PoE-fiber integration enables single-contractor smart building retrofit execution. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with data center engineering directors, BICSI-certified design consultants, hyperscale procurement officers, and contractor operations managers with secondary validation against TIA standards documentation, FCC broadband program disclosures, hyperscaler capital expenditure filings, and Canadian CRTC subsidy allocation records. Bottom-up installation volume estimates and top-down infrastructure spending analysis were triangulated to anchor market sizing.
Comparable-period anchoring linked projection models to historical hyperscale buildout cycles and enterprise refresh patterns across the analysis window. Segmentation dimensions modeled include product type, application vertical, end-user archetype, and installation configuration. CAGRs were derived from deployment density assumptions for AI training clusters and fiber-to-the-premises subsidy flows. Forecast inputs incorporated TIA-942-B adoption timelines and copper commodity price trajectory assumptions.
Inputs from hyperscale operator engineering teams and BICSI certification records were available through the study window; gaps in real-time Canadian rural deployment contracting data introduce uncertainty bands around prairie province volume estimates. Forecasts reflect documented assumptions regarding AI workload bandwidth requirements and subsidy program execution rates. Deviation in hyperscale capital expenditure commitment timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Europe Private 5G Network Market
Network Technology
Hyperconnectivity Market
Network Technology
Internet Protocol Address Management (IPAM) Market
Network Technology
Global Cloud Managed Wi-Fi Market
Network Technology
IT Connector Market
Network Technology
Virtual Router Market
Network Technology
Mobile Accelerator Market
Network Technology
Europe Video Conferencing Hardware Market
Network Technology
Wi-Fi Extender Market
Network Technology
Global Home Networking Device Market
Network Technology
Network Packet Broker Market
Network Technology
Philippines Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
Network Emulator Market
Network Technology
Optical Networking Market
Network Technology
Sand Lane Systems Market
Network Technology
Managed Switches Market