
 Sand Lane Systems Market | 2026-2036
Sand Lane Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Sand Lane Systems Market Analytics
Buyer concentration among European municipal wastewater utilities is realigning procurement patterns across the sand lane systems value chain. CDE Group leverages its wet processing expertise to dominate high-capacity grit removal installations for regional water authorities. Bruce Engineering anchors its position through specialized fabrication of wear-resistant sand lane components for Nordic infrastructure upgrades. Omega Foundry Machinery Ltd competes on precision casting technology that extends equipment lifespan in abrasive operating environments.
Sand lane systems comprise engineered channels, classifiers, and separation units designed to remove grit, sand, and mineral solids from influent streams at flow rates typically exceeding 100 liters per second. These systems prevent abrasion damage to downstream pumps, digesters, and dewatering equipment while enabling landfill diversion of recovered inorganic material. Conveyors and pumps represent mature product categories where margin pools have compressed due to standardized specifications across European utilities. Automation and sensor technology segments are expanding fastest as operators deploy real-time bed-level monitoring and variable-frequency drives to cut energy consumption at remote pumping stations.
EMA guidelines on pharmaceutical residue monitoring in wastewater, REACH restrictions on construction material composition, and the EU Urban Waste Water Treatment Directive collectively shape equipment specifications and replacement cycles across member states. National regulators in Germany and France now mandate energy efficiency benchmarking for new sand lane installations, favoring suppliers with integrated automation architectures. Stakeholders must weigh capex commitments against evolving EU Green Deal compliance thresholds for embodied carbon in infrastructure metals.
Market Dynamics
Automated sensor integration is compressing replacement cycles for legacy sand lane infrastructure across European municipal utilities, forcing equipment suppliers to bundle real-time monitoring capabilities with core separation hardware or face margin erosion.
Growth Catalysts
- EU Urban Waste Water Treatment Directive:Stringent discharge limits for combined sewer overflow systems are mandating grit removal upgrades in Germany, the Netherlands, and Belgium.
- Energy efficiency benchmarking:National regulators in France and Germany now require automated variable-frequency drives on new installations, accelerating demand for integrated control architectures.
- Rhine-Ruhr industrial corridor:Aging combined sewer infrastructure in this dense manufacturing zone requires continuous sand and grit removal capacity expansion.
Market Restraints
- Stainless steel price volatility:Abrasion-resistant alloy components constitute 35-45% of system fabrication costs, exposing margins to nickel and chromium market swings.
- REACH compliance burden:Restrictions on construction material composition extend certification timelines for imported castings and welded assemblies.
- Conveyor and pump commoditization:Standardized specifications across European utilities have compressed margin pools in mature product categories.
Strategic Opportunities
- EMA pharmaceutical residue monitoring:New wastewater testing protocols create demand for enhanced pre-treatment grit removal to protect downstream analytical sampling infrastructure.
- Scandinavian utility automation:Nordic water authorities are displacing manual desanding operations, opening white space for remote monitoring system providers.
- EU Green Deal embodied carbon thresholds:Compliance requirements for infrastructure metals favor suppliers with low-carbon supply chains and circular material certifications.
Industry Challenges
- Automation engineering talent scarcity:Utilities struggle to recruit PLC programmers and SCADA specialists capable of integrating legacy mechanical systems with digital control platforms.
- Legacy system interoperability:Retrofitting real-time bed-level sensors into 1980s-era concrete channels requires custom fabrication and extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sand Lane Systems Market |
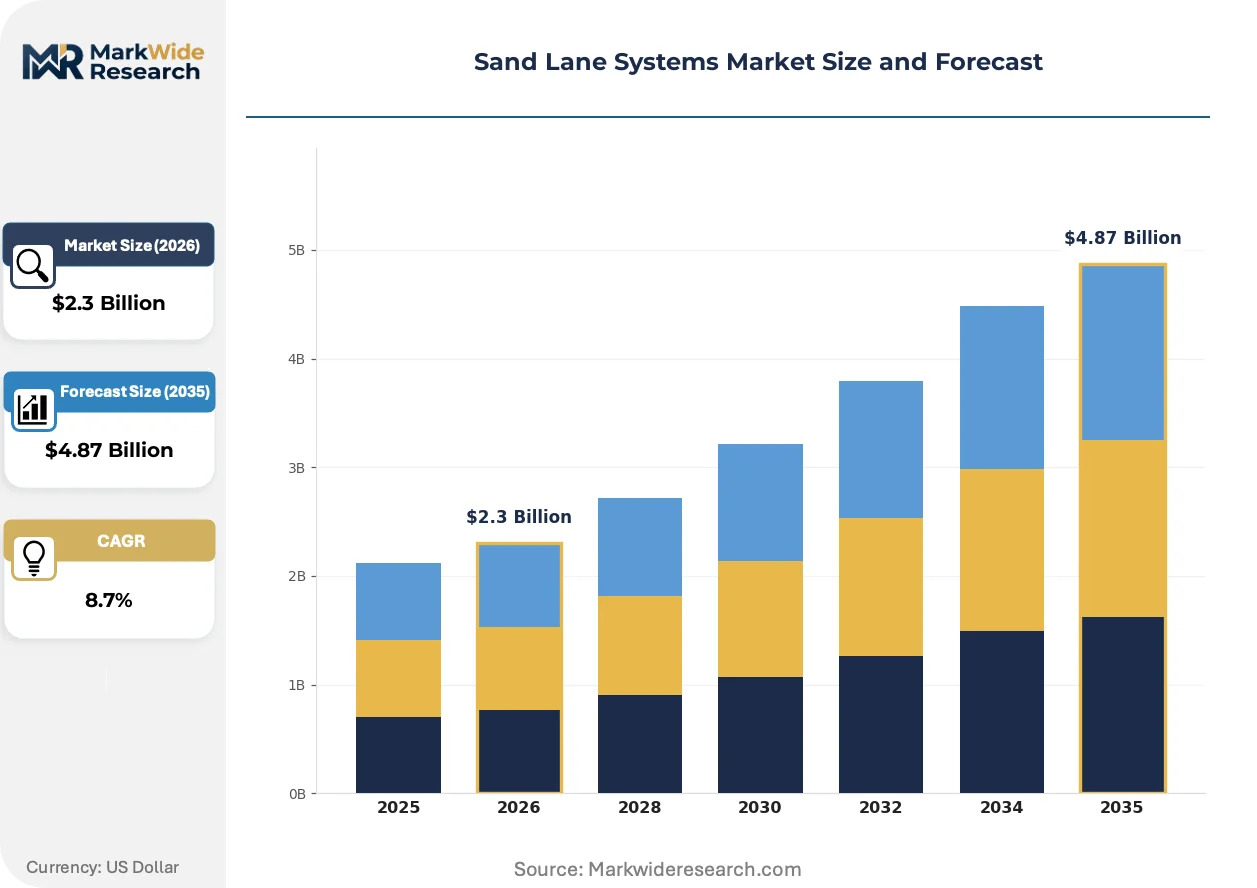
| Market Size in 2026 | $2.3 Billion |
| Market Size in 2035 | $4.87 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conveyors, Mixers, Pumps, Filters Application: Construction, Mining, Manufacturing, Environmental Technology: Automation, Robotics, IoT, Sensor Technology End User: Contractors, Engineers, Environmental Agencies, Manufacturers |
| Companies Covered | CDE Group, Bruce Engineering, Omega Foundry Machinery Ltd, Sahand Rikhtegar, Maitek Srl, Powerscreen, Matec Industries, Sand Separation Systems, Terex Washing Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sand Lane Systems Market Evolving Landscape
Digital twin technology and predictive maintenance algorithms are rewiring how European water utilities manage abrasive wear in high-flow grit separation systems, shifting capital allocation from reactive replacement to condition-based intervention.
Ultrasonic bed-level sensors paired with machine learning classification algorithms are rewriting maintenance economics for municipal sand lane operators. German utilities in North Rhine-Westphalia are deploying these systems at 40+ remote pumping stations. The technology is compressing emergency call-out frequency and extending classifier component lifecycles beyond traditional fixed-interval replacement schedules.
REACH restrictions on hexavalent chromium in surface coatings are forcing foundries to migrate toward trivalent alternatives and thermal spray ceramic overlays. ECHA enforcement of these substance restrictions is lengthening qualification timelines for wear-resistant castings. Suppliers with pre-certified low-toxicity coating processes are capturing specification preference in French and Dutch tender processes.
Performance-based service contracts are displacing traditional equipment-only procurement across Danish and Swedish municipal water boards. Contractors now guarantee grit removal efficiency rates and assume energy consumption risk for multi-year terms. This model concentrates vendor selection criteria on demonstrated operational data rather than upfront capital cost, favoring suppliers with extensive installed base telemetry.
Sand Lane Systems Market Segmentation
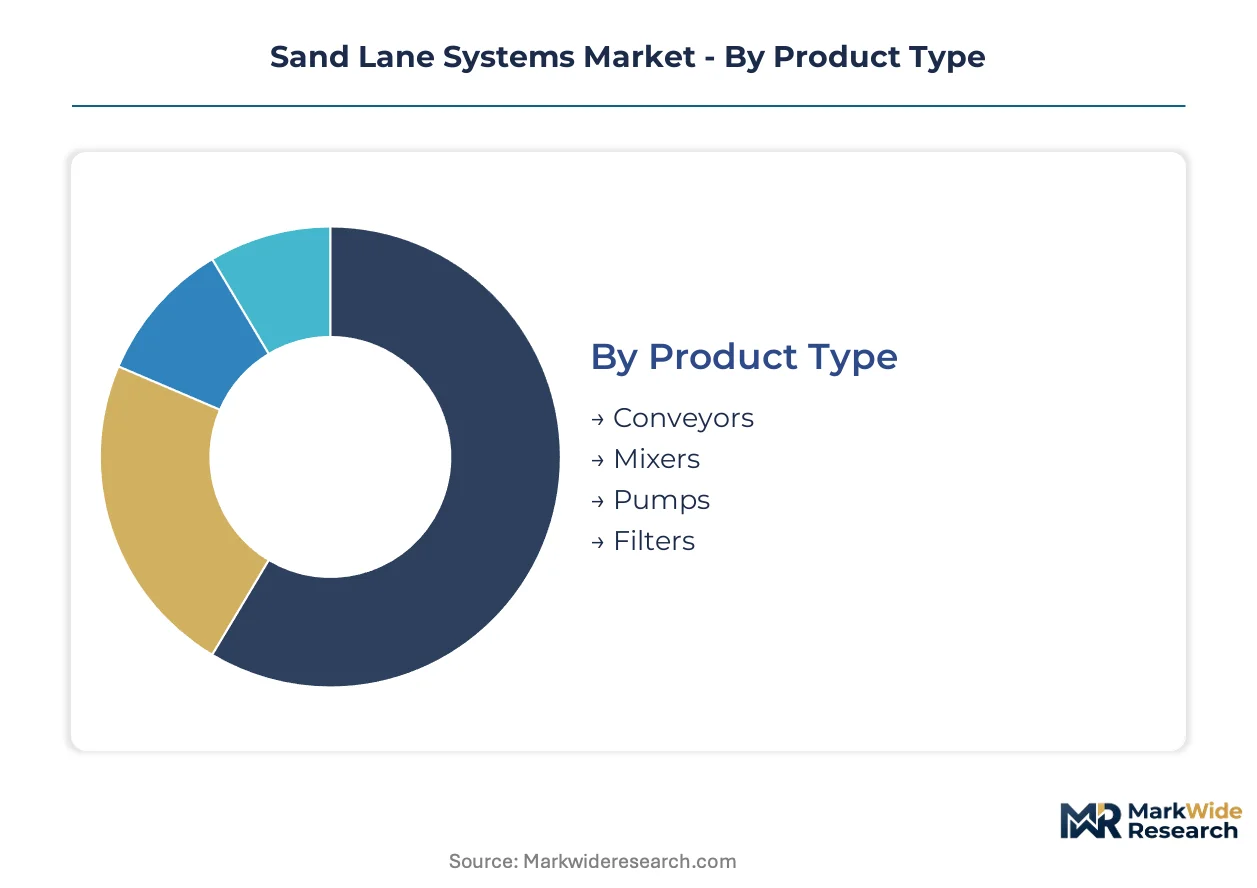
Sand lane systems serve divergent operational environments ranging from abrasive mining slurries to precision municipal wastewater flows. Procurement criteria vary sharply across these contexts, with mining buyers prioritizing wear resistance and water utilities demanding automated compliance documentation. Understanding segment boundaries clarifies where specification standards diverge and margin structures consolidate.
Product Type:
Capital intensity and replacement frequency separate buyers in this category, with continuous-process operators accepting higher upfront costs for extended service intervals.
- Conveyors:Belt and screw configurations transport separated grit from collection hoppers to dewatering or disposal points. German municipal utilities in the Rhine-Ruhr corridor specify abrasion-resistant alloys for these components to survive 20-year infrastructure amortization periods.
- Pumps:Centrifugal and positive-displacement units handle high-solids slurry at flow rates exceeding 100 liters per second. Demand clusters in Dutch polder drainage systems where low-head, high-volume operation meets strict energy efficiency benchmarks.
- Mixers:Paddle and jet systems maintain suspension of dense mineral solids prior to classification. Scandinavian environmental contractors specify these for landfill leachate pre-treatment installations.
- Filters:Screen and media-based units capture fine particulates downstream of primary separation. French water authorities deploy these to protect downstream membrane bioreactors from abrasive damage.
Conveyors lead volumes today; pumps are gaining share fastest through variable-frequency drive retrofits.
Application:
Regulatory exposure and project scale distinguish procurement patterns, with environmental mandates driving standardization and private mining operators tolerating customization.
- Environmental:Municipal wastewater and industrial effluent treatment applications dominate European installed base. The EU Urban Waste Water Treatment Directive mandates grit removal for combined sewer overflow compliance, concentrating demand in Belgium, Germany, and the Netherlands.
- Construction:Tunnel boring and foundation dewatering operations require mobile, high-throughput sand separation. Nordic infrastructure projects specify these systems for spoil management in sensitive groundwater zones.
- Mining:Mineral processing and tailings management applications demand extreme abrasion resistance. Finnish aggregate producers specify hardened steel components for 24/7 slurry processing duty.
- Manufacturing:Foundry sand reclamation and metal finishing operations generate captive demand for closed-loop grit recovery. German automotive suppliers deploy these to meet REACH restrictions on waste disposal.
Environmental applications command the largest installed base; construction is expanding most quickly through tunneling investment in the Alps and Scandinavia.
Technology:
Integration complexity and technical support requirements fragment the buyer base, with large utilities internalizing automation expertise while smaller operators outsource system architecture.
- Automation:PLC-controlled variable-frequency drives and automated valve sequences optimize energy consumption at remote pumping stations. French regulators now mandate this capability for new installations.
- Sensor Technology:Ultrasonic bed-level monitors and flow meters enable condition-based maintenance. North Rhine-Westphalia utilities deploy these at 40+ sites to compress emergency call-out frequency.
- IoT:Cloud-connected telemetry aggregates operational data across distributed asset portfolios. Danish municipal water boards use these platforms to underpin performance-based service contracts.
- Robotics:Automated desanding arms and self-cleaning rake mechanisms displace manual labor in hazardous channel environments. Swedish utilities pilot these for unmanned operation at remote combined sewer overflow structures.
Sensor technology dominates current procurement volumes; IoT connectivity shows the steepest expansion trajectory as performance contracting spreads.
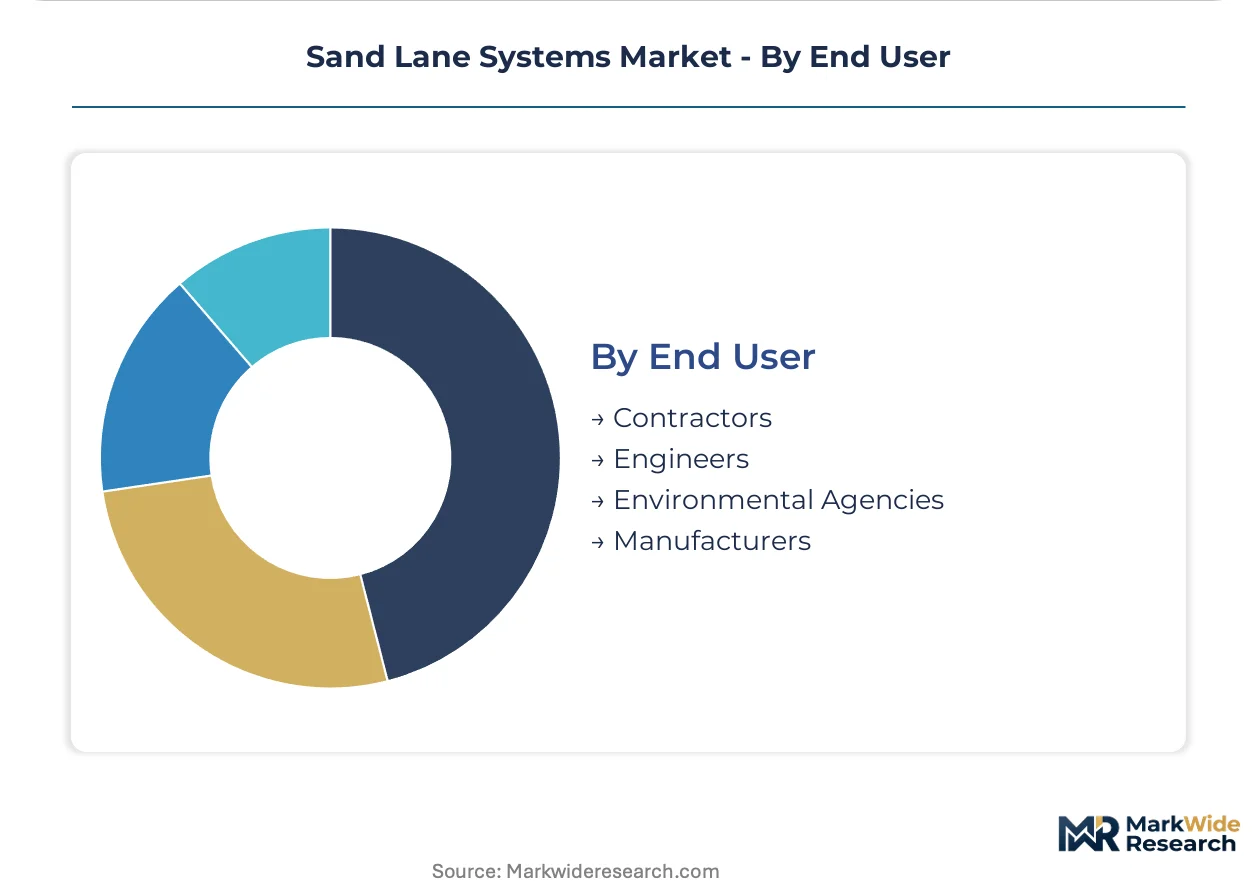
End User:
Technical sophistication and procurement authority determine specification influence, with engineering consultants filtering vendor access to institutional buyers.
- Environmental Agencies:Municipal water authorities and river basin districts specify equipment for compliance-mandated infrastructure. German Landesbetriebe and Dutch waterboards dominate European tender volumes.
- Engineers:Consulting firms and design-build contractors translate regulatory requirements into technical specifications. French and Dutch engineering consultancies increasingly embed lifecycle cost criteria in equipment selection.
- Contractors:Construction and remediation firms procure mobile systems for temporary dewatering and spoil processing. Alpine tunneling consortia drive demand for rapid-deployment containerized units.
- Manufacturers:Industrial facility operators specify captive sand lane systems for process water recycling. German automotive foundries invest in these to secure supply chain continuity amid water stress regulations.
Environmental agencies anchor procurement volumes today; engineering consultancies are capturing disproportionate specification influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys sand lane infrastructure at triple the per-capita density of France, reflecting divergent sewer system ages and regulatory enforcement timelines across the EU's largest economies.
Germany
The Rhine-Ruhr industrial corridor drives replacement demand for aging combined sewer overflow systems. The EU Urban Waste Water Treatment Directive mandates grit removal upgrades in North Rhine-Westphalia. Municipal utilities in Düsseldorf and Essen are automating sand separation at 40+ remote pumping stations.
Netherlands
Dutch polder drainage systems require continuous sand and grit removal to maintain strict discharge standards. REACH restrictions on construction material composition extend equipment certification timelines. Waterboards in the Randstad region specify energy-efficient variable-frequency drives for new installations.
Belgium
Flemish environmental agencies prioritize grit removal infrastructure to meet EU wastewater discharge limits. National regulators mandate automated monitoring capabilities for municipal treatment plants. The Port of Antwerp industrial zone requires high-capacity sand separation for combined sewer systems.
France
French water authorities embed lifecycle cost criteria in equipment procurement decisions. ECHA enforcement of hexavalent chromium restrictions favors suppliers with pre-certified coating processes. Engineering consultancies in Île-de-France specify integrated automation architectures for new sand lane installations.
Sweden
Swedish municipal water boards displace manual desanding operations through performance-based service contracts. Nordic utilities pilot automated desanding arms for unmanned operation at remote structures. The Stockholm metropolitan area concentrates demand for remote monitoring system providers.
Sand Lane Systems Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the sand lane systems value chain. The vendor base organizes into three tiers: global wet processing conglomerates with multi-industry portfolios, regional fabrication specialists serving municipal utilities, and precision casting foundries supplying wear-resistant components. Consolidation pressure is accelerating as automation requirements favor integrated system providers over component suppliers. Strategic moves center on bundling sensor technology with core separation hardware and securing low-carbon supply chain certifications for EU Green Deal compliance.
Among UK-based equipment specialists, CDE Group and Omega Foundry Machinery Ltd occupy positions representing wet processing expertise and precision casting capabilities respectively. Bruce Engineering exemplifies the regional fabrication archetype serving Nordic infrastructure upgrades. These three entities anchor the competitive landscape across distinct capability vectors: system integration, component durability, and geographic specialization.
| Leading Market Players |
|---|
| CDE Group |
| Bruce Engineering |
| Omega Foundry Machinery Ltd |
| Sahand Rikhtegar |
| Maitek Srl |
| Powerscreen |
| Matec Industries |
| Sand Separation Systems |
| Terex Washing Systems |
| Others |
Value Network & Pricing Analysis
Automation-certification bifurcation between premium integrated systems and commodity conveyors manifests in divergent margin structures across German municipal tenders and Nordic mobile installations. Price premiums for real-time sensor architectures reflect supply chain concentration in specialized PLC engineering pools, while standardized pump procurement draws from distributed foundry networks across Central Europe.
Pricing Analysis
Capacity additions in Poland and Czech Republic are reshaping price floors for abrasion-resistant alloy components, compressing margins for mid-tier fabricators serving Dutch waterboards. Three-tier pricing structure across premium automation-integrated, standard energy-efficient, and economy manual systems differentiates procurement outcomes in French municipal tenders. Cost compression in conveyor segments is intensifying because REACH certification timelines extend qualification costs for imported castings. Small Alpine contractors exhibit highest price sensitivity; German Landesbetriebe prioritize lifecycle cost over upfront capital outlay.
Supply Chain Analysis
Freight cost differentials between Baltic port entry and overland routing from Southern Europe influence component sourcing patterns for Scandinavian utility upgrades. Manufacturing concentration centers on Germany, Italy, and Poland for wear-resistant castings, with precision sensor modules drawing from Netherlands and Switzerland. Raw material dependencies span nickel-chromium alloys, tungsten carbide overlays, and ceramic thermal spray coatings. Single-source vulnerability persists in specialized ultrasonic sensor supply. Distribution runs through engineering consultancies that filter vendor access to institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between Germany's stringent energy benchmarking mandates and Poland's expanding fabrication capacity, where regulatory compliance costs diverge by approximately one certification cycle.
For Market Incumbents: Anchor market position through backward integration into low-carbon alloy supply chains and pre-certified coating processes that compress REACH qualification timelines. CDE Group and Omega Foundry Machinery Ltd demonstrate how captive casting capabilities defend against stainless steel price volatility. Prioritize automation engineering talent acquisition to offset PLC programmer scarcity threatening commissioning schedules. For New Entrants and Emerging Players: EU Green Deal embodied carbon thresholds in Germany open a window for low-carbon supply chain specialists to penetrate municipal tender processes. Scandinavian utility automation presents the most penetrable white space, where performance-based contracting shifts vendor selection toward operational data rather than capital cost. Target Danish and Swedish water boards with remote monitoring system bundles that displace manual desanding operations. For Investors and Strategic Acquirers: Consolidation pressure builds where automation requirements favor integrated system providers over component specialists lacking sensor technology capabilities. Mid-cap fabrication specialists with pre-certified REACH processes and established telemetry installed bases represent prime acquisition targets. Monitor ECHA enforcement intensity on hexavalent chromium restrictions as inflection indicator for coating process substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Technology Integration | Ultrasonic bed-level monitors bundled with classifiers capture premium positioning in German municipal tenders. |
| Low-Carbon Supply Chain Certification | EU Green Deal compliance for infrastructure metals secures specification preference in Dutch waterboard procurement. |
| Performance-Based Service Contracts | Danish municipal water boards now guarantee grit removal efficiency rates across multi-year operational terms. |
| REACH Pre-Certification Investment | Trivalent chromium coating processes shorten qualification timelines for wear-resistant casting suppliers. |
| Automation Engineering Acquisition | PLC programming and SCADA integration capabilities address talent scarcity constraining utility retrofit timelines. |
Research Methodology
Coverage spans Western Europe and Scandinavia, with primary inputs from each regional cluster combined with secondary validation. Interviews engaged municipal water authority procurement directors, plant engineers at combined sewer overflow facilities, foundry operations managers, and engineering consultancy specification leads. Secondary sources included EU Urban Waste Water Treatment Directive compliance filings, ECHA substance restriction databases, national energy efficiency benchmarking reports, and municipal tender documentation from German Landesbetriege and Dutch waterboards. Bottom-up equipment unit economics triangulate against top-down infrastructure investment forecasts.
Granularity-level modeling disaggregates volume and value across product type, application, technology, and end user dimensions throughout the projection horizon. Segmentation by automation integration intensity, energy efficiency tier, and geographic regulatory cluster captures specification divergence. CAGRs derive from equipment replacement cycle analysis and infrastructure investment pipeline assessment. Forecast inputs incorporate REACH enforcement timelines, EU Green Deal embodied carbon threshold phase-ins, and municipal automation adoption curves.
Revisions become necessary when ECHA substance restriction enforcement intensifies, nickel and chromium commodity volatility exceeds historical bands, or municipal budget austerity delays infrastructure replacement cycles. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
BYOD Market
Network Technology
Global Industrial Ethernet Switch Market
Network Technology
Wimax Solutions Market
Network Technology
Passive Optical LAN (POL) Market
Network Technology
Managed Switches Market
Network Technology
US Private 5G Network Market
Network Technology
Global Carrier Ethernet Equipment Market
Network Technology
UK Fixed Connectivity Market
Network Technology
Session Border Controller (SBC) Market
Network Technology
Network Fault Monitoring Tools Market
Network Technology
DHCP and IP Address Management Market
Network Technology
Mobile Hotspot Router Market
Network Technology
Europe Self-Healing Networks Market
Network Technology
Wi-Fi Extender Market
Network Technology
Philippines Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
IT Connector Market