
 Global Vasculitis Treatment Market | 2026-2036
Global Vasculitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vasculitis Treatment Market Foresight
Hospital-based infusion centers is consolidating as the dominant site of care for biologic vasculitis therapies. F. Hoffmann-La Roche Ltd leverages its established rheumatology franchise to sustain prescriber loyalty across academic medical centers. AbbVie Inc. anchors its position through deep immunology expertise and broad payer contracts. Bristol-Myers Squibb Company differentiates via its inflammation and immunology pipeline breadth.
Vasculitis treatment encompasses pharmacologic management of blood vessel inflammation through immunomodulation, targeting B-cell pathways, cytokine signaling, and coagulation cascades to prevent end-organ ischemia and necrosis. Biologics command premium positioning due to targeted mechanism of action and superior relapse-free survival compared to conventional immunosuppressants. Immunosuppressants retain substantial volume in induction protocols where cost constraints limit biologic access. Intravenous delivery dominates biologic administration while oral glucocorticoids remain foundational for acute flare management across all therapy areas.
FDA orphan drug designations and EMA PRIME eligibility frameworks incentivize development for rare vasculitis subtypes, compressing timelines from first-in-human to conditional approval. REACH compliance and ISO 13485 quality standards govern manufacturing of parenteral biologics, raising barriers for contract manufacturers serving European and Asian markets. Stakeholders must monitor how biosimilar entry into rituximab and tocilizumab categories reshapes pricing power and site-of-care economics.
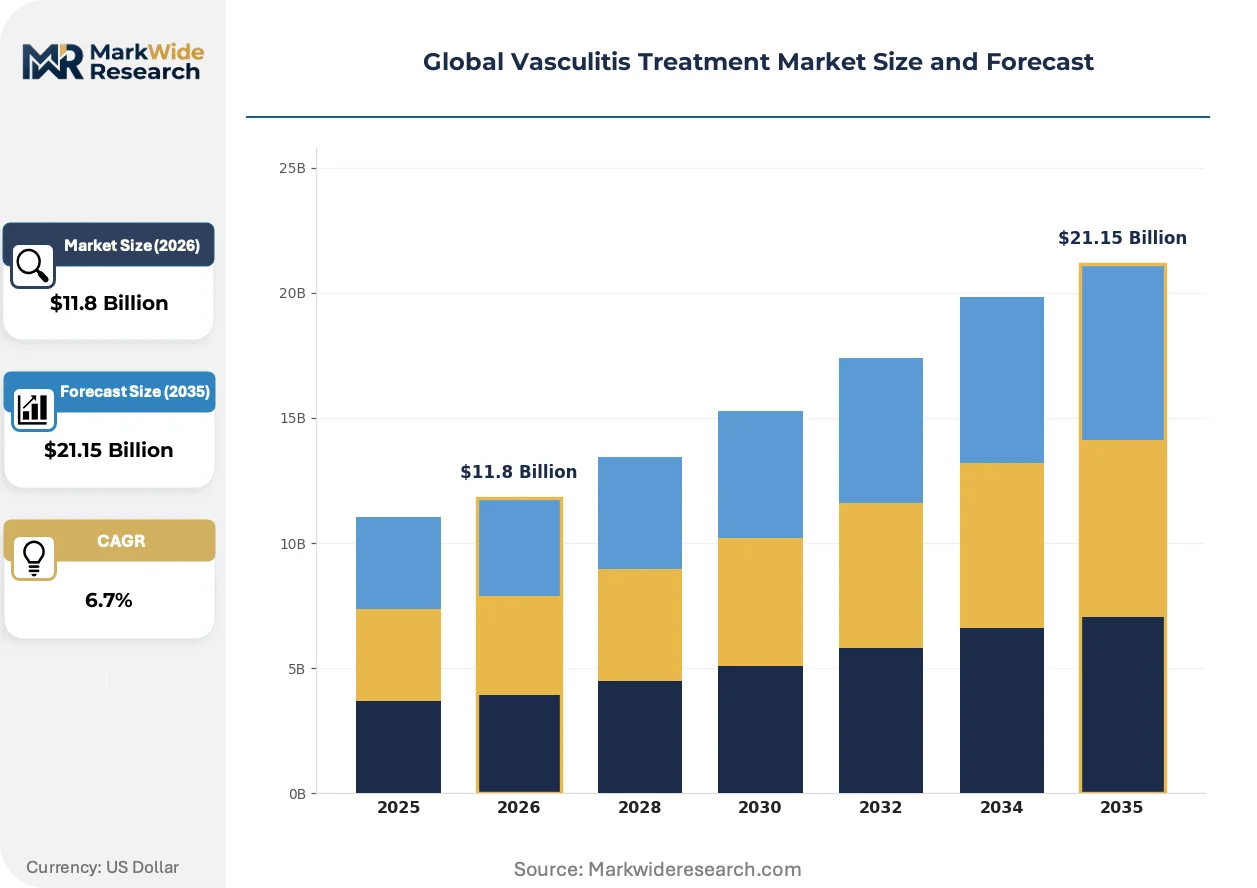
Market Dynamics
Accelerated FDA and EMA approval pathways for orphan autoimmune indications are compressing clinical trial timelines and redistributing R&D investment toward rare vasculitis subtypes, fundamentally altering competitive entry dynamics.
Growth Catalysts
- EMA PRIME Eligibility:Priority medicines designation for rare vasculitis subtypes compresses regulatory review timelines and attracts venture funding into early-stage immunology pipelines.
- Specialty Clinic Expansion:Tertiary referral networks in the United States, Germany, and Japan are consolidating biologic infusion capacity, concentrating prescriber influence and patient volume.
- Biosensor-Enabled Monitoring:Wearable inflammation biomarker tracking is converging with telemedicine platforms to enable remote disease activity surveillance between infusions.
Market Restraints
- Plasma-Derived Protein Supply Concentration:Fractionation capacity for immunoglobulin concentrates in limited European and North American facilities creates batch-to-batch availability volatility.
- REACH Compliance Burden:European chemical safety registration requirements for novel biologic excipients extend formulation development timelines by 18-24 months.
- Glucocorticoid Sparing Protocols:Established corticosteroid tapering regimens in induction therapy limit immediate biologic penetration despite superior relapse-free survival profiles.
Strategic Opportunities
- Subcutaneous Formulation Migration:Self-administered biologic delivery bypasses hospital infusion center capacity constraints and captures patient preference in maintenance-phase therapy.
- Japan's Sakigake Designation:Early approval pathway for innovative regenerative medicines and biologics enables conditional market entry with reduced Phase III data requirements.
- Real-World Evidence Integration:Electronic health record aggregation across academic medical centers is reshaping post-market surveillance and label expansion strategies.
Industry Challenges
- Immunology Specialist Workforce Constraints:Fellowship-trained vasculitis clinicians concentrate in major metropolitan academic centers, limiting rural and community hospital access to protocol-driven care.
- Cold Chain Integrity at Last Mile:Temperature excursions during biologic transport to satellite infusion suites compromise product potency and trigger batch quarantine protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vasculitis Treatment Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $21.15 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glucocorticoids, Immunosuppressants, Biologics, Anticoagulants Therapy Area: Granulomatosis with Polyangiitis, Microscopic Polyangiitis, Eosinophilic Granulomatosis, Giant Cell Arteritis End User: Hospitals, Specialty Clinics, Diagnostic Laboratories, Research Institutes Delivery Mode: Oral, Intravenous, Subcutaneous, Inhalation |
| Companies Covered | F. Hoffmann-La Roche Ltd, AstraZeneca plc, GSK plc, Pfizer Inc., AbbVie Inc., Bristol-Myers Squibb Company, Novartis AG, Amneal Pharmaceuticals, Inc., Merck & Co. Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vasculitis Treatment Market Shifts & Advancements
Precision immunomodulation and site-of-care redistribution are converging to reshape how vasculitis therapies reach patients, with technology-enabled monitoring and regulatory acceleration creating new competitive battlegrounds.
Bispecific antibody engineering is converging with B-cell depletion mechanisms to enable simultaneous targeting of multiple inflammatory pathways within single therapeutic molecules. Academic medical centers in Boston and Heidelberg are piloting these constructs in refractory ANCA-associated vasculitis cohorts. This convergence is compressing the traditional sequential trial design into parallel adaptive protocols that accelerate dose-ranging decisions.
REACH authorization requirements for novel pharmaceutical excipients are forcing reformulation strategies that exclude certain polyethylene glycol variants from European market submissions. Contract manufacturing organizations serving the EU market are retooling purification trains to meet ECHA substance volume thresholds. Biologic developers with late-stage assets are most affected, with several programs delaying European filings to secure alternative excipient supply.
Site-of-care economics are driving infusion center consolidation into hospital outpatient departments and specialty pharmacy networks. Payers in the United States are steering volume toward lower-cost ambulatory settings through differential reimbursement rates. This channel migration is most visible in Medicare Advantage populations, where prior authorization requirements increasingly mandate non-hospital site selection for maintenance rituximab dosing.
Global Vasculitis Treatment Market Segmentation
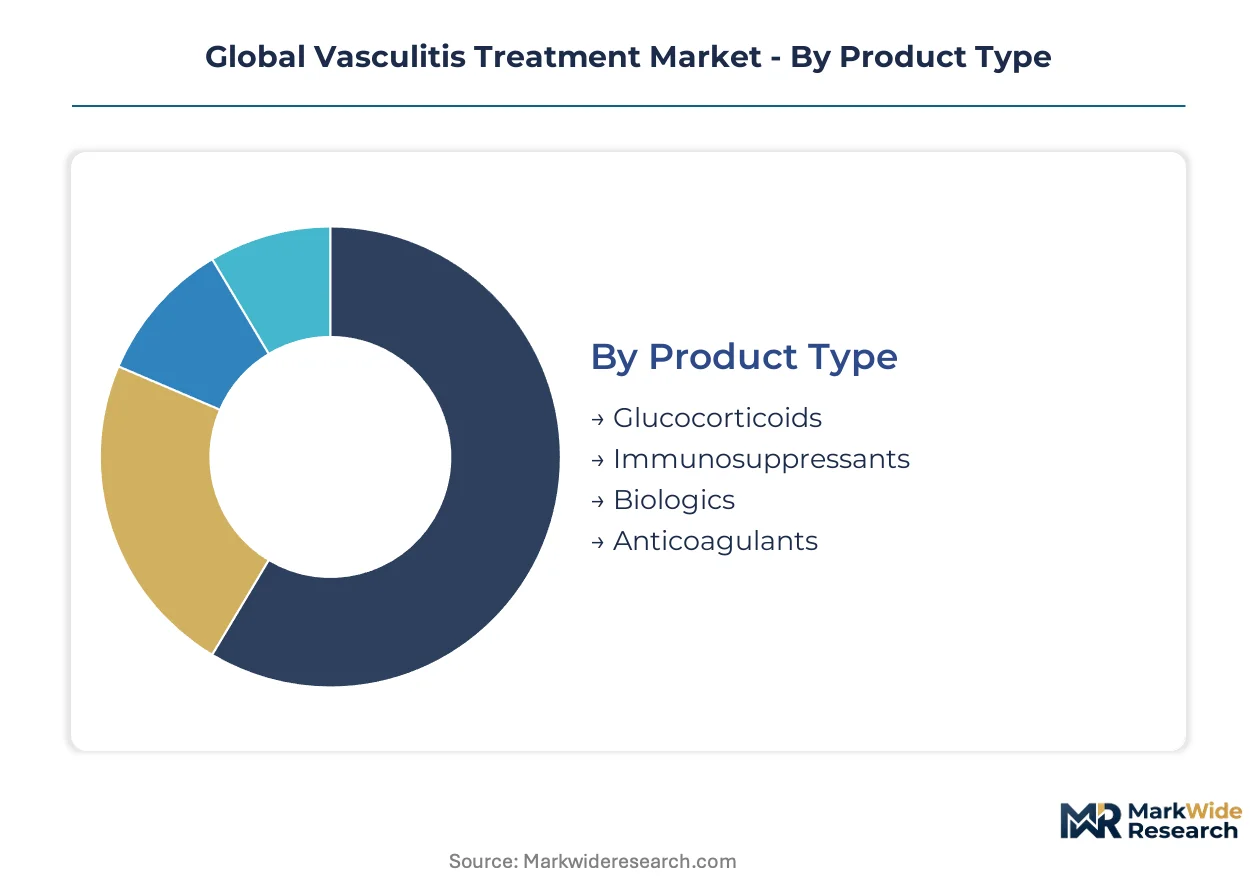
Vasculitis treatment segmentation reflects divergent clinical priorities across induction versus maintenance phases, site-of-care economics, and regulatory acceleration pathways for rare disease subsets. Understanding how patient volume distributes across these dimensions shapes portfolio allocation and geographic targeting decisions.
Product Type:
Cost tier and reimbursement intensity separate buyers in this category, with biologics commanding premium positioning against commoditized immunosuppressants.
- Biologics:Engineered monoclonal antibodies and fusion proteins target B-cell depletion and cytokine blockade with precision mechanism specificity. Demand concentrates in tertiary referral networks across the United States, Germany, and Japan where prior authorization pathways favor targeted immunomodulation over conventional therapy despite higher acquisition costs.
- Immunosuppressants:Small-molecule agents including cyclophosphamide, azathioprine, and mycophenolate mofetil form the backbone of induction protocols. Volume clusters in cost-constrained markets and public hospital systems where biologic access remains restricted by formulary tiers and budget impact thresholds.
- Glucocorticoids:Oral and parenteral corticosteroids remain foundational for acute flare management across all vasculitis subtypes.
- Anticoagulants:Heparin derivatives and direct oral anticoagulants address thrombotic complications in selected vasculitis phenotypes.
Immunosuppressants lead volumes today; biologics are gaining share fastest.
Therapy Area:
Prevalence gradients and unmet medical need intensity differentiate these indications, with ANCA-associated subtypes attracting disproportionate pipeline investment.
- Granulomatosis with Polyangiitis:Necrotizing granulomatous inflammation of upper and lower respiratory tracts combined with glomerulonephritis defines this severe ANCA-associated subtype. Clinical development activity concentrates in Boston, Heidelberg, and Tokyo academic centers where adaptive trial designs compress enrollment timelines for refractory cohorts.
- Giant Cell Arteritis:Large-vessel vasculitis of cranial arteries carries acute vision loss risk requiring urgent high-dose corticosteroid initiation. Demand localizes in aging populations across the United States, Germany, and Japan where temporal artery biopsy capacity and vascular surgery referral networks determine diagnostic throughput.
- Microscopic Polyangiitis:Pauci-immune small-vessel vasculitis with rapidly progressive glomerulonephritis presentation.
- Eosinophilic Granulomatosis:Asthma-driven eosinophilic vasculitis with cardiac and peripheral nerve involvement.
Giant Cell Arteritis dominates current patient volume; Granulomatosis with Polyangiitis shows the steepest expansion trajectory.
End User:
Site-of-care economics and prescriber concentration patterns determine channel strategy, with infusion capacity constraints reshaping patient flow.
- Hospitals:Academic medical centers and community hospital systems retain dominance for induction therapy and acute complications requiring multidisciplinary management. United States Medicare Advantage prior authorization requirements increasingly mandate hospital outpatient departments over traditional inpatient settings for maintenance biologic dosing.
- Specialty Clinics:Rheumatology-focused ambulatory centers concentrate prescriber expertise and infusion capacity for stable maintenance patients. Networks in Germany and Japan are expanding biologic administration suites to capture payer-steered volume from higher-cost hospital settings.
- Diagnostic Laboratories:ANCA serology and histopathology services support definitive subtype classification.
- Research Institutes:Academic centers conduct mechanistic studies and early-phase clinical trials.
Hospitals retain the largest patient share; specialty clinics are expanding most quickly.
Delivery Mode:
Patient convenience and cold chain logistics requirements separate administration routes, with formulation innovation driving migration toward self-administered options.
- Intravenous:Hospital and infusion center-based delivery dominates biologic administration, particularly for rituximab and tocilizumab. Capacity constraints at United States hospital outpatient departments are creating wait lists that push stable patients toward alternative sites.
- Subcutaneous:Prefilled syringe and autoinjector formats enable home administration for maintenance-phase patients. Formulation development pipelines across Boston and Basel biotech clusters prioritize subcutaneous migration to bypass infusion center bottlenecks.
- Oral:Glucocorticoid tapers and small-molecule immunosuppressants maintain universal accessibility.
- Inhalation:Limited application for upper airway manifestations in selected granulomatosis presentations.
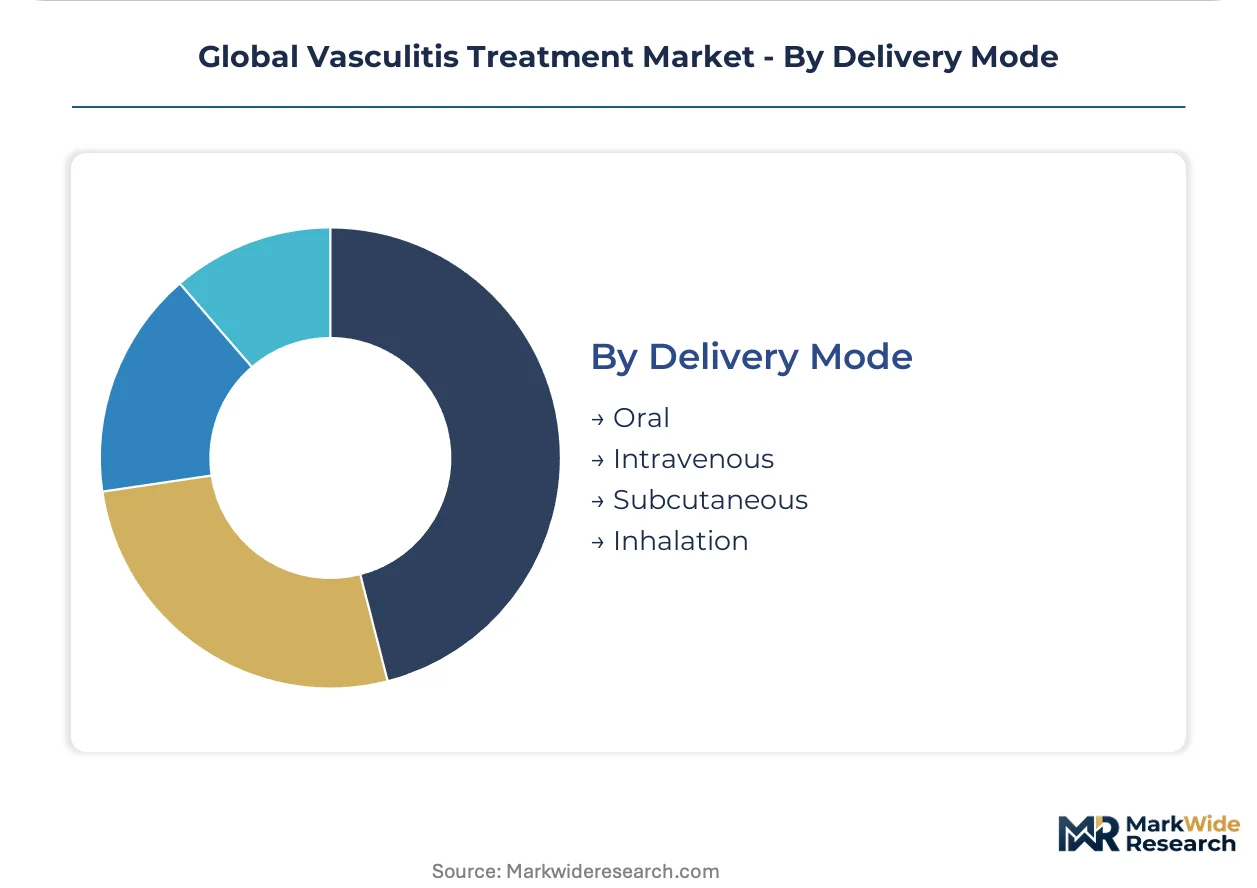
Intravenous administration leads current volume; subcutaneous delivery is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting biologic manufacturing toward jurisdictions with streamlined orphan drug pathways, while tertiary referral networks concentrate demand in markets with established immunology specialist training pipelines.
United States
Academic medical centers in Boston and New York anchor clinical trial enrollment for ANCA-associated vasculitis subtypes. FDA accelerated approval pathways compress development timelines for rare autoimmune indications. The Mayo Clinic Rochester and Cleveland Clinic networks consolidate prescriber influence across the Midwest, steering biologic infusion volume toward hospital outpatient departments.
Germany
Heidelberg and Berlin university hospitals pilot adaptive trial designs for refractory vasculitis cohorts. EMA PRIME eligibility attracts venture funding into early-stage immunology pipelines targeting rare subtypes. REACH compliance requirements for novel biologic excipients extend formulation development timelines, prompting some developers to sequence European filings after US market entry.
Japan
Tokyo and Osaka academic centers manage complex vasculitis cohorts through established tertiary referral networks. PMDA Sakigake designation enables conditional market entry with reduced Phase III data requirements for innovative biologics. The aging demographic concentrates Giant Cell Arteritis patient volume, driving demand for corticosteroid-sparing protocols.
United Kingdom
London and Cambridge rheumatology units participate in pan-European adaptive protocols for B-cell depletion therapies. MHRA post-Brexit regulatory autonomy allows tailored approval timelines for orphan indications. NHS England specialized commissioning frameworks concentrate biologic access in designated vasculitis centers, limiting community hospital prescribing.
Switzerland
Basel biotech clusters prioritize subcutaneous formulation development to bypass infusion center capacity constraints. Swissmedic alignment with EMA standards facilitates parallel European market entry while maintaining distinct national pricing autonomy. The country's fractionation infrastructure supports immunoglobulin concentrate supply for selected vasculitis complications.
Global Vasculitis Treatment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated pharmaceutical conglomerates commanding biologic categories while generic immunosuppressant supply fragments among regional formulators. Market structure tilts toward consolidation at the premium tier, where prescriber loyalty programs and payer contract breadth determine access. Three archetypes dominate: rheumatology franchise holders with established infusion center relationships, immunology pipeline developers with cytokine pathway expertise, and biosimilar entrants targeting rituximab and tocilizumab categories. Capacity expansion into subcutaneous delivery formats and strategic partnerships for European excipient sourcing represent the dominant competitive moves.
Within the integrated pharmaceutical tier, F. Hoffmann-La Roche Ltd and AbbVie Inc. exemplify archetypes built on rheumatology franchise depth and immunology specialization respectively. Bristol-Myers Squibb Company occupies a position anchored by inflammation and immunology pipeline breadth. These entities represent contrasting strategic postures: one leveraging established prescriber relationships across academic medical centers, another deploying broad payer contracts, and the third differentiating through pipeline optionality across multiple inflammatory pathways.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| AstraZeneca plc |
| GSK plc |
| Pfizer Inc. |
| AbbVie Inc. |
| Bristol-Myers Squibb Company |
| Novartis AG |
| Amneal Pharmaceuticals, Inc. |
| Merck & Co. Inc. |
| Others |
Supply & Pricing Matrix
Subcutaneous formulation migration toward prefilled syringe and autoinjector platforms simultaneously compresses per-dose manufacturing costs and redistributes production capacity away from centralized European fractionation facilities toward modular fill-finish operations in Switzerland and Singapore. This technological shift weakens traditional hospital infusion center pricing power while amplifying bargaining leverage for specialty pharmacy networks that aggregate maintenance-phase patient volume.
Pricing Analysis
Hospital outpatient department markup layers over acquisition cost create the dominant pricing architecture for intravenous biologics, with three-tier pricing structure across premium, standard, and economy levels separating originator rituximab from biosimilar entrants and compounded immunoglobulin alternatives. Price differentiation hinges on FDA orphan drug exclusivity duration and EMA PRIME eligibility status, which extend premium positioning for rare vasculitis indications. Pricing pressure stems from Medicare Advantage prior authorization mandates steering volume toward lower-reimbursement ambulatory settings. Public hospital systems and Medicaid-managed plans exhibit highest price sensitivity; academic medical centers with dedicated vasculitis centers demonstrate lowest sensitivity due to protocol-driven formulary adherence.
Supply Chain Analysis
Direct-to-hospital channels handle acute induction therapy demand while specialty pharmacy distribution runs through consolidated networks for maintenance-phase subcutaneous products. Manufacturing concentration centers on Switzerland, Germany, and the United States for monoclonal antibody production, with plasma-derived immunoglobulin sourcing anchored in North American and European fractionation infrastructure. Raw material dependencies include Chinese-manufactured polyethylene glycol excipients, single-use bioreactor bags from South Korea, and purified water systems from German suppliers. Single-source vulnerability for novel biologic excipients under REACH authorization requirements poses structural risk for European market entry timelines. Distribution runs through temperature-controlled logistics partnerships with last-mile cold chain monitoring to satellite infusion suites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between FDA accelerated approval pathways and EMA REACH compliance timelines creates geographic cost differentials that favor sequencing US market entry ahead of European submissions, compressing revenue realization windows for developers with late-stage assets.
For Market Incumbents: Deploy subcutaneous formulation migration to defend hospital infusion center relationships against biosimilar entrants and payer site-of-care steering. Incumbent biologic manufacturers should accelerate backward integration into European excipient supply chains to circumvent REACH authorization delays that threaten competitive positioning. Rituximab originators face imminent biosimilar displacement in Medicare Advantage populations; capturing prescriber loyalty through real-world evidence generation for refractory ANCA-associated vasculitis represents the critical defensive maneuver. For New Entrants and Emerging Players: Telemedicine-enabled remote monitoring platforms offer the most penetrable entry vector for maintenance-phase patient management, bypassing established infusion center relationships that incumbent biologic manufacturers control. New entrants should target Japan's Sakigake designation pathway to secure conditional market entry with reduced Phase III investment, then leverage real-world evidence accumulation for label expansion into US and European markets. Rheumatology-focused specialty clinic networks in Germany and Japan present underexploited channel access points for subcutaneous biologic delivery. For Investors and Strategic Acquirers: Valuations sit cheapest among contract manufacturing organizations with demonstrated REACH-compliant excipient handling capabilities and established relationships with Basel and Boston biotech clusters. Long-term viability over the next decade hinges on portfolio exposure to corticosteroid-sparing protocols in aging populations across the United States, Germany, and Japan. The signal to watch is PMDA Sakigake designation grants for refractory vasculitis indications, which typically precede venture funding inflections into early-stage immunology pipelines by six to twelve months.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Prefilled autoinjector platforms bypass hospital infusion bottlenecks and capture payer-steered volume toward ambulatory settings. |
| EMA PRIME Eligibility Pursuit | Priority medicines designation compresses regulatory review timelines and attracts venture funding for rare vasculitis subtypes. |
| Real-World Evidence Infrastructure | Electronic health record aggregation across academic medical centers enables post-market surveillance and label expansion strategies. |
| Biosimilar Manufacturing Scale-Up | Rituximab and tocilizumab biosimilar entry reshapes pricing power and site-of-care economics in Medicare Advantage populations. |
| Cold Chain Logistics Partnership | Temperature-controlled distribution with last-mile monitoring prevents potency-compromising excursions to satellite infusion suites. |
Research Methodology
Bottom-up patient volume modeling reconciled against top-down biologic manufacturing capacity tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers were combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Triangulation between prescriber-reported treatment patterns and payer-reimbursement claims data ensures segmentation integrity across induction versus maintenance therapy phases.
Historical trendline analysis of biologic infusion volume growth patterns informed the projection framework across the analysis window. Segmentation dimensions modeled include therapy area, product type, delivery mode, site-of-care channel, and regional regulatory cluster. CAGRs were derived from regression analysis of approved therapy adoption curves, adjusted for biosimilar entry timing and payer policy shifts. Forecast inputs incorporate EMA PRIME designation velocity, FDA accelerated approval pathway utilization rates, and subcutaneous formulation pipeline progression data from Basel and Boston biotech clusters.
The model assumes a particular technology adoption path; alternative pathways for wearable inflammation biomarker monitoring would alter the outlook by compressing infusion center visit frequency and accelerating site-of-care redistribution. Forecasts reflect base-case assumptions regarding regulatory pathway efficiency, excipient supply continuity, and immunology specialist workforce expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Gaucher and Pompe Diseases Enzyme Replacement Therapy (ERT) Market
Specialty Medicine
Global Neurotrophic Keratitis Treatment Market
Specialty Medicine
Cutaneous Fibrosis Treatment Market
Specialty Medicine
Rhabdomyosarcoma Market
Specialty Medicine
Sporothrix Schenckii Infection Treatment Market
Specialty Medicine
Eisenmenger Complex Management Market
Specialty Medicine
Global Attention Deficit Hyperactivity Disorder Market
Specialty Medicine
Polymyalgia Rheumatica Treatment Market
Specialty Medicine
Musculoskeletal System Disorders Market
Specialty Medicine
Optic Atrophy Management Market
Specialty Medicine
Osteogenesis Imperfecta Treatment Market
Specialty Medicine
Fibroadenoma Market
Specialty Medicine
Leukocytoclastic Vasculitis Market
Specialty Medicine
Folliculotropic Mycosis Fungoides Treatment Market
Specialty Medicine
Short Bowel Syndrome Market
Specialty Medicine
Multiple Endocrine Neoplasia Market