
 Pneumoconiosis Market | 2026-2036
Pneumoconiosis Market Size, Share, and Industry Trends Forecast 2026-2036
Pneumoconiosis Market Outlook
Hospital procurement channels for pneumoconiosis therapeutics is narrowing as formulary committees tighten respiratory drug budgets across tier-one medical centers. GlaxoSmithKline plc leverages its inhaled therapy portfolio to sustain institutional contracts in European pulmonary wards. Boehringer Ingelheim International GmbH specializes in chronic obstructive overlap indications, anchoring its position in German pneumoconiosis referral networks. Teva Pharmaceutical Industries Ltd. competes through generic bronchodilator availability, extending reach into cost-sensitive clinic segments.
Pneumoconiosis comprises fibrotic lung diseases caused by prolonged inhalation of mineral dusts, principally crystalline silica and coal mine dust, characterized by progressive interstitial inflammation and restrictive ventilatory impairment. Therapeutics dominate product type revenue as antifibrotic protocols expand, while diagnostic kits represent the fastest-growing segment driven by high-resolution CT screening mandates in hazardous occupations. Hospitals anchor end user demand through dedicated occupational lung disease units, though homecare providers capture growing share as long-term oxygen therapy protocols mature.
FDA orphan drug designations and EMA conditional marketing authorizations shape pharmaceutical pipeline prioritization for pneumoconiosis indications, accelerating trial enrollment in exposed worker cohorts. OSHA permissible exposure limits and China's GBZ occupational disease standards mandate employer-funded diagnostic programs, directly stimulating diagnostic kit procurement. Stakeholders must monitor evolving silica substitution regulations in construction materials and mining operations, as these upstream controls will reshape downstream therapeutic demand patterns.
Market Dynamics
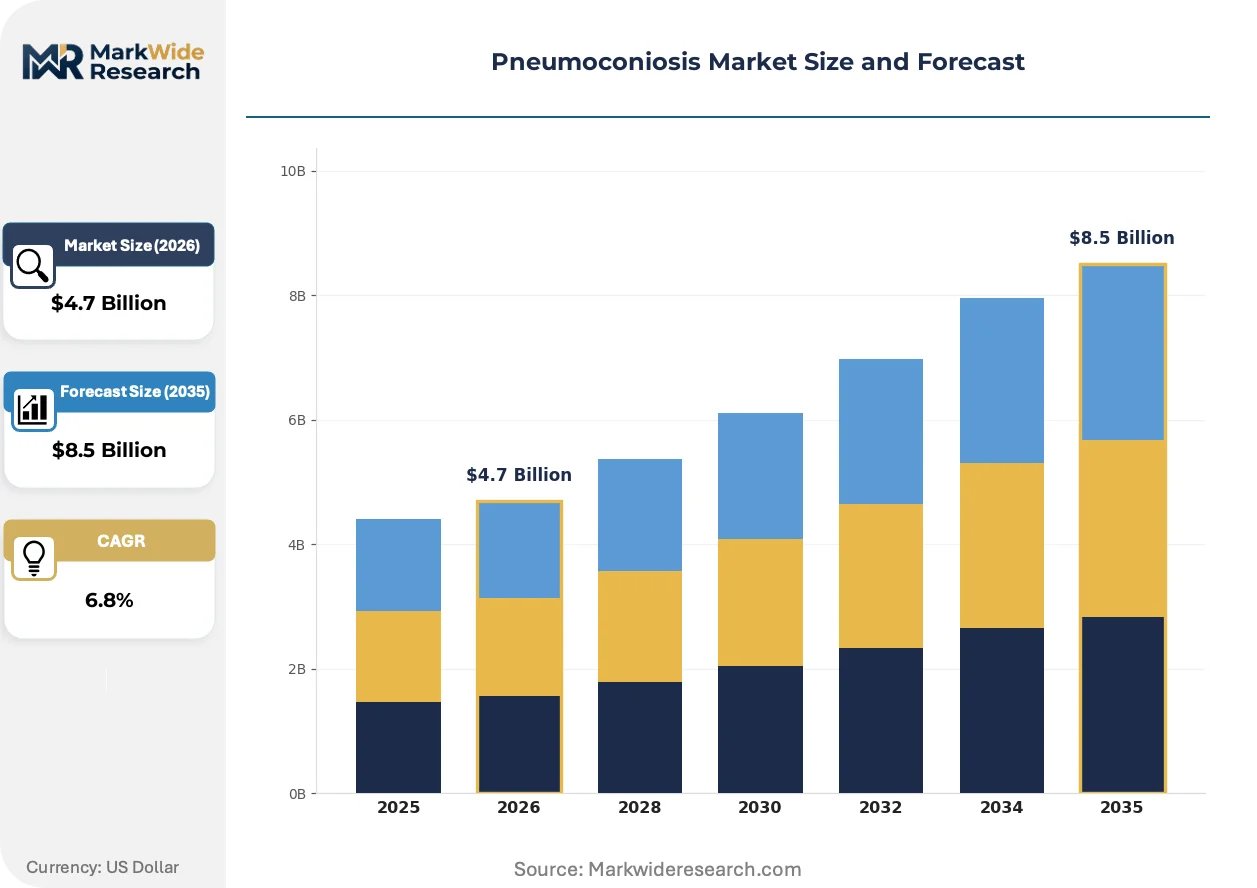
Occupational exposure mandates and antifibrotic protocol expansion are compressing diagnostic-to-treatment timelines across exposed worker cohorts. Regulatory screening obligations in heavy industries now trigger earlier therapeutic intervention, restructuring how hospitals and occupational health clinics sequence patient pathways.
Growth Catalysts
- OSHA permissible exposure limits:Employer-funded diagnostic programs in US mining and construction sectors accelerate high-resolution CT procurement. Mandated screening intervals create recurring revenue streams for diagnostic kit manufacturers.
- China's GBZ occupational disease standards:Quartz processing facilities in Hebei and Shanxi provinces face intensified compliance audits. Central government enforcement drives institutional purchasing of spirometry and imaging equipment.
- Antifibrotic protocol maturation:Nintedanib and pirfenidone reimbursement expansion in German and French pulmonary wards extends treatment windows. Chronic management protocols shift patient volume from acute settings to long-term care infrastructure.
Market Restraints
- Specialized pulmonologist scarcity:Fellowship-trained occupational lung specialists concentrate in Johannesburg, Pittsburgh, and Essen academic centers. Diagnostic capacity bottlenecks delay cohort enrollment for therapeutic trials.
- Silica substitution regulatory lag:Construction material reformulation timelines in developing economies extend hazardous exposure windows. Alternative aggregate certification processes lack harmonized international standards.
- Reimbursement code fragmentation:Pneumoconiosis-specific billing categories remain unconsolidated across US Medicare, German G-DRG, and Chinese social insurance schemes. Administrative complexity elevates claims denial rates.
Strategic Opportunities
- Homecare oxygen therapy expansion:Long-term oxygen protocol maturation in Australian and Canadian rural health systems displaces hospital-based chronic management. Portable concentrator manufacturers capture patient volume from institutional settings.
- EMA conditional marketing authorization:Accelerated approval pathways for orphan respiratory indications compress development timelines. Biotech developers prioritize pneumoconiosis fibrosis mechanisms over crowded idiopathic pulmonary fibrosis indications.
- Artificial intelligence pattern recognition:Machine learning algorithms trained on South African and Chinese occupational cohorts automate radiological severity scoring. Diagnostic workflow compression enables high-volume screening in resource-constrained environments.
Industry Challenges
- Biomarker validation timelines:Serum KL-6 and SP-D assay standardization across FDA and EMA reference laboratories remains incomplete. Clinical endpoint uncertainty complicates trial design for novel antifibrotic candidates.
- Legacy EHR integration:Occupational exposure history capture modules lack interoperability with hospital information systems in tier-two Chinese medical centers. Data fragmentation impedes longitudinal cohort tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pneumoconiosis Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $8.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Kits, Therapeutics, Supportive Care, Medical Devices End User: Hospitals, Clinics, Research Institutions, Homecare Providers Application: Diagnosis, Treatment, Monitoring, Prevention Delivery Mode: Intravenous, Oral, Inhalation, Subcutaneous |
| Companies Covered | GlaxoSmithKline plc, Novartis AG, AstraZeneca PLC, Sanofi S.A., Pfizer Inc., Boehringer Ingelheim International GmbH, Merck & Co., Inc., Teva Pharmaceutical Industries Ltd., F. Hoffmann-La Roche Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pneumoconiosis Market Strategic Shifts
Digital pathology and remote patient monitoring are restructuring how occupational lung disease is detected, staged, and managed across dispersed mining populations. These shifts compress the interval between exposure documentation and clinical intervention.
High-resolution CT screening protocols are collapsing the latency period between silica exposure and definitive diagnosis. South African platinum and gold mining operators now deploy mobile imaging units to underground sites, enabling same-shift radiological assessment. This capability is collapsing referral bottlenecks that previously delayed therapeutic initiation by 18-24 months.
EMA orphan drug incentives and FDA breakthrough therapy designations are accelerating antifibrotic pipeline prioritization for pneumoconiosis-specific indications. Conditional approval frameworks permit surrogate endpoint acceptance in exposed worker trials. European pulmonary referral networks in the Ruhr industrial region and Silesian mining basin are expanding investigator-initiated study infrastructure to capture this regulatory tailwind.
Hospital formulary committees are unbundling chronic respiratory drug procurement from bundled payment contracts. German pneumoconiosis centers in Bochum and Dortmund now negotiate antifibrotic access through separate pharmacy benefit carve-outs. This purchasing autonomy is most visible in North Rhine-Westphalia, where occupational disease unit directors retain direct supplier contracting authority outside centralized hospital procurement.
Pneumoconiosis Market Segmentation
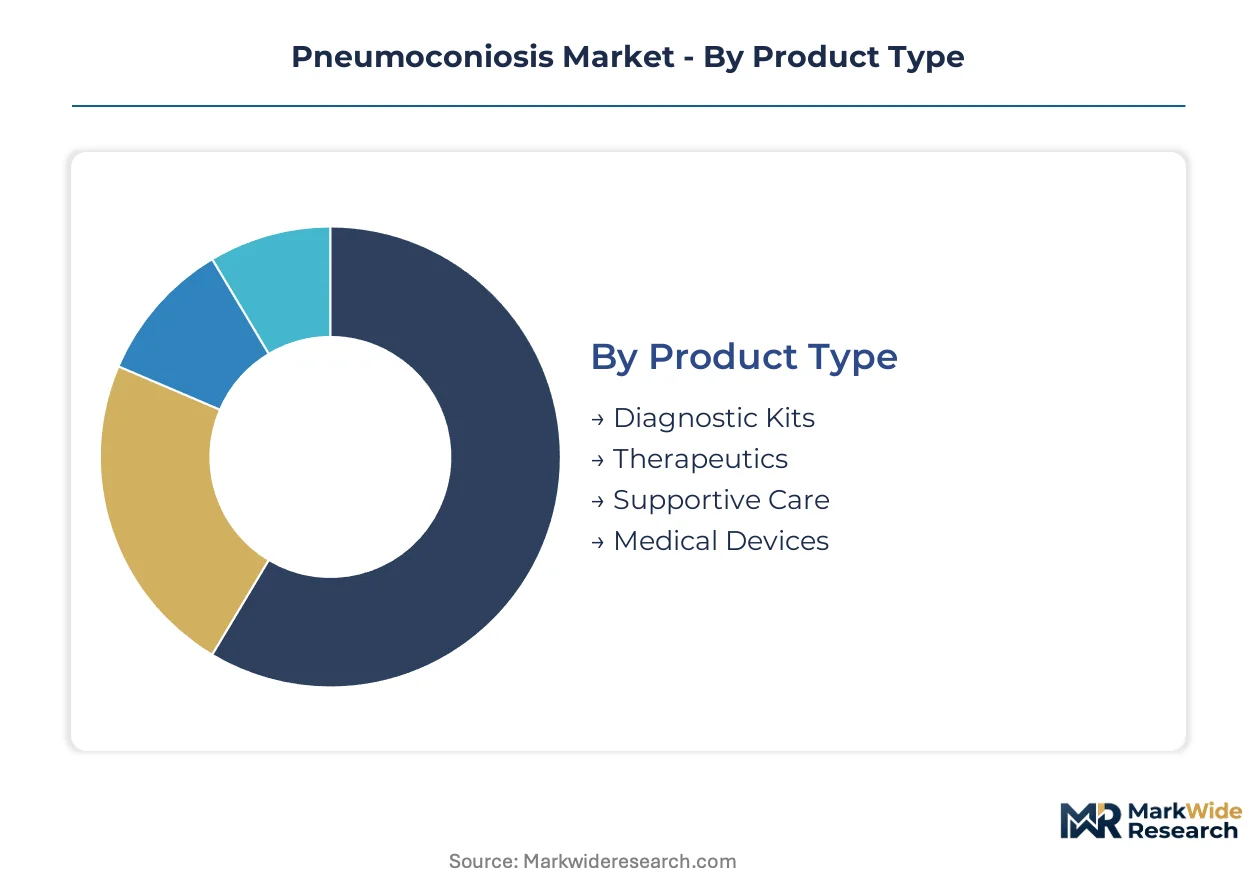
Segmentation in pneumoconiosis markets tracks how regulatory screening mandates and antifibrotic protocol maturation reshape procurement patterns across institutional and homecare channels. Understanding these divides clarifies where diagnostic kit manufacturers capture recurring revenue versus where therapeutic developers secure long-term treatment contracts.
Product Type:
Therapeutics and diagnostic kits operate on fundamentally different replenishment cycles, with consumable screening tools turning over faster than capital-intensive imaging platforms or chronic drug regimens.
- Diagnostic Kits:High-resolution CT contrast agents, spirometry calibration standards, and serum biomarker assays constitute the consumable backbone of occupational screening programs. Chinese quartz processing facilities in Hebei province and South African platinum mining operators drive procurement volume through mandated employee testing intervals.
- Therapeutics:Antifibrotic agents including nintedanib and pirfenidone dominate revenue concentration as chronic management protocols extend treatment windows across German and French pulmonary wards. Reimbursement expansion in European occupational disease centers anchors demand stability.
- Supportive Care:Long-term oxygen therapy equipment and pulmonary rehabilitation supplies serve progressive disease stages in Australian and Canadian rural health systems.
- Medical Devices:Portable spirometers, pulse oximeters, and mobile imaging units enable point-of-care assessment in underground mining environments.
Therapeutics anchors the volume base while diagnostic kits gain share at the steepest rate.
End User:
Customer type determines contract structure, with hospitals negotiating enterprise-level antifibrotic agreements while homecare providers purchase oxygen therapy equipment through decentralized procurement.
- Hospitals:Dedicated occupational lung disease units in Johannesburg, Pittsburgh, and Essen academic centers anchor therapeutic demand through specialized pulmonologist concentration and clinical trial infrastructure.
- Clinics:Occupational health clinics in Chinese industrial zones and US mining regions handle frontline screening and referral coordination under employer-funded diagnostic mandates.
- Research Institutions:Investigator-initiated studies in Ruhr industrial region and Silesian mining basin expand enrollment capacity for orphan drug trials.
- Homecare Providers:Long-term oxygen therapy protocol maturation in dispersed rural populations shifts patient volume from institutional settings to portable concentrator deployment.
Hospitals retain the largest contract value while homecare providers are expanding most quickly.
Application:
Functional purpose segments separate one-time diagnostic events from recurring revenue streams, with prevention and monitoring applications exhibiting divergent margin profiles.
- Diagnosis:High-resolution CT screening and biomarker quantification capture initial patient identification under OSHA and China's GBZ mandatory testing frameworks.
- Treatment:Antifibrotic drug administration and oxygen therapy delivery constitute the revenue core, with chronic protocols generating sustained pharmaceutical consumption.
- Monitoring:Pulmonary function testing and radiological progression tracking create recurring touchpoints between exposed workers and healthcare systems.
- Prevention:Respiratory protection verification and exposure reduction consulting serve upstream industrial hygiene functions with lower healthcare system integration.
Treatment commands the revenue base while monitoring shows the steepest expansion trajectory.
Delivery Mode:
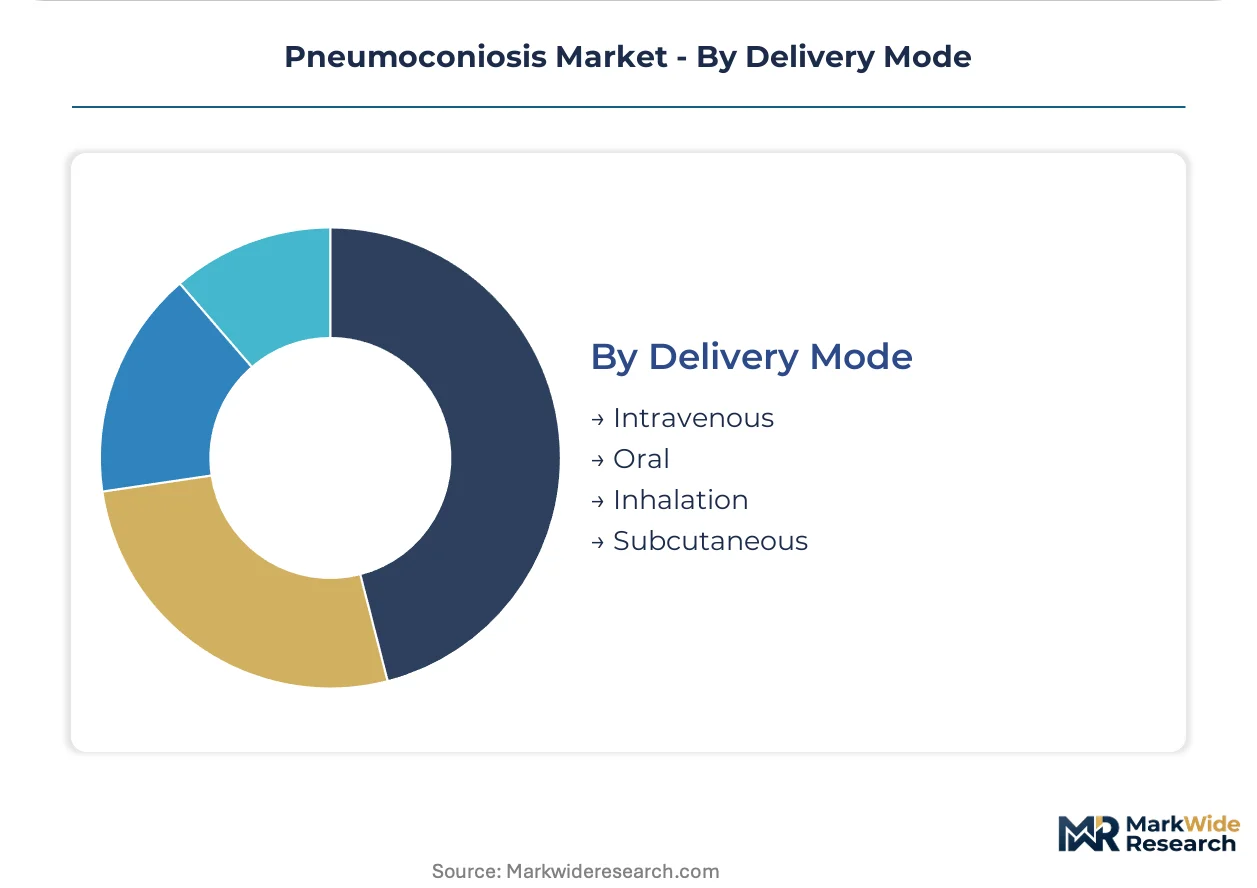
Route of administration segments align with disease stage progression, with oral and inhaled options dominating early chronic management while intravenous routes serve acute exacerbations.
- Oral:Nintedanib capsules and pirfenidone tablets enable self-administered chronic therapy, supporting patient displacement from hospital-based infusion centers to home medication management.
- Inhalation:Bronchodilator and corticosteroid delivery through nebulized and dry powder platforms addresses symptomatic overlap with chronic obstructive pathology in German pneumoconiosis referral networks.
- Intravenous:Hospital-administered acute interventions and investigative antifibrotic infusions concentrate in tertiary pulmonary centers with intensive care capability.
- Subcutaneous:Emerging biologic delivery formats for fibrosis-modifying agents remain in clinical development pipelines with limited current commercial presence.
Oral delivery anchors patient volume while inhalation climbs the fastest on COPD overlap protocol expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rustenburg platinum belt's rail-to-port infrastructure underwrites South Africa's therapeutic procurement scale, while China's high-speed freight corridors connect Shanxi coal provinces to coastal diagnostic manufacturing clusters.
United States
Underground coal operations in Appalachia and hard-rock mining in Nevada sustain employer-funded screening mandates. OSHA permissible exposure limits trigger recurring high-resolution CT procurement cycles. Pittsburgh's academic medical centers anchor specialized pulmonologist concentration and clinical trial infrastructure for antifibrotic protocols.
Germany
Ruhr industrial region pneumoconiosis referral networks in Bochum and Dortmund drive chronic management protocol adoption. EMA orphan drug incentives accelerate investigator-initiated study enrollment in exposed worker cohorts. North Rhine-Westphalia occupational disease units retain direct supplier contracting authority outside centralized hospital procurement.
China
Quartz processing facilities in Hebei and Shanxi provinces face intensified GBZ occupational disease standard compliance audits. Central government enforcement drives institutional purchasing of spirometry and imaging equipment. Yangtze River Delta medical device manufacturers supply portable diagnostic platforms to western mining provinces.
Australia
Western Australian iron ore and Queensland coal mining operations deploy mobile imaging units to remote sites. Long-term oxygen therapy protocol maturation in rural health systems shifts patient volume from institutional settings to portable concentrator deployment. National occupational health frameworks mandate employer-funded diagnostic intervals.
South Africa
Platinum and gold mining operators in the Rustenburg and Free State provinces deploy same-shift radiological assessment capabilities. Mobile imaging units collapse referral bottlenecks that previously delayed therapeutic initiation. Johannesburg academic centers concentrate fellowship-trained occupational lung specialists and antifibrotic trial infrastructure.
Pneumoconiosis Market Competitive Environment
On the supply side, the industry is consolidating around respiratory therapy specialists with established institutional contracts and generic manufacturers competing on cost-sensitive clinic segments. Three archetypes dominate: multinational pharmaceutical conglomerates with inhaled therapy portfolios, mid-cap biotech developers pursuing EMA conditional marketing authorizations, and generic bronchodilator suppliers extending reach through price-competitive positioning. Competitive moves concentrate on formulary committee engagement for separate pharmacy benefit carve-outs and strategic partnerships with occupational health clinic networks.
Among European-based pharmaceutical conglomerates, GlaxoSmithKline plc and Boehringer Ingelheim International GmbH exemplify the institutional-contract archetype, anchoring positions in pulmonary ward procurement channels through dedicated respiratory portfolios. Teva Pharmaceutical Industries Ltd. represents the generic-access tier, occupying a position in cost-sensitive clinic segments through bronchodilator availability. These three entities collectively illustrate how supply-side positioning splits between premium therapeutic development and volume-driven generic penetration.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Novartis AG |
| AstraZeneca PLC |
| Sanofi S.A. |
| Pfizer Inc. |
| Boehringer Ingelheim International GmbH |
| Merck & Co., Inc. |
| Teva Pharmaceutical Industries Ltd. |
| F. Hoffmann-La Roche Ltd. |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Chinese diagnostic reagent manufacturers determines both the three-tier pricing spread across institutional procurement channels and the geographic concentration of supply chain nodes serving occupational health networks. Tariff exposure on imported high-resolution CT contrast agents and spirometry calibration standards forces German and Australian hospital systems into longer-term offtake contracts, compressing margin flexibility for mid-tier distributors.
Pricing Analysis
Volume-discount tiering structures dominate antifibrotic procurement, with nintedanib and pirfenidone contracts scaling rebates against patient enrollment commitments in Ruhr region pneumoconiosis centers. Pricing stratifies across premium originator formulations, standard authorized generics, and economy-tier parallel import channels, with quality-grade certification by EMA and FDA tiers serving as the primary differentiation driver. Cost compression in the economy tier is intensifying as Teva Pharmaceutical Industries extends generic bronchodilator reach into Chinese industrial zone clinics. Employer-funded diagnostic programs in South African mining operations exhibit the lowest price sensitivity due to regulatory mandate pass-through, while Australian rural health systems demonstrate acute sensitivity to portable oxygen concentrator capital costs.
Supply Chain Analysis
Contract-manufacturing concentration for diagnostic kits rests with Yangtze River Delta medical device producers and Indian pharmaceutical reagent specialists, with limited European capacity for high-resolution CT contrast formulation. Raw material dependencies center on iodinated contrast precursors sourced from Chinese chemical processors, quartz-standard reference materials from German metrology institutes, and polymer membranes for portable spirometers from South Korean suppliers. Single-source vulnerability on iodine supply from Chilean caliche ore deposits creates chokepoint exposure for imaging protocol continuity. Distribution runs through occupational health clinic networks in mining provinces, with hospital pharmacy benefit carve-outs in North Rhine-Westphalia bypassing centralized procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antifibrotic protocol maturation in European pulmonary wards signals early-cycle expansion, with EMA conditional marketing authorization tailwinds accelerating orphan drug pipeline prioritization ahead of diagnostic kit saturation.
For Market Incumbents: Harden formulary committee relationships through separate pharmacy benefit carve-out negotiations in German occupational disease centers, insulating nintedanib positioning from bundled payment compression. Deepen backward integration into diagnostic reagent supply through partnerships with Yangtze River Delta manufacturers, mitigating tariff exposure on Chinese-sourced contrast agents. Prioritize certification investment for FDA breakthrough therapy designation to preempt biosimilar entry in Appalachian mining corridor accounts. For New Entrants and Emerging Players: Establish a beachhead in Australian homecare oxygen therapy deployment, where long-term protocol maturation displaces hospital-based chronic management and portable concentrator demand outstrips incumbent service capacity. Target South African mobile imaging unit leasing as the most penetrable segment, leveraging same-shift radiological assessment capabilities to collapse 18-24 month referral bottlenecks. Pursue investigator-initiated study partnerships with Johannesburg academic centers as the primary go-to-market angle, capturing antifibrotic trial infrastructure concentration. For Investors and Strategic Acquirers: EMA conditional marketing authorization reshapes the acquisition landscape, compressing development timelines for orphan respiratory indications and elevating mid-cap biotech developers with exposed worker cohort enrollment capacity. The 5-10 year viability window favors platforms with demonstrated biomarker assay standardization progress and interoperability with legacy EHR systems in tier-two Chinese medical centers. Acquisition target archetypes include vertically integrated diagnostic-therapeutic developers with occupational health clinic network partnerships. Monitor silica substitution regulatory lag in developing economy construction sectors as the signal to watch for downstream therapeutic demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA conditional marketing authorization compresses orphan drug timelines for pneumoconiosis fibrosis mechanisms. |
| Hospital System Partnership | North Rhine-Westphalia occupational disease units retain direct supplier contracting authority outside centralized procurement. |
| Manufacturing Scale-Up | Yangtze River Delta producers expand portable diagnostic platform output for Shanxi province compliance audits. |
| Reimbursement Strategy | German G-DRG and Chinese social insurance scheme consolidation reduces claims denial complexity. |
| Pipeline Diversification | Biotech developers pivot from crowded idiopathic pulmonary fibrosis to pneumoconiosis-specific surrogate endpoints. |
Study Parameters
Cross-validation between FDA orphan drug designation filings and EMA conditional marketing authorization submissions anchors the qualitative findings on pipeline prioritization trends. Primary interviews with drug development executives, regulatory affairs leads, formulary directors in German pulmonary wards, and hospital procurement managers combined with secondary validation against ClinicalTrials.gov enrollment data, OSHA permissible exposure limit documentation, and China's GBZ standard enforcement records. Bottom-up patient volume modeling across exposed worker cohorts and top-down pharmaceutical revenue triangulation ensured segmentation consistency.
Calibration against historical antifibrotic adoption curves in European occupational disease centers shaped the projection framework across the analysis window. Segmentation dimensions modeled include product type, end user channel, application purpose, and delivery mode, with regional regulatory cluster effects captured through differential reimbursement expansion assumptions. CAGRs derived from therapeutic protocol maturation rates and diagnostic kit procurement cycle compression. Forecast inputs incorporated silica substitution regulatory lag timelines and pulmonologist fellowship training pipeline constraints.
Stress conditions across biomarker assay standardization timelines, EHR interoperability deployment rates, and employer-funded diagnostic mandate enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on antifibrotic reimbursement expansion and mobile imaging unit deployment penetration. Quarterly review of EMA conditional approval grant rates and Chinese GBZ compliance audit frequency is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Lipoprotein Metabolism Disorders Treatment Market
Specialty Medicine
North America Precision Medicine Market
Specialty Medicine
Malignant Glioma Therapeutics Market
Specialty Medicine
Metabolic Disorders Therapeutics Market
Specialty Medicine
Generalized Anxiety Disorder (GAD) Market
Specialty Medicine
Polycystic Kidney Disease Treatment Market
Specialty Medicine
Vasomotor Symptoms Market
Specialty Medicine
Chronic Urticaria Market
Specialty Medicine
Endometriosis Market
Specialty Medicine
Radiation Toxicity Treatment Market
Specialty Medicine
Asperger Syndrome Market
Specialty Medicine
Hemorrhagic Stroke Treatment Market
Specialty Medicine
Hepatitis C Treatment Market
Specialty Medicine
China Ulcerative Colitis Market
Specialty Medicine
Paediatric Sports Medicine Market
Specialty Medicine
Germ Cell Tumors Market