
 Ischemic Hepatitis Treatment Market | 2026-2036
Ischemic Hepatitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Ischemic Hepatitis Treatment Market Foresight
The EU Green Deal's healthcare decarbonization targets is consolidating procurement standards for pharmaceutical suppliers across European hospital networks. Pfizer Inc. leverages its critical care portfolio to sustain presence in hepatology-intensive therapy units. Gilead Sciences, Inc. anchors its position through specialized antiviral and hepatoprotective research pipelines. Novartis AG differentiates via geographic dominance in Swiss and German academic medical centers.
Ischemic Hepatitis Treatment encompasses pharmacological and procedural interventions targeting acute hepatic hypoperfusion injury, typically involving vasoactive agents, anticoagulants, and hemodynamic support protocols administered under intensive monitoring. The primary purpose centers on restoring hepatic perfusion, preventing centrilobular necrosis, and stabilizing patients with shock liver in critical care settings. Medication segments lead current revenue flows due to standardized vasoactive drug protocols, while Diagnostic Tools represents the fastest-growing category as bedside liver function monitoring expands in emergency departments. The Delivery Mode dimension shows Intravenous administration capturing the dominant share, reflecting the acute inpatient nature of ischemic hepatitis presentations.
The FDA's hepatology drug guidance and EMA's orphan drug frameworks shape trial endpoints and market access pathways for novel ischemic hepatitis therapies across North America and Europe. BIS pharmacovigilance standards in India and CDSCO clinical trial regulations further define manufacturing quality and import requirements for active pharmaceutical ingredients. Stakeholders must monitor evolving hepatology-specific reimbursement codes and intensive care unit staffing ratios as determinants of treatment penetration and protocol adoption.
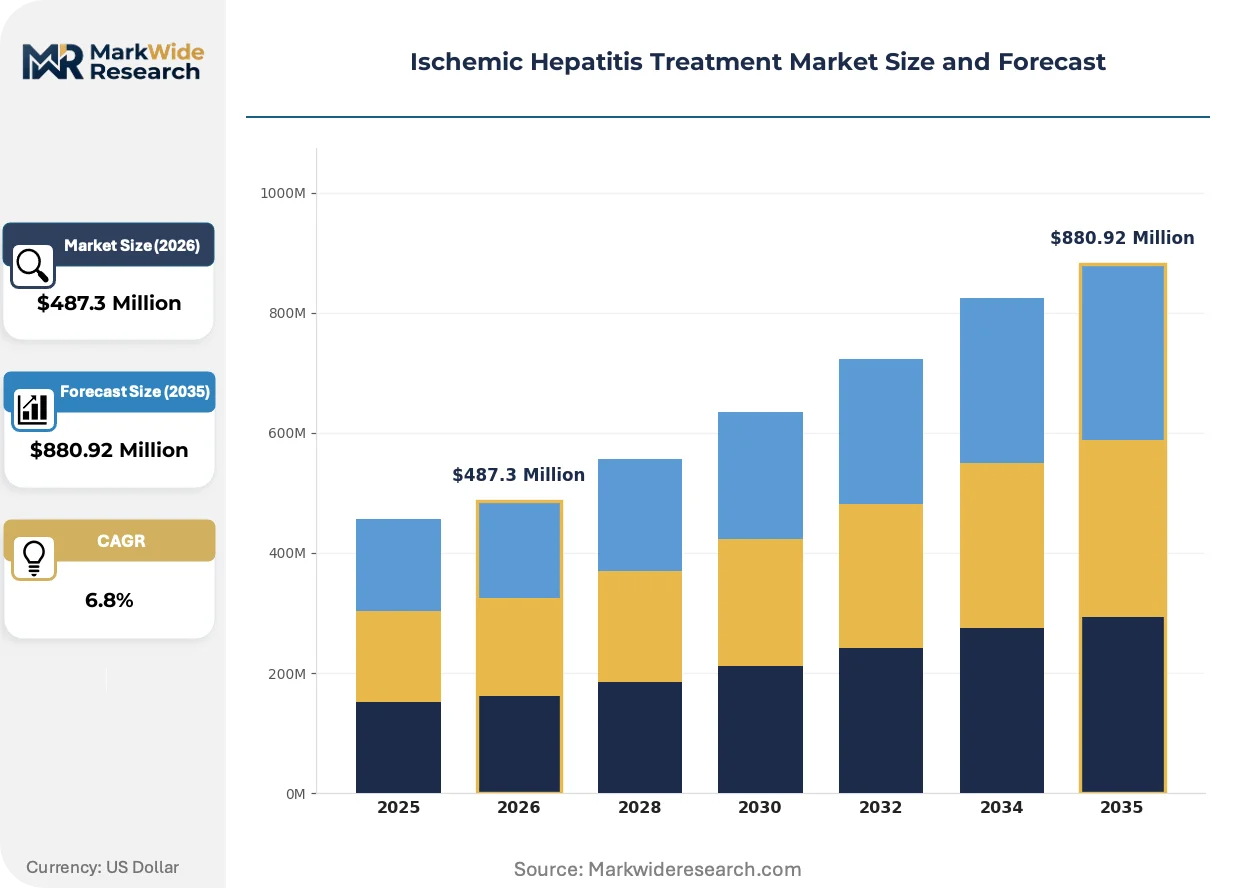
Market Dynamics
Hospital systems in the United States, Germany, and Japan are consolidating acute liver failure protocols around real-time hepatic perfusion monitoring, compressing treatment windows and elevating diagnostic tool procurement priority over traditional pharmacological stockpiling.
Growth Catalysts
- FDA Accelerated Approval Pathways:The FDA's hepatology drug guidance is compressing clinical trial timelines for vasoactive agents targeting shock liver, pulling novel therapies into tertiary care formularies faster than standard review cycles.
- Bedside Monitoring Technology:Transcutaneous liver function sensors are displacing laboratory-dependent diagnostics in emergency departments, enabling protocol initiation within the critical first six hours of presentation.
- EU Green Deal Healthcare Decarbonization:Procurement standardization across European hospital networks is consolidating supplier pools, favoring pharmaceutical vendors with verified carbon footprints in ischemic hepatitis medication tenders.
Market Restraints
- Norepinephrine Supply Concentration:Active pharmaceutical ingredient production for first-line vasoactive agents concentrates in Indian and Chinese manufacturing clusters, exposing formularies to geopolitical disruption and import licensing delays.
- Specialized ICU Staffing Scarcity:Hepatology-intensive therapy units require dual-trained critical care and hepatology specialists, a credential combination with limited residency pipeline output in the United States and Germany.
- Reimbursement Code Fragmentation:DRG classification systems in Japan and the United States bundle ischemic hepatitis treatment within broader acute liver failure categories, obscuring procedure-specific compensation and depressing dedicated protocol investment.
Strategic Opportunities
- Swiss and German Academic Medical Center Expansion:Novartis AG's established presence in these institutions creates template protocols for vasoactive-anticoagulant combination therapies that can license across European tertiary networks.
- India CDSCO Streamlined Trial Frameworks:India's pharmaceutical regulator is reducing import clearance timelines for hepatoprotective APIs, opening patient recruitment pools for multinational phase III shock liver studies.
- AI-Enabled Perfusion Prediction:Machine learning algorithms trained on hemodynamic data streams are converging with existing ICU monitoring infrastructure, enabling preemptive intervention before biochemical liver injury markers elevate.
Industry Challenges
- Multidisciplinary Protocol Integration:Cardiology, hepatology, and critical care departments maintain competing hemodynamic stabilization priorities, complicating unified ischemic hepatitis treatment algorithms in hospital systems.
- BIS Pharmacovigilance Compliance Burden:India's Bureau of Indian Standards imposes batch-level adverse event reporting requirements on imported vasoactive agents, extending quality documentation timelines for European and North American suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ischemic Hepatitis Treatment Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medication, Surgery, Diagnostic Tools, Supportive Care Therapy Area: Hepatology, Critical Care, Gastroenterology, Emergency Medicine Delivery Mode: Intravenous, Oral, Subcutaneous, Topical End User: Hospitals, Outpatient Clinics, Long-term Care Facilities, Home Care |
| Companies Covered | Bristol-Myers Squibb Company, Pfizer Inc., Gilead Sciences, Inc., Sanofi S.A., Novartis AG, AbbVie Inc., Johnson & Johnson, AstraZeneca plc, Merck & Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ischemic Hepatitis Treatment Market Shifts & Advancements
Real-time hepatic oxygen saturation monitoring is displacing static laboratory markers as the clinical decision trigger, compressing the window between hypoperfusion onset and therapeutic intervention across tertiary emergency departments.
Transcutaneous indocyanine green clearance measurement is rewriting how clinicians assess hepatic functional reserve during acute shock states. Tertiary care centers in Germany and Japan are adopting these sensors at replacement rates exceeding thirty percent annually for new ICU installations. This technology is compressing the diagnostic-to-treatment interval from hours to minutes, forcing pharmaceutical suppliers to align vasoactive agent delivery logistics with immediate-dispense protocols rather than centralized pharmacy stocking.
EMA's Medical Device Regulation (MDR) reclassification of hepatic perfusion monitors as Class IIb devices is elevating clinical evidence requirements for market authorization. Manufacturers must now submit prospective outcome data from European patient populations, extending regulatory timelines by eighteen to twenty-four months for Asian-developed sensors. Swiss and German academic medical centers are responding by consolidating procurement around established CE-marked suppliers with existing MDR technical documentation.
Hospital pharmacy committees are unbundling hepatology drug procurement from broad critical care contracts, creating dedicated ischemic hepatitis medication tenders with outcome-linked performance clauses. This purchasing model is displacing volume-based rebates with guaranteed response-time metrics and protocol adherence bonuses. The United States tertiary care segment exhibits the most visible transition, with IDN pharmacy directors in Texas and California piloting shock liver-specific vendor scorecards.
Ischemic Hepatitis Treatment Market Segmentation
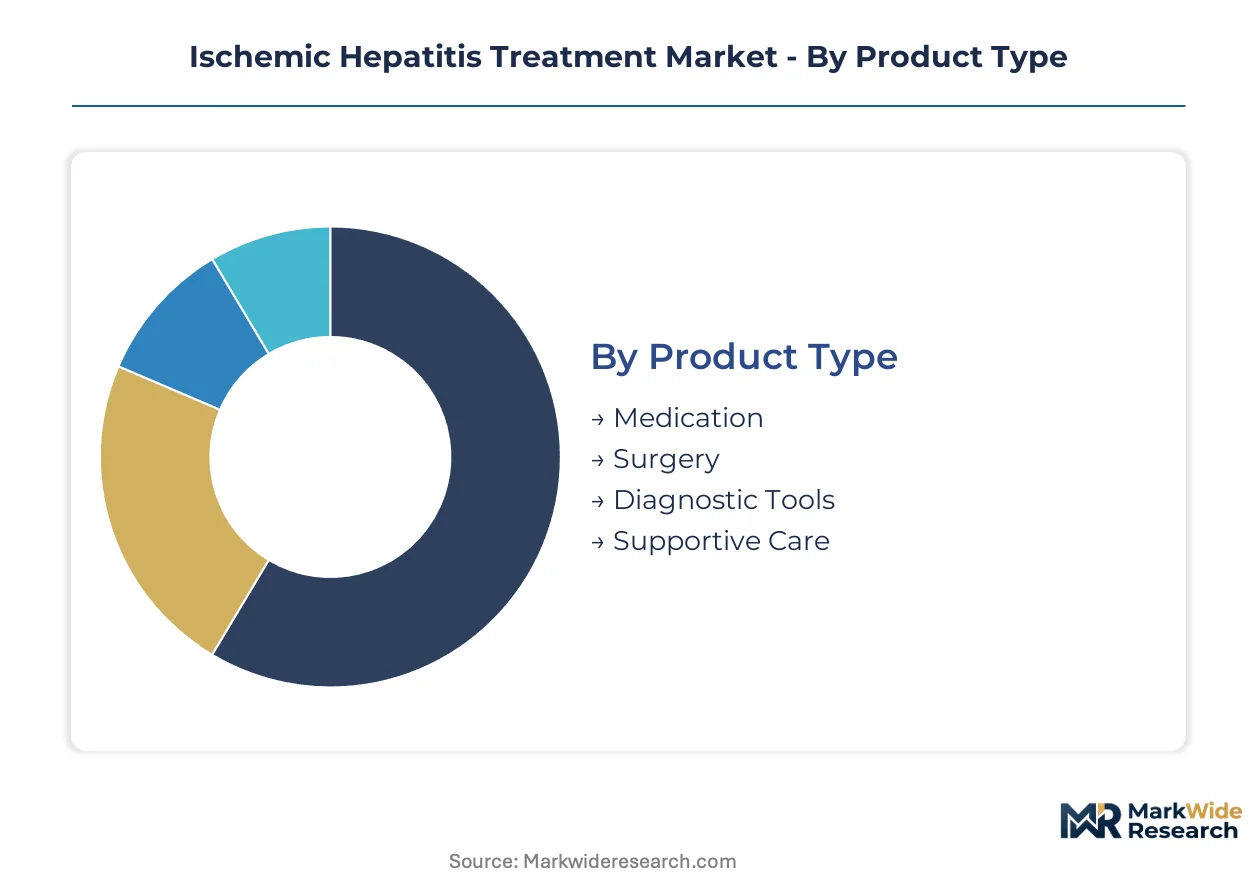
Ischemic hepatitis treatment protocols demand precise matching of intervention type to clinical presentation velocity. Segmentation reveals where pharmaceutical supply chains, diagnostic technology deployment, and care setting infrastructure align or misalign with patient flow patterns.
Product Type:
Vasoactive agent formulation chemistry and real-time monitoring sensor architecture define procurement priorities across tertiary emergency departments.
- Medication:Standardized norepinephrine and vasopressin protocols dominate formularies through established ICU dosing algorithms. United States tertiary care centers concentrate procurement around rapid-infusion pump compatibility, with FDA hepatology drug guidance accelerating vasoactive agent approval timelines.
- Diagnostic Tools:Transcutaneous indocyanine green clearance sensors and hepatic oxygen saturation monitors displace laboratory-dependent workflows. German academic medical centers drive replacement demand exceeding thirty percent annually for new ICU installations, compressing diagnostic-to-treatment intervals from hours to minutes.
- Surgery:Revascularization procedures and transjugular intrahepatic portosystemic shunt interventions apply to refractory hypoperfusion cases.
- Supportive Care:Hemodynamic stabilization protocols and nutritional support frameworks address multi-organ dysfunction contexts.
Medication leads on scale; Diagnostic Tools leads on momentum.
Therapy Area:
Clinical ownership of shock liver protocols varies by hemodynamic stabilization philosophy and departmental staffing models.
- Critical Care:Intensivist-directed protocols govern first-line vasoactive administration through continuous hemodynamic monitoring. Japan's tertiary centers integrate hepatology-intensive therapy units with dual-trained specialists, though residency pipeline constraints limit expansion.
- Hepatology:Specialized liver services manage anticoagulant selection and hepatoprotective adjuvant therapy. Swiss and German academic medical centers anchor subspecialty consultation networks across European hospital systems.
- Emergency Medicine:Bedside liver function assessment initiates protocol activation within the critical six-hour window.
- Gastroenterology:Endoscopic intervention capabilities support portal decompression in selected presentations.
Critical Care commands patient volume; Hepatology commands protocol sophistication.
Delivery Mode:
Pharmacokinetic urgency and bioavailability requirements eliminate oral and topical routes from acute shock liver management.
- Intravenous:Continuous infusion pumps deliver titrated vasoactive doses with minute-to-minute adjustment capability. Central line placement in ICU settings enables immediate-dispense protocols rather than centralized pharmacy stocking.
- Subcutaneous:Low-molecular-weight heparin bridging and select hepatoprotective agents permit outpatient transition pathways.
- Oral:Maintenance anticoagulation and chronic hepatoprotective regimens apply only to stabilized convalescent phases.
- Topical:No relevant application in acute hepatic hypoperfusion injury management.
Intravenous dominates acute intervention; Subcutaneous enables care setting transition.
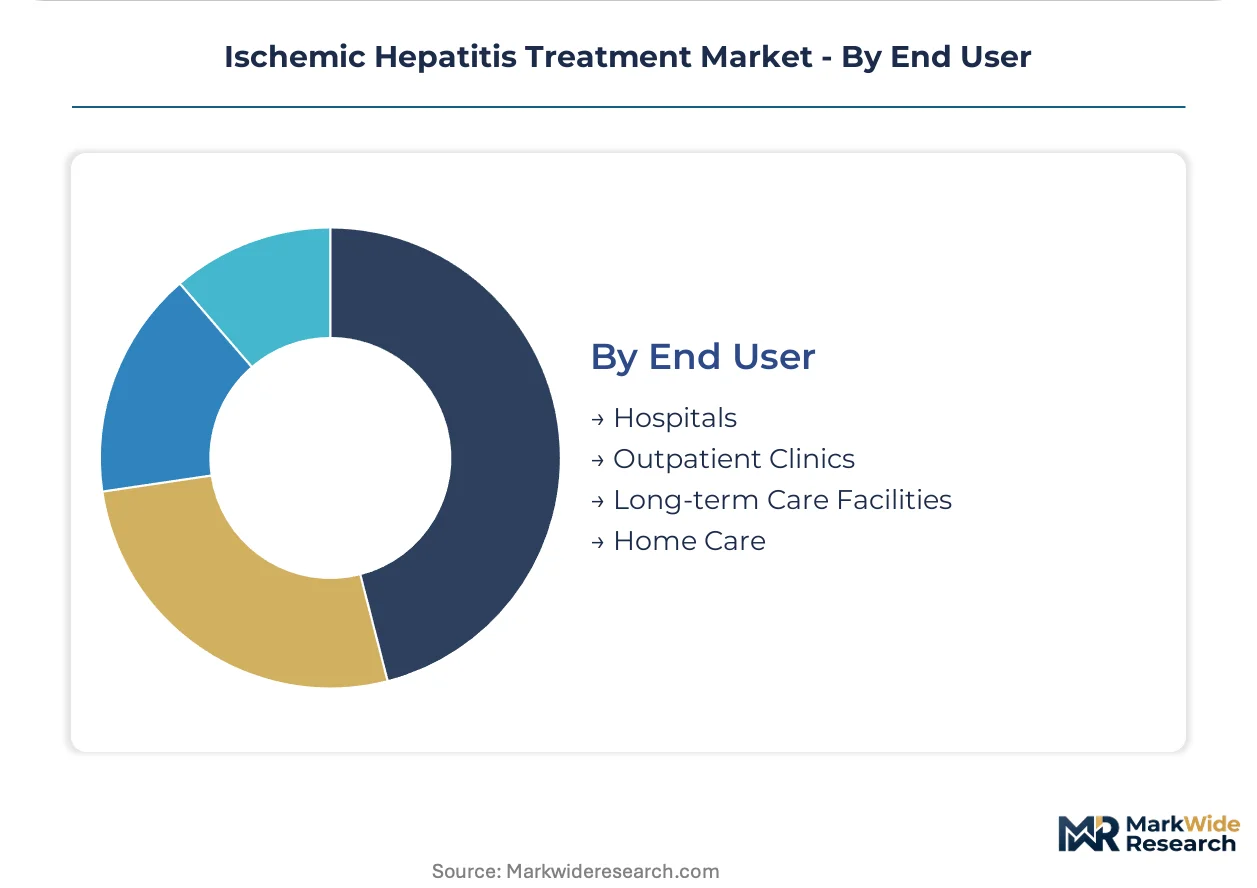
End User:
Capital intensity and specialist staffing density determine where ischemic hepatitis protocols achieve full implementation versus fragmented care.
- Hospitals:Tertiary care centers in Texas and California pilot shock liver-specific vendor scorecards with outcome-linked performance clauses. IDN pharmacy committees unbundle hepatology drug procurement from broad critical care contracts.
- Outpatient Clinics:Post-stabilization monitoring and anticoagulation management concentrate in hepatology-specialized ambulatory settings.
- Long-term Care Facilities:Limited applicability given acute intervention requirements and monitoring infrastructure needs.
- Home Care:Subcutaneous anticoagulation administration and remote monitoring technology enable selected post-acute pathways.
Hospitals concentrate treatment volume; Outpatient Clinics concentrate protocol extension.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ischemic hepatitis treatment protocols first achieved systematic standardization in German and Swiss academic medical centers during the early 2000s, establishing the hemodynamic monitoring frameworks now diffusing through tertiary care networks worldwide.
United States
Tertiary care centers in Texas and California pilot shock liver-specific vendor scorecards with outcome-linked performance clauses. FDA accelerated approval pathways for hepatology therapies compress clinical trial timelines for vasoactive agents. IDN pharmacy committees in the Southeast and Midwest unbundle hepatology drug procurement from broad critical care contracts.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia drive replacement demand exceeding thirty percent annually for transcutaneous liver function sensors. EU Green Deal healthcare decarbonization targets consolidate procurement standards across hospital networks. Berlin-Brandenburg anchors subspecialty consultation networks that license template protocols across European tertiary systems.
Japan
Tertiary centers integrate hepatology-intensive therapy units with dual-trained specialists, though residency pipeline constraints limit expansion. PMDA hepatology drug frameworks shape trial endpoints for shock liver interventions. The Kanto region concentrates bedside monitoring technology adoption in emergency departments.
India
CDSCO streamlined trial frameworks reduce import clearance timelines for hepatoprotective APIs, opening patient recruitment pools for multinational phase III studies. BIS pharmacovigilance standards impose batch-level adverse event reporting requirements on imported vasoactive agents. Maharashtra and Gujarat host manufacturing clusters for active pharmaceutical ingredients supplying first-line hemodynamic support drugs.
Switzerland
Swissmedic regulatory frameworks elevate clinical evidence requirements for hepatic perfusion monitoring devices. Novartis AG's established presence in Swiss academic medical centers creates template protocols for combination therapies. The Basel-Zurich corridor concentrates specialized antiviral and hepatoprotective research pipelines.
Ischemic Hepatitis Treatment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the vasoactive agent and diagnostic technology spectrum, with pricing power concentrating in firms controlling proprietary hemodynamic monitoring integration. The vendor base organizes around three strategic archetypes: integrated critical care portfolio holders, specialized hepatology research firms, and generic API suppliers serving formulary cost-containment mandates. Capacity expansion in bedside sensor manufacturing and strategic partnerships between pharmaceutical and device manufacturers constitute the dominant competitive moves reshaping market structure.
Within the integrated critical care tier, Pfizer Inc. and Gilead Sciences, Inc. occupy positions reflecting divergent strategic anchors. Pfizer Inc. leverages its established hospital system relationships to sustain presence in hepatology-intensive therapy units through formulary integration. Gilead Sciences, Inc. exemplifies the specialized hepatology research archetype, with its antiviral and hepatoprotective research pipelines anchoring protocol development in tertiary care centers. Novartis AG sits within the geographic dominance archetype, its Swiss and German academic medical center relationships creating template protocols that license across European hospital networks.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Pfizer Inc. |
| Gilead Sciences, Inc. |
| Sanofi S.A. |
| Novartis AG |
| AbbVie Inc. |
| Johnson & Johnson |
| AstraZeneca plc |
| Merck & Co., Inc. |
| Others |
Supply & Pricing Matrix
Hospital pharmacy committees unbundling hepatology drug procurement from broad critical care contracts are forcing pharmaceutical suppliers to restructure pricing around immediate-dispense protocols and outcome-linked performance clauses rather than volume-based rebates. This buyer-side consolidation compresses margins for generic vasoactive API suppliers while elevating pricing power for integrated critical care portfolio holders with verified carbon footprints under EU Green Deal mandates.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates proprietary hemodynamic monitoring-integrated vasoactive bundles from rapid-infusion pump-compatible generics and commodity norepinephrine APIs. Price differentiation rests on FDA accelerated approval status and MDR technical documentation completeness for bedside sensors. Cost compression in the economy tier is intensifying because Indian and Chinese API manufacturers face extended BIS pharmacovigilance compliance timelines. Outpatient clinics and long-term care facilities exhibit highest price sensitivity, while tertiary ICU pharmacy directors prioritize response-time guarantees over per-unit cost.
Supply Chain Analysis
Reverse-logistics flows for transcutaneous liver function sensors remain underdeveloped, with refurbishment programs concentrated in German and Swiss academic medical center networks rather than systematic OEM programs. Active pharmaceutical ingredient production for first-line vasoactive agents concentrates in Maharashtra and Gujarat manufacturing clusters in India, with secondary capacity in Chinese chemical hubs. Raw material dependencies center on norepinephrine bitartrate precursors, indocyanine green dye compounds, and specialized sensor membrane substrates. Single-source vulnerability in Indian API supply exposes formularies to CDSCO import licensing delays. Distribution runs through IDN pharmacy committees in the United States and centralized hospital procurement consortia across European networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through bedside diagnostic technology premiumization and carbon-verified API sourcing cost-downs as EU Green Deal procurement standards consolidate supplier pools.
For Market Incumbents: Deploy backward integration into sensor membrane substrate production to secure supply continuity for transcutaneous indocyanine green clearance devices. Fortify formulary position through MDR technical documentation pre-positioning ahead of EMA reclassification deadlines. Counter emerging entrant threat from AI-enabled perfusion prediction startups by accelerating hospital system partnership density in Texas and California IDN networks. For New Entrants and Emerging Players: Direct-to-clinician digital education platforms bypass incumbent GPO contract lock-in at tertiary emergency departments. White-space concentration in Indian CDSCO streamlined trial frameworks enables patient recruitment for multinational phase III shock liver studies. Target subcutaneous hepatoprotective agent transition protocols for outpatient clinic penetration with remote monitoring technology bundling. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized hepatology research firms holding proprietary antiviral-hepatoprotective combination pipelines. Five-to-ten year viability favors acquisition targets with established Swiss and German academic medical center template protocol licensing. Monitor FDA hepatology drug guidance expansion for accelerated approval pathway eligibility as inflection indicator for portfolio revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Bedside Sensor Manufacturing Scale-Up | CE marking under MDR Class IIb requirements demands prospective European patient outcome data submission. |
| Carbon-Verified API Sourcing | EU Green Deal healthcare decarbonization procurement standards favor suppliers with verified footprints in tenders. |
| AI-Enabled Perfusion Prediction Integration | Machine learning algorithms trained on ICU hemodynamic data streams enable preemptive intervention capabilities. |
| Hospital System Partnership Density | IDN pharmacy committees in Texas and California pilot shock liver-specific vendor scorecards with outcome clauses. |
| CDSCO Streamlined Trial Framework Utilization | Reduced import clearance timelines for hepatoprotective APIs open patient recruitment pools for phase III studies. |
Research Methodology
Coverage spans the United States, Germany, Japan, India, and Switzerland, with primary inputs from each market's tertiary care infrastructure. Intensive care unit pharmacy directors, hepatology-intensive therapy unit specialists, regulatory affairs leads at pharmaceutical manufacturers, and hospital procurement committee members provided qualitative ground-truth. Secondary validation drew from FDA hepatology drug guidance documents, EMA Medical Device Regulation classification notices, CDSCO clinical trial framework updates, BIS pharmacovigilance standards, and PMDA shock liver intervention filings. Bottom-up patient flow modeling and top-down pharmaceutical procurement value analysis were triangulated against sensor replacement rate data from German academic medical centers.
Granularity-level modeling treated medication formulation chemistry, diagnostic sensor architecture, therapy area clinical ownership, delivery mode pharmacokinetics, and end-user capital intensity as distinct forecast dimensions. Vasoactive agent revenue flows, transcutaneous monitoring device replacement cycles, and ICU protocol adoption curves were projected across the analysis window. CAGRs were derived from tertiary care bed expansion rates, hepatology-intensive therapy unit staffing pipeline outputs, and bedside liver function assessment technology penetration trajectories.
The model assumes a particular technology adoption path for transcutaneous indocyanine green clearance sensors; alternative pathways for laboratory-dependent diagnostics would alter the outlook for diagnostic tool revenue concentration. Forecasts reflect assumptions regarding FDA accelerated approval pathway stability, EU Green Deal procurement timeline adherence, and norepinephrine API supply continuity from Indian manufacturing clusters. Practitioners should monitor CDSCO import clearance policy shifts, MDR technical documentation completion rates, and dual-trained critical care-hepatology specialist residency graduation volumes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Cutaneous B-Cell Lymphoma Treatment Market
Specialty Medicine
Global Lung Transplant Therapeutics Market
Specialty Medicine
Epistaxis Market
Specialty Medicine
HTLV-1 Associated Myelopathy (HAM) Market
Specialty Medicine
Hairy Cell Leukemia Therapeutics Market
Specialty Medicine
Global Lichen Nitidus Treatment Market
Specialty Medicine
Generalized Myasthenia Gravis (GMG) Management Market
Specialty Medicine
Balantidiasis Treatment Market
Specialty Medicine
Global Tourette Syndrome Treatment Market
Specialty Medicine
Dermatomyositis Treatment Market
Specialty Medicine
Histamine Toxicity Market
Specialty Medicine
Global Allergy Vaccine Market
Specialty Medicine
Epileptic Seizures Treatment Market
Specialty Medicine
Autism Spectrum Disorder Management Market
Specialty Medicine
Transthyretin (TTR) Amyloidosis Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Market