
 Paper Shredder Market | 2026-2036
Paper Shredder Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Shredder Market Intelligence
The integration of Internet of Things (IoT) connectivity and smart sensor technology into high-capacity shredders is reconfiguring how enterprises manage document destruction workflows. Fellowes Brands leverages its strong brand recognition in the small office/home office (SOHO) and corporate segments. HSM GmbH + Co. KG differentiates through its focus on high-security, industrial-grade shredding systems for government and large enterprise clients. ACCO Brands competes with a broad portfolio spanning multiple price points and distribution channels, from retail to commercial supply.
A paper shredder is a mechanical device that cuts paper into fine particles to make documents unreadable. Devices are classified by security levels, like P-4 to P-7 ratings, which dictate the maximum particle size produced by cross-cut or micro-cut mechanisms. Micro-cut models are displacing lower-security types in corporate offices and government agencies due to stringent data protection needs. Strip-cut shredders now primarily serve the price-sensitive personal use segment where security is a lower priority.
Data protection laws such as Europe's GDPR and the US Health Insurance Portability and Accountability Act (HIPAA) directly mandate the secure destruction of sensitive physical documents. Compliance with these frameworks, alongside standards like ISO/IEC 21964 for information destruction, shapes product specifications for security levels. Stakeholder decisions will center on balancing investment in high-security physical shredding against the ongoing enterprise shift toward fully digital workflows.
Market Dynamics
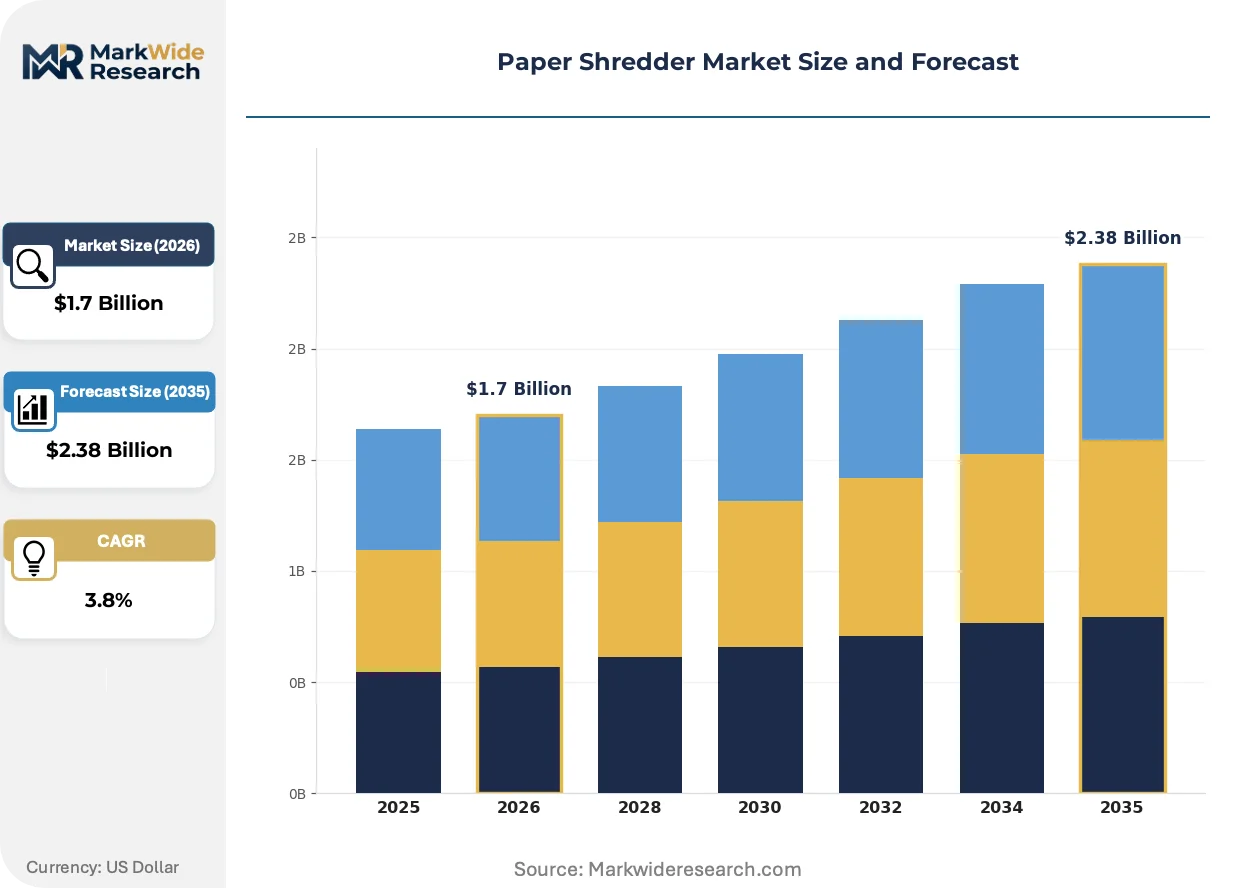
The central force shaping the paper shredder market is the escalating pressure from data privacy regulations. Mandates like Europe's GDPR and the US HIPAA are compelling organizations to move beyond basic document disposal toward certified, high-security destruction methods.
Growth Catalysts
- Data Protection Mandates:Stricter regulations, including Europe's GDPR, directly require secure destruction of physical documents containing personal data, compelling corporate investment in compliant, higher-security shredders to avoid significant financial penalties.
- Government and Defense Sector Demand:Government agencies and defense contractors require P-7 level micro-cut shredders to destroy classified and top-secret information, creating a consistent, non-discretionary demand segment for the highest security-rated equipment.
- Technology Accessibility:The falling production cost of micro-cut shredding mechanisms makes P-4 and P-5 security levels more accessible for small and medium-sized businesses, accelerating the upgrade cycle from less secure strip-cut models.
Market Restraints
- Digital Workflow Substitution:The enterprise-wide transition toward digital-native workflows and paperless office initiatives fundamentally reduces the total volume of physical paper generated, directly shrinking the core demand base for shredding equipment over the long term.
- High Initial Capital Outlay:Industrial-grade, high-security shredders represent a significant capital investment, which can be a barrier for smaller organizations or departments with limited budgets, slowing adoption despite compliance needs.
- Specialized Component Dependency:The market depends on a concentrated supply of hardened steel cutting cylinders, primarily from manufacturers in Germany and Japan, creating a vulnerability to supply chain disruptions and price volatility for critical components.
Strategic Opportunities
- Emerging Regulatory Markets:Untapped demand exists in Latin American and Southeast Asian countries where data privacy laws are beginning to be implemented, creating new growth frontiers for manufacturers who can establish early market presence.
- Integrated Smart Solutions:The convergence of shredders with IoT sensors offers new revenue streams through managed services, such as predictive maintenance, automated bin-full alerts, and integrated waste management for large corporate facilities.
- Material Destruction Diversification:There is an opportunity to develop and market specialized shredders capable of destroying non-paper media, including solid-state drives (SSDs), optical media, and ID cards, to provide a complete information destruction solution.
Industry Challenges
- Certification and Compliance Hurdles:Achieving and maintaining security level certifications, particularly for DIN 66399 or ISO/IEC 21964 standards, is a time-consuming and costly process that can delay product launches and limit market access for new entrants.
- Legacy System Integration:Integrating new, network-connected smart shredders with older enterprise IT security protocols and facilities management platforms presents significant technical challenges, potentially hindering adoption in established corporate environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Shredder Market |
| Market Size in 2026 | $1.7 Billion |
| Market Size in 2035 | $2.38 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Strip Cut, Cross Cut, Micro Cut, Confetti Cut Technology: Manual, Electric, Battery Operated, Automatic Application: Personal Use, Corporate Offices, Government Agencies, Educational Institutions End User: Small Businesses, Large Enterprises, Home Offices, Nonprofit Organizations |
| Companies Covered | Fellowes Brands, ACCO Brands, Intimus Shredders, HSM GmbH + Co. KG, Dahle North America, Inc., Martin Yale Industries, Krug & Priester GmbH & Co. KG, ELCOMAN Srl, Vecoplan LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Shredder Market Strategic Shifts & Innovations
The market is being redefined by the dual forces of stringent security requirements and the integration of smart technologies. This is pushing product development toward higher-value, specialized devices that fit into modern, connected office ecosystems while ensuring auditable data destruction.
Micro-cut shredding technology provides superior security by cutting documents into tiny, confetti-like particles. Corporate legal departments and government agencies are rapidly adopting these systems to meet stringent compliance standards. This technological shift is rendering obsolete the lower-security strip-cut and basic cross-cut models for any application involving sensitive or personally identifiable information.
Global standards like ISO/IEC 21964 are creating a universal language for information destruction security. This framework provides clear specifications for particle size and security levels, from P-1 to P-7, influencing product design and procurement decisions globally. The high-security segment is most affected, as manufacturers must engineer devices to meet these precise, internationally recognized benchmarks for irrecoverability.
A notable behavioral shift is the move from one-time equipment purchases toward comprehensive managed destruction services. This trend disrupts traditional direct-to-enterprise sales channels, favoring specialized service providers who purchase equipment in bulk and offer auditable, on-site or off-site shredding. This service-based model is most prominent in the North American healthcare sector, driven by HIPAA's strict chain-of-custody requirements.
Paper Shredder Market Segmentation
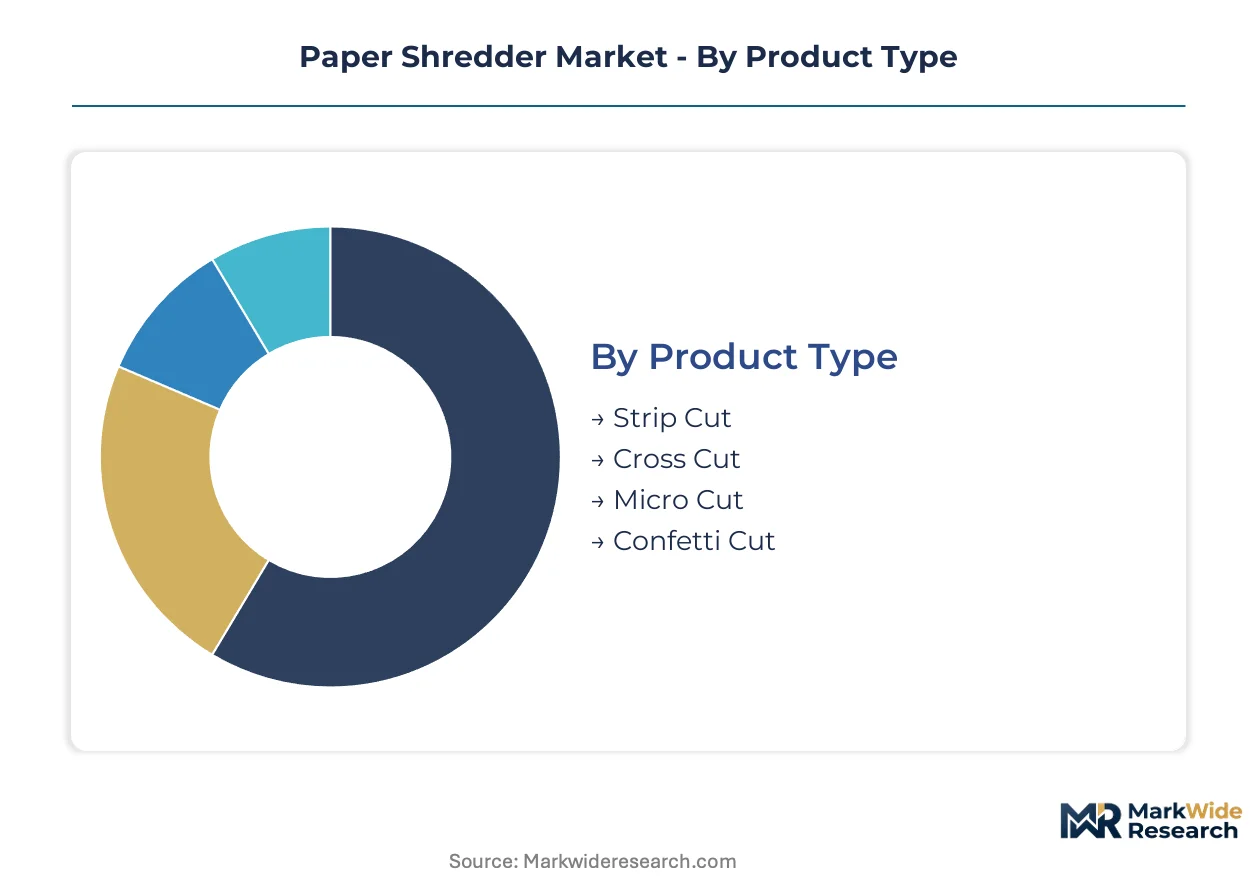
The paper shredder market segmentation provides a granular view of distinct product types, technologies, applications, and end-user requirements. Understanding these segments is crucial for manufacturers to tailor product development and for suppliers to optimize distribution strategies within a landscape shaped by evolving data privacy regulations.
Product Type:
The product type segmentation reveals varying replacement cycles, with high-security shredders typically having longer lifespans than basic models.
- Micro Cut:This product type reduces documents into extremely small, unrecoverable particles, often meeting P-6 or P-7 security standards. Demand concentrates in government agencies and corporate legal departments due to stringent data protection regulations like GDPR.
- Cross Cut:Cross-cut shredders slice paper both horizontally and vertically, producing small rectangular particles that meet P-3 to P-5 security levels. Corporate offices and healthcare providers widely adopt these models for HIPAA compliance and general sensitive document destruction.
- Strip Cut:Strip-cut shredders cut paper into long, narrow strips, offering the lowest security level (P-1 to P-2) for non-sensitive personal documents.
- Confetti Cut:Confetti-cut shredders produce small, irregular particles, providing a security level between cross-cut and micro-cut for varied office applications.
Cross Cut shredders dominate the installed base for general office use. Micro Cut is where expansion concentrates, driven by evolving data privacy mandates.
Technology:
Technology differentiation reflects the varying operational needs from personal convenience to industrial-scale document destruction.
- Electric:Electric shredders utilize a continuous power supply for sustained operation, offering various capacities and security levels for corporate environments. These models are the workhorse in most offices, balancing performance with cost-effectiveness for daily shredding volumes.
- Automatic:Automatic shredders feature self-feeding mechanisms, allowing users to load a stack of paper and let the machine shred autonomously. Large enterprises and busy government offices increasingly adopt automatic models to enhance efficiency and reduce manual labor for high-volume tasks.
- Manual:Manual shredders require hand-cranking, serving the most basic personal use segment where power access is limited or shredding volume is minimal.
- Battery Operated:Battery-operated shredders offer portability and convenience for small, occasional shredding tasks in mobile or remote office setups.
Electric models form the backbone of the installed shredder fleet. Automatic shredders are gaining share fastest within high-volume commercial settings.
Application:
The application segments delineate distinct user requirements, from individual privacy needs to institutional compliance protocols.
- Corporate Offices:This segment requires high-security shredders (P-4 to P-5) to comply with data protection laws and safeguard proprietary information. Demand is driven by the need for auditable destruction of sensitive client data and internal documents.
- Government Agencies:Government agencies mandate the highest security levels (P-6 to P-7) for destroying classified and top-secret information. Procurement decisions are heavily influenced by national security protocols and ISO/IEC 21964 standards.
- Personal Use:Personal use encompasses home office and individual consumer needs, primarily driven by basic privacy concerns for non-sensitive documents.
- Educational Institutions:Educational institutions require shredders for student records and administrative documents, balancing security needs with budget constraints.
Corporate Offices represent the largest segment by volume. Government Agencies exhibit the strongest demand for premium, high-security solutions.
End User:
End-user categories reflect varying purchasing power and willingness to invest in advanced shredding solutions, impacting supplier margins.
- Large Enterprises:These entities often require high-capacity, networked shredders with advanced features and managed destruction services for numerous departments. Their procurement prioritizes integration with existing IT infrastructure and comprehensive compliance reporting.
- Small Businesses:Small businesses seek cost-effective, reliable shredding solutions, typically P-3 to P-4 security, to manage customer data and internal records. Their purchasing decisions are often a balance between regulatory compliance and initial capital outlay.
- Home Offices:Home offices purchase compact, user-friendly shredders, primarily for personal financial documents and basic data privacy protection.
- Nonprofit Organizations:Nonprofit organizations utilize shredders for donor information and operational documents, often prioritizing durability and cost-efficiency within budget limitations.
Large Enterprises drive innovation in integrated smart solutions. Small Businesses represent a substantial, growing market for accessible mid-range security models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers often supply high-security paper shredders to corporate and government clients across Europe. This trade flow underscores the region's advanced manufacturing capabilities and stringent data protection requirements. Specific countries within this corridor exhibit distinct demand profiles shaped by local regulations.
Germany
Corporate offices and government bodies in Germany drive demand for high-security micro-cut shredders. Strict adherence to GDPR and national data protection laws, including DIN 66399, compels organizations to invest in certified destruction solutions. Manufacturing clusters in regions like Baden-Württemberg specialize in precision engineering for industrial-grade shredding systems.
United States
The United States market sees strong demand from healthcare providers and federal agencies. HIPAA regulations mandate the secure disposal of patient data, while government entities require P-7 level shredders for classified information. Major government procurement occurs in the Washington D.C. metropolitan area, influencing product specifications and security ratings.
United Kingdom
Financial services and legal sectors in the United Kingdom are significant consumers of paper shredders. Compliance with UK GDPR and other financial data protection acts necessitates robust document destruction protocols. London's financial district and legal firms consistently upgrade to higher-security models to mitigate data breach risks.
Japan
Japan's corporate sector emphasizes data security and precise document destruction, contributing to steady demand. The Act on the Protection of Personal Information (APPI) influences procurement decisions for sensitive corporate records. Tokyo's dense corporate environment and industrial regions contribute to both high-end shredder demand and specialized component manufacturing.
China
China's emerging corporate landscape and government agencies are increasingly adopting paper shredders for data protection. The Personal Information Protection Law (PIPL) is compelling organizations to implement secure destruction practices. Major economic centers like Shanghai and Beijing are seeing a rise in demand for mid-to-high security office shredders.
Paper Shredder Market Key Industry Players
Channel-controlling players compete with product-specialist players for market share in the paper shredder industry. The market exhibits a tiered structure, with industrial-grade manufacturers at the high end and mass-market brands serving the SOHO segment. Strategic archetypes include integrated solution providers, niche high-security specialists, and broad portfolio generalists. Portfolio diversification and geographic expansion represent dominant competitive moves among these archetypes.
On the premium-tier vector, HSM GmbH + Co. KG exemplifies specialization in industrial-grade, high-security systems for government and large enterprise clients. Fellowes Brands occupies a strong position across the small office/home office and corporate segments, leveraging its brand recognition for a wide array of office solutions. ACCO Brands represents a broad portfolio strategy, offering products across multiple price points and distributing through diverse retail and commercial channels.
| Leading Market Players |
|---|
| Fellowes Brands |
| ACCO Brands |
| Intimus Shredders |
| HSM GmbH + Co. KG |
| Dahle North America, Inc. |
| Martin Yale Industries |
| Krug & Priester GmbH & Co. KG |
| ELCOMAN Srl |
| Vecoplan LLC |
| Others |
Cost & Logistics Intelligence
Hardened steel cutting cylinder overcapacity in specialized manufacturing regions like Germany and Japan drives both supplier behavior and pricing posture across the paper shredder market.
Pricing Analysis
Cost-plus contracts with raw material indexation often govern pricing for industrial-grade shredders. Price differentiation stems from security certification levels, such as P-7 ratings, and the integration of smart features like IoT connectivity. Pricing pressure stems from the ongoing shift towards digital workflows, reducing the overall demand for physical shredding. Corporate offices exhibit moderate price sensitivity, balancing compliance needs with budget constraints, while personal use segments are highly price-sensitive.
Supply Chain Analysis
Specialized cutting cylinder manufacturers in Germany and Japan hold significant contract-manufacturing concentration for high-security shredder components. The supply chain draws from hardened steel as a critical raw material and relies on precision engineering for micro-cut mechanisms. Single-source vulnerability for these specialized components presents a structural supply chain risk. Distribution runs through a dual model, with direct sales to large enterprises and government agencies, alongside retail and commercial supply channels for SOHO and small business segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market's future success hinges on addressing a critical capability gap in integrated data destruction solutions that span both physical and digital media.
For Market Incumbents:Build an intellectual property moat around advanced micro-cut technology and integrated IoT solutions. Invest in R&D for multi-media destruction capabilities to counter the threat of digital workflow substitution. Focus on expanding managed destruction services, leveraging existing brand recognition and customer relationships to offer comprehensive compliance solutions to corporate clients.
For New Entrants and Emerging Players:Establish a beachhead in emerging regulatory markets within Latin America and Southeast Asia, where data privacy laws are nascent. Target small and medium-sized businesses with accessible P-4 and P-5 micro-cut models, offering a compelling blend of security and affordability. A go-to-market angle focusing on ease of compliance and cost-efficiency for regulated industries can drive initial adoption.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among providers of managed destruction services and integrated smart solutions. The long-term viability favors entities capable of providing auditable, end-to-end information destruction. Target acquisition archetypes include specialized component manufacturers or software firms with expertise in data management and compliance reporting. A signal to watch is the increasing adoption rate of P-6 and P-7 shredders in emerging markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Multi-Media Shredders | Expands market beyond paper, addressing the complete information destruction needs of corporate clients. |
| Expand Managed Service Offerings | Creates recurring revenue streams and deepens customer relationships through comprehensive solutions. |
| Invest in IoT Integration | Enhances operational efficiency and data audibility for large enterprise and government users. |
| Target Emerging Regulatory Markets | Unlocks new growth frontiers in regions implementing initial data privacy legislation. |
| Secure Hardened Steel Supply | Mitigates critical component supply chain risks and ensures production continuity for high-security models. |
Research Approach
Operator-level perspectives from procurement managers, IT security officers, compliance specialists, and facilities managers anchored the qualitative base for this analysis. This primary research was validated through extensive secondary data, including government regulations, industry association reports, and technical specifications from leading manufacturers. The study employed both bottom-up and top-down triangulation to ensure data accuracy.
Scenario-bracketing framed the forecast framework, accounting for varying speeds of digital transformation and regulatory enforcement across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and regional regulatory stringency. Compound annual growth rates were derived from historical trends and projected market shifts, with regulatory changes and micro-cut technology adoption serving as key forecast inputs.
Stress conditions across regulatory enforcement levels and raw material price volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding continued digital workflow adoption and increasing data protection mandates. Quarterly review of regulatory updates and micro-cut adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
North America Halal Food and Beverage Market
Others
Convenience Stores Market
Others
Allogeneic Human Chondrocyte Market
Others
Spend Analytics Market
Others
Signal Transformer Market
Others
Global Luxury High End Furniture Market
Others
Surgical Simulation Market
Others
Storage Dewars Market
Others
United States Bean Bags Market
Others
Nonlinear Editing System Market
Others
North America Wiring Duct Market
Others
North America Micro Market
Others
Industrial Air Pollution Control Solutions Market
Others
Pet Care Packaging Market
Others
Metal Air Battery Market
Others
Senior Cat Food Market