
 Green Technologies Market | 2026-2036
Green Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Green Technologies Market Intelligence
The capital-intensity divergence between integrated energy conglomerates and pure-play hardware vendors is unwinding competitive stability across the sector. General Electric leverages its turbine manufacturing heritage to anchor offshore wind deployments in European waters. Tesla sustains vertical control over battery cell chemistry and grid software, differentiating its utility-scale storage offerings from component-assemblers. Siemens competes through digital twin platforms that optimize renewable asset performance across heterogeneous generation fleets.
Green technologies encompass engineered systems that convert, store, or manage energy and resources with measurably lower lifecycle carbon intensity than incumbent alternatives, typically achieving 40-80% emissions reductions against fossil baselines depending on application and grid mix. Solar photovoltaic and energy storage segments command dominant capital flows as module costs fall and lithium-ion cell manufacturing scales, while bioenergy systems occupy narrower but defensible niches in waste-to-value and agricultural residue processing where feedstock logistics create natural moats. Carbon capture applications remain structurally premature for mass deployment, constrained by project finance availability and absence of durable offtake mechanisms at scale.
The EPA enforces stationary source emissions standards that directly mandate scrubber retrofits or fuel switching for coal-fired power plants, while the IRA's tax credit transferability provisions reshape project finance structures for domestic clean energy developers. EMA and REACH frameworks in Europe impose chemical substance registration requirements on battery electrolyte formulations and rare earth magnet compositions, raising compliance costs for non-EU suppliers seeking market access. Stakeholders must monitor how evolving carbon border adjustment mechanisms and domestic content thresholds interact to determine viable supply chain configurations without assuming regulatory continuity.
Market Dynamics
The Inflation Reduction Act's transferable tax credits are compressing project finance timelines for domestic clean energy developers, while lithium-ion supply concentration in East Asian cell manufacturers is forcing Western integrators to secure alternative chemistry pathways.
Growth Catalysts
- Production Tax Credit Transferability:The IRA's direct pay provisions eliminate tax equity bottlenecks for utility-scale solar and storage projects in the United States, accelerating deployment timelines for independent power producers.
- Coal Phase-Out Mandates:Germany's accelerated exit from lignite generation and India's national clean electricity standards are creating concentrated demand for grid-scale battery deployments to manage renewable intermittency.
- Solid-State Electrolyte Advances:Ceramic and sulfide-based cell architectures are reaching pilot-scale manufacturing, promising higher energy density for aviation and heavy-duty transport applications.
Market Restraints
- Lithium Carbonate Volatility:Battery-grade lithium compound prices swing with Chilean and Australian spodumene concentrate availability, compressing margin predictability for cell assemblers.
- Rare Earth Magnet Concentration:Permanent magnet supply chains for offshore wind turbines concentrate in Chinese separation and refining facilities, exposing European turbine OEMs to export restriction risk.
- Carbon Capture Economics:Absence of durable offtake mechanisms at scale and limited project finance availability constrain deployment of point-source capture systems beyond demonstration phases.
Strategic Opportunities
- Green Hydrogen Offtake:The EU Green Deal's renewable fuels of non-biological origin mandates create guaranteed demand corridors for electrolyzer operators serving ammonia and steel producers.
- Agrivoltaic Integration:Dual-use solar installations on agricultural land in Japan and France unlock constrained siting opportunities while generating supplemental revenue for farming operations.
- Virtual Power Plant Aggregation:Distributed battery and demand response assets are coalescing into grid-operable fleets through software platforms, creating new revenue stacks for residential and commercial storage owners.
Industry Challenges
- Electrochemical Engineering Talent Gap:Cell manufacturing scale-up outpaces university pipeline output for battery scientists and process engineers, forcing producers to poach from adjacent semiconductor and chemical sectors.
- Interconnection Queue Congestion:Grid operators in Texas and California face multi-year backlogs for renewable project energization, stranding committed capital and inflating carrying costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Technologies Market |
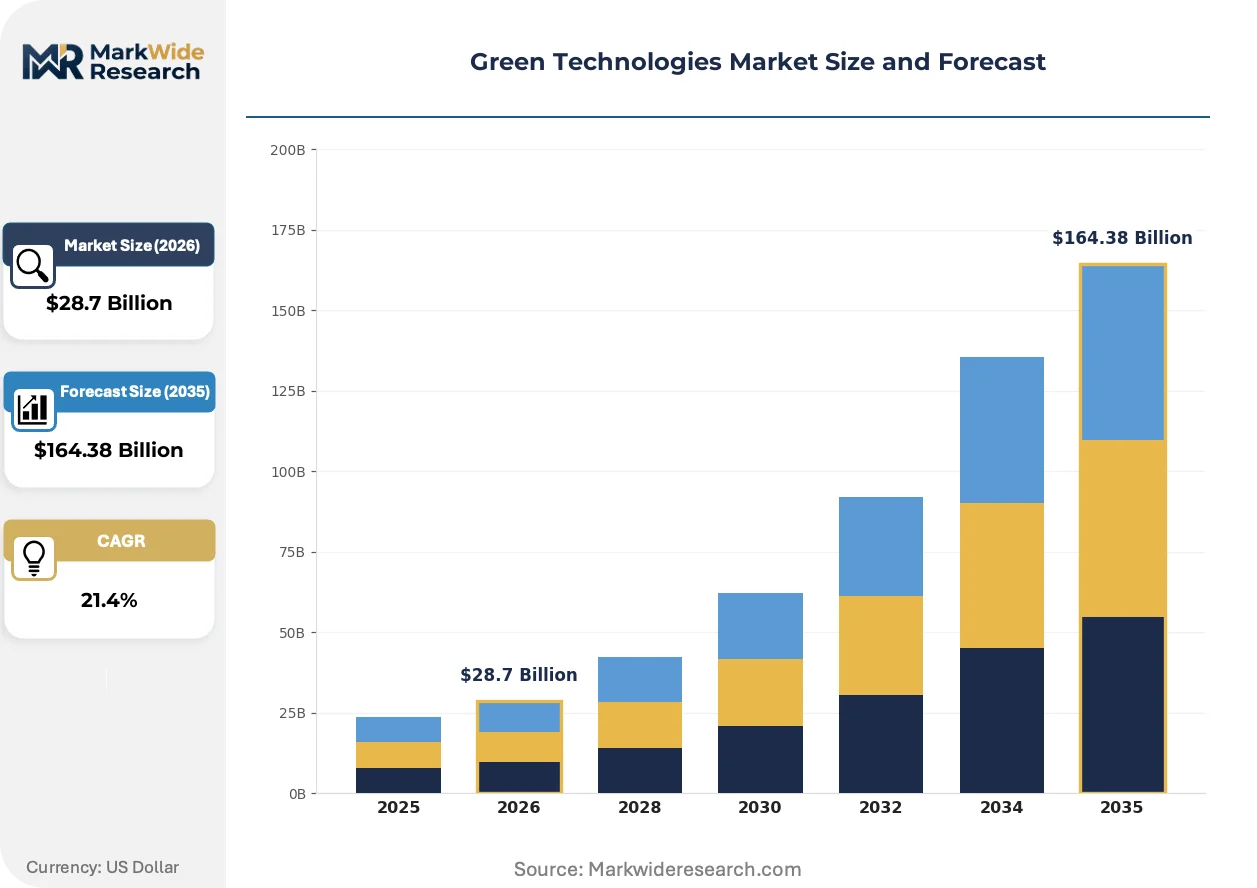
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $164.38 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar Photovoltaic, Wind Turbines, Bioenergy Systems, Geothermal Solutions, Energy Storage Application: Electric Grid Integration, Water Purification, Sustainable Agriculture, Waste Management, Carbon Capture Deployment Model: On-Premise Installations, Cloud-Based Platforms, Hybrid Systems, Distributed Networks, Edge Computing End User Industry: Renewable Energy Producers, Agricultural Firms, Environmental Agencies, Manufacturing Plants, Construction Companies |
| Companies Covered | General Electric, Siemens, Schneider Electric, IBM, Microsoft Corporation, SAP, Tesla, NextEra Energy, Vestas Wind Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Technologies Market Strategic Shifts & Innovations
Technology trajectories in the Green Technologies Market are diverging between incremental cell chemistry optimization and radical system architecture reinvention, with regulatory pressure accelerating both paths simultaneously.
Perovskite tandem solar architectures are fragmenting the crystalline silicon incumbent's cost advantage by layering wide-bandgap absorbers atop conventional cells to capture infrared transmission losses. European module integrators are piloting these stacks in building-integrated applications where space constraints justify premium efficiency. The structural consequence is compressing the efficiency threshold where novel thin-film technologies achieve bankability against field-proven monocrystalline alternatives.
REACH authorization requirements for PFAS substances are forcing electrolyte formulators to accelerate fluorine-free solvent development for lithium-metal and solid-state cell chemistries. The ECHA's restriction roadmap threatens incumbent LiPF6 salt supply chains, compelling European battery manufacturers to qualify alternative lithium borate and imide-based formulations. Cell producers with captive electrolyte blending capacity are responding fastest, while pure-play material suppliers face reformulation timelines that extend beyond the 2025 authorization deadlines.
Corporate renewable energy buyers are consolidating procurement through aggregated virtual power purchase agreements that pool offtake commitments across multiple C&I consumers. This buyer-side concentration is displacing traditional bilateral utility-scale contracting in deregulated markets like Texas and the PJM interconnection. The shift is most visible among data center operators and semiconductor fabs seeking to meet Science Based Targets initiative validation timelines without assuming single-project development risk.
Green Technologies Market Segmentation
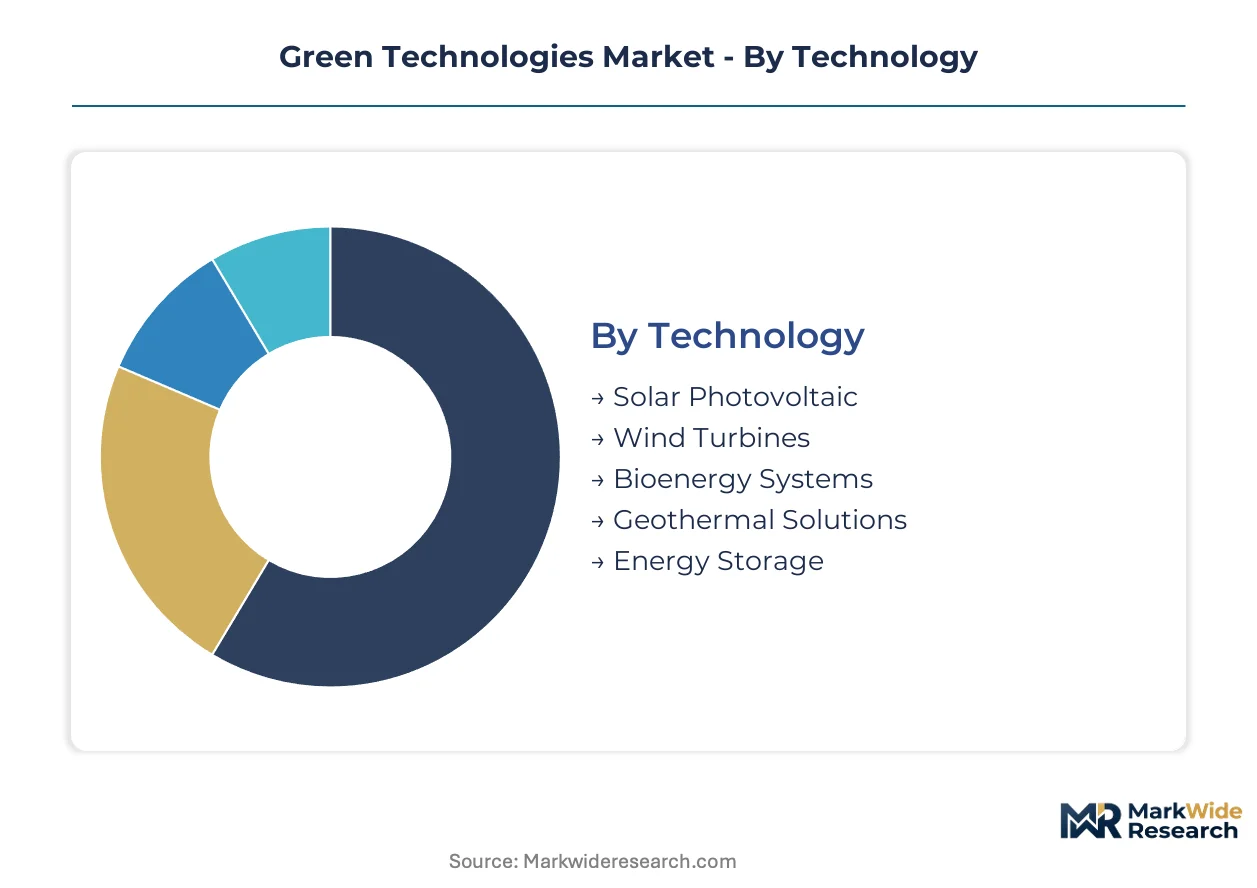
Technology trajectories in the Green Technologies Market fragment across hardware maturity curves and regulatory compliance thresholds. Each segment category carries distinct capital intensity profiles and certification requirements that reshape procurement patterns for end-users.
Technology:
EPA stationary source standards and IRA production tax credits differentiate investment viability across hardware categories, concentrating capital flows toward qualifying configurations.
- Solar Photovoltaic:Crystalline silicon modules dominate utility-scale deployments with proven bankability under FERC interconnection rules. Procurement concentrates among independent power producers in Texas and California seeking direct pay provisions under IRA transferability mechanisms.
- Wind Turbines:Offshore installations leverage larger rotor diameters and higher capacity factors than onshore alternatives. European waters host concentrated demand as REACH-compliant rare earth magnet supply chains face Chinese export restriction exposure.
- Bioenergy Systems:Anaerobic digesters and gasification units process agricultural residues and organic waste streams under EPA renewable fuel standard pathways.
- Geothermal Solutions:Binary cycle plants extract heat from low-to-moderate temperature reservoirs for baseload power generation.
- Energy Storage:Lithium-ion battery systems integrate with solar and wind assets to manage intermittency under grid operator dispatch protocols.
Solar Photovoltaic handles the majority of throughput; Energy Storage is expanding most quickly on share.
Application:
End-use deployment patterns track regulatory enforcement intensity and offtake mechanism durability across jurisdictions.
- Electric Grid Integration:Battery storage and smart inverter deployments stabilize renewable penetration levels under NERC reliability standards. ERCOT and CAISO interconnection queues show concentrated backlogs in Texas and California as developers await energization timelines.
- Carbon Capture:Point-source absorption systems remain structurally premature for mass deployment without durable purchase agreements. Project finance availability constrains deployment beyond demonstration phases despite EPA emissions mandates for coal retrofits.
- Water Purification:Membrane bioreactors and advanced oxidation processes treat industrial effluent under Clean Water Act discharge permits.
- Sustainable Agriculture:Precision irrigation and soil carbon monitoring systems align with USDA conservation program incentives.
- Waste Management:Plasma gasification and mechanical biological treatment facilities process municipal streams under RCRA subtitle D guidelines.
Electric Grid Integration commands the dominant capital allocation; Carbon Capture shows the steepest expansion trajectory conditional on offtake mechanism development.
Deployment Model:
Capital efficiency and operational control requirements segment procurement preferences across ownership structures.
- On-Premise Installations:Captive renewable generation assets at industrial facilities secure power price predictability under long-term PPAs. Manufacturing plants in Germany and India deploy on-site solar-plus-storage to meet coal phase-out compliance deadlines.
- Distributed Networks:Aggregated residential and commercial battery assets coalesce into grid-operable fleets through software orchestration. Virtual power plant platforms in Japan and France unlock new revenue stacks for behind-the-meter storage owners.
- Cloud-Based Platforms:Remote monitoring and predictive maintenance services optimize asset performance across heterogeneous generation portfolios.
- Hybrid Systems:Combined heat and power configurations integrate renewable generation with thermal storage for industrial process loads.
- Edge Computing:Localized data processing units reduce latency for real-time grid control applications at substation level.
On-Premise Installations anchor current deployment volumes; Distributed Networks are gaining share fastest as aggregation software matures.
End User Industry:
Procurement sophistication and balance sheet capacity segment demand intensity across buyer categories.
- Renewable Energy Producers:Independent power developers and utility affiliates finance utility-scale projects through tax equity or direct pay structures. IRA transferability provisions compress development timelines for domestic clean energy developers.
- Manufacturing Plants:Energy-intensive industrial facilities pursue on-site generation to hedge electricity price volatility and meet Science Based Targets initiative validation timelines.
- Agricultural Firms:Anaerobic digesters and agrivoltaic installations generate supplemental revenue under USDA rural energy programs.
- Environmental Agencies:Government entities procure remediation technologies under federal and state superfund allocations.
- Construction Companies:Green building integrators specify low-carbon materials and renewable systems for LEED certification compliance.
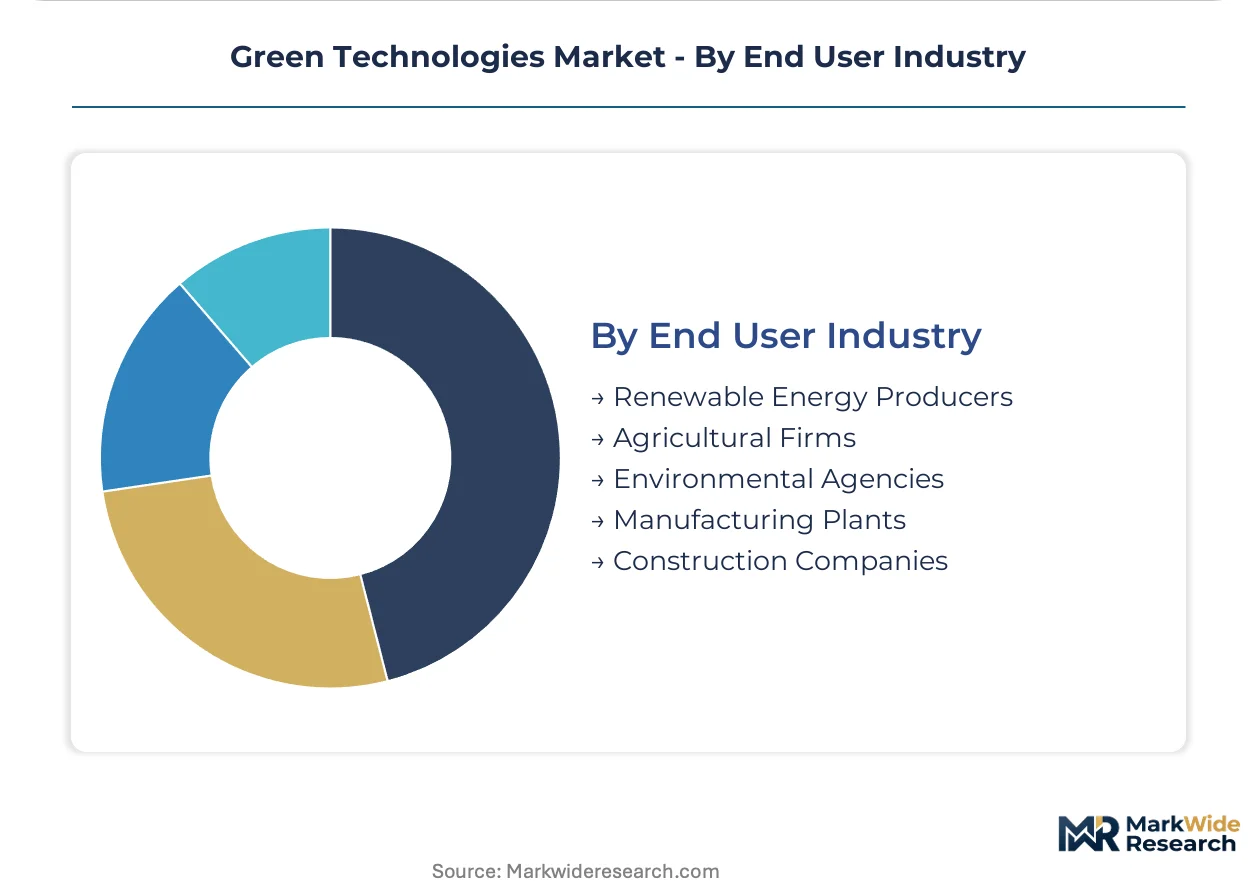
Renewable Energy Producers absorb the dominant share of capital deployment; Manufacturing Plants are climbing the fastest on procurement volume as electrification mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility-scale developers in India exhibit the highest price elasticity to module costs, while German industrial buyers absorb premium pricing for bankable supply chains. Chinese manufacturing clusters drive crystalline silicon economics downward. US tax credit transferability compresses project finance timelines regardless of capital cost fluctuations.
United States
Independent power producers in Texas and California dominate utility-scale solar-plus-storage procurement under IRA direct pay provisions. FERC interconnection rules and NERC reliability standards govern grid integration timelines. ERCOT's multi-year queue backlog strands committed capital in Houston and Dallas-Fort Worth clusters.
Germany
Accelerated lignite phase-out mandates concentrate demand for grid-scale battery deployments to manage renewable intermittency. REACH authorization requirements for PFAS substances force electrolyte reformulation timelines. Offshore wind manufacturing anchors in Bremerhaven and Cuxhaven ports facing rare earth magnet supply exposure.
India
National clean electricity standards and state-level solar parks drive concentrated procurement from independent power producers. CEA grid codes and PLI scheme incentives shape domestic manufacturing scale-up. Gujarat and Rajasthan host the dominant solar installation clusters with aggressive tariff undercutting.
China
Dual carbon goals and provincial renewable portfolio standards sustain manufacturing scale despite export restriction exposure on processed rare earths. MIIT industrial policy and GB standards govern cell chemistry certification. Yangtze River Delta and Pearl River Delta concentrate lithium-ion cell capacity.
Japan
Feed-in tariff reductions and grid saturation constrain utility-scale deployment, shifting focus toward distributed networks and agrivoltaic integration. METI long-term energy strategy and JIS standards govern behind-the-meter storage qualification. Kyushu and Tohoku regions pilot dual-use solar on agricultural land.
Green Technologies Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with capital intensity and regulatory compliance capabilities determining tier membership. Turbine manufacturers leverage heritage engineering assets to anchor offshore wind deployments. Battery cell producers sustain chemistry control and grid software differentiation. Digital platform vendors compete through asset optimization algorithms across heterogeneous generation fleets. Dominant competitive moves include strategic partnerships for supply chain security and capacity expansion in captive cell manufacturing.
Among integrated energy conglomerates, General Electric and Siemens occupy positions exemplifying turbine-to-grid vertical control, while Tesla anchors the pure-play storage tier with in-house cell production. These three companies represent distinct strategic archetypes: heritage industrial diversification, European engineering consolidation, and Silicon Valley vertical integration.
| Leading Market Players |
|---|
| General Electric |
| Siemens |
| Schneider Electric |
| IBM |
| Microsoft Corporation |
| SAP |
| Tesla |
| NextEra Energy |
| Vestas Wind Systems |
| Others |
Cost & Logistics Intelligence
Gigawatt-scale cell manufacturing in the Yangtze River Delta compresses unit economics for lithium-ion battery systems while simultaneously concentrating supplier leverage among Chinese cathode and electrolyte producers. This scale asymmetry creates price floors that Western integrators struggle to match without IRA production tax credit offsets or captive raw material offtake agreements.
Pricing Analysis
After-sales service revenue from predictive maintenance contracts and warranty extensions now drives lifetime value for grid-scale battery integrators more than upfront hardware margins. Three-tier pricing structure across premium, standard, and economy levels segments procurement based on cell chemistry sophistication and software analytics bundling. Cost compression in standard-tier lithium iron phosphate systems is intensifying because of Chilean and Australian spodumene concentrate volatility. Utility-scale independent power producers in Texas and California exhibit the highest price sensitivity, while German industrial buyers absorbing REACH compliance premiums show the least.
Supply Chain Analysis
Strategic stockpile preferences dominate raw material procurement as battery manufacturers buffer against lithium carbonate price swings and rare earth export restriction exposure. Concentrated refining capacity in China, South Korea, and Japan feeds cathode active material and electrolyte salt production. The supply chain draws from spodumene concentrate in Western Australia, Chilean brine operations, and Indonesian nickel laterite. Single-source vulnerability around Chinese rare earth separation facilities threatens European turbine OEMs. Distribution runs through tier-one integrators with captive cell manufacturing capacity rather than merchant component suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among aggregated corporate renewable energy purchasers pooling offtake commitments through virtual power purchase agreements, fragmenting traditional bilateral utility contracting channels.
For Market Incumbents: Compound defensive positioning by securing captive lithium refining capacity in North America to offset Chinese supply concentration exposure, and accelerate solid-state electrolyte R&D to differentiate from commodity cell assemblers. The threat of IRA domestic content threshold tightening demands backward integration into cathode precursor production. Certification investment in UL 9540A fire safety testing creates switching costs for utility customers evaluating storage vendors. For New Entrants and Emerging Players: Lead with agrivoltaic integration deployments in Japan and France where land-use constraints justify premium dual-use solar configurations and regulatory siting preferences reduce interconnection queue competition. The most penetrable segment is behind-the-meter commercial storage aggregation for virtual power plant participation. A software-first go-to-market angle bypasses capital-intensive cell manufacturing scale requirements. For Investors and Strategic Acquirers: Electrolyte formulators with fluorine-free solvent capabilities and captive blending capacity represent the priority acquisition archetype as REACH PFAS restrictions accelerate. Long-term viability hinges on qualifying alternative lithium borate and imide-based formulations before authorization deadlines. The signal to watch is ECHA restriction roadmap acceleration or Chinese rare earth export license tightening. Revision becomes warranted when carbon border adjustment mechanism coverage expands beyond pilot phases.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Domestic cell manufacturing scales under IRA production tax credit transferability provisions. |
| Power Purchase Agreement | Aggregated virtual PPA structures pool C&I offtake commitments across data center operators. |
| Technology Licensing | Perovskite tandem architectures license to European module integrators for building-integrated applications. |
| Vertical Integration into Storage | In-house battery cell chemistry control differentiates utility-scale offerings from component-assemblers. |
| Green Certification Program | Science Based Targets initiative validation timelines drive procurement from manufacturing plants. |
Research Approach
Cross-validation between primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators anchors the qualitative findings against secondary validation from EIA data, IEA reports, FERC filings, and project development databases. Bottom-up installation tracking across solar, wind, and storage segments triangulates against top-down capital flow analysis from tax equity and direct pay structures.
Sensitivity analysis on lithium compound price trajectories, interconnection queue clearance rates, and carbon border adjustment mechanism coverage shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include technology category, deployment scale tier, regulatory framework cluster, and regional grid operator territory. CAGRs derive from capacity addition run rates, learning curve cost reductions, and policy incentive phase-out schedules. Forecast inputs incorporate solid-state electrolyte manufacturing scale-up timelines and coal phase-out mandate enforcement intensity.
Forecasts assume regulatory continuity in IRA tax credit transferability, REACH authorization timelines, and EPA stationary source standards; material policy shifts would require re-modeling. Specific risk factors include lithium carbonate supply disruption, rare earth export restriction escalation, and interconnection queue congestion extending beyond current backlogs. Revision becomes warranted when battery-grade lithium compound prices sustain thresholds that compress developer returns below hurdle rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
North America Thermoformed Plastics Market
Others
Next Gen Video Codecs Market
Others
Asia-Pacific Eyelash Serum Market
Others
Three Proofing Rugged Tablet Market
Others
Connected Living Room Market
Others
Smart Badge Market
Others
Solar Animal Repellent Market
Others
Convertible Shipper Display Market
Others
Video-As-A-Service (Vaas) Market
Others
Duty Free Retail Market
Others
5G Tester Market
Others
Medical Simulation Market
Others
Process Instrumentation Equipment Market
Others
North America Smart Homes Market
Others
Construction Fabrics Market
Others
Automatic Barriers and Bollards Market