
 Double Card Mobile Phone Market | 2026-2036
Double Card Mobile Phone Market Size, Share, and Industry Trends Forecast 2026-2036
Double Card Mobile Phone Market Analysis
Online retail is reconfiguring how dual-SIM devices reach price-sensitive buyers across emerging economies. Samsung Electronics leverages its manufacturing scale to dominate mid-tier smartphone segments with dual-standby models. Xiaomi Corporation anchors volume through flash-sale platforms and direct-to-consumer logistics. OPPO Electronics differentiates via offline retail partnerships in Southeast Asian markets where tactile evaluation drives purchase decisions.
A double card mobile phone incorporates two subscriber identity module slots enabling concurrent network registration, typically supporting dual-standby or dual-active architectures with independent baseband processors or shared radio front-ends. The primary commercial purpose centers on cost arbitrage between carrier plans, geographic coverage optimization, and separation of professional versus personal communications. Smartphones command the dominant margin pool as 5G integration raises bill-of-materials complexity and average selling prices. Feature phones sustain volume in rural Africa and South Asia where dual-SIM utility outweighs smart capability requirements. Enterprise end users represent the fastest-growing adoption vector as bring-your-own-device policies formalize split-billing arrangements.
China's MIIT enforces GB standard compliance for electromagnetic compatibility and network access certification, directly gating market entry for unapproved dual-SIM hardware. India's BIS mandates safety testing under compulsory registration order provisions affecting imports from Shenzhen and Dongguan manufacturing clusters. The EU's REACH and RoHS frameworks constrain solder and substrate material selections for devices sold through European telecom operator channels. Stakeholders must monitor evolving e-waste directives and right-to-repair mandates that threaten sealed-unit designs favoring dual-SIM tray configurations.
Market Dynamics
Enterprise dual-SIM adoption is compressing procurement cycles as organizations consolidate work and personal lines onto single devices, while China's MIIT certification tightening raises compliance barriers for hardware entrants.
Growth Catalysts
- Enterprise BYOD formalization:Split-billing arrangements between employers and employees are standardizing dual-SIM deployment across financial services and logistics sectors, with dedicated work lines now a standard employment benefit.
- India's PLI scheme:Production-linked incentives for mobile handset assembly are attracting component manufacturers to Chennai and Noida, lowering landed costs for dual-SIM devices sold through retail and telecom operator channels.
- Dual-standby architecture maturation:Shared radio front-end designs are reducing bill-of-materials complexity, enabling mid-tier smartphone producers to offer concurrent network registration without dedicated baseband processors.
Market Restraints
- Input cost volatility:RF filter and antenna tuner component prices fluctuate with rare earth element supply from Myanmar and China's processing facilities, squeezing margins on sub-premium dual-SIM handsets.
- Supply concentration risk:Shenzhen and Dongguan manufacturing clusters control over 80% of dual-SIM tray and flex cable production, creating single-geography vulnerability for brands without diversified sourcing.
- Regulatory fragmentation:Divergent electromagnetic compatibility testing between China's GB standards, India's BIS compulsory registration orders, and EU REACH material constraints force redundant certification spend.
Strategic Opportunities
- Rural Africa feature phone penetration:Dual-SIM utility for cross-network cost arbitrage outweighs smart capability requirements in markets with intermittent 3G coverage, sustaining volume for basic dual-standby devices.
- EU right-to-repair mandates:Sealed-unit design restrictions favor modular dual-SIM tray configurations over embedded eSIM alternatives, preserving physical SIM slot demand through 2030.
- Flash-sale platform expansion:Direct-to-consumer logistics models in Southeast Asia bypass traditional distributor margins, enabling price-sensitive buyers to access dual-SIM smartphones at feature phone price points.
Industry Challenges
- Radio frequency engineering talent scarcity:Dual-active architecture design requires specialized expertise in interference mitigation and antenna isolation, with qualified engineers concentrated in Hsinchu and Seoul semiconductor clusters.
- Certification timeline compression:China's MIIT network access approval now averages 14-18 months for dual-standby variants, delaying product launches against faster single-SIM certification pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Double Card Mobile Phone Market |
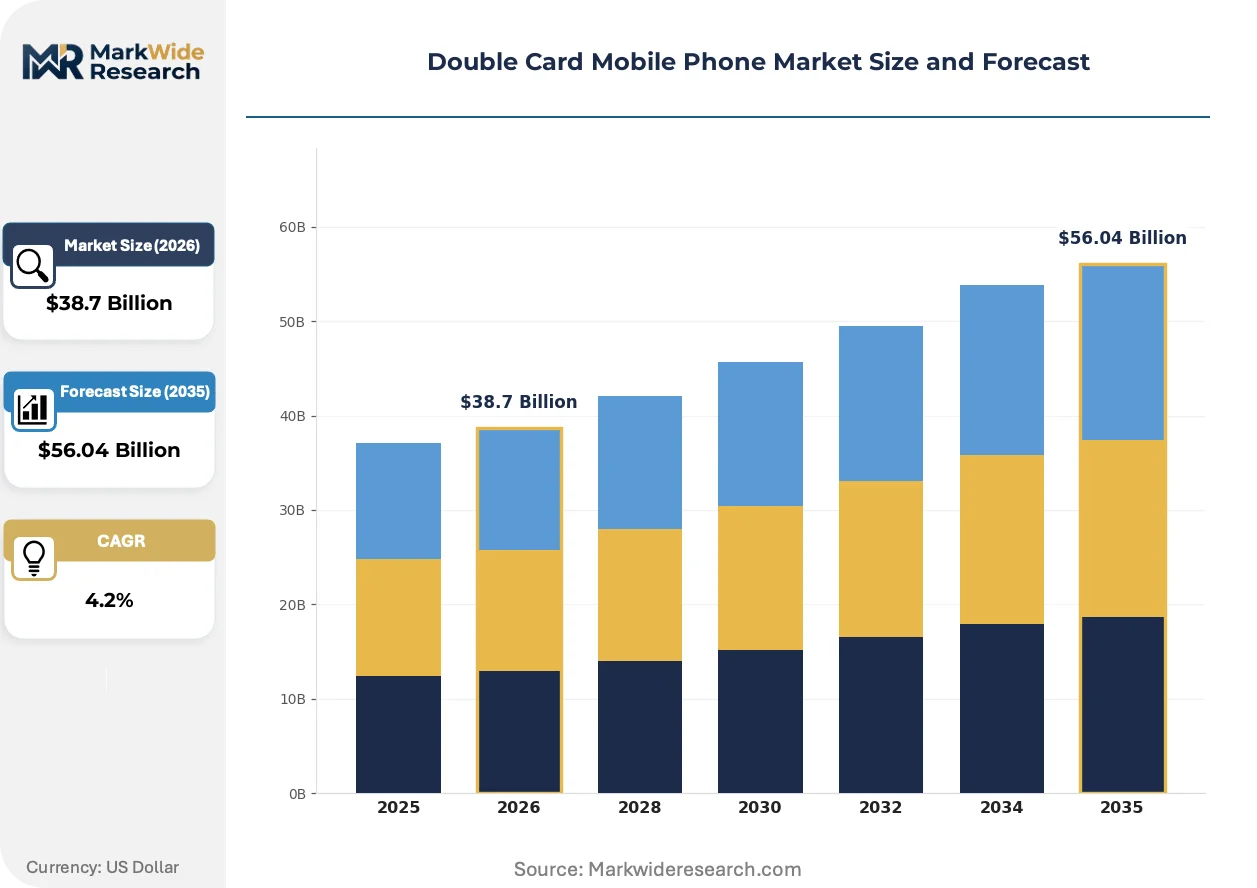
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $56.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Basic Phones, Feature Phones, Phablets Technology: 4G LTE, 5G, Wi-Fi, Bluetooth End User: Consumers, Enterprises, Retail, Government Distribution Channel: Online Retail, Offline Retail, Telecom Operators, Wholesalers |
| Companies Covered | Xiaomi Corporation, ASUSTeK Computer Inc., Samsung Electronics, HTC Corporation, OPPO Electronics, Huawei Technologies, Lenovo Group Limited, Motorola, Apple, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Double Card Mobile Phone Market Emerging Trajectories
Dual-SIM technology is pivoting from cost-driven emerging market utility toward enterprise security and compliance applications, with hardware architecture and distribution models adapting to split-use scenarios.
eSIM-dual-SIM hybrid architectures are migrating from flagship smartphone exclusivity toward mid-tier enterprise devices. Corporate IT departments are mandating physical SIM slots for carrier flexibility alongside embedded profiles for remote provisioning. This migration is compressing the addressable market for pure eSIM-only designs while extending dual-SIM relevance into premium segments previously targeted by single-SIM flagships.
China's MIIT has tightened GB standard electromagnetic compatibility thresholds for dual-standby certification, effective for all network access applications. Domestic manufacturers in Beijing and Shanghai are redesigning RF shielding and ground plane layouts to meet elevated spurious emission limits. Foreign brands without local engineering presence face extended retesting cycles and delayed market entry.
Telecom operator bundling is displacing open-channel retail as the primary dual-SIM acquisition path in Indonesia and Vietnam. Subscribers receive secondary SIM slots pre-provisioned with discounted data allowances, locking hardware to carrier ecosystems. This concentration is visible in Jakarta and Ho Chi Minh City, where operator-exclusive distribution now captures majority volume for sub-premium dual-SIM smartphones.
Double Card Mobile Phone Market Segmentation
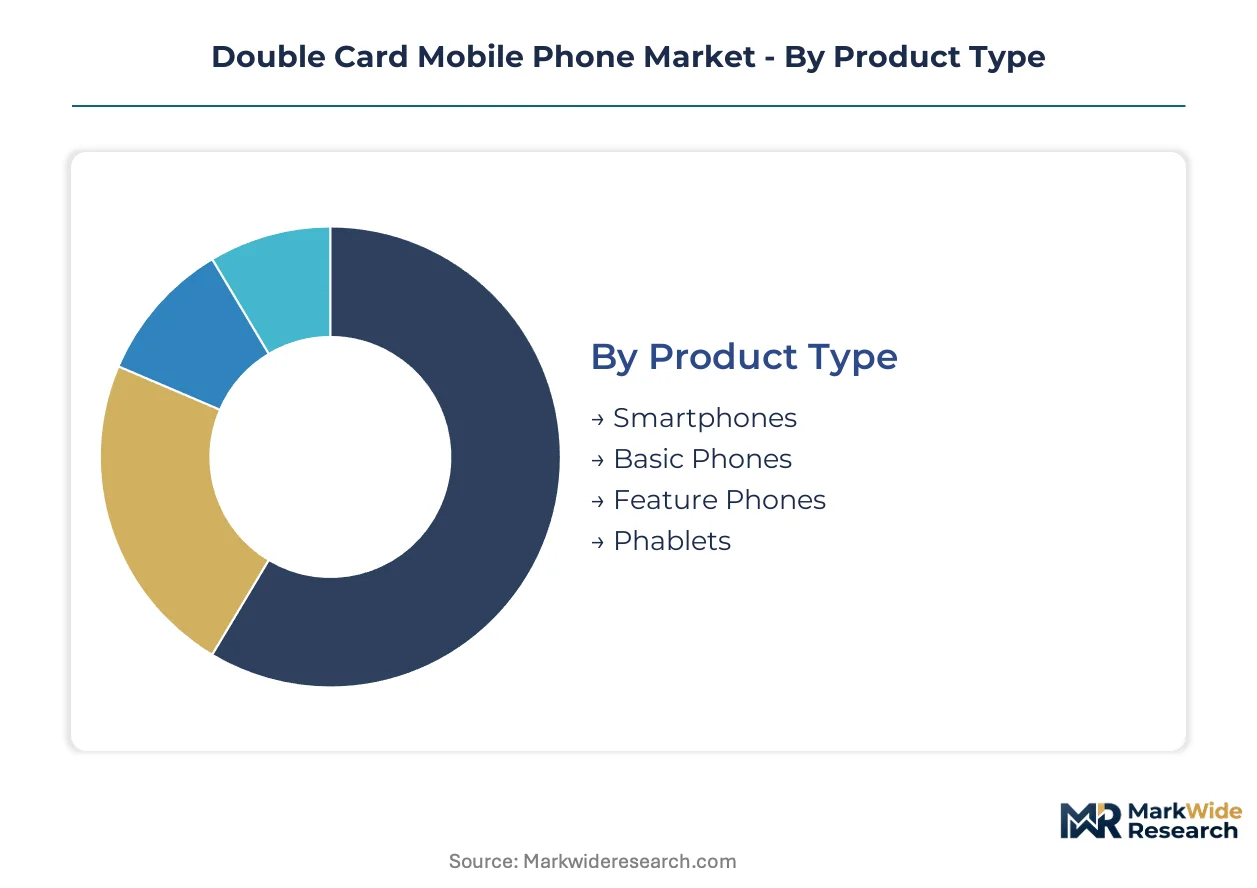
Dual-SIM device segmentation reveals divergent margin structures across hardware tiers and procurement channels. Service complexity varies sharply between enterprise fleet deployments and individual retail purchases, reshaping vendor support obligations.
Product Type:
After-sales service intensity escalates with device capability, as smartphones demand software update pipelines and warranty logistics that basic phones avoid entirely.
- Smartphones:Dual-standby 5G chipsets and app ecosystem dependencies drive enterprise IT support contracts and extended warranty attachments. Samsung Electronics and Xiaomi Corporation dominate procurement through split-billing BYOD arrangements in financial services.
- Basic Phones:Voice-centric dual-SIM utility sustains rural Africa and South Asian markets where intermittent 3G coverage outweighs smart capability requirements. Minimal service touchpoints and disposable price points compress vendor support costs to near-zero.
- Feature Phones:KaiOS-powered hybrids bridge cost arbitrage and limited app functionality for price-sensitive buyers in Indonesia and Vietnam.
- Phablets:Oversized dual-SIM screens serve media consumption and mobile gaming segments in Philippine and Thai urban markets.
By volume, Basic Phones leads. By growth pace, Smartphones is ahead.
Technology:
Cost tier stratification separates premium 5G integration from legacy 4G value engineering, with RF component selection determining margin trajectories.
- 4G LTE:Mature baseband processor supply and shared radio front-end designs enable sub-premium dual-standby pricing for India retail channels. TRAI spectrum allocation continues expanding 4G coverage into tier-three cities, sustaining volume relevance despite 5G transition.
- 5G:Dual-connectivity requirements and independent mmWave antenna modules raise bill-of-materials complexity for enterprise fleet refresh cycles. China's MIIT mandates 5G SA/NSA dual-mode certification, extending network access approval timelines.
- Wi-Fi:Dual-band MIMO integration supports voice-over-WiFi failover for enterprise split-line deployments.
- Bluetooth:Low-energy beacon pairing enables proximity-based enterprise security protocols.
By installed base, 4G LTE leads. By upgrade velocity, 5G is expanding most quickly.
End User:
Customer type determines procurement scale and contract structure, from individual retail transactions to multi-year fleet agreements.
- Consumers:Individual purchasers prioritize carrier plan arbitrage and personal-professional line separation through retail and flash-sale channels. Price elasticity concentrates demand in mid-tier dual-standby smartphones from Shenzhen manufacturing clusters.
- Enterprises:BYOD formalization and split-billing standardization are compressing procurement cycles across logistics and financial services sectors. Corporate IT mandates physical SIM slots alongside eSIM flexibility for carrier portability.
- Retail:Telecom operator bundling and channel inventory financing shape wholesale acquisition patterns.
- Government:Secure dual-line requirements and domestic certification preferences drive procurement from Beijing and Shanghai engineering centers.
By unit volume, Consumers leads. By contract value concentration, Enterprises is climbing the fastest.
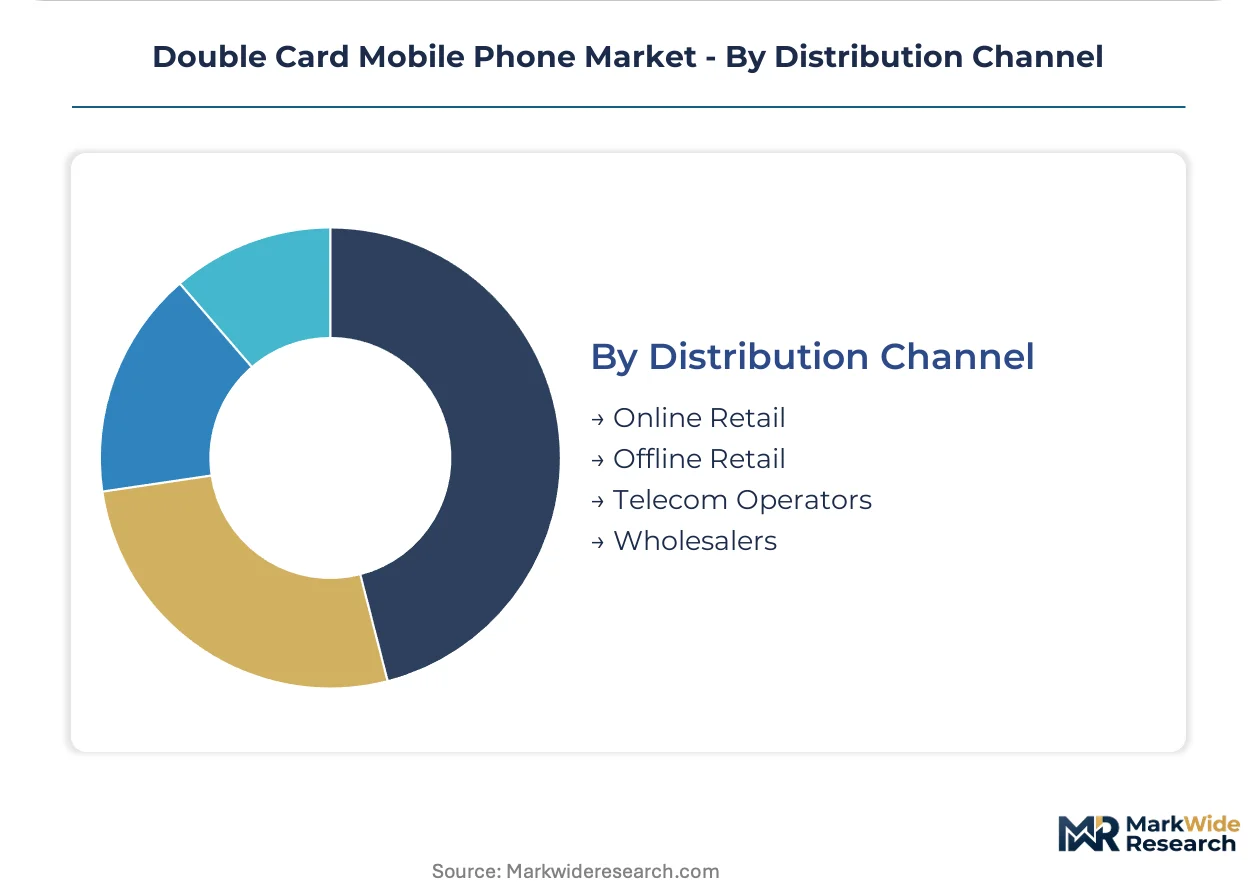
Distribution Channel:
Geographic reach and margin capture vary across direct-to-consumer logistics and traditional distributor networks.
- Online Retail:Flash-sale platforms and direct-to-consumer logistics bypass distributor markups for price-sensitive Southeast Asian buyers. Xiaomi Corporation leverages this channel for volume anchoring through limited-stock release cycles.
- Offline Retail:Tactile evaluation and immediate activation support dominate Indonesian and Vietnamese purchase decisions through OPPO Electronics partnerships.
- Telecom Operators:Pre-provisioned secondary SIM slots and subsidized data allowances lock hardware to carrier ecosystems in Jakarta and Ho Chi Minh City.
- Wholesalers:Bulk import and gray-market distribution sustain rural Africa and South Asian feature phone penetration.
By transaction volume, Offline Retail leads. By margin expansion, Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT certification protocols in China compress network access timelines for dual-standby hardware, while India's PLI scheme and BIS safety mandates reshape assembly economics across South Asian supply chains.
China
Enterprise fleet procurement and consumer dual-line separation drive volume in Beijing and Shanghai engineering centers. GB standard electromagnetic compatibility thresholds now mandate redesigned RF shielding for network access approval. Shenzhen and Dongguan manufacturing clusters control over 80% of dual-SIM tray production, creating concentrated component supply for domestic brands.
India
Retail channel penetration and telecom operator bundling anchor demand through Mumbai and Delhi-NCR distribution hubs. BIS compulsory registration orders enforce safety testing on imports from Chinese manufacturing clusters. PLI scheme incentives attract component manufacturers to Chennai and Noida assembly zones, lowering landed costs for mid-tier devices.
Indonesia
Operator-exclusive distribution and flash-sale platform expansion capture price-sensitive buyers in Jakarta and Surabaya metro areas. Pre-provisioned secondary SIM slots with subsidized data allowances lock hardware to carrier ecosystems. OPPO Electronics leverages offline retail partnerships where tactile evaluation dominates purchase decisions.
Vietnam
Telecom operator bundling displaces open-channel retail as the primary acquisition path in Ho Chi Minh City and Hanoi. Secondary SIM slots arrive pre-provisioned with discounted data allowances, concentrating volume in carrier-exclusive channels. Xiaomi Corporation deploys direct-to-consumer logistics through limited-stock release cycles.
South Korea
Dual-active architecture engineering expertise concentrates in Seoul and Hsinchu semiconductor clusters, creating talent scarcity for interference mitigation design. Corporate IT mandates for split-billing BYOD arrangements standardize dual-SIM deployment across financial services sectors. Samsung Electronics dominates mid-tier smartphone segments through manufacturing scale advantages.
Double Card Mobile Phone Market Vendor Landscape
Scale-driven conglomerates and specialized regional fabricators split the market into consolidated premium tiers and fragmented value segments. The vendor base organizes around three strategic archetypes: integrated electronics conglomerates with captive component supply, regional specialists leveraging flash-sale logistics, and telecom-captive brands anchored to operator distribution. Dominant competitive moves include backward integration into RF component manufacturing and exclusive operator partnership lock-ins across Southeast Asian markets.
Within the integrated conglomerate tier, Samsung Electronics and Xiaomi Corporation exemplify divergent scale strategies, while OPPO Electronics occupies a position bridging offline retail density with carrier ecosystem penetration. Chinese-originated limited companies dominate component-intensive segments where GB certification timelines favor domestic engineering presence. Seoul-based and Taipei-adjacent fabricators anchor dual-active architecture capabilities despite concentrated RF engineering talent pools.
| Leading Market Players |
|---|
| Xiaomi Corporation |
| ASUSTeK Computer Inc. |
| Samsung Electronics |
| HTC Corporation |
| OPPO Electronics |
| Huawei Technologies |
| Lenovo Group Limited |
| Motorola |
| Apple |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Shenzhen and Dongguan manufacturing clusters is compressing supplier margins and forcing extended payment terms onto component vendors, while simultaneously enabling aggressive pricing postures for dual-SIM tray and flex cable procurement by downstream brands.
Pricing Analysis
Geographic price spreads between flash-sale platforms in Southeast Asia and operator-bundled channels in Indonesia and Vietnam reach three-tier levels across premium, standard, and economy segments. Pricing pressure stems from RF filter and antenna tuner input cost volatility tied to rare earth element supply from Myanmar. Enterprise buyers exhibit lowest price sensitivity due to split-billing BYOD formalization, while rural African feature phone purchasers drive volume at disposable price points.
Supply Chain Analysis
Extended payment terms from Shenzhen and Dongguan manufacturing clusters are restructuring supplier-financing relationships for dual-SIM tray and flex cable procurement. Component supply draws from China, South Korea, and Taiwan for baseband processors and RF front-end modules. Single-geography concentration risk pervades tray manufacturing. Distribution runs through telecom operator bundling in Jakarta and Ho Chi Minh City alongside flash-sale direct-to-consumer logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
eSIM-only flagship designs threaten physical dual-SIM slot relevance, forcing incumbents to defend hybrid architecture positioning as enterprise IT departments mandate physical SIM flexibility.
For Market Incumbents: Pre-empt pure eSIM substitution by accelerating eSIM-dual-SIM hybrid deployment into mid-tier enterprise devices before carrier provisioning lock-in solidifies. Secure backward integration into RF filter manufacturing to offset rare earth element price volatility from Myanmar supply. Defend against flash-sale platform disintermediation by anchoring exclusive operator partnerships in Vietnam and Indonesia. For New Entrants and Emerging Players: Build out white-space presence in rural African feature phone segments where dual-SIM utility for cross-network cost arbitrage outweighs smart capability requirements. Target KaiOS-powered hybrid devices in Indonesian and Vietnamese markets underserved by premium smartphone incumbents. Deploy direct-to-consumer logistics through limited-stock release cycles mirroring Xiaomi Corporation's flash-sale model. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among enterprise fleet management providers with multi-year split-billing contracts in financial services and logistics sectors. Long-term viability hinges on RF engineering talent access in Hsinchu and Seoul semiconductor clusters. Monitor MIIT certification timeline compression as inflection signal for domestic Chinese brand competitive advantage.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Active Architecture R&D Investment | Seoul and Hsinchu engineering clusters anchor interference mitigation expertise for premium enterprise devices. |
| Operator Partnership Lock-In | Jakarta and Ho Chi Minh City carrier bundling displaces open-channel retail for sub-premium smartphone volume. |
| RF Component Backward Integration | Captive supply of antenna tuners and filters insulates margins from Myanmar rare earth volatility. |
| Flash-Sale Platform Expansion | Limited-stock release cycles bypass distributor markups for price-sensitive Southeast Asian buyers. |
| MIIT Certification Pre-Approval | Beijing and Shanghai engineering presence compresses 14-18 month network access timelines for dual-standby variants. |
Methodological Framework
A standing panel of RF engineering directors, telecom operator procurement leads, enterprise IT fleet managers, and flash-sale platform logistics heads provided ongoing calibration across the analysis window. Primary interview data combined with secondary validation from MIIT network access filings, BIS compulsory registration orders, TRAI spectrum allocation records, and customs import data from Shenzhen and Dongguan manufacturing clusters. Bottom-up shipment modeling and top-down bill-of-materials cost triangulation anchored volume and value estimates.
Scenario-bracketing around 4G-to-5G transition velocity, enterprise BYOD formalization pace, and eSIM adoption curves shaped projection ranges across the modeling period. Segmentation dimensions included product type, technology tier, end-user archetype, and distribution channel. CAGRs derived from fitted growth curves against historical smartphone refresh cycle patterns and carrier subsidy phase-out trajectories in Indonesia and Vietnam.
Stress conditions across rare earth element supply disruption, MIIT certification timeline extension, and operator bundling concentration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding dual-standby architecture maturation and PLI scheme incentive continuity. Macroeconomic contraction, regulatory fragmentation escalation, or eSIM mandate acceleration would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Nuclear Power Cables Market
Others
Gem Faceting Machine Market
Others
Insoluble Sulfur Market
Others
Sunflower Husk Pellets Market
Others
Inorganic Tin Chemicals Market
Others
Human Enhancement Technology Market
Others
United States Bean Bags Market
Others
Hookah Tobacco Market
Others
Calcined Petroleum Coke Market
Others
France 3D Printing Construction Market
Others
Italy 3D Printing Construction Market
Others
Hardwood Market
Others
Couscous Market
Others
Europe Air Separation Unit Market
Others
Germany 3D Printing Construction Market
Others
Allogeneic Human Chondrocyte Market