
 Nonlinear Editing System Market | 2026-2036
Nonlinear Editing System Market Size, Share, and Industry Trends Forecast 2026-2036
Nonlinear Editing System Market Analysis
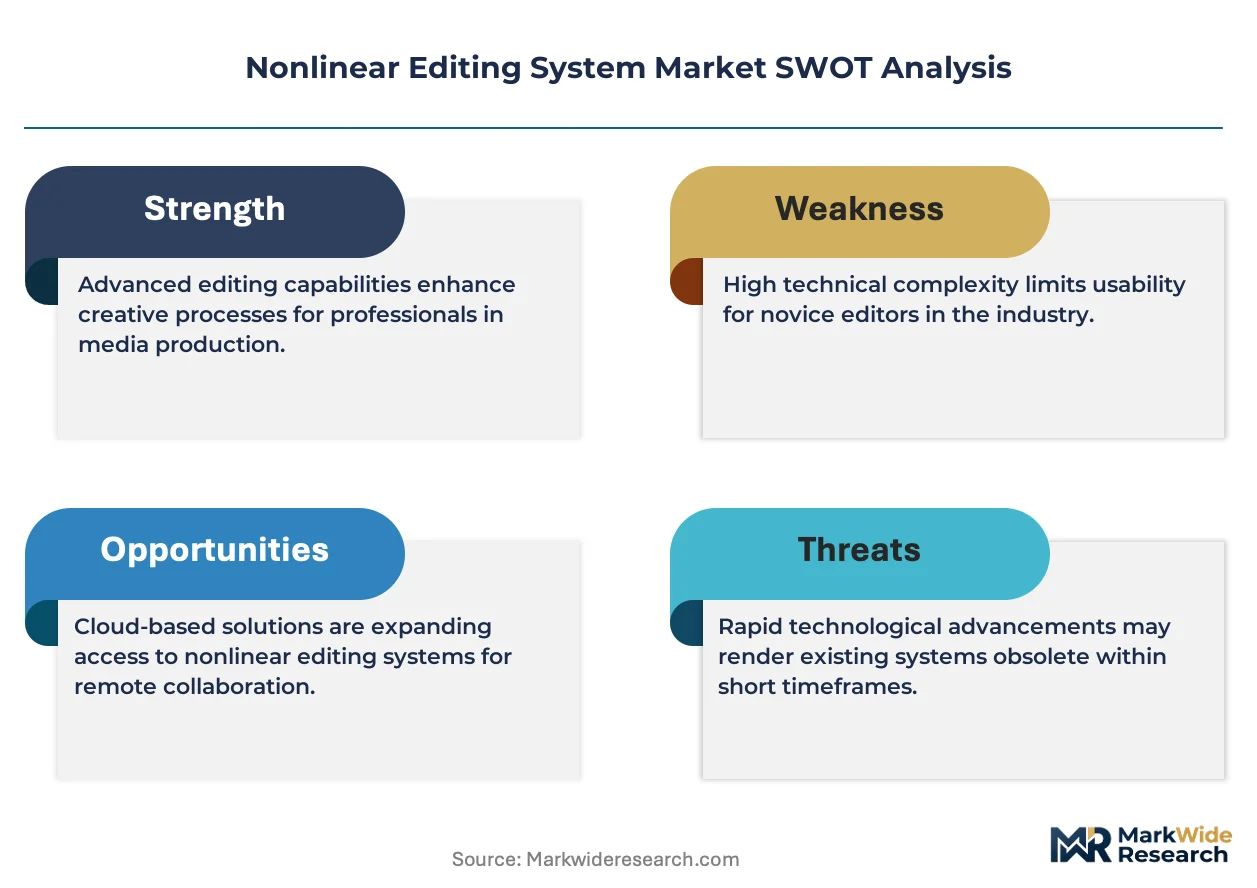
Software licensing revenue is narrowing as cloud-based subscription models displace perpetual licenses across professional post-production workflows. Adobe Systems Incorporated leverages its Creative Cloud ecosystem to sustain recurring revenue from broadcast and studio clients. Blackmagic Design anchors its position through integrated hardware-software bundles for independent filmmakers. Avid Technology competes in high-end television production with media asset management extensions.
A nonlinear editing system is a digital post-production platform that manipulates video and audio source material through random-access frame navigation without destructive sequential processing, typically supporting resolutions from HD to 8K with codec-agnostic timeline architecture. Its primary commercial purpose is enabling iterative creative revision for film, television, and streaming content delivery. Cloud-based solutions are capturing the fastest expansion as distributed production teams demand real-time collaboration features across SaaS deployment models. Hardware configurations retain margin concentration in premium color grading and multi-camera editing suites for theatrical release workflows.
The Federal Communications Commission shapes terrestrial broadcast standards that influence codec and resolution requirements for editing system compatibility, while the International Organization for Standardization defines container formats and metadata exchange protocols that vendors must support for interoperability. Content creators and broadcast engineers must monitor how hybrid deployment architectures evolve under emerging data sovereignty frameworks.
Market Dynamics
Cloud rendering pipelines and remote collaboration protocols are displacing legacy workstation dependency across post-production workflows, compressing capital requirements while redistributing technical talent geographically away from traditional studio clusters.
Growth Catalysts
- Original Content Investment:Streaming platforms are expanding production budgets for exclusive film and television series, directly expanding demand for professional editing infrastructure across Los Angeles, London, and Mumbai post-production clusters.
- FCC Terrestrial Standards:The Federal Communications Commission mandates codec and resolution specifications that force broadcast infrastructure upgrades, ensuring replacement cycles for editing hardware and software compatibility layers.
- 8K Acquisition Pipelines:Camera manufacturers are shipping 8K-capable cinema equipment to documentary and commercial production houses, necessitating timeline architectures with higher throughput and storage bandwidth.
Market Restraints
- GPU Supply Concentration:Premium color grading and real-time playback depend on NVIDIA and AMD accelerator cards sourced primarily from Taiwanese foundries, exposing post-production facilities to semiconductor allocation volatility.
- Perpetual License Collapse:Studios with amortized perpetual software licenses face forced migration to subscription models, compressing multi-year budgeting predictability and inflating total cost of ownership for independent filmmakers.
- Interoperability Friction:ISO container format standards and proprietary codec implementations create timeline translation failures between vendor ecosystems, fragmenting collaborative workflows across distributed production teams.
Strategic Opportunities
- SaaS Deployment Models:Cloud-native editing platforms can capture post-production demand in secondary cities lacking local render farm infrastructure, particularly in Atlanta and Austin where streaming content investment is concentrating.
- Remote Collaboration Features:Real-time proxy streaming and cloud-based media asset management enable talent arbitrage across time zones, allowing facilities to hire colorists and editors from Eastern European markets at reduced labor rates.
- AI-Assisted Editorial Tools:Machine learning algorithms for automated scene detection and dialogue transcription are converging with traditional timeline interfaces, creating premium tier differentiation for high-volume unscripted content producers.
Industry Challenges
- Color Science Expertise Gap:HDR and wide-gamut color pipelines require specialized calibration knowledge that outpaces vocational training program output, forcing facilities to poach talent or invest in extended onboarding cycles.
- Legacy Archive Integration:Decades of tape-based and early-digital source material stored in proprietary formats demand transcoding infrastructure and metadata reconstruction before incorporation into modern timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonlinear Editing System Market |
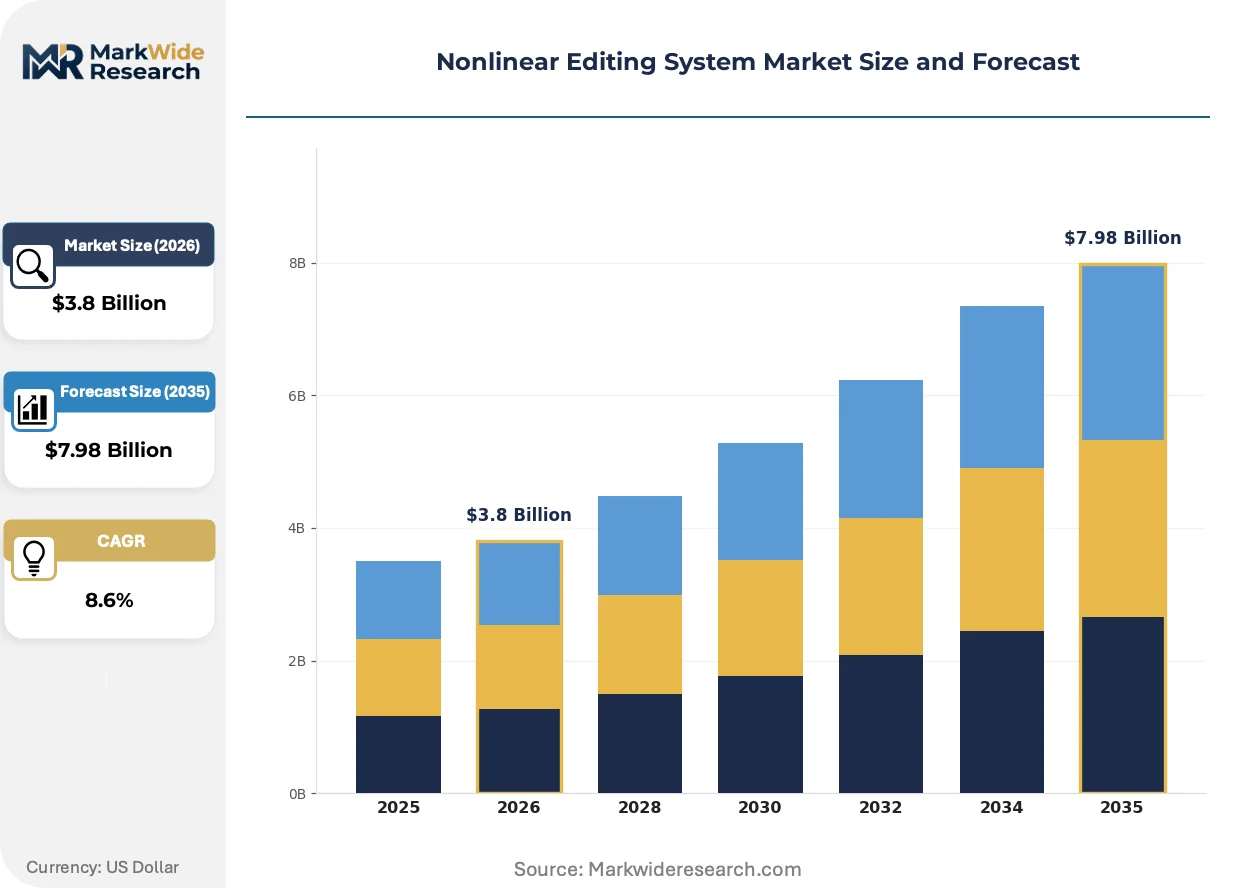
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Cloud-based Solutions, Hybrid Systems Deployment Model: On-premises, SaaS, PaaS, Hybrid End User: Film Production, Television Broadcasting, Content Creators, Educational Institutions Feature: Real-time Collaboration, Multi-camera Editing, Color Grading, Proxy Editing |
| Companies Covered | MAGIX Software GmbH, Corel, Adobe Systems Incorporated, Blackmagic Design, CyberLink Corp, Avid Technology, Microsoft, TechSmith Corporation, Apple, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonlinear Editing System Market Emerging Trajectories
Post-production infrastructure is fragmenting between cloud-native SaaS platforms and specialized on-premise suites, with adoption patterns diverging by project budget tier and security sensitivity rather than consolidating around a single architecture.
Cloud-native editing software is digitizing traditional hardware-bound workflows by moving compute-intensive rendering to distributed server farms. Mid-tier commercial production houses in Chicago and Toronto are adopting these platforms fastest, eliminating upfront capital expenditure while enabling real-time collaboration between editors and clients separated by thousands of miles.
The FCC maintains terrestrial broadcast standards that shape codec requirements and resolution roadmaps for editing system vendors serving US television networks. These mandates force continuous software update cycles, particularly affecting local station groups that must maintain compatibility with both legacy SD archives and emerging ATSC 3.0 transmission specifications.
Buyer behavior is fragmenting across subscription fatigue and perpetual-license nostalgia, with high-end theatrical facilities resisting SaaS models while independent creators embrace monthly billing. This tension is most visible in New York and Los Angeles, where studio post departments negotiate enterprise agreements while freelance editors purchase individual seats through direct-to-consumer channels.
Nonlinear Editing System Market Segmentation
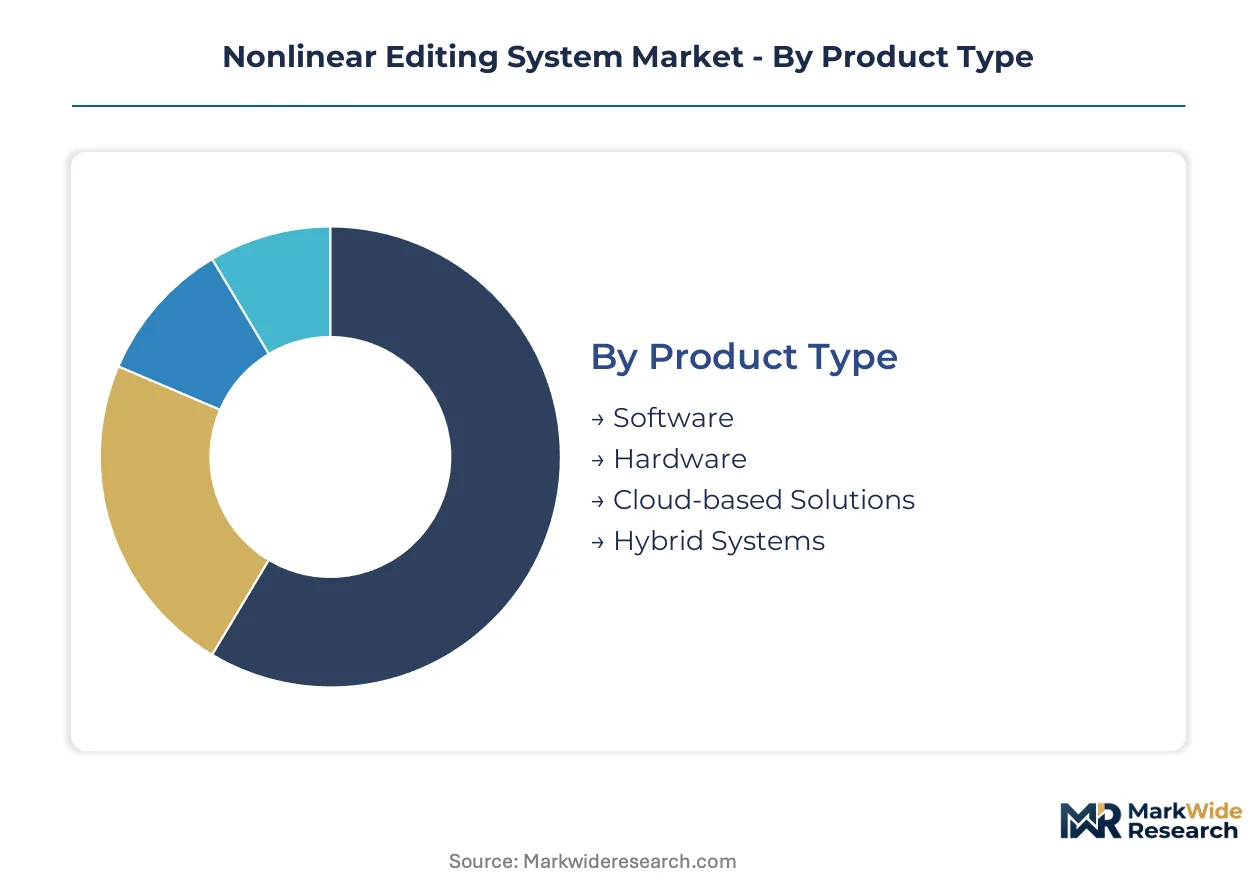
Nonlinear editing system purchasing decisions diverge sharply across technical requirements and budget tiers. Production houses evaluate codec support, timeline architecture, and collaboration capabilities against project scale and delivery deadlines.
Product Type:
Software licensing and hardware configurations span independent creators to theatrical release facilities.
- Software:Codec-agnostic timeline engines support resolutions from HD through 8K with plugin extensibility. Post-production clusters in Los Angeles and London prioritize software with robust API access for pipeline integration.
- Hardware:Dedicated accelerator cards and specialized control surfaces enable real-time 8K playback and precision color manipulation. Premium theatrical facilities in Mumbai maintain hardware suites for HDR mastering and broadcast compliance.
- Cloud-based Solutions:Distributed rendering infrastructure eliminates local compute investment for remote teams.
- Hybrid Systems:On-premise proxy editing with cloud finishing balances security and collaboration flexibility.
The dominant share belongs to Software, while Cloud-based Solutions is closing the gap fastest.
Deployment Model:
Capital expenditure constraints and data sovereignty requirements shape infrastructure decisions across facility tiers.
- On-premises:Physical server installations with dedicated storage arrays maintain editorial control over sensitive unreleased content. Major studio post departments in Burbank and Culver City retain on-premise dominance for tentpole franchise security protocols.
- SaaS:Browser-accessible timelines with automatic version synchronization reduce IT overhead for distributed productions. Commercial houses in Atlanta and Austin adopt SaaS fastest where streaming content investment concentrates without legacy infrastructure.
- PaaS:Customizable development environments enable pipeline-specific workflow automation.
- Hybrid:Mixed architectures allow local editorial with cloud-based review and delivery.
On-premises retains margin concentration in premium tiers, yet SaaS is expanding most quickly among mid-market entrants.
End User:
Content production volume and delivery specifications create distinct purchasing patterns across verticals.
- Film Production:Theatrical release workflows demand RAW codec support, advanced color science, and DCP packaging integration. Feature post facilities in London and Los Angeles require frame-accurate conform and IMF delivery capabilities.
- Television Broadcasting:FCC-mandated ATSC 3.0 compatibility and accelerated turnaround schedules drive replacement cycles. Network affiliate groups across the United States prioritize hardware-software bundles with proven broadcast output certification.
- Content Creators:Independent producers and YouTube-native studios favor subscription pricing and mobile proxy workflows.
- Educational Institutions:University film programs balance curriculum standardization against student licensing costs.
Film Production commands premium pricing, though Content Creators are gaining share fastest through volume expansion.
Feature:
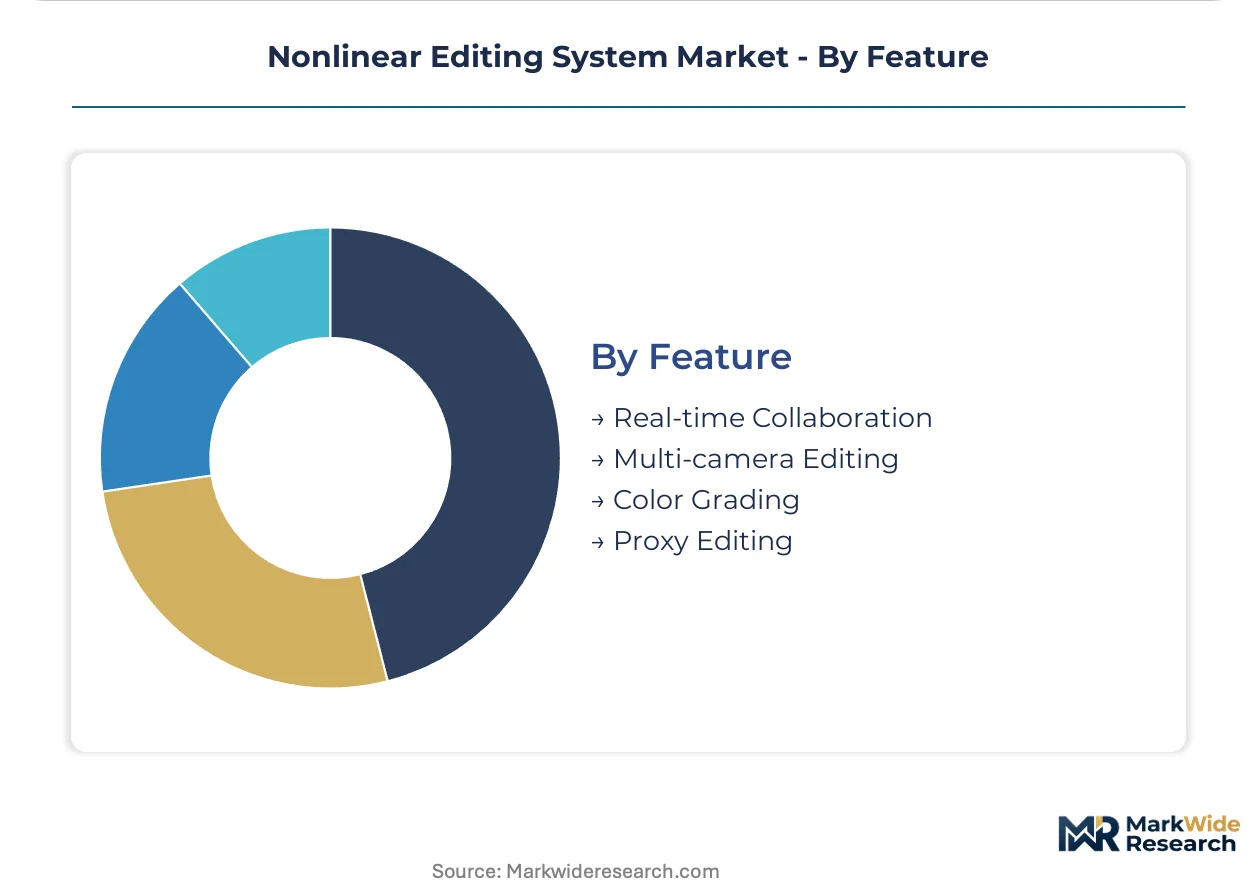
Workflow efficiency and creative capability differentiation concentrate demand in specific functional modules.
- Real-time Collaboration:Simultaneous multi-editor access with conflict resolution and version branching enables distributed post-production. Streaming platform original content pipelines in Austin and Vancouver require real-time collaboration for accelerated delivery schedules.
- Multi-camera Editing:Synchronized angle switching and metadata-driven clip organization accelerate unscripted and live-event turnaround. Reality television producers in Mumbai and London depend on multi-camera efficiency for volume delivery.
- Color Grading:HDR and wide-gamut pipeline tools with calibrated display support.
- Proxy Editing:Low-resolution placeholder workflows for remote bandwidth constraints.
Real-time Collaboration holds the largest addressable base, while Color Grading is climbing the fastest on HDR adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Post-production infrastructure varies sharply by geography. United States facilities cluster around streaming platform headquarters and theatrical release pipelines. European markets emphasize broadcast compliance and multilingual localization workflows. Asian production centers scale rapidly on volume-driven unscripted content and regional streaming investment.
United States
Streaming platform original content budgets and theatrical franchise post-production dominate demand. The FCC mandates ATSC 3.0 broadcast standards that force codec compatibility upgrades across station groups. Los Angeles and New York post houses concentrate premium color grading and HDR mastering for major studio releases.
United Kingdom
High-end television production and international co-production financing drive infrastructure investment. Ofcom broadcast regulations shape technical delivery specifications for terrestrial and satellite distribution. London post-production clusters in Soho and Fitzrovia handle prestige drama series and theatrical conform for European theatrical release.
Germany
Public broadcaster infrastructure modernization and commercial production house consolidation expand editing system procurement. ARD and ZDF technical standards influence codec and resolution roadmaps for vendor compliance. Munich and Cologne post facilities serve Central European dubbing and localization pipelines.
India
Regional streaming platform content investment and volume-driven unscripted production accelerate demand. TRAI broadcast regulations govern carriage and technical standards for satellite and terrestrial distribution. Mumbai post-production clusters handle multi-language versioning and rapid-turnaround reality television delivery.
South Korea
K-content export demand and streaming platform global expansion drive post-production capacity buildout. KCC broadcast technical standards mandate specific codec implementations for terrestrial and cable distribution. Seoul post houses in Sangam-digital media city concentrate K-drama finishing and international format adaptation.
Nonlinear Editing System Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. Premium theatrical and broadcast facilities demand specialized color science and media asset management integration. Mid-market commercial houses prioritize subscription pricing and cloud collaboration. The competitive terrain stratifies across integrated hardware-software bundles, pure-play SaaS platforms, and ecosystem-anchored creative suites. Dominant competitive moves include strategic partnerships between camera manufacturers and editing vendors, plus geographic expansion into secondary production cities lacking legacy infrastructure.
Within the integrated hardware-software tier, Blackmagic Design and Avid Technology occupy positions exemplifying divergent approaches to professional post-production. Adobe Systems Incorporated anchors the ecosystem-driven creative suite archetype through cloud-native subscription architecture. These three companies represent the structural fault lines between perpetual-license heritage, hardware-coupled performance, and SaaS-native recurring revenue models.
| Leading Market Players |
|---|
| MAGIX Software GmbH |
| Corel |
| Adobe Systems Incorporated |
| Blackmagic Design |
| CyberLink Corp |
| Avid Technology |
| Microsoft |
| TechSmith Corporation |
| Apple |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Taiwanese GPU foundries is compressing accelerator card pricing while simultaneously extending vendor payment terms, creating asymmetric cash flow pressure that favors cloud-native editing platforms over hardware-dependent post-production facilities.
Pricing Analysis
Long-term enterprise subscription contracts anchor pricing for broadcast and studio clients, while spot purchases through direct-to-consumer channels serve independent creators. Three-tier pricing structure across premium, standard, and economy levels separates theatrical finishing suites from mid-market commercial houses and freelance editors. Cost compression in SaaS tiers is intensifying because hyperscaler infrastructure investments reduce compute delivery costs. Independent filmmakers exhibit highest price sensitivity, whereas major studio post departments prioritize workflow integration over per-seat economics.
Supply Chain Analysis
Extended payment terms from NVIDIA and AMD to Taiwanese foundry partners ripple through hardware assembly channels, straining working capital for editing workstation assemblers. GPU accelerators draw from Taiwan and South Korea, storage arrays from China and Japan, and specialized control surfaces from Germany and the United States. Single-source vulnerability in NVIDIA's CUDA ecosystem exposes facilities to allocation rationing during semiconductor demand spikes. Distribution runs through authorized reseller networks for enterprise accounts and direct-to-consumer storefronts for individual creators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as Adobe's Creative Cloud ecosystem locks in broadcast clients through interoperability dependencies that rival standalone editing vendors cannot easily replicate.
For Market Incumbents: Build switching-cost moats through deep API integration with streaming platform content management systems. Incumbents should acquire specialized color science startups to close HDR expertise gaps before cloud-native competitors match theatrical finishing capabilities. Vertical integration into media asset management software protects margin position against pure-play SaaS encroachment.
For New Entrants and Emerging Players: Secondary US production cities lacking legacy infrastructure present the most penetrable white-space opportunity. Atlanta and Austin post-production clusters lack established vendor relationships and prioritize subscription pricing over capital expenditure. New entrants should lead with AI-assisted editorial tools for unscripted content producers, where automated transcription and scene detection create immediate workflow value.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native editing platforms with streaming platform integration partnerships. Long-term viability across the projection horizon favors vendors with hybrid deployment architectures that serve both security-sensitive theatrical clients and distributed commercial productions. Investors should monitor FCC ATSC 3.0 implementation timelines as inflection indicators for broadcast infrastructure replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Launch | SaaS deployment captures post-production demand in secondary cities lacking render farm infrastructure. |
| Camera Manufacturer Partnership | Codec optimization agreements with RED and ARRI secure RAW playback performance differentiation. |
| AI Editorial Tool Integration | Machine learning transcription accelerates unscripted turnaround for reality television producers. |
| Geographic Expansion | Local presence in Mumbai and Seoul captures regional streaming platform content investment. |
| Media Asset Management Acquisition | Pipeline integration capabilities defend enterprise accounts against standalone editing competitors. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and streaming platform production investment announcements. Post-production facility operators, broadcast engineering directors, and streaming platform content operations executives provided operational data on editing system procurement patterns. Bottom-up triangulation across facility-level equipment purchases and top-down validation against vendor revenue disclosures ensured consistency.
Forecast inputs span deployment model adoption curves, resolution upgrade cycles from HD through 8K, and regional streaming content investment trajectories. Segmentation dimensions modeled include product type, deployment architecture, end-user vertical, and feature module prioritization. CAGRs were derived from fitted growth curves against historical replacement cycle data and projected original content production budgets.
Practitioners should monitor GPU supply allocation volatility, FCC ATSC 3.0 compliance deadlines, and streaming platform budget reallocation for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Fresh Durian Market
Others
Inorganic Tin Chemicals Market
Others
Mobile Retina Services Market
Others
Running Apparel Market
Others
Consumer Video Feedback Software Market
Others
Allogeneic Human Chondrocyte Market
Others
Industrial Air Purifiers Market
Others
Egg and Egg Products Market
Others
Free Space Optics (FSO) Market
Others
Internet of Things Testing Market
Others
Binoculars Market
Others
Connected Wearable Patches Market
Others
Embedded Computer Market
Others
China Automotive LED Lighting Market
Others
Sprockets Market
Others
Global Compact Wheel Loaders Market