
 Pet Care Packaging Market | 2026-2036
Pet Care Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Care Packaging Market Outlook
Asset-light contract manufacturing and third-party packaging partnerships are fragmenting competitive control across the Pet Care Packaging landscape. ProAmpac LLC leverages flexible packaging specialization to serve mid-tier pet food brands without captive film extrusion. Sonoco Products Co sustains composite can leadership through veterinary and prescription diet channels. Amcor Plc anchors global multi-site supply with pre-qualified structures for retort pouches and barrier bags.
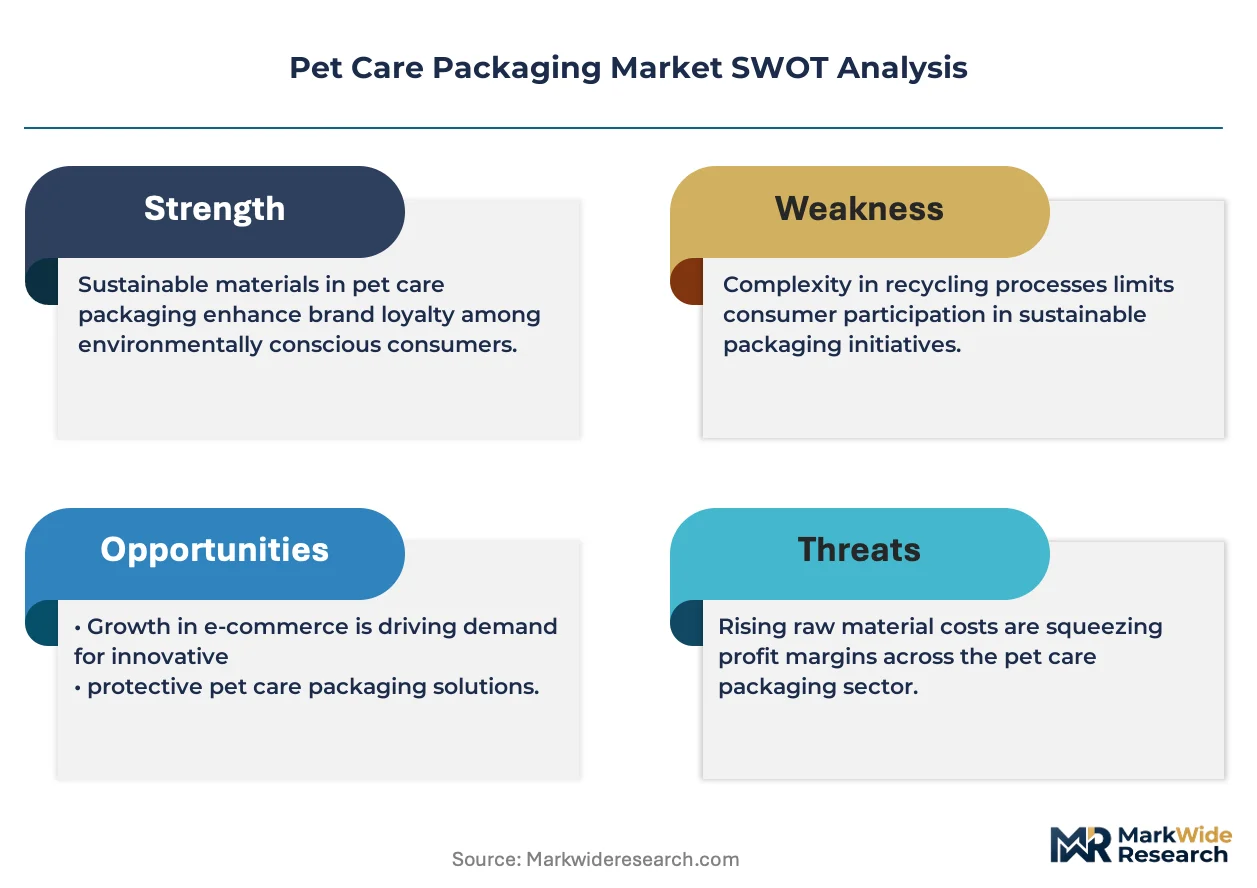
Pet care packaging encompasses primary and secondary containment systems engineered to protect nutritional integrity, extend shelf stability, and enable portion control for animal feed products. Multi-layer coextruded films with oxygen transmission rates below 1 cc/m²/day and ethylene vinyl alcohol (EVOH) barrier cores preserve lipid-sensitive formulations in wet food and treat applications. Plastic pouches represent the fastest-expanding format as brands shift from rigid cans to lightweight, shelf-ready flexible structures with fitment closures. Bags and tubs occupy mature volume positions in dry food bulk retail, while metal cans retain structural importance for therapeutic and prescription wet diets where thermal processing demands exceed flexible film limits.
The FDA Center for Veterinary Medicine governs pet food labeling and container safety, while EPA regulations on per- and polyfluoroalkyl substances (PFAS) are eliminating fluorinated grease barriers from paper-based pet treat packaging. State-level extended producer responsibility laws in California and Oregon are forcing format redesigns toward mono-material polyethylene structures compatible with mechanical recycling streams. Stakeholders must monitor how rapidly advancing chemical recycling infrastructure and evolving state mandates will redefine acceptable material portfolios before the next packaging specification cycle locks in multi-year supply commitments.
Market Dynamics
Material transitions under the EU Packaging and Packaging Waste Regulation are compressing specification cycles as brands race to lock in mono-material polyethylene structures before multi-year supply commitments crystallize.
Growth Catalysts
- EU PPWR mandates:The Packaging and Packaging Waste Regulation accelerates format redesign toward recyclable mono-materials, forcing investment in compatible barrier technologies.
- E-commerce subscription models:Direct-to-consumer pet food delivery concentrates demand for lightweight pouches with resealable fitments and shelf-ready presentation.
- Therapeutic diet expansion:Veterinary-dispensed prescription nutrition drives specialized high-barrier requirements that command premium positioning.
Market Restraints
- EVOH supply concentration:Ethylene vinyl alcohol barrier resin production clusters in Northeast Asia, exposing converters to freight volatility and currency fluctuation.
- Retort film thermal limits:Flexible structures cannot sustain the 121°C sterilization cycles required for certain therapeutic wet diets, preserving metal can dominance in this segment.
- California EPR compliance:Extended producer responsibility laws force redundant testing cycles for paper-based treat packaging seeking mechanical recycling qualification.
Strategic Opportunities
- Chemical recycling infrastructure:Advanced pyrolysis and purification facilities in the Netherlands and Germany enable food-grade recycled polyethylene for premium pet food pouches.
- Veterinary telehealth channels:Remote prescription authorization expands addressable market for therapeutic diet packaging beyond traditional clinic dispensing.
- Smart packaging integration:Near-field communication tags and freshness indicators converge with mono-material substrates to enable traceability without compromising recyclability.
Industry Challenges
- Barrier-coating formulation expertise:The shift from fluorinated grease barriers to mineral-based alternatives requires scarce polymer chemistry talent familiar with both food safety and fiber-based substrates.
- Legacy equipment retrofit costs:Converting lines engineered for multi-layer coextrusion demand substantial capital reconfiguration to process mono-material structures at equivalent throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Care Packaging Market |
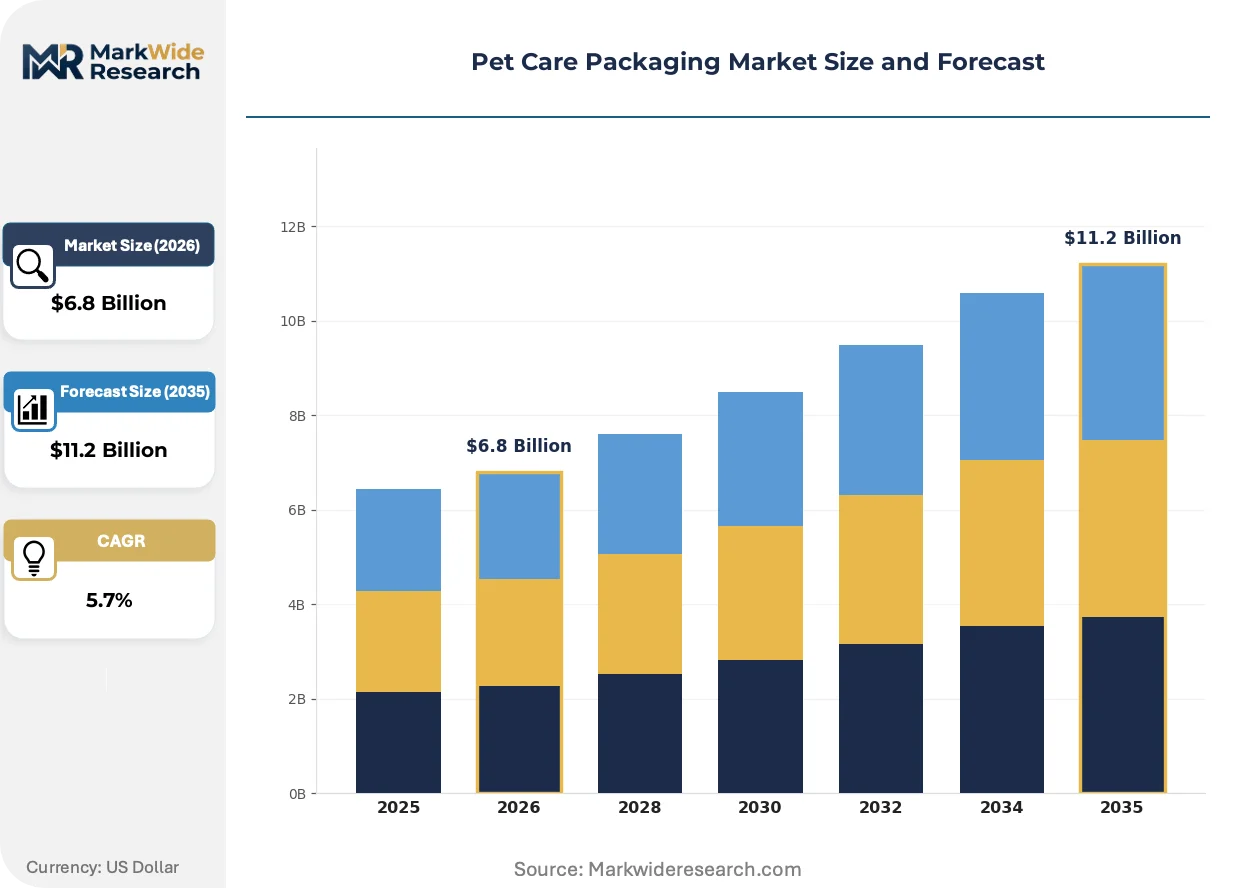
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paper, Metal, Glass Package Format: Bags, Cans, Pouches, Tubs End User: Retailers, E-commerce, Veterinary Clinics, Pet Owners Application: Dry Food, Wet Food, Treats, Supplements |
| Companies Covered | ProAmpac LLC, Sonoco Products Co, Amcor Plc, Constantia Flexibles Group GmbH, WestRock Company, Mondi Group Plc, Berry Global Inc., Ardagh Group S.A., Crown Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Care Packaging Market Strategic Shifts
Active packaging formats and digital integration are compressing the traditional specification cycle, with brands now treating container design as a continuous optimization surface rather than a static cost center.
Barrier technology is hybridizing as metallized polyethylene terephthalate layers bond with sealant-grade polyethylene to create mono-material-compatible structures that match EVOH oxygen transmission performance. Premium wet food brands in Germany and France are piloting these constructions for retort applications. The convergence is collapsing the historical trade-off between recyclability and shelf stability.
REACH restrictions on per- and polyfluoroalkyl substances eliminate fluorinated barriers from paperboard pet treat cartons across European markets. Manufacturers are accelerating mineral-oil-free migration barriers and clay-based grease resistance coatings. The transition compresses margin structures for mid-tier converters lacking in-house coating development capabilities.
Subscription fulfillment models reshape primary packaging specifications as direct-to-consumer brands prioritize cube efficiency and unboxing experience over retail shelf presence. E-commerce-native pet food companies in the United States specify flat-bottom pouches with ergonomic handles and tear-notch convenience features. The channel shift elevates packaging engineers to revenue-critical roles within brand organizations.
Pet Care Packaging Market Segmentation
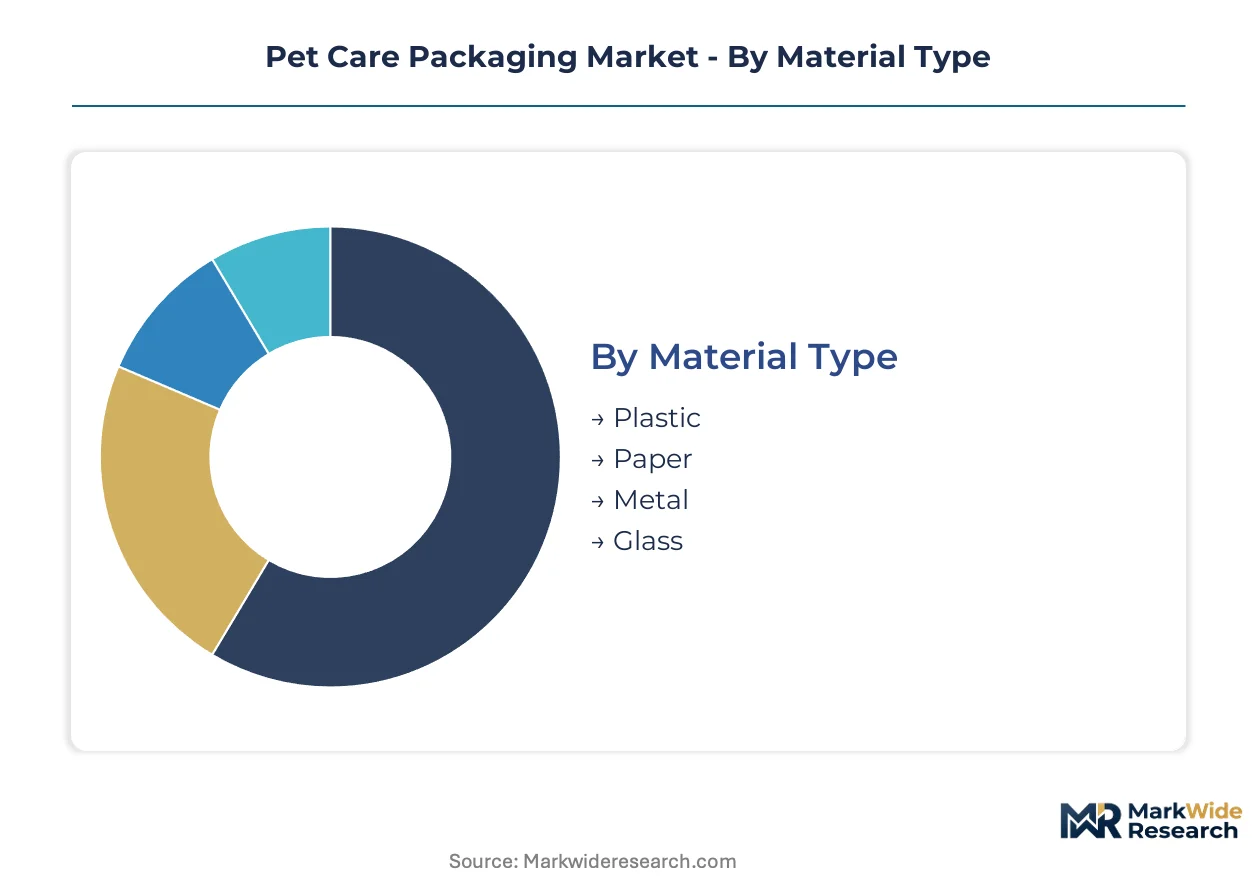
Packaging specifications diverge sharply across material classes and distribution channels in the pet care market. Each segment carries distinct barrier requirements, regulatory exposure, and format flexibility that shape converter capabilities and brand procurement strategies.
Material Type:
Performance demands span from oxygen-sensitive wet food preservation to lightweight e-commerce optimization, creating tiered material selection logic.
- Plastic:Multi-layer coextruded films with EVOH barrier cores dominate wet food and treat applications, with mono-material polyethylene structures gaining traction under EU PPWR mandates. Brand procurement teams in Germany and France are locking in recyclable pouch specifications ahead of compliance deadlines.
- Metal:Tinplate and aluminum cans retain structural necessity for retort-sterilized therapeutic diets where 121°C thermal processing exceeds flexible film limits. Veterinary prescription channels in the United States sustain this segment against format substitution.
- Paper:Clay-coated and mineral-oil-free barrier boards serve dry treat cartons, though EPA restrictions on PFAS grease resistance are forcing coating reformulations. California EPR laws add redundant qualification cycles for mechanical recycling compatibility.
- Glass:Premium positioning for artisanal pet supplements and specialty nutrition, constrained by weight penalties in direct-to-consumer shipping economics.
Established volume favors plastic; emerging adoption favors paper with advanced barrier coatings.
Package Format:
Channel economics and shelf-life requirements dictate format selection across retail, veterinary, and subscription fulfillment contexts.
- Pouches:Flat-bottom and stand-up flexible structures with fitment closures are climbing the fastest as e-commerce-native brands prioritize cube efficiency and unboxing experience. United States subscription services specify ergonomic handles and tear-notch convenience features.
- Bags:Multi-wall paper and plastic constructions retain mature positions in dry food bulk retail, with gusseted formats optimizing pallet density for mass-market distribution.
- Cans:Two-piece aluminum and three-piece tinplate designs preserve dominance in therapeutic wet diets requiring thermal sterilization beyond flexible film capabilities.
- Tubs:Injection-molded polypropylene containers serve semi-moist foods and portion-controlled treats, balancing resealability with retail shelf presence.
Legacy infrastructure favors bags; channel shift momentum favors pouches.
End User:
Procurement authority and specification complexity fragment across retail consolidation, platform economics, and clinical dispensing protocols.
- E-commerce:Direct-to-consumer fulfillment concentrates demand for lightweight, damage-resistant formats with premium unboxing aesthetics. United States subscription platforms are elevating packaging engineers to revenue-critical roles.
- Retailers:Mass-market and specialty pet chains drive standardization toward shelf-ready display cases and pallet-optimized secondary packaging.
- Veterinary Clinics:Prescription diet dispensing requires tamper-evident, high-barrier structures with extended shelf stability for therapeutic formulations.
- Pet Owners:Bulk purchasing and storage convenience influence large-format bag specifications for dry food in warehouse club channels.
Volume concentration favors retailers; margin expansion favors e-commerce.
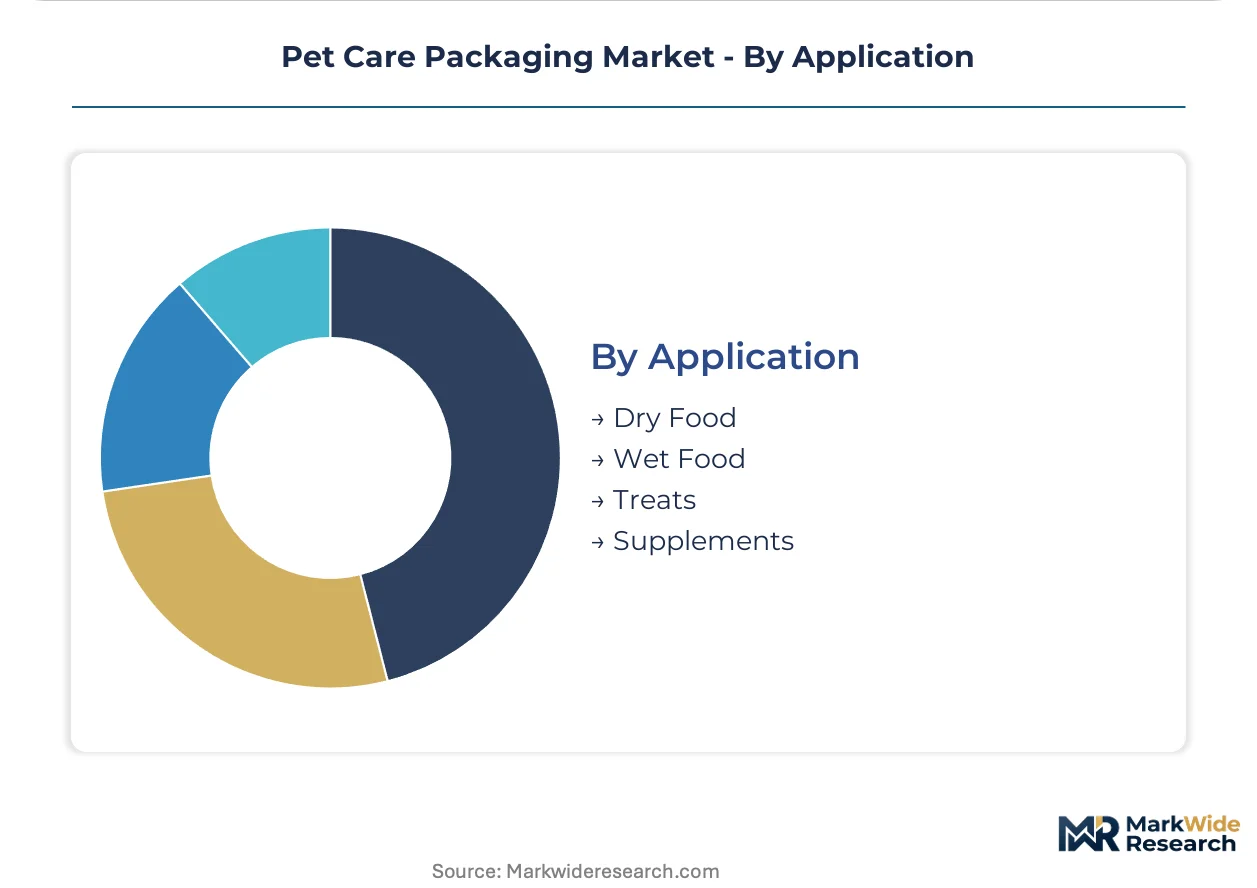
Application:
Nutritional format determines barrier intensity, thermal processing requirements, and portion control features.
- Wet Food:Retort pouches and cans require oxygen transmission rates below 1 cc/m²/day to preserve lipid-sensitive formulations through thermal processing and extended shelf life.
- Dry Food:Multi-wall bags with moisture barriers dominate bulk retail, with format innovation focusing on resealability and dispensing convenience.
- Treats:Paperboard cartons and flexible pouches balance grease resistance with sustainability positioning, pressured by PFAS elimination mandates.
- Supplements:Blister packs, bottles, and single-serve sachets serve functional nutrition with child-resistant and senior-friendly closure requirements.
Unit volume favors dry food; value concentration favors wet food.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Packaging and Packaging Waste Regulation mandates are compressing specification cycles across major pet food markets as brands race to qualify mono-material structures before multi-year supply commitments lock in. The United States sustains volume leadership through e-commerce subscription expansion and veterinary therapeutic diet channels. Germany, France, and the Netherlands anchor European format innovation, while China and Japan concentrate barrier film production and specialized converter capacity.
United States
E-commerce pet food subscriptions from Chewy and Amazon-owned brands concentrate demand for lightweight pouches with resealable fitments and premium unboxing aesthetics. FDA Center for Veterinary Medicine labeling requirements govern container safety for therapeutic diets dispensed through veterinary telehealth channels. Chicago and Minneapolis-St. Paul host major flexible packaging converter clusters serving mid-tier pet food brands without captive film extrusion.
Germany
Premium wet food brands pilot metallized PET-bonded polyethylene structures that match EVOH oxygen transmission performance for retort applications. REACH restrictions on PFAS eliminate fluorinated grease barriers from paperboard treat cartons, forcing mineral-oil-free migration barrier adoption. The Stuttgart and Munich industrial corridors concentrate barrier coating development capabilities for converters serving EU-wide pet food manufacturers.
France
Artisanal pet nutrition brands drive glass and premium flexible format demand for specialty supplements with extended shelf stability requirements. ANSM and DGCCRF enforcement of food contact material regulations tightens qualification cycles for imported packaging components. The Lyon and Paris packaging clusters specialize in high-barrier pouch conversion for export-oriented pet food processors.
Netherlands
Advanced pyrolysis and purification facilities in Rotterdam and Groningen enable food-grade recycled polyethylene for premium pet food pouches targeting circular economy commitments. The Dutch national packaging covenant accelerates mono-material adoption timelines ahead of EU PPWR baseline requirements. Eindhoven's materials science ecosystem supports coating formulation expertise for mineral-based grease resistance alternatives.
China
Ethylene vinyl alcohol barrier resin production concentrates in Northeast Asia, exposing global converters to freight volatility and currency fluctuation. GB standards for food contact materials govern export-oriented packaging production from Shenzhen and Shanghai converter bases. The Yangtze River Delta hosts integrated film extrusion and metallization capacity serving both domestic pet food growth and European brand supply chains.
Pet Care Packaging Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement authority in pet care packaging. The market structure tiers between global multi-site suppliers with pre-qualified retort structures, regional flexible packaging specialists, and asset-light contract manufacturers. Three archetypes dominate: integrated film-to-package converters, composite can specialists, and subscription-optimized pouch engineers. Competitive moves concentrate on M&A for barrier coating capabilities and strategic partnerships for chemical recycling feedstock access.
Among North American flexible packaging specialists, ProAmpac LLC exemplifies the asset-light contract manufacturing archetype serving mid-tier brands without captive extrusion. Sonoco Products Co occupies the composite can leadership position through veterinary and prescription diet channels. Amcor Plc anchors the global multi-site supply tier with pre-qualified structures for retort pouches and barrier bags. These three companies represent distinct strategic postures rather than direct peer competition, as procurement fragmentation allows specialized positioning across subscription, retail, and clinical dispensing channels.
| Leading Market Players |
|---|
| ProAmpac LLC |
| Sonoco Products Co |
| Amcor Plc |
| Constantia Flexibles Group GmbH |
| WestRock Company |
| Mondi Group Plc |
| Berry Global Inc. |
| Ardagh Group S.A. |
| Crown Holdings Inc. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in European barrier coating development is compressing converter margins while amplifying pricing power for specialists serving EU PPWR-compliant mono-material specifications. Utilization rates above 85 percent in Stuttgart and Munich industrial corridors allow qualified suppliers to command premiums for mineral-oil-free migration barriers, forcing mid-tier converters toward asset-light contract manufacturing partnerships to avoid capital-intensive equipment retrofits.
Pricing Analysis
Certification level (FDA-grade vs. EU food contact compliance) creates the primary spread between premium and standard tiers in pet care packaging. Three-tier pricing structure across premium, standard, and economy levels reflects barrier performance, with retort-capable EVOH-core films commanding the highest position. Cost compression in standard-tier multi-layer coextrusion is intensifying because Northeast Asian resin supply exposes converters to freight volatility and currency fluctuation. Mass-market retail buyers exhibit highest price sensitivity, while veterinary prescription channels absorb premium positioning for tamper-evident therapeutic diet packaging.
Supply Chain Analysis
ProAmpac LLC, Constantia Flexibles Group GmbH, and Mondi Group Plc hold dominant contract-manufacturing capacity for flexible pet food packaging across North America and Europe. Geographic supply concentrates in Germany, the United States, and China, with the Yangtze River Delta anchoring integrated film extrusion and metallization capacity. Raw material dependencies rest on ethylene vinyl alcohol barrier resin, metallized polyethylene terephthalate substrates, and sealant-grade polyethylene. Single-source vulnerability in Northeast Asian EVOH production exposes converters to supply disruption. Distribution runs through direct-to-consumer subscription platforms, veterinary clinic networks, and mass-market retail chains with diverging specification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across procurement authority creates niche opportunities as e-commerce subscription models displace traditional retail concentration. Channel-specific packaging engineers now command revenue-critical roles, enabling specialist converters to capture margin from brands lacking in-house specification expertise.
For Market Incumbents: Entrench composite can leadership in veterinary prescription channels where thermal sterilization requirements preserve metal format dominance against flexible substitution. Invest in barrier coating development capabilities to capture EU PPWR-driven specification cycles before mid-tier competitors qualify mineral-oil-free alternatives. Prioritize backward integration into metallized film production to secure supply of mono-material-compatible substrates. For New Entrants and Emerging Players: Chemical recycling feedstock partnerships in the Netherlands and Germany represent the most penetrable entry point for premium pouch converters seeking circular economy positioning. Mid-tier pet food brands without captive film extrusion offer receptive customer bases for asset-light contract manufacturing models. Lead with sustainability certification and rapid specification turnaround as the primary go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription-optimized pouch engineers serving direct-to-consumer pet food platforms with multi-year supply agreements. Long-term viability favors converters with demonstrated EU regulatory compliance and established chemical recycling feedstock relationships. Monitor state-level extended producer responsibility law expansion in California and Oregon as the inflection indicator for format redesign demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating Capability Acquisition | Mineral-oil-free migration expertise addresses REACH PFAS restrictions and EU PPWR compliance deadlines. |
| Chemical Recycling Feedstock Partnership | Rotterdam and Groningen pyrolysis facilities enable food-grade recycled polyethylene for premium pouch positioning. |
| Veterinary Telehealth Channel Expansion | Remote prescription authorization extends addressable market for high-barrier therapeutic diet packaging. |
| Mono-Material Equipment Retrofit | Legacy coextrusion line reconfiguration captures EU specification cycles before multi-year supply commitments crystallize. |
| Smart Packaging Integration | Near-field communication tags on mono-material substrates enable traceability without recyclability compromise. |
Study Parameters
Operator-level perspectives from packaging procurement managers at pet food brands, converter plant engineers, veterinary clinic dispensing coordinators, and e-commerce fulfillment specialists anchored the qualitative base. Primary interviews combined with secondary validation from FDA Center for Veterinary Medicine guidance documents, EPA PFAS restriction filings, EU PPWR regulatory texts, and trade data from flexible packaging industry associations. Bottom-up segment sizing and top-down macroeconomic triangulation cross-validated volume and value estimates.
Scenario-bracketing framed the analytical approach across the analysis window, with segmentation dimensions spanning material type, package format, end user channel, and application. CAGRs derived from regression analysis against pet food industry production indices, e-commerce penetration curves, and regulatory compliance timeline assumptions. Modeled inputs included EVOH resin price volatility indices and chemical recycling capacity buildout schedules in the Netherlands and Germany.
Practitioners should monitor EU PPWR implementation velocity, California EPR law expansion, and Northeast Asian EVOH supply disruptions for early signals requiring forecast revision. Quarterly review of state-level regulatory filings, converter capacity utilization reports, and pet food brand sustainability commitments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Middle East and Africa Surface Analysis Market
Others
Healthcare Bioconvergence Market
Others
5G Edge Computing Market
Others
France Location-Based Services Market
Others
US Cat Food Market
Others
Induced Pluripotent Stem Cells (Ipscs) Market
Others
Global Pumpkin Candles Market
Others
Double Card Mobile Phone Market
Others
Czech Republic Market
Others
Magnetic Stripe Readers Market
Others
US Camping and Caravanning Market
Others
Latin America Travel Retail Market
Others
North America Video Conferencing Hardware Market
Others
Edible Insects for Animal Feed Market
Others
South America Halal Food and Beverages Market
Others
Channel-In-A-Box (Ciab) Market