
 Storage Dewars Market | 2026-2036
Storage Dewars Market Size, Share, and Industry Trends Forecast 2026-2036
Storage Dewars Market Analytics
Aftermarket service revenue is rewriting profit allocation across the Storage Dewars landscape. Thermo Fisher Scientific Inc. leverages its installed base to capture recurring calibration and maintenance contracts. Chart Industries anchors its position through geographic dominance in North American cryogenic infrastructure. IC Biomedical specializes in custom fabrication for biorepository clients with stringent temperature uniformity requirements.
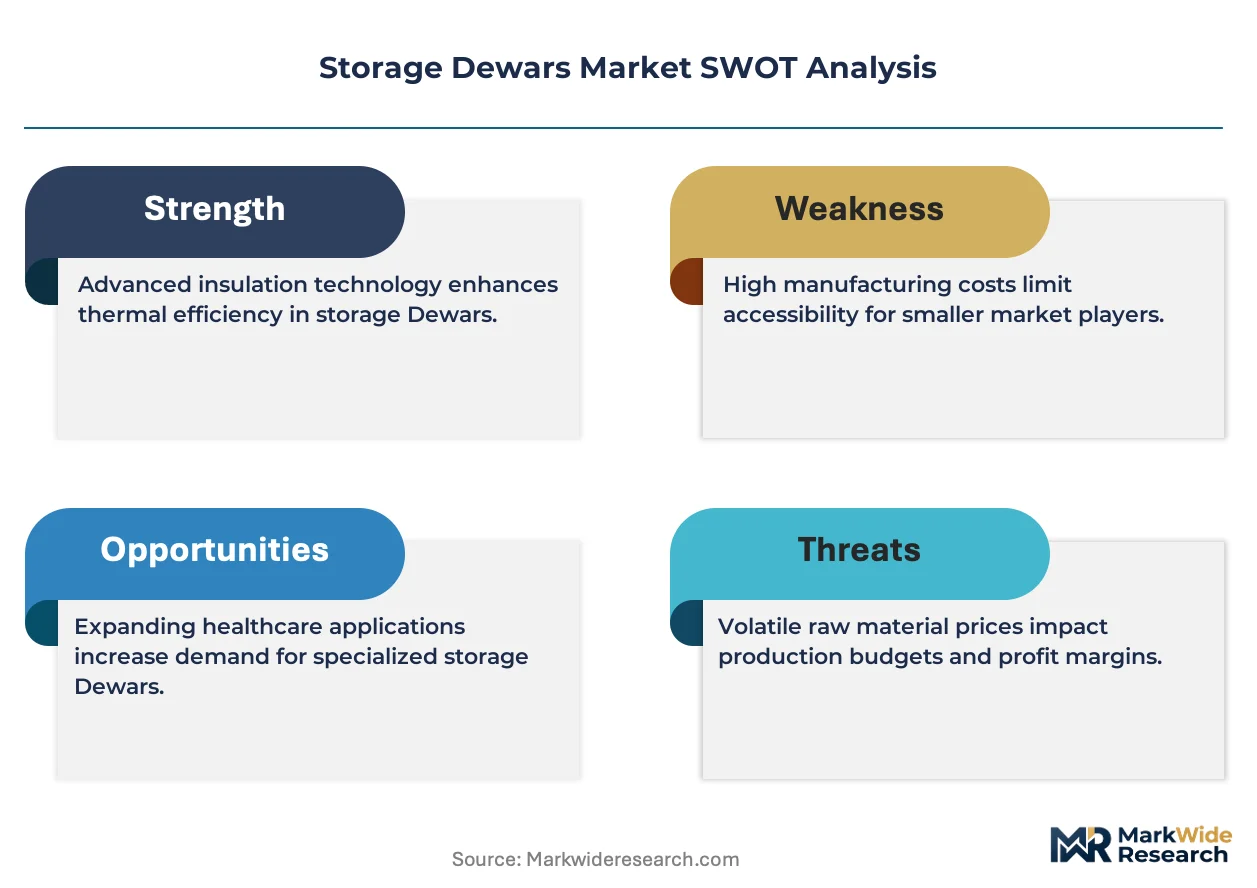
Storage dewars are double-walled vacuum-insulated vessels designed to contain cryogenic fluids at temperatures below minus 150 degrees Celsius, utilizing multilayer insulation and adsorbent materials to minimize radiative and conductive heat transfer for extended hold times. Their primary purpose centers on preserving biological specimens, superconducting magnets, and industrial gases where thermal stability determines operational integrity. Liquid nitrogen dewars occupy the largest volume share due to ubiquitous deployment across pathology and assisted reproduction workflows, while vacuum insulated dewars command premium positioning in semiconductor fabrication where helium conservation drives specification intensity. Stainless steel constructions dominate healthcare procurement for durability and cleanability, though composite materials represent the fastest-growing material category as weight reduction becomes critical for satellite and aerospace cryogenic systems.
The FDA enforces quality system regulation under 21 CFR Part 820 for medical device manufacturing, compelling dewar producers to maintain design controls and process validation documentation that extends time-to-market for new product introductions. OSHA's cryogen safety standards mandate venting and pressure relief configurations that directly influence vessel engineering specifications and customer compliance costs. The Department of Transportation's 49 CFR hazardous materials regulations govern interstate shipment of filled dewars, creating a certification barrier that favors incumbents with established testing protocols and DOT-special permit holdings. Stakeholders must monitor evolving EPA refrigerant management rules and state-level decarbonization mandates that could redirect industrial gas distribution patterns and associated dewar deployment strategies.
Market Dynamics
Aftermarket service revenue streams are restructuring competitive economics across the storage dewars landscape as installed-base monetization supersedes new equipment sales. Thermo Fisher Scientific leverages recurring calibration contracts to capture lifetime value from biorepository clients. Chart Industries defends its North American position through cryogenic infrastructure integration. IC Biomedical targets custom fabrication for temperature-critical specimen preservation workflows.
Growth Catalysts
- NIH-Funded Research Expansion:United States federal laboratory procurement sustains baseline demand for liquid nitrogen dewars across pathology and genomics applications.
- 21 CFR Part 11 Validation:FDA electronic records requirements for biobanking operations compel healthcare facilities to upgrade dewar monitoring and documentation systems.
- Helium Conservation in Semiconductors:Vacuum insulated dewar specifications intensify as fabrication facilities prioritize cryogenic fluid retention for superconducting magnet cooling.
Market Restraints
- Stainless Steel Input Volatility:Raw material cost fluctuations for 304 and 316-grade alloys compress margin predictability for vessel manufacturers serving healthcare procurement.
- DOT Special Permit Concentration:49 CFR hazardous materials certification barriers favor incumbent holders with established interstate shipment testing protocols.
- Composite Material Substitution Limits:Aerospace weight reduction requirements outpace current multilayer insulation adhesion reliability at cryogenic temperatures below minus 196 degrees Celsius.
Strategic Opportunities
- Satellite Cryogenic Systems:Composite dewar fabrication for orbital deployment addresses payload weight constraints in emerging space-based research platforms.
- State Decarbonization Mandates:California and New York industrial gas distribution redirection creates demand for mobile dewar fleets with enhanced thermal efficiency ratings.
- IoT Sensor Convergence:Real-time temperature telemetry integration with cloud-based specimen tracking systems enables predictive maintenance service models.
Industry Challenges
- Cryogenic Welding Certification Scarcity:Qualified vessel fabrication technicians for vacuum-sealed double-wall construction command premium compensation and extended recruitment timelines.
- 21 CFR Part 820 Documentation Burden:FDA quality system regulation design controls extend new product introduction cycles through validation protocol requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Storage Dewars Market |
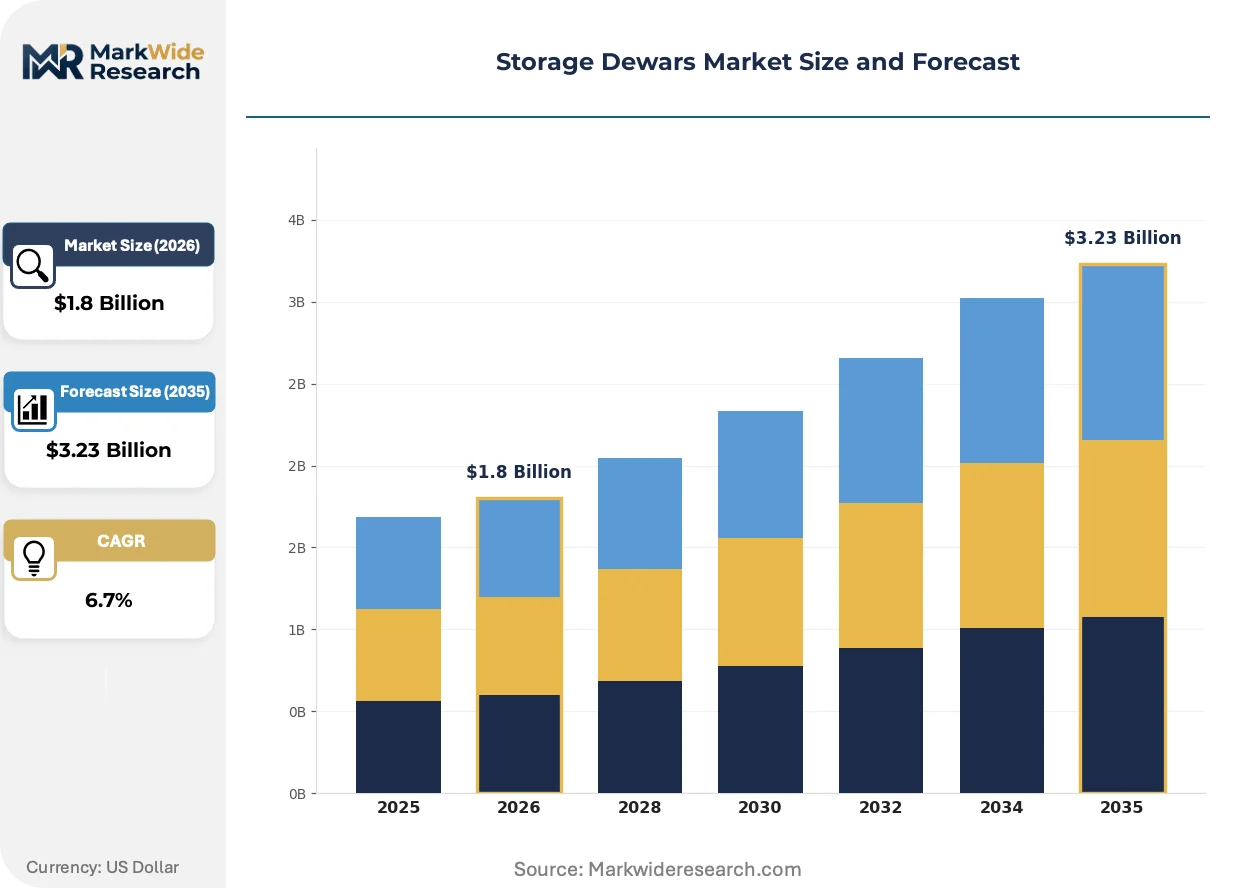
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Nitrogen Dewars, Liquid Helium Dewars, Vacuum Insulated Dewars, Cryogenic Dewars End User: Healthcare Facilities, Research Laboratories, Industrial Applications, Educational Institutions Material: Stainless Steel, Aluminium, Glass, Composite Materials Capacity: 5 Liters, 10 Liters, 20 Liters, 50 Liters |
| Companies Covered | Thermo Fisher Scientific Inc., Chart Industries, IC Biomedical, Cryofab, Statebourne Cryogenics Ltd, BioLife Solutions Inc., Worthington Industries, Cryotherm GmbH & Co. KG, Air Products and Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Storage Dewars Market Evolving Landscape
Digital instrumentation is penetrating cryogenic storage infrastructure at accelerating velocity. Remote monitoring platforms are displacing manual temperature logging. Predictive analytics are compressing maintenance intervals. These converging developments are restructuring how biorepositories and industrial gas operators manage thermal integrity.
Smart dewar systems with embedded IoT sensors and cellular connectivity are virtualizing traditional specimen custody chains. Biobanking facilities at Mayo Clinic and Memorial Sloan Kettering deploy these units to eliminate manual liquid nitrogen level checks. The technology is virtualizing compliance documentation for FDA 21 CFR Part 11 audits while reducing labor allocation to routine monitoring tasks.
EPA refrigerant management rules are tightening enforcement protocols for industrial gas venting and recovery. Dewar manufacturers must now engineer pressure relief configurations that capture boil-off rather than atmospheric release. Semiconductor fabrication clusters in Arizona and Oregon face the steepest compliance cost adjustments as state air quality boards align with federal enforcement timelines.
Biorepository procurement teams are unbundling after-sales service from equipment acquisition. Large academic medical centers now source calibration and preventive maintenance through standalone contracts rather than OEM-integrated packages. This behavior is most pronounced among NIH-funded institutions where grant compliance requirements demand vendor-agnostic documentation standards.
Storage Dewars Market Segmentation
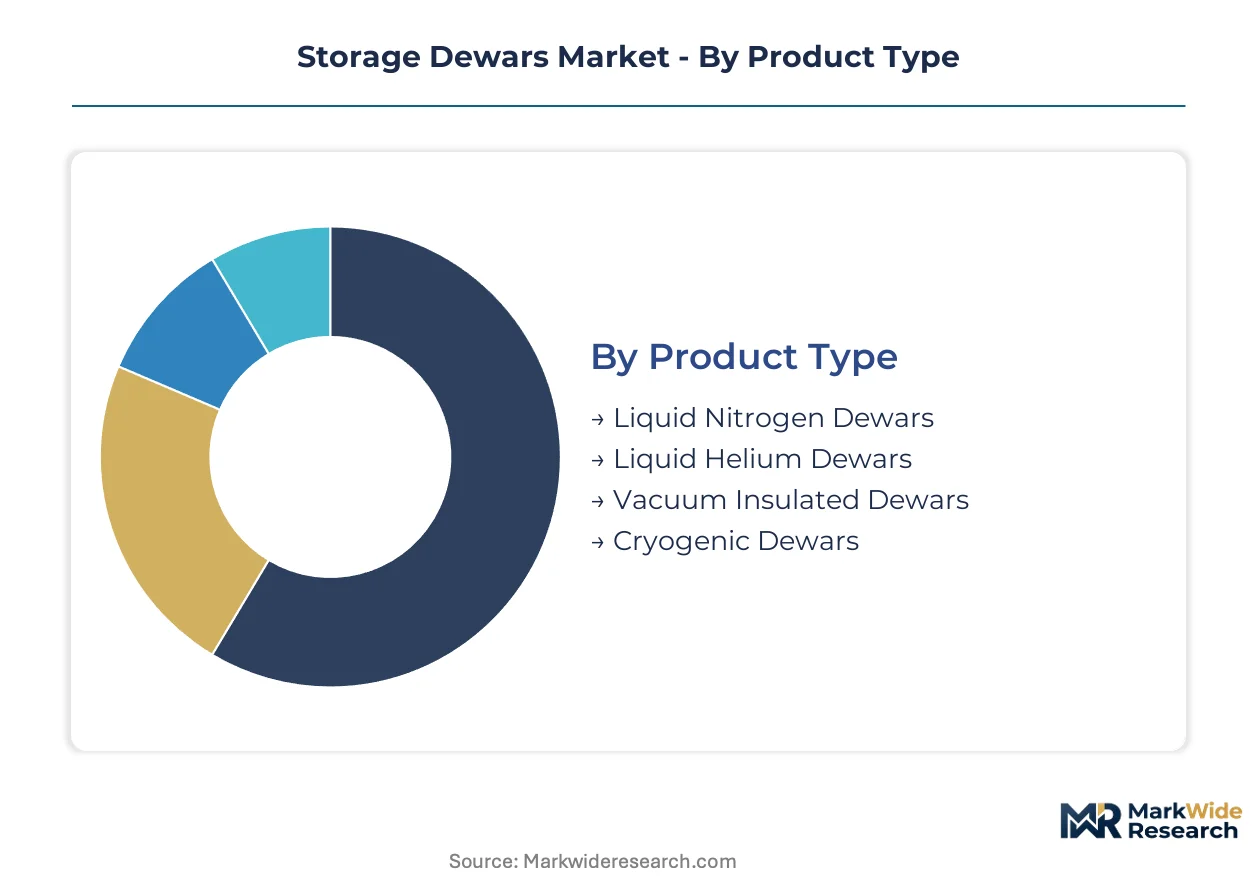
Storage dewar segmentation reveals distinct specification requirements across temperature ranges, vessel geometries, and regulatory compliance tiers. Procurement patterns diverge sharply between healthcare biorepositories prioritizing 21 CFR Part 11 validation and semiconductor fabs demanding helium conservation engineering.
Product Type:
Mature liquid nitrogen systems anchor procurement volumes while emerging vacuum-insulated architectures reshape premium specifications.
- Liquid Nitrogen Dewars:Double-walled vacuum vessels with multilayer insulation achieve hold times exceeding 60 days at minus 196 degrees Celsius. NIH-funded pathology laboratories across the United States sustain procurement volumes for specimen preservation workflows.
- Vacuum Insulated Dewars:Superinsulation systems with activated carbon getters minimize radiative heat transfer for helium and hydrogen containment. Arizona and Oregon semiconductor fabrication clusters drive specification intensity for superconducting magnet cooling applications.
- Liquid Helium Dewars:Specialized vessels with liquid nitrogen shielding reduce helium boil-off rates for MRI magnet servicing.
- Cryogenic Dewars:General-purpose containers spanning liquefied gas categories for industrial gas distribution networks.
Liquid nitrogen dewars handle the majority of throughput; vacuum insulated dewars are climbing the fastest on specification intensity.
End User:
Customer archetypes span grant-funded research infrastructure, regulated healthcare delivery, and process-intensive manufacturing with diverging compliance burdens.
- Healthcare Facilities:Hospital biorepositories and assisted reproduction clinics require FDA 21 CFR Part 820 quality system documentation for specimen custody chains. Mayo Clinic and Memorial Sloan Kettering deployments emphasize IoT-enabled temperature telemetry for audit readiness.
- Research Laboratories:Academic and government labs face NIH grant compliance mandating vendor-agnostic calibration documentation. United States federal procurement sustains baseline demand for liquid nitrogen systems across genomics and cryo-electron microscopy applications.
- Industrial Applications:Semiconductor fabrication and industrial gas distribution prioritize DOT 49 CFR special permit certification for interstate shipment.
- Educational Institutions:University physics and chemistry departments source entry-level vessels for instructional cryogen handling.
Healthcare facilities command premium pricing for validated systems; research laboratories represent the steepest expansion trajectory as NIH funding priorities shift toward cryo-EM infrastructure.
Material:
Material selection trades structural durability against weight constraints with composite architectures disrupting traditional metal vessel economics.
- Stainless Steel:304 and 316-grade austenitic alloys dominate healthcare procurement for corrosion resistance and cleanability under FDA quality system regulations. Raw material cost volatility compresses margin predictability for vessel fabricators serving hospital procurement cycles.
- Composite Materials:Carbon fiber reinforced polymers with multilayer insulation adhesion enable 40% weight reduction for aerospace and satellite deployment. Orbital cryogenic systems for space-based research platforms drive fastest-growing demand as payload constraints intensify.
- Aluminium:Lightweight alloy vessels serve portable field applications and educational settings with reduced thermal mass.
- Glass:Borosilicate and quartz dewars retain niche demand for optical access and laboratory demonstration purposes.
Stainless steel commands the installed base; composite materials are gaining share fastest as satellite cryogenic payload requirements multiply.
Capacity:
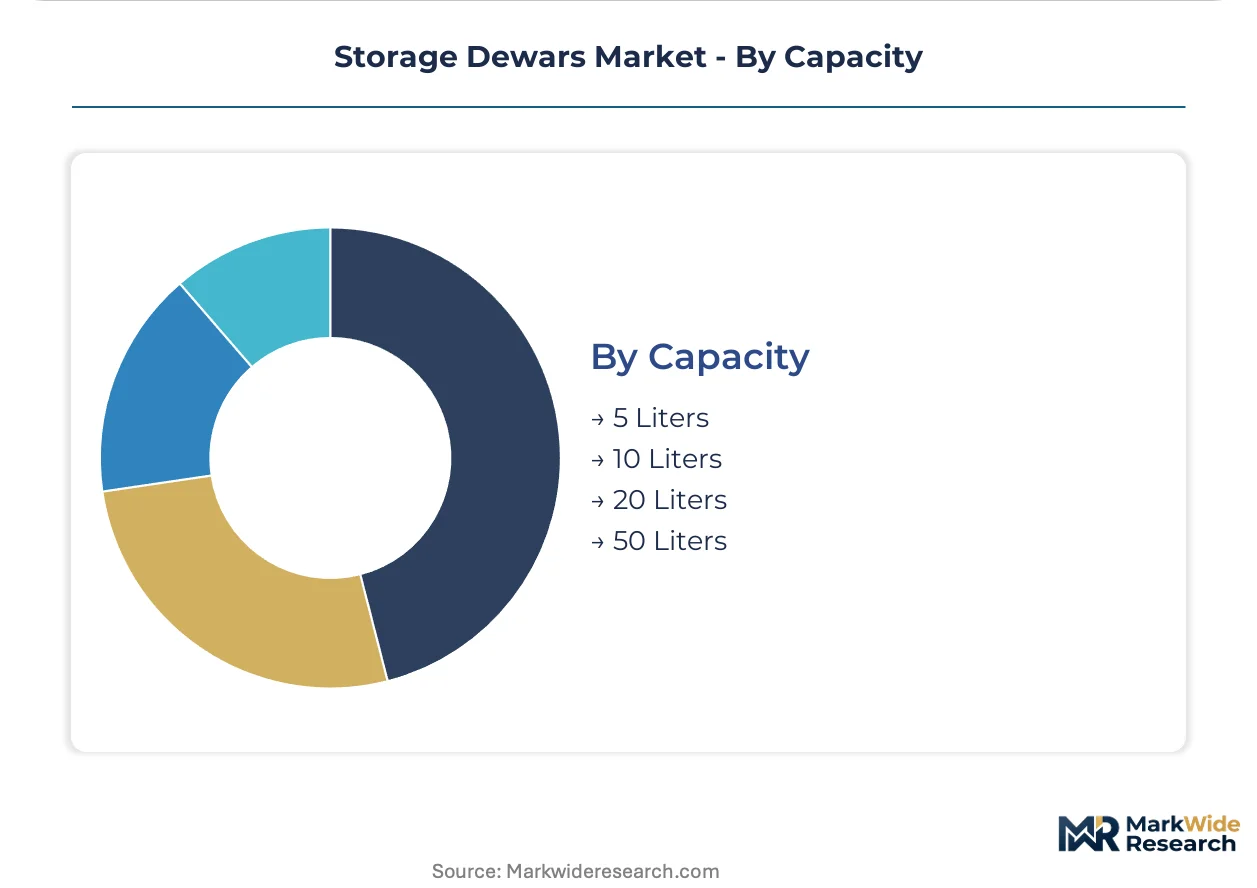
Vessel sizing aligns with specimen throughput volumes and liquid nitrogen replenishment logistics across facility scales.
- 50 Liters:High-capacity vessels with extended hold times serve centralized biorepositories with automated liquid nitrogen level monitoring. Large academic medical centers deploy these units to minimize replenishment labor and optimize bulk procurement economics.
- 20 Liters:Mid-scale containers balance portability against specimen density for distributed pathology workflows and regional research consortia.
- 10 Liters:Compact vessels suit assisted reproduction clinics and mobile cryogenic sampling operations with moderate throughput requirements.
- 5 Liters:Benchtop units address educational demonstrations and low-volume specimen archiving with minimal footprint.
Fifty-liter vessels handle the majority of institutional throughput; ten-liter configurations are expanding most quickly among distributed clinic networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare procurement teams in the United States absorb premium pricing for FDA-validated systems, while industrial buyers in China and Southeast Asia prioritize cost efficiency in bulk liquid nitrogen containment.
United States
NIH-funded research laboratories sustain baseline demand for cryogenic specimen preservation across genomics and cryo-electron microscopy workflows. FDA 21 CFR Part 11 validation requirements compel healthcare facilities to upgrade dewar monitoring systems for electronic records compliance. The Mayo Clinic and Memorial Sloan Kettering biorepository clusters in Minnesota and New York deploy IoT-enabled temperature telemetry for audit readiness.
Germany
Industrial gas distribution networks anchor procurement volumes for vacuum-insulated dewars serving chemical and pharmaceutical manufacturing. ECHA REACH compliance and CE marking requirements shape vessel specification standards for cross-border European shipment. The BASF-Ludwigshafen chemical complex and Bavarian semiconductor fabrication clusters drive demand for helium conservation engineering.
China
NMPA-regulated biobanking infrastructure expansion accelerates stainless steel dewar deployment across provincial hospital networks. MIIT industrial standards and GB certification protocols govern vacuum vessel manufacturing for domestic and export markets. The Yangtze River Delta biotech corridor and Beijing-Tianjin-Hebei research hub concentrate cryogenic equipment procurement.
Japan
PMDA quality system regulations enforce rigorous documentation standards for medical device-grade dewar manufacturing. METI technology roadmaps prioritize superconducting magnet cooling applications in particle physics and semiconductor research. The Kansai Osaka-Kyoto manufacturing belt and Tsukuba science city cluster sustain precision cryogenic equipment demand.
United Kingdom
Academic research consortia drive mid-scale liquid nitrogen dewar procurement for distributed cryo-electron microscopy facilities. MHRA medical device regulations align with EU MDR transitional requirements for biobanking equipment validation. The Cambridge-London-Oxford golden triangle and Manchester biotech cluster concentrate specimen preservation infrastructure investment.
Storage Dewars Market Competitive Landscape
Capability concentration sits with custom fabrication specialists; scale advantage sits with diversified industrial gas equipment manufacturers. The vendor base separates into three tiers: integrated life science conglomerates with installed-base service monetization, cryogenic infrastructure specialists with DOT certification holdings, and regional fabricators serving price-sensitive bulk procurement. Dominant competitive moves include geographic expansion into NIH-funded research corridors and backward integration into multilayer insulation material supply.
Within the integrated life science tier, Thermo Fisher Scientific Inc. and Chart Industries exemplify divergent scale strategies. Thermo Fisher leverages recurring calibration contracts to capture lifetime value from biorepository clients. Chart Industries anchors North American cryogenic infrastructure positioning through established DOT special permit holdings and interstate distribution networks. IC Biomedical occupies a specialist position representing custom fabrication capabilities for temperature-critical specimen preservation workflows.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Chart Industries |
| IC Biomedical |
| Cryofab |
| Statebourne Cryogenics Ltd |
| BioLife Solutions Inc. |
| Worthington Industries |
| Cryotherm GmbH & Co. KG |
| Air Products and Chemicals |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta manufacturing cluster anchors vacuum vessel fabrication capacity, concentrating multilayer insulation supply and cryogenic welding expertise. This geographic density grants incumbent fabricators pricing leverage over hospital procurement cycles and biorepository equipment tenders.
Pricing Analysis
Aftermarket calibration and preventive maintenance contracts drive lifetime value capture threefold beyond initial equipment margins. Pricing stratifies across FDA-validated premium tiers, DOT-certified standard tiers, and uncertified economy tiers for educational markets. Stainless steel input volatility compresses margin predictability for vessel manufacturers serving healthcare procurement. Research laboratories exhibit highest price sensitivity due to grant-funded budget constraints; semiconductor fabs demonstrate lowest sensitivity given helium conservation engineering premiums.
Supply Chain Analysis
Stainless steel feedstock draws from Chinese, German, and Japanese mill complexes with specialized 304 and 316-grade cryogenic certifications. Multilayer insulation materials, activated carbon getters, and vacuum-sealed valve assemblies constitute critical component dependencies. Single-source vulnerability concentrates in DOT-special permit testing protocols held by established North American incumbents. Distribution runs through authorized service networks for validated healthcare systems and direct industrial gas equipment channels for bulk procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue layers expand faster than hardware sales as biorepositories unbundle calibration contracts from OEM-integrated packages. Recurring aftermarket monetization now exceeds new equipment margins in lifetime value calculations.
For Market Incumbents: Harden installed-base lock-in through proprietary IoT telemetry platforms that virtualize compliance documentation for FDA audits. Deepen backward integration into multilayer insulation material supply to offset stainless steel cost volatility. Chart Industries and Thermo Fisher Scientific exemplify divergent scale strategies worth emulating.
For New Entrants and Emerging Players: Pursue satellite cryogenic payload fabrication where composite material weight reduction commands premium positioning. The aerospace research platform segment remains penetrable due to stringent payload constraints outpacing incumbent composite adhesion capabilities. Lead with custom fabrication capabilities for temperature-critical specimen preservation workflows.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors custom fabrication specialists with DOT certification holdings and established NIH-funded research corridor relationships. Acquisition targets should demonstrate captive multilayer insulation supply or proprietary vacuum-sealed welding protocols. Watch for EPA refrigerant management rule enforcement timelines as inflection indicators for boil-off recovery engineering demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Multilayer Insulation | Captive supply of activated carbon getters reduces input cost volatility for vacuum vessel fabricators. |
| IoT Sensor Platform Development | Embedded telemetry enables predictive maintenance contracts at Mayo Clinic and Memorial Sloan Kettering deployments. |
| DOT Special Permit Acquisition | Interstate shipment certification barriers favor holders with established 49 CFR testing protocols. |
| Composite Material R&D Partnership | Carbon fiber adhesion reliability below minus 196 degrees Celsius unlocks satellite payload opportunities. |
| Calibration Service Unbundling | Standalone aftermarket contracts capture NIH-funded laboratory procurement shifting away from OEM bundles. |
Research Methodology
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings. Biorepository managers, cryogenic welding technicians, DOT certification specialists, and hospital procurement officers provided operational perspectives. Secondary sources include FDA 21 CFR Part 820 quality system documentation, EPA refrigerant enforcement protocols, NIH grant expenditure databases, and industrial gas distribution customs records. Bottom-up vessel shipment analysis and top-down healthcare capital equipment spending patterns triangulate market sizing.
Calibration against historical NIH funding allocations and semiconductor fabrication capacity announcements validates projection trajectories across the analysis window. Segmentation dimensions span product type, end-user compliance tier, material architecture, and vessel capacity. CAGRs derive from weighted average of equipment replacement cycles and service contract renewal rates. Cryo-electron microscopy infrastructure buildouts and state decarbonization mandate timelines constitute industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by composite material specialists or IoT platform entrants would shift outcomes. Stainless steel cost trajectories and EPA enforcement intensity represent primary revision risks. Cross-checking against NIH grant award databases and Arizona-Oregon semiconductor cluster capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Inorganic Tin Chemicals Market
Others
Next Gen Video Codecs Market
Others
Heat Treatment Furnace Market
Others
Roasted Wheat Market
Others
Smart TV Platforms Market
Others
5G Enabled Healthcare Services Market
Others
Versatile Video Coding Market
Others
Italy Feed Additives Market
Others
Fluorite Market
Others
Japan Automotive LED Lighting Market
Others
Smart Card Contactless Ticketing Market
Others
Hearables Market
Others
Foldable Smartphone Market
Others
Commercial Aircraft Angle of Attack Sensors Market
Others
Post Consumer Recycled Bottles Market
Others
Canada Laser Hair Removal Market