
 Allogeneic Human Chondrocyte Market | 2026-2036
Allogeneic Human Chondrocyte Market Size, Share, and Industry Trends Forecast 2026-2036
Allogeneic Human Chondrocyte Market Outlook
Collagen-based matrices are displacing autologous chondrocyte implantation as the preferred carrier scaffold, a material substitution that is recalibring per-procedure economics across cartilage repair. Genzyme leverages its established cell-therapy infrastructure to sustain manufacturing scale in allogeneic chondrocyte supply. Vericel Corp. anchors its position through specialized sports medicine channel control. Kolon TissueGene, Inc. differentiates via R&D intensity in gene-modified allogeneic platforms.
Allogeneic human chondrocytes are living cartilage cells derived from donor tissue, expanded in vitro under serum-free or xeno-free conditions, and formulated at specific cell densities for implantation into focal cartilage defects. The primary commercial purpose is to restore articular cartilage function in patients with traumatic or degenerative joint lesions. Cartilage grafts currently lead product type revenue, while biologic agents represent the fastest-expanding category as combination therapies gain traction. Orthopedics dominates therapy area demand, though sports medicine applications are capturing disproportionate growth as athlete populations seek cartilage-preserving alternatives to joint replacement.
FDA regulates allogeneic chondrocyte products through its Center for Biologics Evaluation and Research under section 351 of the Public Health Service Act, requiring extensive safety and efficacy documentation that shapes development timelines and market access barriers. The European Medicines Agency's ATMP classification under Regulation 1394/2007 imposes centralized marketing authorization requirements that filter competitor entry. Stakeholders must monitor evolving FDA guidance on allogeneic cell therapy potency assays and European Medicines Agency refinements to genetically modified organism containment standards as these frameworks will determine which product formats achieve sustainable commercial traction.
Market Dynamics
The FDA's regenerative medicine advanced therapy designation is compressing development timelines while simultaneously intensifying competitive pressure on manufacturing scale and potency assay standardization.
Growth Catalysts
- EMA's ATMP centralized authorization pathway:This framework streamlines cross-border commercialization for approved therapies, reducing duplicate regulatory burden across EU member states.
- Sports medicine centers:Specialized orthopedic facilities in the United States are expanding procedural volume for cartilage-preserving interventions ahead of joint replacement thresholds.
- Serum-free expansion protocols:Advanced cell culture technologies are eliminating xenogeneic material risks while improving batch consistency for allogeneic formulations.
Market Restraints
- Donor tissue supply concentration:Procurement networks for viable articular cartilage remain concentrated among specialized tissue banks, creating single-source vulnerability.
- FDA potency assay requirements:Extensive characterization demands for cell viability, identity, and functional markers extend pre-approval timelines and inflate development costs.
- Autologous chondrocyte implantation persistence:Established reimbursement pathways and surgeon familiarity with patient-derived cells sustain competitive pressure on allogeneic alternatives.
Strategic Opportunities
- Gene-modified allogeneic platforms:Enhanced chondrocyte persistence and matrix production through genetic modification opens differentiation in large defect indications.
- Biologic agent combinations:Co-formulation with growth factors or scaffolds represents white space for premium positioning in complex cartilage lesions.
- Japan's regenerative medicine legislation:Conditional approval pathways under PMDA frameworks accelerate time-to-market for qualifying allogeneic cell therapies.
Industry Challenges
- Cold chain logistics complexity:Maintaining cell viability through cryopreservation, transport, and thaw protocols requires specialized infrastructure that fragments distribution capability.
- Surgeon training standardization:Heterogeneous arthroscopic technique and implant delivery methods create variable clinical outcomes that complicate evidence generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Allogeneic Human Chondrocyte Market |
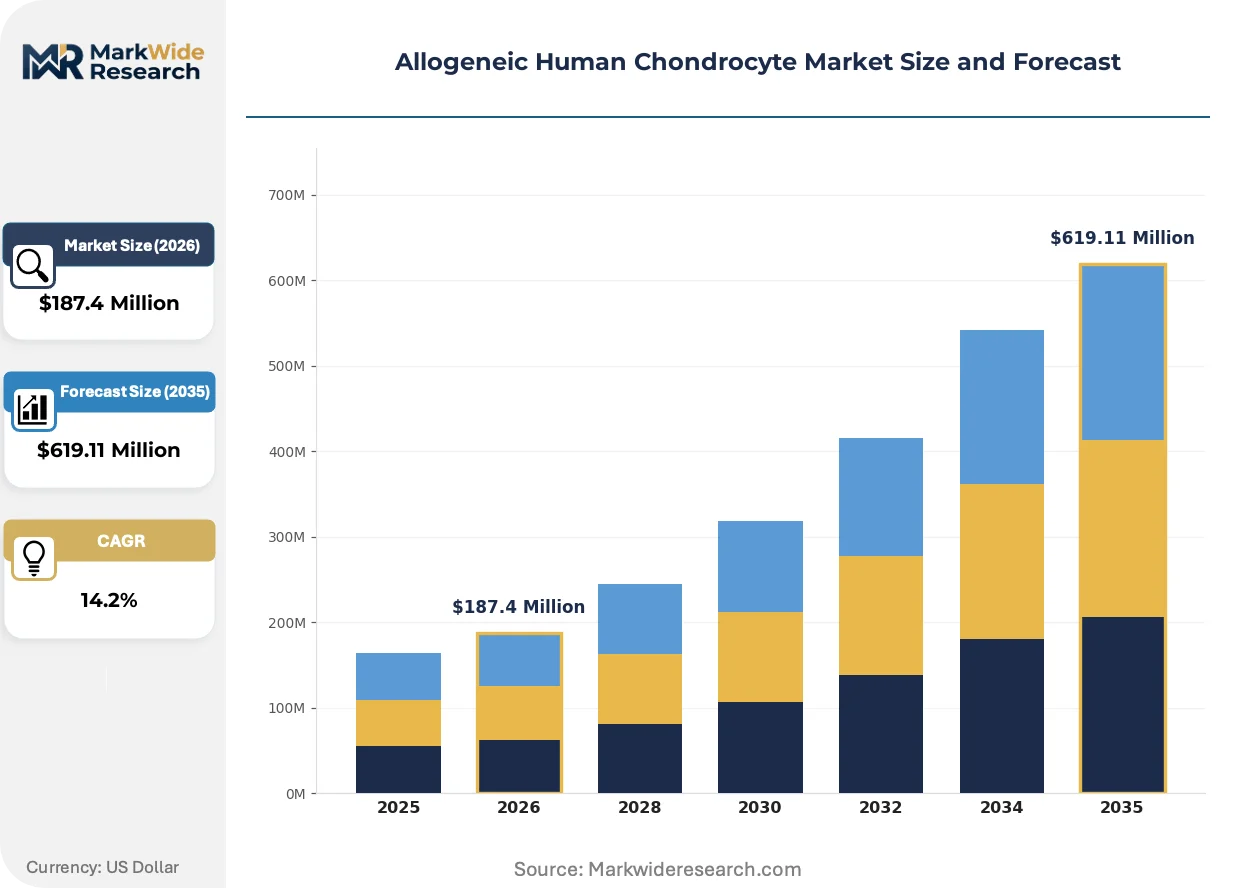
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cartilage Grafts, Stem Cells, Tissue Scaffolds, Biologic Agents Therapy Area: Orthopedics, Rheumatology, Sports Medicine, Pain Management End User: Hospitals, Clinics, Rehabilitation Centers, Research Laboratories Regulatory Approval: FDA Approved, CE Marked, Investigational Devices, Others |
| Companies Covered | Genzyme, EMD Serono, Kolon TissueGene, Inc., Tego Science Inc., Vericel Corp., ISTO Technologies Inc., CellGenix, MEDIPOST Co., Ltd., Zimmer Biomet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Allogeneic Human Chondrocyte Market Strategic Shifts
Automation and closed-system bioprocessing are reconfiguring manufacturing economics while regulatory harmonization efforts and shifting site-of-care preferences reshape commercial architecture.
Closed-system bioreactors are automating cell expansion workflows that previously required open manipulations in cleanroom suites. Contract development and manufacturing organizations are adopting these platforms to reduce contamination risk and labor intensity. This automation is compressing cost-per-dose structures and enabling geographic decentralization of production capacity.
REACH refinements on substance characterization are extending to ancillary materials used in cell therapy manufacturing. Suppliers must now document extractables and leachables profiles for single-use bioreactor components and cryopreservation bags. European manufacturers are responding by qualifying alternative material streams and building redundant supplier relationships.
Site-of-care preparation is displacing centralized pharmacy compounding for certain allogeneic chondrocyte formulations. Hospital-based cell processing laboratories are acquiring thaw-and-administer capabilities that bypass external logistics networks. This pattern is most visible in United States academic medical centers with established cell therapy infrastructure.
Allogeneic Human Chondrocyte Market Segmentation
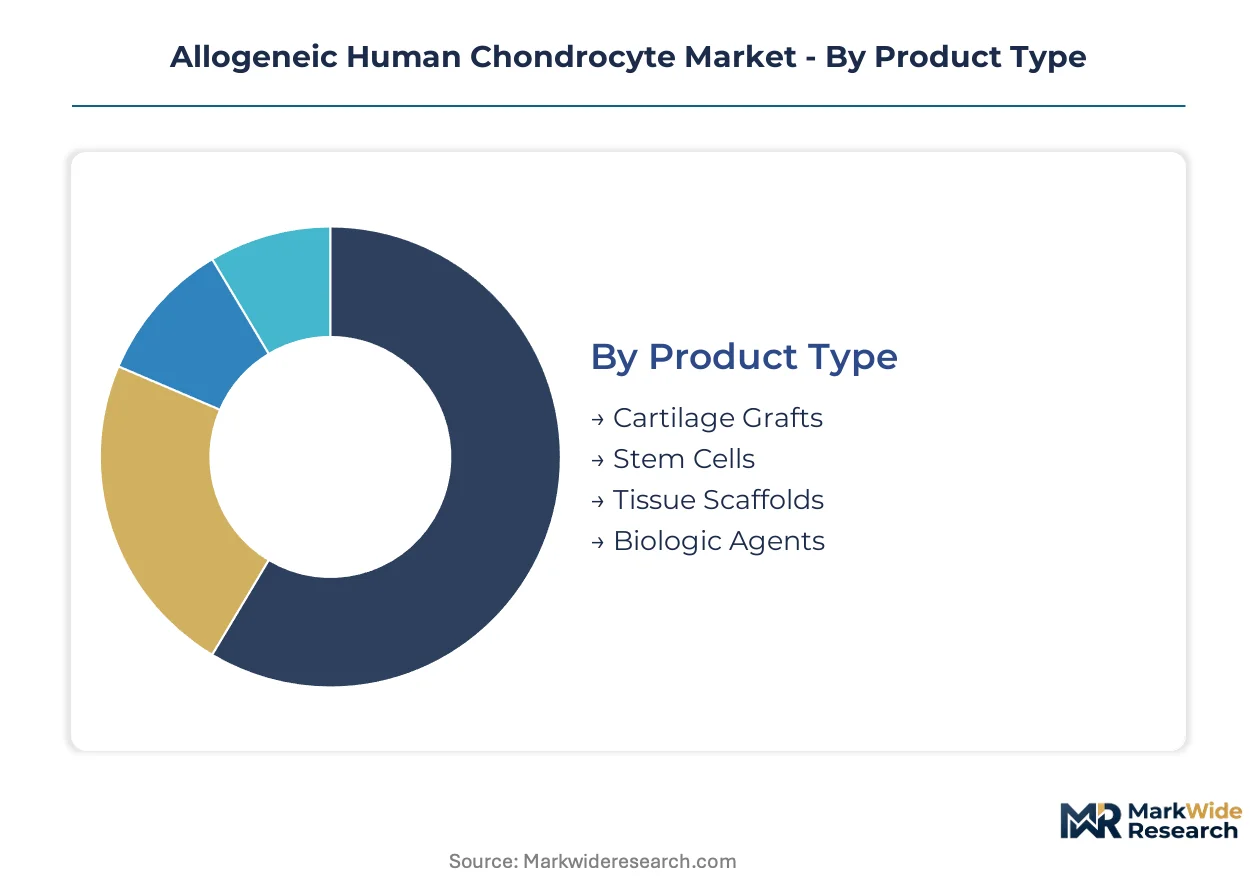
Segmentation in allogeneic chondrocyte markets reveals how product format, clinical setting, and regulatory status interact to determine commercial access and reimbursement pathways. Each axis carries distinct margin profiles and technical barriers that shape competitive positioning.
Product Type:
Cell-matrix combination technologies define the specification spectrum, with scaffold integration and biologic augmentation representing divergent engineering philosophies.
- Cartilage Grafts:Pre-formed hyaline cartilage constructs deliver immediate structural integrity upon implantation. Demand clusters in United States academic medical centers performing high-volume knee restoration procedures, where surgeon preference for off-the-shelf availability reduces operative complexity.
- Biologic Agents:Growth factor-enhanced allogeneic formulations stimulate endogenous repair mechanisms through paracrine signaling. Sports medicine networks in Germany and Switzerland are piloting these combinations for early-stage osteochondral lesions ahead of structural graft requirements.
- Stem Cells:Multipotent progenitor populations require extended in vitro expansion before chondrogenic differentiation.
- Tissue Scaffolds:Acellular collagen or synthetic matrices serve as passive carriers for allogeneic chondrocyte seeding.
Mature deployment sits with Cartilage Grafts. Newer deployment is concentrated in Biologic Agents.
Therapy Area:
Procedure volume and reimbursement intensity vary sharply across musculoskeletal subspecialties, creating tiered market access conditions.
- Orthopedics:Joint reconstruction units in tertiary hospitals perform the majority of implant procedures, with cartilage repair coded separately from arthroplasty in DRG systems. United States Medicare coverage determinations for focal chondral defects sustain procedural economics.
- Sports Medicine:Specialized clinics serving professional and collegiate athletes prioritize cartilage-preserving interventions to extend competitive careers. Australian and Canadian Olympic training institutes have established dedicated cartilage repair protocols.
- Rheumatology:Systemic inflammatory joint disease applications remain investigational with limited commercial traction.
- Pain Management:Palliative cartilage interventions address symptom relief rather than structural restoration.
Volume leadership rests with Orthopedics. Steepest expansion trajectory belongs to Sports Medicine.
End User:
Site-of-care capabilities determine which product formats achieve viable logistics, with infrastructure investment creating segmentation lock-in.
- Hospitals:Integrated operating suites and cell processing laboratories enable same-day thaw-and-implant workflows. Major United States health systems including Mayo Clinic and Cleveland Clinic have centralized cartilage repair services within orthopedic institutes.
- Clinics:Ambulatory surgical centers with arthroscopy capabilities are gaining share for diagnostic arthroscopy combined with microfracture or simple graft placement. German outpatient clinics under DRG pressure seek lower-acuity alternatives to inpatient admission.
- Rehabilitation Centers:Post-operative recovery facilities lack implant capability but influence referral patterns.
- Research Laboratories:Academic cell therapy centers drive protocol development and training.
Established infrastructure dominates in Hospitals. Capacity expansion is accelerating fastest in Clinics.
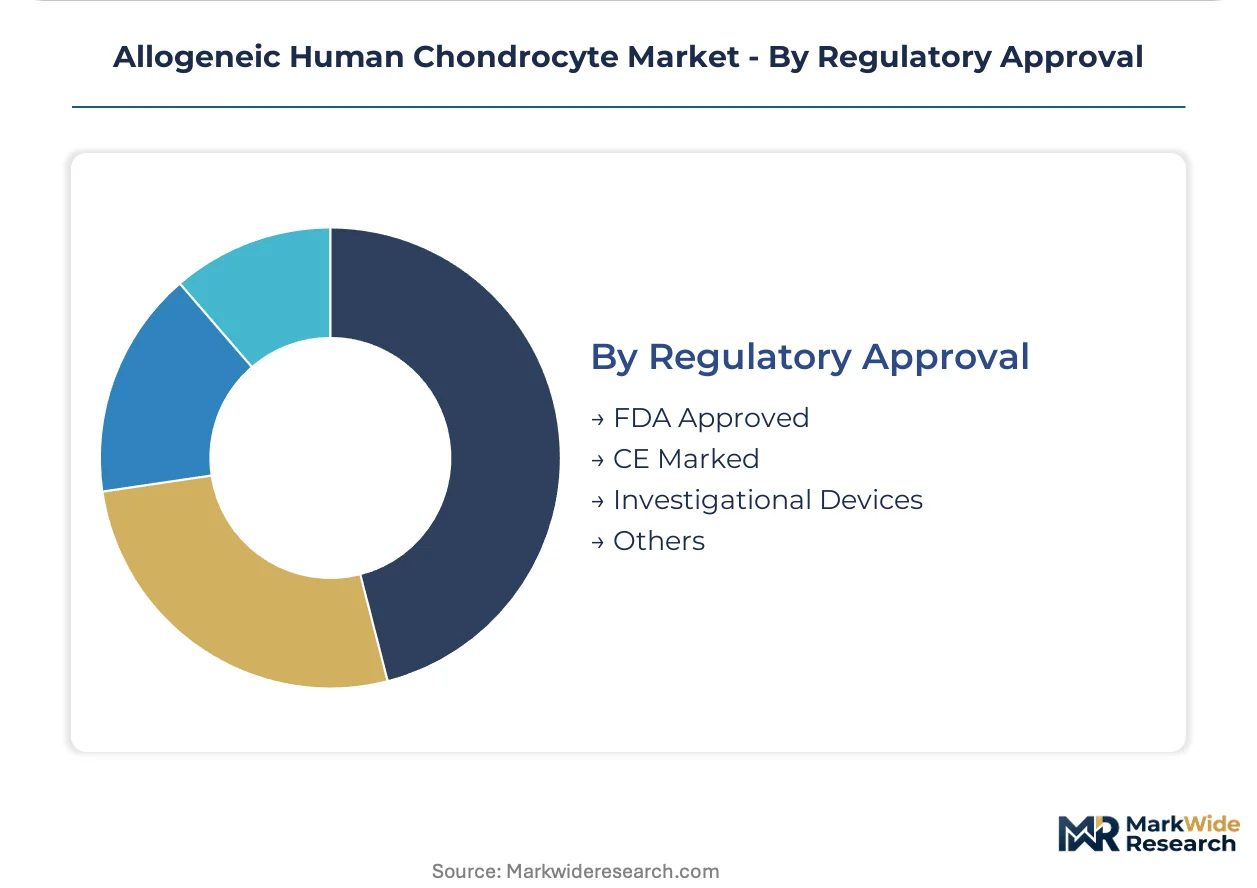
Regulatory Approval:
Marketing authorization status creates discrete commercial tiers with incompatible distribution and promotion rules.
- FDA Approved:Products with BLA or PMA clearance access United States commercial payor contracts and hospital formularies. The regenerative medicine advanced therapy designation pathway has compressed review timelines for qualifying allogeneic chondrocyte products.
- CE Marked:ATMP-classified therapies achieve centralized European Union authorization under EMA oversight, enabling cross-border reimbursement negotiations. Swissmedic maintains parallel recognition agreements for CE-marked advanced therapies.
- Investigational Devices:IDE and clinical trial protocols restrict commercial availability to enrolled sites.
- Others:National pathways including Japan PMDA conditional approval and Health Canada interim orders serve niche access strategies.
Commercial scale concentrates with FDA Approved status. Regulatory diversification is advancing fastest through CE Marked expansions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized biotechnology zones in Massachusetts and California concentrate cell therapy infrastructure, drawing venture capital and clinical trial density that outpaces other jurisdictions.
United States
FDA's regenerative medicine advanced therapy designation compresses review timelines for qualifying allogeneic chondrocyte products. The 21st Century Cures Act provisions accelerate patient access pathways for breakthrough cell therapies. Boston-Cambridge biotech corridor hosts concentrated manufacturing capacity for serum-free expansion protocols.
Germany
EMA's centralized ATMP authorization enables cross-border commercialization across EU member states once German sites achieve approval. The German Medicines Act transposes EU tissue and cell directives into federal enforcement frameworks. Heidelberg and Berlin clusters coordinate multicenter cartilage repair trials with standardized potency assays.
Switzerland
Swissmedic maintains automatic recognition agreements for CE-marked advanced therapies, reducing duplicate regulatory burden. Federal Act on Research involving Human Beings governs donor tissue procurement ethics and traceability. Basel pharmaceutical hub leverages existing biologics infrastructure for allogeneic cell therapy manufacturing scale.
Japan
PMDA conditional approval pathways under the Regenerative Medicine Act accelerate time-to-market for qualifying allogeneic chondrocyte therapies. The Sakigake designation system prioritizes review of innovative cell therapy products. Tokyo-Osaka corridor concentrates hospital-based cell processing laboratories for site-of-care preparation models.
South Korea
MFDS fast-track review for innovative biologics supports domestic development of gene-modified allogeneic platforms. The Korean Ministry of Food and Drug Safety operates dedicated cell therapy consultation programs for pre-submission guidance. Seoul metropolitan area hosts specialized sports medicine institutes piloting biologic agent combinations.
Allogeneic Human Chondrocyte Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated cell therapy developers commanding premium positioning in hospital channels while CDMOs capture manufacturing economics. The vendor base concentrates among entities with established tissue bank relationships and cleanroom infrastructure. Three archetypes dominate: legacy biotech firms with cell therapy heritage, orthopedic device conglomerates diversifying into biologics, and pure-play regenerative medicine specialists. Competitive moves center on strategic partnerships for donor network access and backward integration into tissue procurement.
Within the heritage biotech tier, Genzyme and Vericel Corp. exemplify established cell therapy infrastructure leveraged for allogeneic chondrocyte scale. Among Asia-Pacific developers, Kolon TissueGene, Inc. and MEDIPOST Co., Ltd. occupy positions emphasizing gene-modified platforms and regional regulatory navigation. These entities represent divergent geographic and technological positioning strategies rather than direct segment overlap.
| Leading Market Players |
|---|
| Genzyme |
| EMD Serono |
| Kolon TissueGene, Inc. |
| Tego Science Inc. |
| Vericel Corp. |
| ISTO Technologies Inc. |
| CellGenix |
| MEDIPOST Co., Ltd. |
| Zimmer Biomet |
| Others |
Value Chain & Pricing Dynamics
Serum-free media cost indices cascade through allogeneic chondrocyte manufacturing tiers, compressing margins at standard-grade formulations while gene-modified platforms command premium positioning through proprietary expansion protocols and potency assay differentiation.
Pricing Analysis
Lead-time compression commands premium positioning in the allogeneic chondrocyte market, with cryopreserved inventory available for same-day thaw-and-implant workflows priced above custom-manufactured lots requiring extended expansion cycles. Three-tier pricing structure across premium, standard, and economy levels separates gene-modified platforms with enhanced persistence markers from conventional formulations and research-grade material. Pricing pressure stems from autologous chondrocyte implantation reimbursement parity, which constrains allogeneic premium capture. Hospital procurement committees demonstrate highest price sensitivity, while specialized sports medicine institutes prioritize clinical outcome metrics over unit cost.
Supply Chain Analysis
Domestic-content mandates under FDA's PHS Act section 351 and EMA's ATMP traceability requirements are reshaping sourcing toward qualified tissue banks within regulatory jurisdictions, displacing opportunistic donor network expansion. Supply concentrates in United States specialized tissue procurement organizations, German academic medical center biobanks, and Swissmedic-authorized collection sites. Manufacturing draws from donor cartilage, serum-free expansion media, and cryopreservation excipients as critical inputs. Single-source vulnerability in viable articular cartilage procurement creates structural risk. Distribution runs through hospital-based cell processing laboratories and specialized cold-chain logistics providers serving orthopedic surgery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The allogeneic human chondrocyte market is becoming a vertical-integration race, with donor tissue procurement control and in-house potency assay development emerging as decisive competitive levers.
For Market Incumbents: Deepen backward integration into tissue procurement networks to secure donor cartilage supply against emerging biobank competitors, while expanding manufacturing capacity in Massachusetts and California biotechnology corridors to capture regenerative medicine advanced therapy designation workflow efficiencies. Invest in automated closed-system bioreactor deployment to compress cost-per-dose structures against autologous chondrocyte implantation price benchmarks. For New Entrants and Emerging Players: Capture white space in biologic agent combinations for early-stage osteochondral lesions, where sports medicine networks in Germany and Switzerland are piloting growth factor-enhanced formulations ahead of structural graft requirements. Prioritize Japan's PMDA conditional approval pathway to accelerate time-to-market against FDA review timelines, leveraging site-of-care preparation capabilities in Tokyo-Osaka hospital clusters. For Investors and Strategic Acquirers: Distressed-cycle entries favor contract development and manufacturing organizations with established cleanroom infrastructure and serum-free protocol expertise in the Boston-Cambridge corridor. Long-term viability over the next decade hinges on regulatory navigation capabilities across FDA, EMA, and PMDA frameworks. Monitor FDA guidance refinements on allogeneic cell therapy potency assays as the critical inflection signal for manufacturing scale economics.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA's regenerative medicine advanced therapy designation compresses review timelines for qualifying allogeneic chondrocyte products. |
| Manufacturing Scale-Up | Closed-system bioreactor automation reduces contamination risk and labor intensity in serum-free expansion workflows. |
| Backward Integration | In-house tissue procurement networks mitigate single-source vulnerability in viable articular cartilage supply. |
| Hospital System Partnership | Mayo Clinic and Cleveland Clinic centralized cartilage repair services create channel control for implant volume. |
| Reimbursement Strategy | Medicare coverage determinations for focal chondral defects sustain procedural economics in United States orthopedics. |
Study Parameters
Multi-period observation of FDA approval timelines, EMA ATMP authorization patterns, and hospital procurement contract structures anchored the trend analysis, supplemented by interviews with orthopedic surgeons, cell therapy manufacturing executives, hospital purchasing committee administrators, and regulatory affairs specialists specializing in regenerative medicine. Secondary validation drew from FDA BLA and PMA filings, EMA centralized procedure assessments, ClinicalTrials.gov protocol registrations, and hospital GPO contract databases. Bottom-up procedure volume estimates triangulated against top-down market sizing from payer reimbursement data.
Segment-weighting across product type, therapy area, end user, and regulatory approval status informed the analytical framework, with cartilage graft and biologic agent categories receiving distinct growth trajectory assumptions. CAGRs were derived from procedure volume elasticity to sports medicine center expansion and regenerative medicine advanced therapy designation acceleration effects across the analysis window. Forecast inputs incorporated surgeon training standardization rates and cold-chain logistics infrastructure deployment in target geographies.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA potency assay guidance revisions, EMA genetically modified organism containment standard refinements, and autologous chondrocyte implantation reimbursement parity shifts. Forecasts reflect documented assumptions about donor tissue supply stability and surgeon adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Hydrostatic Testing Market
Others
Global Snow Sports Apparel Market
Others
Mexico Retail Market
Others
Palatants Market
Others
Spain Smart Home Market
Others
Badminton Apparel Market
Others
Vortexers Market
Others
Paraffin Physical Therapy Market
Others
Dried Egg Market
Others
Fire Sprinkler Market
Others
Mobile Computing Devices Market
Others
Moonstone Market
Others
Nonlinear Editing System Market
Others
Bio-Imaging Technologies Market
Others
Spinner Flask Market
Others
Europe Tablet PC Market