
 Global Security Paper Market | 2026-2036
Global Security Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Global Security Paper Market Foresight
Aftermarket authentication service revenue is reconfiguring how security paper suppliers capture lifetime value from government contracts. De La Rue plc leverages its integrated design-to-delivery model across currency and identity platforms. Giesecke+Devrient sustains manufacturing depth through in-house holographic foil production and substrate engineering. Crane & Co., Inc. anchors North American supply relationships with cotton fiber specialization for high-durability banknote stock.
Security paper denotes substrate engineered with embedded or surface-applied features—watermarks, security threads, chemical reagents, and fluorescent fibers—manufactured to prevent unauthorized reproduction and enable machine-readable verification. Intaglio printing and holography technologies command premium positioning due to capital intensity and central bank certification requirements, while thermochromic and fluorescent paper segments expand fastest in lottery and certificate applications where cost-sensitive authentication suffices. Government agencies and financial institutions concentrate procurement volume, though educational institutions represent an emerging channel for diploma and transcript security.
The EU's F-Gas Regulation and REACH standards restrict volatile compounds in coating processes, pushing suppliers toward aqueous UV systems and solvent-free embossing. India's BIS certification and the RBI's substrate specifications create entry barriers that favor established mills with domestic production capacity. Stakeholders must monitor polymer substrate displacement threats and central bank digital currency pilot programs that could alter physical document demand trajectories.
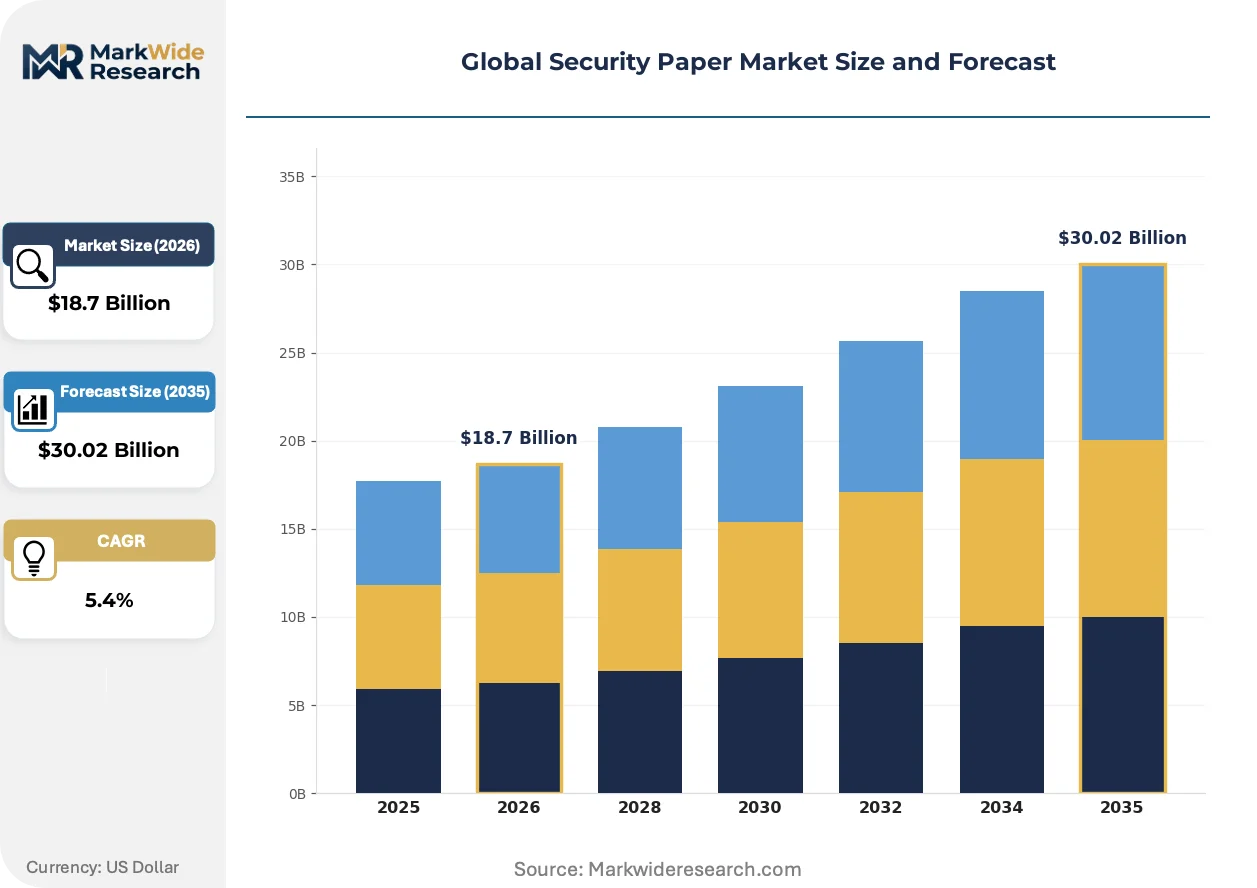
Market Dynamics
Central bank substrate transitions are compressing polymer-to-cotton conversion timelines, forcing security paper mills to retool coating lines and watermark presses ahead of contract renewal cycles. This capital reallocation is reshaping supplier relationships with national mints and identity document issuers.
Growth Catalysts
- REACH chemical restrictions:European coating facilities face mandatory solvent reduction, accelerating aqueous UV system deployment and creating premium positioning for compliant substrate suppliers.
- Polymer banknote durability mandates:Reserve Bank of India specifications drive volume for thread-embedded cotton substrates with extended circulation lifespans.
- Intaglio printing certification:Central bank security departments maintain rigid qualification protocols that lock in incumbent suppliers with proven track records.
Market Restraints
- Cotton fiber price volatility:Raw material fluctuations in commodity cotton markets compress margin predictability for banknote substrate producers.
- Supply concentration in European holographic foil:Limited qualified suppliers of optically variable thread create single-source vulnerability for tier-one currency printers.
- Central bank digital currency pilots:Live testing of CBDC platforms in Nigeria, China, and Sweden threatens long-term physical banknote demand trajectories.
Strategic Opportunities
- Educational credential authentication:Universities in Southeast Asia and Latin America represent underpenetrated demand for diploma security substrates with QR-code integration.
- Lottery ticket thermochromic expansion:State gaming commissions seek cost-sensitive authentication layers that shift color under thermal stress.
- EU F-Gas Regulation compliance services:Paper mills offering solvent-free embossing and coating consultation capture adjacent revenue from competitor retooling delays.
Industry Challenges
- Intaglio press operator scarcity:Skilled crafts capable of maintaining engraved plate precision are retiring faster than apprenticeship programs replenish talent pipelines.
- Multi-layer substrate integration:Combining polymer windows with cotton fiber cores requires cleanroom-grade lamination facilities that few mills possess.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Security Paper Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Watermarked Paper, Thermochromic Paper, Chemical Sensitive Paper, Fluorescent Paper, Magnetic Ink Paper Technology: Intaglio Printing, Micro-Printing, Holography, Foil Stamping, UV Coating, Embossing Application: Banknotes, Passports, Certificates, Legal Documents, Lottery Tickets, Identity Cards End User: Financial Institutions, Government Agencies, Educational Institutions, Legal Firms, Postal Services |
| Companies Covered | Giesecke+Devrient, Fedrigoni Group, De La Rue plc, Security Paper Limited, Crane & Co., Inc., Louisenthal, Simpson Security Papers, Ciotola S.R.L., Ceprohart SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Security Paper Market Shifts & Advancements
Authentication substrate engineering is converging with digital verification layers, compressing the boundary between physical document security and machine-readable traceability. This fusion is redefining how security paper suppliers architect product roadmaps and service offerings.
Machine-readable fluorescent fiber embedding is hybridizing physical substrate durability with automated sorting compatibility. Postal services in Germany and Japan are retrofitting high-speed mail processing equipment to detect these fibers at throughput rates exceeding 40,000 items per hour. The technology is compressing authentication costs for volume document issuers while maintaining human-visible verification.
EU F-Gas Regulation phase-down schedules are forcing coating chemistry reformulation across security paper production lines. Solvent-based embossing systems face mandatory replacement timelines, pushing suppliers toward aqueous UV curing and electron beam technologies. Currency printers in France and Italy are qualifying these alternative processes ahead of 2027 compliance deadlines.
Aftermarket authentication verification services are unbundling from initial substrate supply contracts. Government agencies now procure multi-year document integrity monitoring separately from paper stock, creating recurring revenue streams for suppliers with distributed authentication networks. India's postal division and South Korea's national ID program have adopted this service separation model.
Global Security Paper Market Segmentation
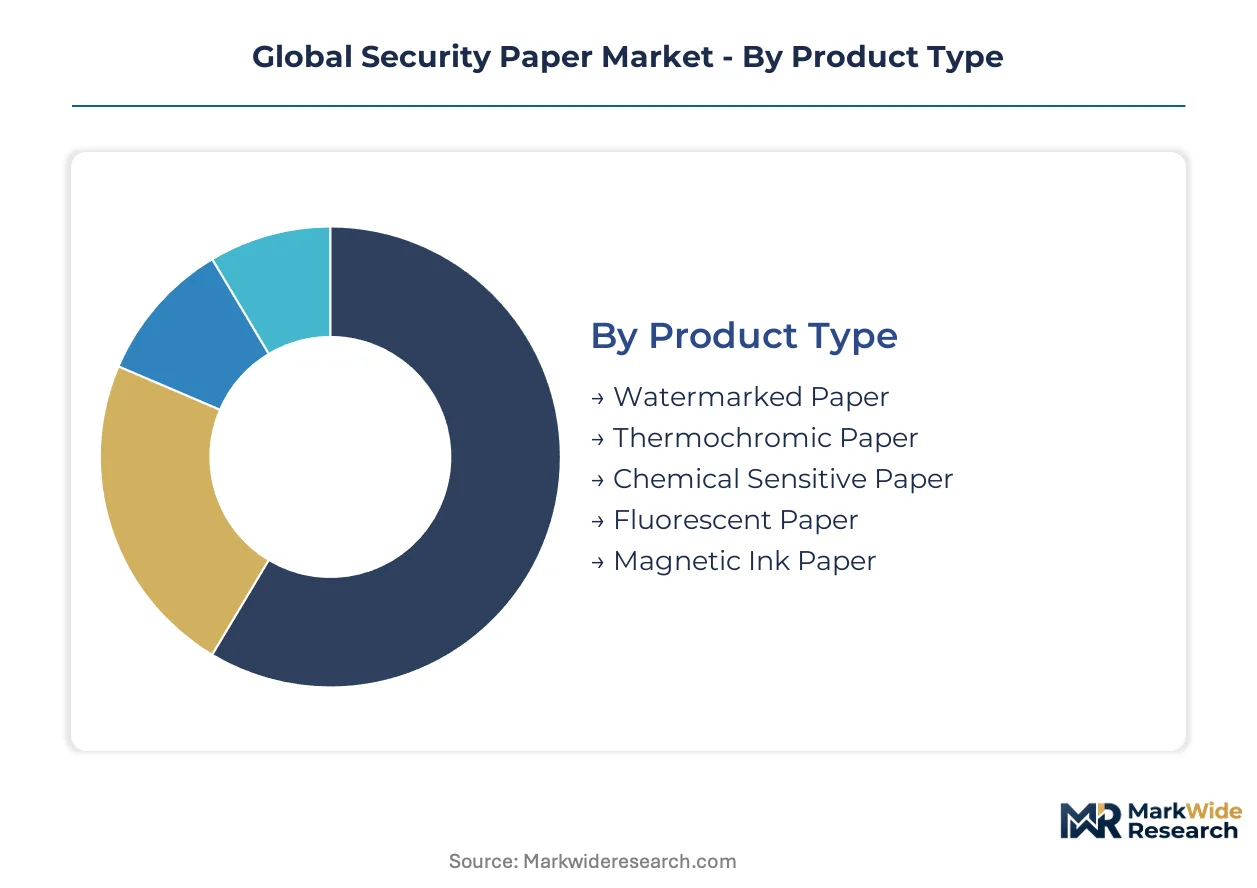
Segmentation in security paper markets reveals how authentication requirements diverge across document lifecycles and threat profiles. Product specifications, manufacturing technologies, and end-user procurement patterns each create distinct competitive arenas with different margin structures and certification barriers.
Product Type:
After-sales service intensity varies sharply across substrate categories, with watermarked and thermochromic papers demanding ongoing technical support for press calibration and color-shift verification protocols.
- Watermarked Paper:Cotton fiber substrates incorporate dimensional designs visible under transmitted light, requiring precision dandy roll engineering. Central banks in India and Egypt specify multi-tone watermarks for high-denomination banknotes, with RBI mandating thread-embedded variants that extend circulation lifespan. By volume, Watermarked Paper leads. By growth pace, Chemical Sensitive Paper is ahead.
- Thermochromic Paper:Leuco dye coatings enable reversible color shifts at defined temperature thresholds. State gaming commissions in Brazil and Australia procure thermochromic lottery stocks where cost-sensitive authentication suffices without holographic premium.
- Chemical Sensitive Paper:Acid-base indicator integration detects tampering through visible staining reactions. India's postal networks specify chemical-reactive substrates for money order security.
- Fluorescent Paper:UV-excited fiber embedding supports machine-readable sorting at postal processing velocities exceeding 40,000 items hourly in Germany and Japan.
- Magnetic Ink Paper:Ferrous particle integration enables automated character recognition for check clearing systems at North American financial institutions.
Cost tier separation distinguishes premium watermark substrates from commodity fluorescent stocks, with authentication complexity determining pricing architecture.
Technology:
Application-specific performance requirements segment manufacturing processes by capital intensity and central bank certification rigor.
- Intaglio Printing:Engraved plate transfer creates tactile ridge structures resistant to photocopy reproduction. The European Central Bank and Bank of England maintain rigid qualification protocols that lock in incumbent suppliers with proven track records.
- Holography:Optically variable devices command premium positioning due to limited qualified foil suppliers in France and Germany. By volume, UV Coating leads. By growth pace, Holography is ahead.
- Micro-Printing:Sub-millimeter text embedding defeats standard scanning resolution for passport and ID document applications.
- Foil Stamping:Metallic transfer decoration provides visual authentication without machine-readable functionality for certificate and diploma markets.
- UV Coating:Aqueous curing systems replace solvent-based processes under EU F-Gas Regulation mandates, reshaping supplier compliance investments.
- Embossing:Pressure-raised surface patterns create tactile verification layers for blind accessibility in Canadian and Australian currency.
Capital deployment concentrates in intaglio and holography where certification barriers protect incumbent positions, while UV coating adoption accelerates fastest under regulatory phase-down schedules.
Application:
Document lifecycle durability requirements and fraud exposure levels determine substrate specification intensity across use cases.
- Banknotes:Multi-layer cotton-polymer substrates with integrated threads and watermarks face the most stringent central bank durability mandates. By volume, Banknotes lead. By growth pace, Certificates are ahead.
- Passports:ICAO-compliant polycarbonate and composite pages require holographic laminates and laser-engraved personalization resistant to photo substitution.
- Certificates:Educational credential authentication expands fastest in Southeast Asian and Latin American universities seeking QR-code integration with physical substrate security.
- Legal Documents:Deed and contract security papers emphasize chemical sensitivity for tamper evidence rather than machine readability.
- Lottery Tickets:Thermochromic and fluorescent layers balance cost constraints against retail validation needs at point-of-sale terminals.
- Identity Cards:Government ID programs in South Korea and India separate document integrity monitoring from substrate supply, creating recurring authentication service revenue.
Procurement concentration in government channels contrasts with emerging educational demand, where volume scale remains modest but specification flexibility permits faster supplier entry.
End User:
Procurement sophistication and compliance mandate stringency create distinct customer tiers with diverging supplier relationship models.
- Government Agencies:Central banks, national ID authorities, and postal services drive volume through multi-year framework agreements with embedded technical support clauses. By volume, Government Agencies lead. By growth pace, Educational Institutions are ahead.
- Financial Institutions:Check stock and certificate procurement emphasizes magnetic ink compatibility and automated processing integration.
- Educational Institutions:University diploma security programs in Indonesia, Mexico, and Colombia represent underpenetrated demand for QR-linked substrate authentication.
- Legal Firms:Document security procurement concentrates in notarial bond paper with chemical sensitivity for evidentiary integrity.
- Postal Services:High-speed sorting compatibility requirements in Japan Post and Deutsche Post drive fluorescent fiber specification standardization.
Customer maturity separates long-cycle government contracts with embedded service obligations from faster-turn educational procurement where technical consultation requirements remain limited.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. India and China prioritize high-durability banknote substrates with extended circulation lifespans. European markets emphasize regulatory-compliant coating chemistries under solvent-reduction mandates.
India
The Reserve Bank of India drives volume for thread-embedded cotton substrates across high-denomination banknote series. BIS certification requirements and domestic production mandates favor established mills with local watermark press capacity. Mumbai and Nashik host concentrated currency substrate manufacturing clusters serving RBI procurement cycles.
Germany
Deutsche Post specifications for fluorescent fiber detection at 40,000 items hourly sustain demand for machine-readable postal substrates. REACH solvent restrictions and F-Gas Regulation phase-downs accelerate aqueous UV coating adoption across Bavarian and North Rhine-Westphalian production facilities. Frankfurt and Munich anchor holographic foil engineering clusters supplying optically variable thread to European currency printers.
United States
Magnetic ink paper demand concentrates in check-clearing systems at North American financial institutions. Crane & Co. anchors cotton fiber specialization for Federal Reserve banknote stock through Massachusetts-based production. Boston-Worcester corridor maintains legacy intaglio press capacity with skilled operator apprenticeship programs.
China
Central bank digital currency pilot programs in Shenzhen and Suzhou threaten long-term physical banknote trajectories even as substrate volume holds. SAMR quality standards and GB certification frameworks govern domestic security paper procurement. Shanghai and Guangdong manufacturing bases supply polymer window integration for hybrid cotton-polymer substrates.
Brazil
State gaming commissions procure thermochromic lottery stocks where cost-sensitive authentication suffices without holographic premium. ANVISA regulatory frameworks apply to document security for pharmaceutical serialization applications. São Paulo and Rio de Janeiro concentrate lottery ticket printing capacity with regional substrate sourcing.
Global Security Paper Market Competitive Landscape
Capability concentration sits with heritage currency substrate specialists; scale advantage sits with diversified paper conglomerates. The vendor base stratifies across three tiers: integrated design-to-delivery platforms, substrate engineering specialists, and regional security printers. Dominant competitive moves include capacity retooling for polymer-cotton hybrid substrates and geographic expansion into educational credential authentication markets.
Within the integrated platform tier, De La Rue plc and Giesecke+Devrient occupy positions spanning currency and identity document ecosystems. Crane & Co., Inc. exemplifies the North American cotton fiber specialization archetype with captive supply relationships to Federal Reserve procurement. Fedrigoni Group represents the European diversified paper conglomerate model with security substrate capabilities embedded within broader specialty paper portfolios.
| Leading Market Players |
|---|
| Giesecke+Devrient |
| Fedrigoni Group |
| De La Rue plc |
| Security Paper Limited |
| Crane & Co., Inc. |
| Louisenthal |
| Simpson Security Papers |
| Ciotola S.R.L. |
| Ceprohart SA |
| Others |
Supply & Pricing Matrix
Mumbai and Nashik manufacturing clusters anchor global watermark press capacity, concentrating supply-side leverage among established mills with Reserve Bank of India certification. This geographic concentration amplifies pricing power for thread-embedded cotton substrates while compressing margin flexibility for newer entrants lacking domestic production credentials.
Pricing Analysis
Long-term offtake contracts dominate central bank procurement, with multi-year framework agreements locking in volume commitments for watermark and holographic substrate tiers. Price differentiation rests on certification grade and after-sales service bundling, with RBI-qualified suppliers commanding premium positioning over uncertified competitors. Cost compression in fluorescent paper segments is intensifying because state gaming commissions prioritize cost-sensitive authentication over holographic premium. Educational institutions exhibit highest price sensitivity due to limited procurement sophistication, while central banks maintain lowest sensitivity given durability mandates and counterfeiting risk exposure.
Supply Chain Analysis
Cotton fiber feedstock draws from commodity markets in India, Egypt, and the United States, with fluctuations in raw material costs transmitting directly to banknote substrate producers. Holographic foil and optically variable thread hinge on qualified suppliers concentrated in France and Germany, creating single-source vulnerability for tier-one currency printers. Distribution runs through national mints and security printers with embedded technical support obligations, limiting direct mill-to-agency relationships. Tariff exposure on specialty coating chemicals compounds supply risk under EU REACH and F-Gas Regulation phase-down timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated government procurement channels, with central banks and national ID authorities consolidating volume through fewer multi-year framework agreements that embed stringent certification requirements.
For Market Incumbents: Insulate core currency substrate positions through captive holographic foil production and in-house watermark press capacity additions in India and Germany. Central bank digital currency pilots threaten long-term physical banknote trajectories, making certification investment in polymer-cotton hybrid substrates the priority defensive lever against substrate displacement. For New Entrants and Emerging Players: Establish a beachhead in Southeast Asian educational credential authentication, where Indonesian and Mexican universities seek QR-code integrated diploma substrates with limited incumbent penetration. Thermochromic lottery stock procurement by Brazilian and Australian state gaming commissions offers the most penetrable application, with technical consultation partnerships providing the optimal go-to-market angle against established holographic suppliers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors substrate engineering specialists with aqueous UV coating capabilities and cleanroom-grade lamination facilities for polymer-cotton hybrid production. Long-term viability rests on exposure to central bank durability mandates rather than cost-sensitive lottery and certificate segments. The signal to watch is central bank digital currency pilot program acceleration in Nigeria, China, and Sweden as inflection indicator for physical substrate demand trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Polymer-Cotton Hybrid Capacity Expansion | Retooling coating lines for RBI durability specifications captures emerging banknote substrate transitions. |
| Aqueous UV Coating Transition | Compliance with EU F-Gas Regulation phase-downs opens premium positioning for European currency printers. |
| Educational Credential Authentication Partnership | QR-code integration with physical substrates penetrates underdeveloped Southeast Asian university demand. |
| Aftermarket Verification Service Unbundling | Separating document integrity monitoring from substrate supply creates recurring revenue at India Post and South Korea's national ID program. |
| Holographic Foil Backward Integration | In-house optically variable thread production mitigates single-source vulnerability from French and German qualified suppliers. |
Research Methodology
Cross-validation between primary interviews with currency substrate plant managers, central bank procurement officers, and postal service operations directors and secondary validation through customs trade data, BIS certification records, and RBI procurement disclosures anchors the qualitative findings. Bottom-up demand modeling from individual national mint and security printer volumes triangulates against top-down central bank currency circulation data and polymer substrate transition announcements.
Calibration against historical substrate procurement cycles and central bank contract renewal timelines shapes the analytical framework across the analysis window. Segmentation dimensions modeled include product type, manufacturing technology, application lifecycle durability requirements, and end-user procurement sophistication. CAGRs derive from volume-weighted averaging of country-level substrate demand trajectories, with polymer-to-cotton conversion timelines and CBDC pilot program acceleration serving as industry-specific forecast inputs.
Sensitivities concentrate around central bank digital currency adoption velocity, cotton fiber commodity price volatility, and REACH/F-Gas Regulation compliance timeline acceleration. Forecasts reflect documented assumptions regarding substrate durability mandate persistence and holographic foil supplier concentration stability. Cross-checking against central bank annual report currency production disclosures and postal service automation investment announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Specialty Paper Market
Paper Products
Middle East and Africa Decor Paper Market
Paper Products
Fluff Pulp Market
Paper Products
Photographic Paper Market
Paper Products
Sanitary Paper Products Market
Paper Products
Europe Decor Paper Market
Paper Products
Reprographic Paper Market
Paper Products
Global Pulp and Paper Machinery Market
Paper Products
Pulp and Paper Market
Paper Products
Hardwood Pulp Market
Paper Products
Compressed Fiberboard Market
Paper Products
Pulp and Paper Chemicals Market
Paper Products
Uncoated White Top Testliner Market
Paper Products
Paper Pigment Market
Paper Products
Graphic Paper Market
Paper Products
White Line Chipboard Market