
 Global Luxury High End Furniture Market | 2026-2036
Global Luxury High End Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Global Luxury High End Furniture Market Outlook
Project finance and asset-light leasing models are reshaping competitive entry in luxury furniture, allowing design studios to scale without captive manufacturing. Restoration Hardware (RH) leverages direct-to-consumer gallery formats to control pricing and brand narrative. Poltrona Frau anchors its position through vertically integrated leather tanning and upholstery craftsmanship in Italy. Herman Miller-Knoll competes across corporate and residential segments with licensed designer collections and commercial-scale production.
Luxury high end furniture comprises bespoke and limited-production interior furnishings crafted from premium materials such as full-grain leather, solid hardwoods, and hand-blown glass, primarily serving affluent residential, hospitality, and corporate environments where aesthetic distinction and durability justify premium expenditure. The wood material segment dominates absolute value given its centrality to classical and contemporary collections, while leather commands outsized margins in upholstery-heavy hospitality installations. The hospitality end user category represents the fastest-growing demand pool as luxury hotel chains in the Middle East and Asia-Pacific commission custom interiors to differentiate guest experiences.
EU ECHA REACH regulations constrain chemical treatments and finishes permitted on imported wood and leather substrates, directly affecting supplier qualification costs for brands selling into Europe. The US EPA and California Air Resources Board jointly enforce formaldehyde emission standards that shape composite wood sourcing decisions for manufacturers serving North American commercial clients. Stakeholders must monitor evolving extended producer responsibility frameworks across multiple jurisdictions, as compliance architecture increasingly determines which suppliers retain access to premium distribution channels.
Market Dynamics
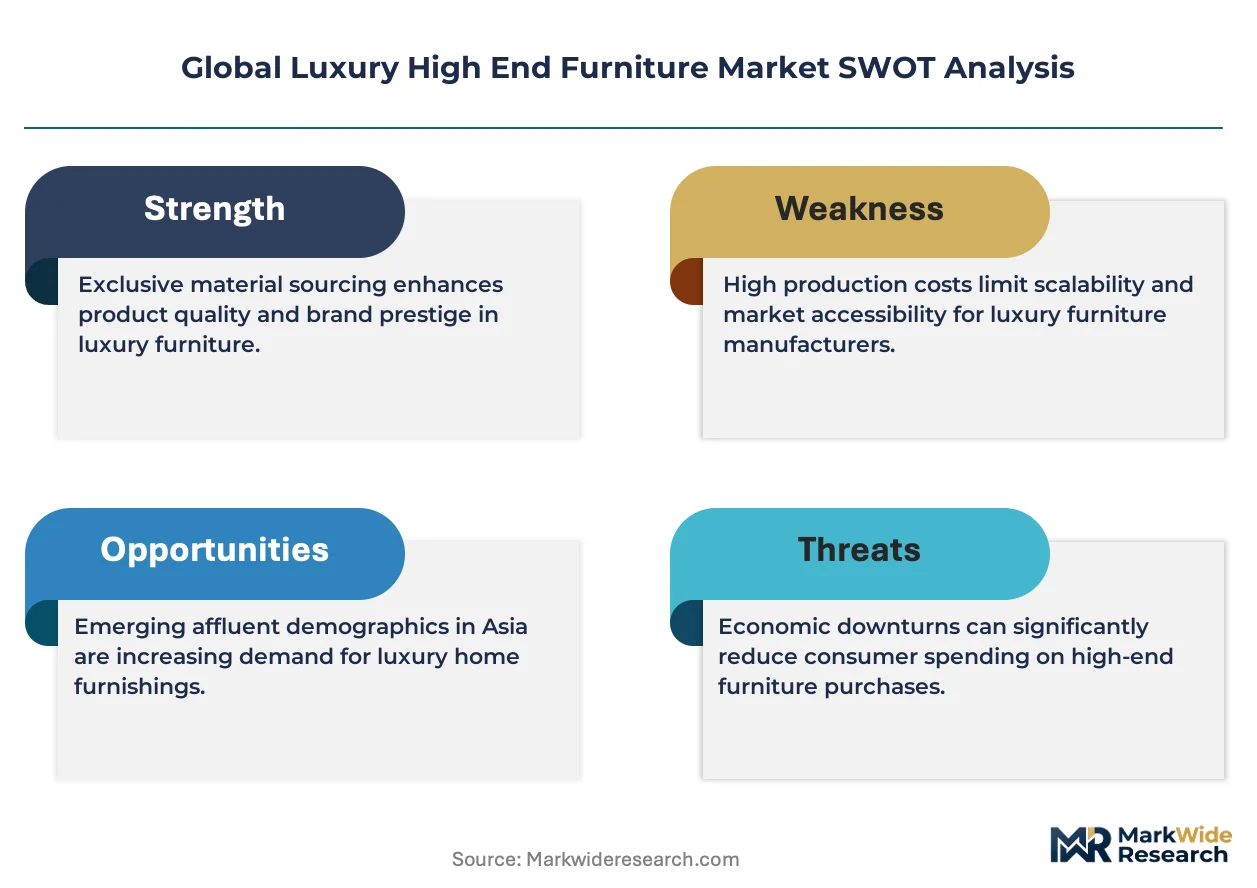
EU ECHA REACH compliance mandates and extended producer responsibility frameworks are forcing manufacturers to restructure certified sustainable supply chains, compressing supplier qualification timelines and elevating compliance costs across wood sourcing and chemical treatment protocols.
Growth Catalysts
- Brianza Cluster Infrastructure:Italy's concentrated artisanal manufacturing heritage intersects with scaled export logistics, enabling rapid fulfillment of bespoke residential and hospitality commissions.
- Middle East Ultra-High-Net-Worth Residential Expansion:Dubai and Riyadh buyers are expanding procurement of custom interior collections, driving demand for full-grain leather and solid hardwood furnishings.
- EU Green Deal Timber Certification:Mandatory chain-of-custody documentation under the EU Timber Regulation is accelerating formal adoption of FSC and PEFC certified wood substrates among European manufacturers.
Market Restraints
- Full-Grain Leather Input Volatility:Tannery capacity concentration in Northern Italy creates supply bottlenecks during peak hospitality commissioning cycles.
- REACH Compliance Cost Burden:ECHA chemical restriction lists expand testing requirements for finishes and adhesives, directly elevating per-unit qualification expenses for European market entry.
- Artisan Labor Pool Constraints:Hand-finishing and marquetry skill scarcity in traditional manufacturing clusters limits production scaling without quality degradation.
Strategic Opportunities
- Saudi Arabia Giga-Project Hospitality:Neom and Red Sea Development Authority commissions represent underpenetrated demand for custom interior installations at unprecedented scale.
- Asset-Light Leasing Models:Design studios are deploying direct-to-consumer gallery formats that eliminate wholesale margin compression and enable dynamic pricing control.
- Digital Fabrication Convergence:CNC routing combined with traditional hand-finishing is collapsing production lead times for complex joinery while preserving artisanal value perception.
Industry Challenges
- Multi-Jurisdiction Extended Producer Responsibility:Divergent e-waste and furniture end-of-life mandates across EU member states, US states, and UAE emirates complicate reverse logistics architecture.
- Master Craftsman Succession Gaps:Upholstery and veneer specialist knowledge transfer lags retirement curves in Italy's aging artisan workforce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Luxury High End Furniture Market |
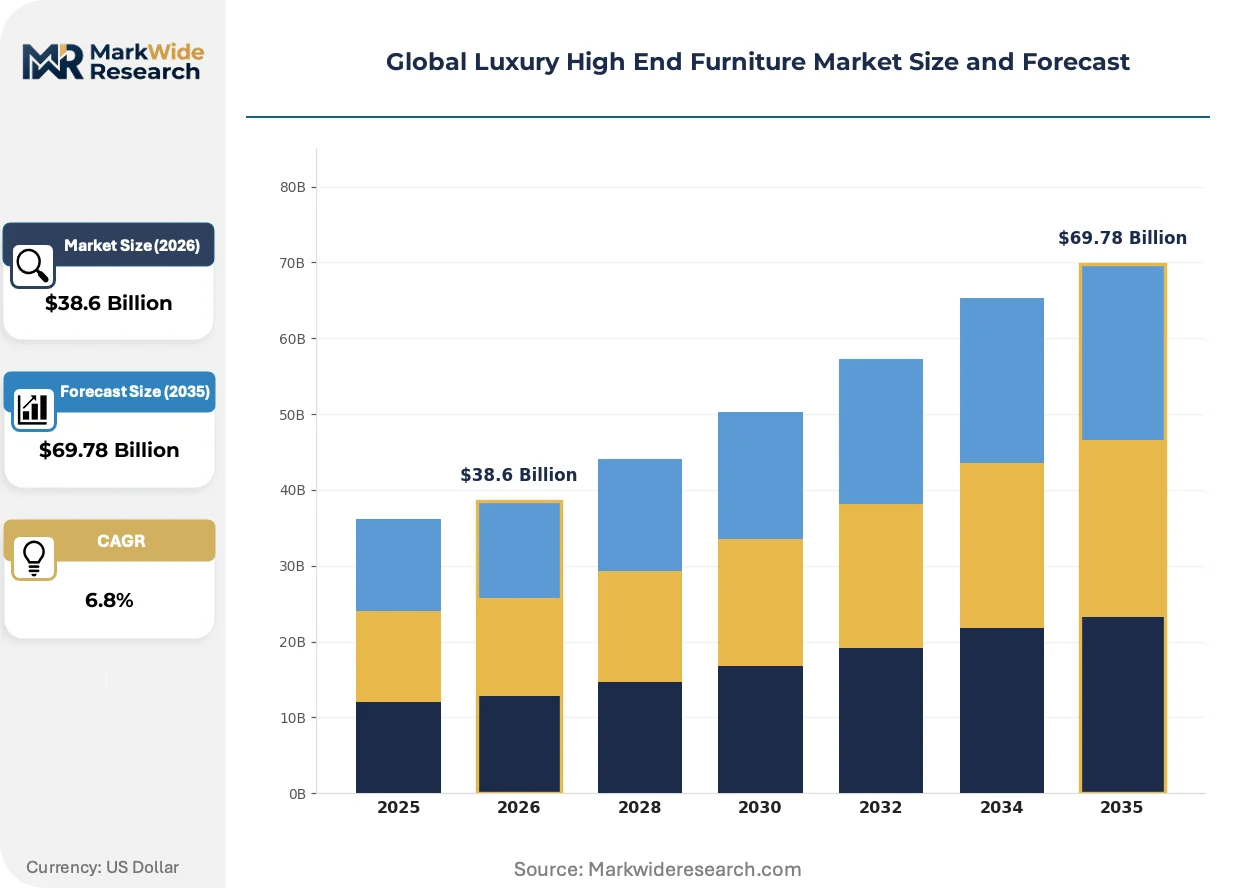
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chairs, Sofas, Tables, Cabinets Material: Wood, Metal, Glass, Leather Style: Modern, Classical, Vintage, Contemporary End User: Residential, Commercial, Hospitality, Corporate |
| Companies Covered | Restoration Hardware (RH), Roche Bobois, Herman Miller-Knoll, Poltrona Frau, Luxury Living Group (Fendi Casa), B&B Italia, Minotti, Natuzzi, Baker Furniture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Luxury High End Furniture Market Strategic Shifts
Digital manufacturing integration and regulatory transparency mandates are compressing traditional production timelines while elevating material provenance as a competitive differentiator across residential and hospitality procurement.
Parametric design software paired with robotic milling is collapsing the cost differential between custom one-off pieces and limited production runs. Luxury hotel chains in Singapore and Qatar are adopting these workflows to accelerate bespoke commissioning cycles from eighteen months to under nine months. The technology is collapsing the historical trade-off between artisanal uniqueness and commercial scalability.
ECHA REACH Annex XVII restrictions on chromium VI in leather tanning entered force across all EU member states, prohibiting specific chemical treatments previously standard in upholstery manufacturing. Italian tanneries serving Poltrona Frau and comparable houses have reformulated vegetable-tanning protocols to maintain European market access. Hospitality projects with EU delivery requirements now specify REACH-compliant substrates regardless of final installation geography.
Direct procurement from design studios is displacing traditional wholesale and retail intermediation among ultra-high-net-worth residential buyers in Dubai and Riyadh. These buyers increasingly commission entire interior collections through single-source relationships with established ateliers, bypassing multi-brand showrooms entirely. The pattern is most visible in residential estates exceeding fifteen thousand square feet where coordination complexity favors consolidated accountability.
Global Luxury High End Furniture Market Segmentation
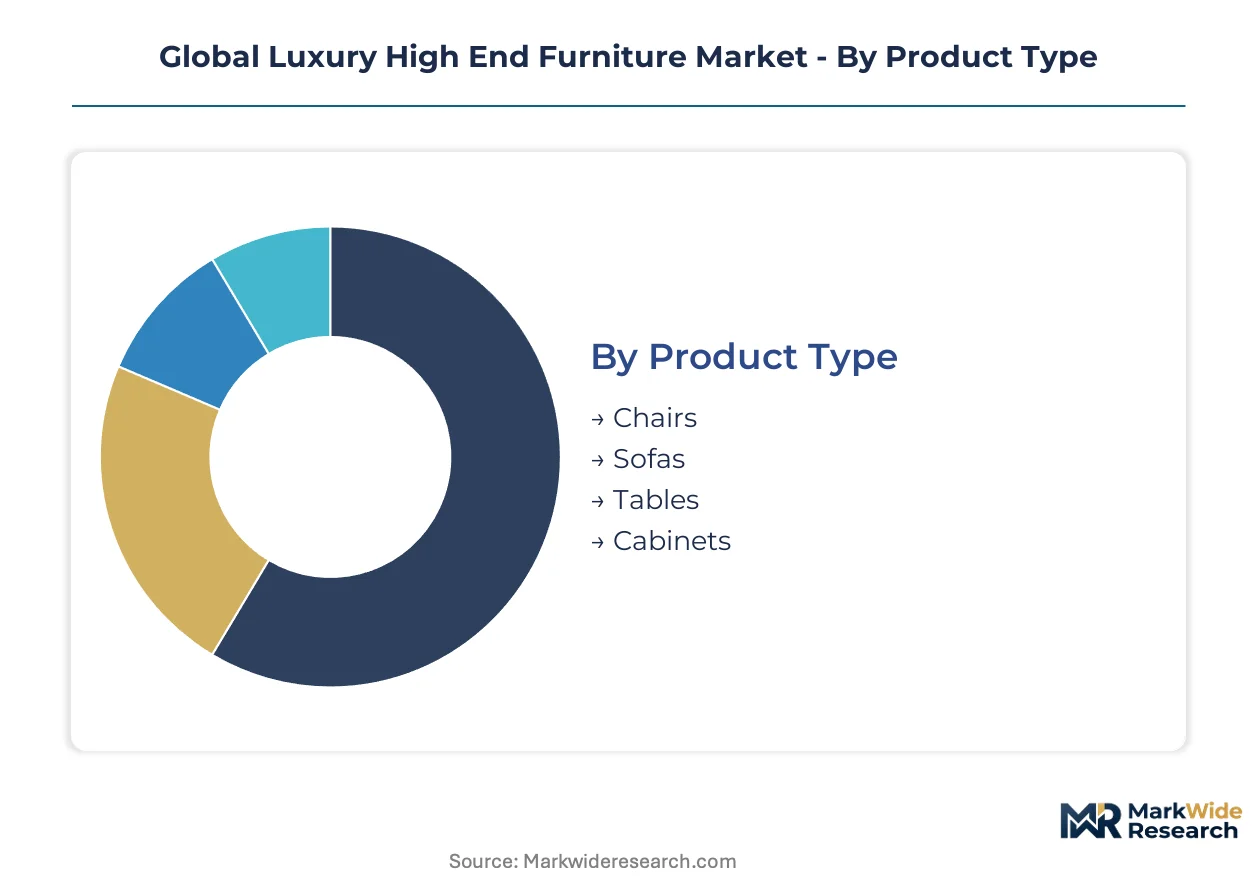
Segmentation in luxury furniture determines procurement cadence and margin architecture. Product type and material selection drive replacement cycles, while end-user category shapes specification intensity and compliance requirements.
Product Type:
Replacement velocity varies dramatically across furnishings, with seating categories turning over fastest due to wear patterns and style obsolescence.
- Sofas:Upholstered seating systems with engineered suspension and cushion cores represent the largest absolute revenue pool. Hospitality procurement in Dubai and Riyadh concentrates demand for oversized sectional configurations, though artisan labor scarcity in Italy's Brianza cluster constrains fulfillment scaling during peak commissioning windows.
- Chairs:Task, dining, and accent seating span the broadest price bandwidth. Corporate installations in Singapore and Qatar drive specification of ergonomic executive seating with certified sustainable wood substrates, pressured by EU ECHA REACH compliance mandates on chemical treatments.
- Tables:Dining, conference, and occasional surfaces with complex joinery or stone inlay.
- Cabinets:Storage systems including credenzas, armoires, and built-in millwork.
Sofas anchor the volume base while chairs gain share at the steepest rate.
Material:
Cost tier stratification separates mass-luxury accessible materials from scarcity-driven substrates commanding extreme premiums.
- Wood:Solid hardwoods and engineered substrates with certified chain-of-custody documentation. EU Green Deal timber certification requirements accelerate FSC and PEFC adoption among European manufacturers, while US EPA formaldehyde emission standards shape composite sourcing for North American commercial clients.
- Leather:Full-grain and top-grain hides with vegetable or chrome tanning. Northern Italian tannery capacity concentration creates supply bottlenecks during peak hospitality cycles, with ECHA REACH Annex XVII chromium VI restrictions forcing reformulation of standard treatment protocols.
- Metal:Brass, bronze, and stainless steel in structural and decorative applications.
- Glass:Hand-blown and tempered architectural elements.
Wood dominates absolute value while leather commands the widest margin expansion.
Style:
Geographic preference divergence creates distinct demand centers with minimal overlap in procurement patterns.
- Classical:Ornamented forms referencing 18th and 19th century European traditions. Saudi Arabia giga-project hospitality commissions sustain demand for marquetry and gilt surfaces, though master craftsman succession gaps in Italy's aging artisan workforce constrain quality-conservative scaling.
- Modern:Clean-lined geometries emphasizing material honesty and functional clarity. Singapore and Qatar luxury hotel chains adopt parametric design software with robotic milling to accelerate bespoke commissioning cycles.
- Contemporary:Current design vocabulary blending multiple historical references.
- Vintage:Authentic period pieces and reproductions of 20th century iconic designs.
Classical retains the deepest geographic penetration while modern climbs the fastest in new-build hospitality.
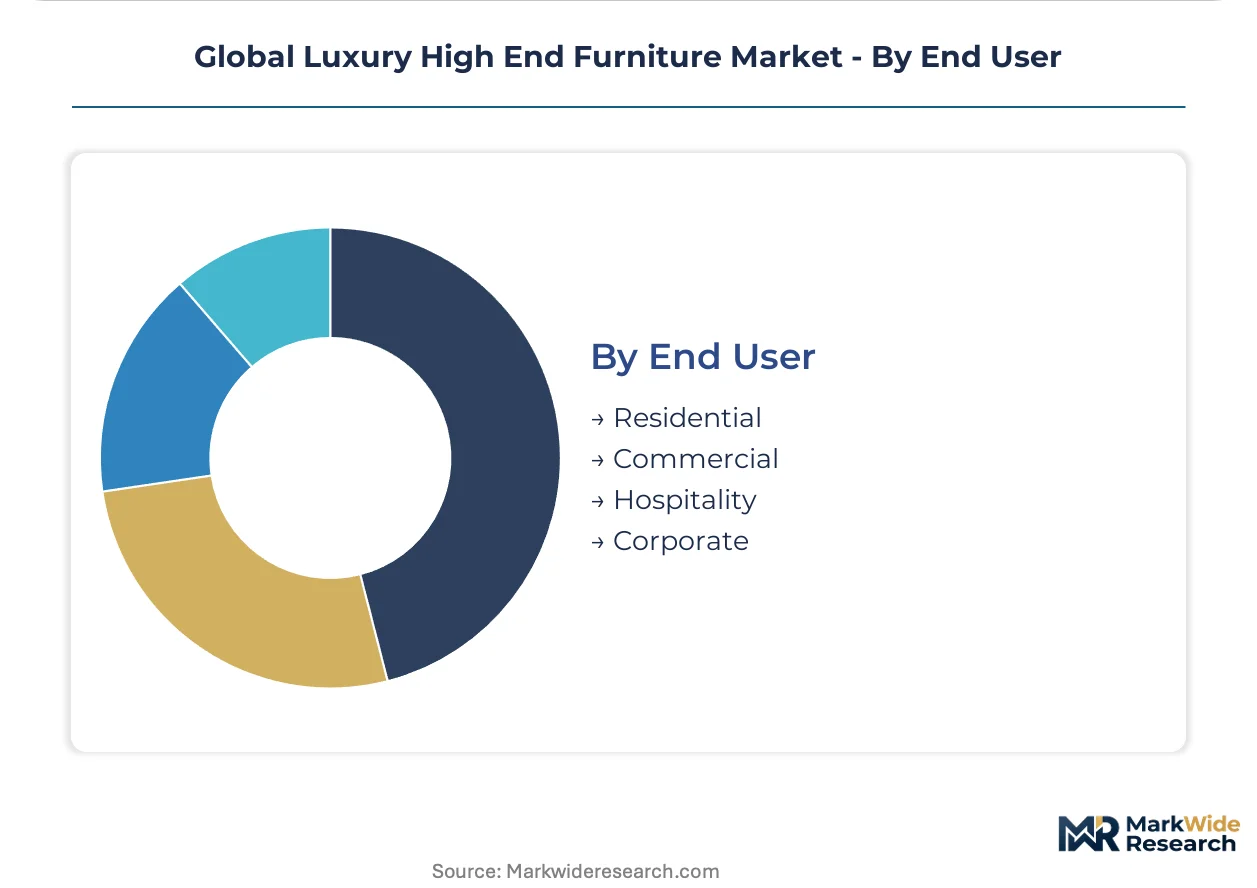
End User:
Application context determines specification durability requirements and aesthetic risk tolerance.
- Hospitality:Custom interior installations for luxury hotel chains and resort developments. Neom and Red Sea Development Authority commissions in Saudi Arabia represent unprecedented scale demand, with direct procurement from design studios displacing traditional wholesale intermediation among project developers.
- Residential:Ultra-high-net-worth individual procurement for primary and secondary estates. Dubai and Riyadh buyers increasingly commission entire interior collections through single-source atelier relationships, favoring consolidated accountability over multi-brand showroom coordination.
- Corporate:Executive office and boardroom furnishings with licensed designer collections.
- Commercial:High-end retail, restaurant, and public space installations.
Residential anchors the revenue base while hospitality expands most quickly in absolute dollar terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reveal Italy's persistent trade surplus in finished luxury furnishings against China's dominance in component substrates and the United States' deficit in premium upholstery. Demand concentration in Gulf Cooperation Council residential estates and European hospitality refurbishment creates divergent procurement patterns across three continents.
Italy
Ultra-high-net-worth residential buyers in Milan and Lake Como estates sustain demand for bespoke interior collections. EU ECHA REACH Annex XVII restrictions on chromium VI in leather tanning force reformulation of standard treatment protocols among Brianza cluster tanneries. The Brianza furniture manufacturing district north of Milan concentrates artisanal upholstery workshops with scaled export logistics serving Middle East hospitality commissions.
United States
Corporate headquarters relocation to Texas and Florida drives specification of executive seating systems with certified sustainable wood substrates. US EPA and California Air Resources Board joint enforcement of formaldehyde emission standards shapes composite wood sourcing decisions for manufacturers serving North American commercial clients. Direct-to-consumer gallery formats in New York and Los Angeles displace traditional wholesale intermediation among affluent residential buyers.
China
Domestic luxury hospitality development in Shanghai and Shenzhen accelerates procurement of imported Italian leather upholstery and solid hardwood furnishings. The country's national environmental regulator enforces dual carbon goals that constrain energy-intensive manufacturing processes in traditional furniture production zones. Pearl River Delta fabricators specialize in CNC-milled components for European and North American brands seeking cost-optimized joinery.
United Arab Emirates
Dubai's ultra-high-net-worth residential expansion concentrates demand for full-collection interior commissioning through single-source atelier relationships. MOHAP product safety standards govern chemical treatment disclosure requirements for imported furnishings entering the emirate. Dubai Design District hosts consolidated showrooms where direct procurement from European manufacturers displaces traditional multi-brand retail intermediation.
Saudi Arabia
Neom and Red Sea Development Authority hospitality commissions represent unprecedented scale demand for custom interior installations. SFDA chemical safety regulations align with EU REACH protocols for imported wood and leather substrates. Riyadh's emerging design district attracts direct atelier presences from Northern Italian manufacturers seeking consolidated accountability relationships with giga-project developers.
Global Luxury High End Furniture Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream on materials and craftsmanship. The vendor base stratifies between vertically integrated heritage houses with captive tannery and upholstery operations and asset-light design studios scaling through direct-to-consumer formats. Three archetypes dominate: vertically integrated Italian manufacturers controlling leather tanning and joinery, North American direct-to-consumer platforms with gallery-based distribution, and licensed designer collection houses serving corporate and hospitality segments. Competitive moves concentrate on backward integration into raw material supply and geographic expansion through flagship gallery openings in Gulf Cooperation Council markets.
Within the vertically integrated heritage tier, Poltrona Frau exemplifies captive supply chain control through in-house leather tanning and upholstery craftsmanship in Italy's Brianza cluster. Among North American platform operators, Restoration Hardware occupies a position defined by direct-to-consumer gallery formats that eliminate wholesale margin compression. At the licensed collection end, Herman Miller-Knoll represents the convergence of corporate and residential segment coverage through designer collaboration models. These three anchors illustrate divergent strategic postures on manufacturing ownership versus asset-light scaling.
| Leading Market Players |
|---|
| Restoration Hardware (RH) |
| Roche Bobois |
| Herman Miller-Knoll |
| Poltrona Frau |
| Luxury Living Group (Fendi Casa) |
| B&B Italia |
| Minotti |
| Natuzzi |
| Baker Furniture |
| Others |
Value Chain & Pricing Dynamics
Italy's Brianza furniture manufacturing district concentrates artisanal upholstery capacity that feeds pricing power downstream to heritage houses controlling in-house leather tanning. Northern Italian tannery bottlenecks during peak hospitality commissioning cycles translate directly into margin expansion for vertically integrated manufacturers serving Middle East giga-projects.
Pricing Analysis
Ultra-high-net-worth residential buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade—FSC chain-of-custody documentation commands substantial premiums—and customization depth for bespoke interior collections. Cost compression in standard-tier upholstery is intensifying because ECHA REACH Annex XVII testing requirements elevate per-unit qualification expenses. Hospitality procurement teams exhibit lowest price sensitivity, while corporate facilities managers face tightening budget constraints on certified sustainable wood substrates.
Supply Chain Analysis
Full-grain hides from Northern Italian tanneries, solid hardwoods from certified European forests, and CNC-milled components from China's Pearl River Delta feed finished goods assembly. Raw material dependencies center on vegetable-tanned leather substrates, FSC-certified oak and walnut, and precision-engineered suspension hardware. Single-source vulnerability concentrates in Brianza's aging artisan workforce, where master craftsman succession gaps threaten quality-conservative scaling. Distribution runs through direct-to-consumer gallery formats in Dubai Design District and Riyadh's emerging design district, displacing traditional multi-brand retail intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct procurement platforms are collapsing traditional wholesale intermediation, creating platform-economics inflection as design studios capture buyer relationships previously held by multi-brand showrooms. Interoperability between parametric design software and robotic milling workflows accelerates bespoke commissioning cycles.
For Market Incumbents: Build captive tannery capacity moats through backward integration into vegetable-tanning protocols that satisfy ECHA REACH Annex XVII chromium VI restrictions. Acquire distressed artisan workshops in Italy's Brianza cluster to preempt competitor access to scarce hand-finishing labor pools. Consolidate accountability relationships with Saudi giga-project developers before asset-light design studios establish single-source atelier presences.
For New Entrants and Emerging Players: Saudi Arabia's Neom and Red Sea Development Authority hospitality commissions represent underpenetrated white-space at unprecedented scale. Target corporate headquarters relocation clusters in Texas and Florida with certified sustainable executive seating systems. Deploy direct-to-consumer gallery formats that eliminate wholesale margin compression and enable dynamic pricing control against heritage house markups.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated heritage houses with captive leather tanning and established Brianza manufacturing footprints. Long-term viability hinges on succession planning for master craftsman knowledge transfer as Italy's artisan workforce ages. Watch digital fabrication convergence—CNC routing paired with traditional hand-finishing—as the inflection signal separating scalable ateliers from capacity-constrained competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tannery Operations | ECHA REACH Annex XVII compliance secures European market access for upholstery substrates. |
| Direct-to-Consumer Gallery Expansion | Dubai Design District and Riyadh flagships displace wholesale intermediation among ultra-high-net-worth buyers. |
| Digital Fabrication Convergence | Parametric design software with robotic milling collapses bespoke commissioning cycles from eighteen to nine months. |
| Certified Sustainable Supply Chain Restructuring | FSC and PEFC chain-of-custody documentation satisfies EU Green Deal timber certification mandates. |
| Artisan Workforce Succession Programs | Knowledge transfer protocols address master craftsman retirement curves in Italy's Brianza cluster. |
Study Parameters
The analysis maps bespoke residential collections, hospitality custom installations, and corporate licensed designer segments, each validated through primary interviews with furniture atelier directors, hospitality procurement executives, and corporate facilities managers. Secondary sources include EU ECHA regulatory filings, FSC and PEFC chain-of-custody databases, and customs trade records for finished furniture imports. Bottom-up demand modeling from end-user specification patterns triangulates against top-down supply capacity assessments across Italy's Brianza cluster and China's Pearl River Delta fabricators.
Forecasts assume stable regulatory enforcement intensity across the analysis window, with segmentation dimensions spanning product type, material substrate, style category, and end-user application. CAGRs derive from fitted growth curves applied to disclosed commissioning volumes at Saudi giga-projects and Dubai residential developments. Industry-specific inputs include artisan labor availability indices and tannery capacity utilization rates from Northern Italian suppliers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by asset-light design studios or technology-enabled direct-to-consumer platforms would shift outcomes substantially. Cross-checking against hospitality pipeline databases and ultra-high-net-worth residential construction permits is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Europe Electric Forklift Market
Others
Electric Chainsaw Market
Others
Ultrasonic Flow Meter Market
Others
Asia-Pacific 3D Printing Construction Market
Others
Aerospace Tester Market
Others
Exosome Technologies Market
Others
Infant Fever Stickers Market
Others
Asia Pacific Contract Packaging Market
Others
South Korea Smart Home Market
Others
Global Military and Aerospace Sensors Market
Others
Global Digital Caliper Market
Others
Printing Machines Market
Others
North America Compressor Oil Market
Others
HPHT Diamond Cubic Press Market
Others
Europe Flow Battery Market
Others
Global Multi-Access Edge Computing Market