
 Metal Air Battery Market | 2026-2036
Metal Air Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Air Battery Market Intelligence
Electric vehicle deployment is restructuring the buyer landscape for metal air batteries as vehicle assemblers seek higher energy density alternatives. Phinergy anchors its position through aluminum-air technology leadership in automotive applications. Log 9 Materials dominates Indian electric mobility with zinc-air innovations for two-wheelers and commercial fleets. Duracell sustains consumer electronics channel control through established retail distribution for hearing aid zinc-air cells.
Metal air batteries generate electricity through electrochemical oxidation of metallic anodes—typically zinc, aluminum, or lithium—paired with ambient oxygen reduction at the cathode, achieving theoretical energy densities exceeding 1,000 Wh/kg depending on metal selection. Solid electrolyte configurations command premium positioning due to enhanced safety profiles and cycle stability versus liquid counterparts. Zinc-air technology occupies the most mature segment with established hearing aid and remote monitoring applications, while lithium-air systems represent the fastest-growing category driven by aerospace and long-range electric vehicle research programs. Grid storage applications concentrate margin pools through utility-scale procurement contracts requiring decade-long operational warranties.
The US Department of Energy and EPA shape domestic demand through clean energy storage incentives and emissions reduction benchmarks for federal procurement. REACH and the EU Green Deal mandate substance transparency and carbon footprint disclosure across European battery supply chains, directly affecting market access for non-compliant manufacturers. China's MIIT enforces GB standards for electrochemical safety and recycling protocols that constrain import eligibility. Stakeholders must monitor evolving electrolyte chemistry regulations and build certification roadmaps before scaling production commitments.
Market Dynamics
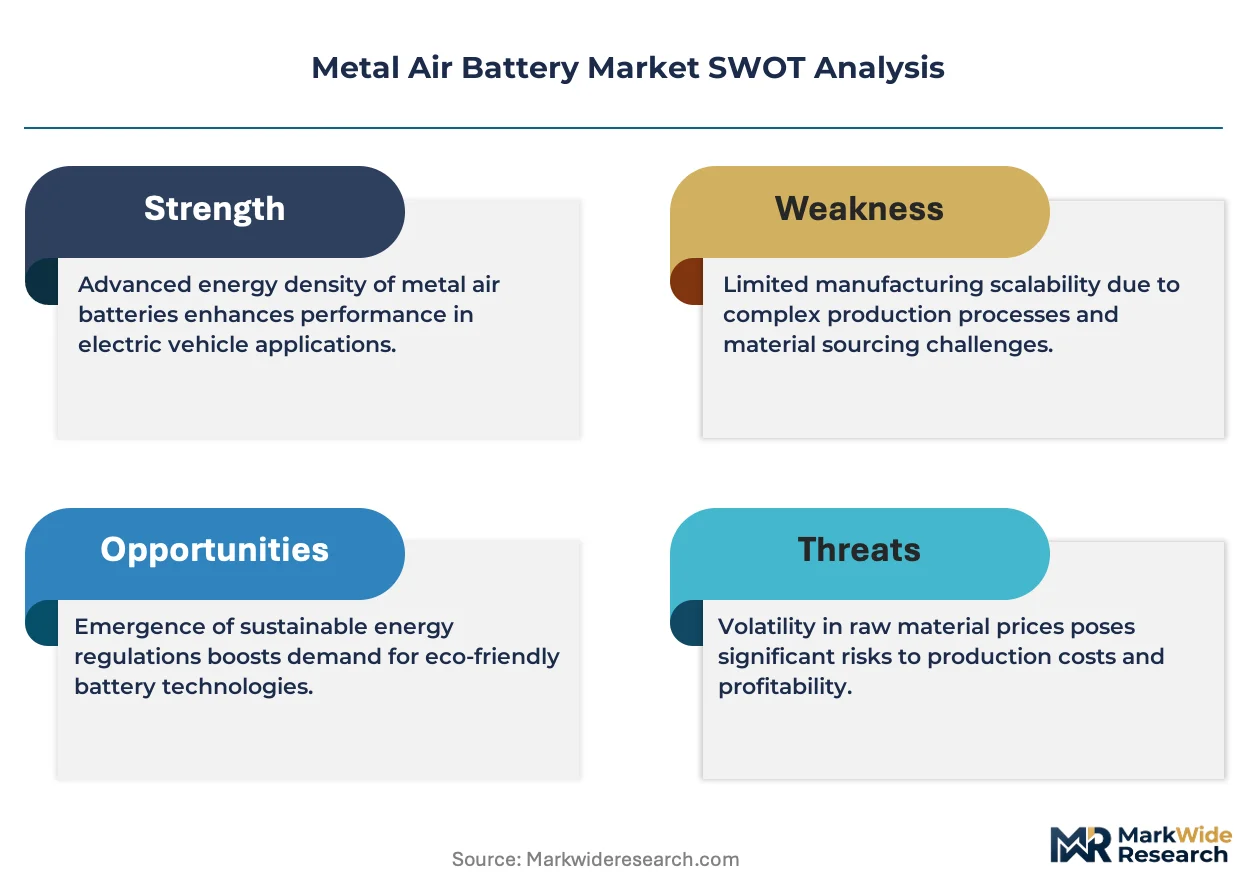
Electric vehicle manufacturers are accelerating aluminum-air and zinc-air procurement as carbon neutrality mandates compress lithium-ion supply timelines and force energy density upgrades across automotive platforms.
Growth Catalysts
- EU Green Deal carbon footprint disclosure:Battery supply chain transparency mandates are forcing OEMs to source metal-air alternatives with cleaner production profiles, redirecting procurement toward aluminum-air systems.
- China's dual carbon goals:MIIT enforcement of GB standards for electrochemical safety is channeling state-backed R&D funding into domestic zinc-air pilot manufacturing for grid storage.
- Aerospace long-range propulsion:Lithium-air theoretical density advantages are attracting defense and commercial aviation research contracts for unmanned aerial systems requiring extended endurance.
Market Restraints
- Electrolyte material cost volatility:Solid-state electrolyte precursor supply concentrates in East Asian chemical processors, exposing cell manufacturers to ionic liquid price swings.
- Cycle stability technical ceiling:Aluminum-air systems face irreversible anode corrosion limiting rechargeability, constraining deployment to primary-cell applications despite energy density advantages.
- REACH substance registration friction:European chemical compliance timelines delay new electrolyte formulations from reaching commercial scale, favoring incumbent zinc-air chemistry.
Strategic Opportunities
- India electric two-wheeler penetration:Zinc-air retrofit kits for existing lithium-ion fleets offer a cost-accessible bridge technology in price-sensitive urban mobility markets.
- US IRA clean energy storage incentives:Tax credits for domestic battery manufacturing are attracting aluminum-air pilot lines to leverage federal procurement benchmarks for grid-scale deployments.
- Solid-liquid hybrid electrolyte convergence:Combining polymer stability with liquid ionic conductivity is opening patent white space for next-generation cell architectures.
Industry Challenges
- Electrochemist talent scarcity:Metal-air specific expertise in oxygen reduction catalysis and anode passivation remains concentrated in national laboratory and elite university programs, constraining hiring pipelines.
- Decade-long warranty certification:Utility-scale procurement contracts require operational validation periods that exceed current aluminum-air field test histories, compressing competitive entry timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Air Battery Market |
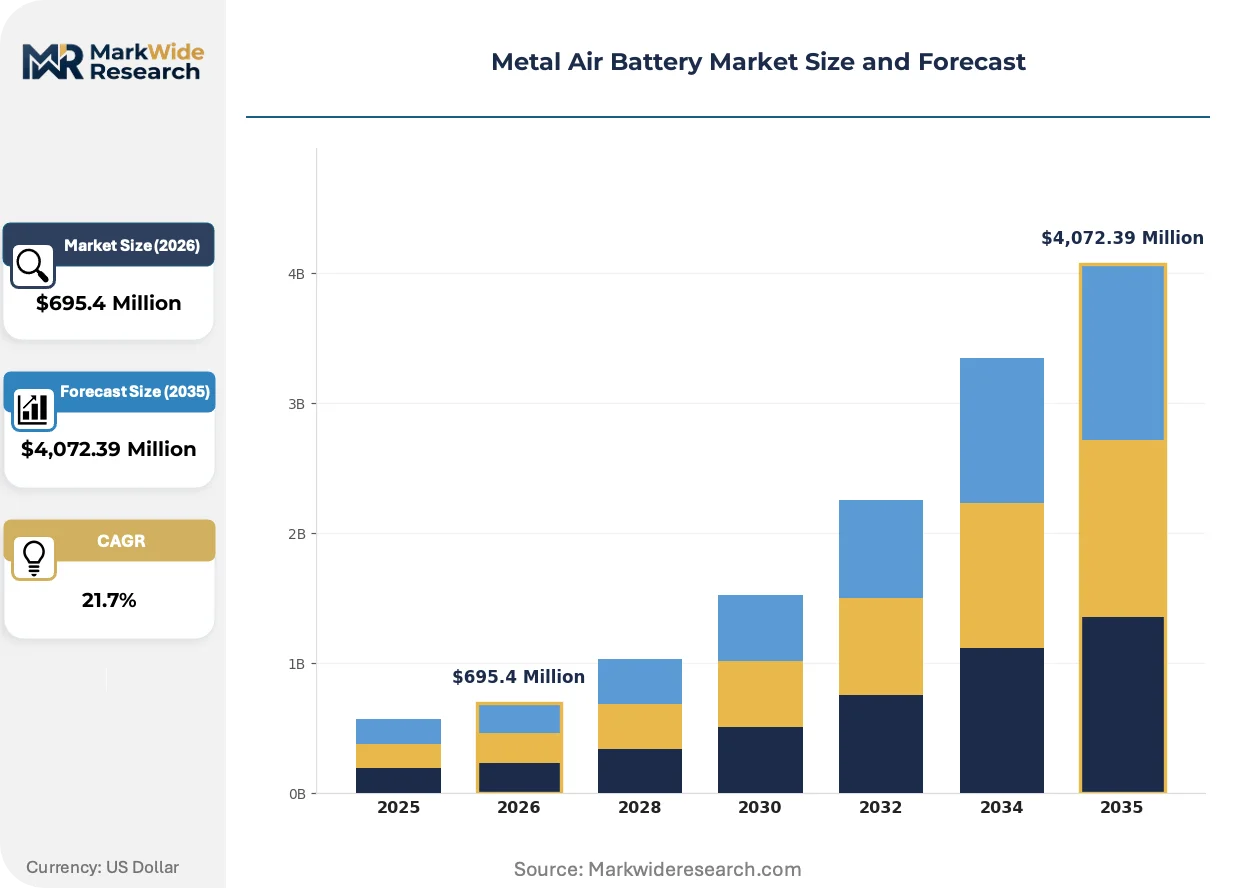
| Market Size in 2026 | $695.4 Million |
| Market Size in 2035 | $4,072.39 Million |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Zinc Air, Lithium Air, Aluminum Air, Magnesium Air, Sodium Air Technology: Solid Electrolyte, Liquid Electrolyte, Gel Electrolyte, Hybrid Electrolyte Application: Consumer Electronics, Electric Vehicles, Grid Storage, Military Equipment, Wearables End User: Electronics Manufacturers, Vehicle Assemblers, Energy Providers, Defense Contractors |
| Companies Covered | Duracell, Phinergy, GP Batteries International, Log 9 Materials, NantEnergy, Arotech Corporation, Renata SA, E-stone, Energizer Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Air Battery Market Strategic Shifts & Innovations
Automation of cell assembly and diagnostic testing is compressing development cycles while regulatory pressure on supply chain transparency accelerates chemistry disclosure requirements across jurisdictions.
Solid electrolyte deposition systems are automating layer-by-layer manufacturing precision previously requiring manual cleanroom intervention. Automotive tier-one suppliers are adopting these platforms for pilot aluminum-air prototyping, reducing defect rates and compressing time-to-validation for OEM qualification programs. This automation is automating the transition from laboratory bench to scalable production, eroding the historical advantage of liquid-electrolyte incumbents in manufacturing yield.
REACH substance transparency mandates and the EU Green Deal carbon footprint disclosure framework are compelling battery manufacturers to document full lifecycle emissions from mine to cell. European OEMs now require supplier certification through ECHA-registered databases, disqualifying non-compliant Asian producers from premium procurement tiers. Grid storage integrators in Germany and the Netherlands are responding by demanding aluminum-air systems with verified low-carbon aluminum smelting sourcing.
Utility procurement teams are consolidating supplier relationships around integrated cell-plus-management-system offerings rather than commoditized cell-only contracts. This bundling preference disadvantages pure-play chemistry developers lacking power electronics capabilities, favoring diversified energy storage conglomerates. The shift is most pronounced in South Korean and Japanese utility markets where long-term operational risk transfer to suppliers is standard contracting practice.
Metal Air Battery Market Segmentation
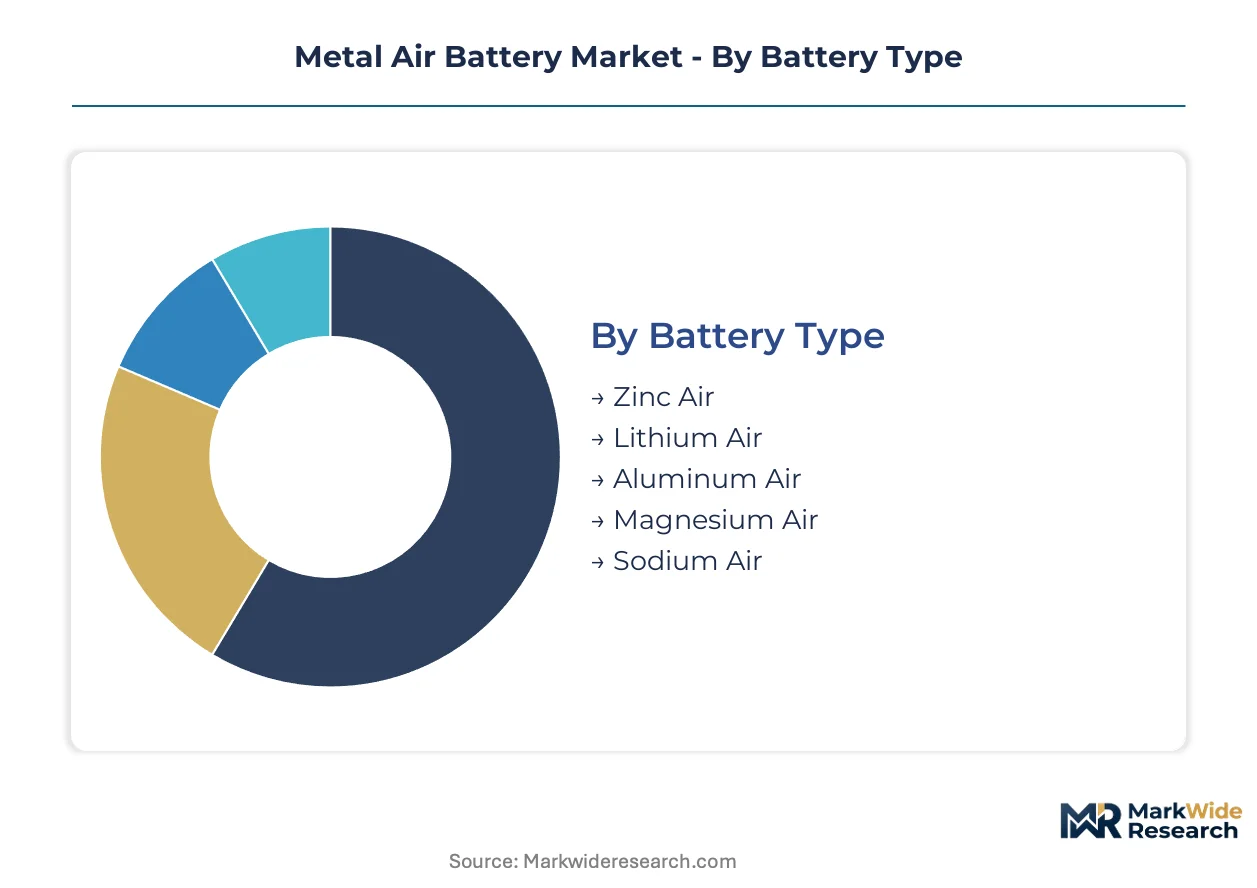
Metal air battery deployment varies sharply across chemistry, electrolyte architecture, and end-use application, with each segment carrying distinct certification requirements and supply chain configurations. Procurement patterns diverge significantly between hearing aid zinc-air cells requiring simple CE marking and automotive aluminum-air systems facing MIIT GB standard compliance and EPA emissions benchmarking.
Battery Type:
Certification burdens concentrate in automotive and aerospace segments where aluminum-air and lithium-air systems face MIIT electrochemical safety protocols, EPA clean energy procurement benchmarks, and EU Green Deal carbon footprint disclosure mandates. Zinc-air hearing aid cells navigate lighter REACH substance registration requirements.
- Zinc Air:The most mature chemistry employs aqueous alkaline electrolytes with ambient oxygen reduction at porous carbon cathodes. Demand concentrates in hearing aid and remote patient monitoring devices across Germany and Japan where ISO 13485 medical device certification dominates procurement. REACH substance registration friction favors incumbent chemistry with established ECHA-registered supply chains.
- Lithium Air:Theoretical energy density exceeding 3,000 Wh/kg drives aerospace and long-range electric vehicle research programs. Defense contractors in the US and commercial aviation developers in France pursue unmanned aerial system contracts requiring FAA airworthiness validation alongside EPA emissions reduction benchmarks for federal procurement eligibility.
- Aluminum Air:Primary-cell architecture with irreversible anode corrosion limits applications to range-extender packs for commercial fleets. Indian electric mobility developers and German automotive tier-one suppliers pilot systems under BIS certification and KBA automotive safety protocols.
- Magnesium Air:Emerging seawater-activated chemistry targets marine signaling and underwater vehicle applications. Japanese METI-funded research programs and South Korean naval procurement drive limited commercialization.
- Sodium Air:Low-cost metal abundance attracts grid storage research despite moisture sensitivity challenges. China's MIIT state-backed R&D funding channels pilot manufacturing for domestic utility-scale deployments under GB standard compliance.
Leading the category by volume: Zinc Air. Growing fastest: Lithium Air.
Technology:
Electrolyte selection determines manufacturing cost tier and end-use accessibility, with solid-state configurations commanding premium positioning for automotive safety requirements while liquid systems dominate price-sensitive consumer electronics.
- Solid Electrolyte:Polymer-ceramic composites eliminate flammability risks and enable thin-film cell geometries. Automotive OEMs in South Korea and Japan specify solid electrolyte aluminum-air systems for electric vehicle range extenders requiring decade-long operational warranties and METI safety certification.
- Liquid Electrolyte:Aqueous alkaline or ionic liquid formulations deliver highest ionic conductivity at lowest material cost. Zinc-air hearing aid and consumer electronics manufacturers in Germany leverage established supply chains with REACH-compliant ECHA-registered precursor sourcing.
- Gel Electrolyte:Semi-solid polymer matrices balance conductivity with mechanical stability for wearable applications. Electronics manufacturers in Japan integrate gel-electrolyte zinc-air cells into medical monitoring patches requiring JIS standard biocompatibility certification.
- Hybrid Electrolyte:Solid-liquid composite architectures combine polymer mechanical stability with liquid ionic transport. Patent white space in hybrid configurations attracts US-based startups targeting IRA clean energy storage incentives for grid-scale aluminum-air deployments.
Highest margin capture: Solid Electrolyte. Widest deployment: Liquid Electrolyte.
Application:
Application segmentation tracks directly to warranty duration requirements and operational environment severity, with military and grid storage demanding decade-plus validation periods that exceed current aluminum-air field test histories.
- Consumer Electronics:Hearing aids, wireless earbuds, and remote sensors dominate zinc-air consumption. Electronics manufacturers in Germany and Japan specify cells with verified low-carbon supply chains to satisfy EU Green Deal procurement mandates and METI efficiency benchmarks.
- Electric Vehicles:Range-extender packs and emergency reserve systems employ aluminum-air primary cells. Vehicle assemblers in India retrofit zinc-air kits onto existing lithium-ion two-wheeler fleets under BIS electrochemical safety protocols while German OEMs pilot aluminum-air integration with KBA homologation requirements.
- Grid Storage:Utility-scale procurement contracts require integrated cell-plus-management-system offerings with decade-long warranties. Energy providers in South Korea and Japan consolidate supplier relationships around conglomerates capable of operational risk transfer under standard contracting practice.
- Military Equipment:Extended endurance requirements for unmanned aerial systems drive lithium-air defense research. US defense contractors pursue FAA airworthiness certification alongside EPA federal procurement emissions benchmarks for next-generation propulsion systems.
- Wearables:Thin-film zinc-air cells power medical monitoring and fitness tracking devices. Electronics manufacturers specify gel electrolyte configurations with ISO 13485 medical device quality management and JIS biocompatibility validation.
Largest addressable market: Consumer Electronics. Steepest expansion trajectory: Electric Vehicles.
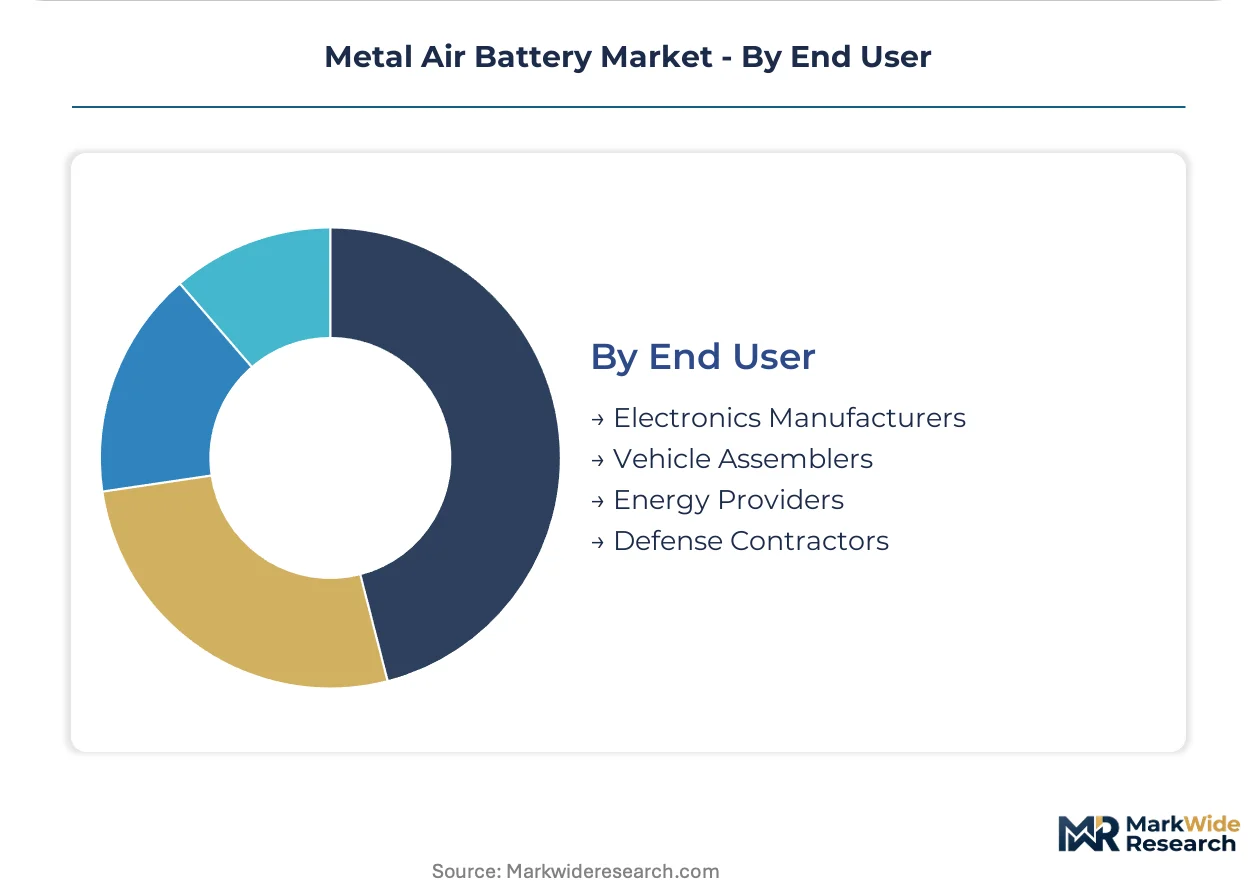
End User:
End user segmentation reveals procurement capability divergence, with energy providers and defense contractors demanding integrated system offerings while electronics manufacturers source commoditized cells through established distribution channels.
- Electronics Manufacturers:Hearing aid and wearable device assemblers specify zinc-air cells through retail and medical distribution networks. German and Japanese electronics manufacturers enforce ECHA-registered supply chain transparency and METI efficiency benchmarking across procurement tiers.
- Vehicle Assemblers:Electric mobility platforms seek aluminum-air range extenders and zinc-air retrofit solutions. Indian two-wheeler manufacturers and German automotive tier-one suppliers navigate divergent certification requirements under BIS, KBA, and MIIT GB standards.
- Energy Providers:Utility-scale storage procurement concentrates in South Korea and Japan where integrated cell-plus-management-system contracts transfer operational risk to suppliers. German and Dutch grid integrators demand verified low-carbon aluminum smelting sourcing under EU Green Deal frameworks.
- Defense Contractors:Aerospace and unmanned systems developers pursue lithium-air research contracts with extended endurance specifications. US defense procurement channels EPA federal emissions benchmarks and FAA airworthiness requirements into technology selection criteria.
Most fragmented procurement: Electronics Manufacturers. Most consolidated contracting: Energy Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China and India's industrial corridors concentrate metal-air battery pilot manufacturing, while Germany's automotive clusters and US federal procurement zones anchor Western demand concentration.
China
MIIT state-backed R&D funding channels domestic zinc-air pilot manufacturing for grid storage under GB standard compliance. The Yangtze River Delta hosts electrochemical safety testing facilities serving aluminum-air developers seeking MIIT certification for automotive range extenders.
Germany
KBA automotive safety protocols and EU Green Deal carbon footprint disclosure mandate cleaner aluminum smelting sourcing for battery supply chains. Bavaria's industrial clusters support advanced prototyping of solid-electrolyte systems for electric vehicle integration programs.
India
BIS electrochemical safety certification governs zinc-air retrofit kits for two-wheeler fleets in price-sensitive urban mobility markets. Log 9 Materials anchors domestic electric mobility innovation from Bengaluru's technology corridor.
United States
IRA clean energy storage incentives attract aluminum-air pilot lines seeking federal procurement eligibility under EPA emissions benchmarks. Defense contractors pursue FAA airworthiness certification for lithium-air unmanned aerial systems in aerospace research zones.
Japan
METI safety certification and decade-long operational warranty requirements shape utility-scale procurement for integrated cell-plus-management-system offerings. South Korean and Japanese energy providers consolidate supplier relationships around conglomerates capable of operational risk transfer.
Metal Air Battery Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with hearing aid zinc-air cells consolidating around established consumer electronics channels while automotive aluminum-air systems fragment across national laboratory spinouts and tier-one supplier partnerships. Three archetypes dominate: chemistry-focused developers advancing specific metal-air configurations, diversified energy storage conglomerates bundling power electronics capabilities, and medical device specialists controlling retail distribution for primary-cell applications. Competitive moves concentrate on strategic partnerships with automotive OEMs for pilot qualification programs and backward integration into electrolyte precursor supply to secure REACH-compliant sourcing.
Within the chemistry-focused tier, Phinergy and Log 9 Materials exemplify divergent geographic and application specializations. Phinergy represents Israeli-developed aluminum-air technology leadership targeting automotive range-extender markets, while Log 9 Materials occupies a position as an Indian private limited company concentrating on zinc-air innovations for domestic electric two-wheeler and commercial fleet segments. Duracell anchors the consumer electronics channel archetype through established retail distribution networks for hearing aid zinc-air cells.
| Leading Market Players |
|---|
| Duracell |
| Phinergy |
| GP Batteries International |
| Log 9 Materials |
| NantEnergy |
| Arotech Corporation |
| Renata SA |
| E-stone |
| Energizer Holdings |
| Others |
Cost & Logistics Intelligence
Solid electrolyte deposition automation simultaneously compresses manufacturing defect rates and concentrates production capability among automotive tier-one suppliers with capital access for pilot prototyping platforms. This technology shift redistributes pricing power toward integrated cell-plus-management-system providers while squeezing pure-play chemistry developers lacking power electronics bundling capabilities.
Pricing Analysis
Lead-time-driven pricing stratification separates premium contracts for automotive OEM qualification programs from discounted spot inventory for hearing aid zinc-air commodity cells. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—MIIT GB standard compliance and METI safety certification command substantial premiums over basic CE marking. Cost compression in liquid-electrolyte zinc-air hearing aid cells is intensifying because REACH-compliant ECHA-registered precursor sourcing constrains supply elasticity. Electronics manufacturers in Germany exhibit highest price sensitivity due to margin pressure in retail distribution, while South Korean utility-scale energy providers demonstrate lowest sensitivity given operational risk transfer requirements.
Supply Chain Analysis
Electrochemist talent scarcity in oxygen reduction catalysis and anode passivation concentrates manufacturing gravity in Germany, Japan, and South Korea where national laboratory and elite university programs feed hiring pipelines. Raw material dependencies center on East Asian ionic liquid precursor processors, low-carbon aluminum smelting operations in Norway and Iceland, and porous carbon cathode suppliers in Japan. Single-source vulnerability in solid-state electrolyte precursor supply exposes cell manufacturers to price volatility and qualification delays. Distribution runs through integrated conglomerate channels for utility-scale deployments and established retail networks for consumer electronics applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into electrolyte precursor supply and forward integration into power electronics bundling defines competitive positioning in this market. Players are racing to secure REACH-compliant sourcing and decade-long warranty certification capabilities before scaling production commitments.
For Market Incumbents: Acquire oxygen reduction catalysis expertise through targeted hiring from national laboratory programs and university electrochemistry departments. Consolidate supplier relationships around ECHA-registered databases to defend against European OEM procurement disqualification. Capacity addition in Bavaria's industrial clusters and South Korean automotive corridors reinforces geographic proximity to qualification programs. For New Entrants and Emerging Players: Capture hybrid electrolyte patent white space combining polymer stability with liquid ionic conductivity for grid-scale aluminum-air deployments. India's electric two-wheeler retrofit market offers the most penetrable geography given price-sensitive urban mobility demand and lighter BIS certification burdens. Direct OEM partnership models bypass established distribution channel control by Duracell and Energizer Holdings in hearing aid segments. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified energy storage conglomerates seeking cell-plus-management-system bundling capabilities. Long-term viability hinges on successful navigation of decade-long utility warranty validation periods that exceed current aluminum-air field test histories. Monitor MIIT GB standard enforcement timelines and EPA federal procurement benchmark revisions as inflection indicators for domestic manufacturing investment decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrolyte Precursors | REACH-compliant ECHA-registered sourcing secures European OEM procurement eligibility under EU Green Deal mandates. |
| Power Electronics Capability Buildout | Integrated cell-plus-management-system offerings satisfy South Korean and Japanese utility operational risk transfer requirements. |
| Solid Electrolyte Deposition Automation | Automated layer-by-layer manufacturing precision reduces defect rates for automotive tier-one supplier qualification programs. |
| Low-Carbon Aluminum Smelting Partnerships | Verified sourcing from Norway and Iceland operations satisfies German and Dutch grid integrator carbon footprint disclosure requirements. |
| National Laboratory Talent Acquisition | Oxygen reduction catalysis expertise from elite university programs addresses electrochemist hiring pipeline constraints. |
Research Approach
Independent corroboration across primary interviews with electrochemistry R&D directors, automotive tier-one supplier procurement leads, utility-scale energy provider planning officers, and medical device regulatory affairs specialists underwrites the qualitative findings. Secondary validation draws from MIIT GB standard filings, EPA clean energy procurement benchmark disclosures, ECHA-registered substance databases, and METI safety certification records. Bottom-up cell shipment modeling and top-down energy storage investment flow analysis triangulate volume and value estimates.
Rate-of-change decomposition across chemistry type, electrolyte architecture, application severity, and end-user procurement capability dimensions structures the analytical framework. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion across the analysis window. Forecast inputs incorporate aluminum-air range-extender pilot program timelines, lithium-air aerospace research contract awards, and zinc-air hearing aid replacement cycle frequencies.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to electrolyte material cost volatility, cycle stability technical breakthroughs, and REACH substance registration timeline revisions. Material deviation in MIIT enforcement intensity or IRA clean energy storage incentive renewal warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Rotary Union Market
Others
Europe Transportation Management Systems Market
Others
Managed Testing Services Market
Others
Vegetable Carbon Market
Others
Pet Care Packaging Market
Others
Asia-Pacific IVD Regulatory Affairs Outsourcing Market
Others
Africa Cotton Market
Others
Global Tobacco Market
Others
Printing Machines Market
Others
Mobile Computing Devices Market
Others
Asia Pacific Cloud Infrastructure Testing Services Market
Others
Performance Testing Tools Market
Others
Post Consumer Recycled Bottles Market
Others
Quadrant Scale Market
Others
Deflectometer Market
Others
Electric Chainsaw Market