
 Industrial Air Pollution Control Solutions Market | 2026-2036
Industrial Air Pollution Control Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Air Pollution Control Solutions Market Foresight
The EU Green Deal's industrial emissions directive is recalibrating capital allocation across European process industries. Mitsubishi Heavy Industries leverages its electrostatic precipitator heritage to dominate utility-scale installations in East Asia. Thermax Ltd anchors its position through captive engineering services tied to scrubber deployments across Indian cement and steel complexes. CECO Environmental differentiates via wet scrubbing specialization for chemical processing clients requiring acid gas removal.
Industrial air pollution control solutions encompass engineered systems designed to capture, neutralize, or destroy airborne contaminants before stack release, typically operating at gas temperatures between 120°C and 350°C with pressure drops measured in kilopascals. These installations serve primarily to ensure regulatory compliance while protecting downstream equipment and neighboring communities from hazardous emissions. Electrostatic precipitators command the largest installed base among product types due to decades of power sector reliance, though wet scrubbing technology is gaining fastest in chemical processing applications where multi-pollutant removal justifies higher capital outlays. Filters occupy mature positions in mining and manufacturing dust collection, while biofiltration remains niche but carries superior margins in food and pharmaceutical odor control.
The EPA enforces Maximum Achievable Control Technology standards under the Clean Air Act, compelling US manufacturers to upgrade legacy systems or face operational penalties. China's MEE implements GB emission standards that tighten particulate limits annually, forcing domestic producers toward higher-efficiency precipitators and hybrid scrubber configurations. India's CPCB mandates continuous emission monitoring systems across seventeen critically polluted industrial clusters, creating persistent retrofit demand. Stakeholders must weigh technology migration timelines against the risk of stranded assets as regulatory baselines shift upward.
Market Dynamics
Hybrid wet-dry scrubbing architectures are forcing capital reallocation across heavy process industries as multi-pollutant capture requirements harden under tightening emission ceilings.
Growth Catalysts
- GB Standard Tightening:China's MEE annual particulate limit reductions force domestic producers toward higher-efficiency precipitator retrofits and combined scrubber configurations.
- Cement Sector Mandates:India's Central Pollution Control Board scrubber installation directives create persistent equipment demand across seventeen critically polluted industrial clusters.
- Electrostatic Precipitator Modernization:Utility-scale power generators replace aging plate-wire configurations with advanced pulse-energized systems to meet stack opacity requirements.
Market Restraints
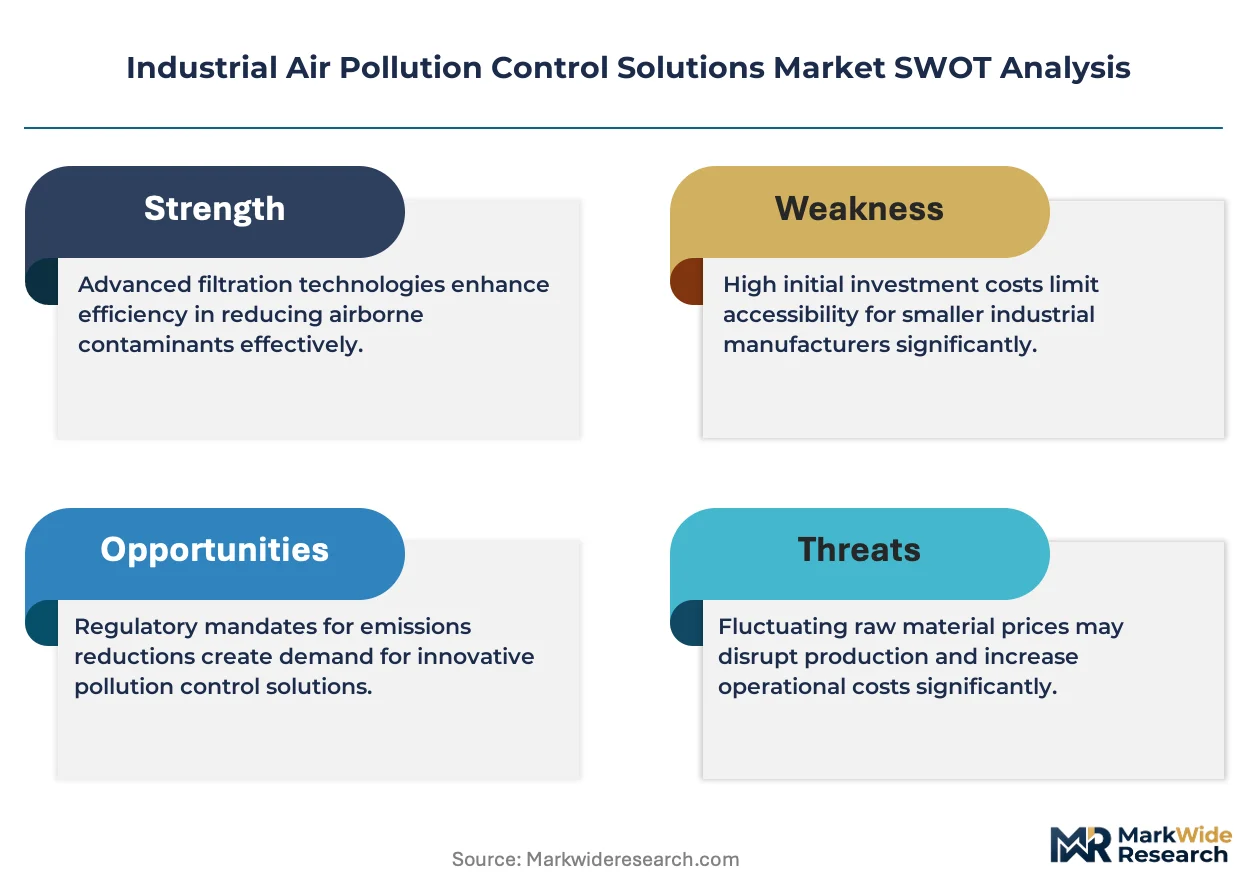
- Specialty Alloy Input Volatility:Hastelloy and titanium demand from chemical processing scrubber fabrication exposes fabricators to nickel and molybdenum price swings.
- High-Purity Limestone Supply Concentration:Wet flue gas desulfurization reagent sourcing clusters in select mining districts, creating geographic vulnerability for scrubber operators.
- Retrofit Downtime Constraints:Continuous process industries face production loss risks during legacy system replacement, compressing installation windows.
Strategic Opportunities
- Carbon Capture Integration:Amine-based post-combustion capture retrofits onto existing scrubber infrastructure open equipment bundling prospects for cement and steel producers.
- Continuous Emission Monitoring Mandates:India's CPCB CEMS requirements across seventeen clusters create recurring instrumentation and service contract demand.
- Modular Skid Delivery:Pre-assembled scrubber packages reduce field construction timelines for remote mining and petrochemical sites lacking skilled local labor pools.
Industry Challenges
- Corrosion Engineering Talent Scarcity:Wet acid gas scrubber design requires specialized materials expertise that outpaces vocational training program output.
- Legacy Control System Integration:Digital retrofit of 1980s-vintage precipitator power supplies with modern PLC architectures creates commissioning complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Air Pollution Control Solutions Market |
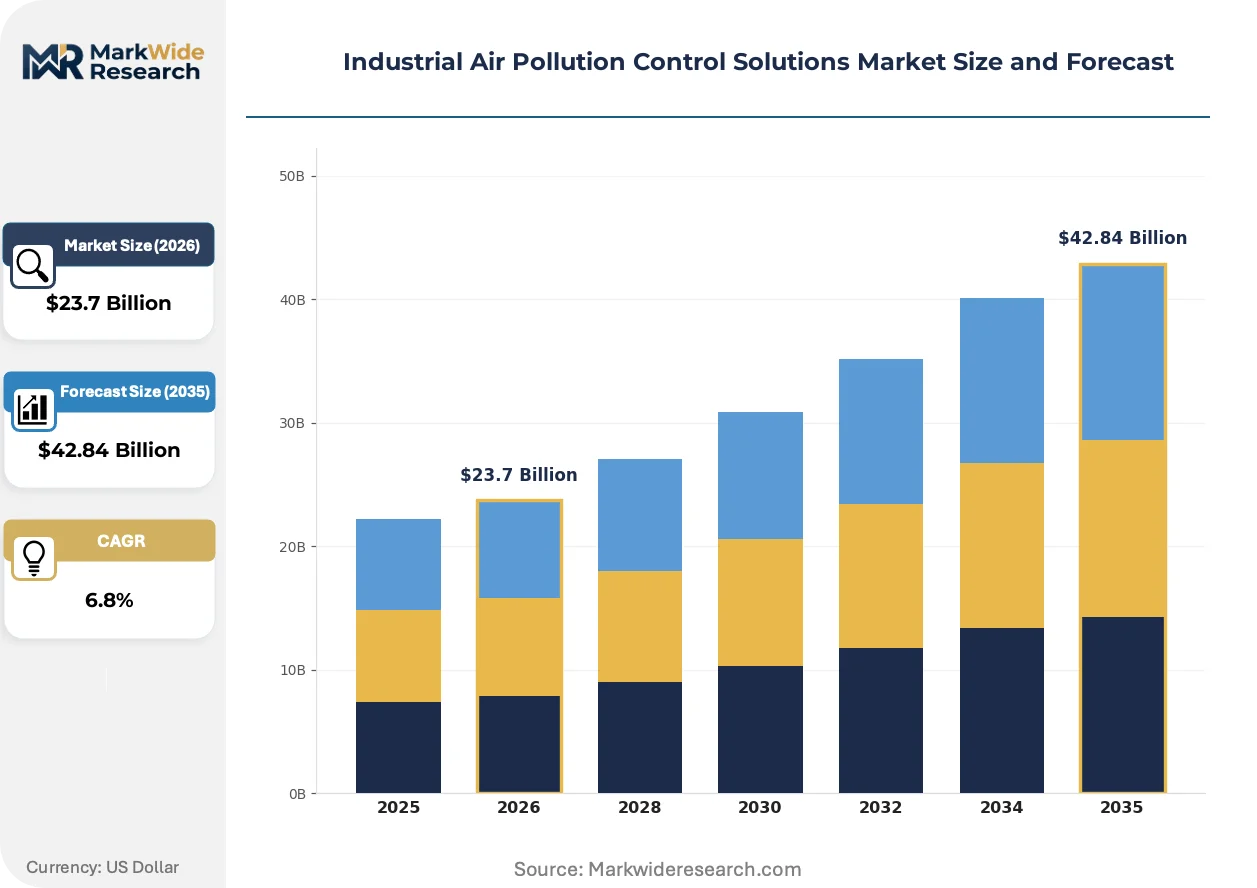
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scrubbers, Filters, Electrostatic Precipitators, Catalytic Converters Application: Power Generation, Manufacturing, Waste Incineration, Chemical Processing End User: Utilities, Construction, Mining, Aerospace Technology: Wet Scrubbing, Dry Scrubbing, Adsorption, Biofiltration |
| Companies Covered | Mitsubishi Heavy Industries, Thermax Ltd, Babcock & Wilcox Enterprises, General Electric Company, Fujian Longking Co. Ltd., CECO Environmental, Donaldson Company Inc., AAF International, Dürr Systems AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Air Pollution Control Solutions Market Shifts & Advancements
Process intensification and digital instrumentation are compressing equipment footprints while expanding real-time optimization capabilities across emission control installations.
Condensing wet electrostatic precipitators are overtaking conventional dry configurations in chemical processing applications where sub-micron particulate and acid mist co-capture justifies higher capital outlays. Refinery and petrochemical operators in the US Gulf Coast corridor are retrofitting existing stacks with tube-bundle designs. This architecture is overtaking plate-type alternatives by eliminating re-entrainment losses in saturated gas streams.
The EU Green Deal's industrial emissions directive recalibrates Best Available Technique reference documents across cement, lime, and minerals processing. Large combustion plant operators face tightened mercury and ammonia slip requirements. German and Polish power generators are accelerating selective catalytic reduction catalyst replacement cycles to maintain deNOx performance.
Performance-based service contracting is displacing traditional equipment sale models among capital-constrained industrial buyers. Engineering firms now guarantee emission compliance outcomes through multi-year operating agreements. This shift concentrates most visibly in Indian cement and steel complexes where project finance constraints favor operational expenditure structures over upfront capital deployment.
Industrial Air Pollution Control Solutions Market Segmentation
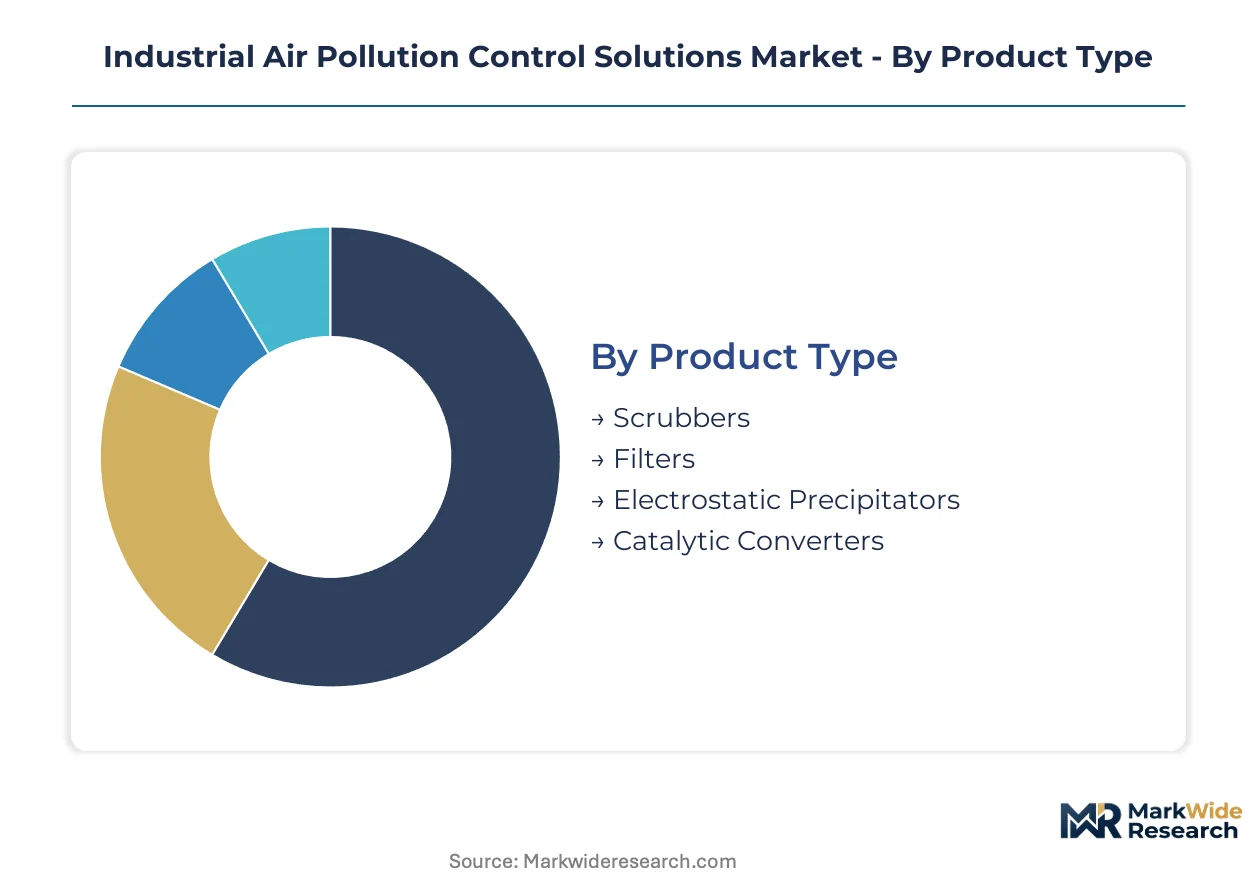
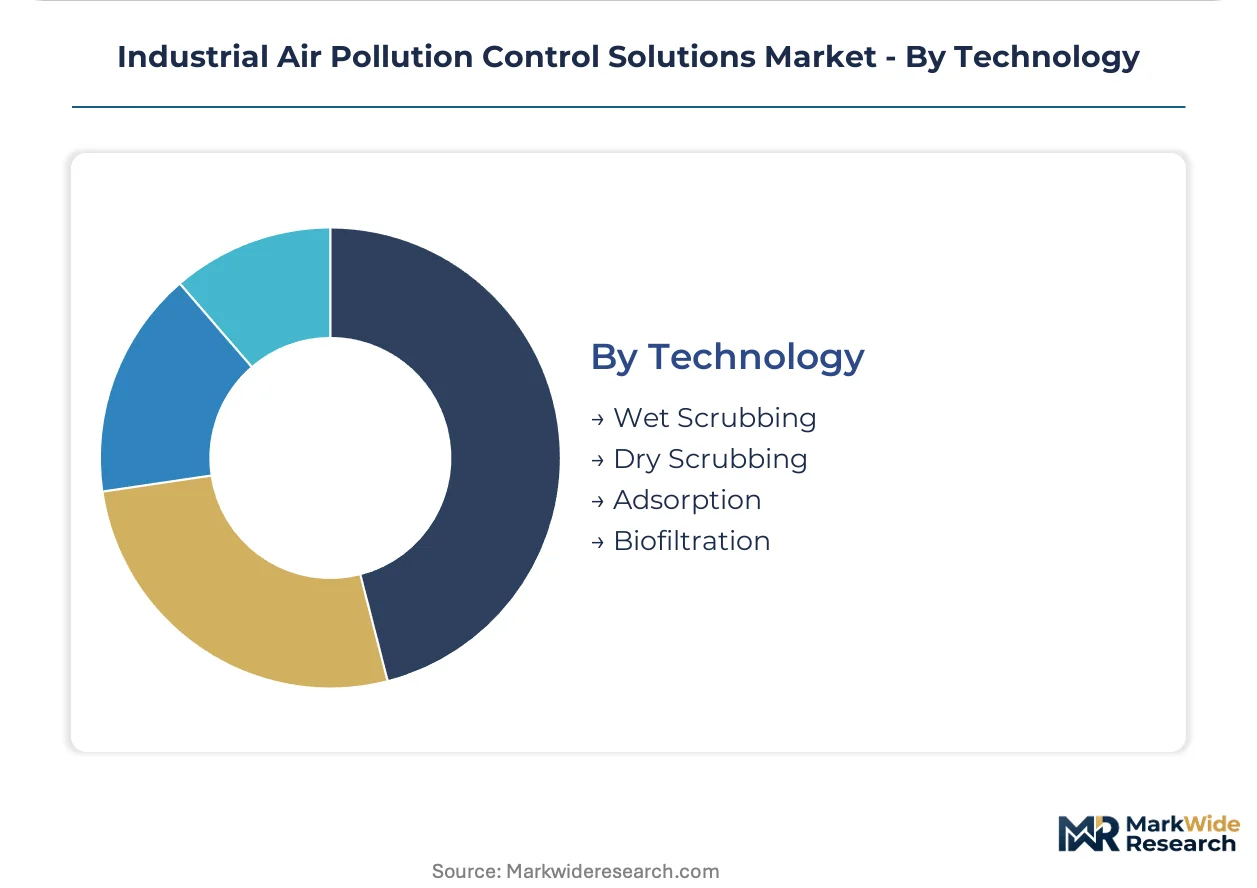
Technology differentiation across capture mechanisms determines equipment selection for specific contaminant profiles. End-use concentration in heavy process industries shapes regional deployment patterns and service contracting models.
Product Type:
Engineered systems vary by contaminant removal mechanism, capital intensity, and operational temperature range.
- Electrostatic Precipitators:Plate-wire or tube-bundle configurations apply high-voltage fields to ionize and collect particulate matter from gas streams between 120°C and 350°C. Utility-scale power generators in China and India dominate retrofit demand as GB standards and CPCB mandates tighten stack opacity limits.
- Scrubbers:Liquid-gas contact chambers neutralize acid gases and capture sub-micron particulate through chemical absorption. Chemical processing facilities on the US Gulf Coast favor condensing wet designs for simultaneous acid mist and mercury co-capture.
- Filters:Fabric or cartridge media mechanically separate dust loads in dry gas streams. Mining operations in Australia's Pilbara region deploy pulse-jet baghouses for iron ore handling.
- Catalytic Converters:Honeycomb substrates coated with precious metal catalysts oxidize or reduce gaseous pollutants. Selective catalytic reduction units serve German and Polish power plants facing EU Green Deal ammonia slip requirements.
Electrostatic precipitators lead on scale; scrubbers lead on momentum.
Application:
Contaminant load characteristics and process continuity requirements dictate technology matching across verticals.
- Chemical Processing:Multi-pollutant streams containing acid gases, volatile organics, and particulate demand hybrid wet-dry architectures. Refinery operators in Texas and Louisiana prioritize corrosion-resistant Hastelloy construction.
- Power Generation:High-volume flue gas streams from coal and biomass combustion require utility-scale precipitator or scrubber trains. Indian thermal plants face CPCB-mandated continuous emission monitoring retrofits.
- Manufacturing:Dispersed dust sources from grinding, cutting, and coating operations use compact filter collectors. Automotive stamping plants in Michigan and Ohio specify cartridge systems for weld fume capture.
- Waste Incineration:Heterogeneous feedstocks produce complex emissions requiring activated carbon injection plus fabric filtration. Municipal facilities in Japan's Kanto region deploy dry scrubber-baghouse combinations for dioxin control.
Power generation commands installed base; chemical processing shows steepest expansion trajectory.
End User:
Capital availability and regulatory exposure shape procurement preferences between equipment purchase and performance contracting.
- Utilities:Rate-base-regulated power producers amortize large precipitator investments over decades. State-level renewable portfolio standards in the US accelerate coal plant scrubber abandonment decisions.
- Construction:Cement and lime manufacturers face EU BAT reference document revisions and Indian CPCB scrubber mandates. Performance-based service contracts dominate procurement in capital-constrained Indian complexes.
- Mining:Remote site locations favor modular skid-delivered scrubber packages to minimize field construction. Western Australian iron ore ports specify pre-assembled dust suppression systems.
- Aerospace:Coating and surface treatment operations generate volatile organic compound streams requiring regenerative thermal oxidizers. California's South Coast Air Quality Management District enforces strict VOC limits on Los Angeles-area finishing facilities.
Utilities anchor revenue concentration; construction drives retrofit velocity.
Technology:
Process intensification trends favor compact footprints and real-time optimization capabilities.
- Wet Scrubbing:Liquid reagent contact removes soluble gases and captures particulate through inertial impaction. High-purity limestone sourcing constraints in select mining districts create geographic vulnerability for flue gas desulfurization operators.
- Dry Scrubbing:Dry sorbent injection neutralizes acid gases without wastewater generation. Circulating fluidized bed absorbers serve European waste-to-energy plants facing stringent residue disposal regulations.
- Adsorption:Activated carbon or zeolite media capture organic vapors and mercury. Powdered activated carbon injection systems retrofit onto existing particulate control devices at US Midwestern coal plants.
- Biofiltration:Microbial oxidation degrades odorous compounds in low-concentration streams. Food and pharmaceutical facilities in the Netherlands deploy bio-trickling filters for VOC and odor control at superior margins.
Wet scrubbing dominates volume deployment; biofiltration captures premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The electrostatic precipitator industry traces its commercial roots to German power engineering of the 1920s, with subsequent scaling through American utility deployment in the post-war decades. Modern demand patterns reflect this bifurcated heritage between European process engineering and Asian industrial expansion.
China
Coal-fired generation and steelmaking dominate equipment procurement along the Yangtze River Delta and around Tianjin. The MEE enforces annual tightening of GB emission standards for particulate matter. Provincial environmental bureaus in Jiangsu and Hebei provinces mandate precipitator upgrades at steel complexes in Tangshan and Nanjing.
India
Cement and thermal power sectors drive scrubber and precipitator demand across seventeen critically polluted industrial clusters. The CPCB mandates continuous emission monitoring systems with hard installation deadlines. Scrubber deployment concentrates in Gujarat's cement belt and Chhattisgarh's power generation corridor.
United States
Chemical processing and refinery operators on the Gulf Coast retrofit stacks with condensing wet electrostatic precipitators. The EPA enforces Maximum Achievable Control Technology standards under the Clean Air Act. Texas and Louisiana facilities face particular pressure on acid gas and mercury co-capture requirements.
Germany
Large combustion plant operators accelerate selective catalytic reduction catalyst replacement cycles. The EU Green Deal's industrial emissions directive recalibrates Best Available Technique reference documents. Power generators in North Rhine-Westphalia and lignite regions of eastern Germany face tightened mercury and ammonia slip ceilings.
Japan
Waste incineration facilities deploy dry scrubber-baghouse combinations for dioxin control in the Kanto region. METI oversees technical standards for municipal and industrial waste thermal treatment. Tokyo-area plants lead adoption of activated carbon injection systems for hazardous emission suppression.
Industrial Air Pollution Control Solutions Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology specialization depth and service contracting sophistication. The vendor base organizes into three tiers: integrated engineering conglomerates with utility-scale heritage, mid-cap specialists focused on wet scrubbing or biofiltration niches, and regional fabricators serving mining and manufacturing dust collection. Consolidation pressure runs highest among precipitator specialists facing legacy control system integration challenges. Competitive moves center on performance-based service contracting conversions and modular skid delivery capabilities for remote site access.
Within the integrated engineering tier, Mitsubishi Heavy Industries and General Electric Company exemplify scale-driven positions anchored to utility-sector relationships. Among mid-cap specialists, CECO Environmental occupies a wet scrubbing focus, while Thermax Ltd represents the performance-contracting model prevalent in capital-constrained Indian industrial complexes. Fujian Longking Co. Ltd. sits within the China-based fabricator archetype serving domestic emission compliance mandates.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries |
| Thermax Ltd |
| Babcock & Wilcox Enterprises |
| General Electric Company |
| Fujian Longking Co. Ltd. |
| CECO Environmental |
| Donaldson Company Inc. |
| AAF International |
| Dürr Systems AG |
| Others |
Supply & Pricing Matrix
Corrosion engineering talent scarcity in Germany's Ruhr industrial region widens pricing spreads between premium Hastelloy-fabricated wet scrubbers and standard carbon-steel alternatives, as labor-cost differentials compound specialty alloy premiums.
Pricing Analysis
Project-based equipment procurement with multi-year service bundling anchors pricing structures across utility and chemical processing buyers. Three-tier pricing structure across premium, standard, and economy levels separates corrosion-resistant alloy construction from epoxy-coated carbon steel and refurbished legacy units. Pricing pressure stems from Indian cement sector procurement shifts toward performance-based contracting that compresses upfront equipment margins. Capital-constrained construction end-users exhibit highest price sensitivity, while Gulf Coast petrochemical operators prioritize acid gas removal efficiency over capital outlay.
Supply Chain Analysis
ASME Section VIII and EN 1090 certification gating restricts qualified fabrication to a limited vendor pool across Germany, Japan, and South Korea. Hastelloy C-276 sheet, titanium tubing, and high-purity limestone reagent constitute critical input dependencies. Single-source vulnerability concentrates in specialty alloy melt shops serving scrubber pressure vessel construction. Distribution runs through engineering-procurement-construction contractors with established utility relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in aftermarket service contracting and modular skid delivery, as remote mining site access commands premium pricing and recurring instrumentation revenue stabilizes cash flow volatility.
For Market Incumbents: Hedge against stranded precipitator assets by accelerating pulse-energized retrofit capabilities and securing captive limestone supply agreements in Gujarat and Chhattisgarh. Performance-based service contracting in Indian cement complexes defends revenue concentration against Chinese equipment fabricators with state-backed financing. For New Entrants and Emerging Players: Begin with modular skid-delivered wet scrubbing packages for Western Australian iron ore ports and Chilean copper concentrate handling facilities, where field construction labor scarcity creates penetrable white space. Partner with regional EPC contractors possessing established mining relationships rather than competing directly for utility-scale precipitator tenders. For Investors and Strategic Acquirers: Engineering conglomerates with utility-sector heritage represent the most active acquirer category in this space, targeting wet scrubbing specialists with chemical processing credentials. Long-term viability hinges on carbon capture integration capabilities across cement and steel verticals. Watch for GB standard tightening announcements from China's MEE as inflection triggers for precipitator retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Service Contracting | Indian cement producers under CPCB mandates favor opex structures over capital deployment. |
| Modular Skid Delivery Capability | Pre-assembly reduces field timelines at remote Pilbara iron ore and Chilean copper sites. |
| Carbon Capture Integration | Amine scrubber retrofits open equipment bundling prospects for EU Green Deal compliance. |
| Specialty Alloy Backward Integration | Hastelloy sourcing control mitigates nickel-molybdenum price volatility exposure. |
| Continuous Emission Monitoring Systems | CPCB-mandated CEMS retrofits create recurring instrumentation revenue across seventeen clusters. |
Research Methodology
Multiple input streams — primary technical interviews, regulatory filing analysis, and trade flow reconciliation — were combined to construct segment-level demand estimates. Plant engineers, procurement leads at cement and steel complexes, EPC contractor project directors, and aftermarket service heads provided operational perspective. Secondary validation drew from EPA enforcement databases, MEE GB standard publications, CPCB cluster notifications, and customs records for specialty alloy imports. Bottom-up equipment deployment tallies were cross-checked against top-down industrial capacity estimates.
Historical installation patterns were cross-referenced against panel input from equipment fabricators and utility planning officers to anchor projection trajectories. Segmentation modeling encompassed technology type, contaminant removal mechanism, end-use vertical, and regional regulatory cluster. CAGRs were derived from fitted trend lines across documented retrofit cycles and mandate implementation timelines. Forecast inputs incorporated MEE annual particulate limit reduction schedules and CPCB continuous monitoring system deadlines.
Several conditions sit outside the modeled scope, including unannounced regulatory accelerations, breakthrough capture technologies displacing incumbent systems, and commodity price shocks exceeding historical volatility bands. Forecasts reflect documented assumptions regarding mandate adherence timelines and equipment replacement cycles. A model refresh is warranted upon material change in EU Green Deal BAT reference document implementation schedules or MEE GB standard tightening announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Europe Travel Retail Market
Others
Hotel Wardrobe Market
Others
India Home Automation Market
Others
Middle East and Africa Home Care Packaging Market
Others
Smart Badge Market
Others
North America 3D Printing Construction Market
Others
HPHT Diamond Cubic Press Market
Others
Japan Automotive LED Lighting Market
Others
Bakery Packaging Market
Others
Thermal Insulation Solution for LNG and LPG Market
Others
Reusable Wine Bags Market
Others
Singapore Retail Market
Others
Conditional Access System (CAS) Market
Others
Global Pumpkin Candles Market
Others
Gesture Recognition for Smart TV Market
Others
Corn Fiber Market